
 Belt Weigh Feeder Market | 2026-2036
Belt Weigh Feeder Market Size, Share, and Industry Trends Forecast 2026-2036
Belt Weigh Feeder Market Insights
CE marking under the EU Machinery Directive is consolidating compliance burdens for belt weigh feeder vendors serving European cement and mining clients. Schenck Process leverages its German engineering base to sustain certification depth across load cell and electromagnetic product lines. ABB Ltd anchors automation-integrated weigh belt systems for bulk material handlers navigating EU Green Deal carbon tracking obligations.
A belt weigh feeder is a continuous gravimetric feeding device that measures bulk material mass flow via load cell or electromagnetic sensing elements mounted on a troughed conveyor belt, typically achieving accuracies within 0.25% to 1.0% of set rate. The instrument controls material discharge from hoppers or silos into downstream process equipment in cement kilns, coal pulverizers, and chemical reactors. Load cell configurations dominate installed base in mining and cement due to proven durability in abrasive environments, while electromagnetic variants capture expanding share in food processing where washdown hygiene protocols demand hermetic sensor enclosures. Weigh belt installations in chemical plants concentrate margin pools around automated calibration and remote diagnostics capabilities.
EPA emissions monitoring rules under the Clean Air Act shape belt weigh feeder specification in US coal and cement plants, where fuel feed rate accuracy directly determines stack gas reporting validity. China's MEE enforces parallel bulk material measurement standards for thermal power generators under dual carbon goals. India's CEA mandates continuous coal flow monitoring at utility-scale boilers, tightening metrological traceability requirements. Stakeholders must weigh regional certification divergence against platform standardization economics when configuring global product portfolios.
Market Dynamics
Dual carbon mandates in China and India's tightening CEA coal monitoring rules are forcing simultaneous accuracy upgrades across installed bases and new procurement specifications, compressing vendor certification cycles and fragmenting regional product platforms.
Growth Catalysts
- CE marking convergence:EU Machinery Directive compliance burdens are consolidating vendor qualification pools, advantaging engineering-heavy suppliers with in-house metrology labs over trading-house distributors.
- Load cell durability advances:Abrasive-environment cement and mining operations are extending replacement cycles through ceramic-coated strain gauge configurations, reducing total cost of ownership calculations in procurement evaluations.
- China MEE thermal power standards:Coal-fired generators under dual carbon goals are retrofitting continuous gravimetric feeders to replace volumetric systems, creating concentrated demand corridors in Shanxi and Inner Mongolia heavy industry clusters.
Market Restraints
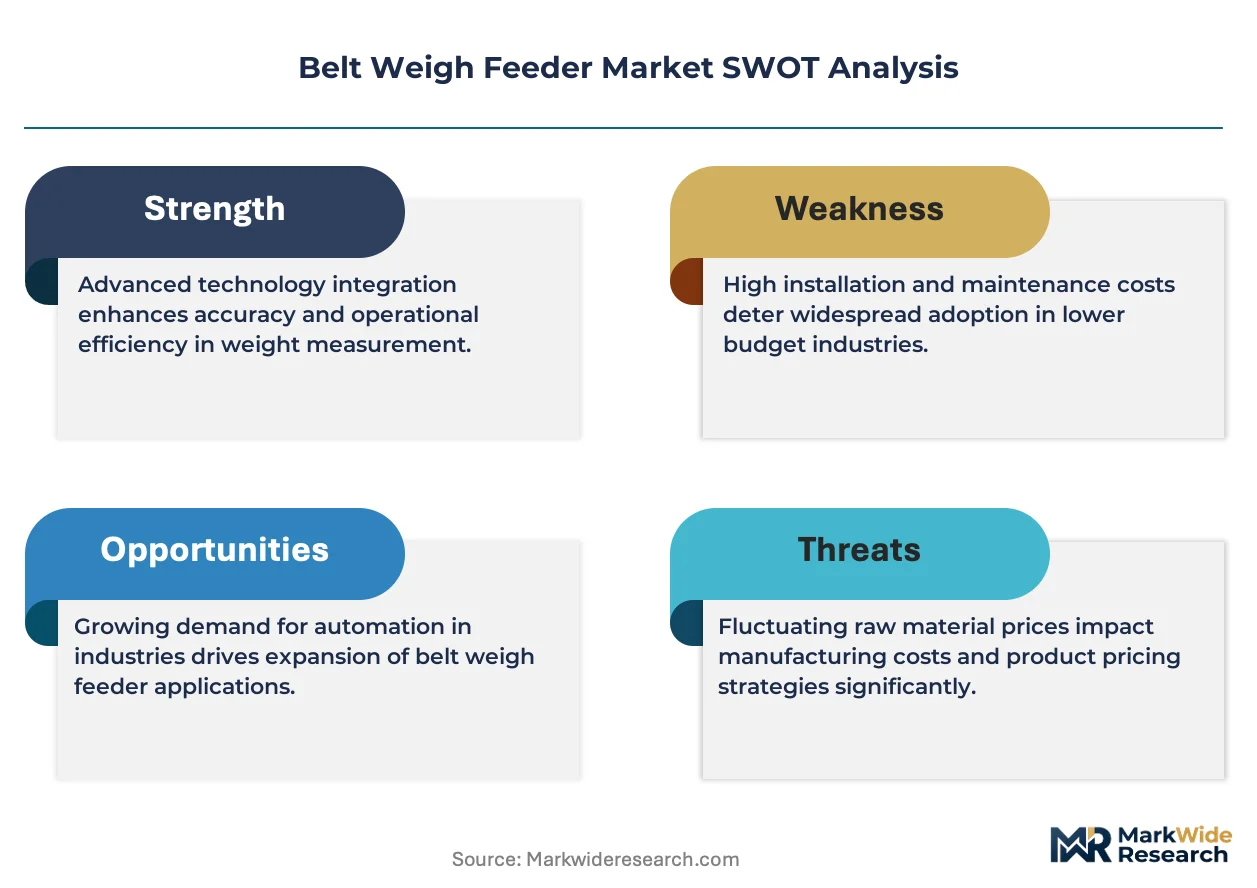
- Stainless steel input volatility:Belt weigh feeder frames and load cell housings face nickel and chromium price swings that compress margin predictability for fixed-price EPC contracts.
- Sensor supply concentration:Hermetic electromagnetic sensing element production clusters in German and Japanese precision manufacturing regions, exposing procurement timelines to single-source bottlenecks.
- Calibration labor intensity:Gravimetric accuracy maintenance requires certified technicians that mining and cement sites in remote geographies struggle to retain, extending downtime risk.
Strategic Opportunities
- Remote diagnostics penetration:Chemical plant operators in the US Gulf Coast are unbundling after-sales service from hardware procurement, creating recurring revenue streams for predictive maintenance platforms.
- Food processing washdown protocols:Electromagnetic sensor variants with IP69K hermetic sealing are capturing share in dairy and meat processing where load cell corrosion failures disqualify incumbent technologies.
- India PLI scheme alignment:Domestic manufacturing incentives for industrial automation components are opening local assembly pathways for multinational vendors previously reliant on fully-imported systems.
Industry Challenges
- Metrological traceability gaps:Cross-border calibration certificate recognition between national standards bodies delays commissioning schedules for multinational EPC contractors.
- Legacy DCS integration friction:Brownfield cement and coal plants running proprietary control architectures face protocol translation costs that erode automation upgrade business cases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Belt Weigh Feeder Market |
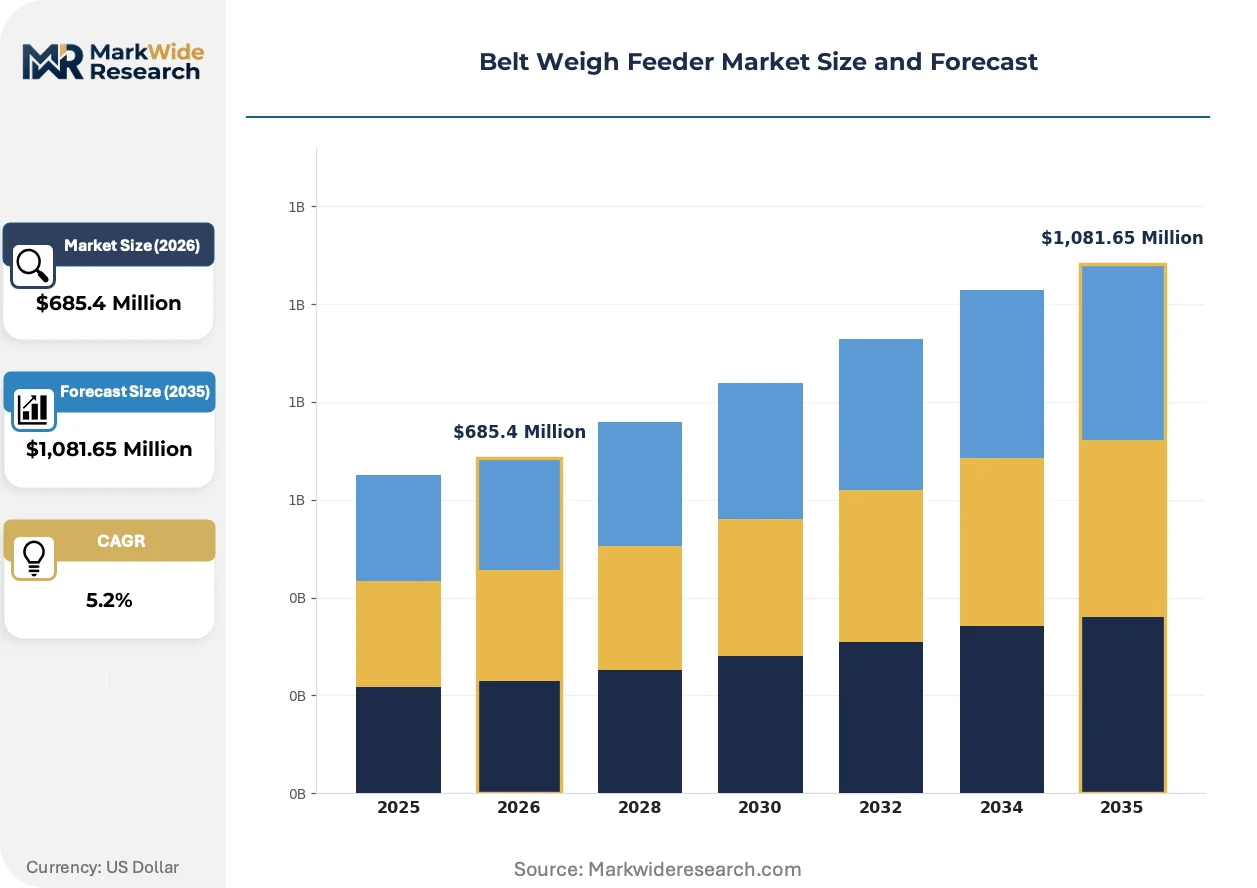
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,081.65 Million |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electromagnetic, Load Cell, Pneumatic, Weigh Belt Industry Vertical: Food Processing, Mining, Chemical, Pharmaceutical End User: Manufacturers, Distributors, Retailers, Contractors Installation Type: Fixed, Portable, Automated, Manual |
| Companies Covered | Mettler-Toledo International Inc., Siemens AG, Schenck Process, Minebea Intec GmbH, ABB Ltd, Merrick Industries, Endress+Hauser AG, Acrison, Thayer Scale, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Belt Weigh Feeder Market Trends and Innovations
Edge computing architectures and predictive algorithm deployment are redefining maintenance economics and accuracy assurance models across heavy bulk material handling corridors.
Machine learning-based drift compensation algorithms are integrating with load cell signal conditioning modules to auto-correct for temperature and tension variations without manual recalibration. Mining operators in Australian iron ore Pilbara operations are piloting these systems to sustain 0.25% accuracy bands across 24-hour continuous cycles. The technology is integrating calibration labor out of operating expenditure structures while compressing vendor service contract values toward software subscription models.
EPA Clean Air Act emissions monitoring enforcement is tightening fuel feed rate accuracy requirements for stack gas reporting validity in US coal and cement plants. Continuous gravimetric measurement is displacing volumetric estimation in regulatory compliance filings, with accuracy documentation now subject to third-party audit trails. Load cell-based systems with NIST-traceable calibration certificates are capturing preference share over electromagnetic alternatives in utility-scale boiler applications.
Procurement centralization among multinational cement groups is consolidating specification authority at engineering headquarters, displacing distributed site-level purchasing autonomy. Regional operations managers in Holcim and Heidelberg Materials networks now route feeder procurement through global framework agreements that mandate unified load cell protocols and remote diagnostics compatibility. This concentration is visible most acutely in European and North African kiln upgrade cycles where standardization economics override local vendor relationships.
Belt Weigh Feeder Market Segmentation
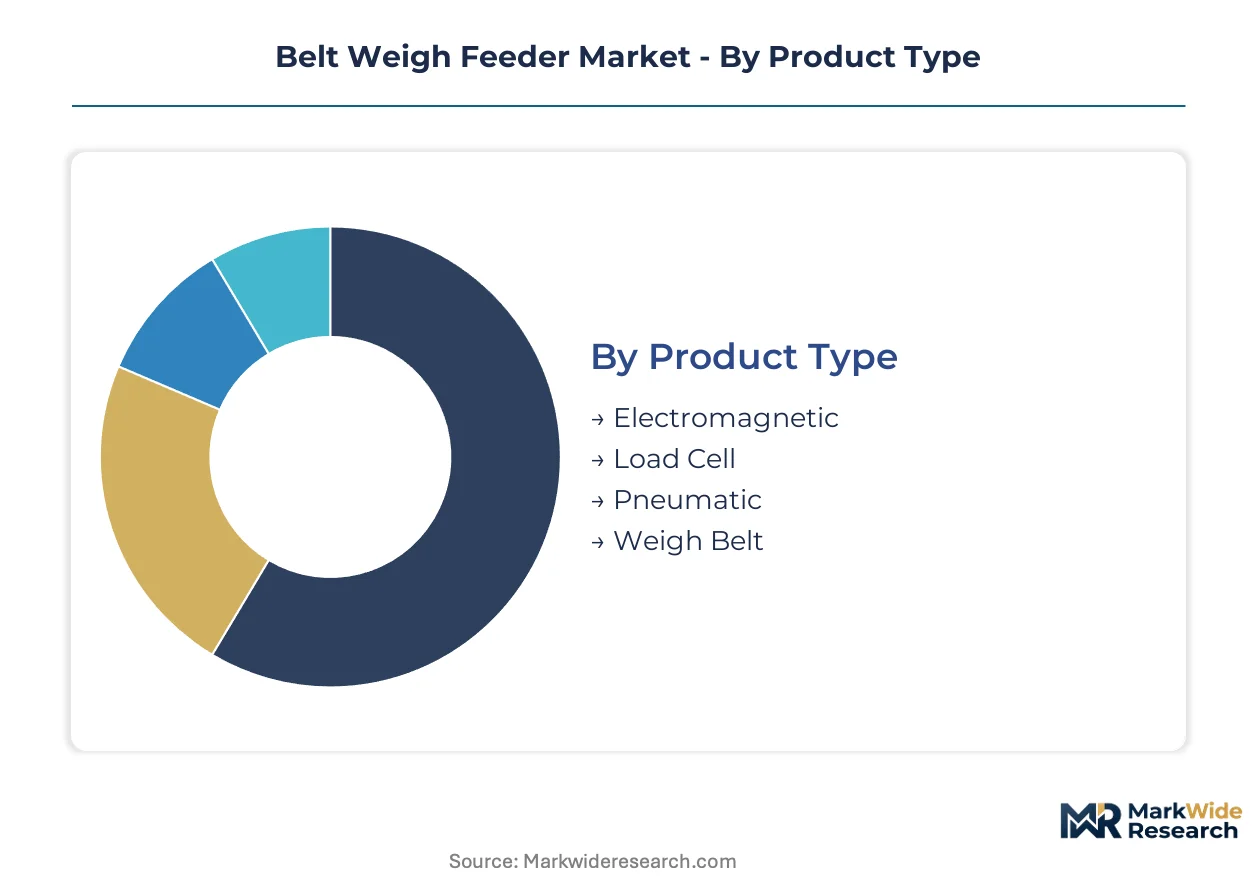
Belt weigh feeder procurement patterns diverge sharply across sensing technologies and installation contexts, with upgrade cycles in heavy industry driving specification fragmentation. Vendors must configure modular platforms that span abrasive mining environments and hygienic food processing lines without sacrificing metrological traceability.
Product Type:
Replacement cycles in cement and coal handling operations are accelerating technology transitions from legacy volumetric systems to gravimetric platforms with integrated diagnostics.
- Load Cell:Strain gauge configurations with ceramic-coated sensing elements dominate mining and cement installations where abrasive dust and vibration degrade lesser instruments. Indian cement producers under CEA emissions monitoring mandates are retrofitting load cell feeders to replace mechanical scales, concentrating demand in Rajasthan and Madhya Pradesh clinker corridors.
- Electromagnetic:Hermetically sealed sensing coils enclosed in stainless steel housings achieve IP69K ratings required for dairy and meat processing washdown protocols. Food safety auditors in EU member states are disqualifying load cell installations where moisture ingress risks bacterial harborage, redirecting specification authority toward electromagnetic variants in Northern European dairy cooperatives.
- Pneumatic:Compressed-air actuated feeding mechanisms serve specialized chemical reactor applications where explosive atmosphere classifications preclude electrical sensor proximity.
- Weigh Belt:Integrated conveyor-weighing platforms with modular frame construction accommodate brownfield retrofit constraints in aging US coal preparation facilities.
Load Cell sits at the top of the volume ranking, with Electromagnetic climbing the fastest.
Industry Vertical:
Margin structures concentrate around regulatory compliance intensity, with emissions monitoring mandates creating premium pricing pockets in carbon-intensive sectors.
- Mining:Iron ore and copper concentrate handlers in Australian Pilbara operations and Chilean Atacama deposits specify 0.25% accuracy bands with 24-hour continuous duty cycles. Machine learning drift compensation modules are displacing manual calibration labor from operating budgets in these high-tonnage corridors.
- Chemical:Continuous reactor feeding for polymer and fertilizer production demands automated calibration protocols and remote diagnostic compatibility. Gulf Coast petrochemical operators are unbundling service contracts from hardware procurement, creating recurring revenue streams for predictive maintenance platforms.
- Food Processing:Dairy, meat, and baked goods manufacturers prioritize hermetic sensor enclosures and rapid clean-in-place compatibility over absolute accuracy specifications.
- Pharmaceutical:Active ingredient batching operations require 21 CFR Part 11 compliant data integrity and audit trail documentation for FDA submission packages.
Mining commands the largest installed base, while Chemical exhibits the steepest expansion trajectory.
End User:
Procurement authority is consolidating at engineering headquarters among multinational operators, displacing distributed site-level purchasing autonomy.
- Manufacturers:Integrated cement and mining companies with captive processing operations specify unified load cell protocols across global asset portfolios. Holcim and Heidelberg Materials procurement frameworks now mandate remote diagnostics compatibility for all new feeder installations.
- Contractors:Engineering-procurement-construction firms executing turnkey kiln upgrades and coal plant retrofits face compressed certification cycles as dual carbon mandates in China and India's CEA rules tighten metrological traceability requirements simultaneously.
- Distributors:Regional equipment suppliers serving fragmented quarry and batch plant operators compete on spare parts availability and local technician certification depth.
- Retailers:Agricultural supply cooperatives and construction materials wholesalers handle lower-specification portable units for seasonal or mobile applications.
Manufacturers retain dominant specification authority, with Contractors gaining procurement share fastest.
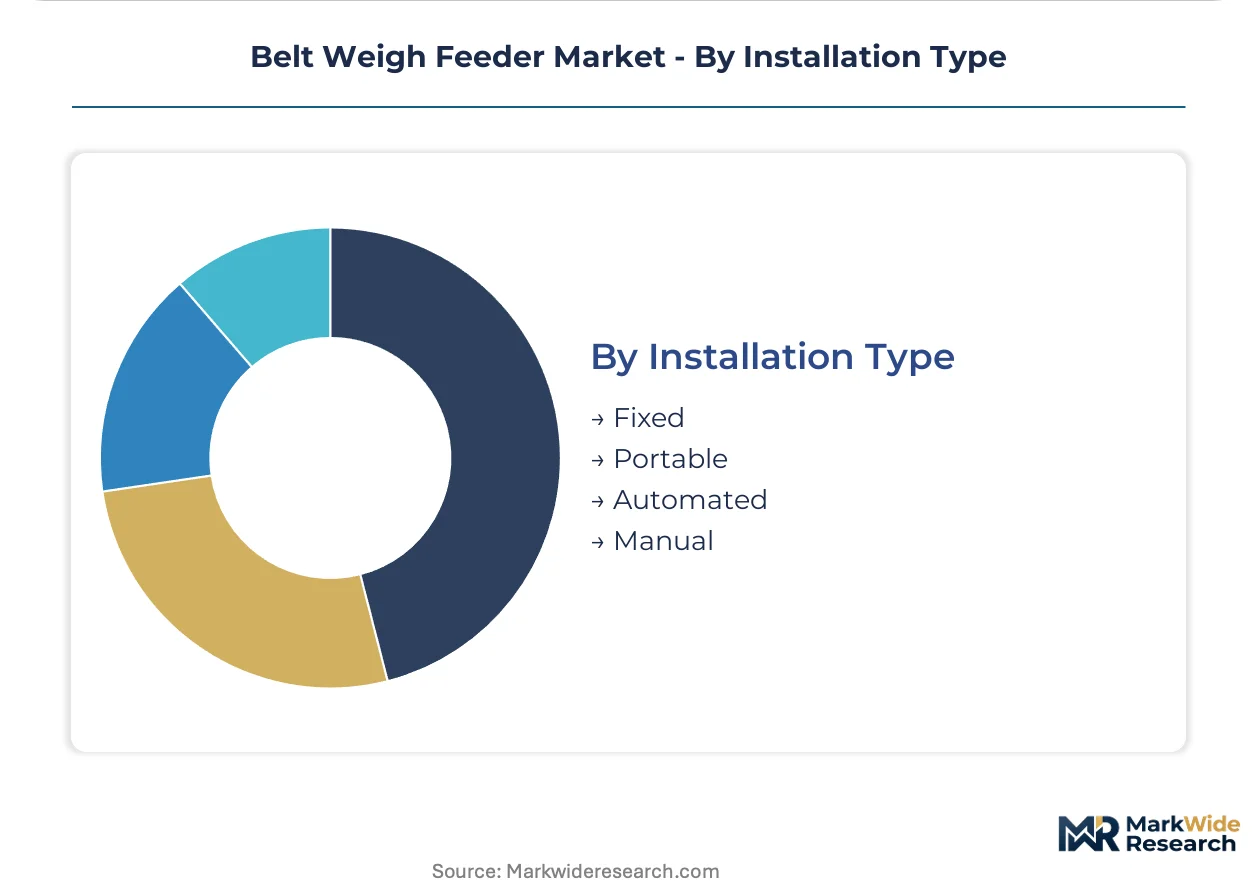
Installation Type:
Capital deployment patterns split between greenfield automation integration and brownfield retrofit constraints.
- Fixed:Permanent troughed conveyor installations with structural steel foundations anchor heavy bulk material handling corridors in Chinese Shanxi coal clusters and Indian thermal power belts. These configurations achieve highest accuracy stability but require extended commissioning schedules.
- Automated:Integrated feeder-DCS architectures with edge computing modules and predictive algorithms are redefining maintenance economics in US coal and cement plants facing EPA Clean Air Act enforcement tightening.
- Portable:Skid-mounted or trailer-deployed units serve quarry mobile crushing circuits and temporary construction materials batching operations.
- Manual:Basic mechanical or semi-automated configurations persist in developing economy small-scale mining and agricultural processing where labor cost structures delay automation adoption.
Fixed installations dominate capital expenditure allocation, with Automated configurations expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German engineering houses pioneered precision gravimetric feeding technology for heavy bulk material handling in the mid-20th century, establishing metrological standards that persist across European cement and mining corridors. Contemporary demand concentrates in coal-dependent economies upgrading emissions monitoring infrastructure and industrial automation clusters serving chemical processing.
China
Shanxi and Inner Mongolia coal belts are retrofitting continuous gravimetric feeders to replace volumetric systems under MEE thermal power standards. Dual carbon mandates enforce parallel bulk material measurement accuracy for stack gas reporting validity. Heavy industry clusters in these northern provinces account for concentrated procurement of load cell-based installations.
United States
EPA Clean Air Act enforcement tightens fuel feed rate accuracy requirements for coal and cement plant stack gas documentation. Gulf Coast petrochemical operators unbundle after-sales service from hardware procurement. Appalachian coal preparation facilities and Texas chemical corridors drive automated calibration protocol specification.
India
Rajasthan and Madhya Pradesh clinker corridors are retrofitting load cell feeders under CEA continuous coal flow monitoring mandates. Cement producers expand belt weigh feeder installations to meet stricter emissions monitoring rules. PLI scheme incentives for industrial automation components open local assembly pathways for multinational vendors.
Germany
CE marking under the EU Machinery Directive consolidates compliance burdens for vendors serving European cement and mining clients. Engineering-heavy suppliers with in-house metrology labs sustain certification depth across product lines. Industrial automation clusters in Baden-Württemberg and North Rhine-Westphalia anchor precision manufacturing of electromagnetic sensing elements.
Australia
Pilbara iron ore operations pilot machine learning drift compensation to sustain accuracy bands across 24-hour continuous cycles. Mining operators displace manual calibration labor through predictive algorithm deployment. Western Australian heavy bulk material handling corridors concentrate demand for ceramic-coated strain gauge configurations.
Belt Weigh Feeder Market Competitive Landscape
The competitive structure tilts toward engineering-heavy specialists with captive metrology capabilities. Vendor qualification pools consolidate around in-house certification depth versus trading-house distribution models. Two strategic archetypes dominate: German precision engineering houses with integrated load cell manufacturing and diversified automation conglomerates with feeder-DCS integration platforms. Competitive moves concentrate on remote diagnostics capability acquisition and regional assembly partnerships under domestic manufacturing incentive schemes.
Among Swiss and German precision engineering specialists, Mettler-Toledo International Inc., Schenck Process, and Minebea Intec GmbH exemplify the certification-heavy archetype. These entities occupy positions sustained by in-house metrology lab infrastructure and CE marking depth across electromagnetic and load cell product lines. Diversified automation conglomerates such as Siemens AG and ABB Ltd represent the platform integration vector, anchoring feeder specifications within broader distributed control system architectures. Merrick Industries and Thayer Scale sit within the North American specialist tier, serving coal and cement utility markets under EPA emissions monitoring compliance frameworks.
| Leading Market Players |
|---|
| Mettler-Toledo International Inc. |
| Siemens AG |
| Schenck Process |
| Minebea Intec GmbH |
| ABB Ltd |
| Merrick Industries |
| Endress+Hauser AG |
| Acrison |
| Thayer Scale |
| Others |
Pricing and Supply Chain Analysis
Captive in-house production of ceramic-coated strain gauge load cells anchors pricing power for German and Japanese engineering specialists, insulating them from nickel and chromium volatility that erodes margins for EPC contractors locked into fixed-price agreements. This backward integration into precision sensing element manufacturing concentrates value capture upstream while forcing distributors and trading-house competitors toward commoditized hardware margins.
Pricing Analysis
Bundled after-sales service contracts are unbundling into separate hardware procurement and predictive maintenance subscriptions across US Gulf Coast chemical corridors. Pricing stratifies across premium, standard, and economy tiers based on NIST-traceable calibration certificate depth and remote diagnostics compatibility. Cost compression in economy-tier portable units is intensifying because agricultural supply cooperatives prioritize spare parts availability over accuracy specifications. Cement manufacturers running continuous kiln operations exhibit lowest price sensitivity, while seasonal quarry operators demand economy configurations.
Supply Chain Analysis
Refurbishment flows for load cell sensing elements are creating secondary supply channels from Australian Pilbara mining operations back to German precision manufacturing clusters. Hermetic electromagnetic coil production draws from Baden-Württemberg and North Rhine-Westphalia industrial automation corridors, with raw material dependencies on Japanese precision steel and Chinese rare-earth magnet feedstocks. Single-source vulnerability concentrates in hermetic sensor enclosure manufacturing. Distribution runs through engineering-procurement-construction contractors executing turnkey retrofits under compressed certification cycles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Belt Weigh Feeder Market functions as a stable compounder anchored by regulatory mandates that mandate continuous accuracy upgrades across installed bases. Emissions monitoring enforcement creates replacement demand independent of cyclical capital expenditure cycles.
For Market Incumbents: Lock in certification depth advantages by expanding in-house metrology lab capacity to serve fragmented national standards body recognition requirements. Defend against trading-house distributors by embedding remote diagnostics platforms into global framework agreements with Holcim and Heidelberg Materials procurement headquarters. Vertical integration into ceramic-coated strain gauge manufacturing insulates margin structures from stainless steel input volatility. For New Entrants and Emerging Players: The premium-to-economy price-point gap in Indian cement retrofit corridors offers white-space entry for domestic assembly operations aligned with PLI scheme incentives. Target Rajasthan and Madhya Pradesh clinker belt contractors facing compressed CEA compliance timelines with rapid-commissioning load cell configurations. Partner with regional equipment distributors to bypass captive technician certification barriers in remote mining geographies. For Investors and Strategic Acquirers: Roll-up economics work for mid-cap electromagnetic sensor specialists because metrological traceability gaps fragment cross-border calibration certificate recognition and create consolidation value. Engineering-heavy vendors with CE marking depth across EU Machinery Directive requirements represent durable acquisition targets. Monitor EPA Clean Air Act enforcement intensity for early signals of accelerated fuel feed rate accuracy upgrade cycles in Appalachian coal preparation facilities.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Load Cell Manufacturing | Captive ceramic-coated strain gauge production insulates German specialists from nickel price swings. |
| Remote Diagnostics Platform Deployment | Predictive maintenance subscriptions capture recurring revenue from US Gulf Coast chemical operators. |
| PLI Scheme Local Assembly Partnership | Domestic manufacturing incentives open India cement corridor pathways for multinational vendors. |
| Machine Learning Drift Compensation Integration | Auto-calibration algorithms displace manual labor from Australian Pilbara iron ore operating budgets. |
| CE Marking Certification Depth Expansion | EU Machinery Directive compliance consolidates vendor qualification pools around engineering-heavy suppliers. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with plant engineers at cement and coal handling facilities, aftermarket service heads at precision engineering specialists, procurement leads at multinational EPC contractors, and maintenance directors at Australian mining operations with secondary validation against EPA enforcement databases, CEA circulars, MEE thermal power standards, EU Machinery Directive guidance documents, and SEC filings from listed automation conglomerates. Bottom-up installation tracking across Shanxi coal belts and Rajasthan clinker corridors triangulated against top-down market sizing from equipment import records.
Segment-weighting approaches distributed value and volume across load cell, electromagnetic, pneumatic, and weigh belt product configurations, with cross-cutting dimensions for mining, chemical, food processing, and cement industry verticals. CAGRs derived from regression analysis against coal-fired capacity additions, clinker production forecasts, and emissions monitoring rule implementation timelines. Modeling incorporated stainless steel price indices, technician certification density by geography, and remote diagnostics penetration rates as industry-specific forecast inputs.
Caveats apply where MEE enforcement intensity or CEA metrological traceability requirement revisions could materially shift the outlook. Forecasts reflect assumptions regarding dual carbon mandate continuity and EU Green Deal carbon tracking obligation expansion. Practitioners should monitor EPA Clean Air Act audit trail tightening and India PLI scheme extension decisions for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Conveyor Belt Market
Material Handling Equipment
Latin America Conveyors Market
Material Handling Equipment
Crushing Screening Equipment Market
Material Handling Equipment
Japan Conveyor Belt Market
Material Handling Equipment
Electric Wire Rope Hoist Market
Material Handling Equipment
Drum Dumper Market
Material Handling Equipment
Modular Self-Contained Aisle and Racking Systems Market
Material Handling Equipment
High Pressure Grease Hose Market
Material Handling Equipment
Bale Clamp Intensive Market
Material Handling Equipment
Froth Flotation Equipment Market
Material Handling Equipment
Can Racks Market
Material Handling Equipment
Global Automatic Palletizer and Depalletizer Market
Material Handling Equipment
Pedestal Boom System Market
Material Handling Equipment
Sorting Machines Market
Material Handling Equipment
Hose Pump Market
Material Handling Equipment
Hydraulic Hoist Market