
 Building Asphalt Market | 2026-2036
Building Asphalt Market Size, Share, and Industry Trends Forecast 2026-2036
Building Asphalt Market Analysis
Polymer-modified binder grades is redrawing competitive positioning among specialized producers. FAYAT leverages its manufacturing scale across European and North American asphalt plant installations. SHOWA REKISEI INDUSTRIES CO., LTD. anchors its position through advanced polymer modification capabilities in Asian markets. Parker Plant Limited competes on equipment integration that supports higher-specification mix production.
Building asphalt comprises bituminous binders mixed with mineral aggregates, typically formulated to achieve specific penetration grades, softening points, and viscosity ranges for load-bearing surfaces. Its primary purpose is to create durable, waterproof pavement and roofing layers that withstand cyclic thermal stress and mechanical loading. Hot mix asphalt retains the largest volume share across highway and arterial road projects, while warm mix asphalt is gaining share fastest as agencies prioritize lower-temperature production. Porous asphalt commands premium positioning in stormwater management applications, though it occupies a narrower niche in overall pavement construction.
EPA emissions standards and state-level Department of Transportation specifications in the United States shape product formulation requirements and plant permitting timelines. The Federal Highway Administration's recycled materials policies directly influence recycling technology adoption rates among contractors and public agencies. Stakeholders must monitor evolving polymer supply chain conditions and binder certification protocols to secure specification-compliant positioning in upcoming infrastructure procurement cycles.
Market Dynamics
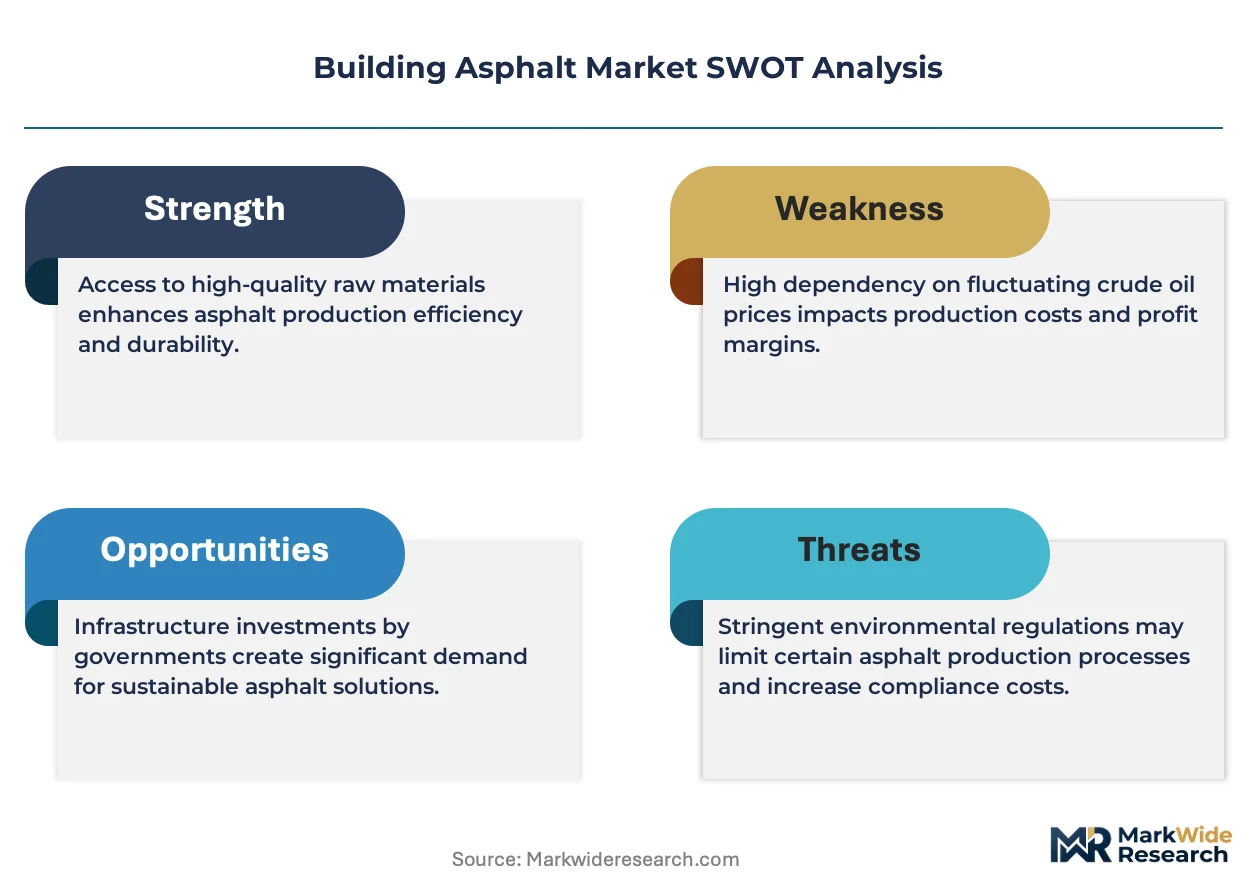
Warm mix asphalt technology is decomposing traditional production economics by cutting fuel consumption 20-40% while meeting identical performance specifications, forcing contractors to retool plants or lose municipal contracts.
Growth Catalysts
- Federal Highway Administration recycled materials mandates:State transportation departments must hit rising reclaimed asphalt pavement targets, accelerating cold recycling equipment deployment.
- Polymer modification capabilities:Specialized binders meeting Superpave performance grades unlock high-stress applications on interstate corridors and airport runways.
- Stormwater management infrastructure:Porous asphalt installations expand as municipalities face EPA National Pollutant Discharge Elimination System compliance deadlines.
Market Restraints
- Crude-linked bitumen cost volatility:Refinery output decisions tied to marine fuel demand swings destabilize binder pricing for contractors locked into fixed municipal bids.
- Specialized additive supply concentration:Styrene-butadiene-styrene and ethylene-vinyl-acetate modifiers depend on petrochemical complexes concentrated along Gulf Coast corridors.
- Performance-graded binder certification timelines:AASHTO M320 and M332 testing protocols create 6-12 month qualification windows that freeze formulation innovation.
Strategic Opportunities
- India National Highway Development:Bharatmala Pariyojana phase-2 corridors require 65,000 lane-kilometers of flexible pavement, opening polymer-grade specification markets.
- Carbon capture integration:Warm mix foaming systems paired with bio-based fluxing agents create net-zero production pathways eligible for IRA 45Q credits.
- Rooftop solar mounting compatibility:Cool roof asphalt membranes with high solar reflectance index ratings penetrate commercial building retrofit channels.
Industry Challenges
- Polymer modification technical talent scarcity:Rheology specialists capable of tuning complex modulus across temperature ranges command premium compensation, constraining plant expansion.
- Legacy batch plant retrofit complexity:Converting drum-mix facilities for warm mix foaming or RAP injection requires 18-24 month engineering timelines with uncertain performance guarantees.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Building Asphalt Market |
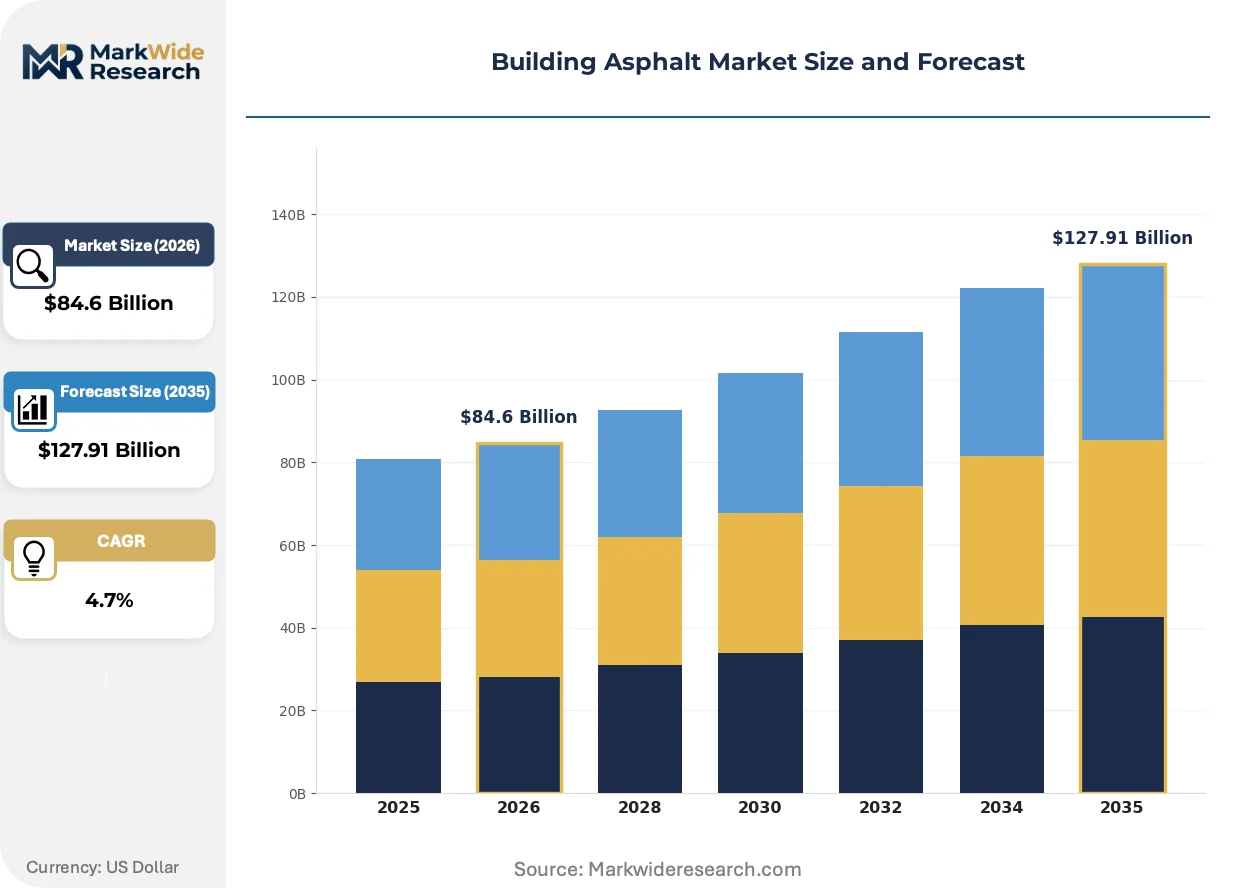
| Market Size in 2026 | $84.6 Billion |
| Market Size in 2035 | $127.91 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hot Mix Asphalt, Warm Mix Asphalt, Cold Mix Asphalt, Porous Asphalt Application: Pavements, Roofs, Parking Lots, Driveways Technology: Recycling Technology, Polymer Modified Asphalt, Chip Sealing, Asphalt Emulsions End User: Construction Companies, Local Governments, Private Developers, Contractors |
| Companies Covered | POLYGONMACH, Wahal Engineers, SAE Manufacturing Specialties Corp, Rose Paving, SHOWA REKISEI INDUSTRIES CO., LTD., Parker Plant Limited, TTC Engineering, Ruston Paving Co., FAYAT, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Building Asphalt Market Emerging Trajectories
Production technology and binder chemistry are converging to cut emissions intensity while extending pavement service life, reshaping how contractors compete for public infrastructure awards.
Rejuvenator chemistry is decomposing the historical trade-off between high recycled content and fatigue resistance. Bio-based recycling agents and engineered maltene restorers now permit 50% reclaimed asphalt pavement in surface courses without cracking penalties. State DOTs in California and Texas are piloting these formulations on high-volume routes, compressing the premium once commanded by virgin binder mixes.
EPA New Source Performance Standards for asphalt plants are tightening particulate and volatile organic compound limits. Facilities must install thermal oxidizers or baghouse upgrades to secure air permits, adding $2-4 million per plant in environmental controls. Smaller contractors in non-attainment zones face consolidation pressure as permit timelines stretch 18-36 months.
Performance-based contracting is displacing unit-price procurement for highway rehabilitation. Agencies in Virginia, Florida, and Michigan now specify 10-15 year pavement warranties, transferring lifecycle risk to contractors. This compresses bidding pools to vertically integrated firms with in-house materials testing and long-term maintenance capabilities.
Building Asphalt Market Segmentation
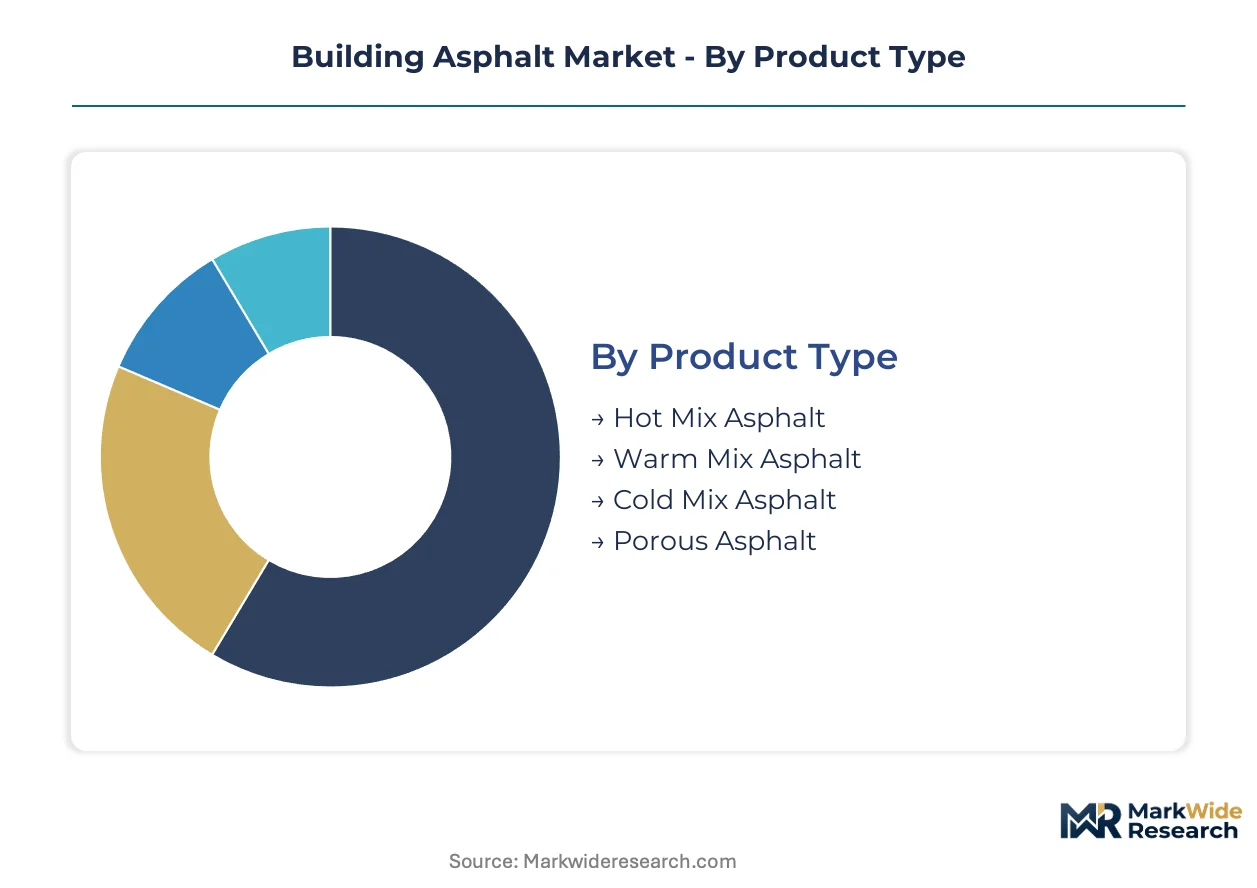
Product formulation choices in building asphalt directly determine fuel consumption profiles, emissions compliance costs, and pavement warranty terms. Contractors segment procurement strategies around production temperature requirements and recycled content mandates from state transportation departments.
Product Type:
Substitution pressure from concrete pavement and synthetic roofing membranes weighs most heavily on high-temperature production segments, forcing asphalt producers to defend positioning through lifecycle cost arguments and recycled content flexibility.
- Hot Mix Asphalt:Conventional bituminous binder heated to 150-190°C, mixed with graded aggregates at central plant facilities. Demand concentrates on federal interstate corridors and airport runway resurfacing where Superpave performance grades mandate high stiffness modulus. State DOTs in Texas and California specify this grade for heavy truck traffic lanes despite fuel cost penalties.
- Warm Mix Asphalt:Production temperatures reduced 20-40°C through chemical additives, water foaming, or organic waxes without compromising compaction density. Municipal contracts in EPA non-attainment zones increasingly require warm mix to meet volatile organic compound limits, with Virginia DOT mandating its use on urban rehabilitation projects.
- Cold Mix Asphalt:Emulsion-based formulations cured through evaporation rather than heat, enabling stockpiling and patch repairs without continuous plant operation.
- Porous Asphalt:Open-graded aggregate structure with 15-25% interconnected void space for stormwater infiltration, commanding specification premiums in EPA National Pollutant Discharge Elimination System compliance zones.
Hot Mix Asphalt anchors the volume base while Warm Mix Asphalt gains share at the steepest rate.
Application:
Cost tier differentiation separates specification-heavy infrastructure work from price-sensitive residential and commercial surface treatments.
- Pavements:Highway, arterial road, and bridge deck surfacing requiring performance-graded binders certified under AASHTO M320 protocols. Federal Highway Administration recycled materials mandates drive cold recycling equipment deployment across state transportation department contracts.
- Roofs:Built-up roofing membranes and modified bitumen sheets formulated for waterproofing and thermal resistance. Cool roof specifications with high solar reflectance index ratings penetrate commercial building retrofit channels in California Title 24 compliance zones.
- Parking Lots:Medium-duty surface courses balancing initial cost against maintenance liability, typically specified at lower binder grades than highway pavements.
- Driveways:Residential and light commercial installations where contractor availability and seasonal scheduling constrain specification complexity.
Pavements generate the largest revenue concentration while Roofs expand most quickly through energy code compliance requirements.
Technology:
Customer type fragmentation separates public agency procurement with extended warranty terms from private developer emphasis on speed-to-completion.
- Recycling Technology:Cold and hot in-place recycling systems reclaiming existing pavement layers without full reconstruction. State DOTs must hit rising reclaimed asphalt pavement targets, accelerating equipment deployment among vertically integrated contractors.
- Polymer Modified Asphalt:Styrene-butadiene-styrene or ethylene-vinyl-acetate elastomers blended to enhance elastic recovery and rutting resistance. Interstate corridor resurfacing and airport runway specifications in Florida and Michigan require Superpave PG 76-22 or higher grades.
- Chip Sealing:Surface treatment applying binder spray followed by aggregate chips for cost-effective maintenance of low-volume roads.
- Asphalt Emulsions:Bitumen dispersed in water with emulsifying agents for cold application tack coats and surface treatments.
Recycling Technology dominates public sector procurement volumes while Polymer Modified Asphalt shows the steepest specification expansion in high-stress applications.
End User:
Supply concentration around specialized polymer modification capabilities and plant permitting timelines shapes competitive access across end user categories.
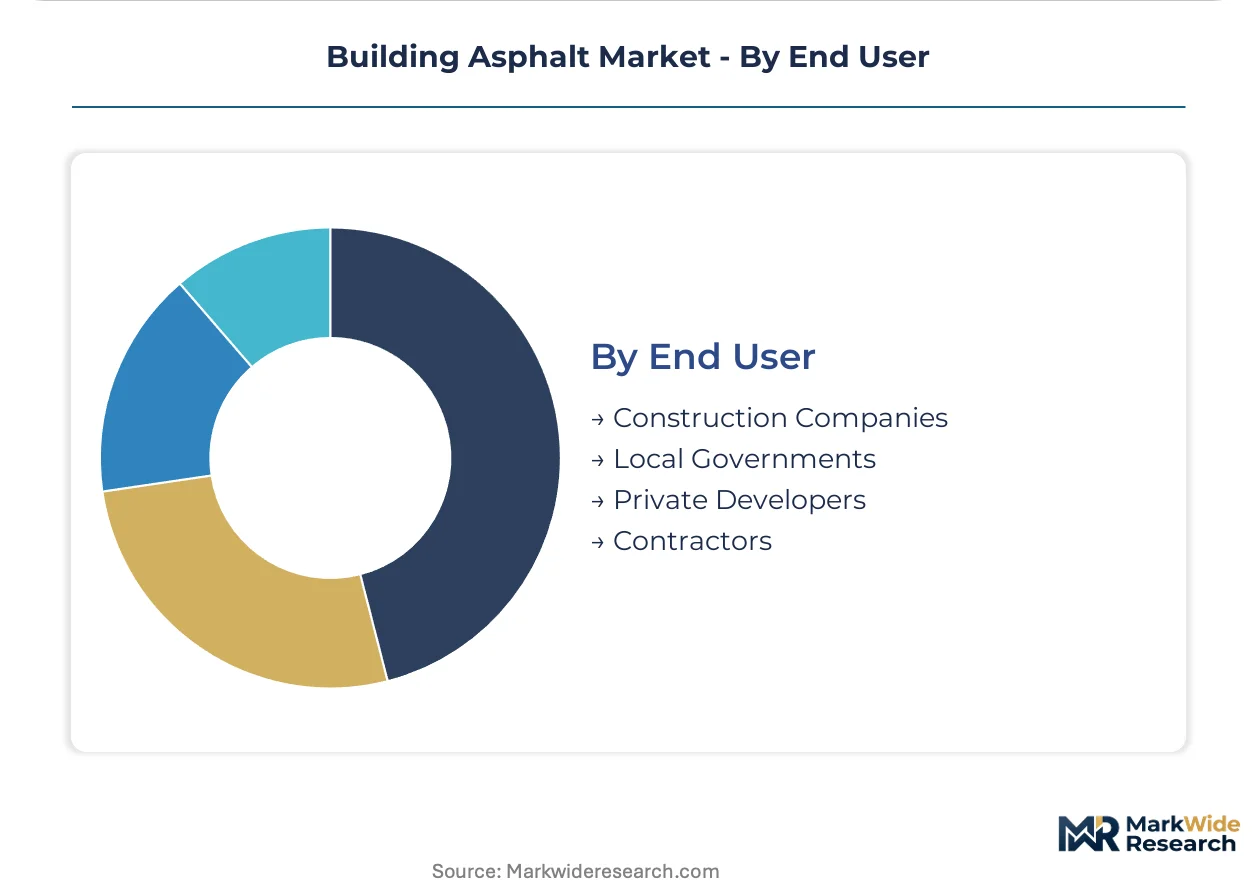
- Construction Companies:Vertically integrated firms with in-house materials testing and long-term maintenance capabilities competing for performance-based contracts. Virginia, Florida, and Michigan agencies now specify 10-15 year pavement warranties, compressing bidding pools to qualified integrated operators.
- Local Governments:Municipal street departments with constrained capital budgets prioritizing unit-price procurement and seasonal maintenance schedules. Smaller contractors face consolidation pressure as EPA air permit timelines stretch 18-36 months in non-attainment zones.
- Private Developers:Commercial and residential project owners optimizing for speed-to-completion and initial cost rather than lifecycle performance.
- Contractors:Specialized paving firms executing work under prime contract or subcontract arrangements, dependent on plant fleet configuration and environmental control investments.
Construction Companies capture the premium specification tier while Local Governments represent the largest contract volume base.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Refinery capacity and polymer modification infrastructure cluster disproportionately along the United States Gulf Coast, with secondary concentrations in Germany's Rhine-Ruhr corridor and India's western industrial belt.
United States
Federal highway rehabilitation contracts and state DOT pavement warranty programs drive specification-grade demand. EPA New Source Performance Standards tighten particulate limits for asphalt plants, extending permit timelines in California and Texas. The Houston-Galveston petrochemical corridor supplies styrene-butadiene-styrene modifiers to contractors bidding on Superpave PG 76-22 interstate projects.
Germany
Federal transport infrastructure investment programs prioritize low-temperature asphalt technologies for carbon reduction targets. EU Green Deal emissions benchmarks accelerate warm mix adoption on Bundesautobahn resurfacing contracts. The Rhine-Ruhr industrial region hosts specialized binder modification facilities serving Dutch and Belgian cross-border paving consortia.
India
Bharatmala Pariyojana phase-2 corridor development requires 65,000 lane-kilometers of flexible pavement with polymer-modified specifications. Ministry of Road Transport and Highway mandates for recycled content rise annually, pushing cold recycling equipment deployment. Gujarat and Maharashtra industrial zones concentrate bitumen refinery capacity and emulsion production for western state highway contracts.
China
Provincial expressway expansion and urban road network upgrades sustain hot mix volume despite environmental compliance pressures. Ministry of Ecology and Environment emissions standards force thermal oxidizer retrofits at drum-mix plants in the Yangtze River Delta. Shandong Province refineries supply penetration-grade binders for Belt and Road Initiative infrastructure exports.
Saudi Arabia
NEOM linear city and Red Sea coastal tourism projects specify high-performance pavement for desert thermal cycling conditions. Saudi Standards, Metrology and Quality Organization certification protocols align with AASHTO performance grading for imported polymer modifiers. Eastern Province refineries leverage feedstock proximity to serve contractor demand across GCC highway interconnection programs.
Building Asphalt Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a bifurcated competitive structure. Integrated refinery-chemical conglomerates with captive bitumen supply compete against specialized plant equipment fabricators and regional paving contractors with in-place recycling capabilities. Three archetypes dominate: polymer modification specialists, warm mix technology licensors, and vertically integrated infrastructure contractors. Consolidation pressure intensifies as environmental permit timelines stretch and performance-based contracting transfers lifecycle risk to bidders with balance sheet capacity.
Among the named participants, FAYAT exemplifies the equipment-integrated archetype with manufacturing scale across European and North American asphalt plant installations. SHOWA REKISEI INDUSTRIES CO., LTD. occupies a position representing advanced polymer modification capabilities concentrated in Asian markets. Parker Plant Limited sits within the specialized equipment tier, competing on production system integration that supports higher-specification mix output. These three represent distinct strategic postures rather than interchangeable competitors.
| Leading Market Players |
|---|
| POLYGONMACH |
| Wahal Engineers |
| SAE Manufacturing Specialties Corp |
| Rose Paving |
| SHOWA REKISEI INDUSTRIES CO., LTD. |
| Parker Plant Limited |
| TTC Engineering |
| Ruston Paving Co. |
| FAYAT |
| Others |
Supply Flow & Price Mechanics
Plant utilization rates above 85% at Gulf Coast refineries compress marginal cost curves for bitumen producers, concentrating supply-side pricing power among integrated operators while forcing smaller batch-plant contractors toward fixed-price municipal bids that expose them to crude-linked volatility.
Pricing Analysis
EPA New Source Performance Standards dictate the pricing tier structure across the building asphalt market. Three-tier pricing structure across premium, standard, and economy levels separates polymer-modified Superpave grades from conventional hot mix and cold patch formulations. Cost compression in standard-grade hot mix is intensifying because state DOTs are consolidating procurement volumes under performance-based contracts. Local governments and small residential contractors exhibit the highest price sensitivity, while airport authorities and interstate corridor agencies prioritize performance certification over unit cost.
Supply Chain Analysis
The United States, Germany, and India anchor bitumen refining and polymer modification capacity for global building asphalt supply. Production draws from crude oil distillation residues, styrene-butadiene-styrene elastomers, and engineered recycling agents. Single-source vulnerability concentrates around Gulf Coast petrochemical complexes for specialized modifiers. Distribution runs through vertically integrated contractors with captive plant fleets, bulk terminal networks, and direct state DOT contracting relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward state transportation departments as performance-based contracting consolidates procurement volumes under fewer prime contractors with balance sheet capacity to absorb lifecycle warranty risk.
For Market Incumbents: Consolidate plant fleet capacity in EPA non-attainment zones where permit timelines stretch 18-36 months and smaller competitors face exit pressure. Acquire cold recycling equipment capabilities to meet Federal Highway Administration reclaimed asphalt pavement mandates. Backward integration into polymer modification secures specification-grade positioning as Superpave performance requirements tighten on interstate corridors. For New Entrants and Emerging Players: Equipment retrofit consulting for legacy drum-mix plants represents a service-layer gap where incumbents under-serve smaller contractors facing warm mix conversion deadlines. Target municipal street departments in mid-sized metropolitan areas bypassed by vertically integrated primes. Lead with engineering partnerships that de-risk plant modification timelines against performance guarantees. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among contractors holding multi-year performance-based highway rehabilitation contracts with state DOTs. Long-term viability hinges on environmental permit holdings and in-house materials testing capabilities. Watch for inflection signals in state-level recycled content mandate acceleration that would reposition cold recycling equipment as core infrastructure rather than optional capability.| Strategic Initiative | Industry Significance |
|---|---|
| Warm Mix Technology Licensing | EPA emissions compliance in non-attainment zones creates specification advantage for early adopters. |
| Polymer Modification Facility Expansion | Gulf Coast SBS supply concentration rewards captive production for Superpave-grade positioning. |
| Cold Recycling Equipment Deployment | Federal Highway Administration RAP targets accelerate contractor equipment refresh cycles. |
| Performance-Based Contracting Capability | Virginia and Florida DOT warranty programs compress bidding pools to qualified integrated operators. |
| Carbon Capture Integration Partnership | IRA 45Q credits for warm mix foaming systems create net-zero production pathway differentiation. |
Methodological Framework
Operator-level perspectives from asphalt plant managers, state DOT procurement officers, polymer modification chemists, and paving contractor executives anchored the qualitative base. Primary fieldwork combined with secondary validation from Federal Highway Administration recycled materials policy documents, EPA New Source Performance Standards filings, state DOT specification manuals, and AASHTO M320/M332 certification protocols. Bottom-up plant capacity estimates triangulated against top-down highway construction expenditure data.
Sensitivity analysis tested volume and value outputs across the projection horizon against crude price volatility scenarios and recycled content mandate acceleration curves. Segmentation dimensions modeled include product formulation temperature tier, application stress level, polymer modification grade, recycling technology adoption, and end-user procurement sophistication. CAGRs were derived from regression-weighted historical deployment rates projected through infrastructure spending authorization trajectories and emissions compliance deadline schedules.
Underlying assumptions cover steady-state refinery bitumen output decisions, state DOT budget authorization continuity, and polymer supply chain stability, with deviation risk concentrated in crude-linked input cost spikes and EPA permit timeline extensions. Recalibration cycles align with material shifts in federal infrastructure appropriations and state-level recycled content mandate revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Materials
Industrial Concrete Flooring Market
Building Materials
Europe Fiber Cement Market
Building Materials
North America Cement Market
Building Materials
Steel Products Market
Building Materials
Global Lightweight Aggregate Concrete Market
Building Materials
HDG Steel Pipe Market
Building Materials
Zinc Polycarboxylate Cement Market
Building Materials
Global Corrugated Steel Sheets Market
Building Materials
Fiber Reinforced Polymer Composites (FRP) Market
Building Materials
Masonry Cement Market
Building Materials
Spain Architectural Coatings Market
Building Materials
Saudi Arabia GRC Cladding Market
Building Materials
West Africa Cement Market
Building Materials
France Architectural Coatings Market
Building Materials
Construction Repair Composites Market
Building Materials
Dry Mix Mortar Market