
 Cementitious Waterproofing Market | 2026-2036
Cementitious Waterproofing Market Size, Share, and Industry Trends Forecast 2026-2036
Cementitious Waterproofing Market Outlook
Buyer concentration in the commercial construction sector is expanding as infrastructure megaprojects aggregate procurement decisions into fewer engineering-procurement-construction firms. Sika AG leverages its integrated mortar-admixture portfolio to anchor specification decisions across European transit projects. BASF SE sustains R&D intensity in crystalline capillary systems that penetrate concrete pore structures. Kryton International Inc. specializes in self-sealing formulations that differentiate its offering for water-retaining structures.
Cementitious waterproofing comprises Portland cement-based blends combined with active chemicals, quartz sand, and proprietary admixtures that react with concrete moisture to form insoluble crystalline structures blocking water ingress; these systems achieve 1.5–2.0 MPa bond strength to substrates and serve primarily to protect below-grade and water-contacting concrete elements from hydrostatic pressure damage. Liquid formulations lead specification volumes for complex geometries while ready-mix products capture margin pools through contractor labor savings on large horizontal surfaces. Powder segments dominate emerging-market distribution where site mixing controls material costs, and grout applications are accelerating in tunnel segment joint sealing.
REACH compliance in Europe mandates disclosure of crystalline silica content, while EPA stormwater regulations in the United States shape below-grade specification standards for runoff containment. India's BIS certification requirements for waterproofing admixtures create market-access thresholds for imported formulations. Stakeholders must monitor regulatory divergence between crystalline admixture classifications and membrane-equivalent performance standards as specification committees revise building codes.
Market Dynamics
Crystalline waterproofing chemistry is restructuring competitive advantage as contractors abandon sheet-membrane systems for integral concrete protection, compressing installation timelines and reshaping specification authority toward admixture suppliers.
Growth Catalysts
- India's urban corridor buildout:Metro rail and smart city mandates under the Ministry of Housing and Urban Affairs are aggregating waterproofing procurement into centralized engineering-procurement-construction packages.
- REACH crystalline silica disclosure:ECHA transparency requirements are accelerating substitution toward low-silica crystalline formulations that penetrate concrete pore structures without hazardous classification.
- Below-grade hydrostatic pressure standards:Rising water table exposure in coastal megaprojects is mandating crystalline admixtures for basements and tunnels.
Market Restraints
- White cement supply concentration:Production clusters in Turkey and Egypt create input cost volatility for light-colored architectural waterproofing blends.
- Sheet-membrane incumbent resistance:Established roofing contractors with membrane installation equipment delay crystalline specification adoption.
- BIS certification timelines:India's Bureau of Indian Standards testing protocols extend market entry for imported crystalline admixtures by 8-14 months.
Strategic Opportunities
- Vietnam's subway expansion:Ho Chi Minh City Metro and Hanoi urban rail projects represent untapped specification volume for tunnel segment joint grouting.
- Green building certification convergence:LEED v4.1 and BREEAM alignment on embodied carbon scoring creates preference for cementitious systems over petroleum-derived membranes.
- Digital specification platforms:Building information modeling libraries are displacing traditional distributor relationships for contractor material selection.
Industry Challenges
- Crystalline chemistry formulation expertise:Shortage of concrete technologists capable of calibrating pore-blocking admixture dosages for variable aggregate quality.
- Multi-standard compliance:Divergent performance testing between ASTM hydrostatic head methods and EN water permeability coefficients complicates cross-border product positioning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cementitious Waterproofing Market |
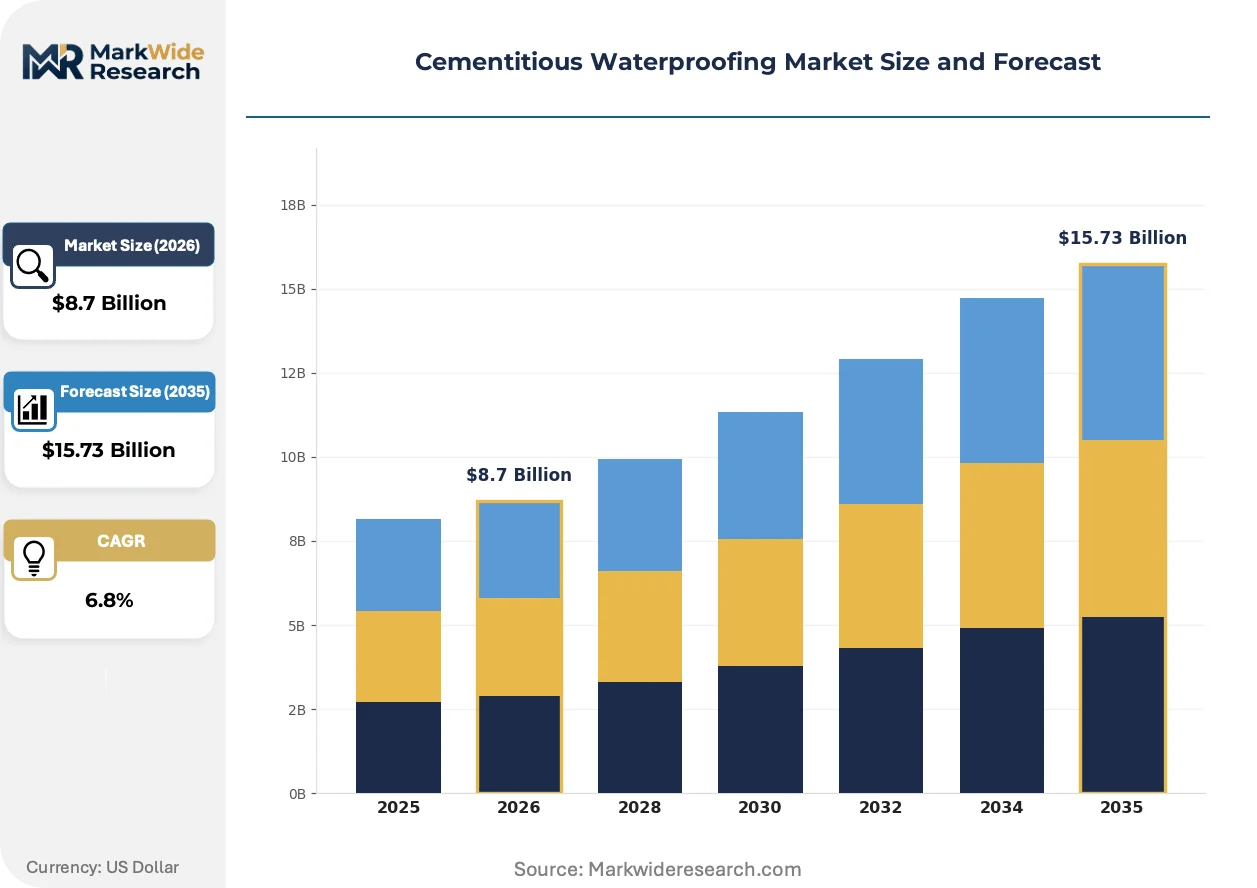
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid, Powder, Ready-Mix, Grout Application: Basement, Swimming Pool, Roof, Foundation End User: Construction, Infrastructure, Residential, Commercial Distribution Channel: Direct Sales, Retail, Online, Distributors |
| Companies Covered | Fosroc International Ltd, GCP Applied Technologies Inc., Sika AG, Tremco Incorporated, Kryton International Inc., BASF SE, Saint-Gobain, Cemex S.A.B. de C.V., Mapei S.p.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cementitious Waterproofing Market Strategic Shifts
Specification authority is migrating from general contractors to concrete producers as crystalline admixtures become integral to mix design rather than applied finishes, compressing traditional waterproofing trade boundaries.
Hybrid crystalline-polymer systems are modularizing application protocols for complex geometries. Transit authorities in Germany and Japan specify these formulations for station box structures where traditional sheet membranes fail at re-entrant corners. The technology is modularizing contractor skill requirements, enabling general concrete crews to execute waterproofing without specialized membrane installation certification.
EPA stormwater regulations under the Clean Water Act are tightening below-grade containment standards for commercial development. Runoff coefficient mandates now require permeability testing documentation for foundation systems. Below-grade applications in Florida and coastal California face the strictest enforcement, driving specification toward crystalline systems with certified ASTM D7088 performance data.
Engineering-procurement-construction firms are consolidating material procurement through captive concrete supply agreements. Skanska and Bechtel project portfolios now specify ready-mix with pre-dosed crystalline admixtures, bypassing traditional waterproofing subcontractors. This concentration is most visible in China's state-owned construction enterprises and India's National Highways Authority contracts, where single-source concrete procurement reduces interface liability.
Cementitious Waterproofing Market Segmentation
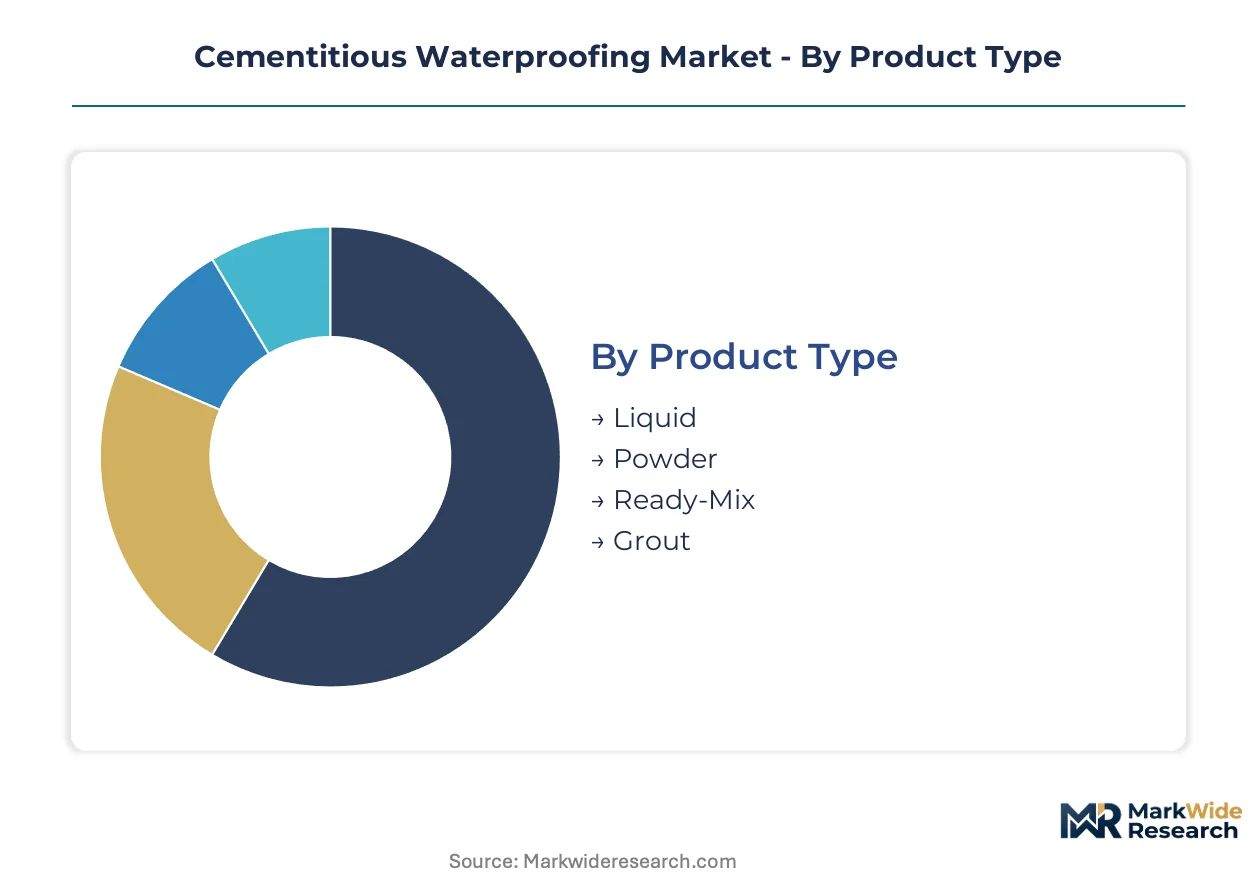
Crystalline chemistry is fragmenting specification authority across product formats, while application complexity and procurement scale reshape channel economics. Understanding how these dimensions intersect reveals where margin pools concentrate and where substitution risks emerge.
Product Type:
Specification authority migrates toward formats that compress installation labor or integrate into concrete production workflows.
- Liquid:Solvent-free and water-based formulations penetrate complex geometries and re-entrant corners where sheet membranes fail. Demand clusters in German and Japanese transit station boxes where hybrid crystalline-polymer systems replace traditional applied finishes.
- Ready-Mix:Pre-dosed crystalline admixtures supplied through captive concrete agreements eliminate waterproofing subcontractor interfaces. Skanska and Bechtel project portfolios specify this format for below-grade hydrostatic pressure protection.
- Powder:Site-mixed blends dominate emerging-market distribution where contractors control material costs through local sourcing.
- Grout:Tunnel segment joint sealing applications are accelerating in Vietnam's Ho Chi Minh City Metro and Hanoi urban rail projects.
Liquid leads on scale; grout leads on momentum.
Application:
Water table exposure and hydrostatic pressure severity determine specification intensity and compliance documentation requirements.
- Basement:Coastal megaprojects in Florida and California face EPA stormwater mandates requiring ASTM D7088 certified permeability data. Rising water tables are mandating crystalline admixtures over conventional membranes.
- Foundation:Below-grade containment standards under the Clean Water Act tighten runoff coefficient requirements for commercial development.
- Swimming Pool:Water-retaining structures favor self-sealing formulations that autogenously heal micro-cracks under continuous immersion.
- Roof:Sheet-membrane incumbents with installed equipment bases delay crystalline adoption in exposed horizontal applications.
Basement leads on scale; foundation leads on momentum.
End User:
Procurement concentration and project scale reshape whether specification authority rests with concrete producers or applied-finish contractors.
- Infrastructure:Metro rail and smart city mandates under India's Ministry of Housing and Urban Affairs aggregate waterproofing into centralized engineering-procurement-construction packages.
- Commercial:Engineering-procurement-construction firms consolidate material procurement through single-source concrete agreements, bypassing traditional waterproofing subcontractors.
- Construction:General contractors with membrane installation equipment resist crystalline specification shifts that obsolete capital investments.
- Residential:Smaller-scale projects retain distributor relationships for powder and liquid formats where site mixing controls costs.
Infrastructure leads on scale; commercial leads on momentum.
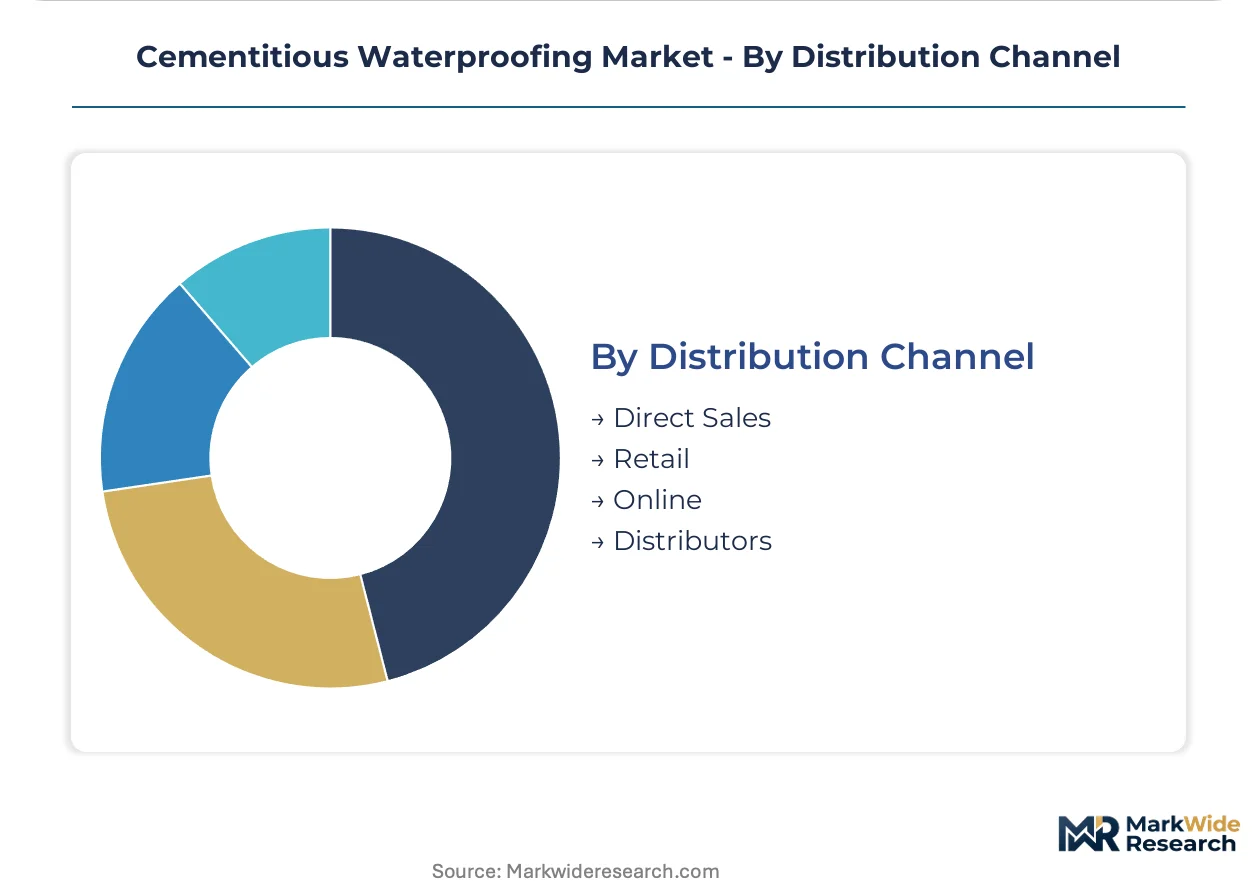
Distribution Channel:
Digital platforms and captive supply agreements are displacing traditional distributor relationships for contractor material selection.
- Direct Sales:Building information modeling libraries enable specification locking before traditional distributor engagement. China's state-owned construction enterprises and India's National Highways Authority contracts favor direct concrete procurement.
- Distributors:Powder segments depend on regional stocking for emerging-market contractors managing site-mixed material costs.
- Retail:Smaller residential and maintenance applications access liquid and powder formats through construction material merchants.
- Online:Digital specification platforms are capturing technical documentation and certification data for compliance-driven procurement.
Direct sales leads on scale; online leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's urban corridor buildout generates procurement volumes that exceed Germany's transit infrastructure renewal, yet both markets crystallize specification authority around engineering-procurement-construction consolidation.
India
Metro rail expansion under the Ministry of Housing and Urban Affairs and smart city mandates concentrate waterproofing procurement into centralized packages. BIS certification requirements for waterproofing admixtures create eight-to-fourteen month market entry timelines for imported formulations. Mumbai and Delhi-NCR anchor demand clusters where state-owned construction enterprises specify ready-mix with pre-dosed crystalline admixtures.
Germany
Transit station box structures and below-grade hydrostatic pressure protection drive specification intensity for hybrid crystalline-polymer systems. ECHA REACH compliance mandates crystalline silica disclosure, accelerating substitution toward low-silica formulations. The Rhine-Ruhr metropolitan region concentrates engineering-procurement-construction procurement through captive concrete supply agreements that bypass traditional waterproofing subcontractors.
United States
EPA stormwater regulations under the Clean Water Act tighten below-grade containment standards for commercial development in Florida and coastal California. ASTM D7088 certified permeability documentation is now mandatory for foundation systems facing rising water table exposure. Miami and Los Angeles metropolitan areas face strictest enforcement, driving specification toward crystalline systems with certified performance data.
China
Subway expansion programs and state-owned construction enterprise consolidation reshape procurement through single-source concrete agreements. GB standards for waterproofing materials intersect with dual carbon goals that favor cementitious systems over petroleum-derived membranes. Beijing-Tianjin-Hebei and Yangtze River Delta clusters concentrate specification authority within centralized engineering-procurement-construction frameworks.
Vietnam
Ho Chi Minh City Metro and Hanoi urban rail projects represent emerging specification volume for tunnel segment joint grouting applications. National infrastructure investment frameworks prioritize localized material sourcing for cost control. The Red River Delta and Southeast economic regions concentrate contractor procurement decisions through distributor relationships for powder and liquid formats.
Cementitious Waterproofing Market Competitive Environment
European producers anchor the premium formulation tier; Asia-Pacific specialists hold emerging-market distribution networks through regional stocking partnerships. The vendor base organizes around three strategic archetypes: integrated chemical conglomerates with mortar-admixture portfolios, crystalline chemistry specialists with self-sealing intellectual property, and construction materials multinationals with captive concrete supply channels. Competitive moves concentrate on backward integration into white cement sourcing and technology licensing for low-silica crystalline formulations.
Within the integrated chemical tier, Sika AG and BASF SE exemplify specification authority through combined admixture-masonry portfolios that lock engineering-procurement-construction decisions early in project design phases. Kryton International Inc. occupies a specialist position anchored on crystalline chemistry expertise for water-retaining structures. These three entities represent distinct competitive vectors: geographic coverage depth, research intensity in capillary-pore systems, and application-specific formulation focus.
| Leading Market Players |
|---|
| Fosroc International Ltd |
| GCP Applied Technologies Inc. |
| Sika AG |
| Tremco Incorporated |
| Kryton International Inc. |
| BASF SE |
| Saint-Gobain |
| Cemex S.A.B. de C.V. |
| Mapei S.p.A. |
| Others |
Value Chain & Pricing Dynamics
Concrete technologist shortages in Germany's Rhine-Ruhr corridor compress premium-tier spreads against emerging-market powder formats, as labor-cost differentials between captive ready-mix supply and site-mixed application widen pricing stratification across certification grades.
Pricing Analysis
Capacity additions in Turkey and Egypt are reshaping price floors for white cement architectural blends, intensifying cost compression in light-colored formulations. Three-tier pricing structure across premium crystalline-polymer hybrids, standard liquid membranes, and economy powder segments separates ASTM-certified hydrostatic performance from basic BIS-compliant admixtures. Pricing pressure stems from REACH-mandated low-silica formulation shifts that elevate R&D recovery costs. Infrastructure contractors with captive concrete agreements exhibit lowest price sensitivity; residential distributors face acute margin compression.
Supply Chain Analysis
Single-source vulnerability sits with Egyptian and Turkish white cement clusters that feed architectural waterproofing production. Raw material dependencies center on Portland cement grades, quartz sand purity specifications, and proprietary crystalline activator chemicals. Tariff exposure on Turkish cement imports into India disrupts cost structures for light-colored formulations. Distribution runs through engineering-procurement-construction captive agreements for ready-mix volumes, while powder segments rely on regional distributor stocking partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Crystalline chemistry specialization unlocks margin expansion as specification authority migrates toward admixture-integrated concrete producers, compressing traditional waterproofing subcontractor value capture.
For Market Incumbents: Anticipate hybrid crystalline-polymer substitution accelerating in transit infrastructure as German and Japanese authorities modularize contractor skill requirements. Defend specification lock-in through backward integration into white cement sourcing for architectural grades. Deepen BIM library penetration to preempt distributor-based material selection. For New Entrants and Emerging Players: Capture Vietnam's tunnel segment joint grouting demand as Ho Chi Minh City Metro and Hanoi urban rail projects aggregate procurement volumes. Target India's BIS certification gap for imported formulations, where eight-to-fourteen month entry timelines strand foreign competitors. Lead with liquid format technical service capabilities to displace site-mixed powder incumbents. For Investors and Strategic Acquirers: Valuations sit cheapest among regional crystalline chemistry specialists with water-retaining structure intellectual property and limited geographic footprint. Long-term viability hinges on formulation expertise scarcity as concrete producers internalize waterproofing specification authority. Watch ECHA REACH low-silica substitution mandates as inflection indicator for R&D-intensive acquisition premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into White Cement Sourcing | Turkish and Egyptian production clusters reduce input cost volatility for architectural blends. |
| Low-Silica Crystalline Formulation Licensing | ECHA REACH compliance accelerates substitution away from hazardous silica classifications. |
| BIM Library Specification Lock-In | Digital platforms displace traditional distributor relationships for contractor material selection. |
| Captive Concrete Supply Agreements | Skanska and Bechtel portfolios bypass waterproofing subcontractors through pre-dosed admixture contracts. |
| Tunnel Segment Joint Grouting Specialization | Vietnam's Ho Chi Minh City Metro creates untapped specification volume for grout applications. |
Study Parameters
Coverage spans India, Germany, the United States, China, and Vietnam, with primary inputs from each market's engineering-procurement-construction procurement directors, concrete plant managers, waterproofing subcontractor technical leads, and regulatory compliance officers. Secondary validation draws from BIS certification records, ECHA REACH substance databases, EPA stormwater enforcement documentation, and customs trade data for white cement flows. Bottom-up project pipeline aggregation triangulates against top-down construction spending forecasts.
Rate-of-change decomposition separates volume effects from mix-shift toward higher-value crystalline admixtures across the analysis window. Segmentation dimensions encompass product format, application severity, end-user procurement concentration, and regional regulatory cluster. CAGRs derive from installed base erosion models for sheet-membrane systems and crystalline chemistry penetration curves. Forecast inputs include water table exposure projections for coastal megaprojects and transit infrastructure investment commitments.
Regulatory timeline slippage, crystalline silica substitution cost shocks, and white cement supply disruption are the dominant revision risks to modeled outcomes. Forecasts reflect documented assumptions about specification authority migration speed and EPC procurement consolidation trajectories. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Materials
North America Building and Construction Sheets Market
Building Materials
Europe Acrylic Resin Dispersion Based Primers in Construction Market
Building Materials
Europe Concealed Cistern Market
Building Materials
Polymer-Modified Cementitious Mortar Market
Building Materials
Cement Board Market
Building Materials
Thermoplastic Composite Exterior Clips and Brackets Market
Building Materials
Europe Fireproof Cladding Market
Building Materials
China Cement Market
Building Materials
Middle East and Africa Concrete Admixtures Market
Building Materials
Italy Cement Market
Building Materials
Lightweight Cellular Concrete Market
Building Materials
Foam Concrete Market
Building Materials
North America Architectural Coatings Market
Building Materials
Thin Brick Market
Building Materials
Engineered Stone Market
Building Materials
Foam Bricks Market