
 ASEAN Dry Mix Mortar Market | 2026-2036
ASEAN Dry Mix Mortar Market Size, Share, and Industry Trends Forecast 2026-2036
ASEAN Dry Mix Mortar Market Outlook
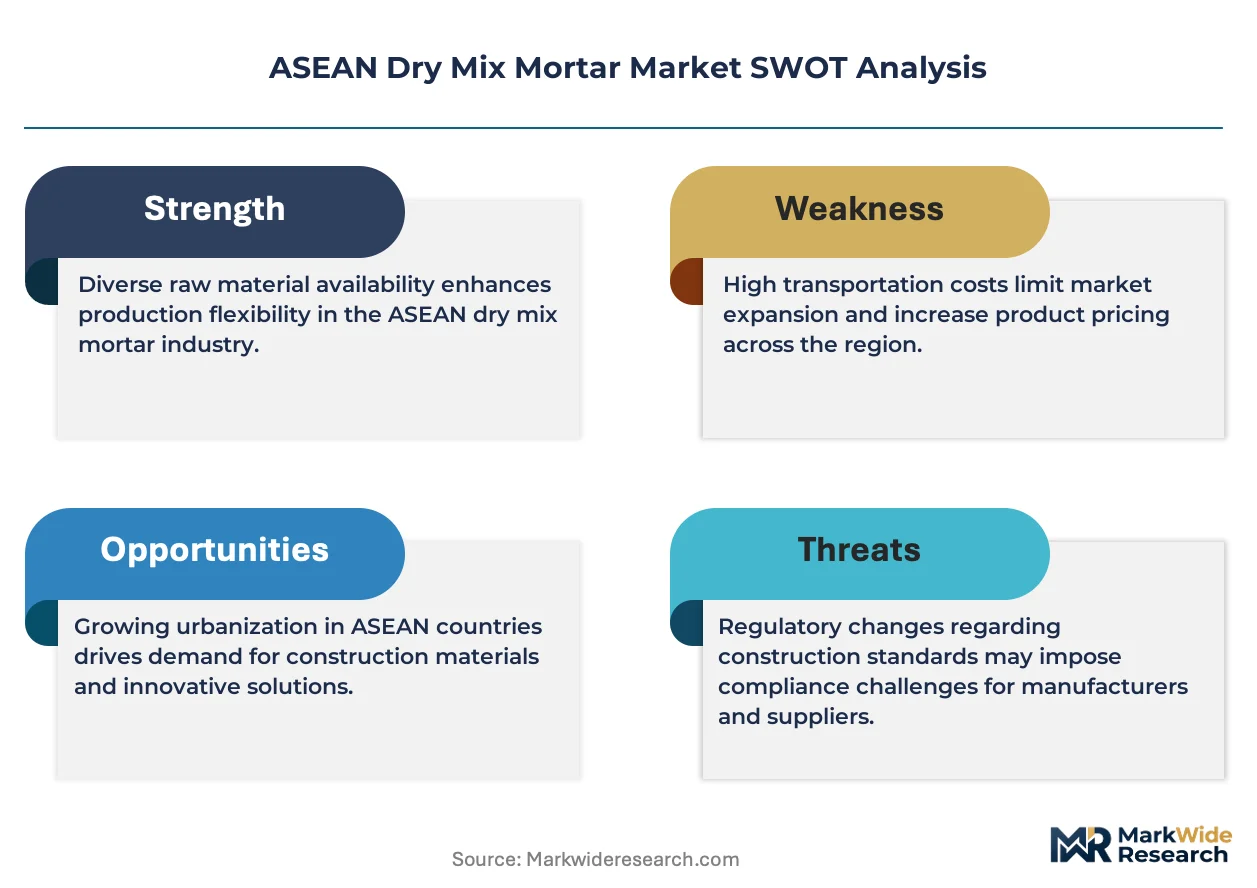
The gap between premium polymer-modified formulations and commodity cement-based mortars is consolidating as a defining market fracture. Knauf Gips KG leverages its gypsum expertise to anchor premium plastering systems across Thailand and Malaysia. Sika AG competes through specialized waterproofing-adhesive hybrids that dominate high-specification commercial facades. Greco Asia Sdn Bhd sustains a cost-focused position in bulk masonry mortars for Indonesia's residential sector.
Dry mix mortar consists of precisely graded sand, cementitious binders, and functional additives blended in controlled ratios to deliver consistent performance when site-mixed with water; polymer redispersible powders typically constitute two to eight percent by weight in premium grades to enhance adhesion and flexibility. Tile adhesives command the deepest margin pools as large-format porcelain gains share across ASEAN residential towers. Self-leveling compounds represent the fastest-expanding product category, driven by precision flooring demands in Vietnam's electronics manufacturing zones. Masonry mortars remain structurally mature, with volume anchored in Indonesia's low-rise housing belt where price sensitivity limits additive penetration.
Thailand's Industrial Standards Institute, Indonesia's SNI certification body, and Vietnam's Directorate for Standards and Quality each enforce compressive strength and emissions benchmarks that filter substandard imports from regional trade flows. Green building rating tools including Singapore's Green Mark and Indonesia's Greenship are tightening VOC thresholds, redirecting procurement toward certified low-emission mortar systems. Stakeholders must monitor how divergent national certification timelines reshape cross-border product registration costs and local formulation partnerships.
Market Dynamics
The ASEAN dry mix mortar sector is bifurcating around polymer-modified premium formulations versus commodity cement-based grades, with prefabrication adoption in residential towers compressing traditional site-mix practices and forcing reformulation investments.
Growth Catalysts
- Green building code tightening:Singapore's Green Mark and Indonesia's Greenship are mandating VOC thresholds that redirect procurement toward certified low-emission systems.
- Electronics manufacturing precision flooring:Vietnam's northern industrial corridor is absorbing self-leveling compounds for cleanroom specifications in semiconductor assembly plants.
- Tile adhesive specification upgrades:Large-format porcelain installation in Bangkok and Jakarta high-rises is displacing conventional thin-set methods with polymer-enhanced alternatives.
Market Restraints
- Cement price volatility:Input cost swings from clinker supply disruptions in Vietnam and Indonesia compress margin predictability for commodity-grade producers.
- Import filtration via national standards:Thailand's Industrial Standards Institute and Indonesia's SNI certification body enforce compressive strength benchmarks that block substandard regional imports.
- Site-mix substitution persistence:Informal construction labor in Indonesia's low-rise housing belt continues using traditional sand-cement hand mixing despite quality inconsistency.
Strategic Opportunities
- Waterproofing-adhesive hybrid expansion:Tropical climate exposure in Manila and Ho Chi Minh City is creating specification pull for dual-function systems in podium-level facades.
- Cement-reduced binder innovation:Supplementary cementitious material blends are opening formulation partnerships with industrial waste suppliers in Malaysia's steel and power sectors.
- Prefabrication integration partnerships:Panelized construction growth in Thailand's Eastern Economic Corridor is creating captive demand for factory-preconditioned mortar systems.
Industry Challenges
- Polymer redispersible powder formulation expertise:Two to eight percent additive optimization requires chemists scarce in Vietnam's domestic talent pool.
- Cross-border product registration divergence:Divergent SNI, TISI, and STAMEQ certification timelines are fragmenting regional brand consolidation strategies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | ASEAN Dry Mix Mortar Market |
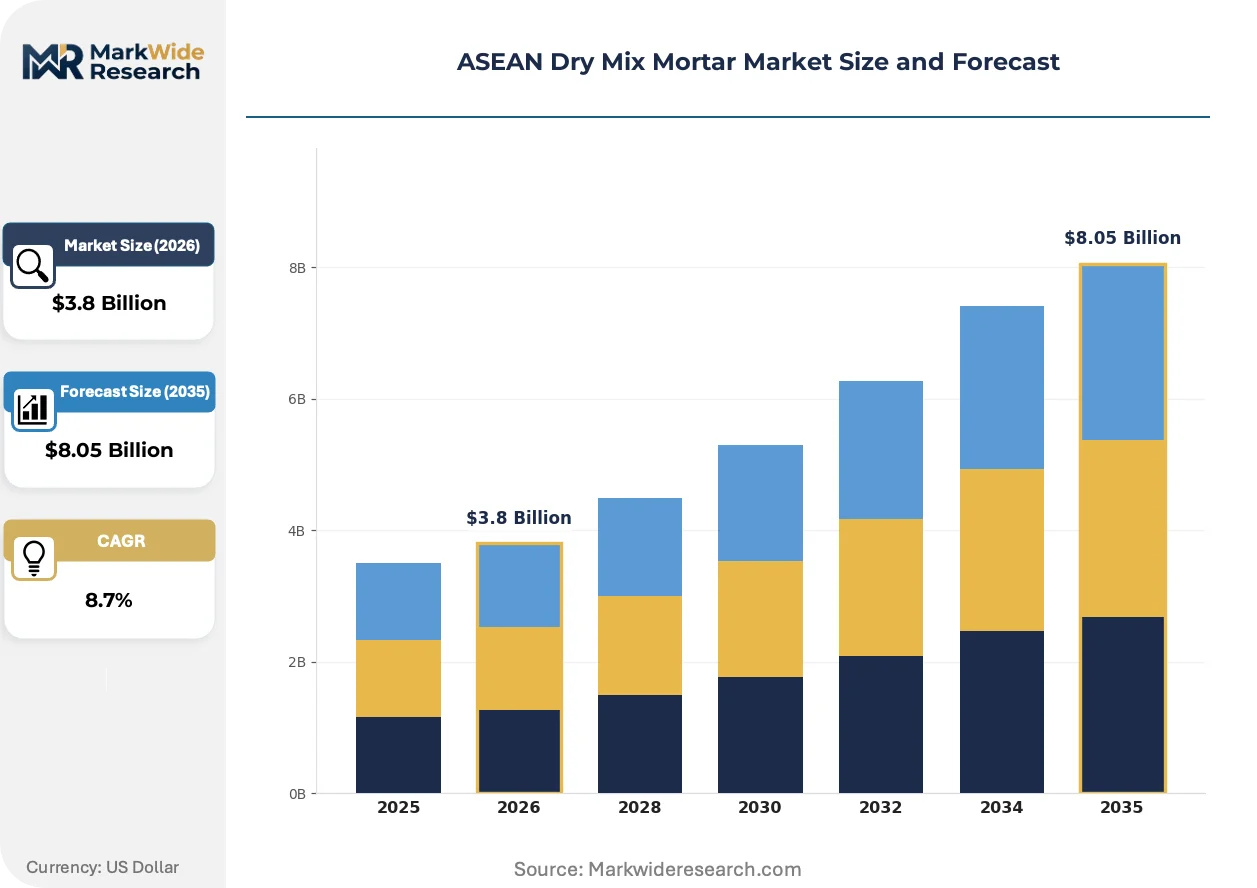
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tile Adhesives, Masonry Mortars, Plastering Mortars, Self-Leveling Compounds End User: Residential Construction, Commercial Construction, Industrial Construction, Infrastructure Projects Distribution Channel: Direct Sales, Distributors, Retail Stores, Online Sales Application: Interior Walls, Exterior Walls, Floors, Facades |
| Companies Covered | Knauf Gips KG, Ardex Group, Henkel AG & Co KGaA, Saint-Gobain, MAPEI S p A, Greco Asia Sdn Bhd, Sika AG, Siam City Cement Group, PT Indocement Tunggal Prakarsa Tbk, Others |
| Regions Covered | Southeast Asia: Indonesia, Thailand, Vietnam, Philippines, Malaysia, Singapore, Myanmar, Cambodia, Rest of Southeast Asia |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
ASEAN Dry Mix Mortar Market Strategic Shifts
Digital batching and quality control systems are penetrating ASEAN mortar plants, compressing batch-to-batch variability while enabling just-in-time delivery models for large-scale residential developers.
Automated dry mix blending with integrated moisture sensing and real-time particle grading is automating quality assurance previously dependent on manual sampling. Thailand's leading plastering system suppliers are retrofitting plants with these sensor arrays. The technology is automating workforce reduction in high-wage Malaysian facilities while enabling 24-hour continuous production cycles.
Indonesia's SNI certification body and Vietnam's Directorate for Standards and Quality are synchronizing compressive strength testing protocols with ASEAN harmonization frameworks. This regulatory convergence is streamlining cross-border product registration for multinational suppliers. Thailand and Malaysia manufacturers are responding by consolidating regional formulation platforms to serve multiple national markets from single production bases.
Large-format tile contractors in Jakarta and Ho Chi Minh City are consolidating procurement through direct manufacturer relationships, bypassing traditional distributor markups. This channel compression is squeezing regional trading houses that previously dominated bulk masonry mortar flows. The shift is most visible in Vietnam's northern industrial corridor where electronics factory developers specify adhesive grades through engineering-procurement-construction consortiums rather than open market sourcing.
ASEAN Dry Mix Mortar Market Segmentation
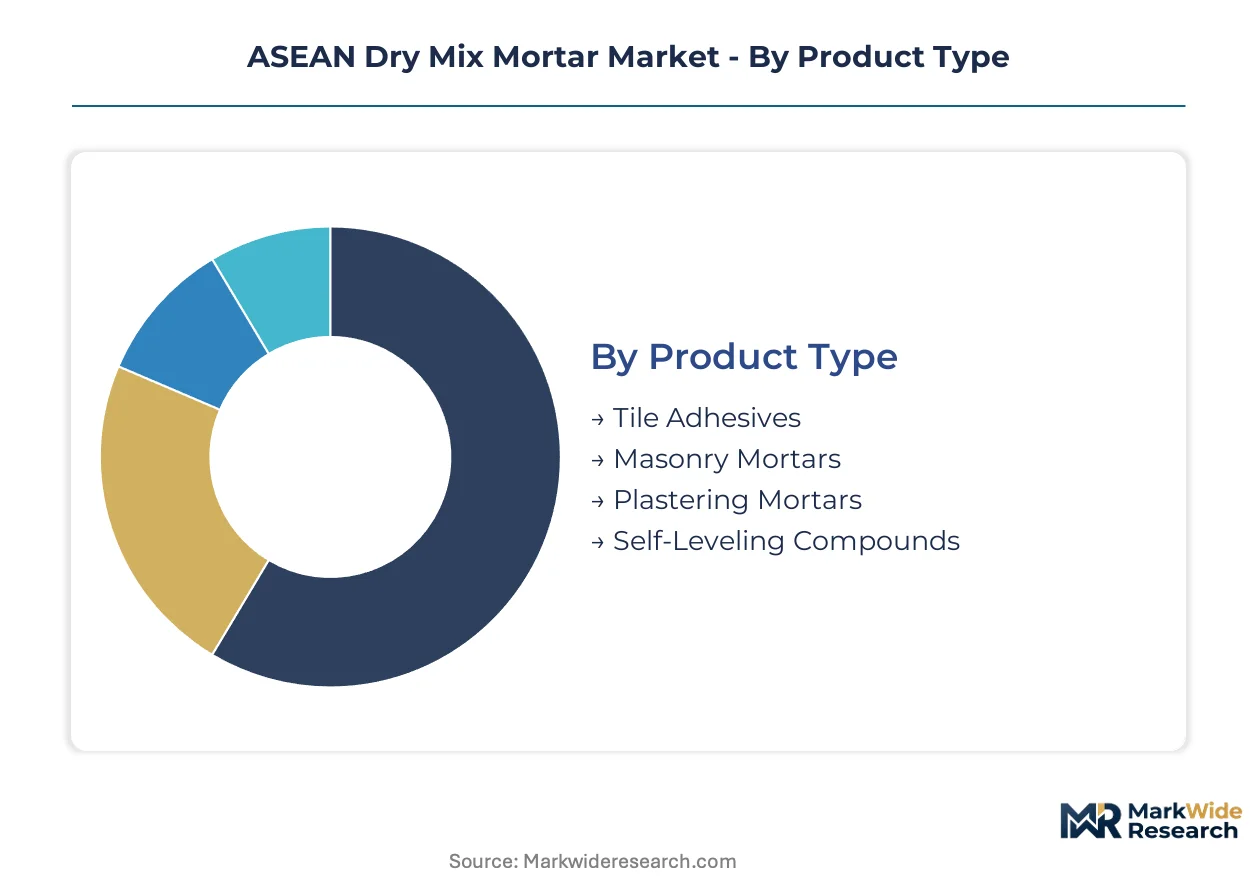
Dry mix mortar segmentation in ASEAN reflects divergent capital requirements across formulation complexity and distribution infrastructure. Product categories separate sharply around polymer modification levels, while end-user segments track construction cycle volatility and specification intensity.
Product Type:
Capital intensity escalates with additive sophistication and quality control systems required for consistent batch performance.
- Tile Adhesives:Polymer-modified formulations incorporate two to eight percent redispersible powders by weight to bond large-format porcelain in Bangkok and Jakarta high-rises. Vietnam's electronics manufacturing zones specify these grades for cleanroom flooring where precision tolerances exclude conventional thin-set alternatives.
- Self-Leveling Compounds:These cementitious or gypsum-based systems flow to create flat substrates for subsequent flooring installation. Northern Vietnam's semiconductor assembly plants absorb volumes for subfloor preparation where laser-leveling requirements dominate procurement specifications.
- Masonry Mortars:Bulk cement-sand blends serve Indonesia's low-rise housing belt with minimal additive penetration.
- Plastering Mortars:Gypsum and cement-lime formulations finish interior and exterior wall surfaces across Thailand's prefabrication growth corridors.
Masonry mortars absorb the bulk of installed capacity; self-leveling compounds are expanding most quickly.
End User:
Application scale and specification stringency determine procurement channel selection and margin capture potential.
- Residential Construction:Indonesia's Greater Jakarta region and Vietnam's urban corridors drive tile adhesive consumption as high-rise towers displace traditional low-rise development. Prefabrication adoption in Thailand compresses site-mix practices and forces packaged mortar conversion.
- Commercial Construction:High-specification facades in Manila and Ho Chi Minh City specify waterproofing-adhesive hybrids for podium-level exposure to tropical climate stress.
- Industrial Construction:Electronics manufacturing facilities in Vietnam's northern industrial corridor demand precision flooring systems with compressive strength and emissions certifications.
- Infrastructure Projects:Government-backed transportation and utility construction across ASEAN member states anchors bulk masonry mortar volumes with price-sensitive procurement.
Residential construction commands the deepest specification pools; industrial construction is climbing the fastest on precision flooring demand.
Distribution Channel:
Channel economics shift with batch size requirements and technical support intensity for specification-grade products.
- Direct Sales:Large-format tile contractors in Jakarta and Ho Chi Minh City consolidate procurement through manufacturer relationships, bypassing distributor markups for volume commitments.
- Distributors:Regional trading houses retain bulk masonry mortar flows to Indonesia's low-rise housing belt where fragmented contractor bases resist direct engagement.
- Retail Stores:Small-project and renovation demand in Thailand and Malaysia accesses bagged products through construction material retailers with limited technical consultation.
- Online Sales:Digital procurement platforms emerge for standardized grades where specification risk is minimal and logistics integration matures.
Distributors retain the widest geographic coverage; direct sales channels are gaining share fastest among specification-grade segments.
Application:
Exposure conditions and aesthetic requirements dictate formulation selection and performance certification needs.
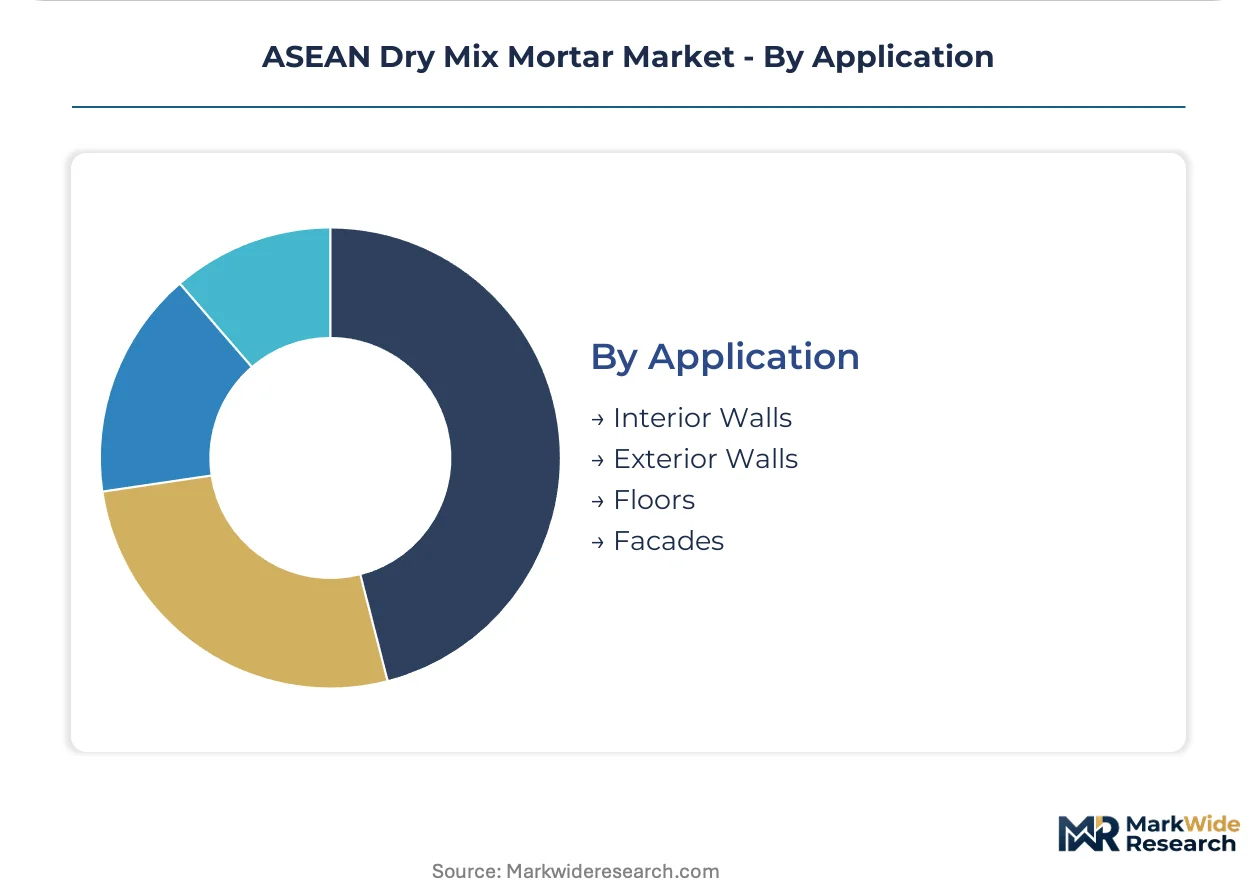
- Interior Walls:Gypsum-based plastering systems dominate Thailand and Malaysia where Knauf Gips KG anchors premium positioning through controlled indoor environment performance.
- Exterior Walls:Cement-based renders with waterproofing additives withstand tropical humidity and monsoon exposure across the archipelago geography of Indonesia and Philippines.
- Floors:Self-leveling compounds and tile adhesives concentrate in Vietnam's manufacturing zones and ASEAN commercial tower podiums where flatness tolerances drive specification.
- Facades:Podium and cladding applications in Singapore and Bangkok integrate waterproofing-adhesive hybrids for dual-function performance under Green Mark and Greenship thresholds.
Interior wall applications anchor volume scale; facade applications are expanding most quickly on green code tightening.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Greater Jakarta anchors ASEAN dry mix mortar consumption, absorbing bulk masonry mortars for Indonesia's sprawling low-rise residential belt while Thailand's Eastern Economic Corridor drives prefabrication-linked premium plastering demand.
Indonesia
Greater Jakarta and Surabaya's industrial zones absorb bulk masonry mortars for low-rise housing construction where price sensitivity limits polymer penetration. SNI certification requirements enforce compressive strength benchmarks that filter substandard imports from regional trade flows. Batam's manufacturing corridor is seeing specification-grade tile adhesive uptake as electronics assembly facilities expand flooring precision requirements.
Thailand
Bangkok's high-rise residential towers specify polymer-modified tile adhesives for large-format porcelain installation as prefabrication methods displace site-mix practices. The Industrial Standards Institute enforces BIS-equivalent national standards that redirect procurement toward certified low-emission systems. The Eastern Economic Corridor is absorbing factory-preconditioned mortar systems from panelized construction growth.
Vietnam
Hanoi's northern industrial corridor demands self-leveling compounds for semiconductor cleanroom flooring where laser-leveling tolerances exclude conventional alternatives. The Directorate for Standards and Quality synchronizes compressive strength protocols with ASEAN harmonization frameworks. Hai Phong's port-linked manufacturing zones are seeing direct procurement consolidation through engineering-procurement-construction consortiums.
Singapore
Green Mark rating tools mandate VOC thresholds that redirect commercial facade procurement toward certified low-emission mortar systems. Building and Construction Authority regulations tighten emissions benchmarks for podium-level waterproofing applications. Jurong's industrial district is specifying cement-reduced binder formulations for infrastructure durability requirements.
Malaysia
Johor's Iskandar development corridor absorbs gypsum-based plastering systems for controlled indoor environment performance in commercial and residential towers. SIRIM certification aligns with regional harmonization efforts to streamline cross-border product registration. Penang's electronics manufacturing belt is demanding precision flooring systems with emissions certifications for cleanroom specifications.
ASEAN Dry Mix Mortar Market Competitive Environment
Premium-margin players sit above commodity-margin players across formulation sophistication and certification depth, with polymer-modified specialists commanding specification-grade pricing while bulk cement-sand blenders compete on volume scale. The vendor base organizes around three strategic archetypes: European multinationals with gypsum and waterproofing expertise, regional cement majors leveraging clinker integration, and Asian specialists focused on cost-optimized masonry grades. Competitive moves concentrate on backward integration into redispersible powder supply and captive distribution networks for large-project direct engagement.
Within the European multinational tier, Knauf Gips KG and Sika AG exemplify premium-formulation positioning through specialized plastering and waterproofing-adhesive hybrid expertise. Greco Asia Sdn Bhd occupies a cost-focused archetype serving Indonesia's price-sensitive residential sector with bulk masonry mortar volumes. These three entities represent the span from specification-grade premium capture to commodity-margin volume play across ASEAN national markets.
| Leading Market Players |
|---|
| Knauf Gips KG |
| Ardex Group |
| Henkel AG & Co KGaA |
| Saint-Gobain |
| MAPEI S p A |
| Greco Asia Sdn Bhd |
| Sika AG |
| Siam City Cement Group |
| PT Indocement Tunggal Prakarsa Tbk |
| Others |
Value Chain & Pricing Dynamics
Engineering-procurement-construction consortiums in Vietnam's northern industrial corridor anchor procurement power, compressing distributor markups and forcing manufacturers toward direct sales models with volume-based contract structures.
Pricing Analysis
Value-based pricing anchored to compressive strength certification and VOC compliance thresholds dominates specification-grade segments, separating SNI-certified premium formulations from uncertified commodity blends. Price differentiation rests on polymer modification levels and green building rating alignment, with Singapore's Green Mark and Indonesia's Greenship redirecting procurement toward certified low-emission systems. Pricing pressure stems from cement price volatility in Vietnam and Indonesia, compressing margin predictability for commodity-grade producers. Bulk masonry mortar buyers in Indonesia's low-rise housing belt exhibit highest price sensitivity, while semiconductor cleanroom developers in Vietnam's northern corridor accept premium positioning for precision flooring specifications.
Supply Chain Analysis
Reverse-logistics flows for bagged product returns and moisture-damaged inventory create working capital burdens for distributors serving Indonesia's fragmented contractor base. Manufacturing concentration centers on Thailand, Vietnam, and Indonesia, with clinker supply disruptions in Vietnam and Indonesia feeding raw material volatility. The supply chain draws from polymer redispersible powder imports, cementitious binders, and precisely graded sand sources. Single-source vulnerability in redispersible powder supply from European and Chinese producers creates formulation bottlenecks for premium-grade manufacturers. Distribution runs through regional trading houses for bulk masonry flows, while direct manufacturer relationships capture specification-grade segments in high-rise residential and industrial construction.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Polymer redispersible powder formulation expertise scarcity props pricing premiums, constraining capacity expansion for domestic Vietnamese producers and sustaining import dependency for specification-grade outputs.
For Market Incumbents: Deploy captive distribution networks to defend direct procurement relationships with EPC consortiums in Vietnam's northern industrial corridor. Backward integration into redispersible powder supply buffers formulation cost volatility from Chinese and European import dependency. Certification depth across Thailand's TISI, Indonesia's SNI, and Vietnam's STAMEQ protocols creates switching costs that entrench position against regional trading house competitors. For New Entrants and Emerging Players: The gap between premium polymer-modified formulations and economy cement-sand blends opens white-space targeting in Malaysia's Johor corridor and Indonesia's Batam manufacturing zone. Indonesia's low-rise housing belt remains penetrable for cost-optimized masonry grades with minimal additive content. Direct digital procurement platforms for standardized bagged products bypass incumbent distributor relationships in Thailand's renovation segment. For Investors and Strategic Acquirers: The window for entry favors regional cement majors with clinker integration and formulation partnership capabilities. Long-term viability hinges on green building code alignment across Singapore's Green Mark, Indonesia's Greenship, and Thailand's tightening VOC thresholds. Acquisition targets should demonstrate cross-border registration capabilities spanning multiple ASEAN certification bodies. The signal to watch is harmonization momentum in compressive strength testing protocols between Indonesia's SNI and Vietnam's Directorate for Standards and Quality.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Redispersible Powder Supply | Captive polymer sourcing buffers Thai and Vietnamese manufacturers from Chinese import volatility. |
| Green Certification Investment | Singapore's Green Mark and Indonesia's Greenship compliance unlocks premium facade specification pools. |
| Direct Sales Channel Expansion | Manufacturer-consortium relationships in Vietnam's northern corridor displace distributor markups. |
| Prefabrication Partnership Development | Thailand's Eastern Economic Corridor panelized construction creates captive factory-preconditioned demand. |
| Cross-Border Registration Consolidation | Harmonized ASEAN protocols streamline multi-market product approval for regional formulation platforms. |
Study Parameters
Multi-period observation of polymer modification adoption rates, certification penetration, and prefabrication construction volumes anchored the trend analysis, supplemented by interviews with plant managers at Thai and Vietnamese dry mix facilities, procurement leads at Indonesian residential developers, technical R&D directors at polymer additive suppliers, and distribution channel partners across Malaysia and Singapore. Secondary validation drew from customs and trade data tracking cement and polymer powder imports, SEC filings of multinational construction material suppliers, national standards body certification registries, and green building rating project databases. Bottom-up capacity and consumption estimates triangulated against top-down construction sector expenditure flows.
Segment-weighting approaches applied product type, end user vertical, and distribution channel dimensions across the projection horizon, with tile adhesive, self-leveling compound, and masonry mortar categories modeled separately. CAGRs derived from elasticity-adjusted construction output forecasts and substitution rate assumptions for site-mix displacement. Industry-specific inputs included clinker price volatility indices, SNI and TISI certification timeline data, and electronics manufacturing facility build-out pipelines in Vietnam's northern provinces.
Inputs from plant managers, procurement leads, and standards body registries were available through the study window; gaps in real-time polymer redispersible powder inventory levels and informal sector site-mix volume estimates introduce uncertainty bands around commodity-grade consumption forecasts. Forecasts reflect documented assumptions regarding green building code adoption velocity and prefabrication penetration rates. Material deviation in cement price volatility, regulatory harmonization momentum, or semiconductor capital expenditure cycles warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Materials
Rubbing Bricks Market
Building Materials
Saudi Arabia GRC Cladding Market
Building Materials
UK Aluminum Door and Window Market
Building Materials
Global Builders Joinery and Carpentry of Wood Market
Building Materials
Roofing and Insulation Market
Building Materials
Global Pozzolan Market
Building Materials
Construction Repair Composites Market
Building Materials
Global Glass Fiber Reinforced Concrete Market
Building Materials
United States White Cement Market
Building Materials
Cross Laminated Timber (CLT) Market
Building Materials
France Architectural Coatings Market
Building Materials
Zinc Polycarboxylate Cement Market
Building Materials
United Kingdom Architectural Coatings Market
Building Materials
Bio-Based Structural Wood Adhesives for Modular Construction Market
Building Materials
Asia-Pacific Building and Construction Sheets Market
Building Materials
Germany Aluminum Door and Window Market