
 India Roofing Market | 2026-2036
India Roofing Market Size, Share, and Industry Trends Forecast 2026-2036
India Roofing Market Outlook
Dealer networks in tier-three towns is fragmenting as direct-to-contractor digital platforms gain share. Hindalco Industries Ltd leverages its integrated aluminum supply chain to dominate premium metal roofing segments. Tata Bluescope Steel Private Limited anchors its position through specialized pre-painted steel solutions for industrial clients. JSW Steel competes aggressively on manufacturing scale, sustaining cost leadership across standardized product lines.
India roofing encompasses engineered systems designed to protect structures from precipitation, thermal radiation, and wind loads, typically fabricated from galvanized steel, aluminum-zinc alloys, clay, or fiber-reinforced cement with specified load-bearing capacities. These assemblies serve residential, commercial, and industrial buildings by ensuring waterproofing, insulation, and structural integrity over design lifespans. Metal roofing commands the fastest expansion trajectory driven by industrial warehouse construction and government infrastructure mandates. Clay tiles retain entrenched demand in premium residential applications across southern states where traditional aesthetics dominate buyer preference. Green roofs remain nascent but attract policy support under urban heat-island mitigation programs in select metropolitan jurisdictions.
BIS mandates govern material tensile strength, fire resistance ratings, and corrosion protection thresholds for all roofing products sold in India. The Bureau of Energy Efficiency supplements these standards through cool-roof specifications that shape product development priorities for manufacturers seeking public project eligibility. State-level municipal corporations enforce additional structural load certifications that vary across jurisdictions, complicating national distribution strategies. Stakeholders must monitor evolving state building codes and green certification requirements to anticipate compliance costs and product specification shifts.
Market Dynamics
Direct-to-contractor digital platforms are fragmenting traditional dealer networks across tier-three towns, compressing distribution margins and forcing incumbents to rebuild channel economics around project-scale procurement rather than stock-and-sell models.
Growth Catalysts
- PLI scheme for specialty steel:Production-linked incentives for coated steel are lowering input costs for domestic manufacturers, accelerating metal roofing substitution over traditional materials in industrial construction.
- Affordable housing pipeline:Central government mandates for low-cost urban housing are concentrating demand in tier-two cities where standardized metal roofing solutions achieve rapid deployment at scale.
- Cool-roof specifications:Bureau of Energy Efficiency thermal reflectance standards are creating eligibility requirements for public infrastructure tenders, pulling compliant product development from manufacturers.
Market Restraints
- Aluminum-zinc alloy import dependence:Domestic supply gaps for high-grade coating substrates expose manufacturers to LME price volatility and currency fluctuation risks.
- BIS certification timelines:Bureau of Indian Standards testing protocols for fire resistance and tensile strength extend product launch cycles by 8-14 months, freezing working capital in pipeline inventory.
- Clay tile artisan scarcity:Traditional roofing craft skills concentrate in southern states with limited inter-regional mobility, constraining premium residential project completion rates elsewhere.
Strategic Opportunities
- Rajasthan-Gujarat solar corridor:Integrated photovoltaic roofing systems for industrial warehouses in this zone combine generation assets with structural weatherproofing under single-installation contracts.
- Green roof mandates:Urban heat-island mitigation programs in Delhi NCR and Bengaluru are creating compliance-driven demand for vegetated assemblies with waterproofing substrate integration.
- Contractor platform aggregation:Digital procurement networks that consolidate small commercial project demand are enabling manufacturers to bypass fragmented dealer tiers and capture margin recovery.
Industry Challenges
- Structural engineer certification backlog:Municipal corporation load-bearing approvals for innovative metal profiles face inspector capacity constraints in Maharashtra and Tamil Nadu, delaying project handovers.
- Cool-roof testing infrastructure:Limited Bureau of Energy Efficiency accredited laboratories for solar reflectance index validation create bottlenecks for product qualification.
- Legacy asbestos remediation:Fiber-cement replacement cycles require specialized handling protocols that general roofing contractors lack, fragmenting service capabilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Roofing Market |
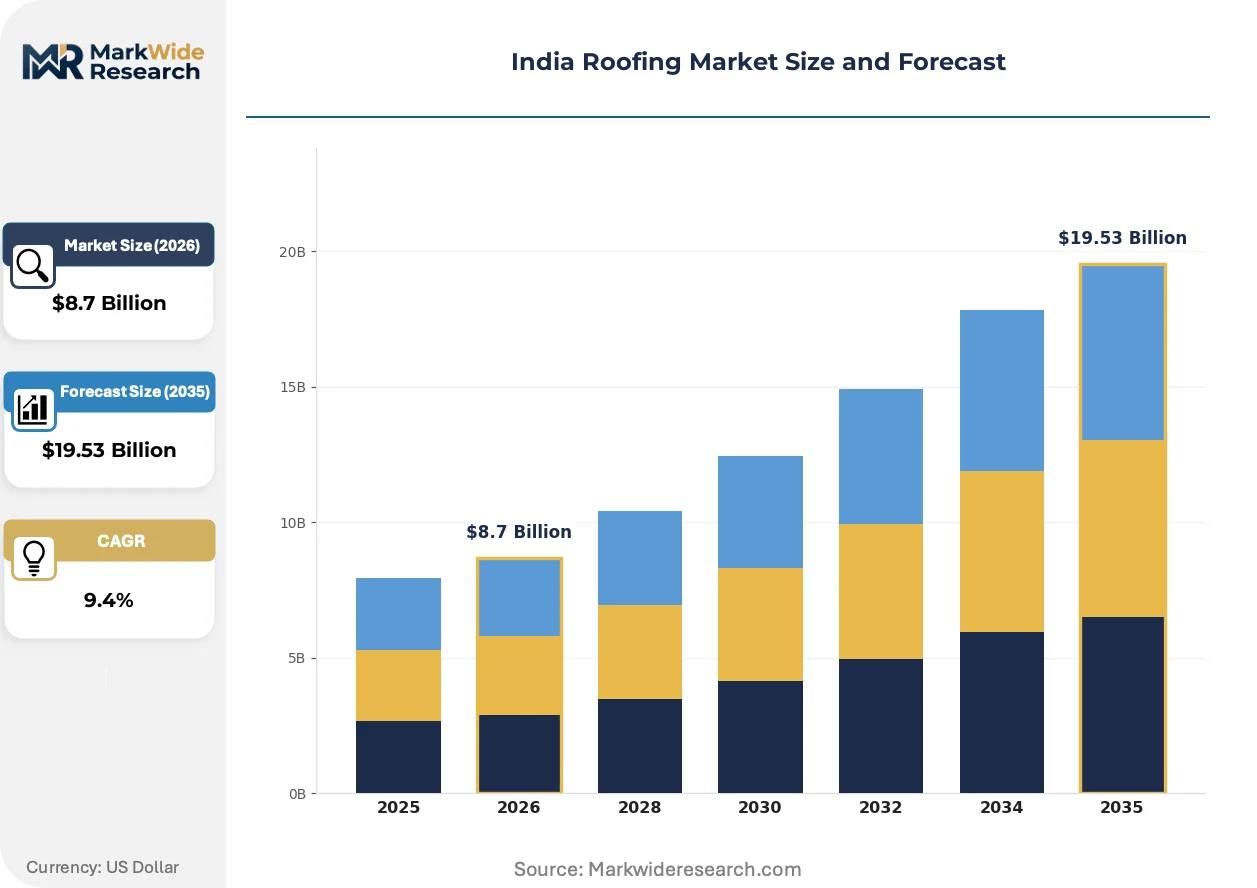
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Asphalt Shingles, Metal Roofing, Clay Tiles, Green Roofs Application: Residential, Commercial, Industrial, Agricultural Material: Concrete, PVC, Fiber Cement, Wood End User: Homeowners, Contractors, Builders, Developers |
| Companies Covered | Hindalco Industries Ltd, BirlaNu Limited, Tata Bluescope Steel Private Limited, Dion Incorporation, Visaka Industries Limited, JSW Steel, Bansal Roofing Products Limited, CK Birla Group, Everest Industries Limited, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Roofing Market Strategic Shifts
Building-integrated photovoltaics and thermal performance engineering are converging to redefine roofing from passive shelter to active energy infrastructure, compressing the traditional separation between structural and mechanical building systems.
Building information modeling software is virtualizing pre-construction specification workflows for complex industrial roofing projects. EPC contractors in Gujarat and Tamil Nadu are adopting these platforms to coordinate structural steel, insulation, and waterproofing layers before site mobilization. This virtualization is compressing change-order frequency and reducing material waste ratios in large-format warehouse construction.
Bureau of Energy Efficiency cool-roof mandates are hardening thermal performance thresholds for government building eligibility. Manufacturers must now certify solar reflectance index values above mandated floors to qualify for public tender participation. Industrial pre-painted steel suppliers are responding by reformulating topcoat chemistries to meet these specifications without sacrificing corrosion protection durability.
Project-scale procurement aggregators are consolidating fragmented commercial demand across tier-two and tier-three markets. These platforms disintermediate traditional stockist networks by connecting contractors directly to mill-direct pricing for standardized profiles. Maharashtra and Karnataka show the highest platform penetration, where mid-size industrial warehouse construction concentrates buyer activity.
India Roofing Market Segmentation
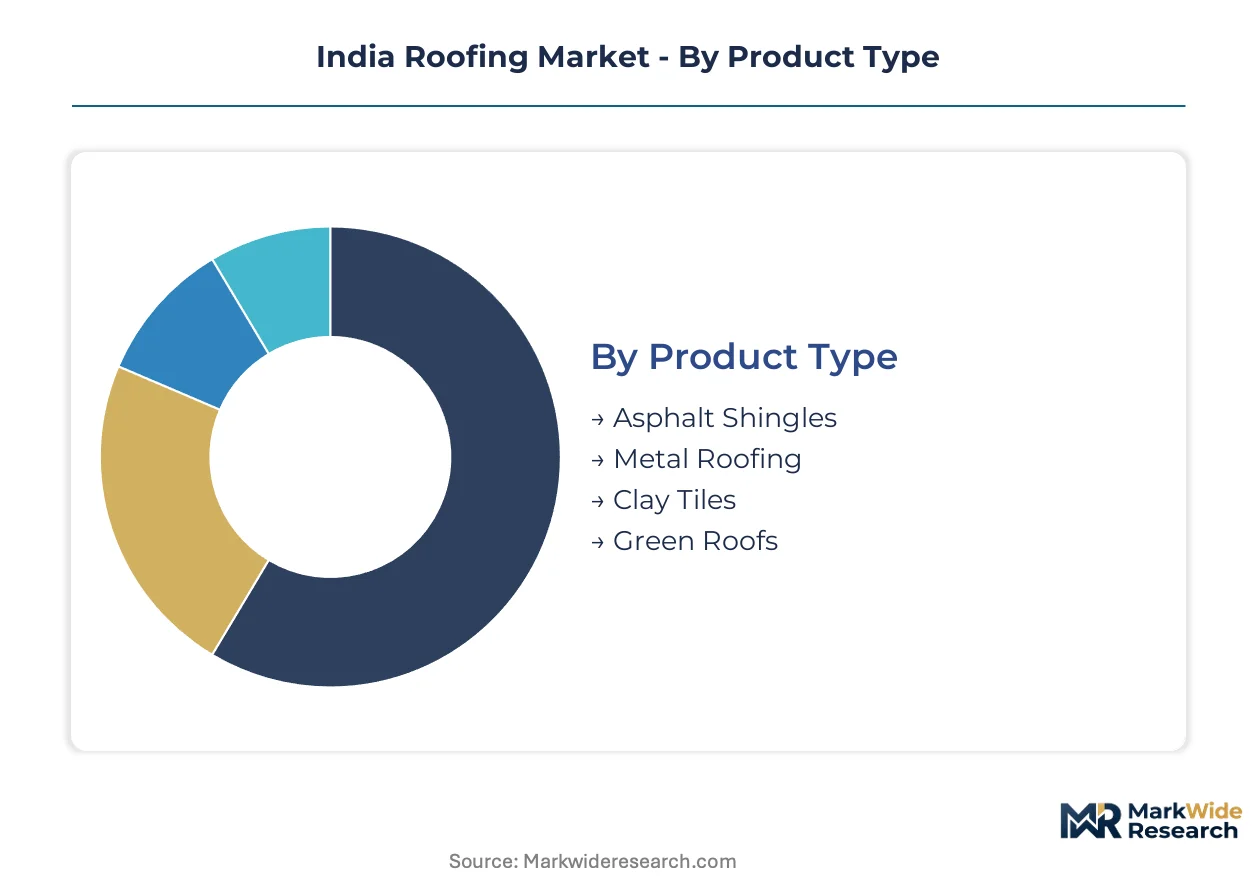
Segmentation in India's roofing sector reveals how specification requirements diverge across climate zones, building codes, and procurement channels. Understanding these fault lines helps manufacturers align product portfolios with the highest-velocity demand corridors and anticipate where service intensity will compress margins.
Product Type:
After-sales service intensity varies dramatically across roofing categories, with metal systems demanding technical support for thermal expansion management while clay tiles require artisan availability for replacement matching.
- Metal Roofing:Galvanized steel and aluminum-zinc alloy profiles deliver specified load-bearing capacity for industrial warehouses and infrastructure projects. Demand concentrates in Gujarat and Maharashtra where manufacturing corridor expansion drives specification of pre-painted coated steel with corrosion warranties. Bureau of Energy Efficiency cool-roof compliance now filters tender eligibility for public projects.
- Clay Tiles:Traditional fired clay assemblies provide thermal mass and aesthetic continuity for premium residential construction across southern states. Artisan scarcity in Karnataka and Andhra Pradesh constrains project completion timelines despite entrenched buyer preference for terracotta finishes in Kerala and Tamil Nadu.
- Asphalt Shingles:Bituminous laminate products serve cost-sensitive residential retrofits with standardized installation protocols.
- Green Roofs:Vegetated assemblies with integrated waterproofing substrates attract policy support under urban heat-island programs in Delhi NCR and Bengaluru.
By volume, metal roofing leads. By growth pace, green roofs are expanding most quickly.
Application:
Project scale and specification authority shift across application types, with industrial buyers consolidating procurement through EPC contractors while residential demand fragments across individual homeowners.
- Industrial:Large-format warehouse and factory construction commands engineered metal roofing systems with structural load certifications. Central government infrastructure mandates and PLI scheme subsidies for coated steel accelerate adoption across Maharashtra and Tamil Nadu industrial corridors.
- Residential:Single-family and multi-unit housing spans clay tile prestige segments in southern states to standardized metal solutions in affordable housing pipelines. Tier-two city concentration under central housing programs drives volume procurement of certified profiles.
- Commercial:Retail and office buildings balance aesthetic specification with thermal performance requirements under municipal green building codes.
- Agricultural:Farm structures and storage facilities prioritize cost-minimized coverage with shorter design lifespans than commercial installations.
Industrial applications dominate current volume. Residential pipelines show steepest expansion trajectory through affordable housing mandates.
Material:
Raw material sourcing geography and BIS certification pathways differentiate competitive positioning across substrate categories.
- Concrete:Fiber-reinforced cement tiles and sheets provide fire-resistant coverage for institutional buildings. BIS fire rating requirements and legacy asbestos remediation protocols shape replacement demand in Maharashtra and Gujarat.
- PVC:Polymer membrane systems serve commercial flat-roof applications with heat-welded seam integrity. Demand clusters in Bengaluru and Hyderabad technology park construction where rapid installation cycles compress project schedules.
- Fiber Cement:Compressed cellulose-fiber boards offer intermediate durability for residential and light commercial applications.
- Wood:Timber shingles and shakes retain niche specification in heritage restoration and premium hillside construction.
Concrete materials lead by installed base. PVC membranes are gaining share fastest in commercial segments.
End User:
Procurement authority and technical specification capability fragment across buyer types, with developers consolidating volume leverage against manufacturer direct sales teams.
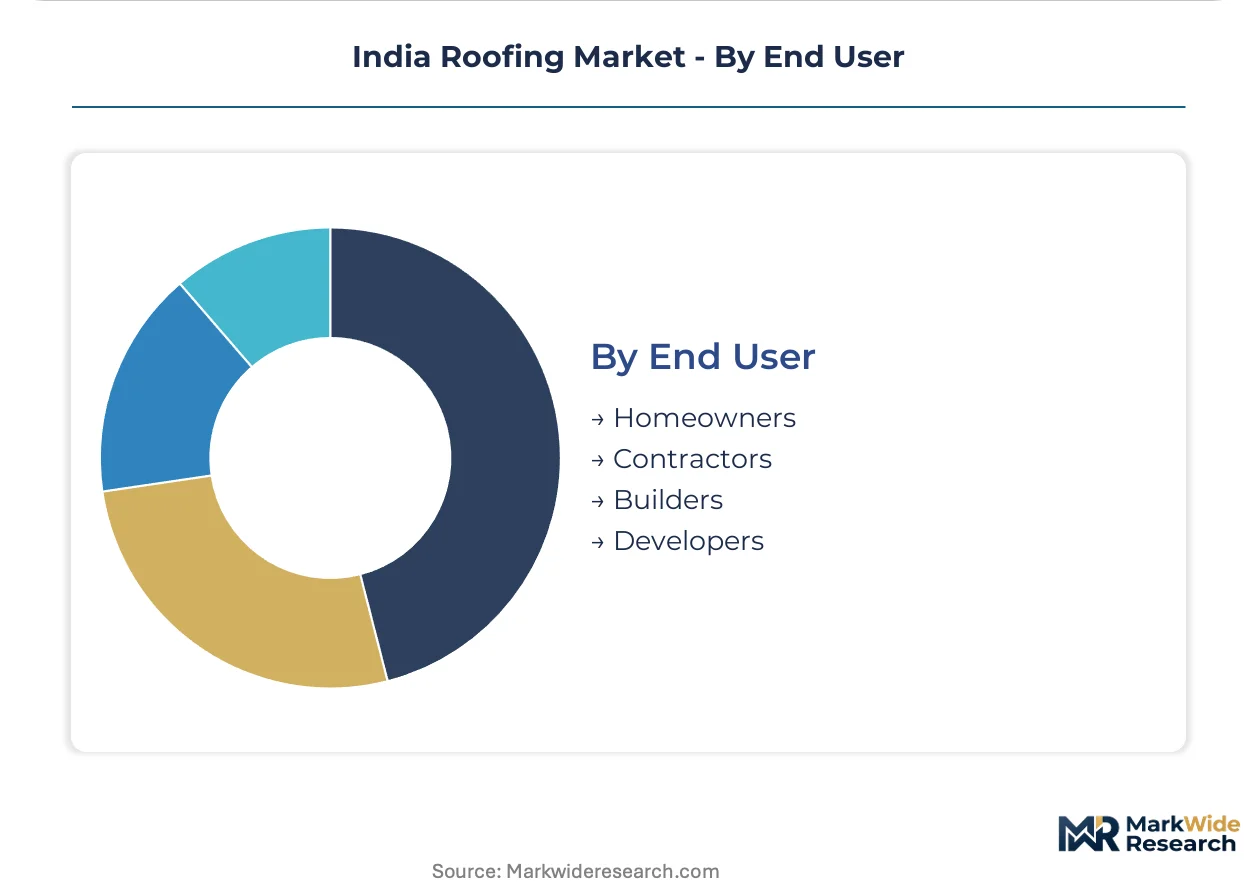
- Builders:Mid-scale construction firms coordinate material procurement across multiple residential projects simultaneously. Digital platform adoption in Karnataka and Maharashtra enables mill-direct pricing bypass for standardized metal profiles.
- Developers:Large real estate entities specify roofing systems at master planning stage with integrated thermal performance requirements. Affordable housing mandates concentrate their demand in tier-two cities where scale procurement meets BIS certification thresholds.
- Contractors:Installation specialists influence material selection through established supplier relationships and warranty service access.
- Homeowners:Individual buyers rely on contractor recommendation for repair and replacement decisions with limited direct specification authority.
Builders currently transact highest volume. Developers are climbing the fastest as affordable housing pipelines mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The PLI scheme for specialty steel is redistributing manufacturing capacity across state boundaries. State-level building codes and municipal load certifications are creating divergent compliance environments. Industrial corridor development concentrates demand in western and southern states.
Maharashtra
Mumbai-Pune industrial belt expansion and affordable housing mandates in Nagpur drive metal roofing procurement. BIS certification requirements for fire resistance ratings filter supplier eligibility for public tenders. Aurangabad's manufacturing corridor anchors pre-painted steel consumption for warehouse construction.
Gujarat
DMIC infrastructure investments and port-linked industrial zones accelerate engineered roofing adoption. State municipal corporations enforce structural load certifications that exceed national BIS baselines. Surat-Vadodara corridor dominates coated steel specification for logistics facilities.
Tamil Nadu
Sriperumbudur-Oragadam automotive cluster expansion sustains demand for thermally efficient metal systems. Bureau of Energy Efficiency cool-roof specifications shape eligibility for government building contracts. Coimbatore's SME manufacturing base drives standardized profile procurement.
Karnataka
Bengaluru technology park construction and warehouse densification pull polymer membrane and metal solutions. State-level green building codes mandate solar reflectance thresholds for commercial projects. Mysuru-Mandya corridor emerging as secondary demand node for agricultural roofing replacement.
Delhi-NCR
Urban heat-island mitigation programs and green roof mandates create compliance-driven specification shifts. Municipal corporation load-bearing approval backlogs delay project handovers for innovative metal profiles. Gurugram-Noida industrial zones concentrate demand for integrated photovoltaic roofing systems.
India Roofing Market Competitive Environment
On the supply side, the industry is consolidating around integrated metal producers and specialized coating specialists. Three strategic archetypes dominate: aluminum-zinc alloy integrators with captive smelting capacity, pre-painted steel formulators serving industrial EPC contractors, and fiber-cement legacy players managing asbestos remediation transitions. Competitive moves center on backward integration into coating substrate production and direct-to-contractor digital platform partnerships.
Within the integrated aluminum tier, Hindalco Industries Ltd anchors premium metal roofing supply through upstream control over primary metal production. Tata Bluescope Steel Private Limited and JSW Steel occupy positions at the scale-driven end of coated steel fabrication, representing the manufacturing volume archetype that competes on mill-direct pricing and standardized profile availability.
| Leading Market Players |
|---|
| Hindalco Industries Ltd |
| BirlaNu Limited |
| Tata Bluescope Steel Private Limited |
| Dion Incorporation |
| Visaka Industries Limited |
| JSW Steel |
| Bansal Roofing Products Limited |
| CK Birla Group |
| Everest Industries Limited |
| Others |
Value Chain & Pricing Dynamics
LME price volatility for aluminum-zinc alloy substrates determines both pricing tier spreads and supply chain shape across India's roofing sector, compressing margins on standardized metal profiles while rewarding backward-integrated manufacturers with captive smelting capacity.
Pricing Analysis
Certification level creates the primary spread between product tiers, with BIS fire-resistance and tensile-strength ratings separating premium pre-painted steel from uncertified imports. Three-tier pricing structure across premium certified, standard compliant, and economy unbranded levels dominates transactional dynamics. Cost compression in the economy tier is intensifying because direct-to-contractor digital platforms consolidate demand and bypass traditional dealer markups. Affordable housing developers exhibit highest price sensitivity, while industrial EPC contractors prioritize corrosion warranty terms over unit cost.
Supply Chain Analysis
Coated steel capacity concentrates at integrated mills in Maharashtra and Gujarat, with Hindalco's aluminum smelters in Odisha and Renukoot anchoring premium alloy supply. Raw material dependencies rest on imported aluminum-zinc coating substrates, domestic hot-rolled coil from JSW and Tata Steel, and specialty pigments from Germany and Japan. Single-source vulnerability for high-grade coating alloys exposes formulators to currency fluctuation and maritime logistics disruption. Distribution runs through project-scale procurement aggregators in tier-two cities, displacing fragmented stockist networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
India's roofing market is recovering from input cost cyclicality, with PLI scheme subsidies for specialty steel providing the cyclical uplift that rewards early capacity positioning.
For Market Incumbents: Pre-empt margin erosion from direct-to-contractor platforms by acquiring digital procurement networks or building proprietary contractor-facing portals. Secure captive supply of aluminum-zinc coating substrates through long-term offtake agreements with Hindalco or Vedanta to neutralize LME volatility exposure. For New Entrants and Emerging Players: Establish a beachhead in green roof assemblies for Delhi NCR and Bengaluru compliance markets, where Bureau of Energy Efficiency mandates create protected demand corridors with limited incumbent specialization. Target agricultural roofing replacement in Karnataka's Mysuru-Mandya corridor through standardized fiber-cement profiles with rapid-installation protocols. For Investors and Strategic Acquirers: Coating technology specialists with BIS-accredited testing infrastructure and established EPC contractor relationships represent the most defensible acquisition archetype. Monitor PLI scheme disbursement velocity and state-level municipal corporation certification backlogs as inflection indicators for manufacturing capacity utilization.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Coating Substrates | Hindalco's captive aluminum supply chain demonstrates how upstream control neutralizes LME price volatility for premium metal roofing. |
| Digital Platform Partnership | Direct-to-contractor procurement networks in Maharashtra and Karnataka compress distribution margins and rebuild channel economics around project-scale aggregation. |
| Cool-Roof Certification Investment | Bureau of Energy Efficiency thermal reflectance standards filter public tender eligibility, pulling compliant product development from manufacturers. |
| Green Roof Assembly Development | Urban heat-island mitigation programs in Delhi NCR create compliance-driven demand for vegetated systems with integrated waterproofing substrates. |
| Rajasthan-Gujarat Solar Corridor Positioning | Integrated photovoltaic roofing systems for industrial warehouses combine generation assets with structural weatherproofing under single-installation contracts. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with roofing product manufacturers, EPC contractors, municipal corporation building inspectors, and dealer network operators; and secondary validation through BIS certification registries, Bureau of Energy Efficiency cool-roof qualification databases, PLI scheme disbursement records, and state-level industrial corridor investment disclosures. Bottom-up volume triangulation across product type, application, and end-user segments was cross-checked against top-down macroeconomic indicators including construction sector GVA and affordable housing pipeline announcements.
Forecast inputs considered industrial warehouse construction permits, PLI scheme subsidy allocation trajectories, and state-level building code adoption timelines across the analysis window. Segmentation dimensions modeled include product type, application category, material substrate, and end-user procurement authority. CAGRs were derived from regression analysis of historical installation volumes against explanatory variables including manufacturing corridor investment, municipal green building mandate adoption, and digital platform penetration rates. Metal roofing substitution elasticity and artisan availability constraints for clay tiles were incorporated as industry-specific forecast inputs.
Stress conditions across aluminum-zinc alloy import pricing, BIS certification timeline extensions, and municipal load-bearing approval backlogs were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding PLI scheme continuity and state-level building code harmonization. Quarterly review of industrial construction permit issuance and cool-roof laboratory accreditation expansion is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Softwood Lumber Market
Building & Construction Materials
Japan Cross Laminated Timber (CLT) Market
Building & Construction Materials
APAC Commercial Glazing System Market
Building & Construction Materials
India Manufacturing Market
Building & Construction Materials
Wood Panel Market
Building & Construction Materials
Brick Market
Building & Construction Materials
Precast Concrete Pile Market
Building & Construction Materials
Windows and Doors Market
Building & Construction Materials
Travertine Market
Building & Construction Materials
Rebars Market
Building & Construction Materials
Exterior Wall System Market
Building & Construction Materials
Air Barrier Market
Building & Construction Materials
Japan Oriented Strand Board Market
Building & Construction Materials
Middle-East and Africa Industrial Flooring Market
Building & Construction Materials
Residential Non-metal Electrical Conduit Market
Building & Construction Materials
Concrete Sealer Market