
 Robot End-Effector Market | 2026-2036
Robot End-Effector Market Size, Share, and Industry Trends Forecast 2026-2036
Robot End-Effector Market Intelligence
The EU Machinery Directive revision is recalibrating compliance costs for end-effector manufacturers selling into European automation lines. Schunk leverages its modular gripper architecture to sustain certification breadth across multiple safety categories. ABB anchors its position through integrated force-torque sensing in collaborative robot wrists. Festo competes on pneumatic density, packing multiple actuation channels into compact end-of-arm envelopes.
A robot end-effector constitutes the terminal device mounted to a robotic arm wrist joint, typically integrating force sensors, pneumatic valves, or servo motors within an IP-rated housing to execute physical interaction tasks with workpieces. Electric gripper variants dominate precision assembly in electronics manufacturing due to programmable force control down to sub-Newton resolution, while vacuum cup configurations retain cost advantages in high-speed packaging processes across food processing units. Pneumatic technology still occupies the largest installed base among metal fabricators, though piezoelectric actuation is gaining traction in inspection tasks requiring micro-positioning stability.
FDA guidance on pharmaceutical manufacturing automation shapes validation protocols for end-effectors deployed in aseptic filling lines, while ISO 10218 safety standards dictate collision-force thresholds for collaborative applications. China's GB standards and NMPA quality system requirements create parallel compliance tracks for suppliers targeting domestic pharmaceutical production. Stakeholders must weigh regional certification divergence against platform standardization when configuring global product portfolios.
Market Dynamics
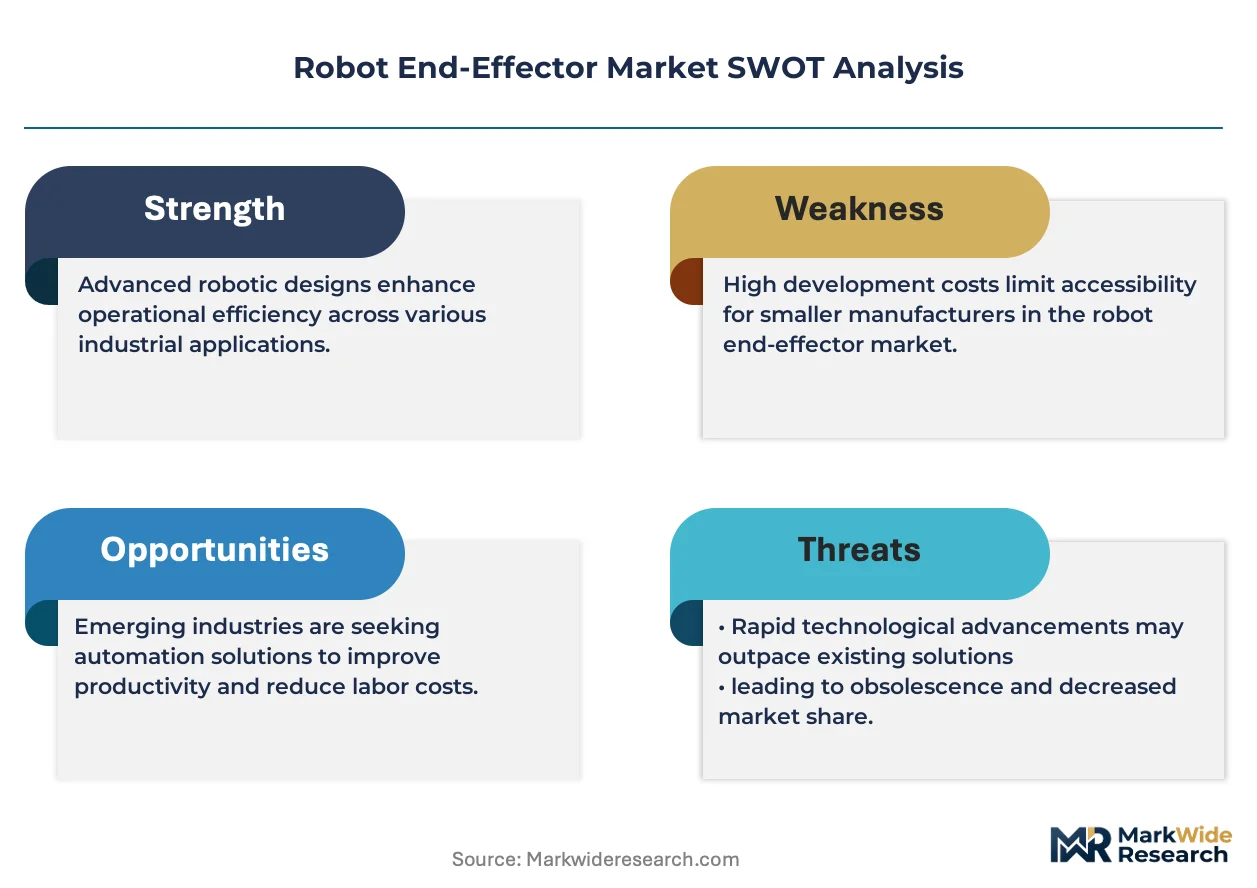
The EU Machinery Directive revision is compressing certification timelines for end-effector manufacturers while simultaneously fragmenting product architectures to satisfy regional safety categories.
Growth Catalysts
- Collaborative Robot Deployment:Automotive OEMs in Germany and Japan are scaling precision assembly lines with force-limited end-effectors. This creates pull for integrated torque-sensing modules.
- EU Machinery Directive:The revised directive tightens functional safety requirements for human-robot collaboration interfaces. Suppliers must recalibrate control system architectures to maintain CE marking access.
- Yangtze River Delta Concentration:Electronics contract manufacturers in this corridor are retrofitting production lines with adaptive gripper systems. Demand concentrates where smartphone assembly volumes remain highest.
Market Restraints
- Pneumatic Input Volatility:Compressor energy costs and aluminum body casting prices create margin pressure for pneumatic gripper suppliers serving metal fabricators.
- Sensor Supply Concentration:Force-torque sensor manufacturing concentrates in Japanese and German component houses. Disruption ripples through collaborative robot wrist integration timelines.
- ISO 10218 Collision Thresholds:The safety standard's force limits constrain payload-to-weight ratios for electric gripper designs targeting electronics assembly.
Strategic Opportunities
- Pharmaceutical Aseptic Lines:FDA guidance on manufacturing automation shapes validation protocols for end-effectors in filling operations. Suppliers can capture premium positioning through pre-validated modular architectures.
- India PLI Scheme:Production-linked incentives for electronics manufacturing are drawing contract manufacturers to Gujarat and Tamil Nadu. Greenfield facilities need complete end-of-arm tooling suites.
- Piezoelectric-Vision Convergence:Micro-positioning stability from piezoelectric actuation combined with inline inspection cameras opens inspection-task applications in semiconductor handling.
Industry Challenges
- Safety Certification Timelines:Parallel tracks for China's GB standards, EU CE marking, and FDA validation extend product launch cycles by 14-18 months for pharmaceutical-targeted designs.
- Legacy Pneumatic Integration:Metal fabricators with extensive compressed air infrastructure resist electric gripper retrofits despite precision advantages. Sales cycles lengthen where pneumatic sunk costs dominate.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Robot End-Effector Market |
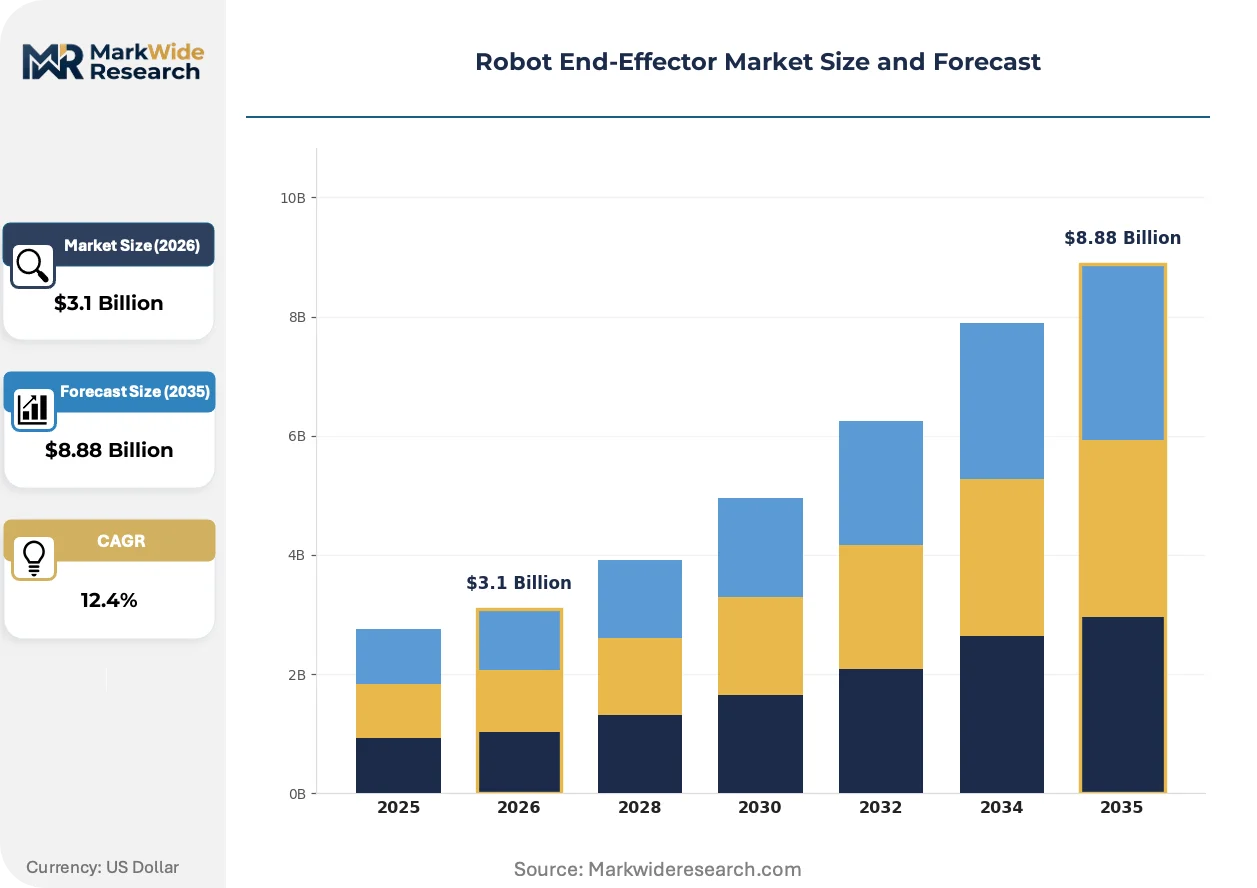
| Market Size in 2026 | $3.1 Billion |
| Market Size in 2035 | $8.88 Billion |
| CAGR (2026 – 2036) | 12.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Grippers, Welding Torches, Vacuum Cups, Adhesive Applicators, Cutting Tools, Multipurpose Hands Technology: Electric, Pneumatic, Hydraulic, Magnetic, Mechanical, Piezoelectric Application: Material Handling, Assembly Operations, Packaging Processes, Machine Tending, Electronic Component Handling, Inspection Tasks End User Industry: Electronics Manufacturing, Aerospace Contractors, Food Processing Units, Pharmaceutical Production, Consumer Goods Makers, Metal Fabricators |
| Companies Covered | ATI Industrial Automation, SMC Corporation, Schunk, Destaco, Robotiq Inc., Zimmer Group, Festo, Piab AB, ABB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Robot End-Effector Market Strategic Shifts & Innovations
Three forces are compressing the competitive cycle: electric actuation architectures are overtaking pneumatic dominance, regulatory divergence is fragmenting product platforms, and buyer procurement patterns are shifting toward subsystem integration contracts.
Electric gripper variants with programmable force control down to sub-Newton resolution are overtaking pneumatic configurations in electronics precision assembly. Contract manufacturers in China's manufacturing corridors specify electric architectures for new line installations. This shift compresses the installed base advantage pneumatic suppliers held among metal fabricators.
REACH substance restrictions and the EU AI Act are recalibrating material selection and algorithmic transparency requirements for end-effectors with embedded sensing. Manufacturers must document force-sensor calibration chains and control logic auditability. Collaborative robot deployments in European automotive lines face the steepest compliance recalibration.
Electronics OEMs are consolidating vendor relationships around subsystem integrators who bundle end-effectors with vision systems and control software. Traditional component distributors lose share to robotics system houses in Germany and Japan. This concentration is most visible where smartphone contract manufacturers negotiate line-wide automation packages.
Robot End-Effector Market Segmentation
End-effector procurement patterns diverge sharply across automation maturity levels, with upgrade cycles compressing in electronics while metal fabrication retains legacy pneumatic infrastructure. Component selection hinges on force-resolution requirements, environmental sealing needs, and integration complexity with existing robot controllers.
Type:
Retrofit decisions in established automotive lines favor modular architectures that minimize controller reprogramming, while greenfield electronics facilities specify purpose-built configurations from commissioning.
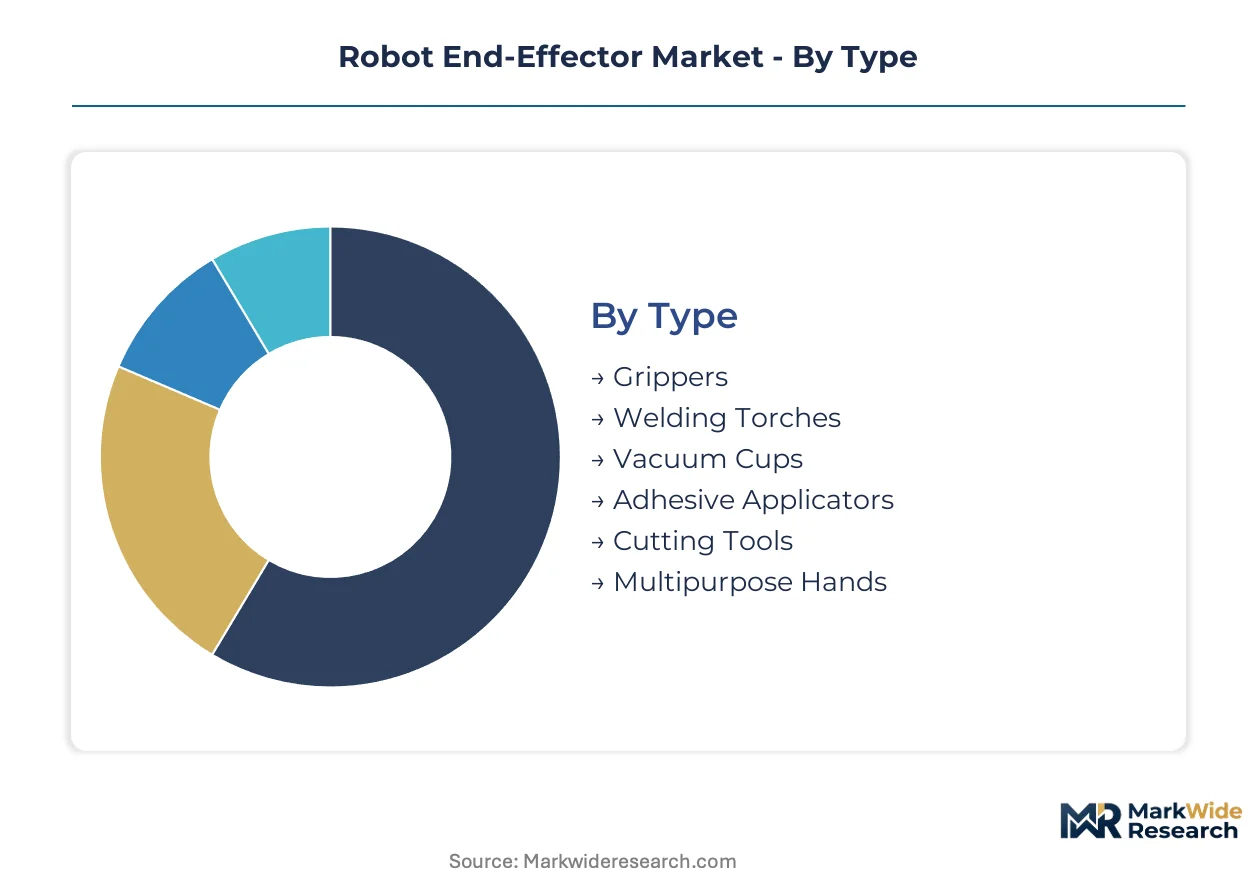
- Grippers:Two-finger parallel designs with integrated force-torque sensing dominate precision assembly in German automotive plants. Electronics contract manufacturers in China's Yangtze River Delta specify adaptive finger geometries for mixed-model smartphone production.
- Vacuum Cups:Multi-bellow silicone configurations handle irregular food packaging surfaces at high cycle rates. Compressed air infrastructure in legacy metal fabrication plants sustures demand despite electric alternatives gaining precision advantages.
- Welding Torches:Water-cooled MIG configurations integrate wire feed and gas management in compact envelopes for Japanese automotive body-in-white lines.
- Adhesive Applicators:Precision dispensing heads with heated reservoirs serve aerospace composite bonding in Toulouse and Hamburg manufacturing clusters.
- Cutting Tools:Spindle-mounted rotary cutters trim flash from injection-molded consumer goods in Tamil Nadu plastics operations.
- Multipurpose Hands:Dexterous five-finger configurations with tactile sensing enable bin-picking in pharmaceutical kitting operations under FDA validation protocols.
Grippers sit at the top of the volume ranking, with multipurpose hands climbing the fastest.
Technology:
Energy cost differentials and precision requirements split procurement between compressed air infrastructure regions and electric-forward electronics corridors.
- Electric:Servo-driven architectures with sub-Newton force resolution enable collaborative robot deployment in Japanese automotive assembly. Programmability advantages accelerate replacement of pneumatic systems in Shenzhen electronics facilities.
- Pneumatic:Aluminum-bodied gripper arrays leverage existing compressor infrastructure in Midwest US metal fabrication plants. Energy consumption penalties constrain expansion into new European lines facing compressed air taxation.
- Hydraulic:High-force density actuation serves heavy-payload forging operations in German steel processing.
- Magnetic:Electromagnetic handling of ferrous blanks persists in Korean shipyard panel assembly.
- Mechanical:Passive compliant mechanisms with no power supply suit explosive-environment operations in Norwegian offshore equipment handling.
- Piezoelectric:Nanometer-stable positioning enables semiconductor wafer alignment in Dutch lithography equipment integration.
Pneumatic technology retains the largest installed base, though electric architectures are expanding most quickly in new line specifications.
Application:
Line balancing requirements and cycle time targets determine end-effector specialization versus flexibility trade-offs in contract manufacturer procurement.
- Material Handling:Palletizing vacuum arrays in food processing units prioritize speed over precision, with cycle rates dictating multi-cup configurations. German dairy cooperatives specify stainless steel housings for washdown compliance.
- Assembly Operations:Force-limited electric grippers with torque feedback enable human-robot collaboration in Stuttgart automotive plants. ISO 10218 compliance thresholds shape actuator selection for mixed workstation layouts.
- Packaging Processes:High-speed carton handling in Mumbai consumer goods facilities favors pneumatic delta robots with lightweight vacuum tooling.
- Machine Tending:CNC loading operations in Turin metalworking clusters require chip-resistant sealing and coolant compatibility.
- Electronic Component Handling:ESD-safe electric grippers with vision alignment serve PCB population in Penang contract manufacturing.
- Inspection Tasks:Piezoelectric-actuated probe positioning integrates with coordinate measuring machines in precision aerospace component verification.
Material handling commands the highest unit volumes, with inspection tasks gaining share fastest as inline quality verification expands.
End User Industry:
Regulatory validation burdens and automation maturity create divergent procurement cycles across verticals, with pharmaceutical timelines extending 14-18 months for safety certification.
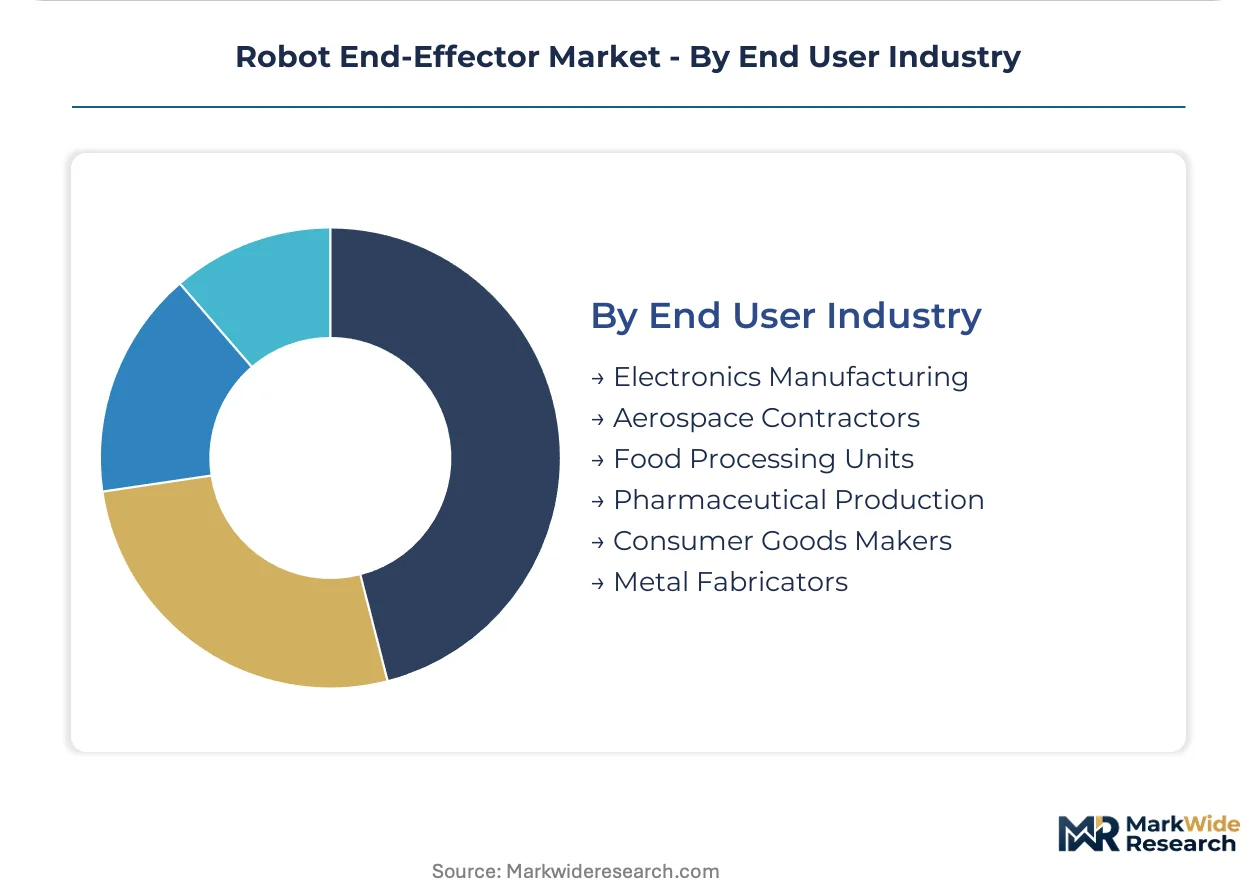
- Electronics Manufacturing:Smartphone assemblers in China's manufacturing corridors specify electric grippers with vision integration for sub-millimeter placement accuracy. Contract manufacturer consolidation around subsystem integrators compresses vendor counts in this vertical.
- Pharmaceutical Production:Aseptic filling line end-effectors require FDA validation documentation and sterilization compatibility. Stainless steel construction and SIP/CIP sealing dominate specifications for vial and syringe handling.
- Aerospace Contractors:Composite drilling and fastening operations in Toulouse and Seattle demand force-controlled drilling units with debris extraction.
- Food Processing Units:IP69K-rated pneumatic grippers with quick-change tooling suit high-mix protein packaging in Danish cooperatives.
- Consumer Goods Makers:Injection molding machine tending in Vietnam facilities prioritizes cost-optimized pneumatic configurations.
- Metal Fabricators:Laser cutting load/unload operations in Pittsburgh job shops retain pneumatic dominance due to compressed air infrastructure sunk costs.
Electronics manufacturing sits at the top of the volume ranking, with pharmaceutical production climbing the fastest as aseptic automation investments accelerate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial robot end-effector manufacturing traces its commercial origins to German automotive automation in the 1980s, with Japanese electronics assembly scaling precision gripper demand through the 1990s. Production lineage now spans five concentrated national bases where regulatory frameworks and industrial clustering create distinct procurement environments.
Germany
Stuttgart automotive plants deploy force-limited electric grippers for human-robot collaboration on precision assembly lines. The EU Machinery Directive revision tightens functional safety requirements for CE marking on collaborative interfaces. Bavaria's automation corridor hosts subsystem integrators bundling end-effectors with vision systems for line-wide contracts.
China
Electronics contract manufacturers in the Yangtze River Delta retrofit production lines with adaptive gripper systems for smartphone assembly volumes. NMPA quality system requirements and GB standards create parallel compliance tracks for pharmaceutical-targeted designs. Shenzhen facilities specify electric architectures with sub-millimeter placement accuracy for new line installations.
Japan
Automotive OEMs scale collaborative robot deployments with integrated torque-sensing modules for precision assembly tasks. METI industrial policy supports domestic force-torque sensor manufacturing concentration. Nagoya's automotive belt anchors demand for water-cooled welding torch configurations in body-in-white operations.
United States
Midwest metal fabricators retain pneumatic gripper dominance due to sunk compressed air infrastructure costs. FDA guidance shapes validation protocols for end-effectors in pharmaceutical aseptic filling lines. Pittsburgh job shops prioritize cost-optimized configurations for laser cutting load/unload operations.
India
Electronics manufacturing draws contract manufacturers to Gujarat and Tamil Nadu under PLI scheme incentives requiring complete end-of-arm tooling suites. BIS standards and CDSCO quality requirements add certification complexity for pharmaceutical applications. Greenfield facilities in these states specify subsystem-integrated packages from commissioning.
Robot End-Effector Market Key Industry Players
The competitive structure tilts toward diversified industrial automation conglomerates with captive end-effector divisions. Tiered specialization separates precision assembly specialists from pneumatic volume suppliers and subsystem integrators bundling vision-software-gripper packages. Dominant competitive moves include backward integration into force-torque sensor manufacturing and geographic expansion through subsystem partnership networks in Asian electronics corridors.
Among German-based automation specialists, Schunk GmbH exemplifies the modular architecture archetype sustaining certification breadth across multiple safety categories. Festo AG & Co. KG represents the pneumatic density specialist position, while ABB anchors the integrated force-sensing tier through collaborative robot wrist convergence. These three occupy distinct competitive vectors rather than direct overlap.
| Leading Market Players |
|---|
| ATI Industrial Automation |
| SMC Corporation |
| Schunk |
| Destaco |
| Robotiq Inc. |
| Zimmer Group |
| Festo |
| Piab AB |
| ABB |
| Others |
Cost & Logistics Intelligence
Family-owned German automation specialists anchor supply discipline through generational capital structures that resist quarterly margin pressure, enabling sustained R&D commitment across pneumatic and electric actuator portfolios while pricing power concentrates in force-torque sensor integration tiers.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates force-sensing collaborative modules from basic pneumatic arrays and commodity vacuum tooling. Price differentiation hinges on ISO 10218 safety certification grade and after-sales service bundling for pharmaceutical validation support. Pricing pressure stems from electric gripper cost compression in Shenzhen electronics corridors where contract manufacturers consolidate vendor counts. Metal fabricators in Midwest US plants exhibit highest price sensitivity due to compressed air infrastructure sunk costs, while pharmaceutical OEMs accept premium positioning for FDA-validated modular architectures.
Supply Chain Analysis
Force-torque sensor manufacturing rests on Japanese and German component houses with Nagoya and Stuttgart anchoring precision strain-gauge production. Aluminum body castings draw from Chinese foundries serving pneumatic gripper arrays, while servo motor assemblies feed from South Korean and Taiwanese motor specialists. Single-source vulnerability concentrates in semiconductor-grade piezoelectric ceramics for nanometer-stable positioning applications. Distribution runs through robotics system integrators in Bavaria and subsystem bundlers in China's Yangtze River Delta manufacturing corridor.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where EU Machinery Directive revision and FDA validation protocols continuously reset compliance barriers, embedding incumbents with certified architectures while extracting premium economics from safety-critical applications.
For Market Incumbents: Acquire force-torque sensor manufacturing capabilities to reduce dependency on Japanese component houses facing disruption risk. Deepen backward integration into piezoelectric actuator supply for semiconductor handling applications. Anchor certification breadth across EU CE marking, FDA validation, and China GB standards to extend product launch cycle advantages over emerging competitors lacking parallel compliance infrastructure. For New Entrants and Emerging Players: Tier 2 automotive suppliers in India's Gujarat and Tamil Nadu corridors represent underserved buyer archetypes seeking complete end-of-arm tooling suites under PLI scheme incentives. Greenfield pharmaceutical facilities in these states lack pre-validated modular architectures for aseptic filling operations. Position through subsystem partnership networks with established vision system houses to bypass direct certification timeline disadvantages. For Investors and Strategic Acquirers: Valuations sit cheapest among pneumatic volume suppliers facing electric architecture displacement in electronics corridors. Five-to-ten-year viability hinges on compressed air taxation exposure in European markets versus retrofit inertia in legacy metal fabrication infrastructure. Monitor EU Machinery Directive implementation timelines as inflection indicator for compliance cost recalibration across supplier tiers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Force-Torque Sensors | Reduces supply risk from Japanese and German component concentration for collaborative robot wrist modules. |
| Pre-Validated Modular Architecture Development | Captures premium positioning in FDA-guided pharmaceutical aseptic filling line deployments. |
| Subsystem Partnership Network Expansion | Penetrates China's Yangtze River Delta electronics corridors where vendor consolidation favors bundled offerings. |
| Piezoelectric-Vision Convergence Investment | Opens semiconductor wafer handling applications requiring nanometer-stable positioning with inline inspection. |
| Multi-Regional Certification Infrastructure | Sustains CE marking, FDA validation, and China GB standard access across divergent regulatory tracks. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with robotics OEM procurement teams, automation subsystem integrators, plant engineers at electronics contract manufacturers, and pharmaceutical manufacturing validation specialists with secondary validation from SEC filings of listed automation conglomerates, customs data on aluminum body casting trade flows, FDA 510(k) submission databases for aseptic handling equipment, and EU Machinery Directive implementation guidance documents. Bottom-up demand aggregation across end-user industries and top-down supply-side capacity assessment were cross-referenced for convergence.
Historical reference periods anchored the projection horizon through installed base analysis of pneumatic versus electric gripper penetration rates across metal fabrication and electronics manufacturing verticals. Segmentation dimensions modeled include gripper type, actuation technology, application task, and end-user industry regulatory cluster. CAGRs were derived from elasticity-adjusted demand curves incorporating collaborative robot deployment trajectories and compliance cost inflation across EU, US, and Chinese regulatory frameworks.
Inputs from robotics OEM procurement teams and subsystem integrators were available through the study window; gaps in real-time pharmaceutical validation timeline data introduce uncertainty bands around aseptic line automation forecasts. Forecasts reflect documented assumptions on EU Machinery Directive enforcement intensity and India PLI scheme facility commissioning rates. Material deviation in named regulatory triggers or sovereign incentive program funding levels warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
Asia Pacific Warehouse Robotics Market
Robotics and Automation
Global Automotive Gesture Recognition System Market
Robotics and Automation
Robotic Waste Sorting System Market
Robotics and Automation
Latin America Cloud Robotics Market
Robotics and Automation
Mobile Cobots Market
Robotics and Automation
Middle East Cloud Robotics Market
Robotics and Automation
Indonesia Robotics Market
Robotics and Automation
Simultaneous Localization and Mapping (SLAM) Market
Robotics and Automation
Healthcare Robots Market
Robotics and Automation
Surgical Robots Market
Robotics and Automation
Spain Cloud Robotics Market
Robotics and Automation
Canada Cloud Robotics Market
Robotics and Automation
Global Wafer Handling Robots Market
Robotics and Automation
Micro Robots Market
Robotics and Automation
Self-Driving Delivery Robot Market
Robotics and Automation
Robot Coffee Kiosk Market