
 Surgical Robots Market | 2026-2036
Surgical Robots Market Size, Share, and Industry Trends Forecast 2026-2036
Surgical Robots Market Analysis
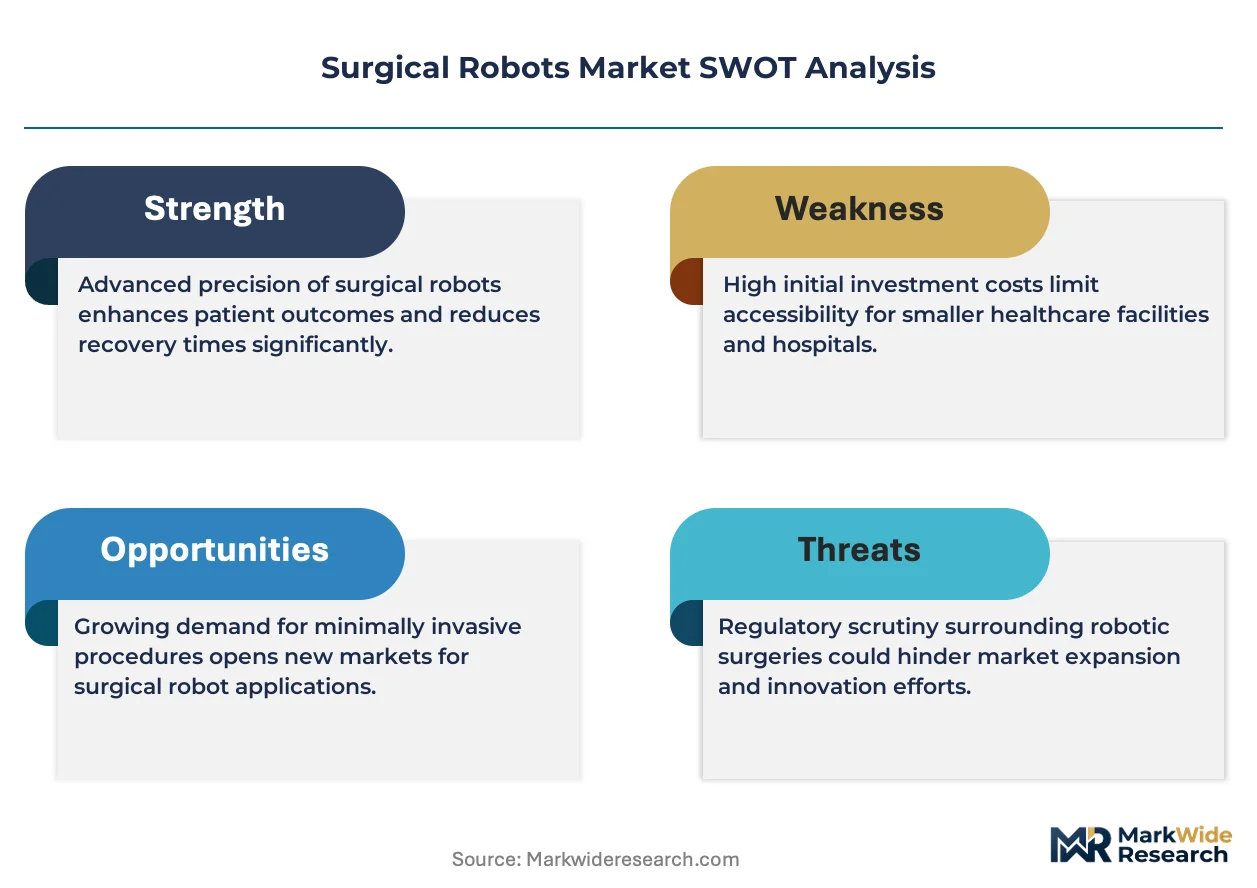
Leasing and pay-per-procedure financing is narrowing the competitive field for mid-tier hospitals seeking robotic capabilities. Intuitive Surgical leverages its installed base of da Vinci systems to sustain recurring instrument revenue. Stryker Corporation anchors its position through orthopedic robotics specialization. Medtronic competes by extending surgical navigation integration across its broader portfolio.
Surgical robots comprise electromechanical platforms with articulated instrument arms, haptic feedback controllers, and sub-millimeter positioning accuracy designed to execute minimally invasive procedures. These systems reduce incision size, blood loss, and recovery time compared to open surgery. Robotic surgical systems dominate capital expenditure budgets while surgical instruments generate the highest-margin recurring revenue stream. Teleoperated systems lead technology adoption whereas automated systems represent the fastest-growing category as autonomy algorithms mature. Hospitals command the largest end-user segment though ambulatory surgical centers are expanding robotic capabilities for outpatient procedures.
FDA premarket notification requirements and ISO 13485 quality management standards govern device safety and clinical validation pathways in the United States. The EU Medical Device Regulation mandates stricter clinical evidence for robotic systems seeking CE marking access. Stakeholders must monitor reimbursement parity between robotic and laparoscopic procedures as payer policies determine hospital return-on-investment timelines.
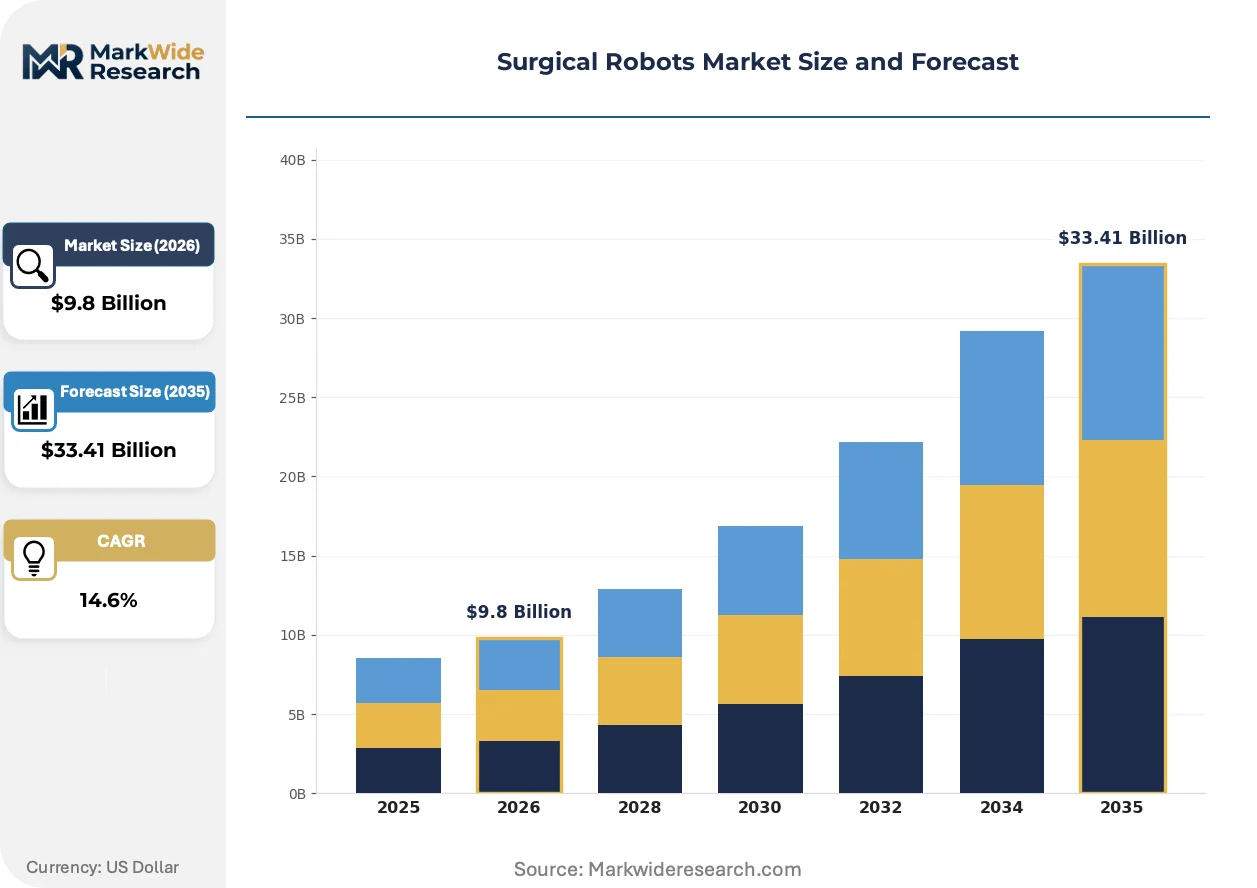
Market Dynamics
Leasing structures and pay-per-procedure financing are compressing capital barriers for mid-tier hospitals, while FDA premarket notification pathways for autonomous surgical features accelerate competitive differentiation among electromechanical platform developers.
Growth Catalysts
- EU Medical Device Regulation:MDR mandates for stricter clinical evidence create certification moats that favor established robotic system manufacturers with validated quality management systems.
- Ambulatory surgical centers:Outpatient procedure volume expansion in Germany and the United States drives demand for compact teleoperated platforms with faster setup protocols.
- Autonomy algorithms:Machine learning integration into instrument positioning systems enables sub-millimeter accuracy improvements that reduce operative time and blood loss metrics.
Market Restraints
- Instrument arm actuator supply:Precision electromechanical component manufacturing concentrates among specialized suppliers in Japan and Germany, creating input cost volatility and lead time risk.
- Reimbursement parity gaps:Payer policies in the United States and European Union frequently lag robotic procedure coding updates, extending hospital return-on-investment timelines beyond capital planning cycles.
- Open surgery substitution:Conventional laparoscopic techniques retain cost advantages for routine procedures in price-sensitive healthcare systems, limiting addressable procedure expansion.
Strategic Opportunities
- India's tertiary hospital network:Government medical college hospitals and corporate hospital chains present underpenetrated demand for teleoperated systems as surgical training infrastructure expands.
- Orthopedic robotics convergence:Integration of haptic feedback controllers with navigation systems for spine and joint procedures opens procedure categories beyond abdominal surgery.
- Japan's PMDA fast-track pathway:Expedited review designation for robotic surgical systems with demonstrated safety profiles accelerates market entry timelines for novel platform developers.
Industry Challenges
- Surgeon training pipelines:Proctored credentialing requirements for robotic console operation create bottlenecks as hospital programs scale, extending time-to-revenue for new system installations.
- ISO 13485 audit complexity:Quality management system maintenance across multiple notified bodies strains regulatory affairs resources, particularly for manufacturers pursuing simultaneous FDA and CE marking submissions.
- Legacy EMR integration:Surgical robot data architectures require custom interface development with existing hospital information systems, complicating procurement decisions and implementation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Surgical Robots Market |
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $33.41 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Robotic Surgical Systems, Surgical Instruments, Visualization Systems, Control Consoles Application: Orthopedic Surgery, Urological Surgery, Cardiothoracic Surgery, Neurosurgery End User: Hospitals, Ambulatory Surgical Centers, Clinics, Academic Institutions Technology: Teleoperated Systems, Automated Systems, Minimally Invasive Techniques, Hybrid Systems |
| Companies Covered | Intuitive Surgical, Stryker Corporation, Medtronic, Smith & Nephew, Zimmer Biomet Holdings, Johnson & Johnson, CMR Surgical, Asensus Surgical, THINK Surgical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Surgical Robots Market Emerging Trajectories
Autonomous feature development and financing model innovation are restructuring competitive access patterns across hospital tiers, while regulatory frameworks in major jurisdictions accelerate differentiation between teleoperated and automated system categories.
Sensor fusion architectures combining force feedback, optical tracking, and anatomical mapping is collapsing the boundary between navigation assistance and autonomous instrument control. Academic medical centers in Germany and the United States are piloting these integrated platforms for partial nephrectomy and prostatectomy procedures. The compression of human-in-the-loop requirements is enabling procedure standardization that reduces operative variability and training duration.
FDA premarket notification requirements for autonomous surgical features are tightening evidentiary standards for software-as-a-medical-device components in robotic platforms. Manufacturers must now submit clinical validation data for algorithm-driven instrument positioning that exceeds historical predicate device pathways. United States hospital systems are prioritizing vendors with established FDA quality system inspection records to mitigate regulatory delay risk.
Hospital procurement committees are unbundling capital acquisition from instrument supply agreements, forcing manufacturers to compete on recurring revenue terms rather than installed base lock-in. Ambulatory surgical centers in Florida and Texas are driving this pattern by negotiating per-procedure pricing without long-term exclusivity clauses. The disaggregation of financing from consumables is compressing margin structures for established platform vendors while opening vendor switching opportunities for mid-tier facilities.
Surgical Robots Market Segmentation
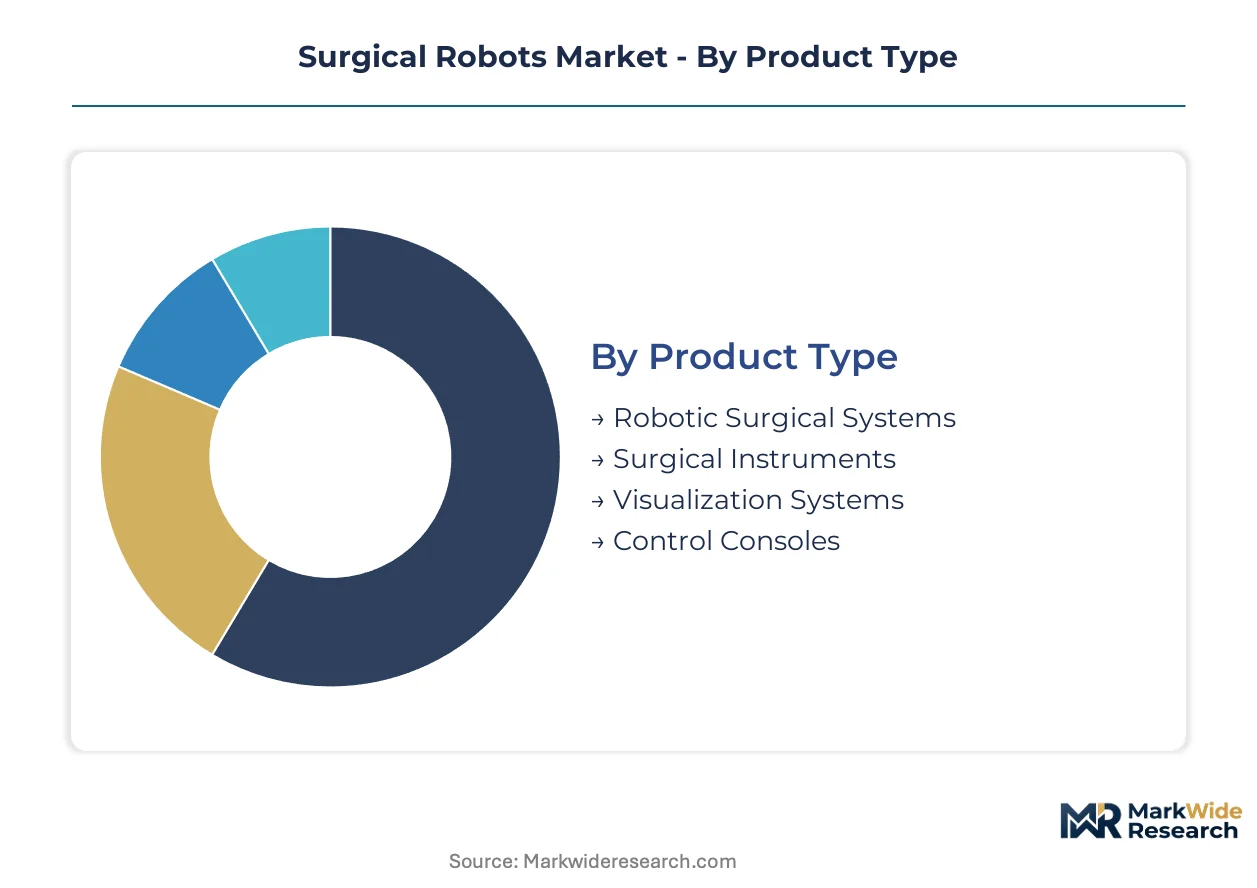
Surgical robot segmentation reveals divergent capital intensity patterns across product categories, with instrument revenue cycling faster than platform depreciation schedules. Application-level demand concentrates in procedure categories where robotic precision justifies premium reimbursement coding.
Product Type:
Replacement cycles vary dramatically across this category, with consumable instruments turning over in months while capital platforms depreciate over seven to ten years.
- Robotic Surgical Systems:Electromechanical platforms with articulated instrument arms and sub-millimeter positioning accuracy form the capital foundation. Demand concentrates in North American academic medical centers expanding multi-specialty robotic surgery programs as FDA clearance pathways for autonomous features mature.
- Surgical Instruments:Single-use or limited-reuse end effectors, graspers, and energy devices generate recurring revenue streams. German university hospitals drive procurement volume for specialized instrument sets supporting complex teleoperated procedures.
- Visualization Systems:High-definition camera stacks and optical tracking modules enable anatomical navigation.
- Control Consoles:Haptic feedback interfaces and surgeon workstations complete the platform ecosystem.
Robotic surgical systems anchor the volume base while surgical instruments gains share at the steepest rate.
Application:
Cost tiers separate this category, with high-complexity procedures justifying capital investment while routine applications face laparoscopic competition.
- Urological Surgery:Prostatectomy and partial nephrectomy procedures represent the most mature robotic application category. North American hospital systems standardize on robotic platforms for oncologic urology as payer reimbursement parity solidifies.
- Orthopedic Surgery:Spine and joint reconstruction applications integrate navigation with haptic feedback for implant positioning. German orthopedic centers drive adoption of specialized systems as training infrastructure expands.
- Cardiothoracic Surgery:Mitral valve repair and coronary bypass procedures demand advanced instrument articulation.
- Neurosurgery:Cranial and spinal applications require sub-millimeter accuracy for tumor resection and electrode placement.
Urological surgery anchors the volume base while orthopedic surgery expands most quickly as platform specialization deepens.
End User:
Customer type determines procurement authority, with centralized hospital systems negotiating enterprise agreements while independent surgical centers seek flexible financing.
- Hospitals:Tertiary and quaternary care facilities command the largest installed base of multi-port robotic systems. Academic institutions in Germany and the United States drive replacement demand as first-generation platforms reach end-of-life.
- Ambulatory Surgical Centers:Outpatient-focused facilities in Florida and Texas negotiate per-procedure pricing without long-term exclusivity. Compact teleoperated platforms with faster setup protocols address space constraints and throughput requirements.
- Clinics:Specialized surgical practices pursue limited robotic capabilities for high-volume routine procedures.
- Academic Institutions:Medical school affiliates prioritize training consoles and simulation infrastructure.
Hospitals anchor the volume base while ambulatory surgical centers climb the fastest as site-of-care migration accelerates.
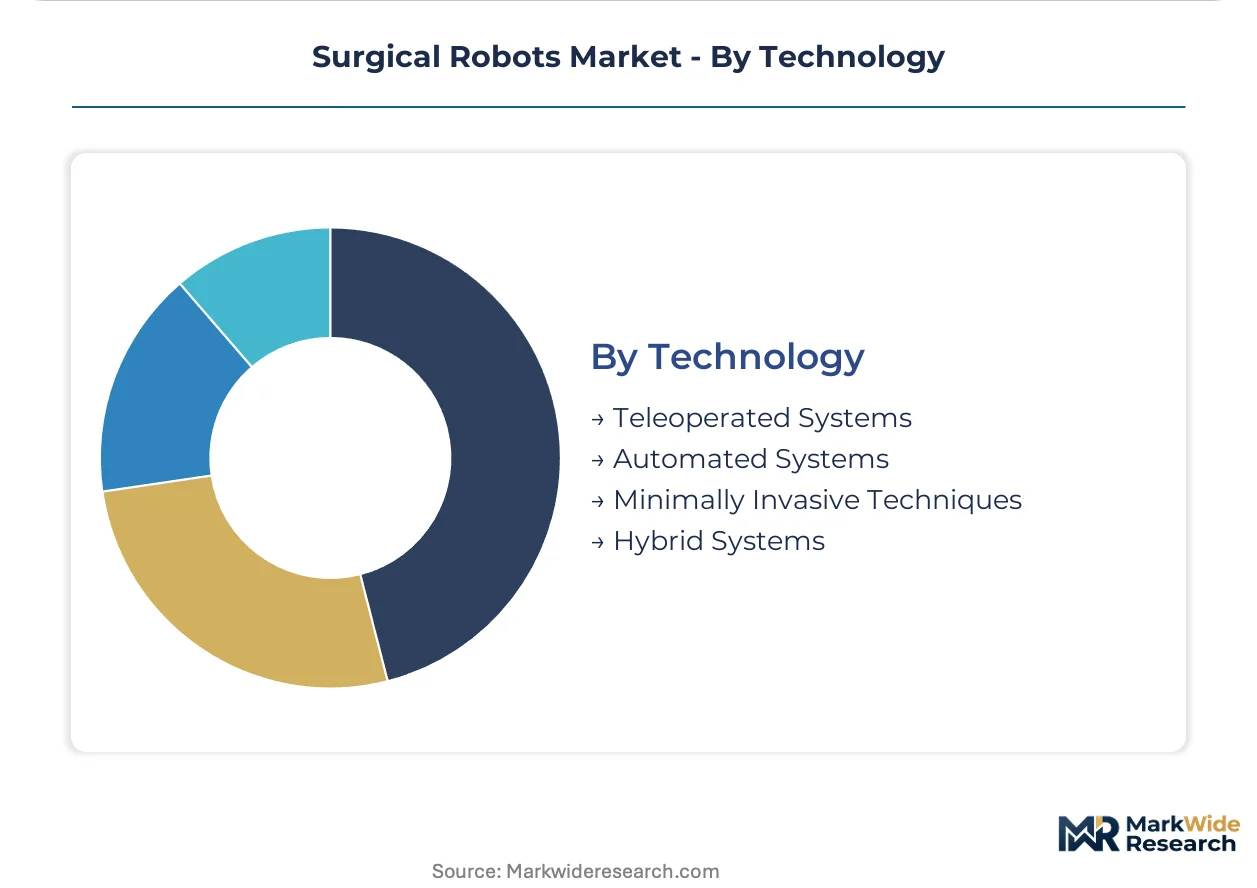
Technology:
Maturity gradients separate established teleoperated platforms from emerging automated categories facing evolving regulatory pathways.
- Teleoperated Systems:Master-slave architectures with real-time surgeon control dominate current installations. FDA premarket notification requirements for software updates maintain quality system scrutiny as autonomy algorithms advance.
- Automated Systems:Machine learning-driven instrument positioning reduces human-in-the-loop requirements for standardized tasks. Japan's PMDA fast-track pathway accelerates market entry for platforms with demonstrated safety profiles.
- Minimally Invasive Techniques:Laparoscopic and thoracoscopic access methods provide the procedural foundation.
- Hybrid Systems:Configurations combining teleoperation with autonomous subroutines bridge technology generations.
Teleoperated systems anchor the volume base while automated systems follow the steepest expansion trajectory as clinical validation accumulates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in the United States exceeds that in Germany by roughly 30% for comparable robotic surgical systems, reflecting divergent reimbursement frameworks and hospital procurement authority. This asymmetry shapes manufacturer prioritization across developed markets.
United States
Academic medical centers in Texas and Florida drive replacement demand as first-generation da Vinci platforms reach end-of-life. FDA premarket notification pathways for autonomous surgical features are tightening evidentiary standards for software-as-a-medical-device components. The Houston Methodist and Mayo Clinic networks anchor multi-specialty robotic surgery program expansion.
Germany
University hospitals in Bavaria and Baden-Württemberg concentrate procurement of teleoperated systems for complex urological and orthopedic procedures. The EU Medical Device Regulation mandates stricter clinical evidence for CE marking, favoring established manufacturers with validated quality management systems. Berlin Charité and Heidelberg University Hospital pilot integrated sensor fusion platforms for partial nephrectomy.
Japan
Metropolitan hospital systems in Tokyo and Osaka prioritize compact platforms for space-constrained surgical suites. The PMDA fast-track pathway expedites review for robotic surgical systems with demonstrated safety profiles, accelerating market entry timelines. Nagoya University Hospital and Juntendo University anchor training infrastructure expansion for robotic console operation.
India
Government medical college hospitals in Maharashtra and Karnataka present underpenetrated demand as surgical training infrastructure expands. The CDSCO regulates device safety and clinical validation pathways, with import licensing requirements shaping procurement timelines. Apollo Hospitals and Fortis Healthcare chains in Delhi-NCR and Chennai drive corporate hospital adoption.
United Kingdom
NHS trusts in London and the Southeast negotiate enterprise agreements for multi-port robotic systems as reimbursement parity for robotic procedures solidifies. The MHRA operates post-Brexit regulatory frameworks aligned with EU MDR standards but with separate UKCA marking requirements. Guy's and St Thomas' NHS Foundation Trust and Imperial College Healthcare anchor academic program scaling.
Surgical Robots Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in precision electromechanical supply chains. The vendor base concentrates among three to five established manufacturers with validated FDA quality system inspection records, while mid-tier entrants compete on financing flexibility. Two strategic archetypes dominate: integrated platform vendors leveraging installed base lock-in, and specialized orthopedic or navigation-focused competitors. Capacity expansion and strategic partnerships represent the dominant competitive moves, with manufacturers securing instrument arm actuator supply agreements to mitigate input cost volatility.
Among platform integrators, Intuitive Surgical and Stryker Corporation exemplify contrasting specialization strategies. Intuitive Surgical anchors the teleoperated system tier through its da Vinci installed base and recurring instrument revenue streams. Stryker Corporation occupies a position within orthopedic robotics, integrating haptic feedback controllers with navigation systems for spine and joint procedures. Medtronic sits within the diversified medical technology archetype, competing through surgical navigation integration across its broader portfolio rather than pure-play robotic specialization.
| Leading Market Players |
|---|
| Intuitive Surgical |
| Stryker Corporation |
| Medtronic |
| Smith & Nephew |
| Zimmer Biomet Holdings |
| Johnson & Johnson |
| CMR Surgical |
| Asensus Surgical |
| THINK Surgical |
| Others |
Supply Flow & Price Mechanics
Precision electromechanical component manufacturing concentrates among specialized suppliers in Japan and Germany, concentrating margin capture upstream while system integrators compete on financing flexibility and instrument attach rates downstream. This supply concentration shapes pricing power dynamics across robotic surgical platform tiers.
Pricing Analysis
The customization-premium spread between configured-to-order surgical platforms and standard configurations spans significant margin territory, with teleoperated systems commanding premium positioning against compact outpatient variants. Pricing stratifies across premium multi-port systems, standard single-port platforms, and economy-tier refurbished installations, with FDA quality system inspection records and ISO 13485 certification tiers serving as primary differentiation drivers. Cost compression in mid-tier hospital procurement is intensifying because ambulatory surgical centers negotiate per-procedure pricing without long-term exclusivity clauses. Corporate hospital chains in India exhibit highest price sensitivity, while academic medical centers in Germany and the United States demonstrate lowest sensitivity due to reimbursement parity and training infrastructure investments.
Supply Chain Analysis
Tariff exposure between precision manufacturing hubs in Japan and assembly operations in the United States and Germany dominates supply chain risk assessment for instrument arm actuator sourcing. Component manufacturing draws from Japan, Germany, and Switzerland for precision electromechanical actuators, optical tracking modules, and haptic feedback controllers. Raw material dependencies span rare earth magnets for motor assemblies, high-grade aluminum alloys for instrument arms, and specialized optical glass for camera stacks. Single-source vulnerability concentrates in sub-millimeter positioning sensor supply. Distribution runs through direct manufacturer sales forces for capital platforms, with third-party logistics handling instrument and consumable replenishment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Surgical robotics is approaching a platform-economics inflection where unbundled financing and interoperability standards are collapsing traditional installed-base lock-in, reshaping competitive moats around ecosystem breadth rather than hardware exclusivity.
For Market Incumbents: Entrench recurring revenue streams by deepening instrument supply agreements with GPO contracts managers and hospital procurement committees before competitive switching opportunities mature. Prioritize backward integration into precision actuator manufacturing to mitigate input cost volatility from Japanese and German suppliers. Defend against emerging compact platform entrants by accelerating FDA submissions for autonomous features that extend teleoperated system relevance.
For New Entrants and Emerging Players: Build out per-procedure financing capabilities targeting ambulatory surgical centers in Florida and Texas, where space constraints and throughput requirements favor compact platforms with faster setup protocols. India's government medical college hospitals present the most penetrable geography as surgical training infrastructure expands. Pursue go-to-market partnerships with regional distributors possessing established relationships with biomedical engineering departments.
For Investors and Strategic Acquirers: Capital is best deployed toward component specialists with validated FDA quality system inspection records and ISO 13485 certification across multiple notified bodies, as regulatory affairs resources become constraining across the analysis window. Long-term viability favors manufacturers with demonstrated clinical validation for autonomous instrument positioning algorithms. Watch PMDA fast-track designations and FDA premarket notification clearance timelines for novel platform developers as inflection indicators.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR compliance opens access to German university hospital procurement channels. |
| Hospital System Partnership | Enterprise agreements with Texas and Florida networks anchor multi-specialty program expansion. |
| Software Companion Development | Autonomous positioning algorithms reduce human-in-the-loop requirements for standardized procedures. |
| Reimbursement Strategy | CMS coding parity for robotic urological procedures solidifies hospital ROI timelines. |
| Backward Integration | Captive actuator manufacturing mitigates supply concentration risk from Japanese suppliers. |
Methodological Framework
A spread of perspectives from hospital purchasing committees, biomedical engineers, GPO contracts managers, and regulatory affairs leads converged on the working assumptions underlying demand and competitive dynamics. Primary interviews with clinicians and robotic surgery program directors combined with secondary validation against FDA 510(k) filings, EU MDR notified body databases, hospital procurement records, and CMS reimbursement coding updates. Bottom-up procedure volume modeling and top-down capital expenditure analysis triangulated market sizing across product and application segments.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, with segmentation dimensions spanning technology maturity, procedure complexity tiers, end-user facility type, and regional regulatory clusters. CAGRs derived from instrument replacement cycle analysis and platform depreciation schedules, incorporating surgeon training pipeline constraints and reimbursement policy evolution as industry-specific forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive moves by autonomous platform developers or unexpected FDA clearance accelerations would shift outcomes beyond modeled ranges. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
Middle East and Africa Medical Robots Market
Robotics and Automation
Biaxial Mobile Phone Stabilizer Market
Robotics and Automation
Smart Curtain Robot Market
Robotics and Automation
Cognitive Robotic Process Automation Market
Robotics and Automation
Global Adaptive Robotics Market
Robotics and Automation
Spain Cloud Robotics Market
Robotics and Automation
Global Mobile Robots Market
Robotics and Automation
South America AUV Market
Robotics and Automation
Long-Range Drone Package Delivery Market
Robotics and Automation
High-Precision Truss Robot Market
Robotics and Automation
Vision Guided Robotics Market
Robotics and Automation
Robotic Coffee Bars Market
Robotics and Automation
Social Robots Market
Robotics and Automation
Marine Robots Market
Robotics and Automation
China Autonomous Mobile Robot Market
Robotics and Automation
Commercial Robotics Market