
 Micro Robots Market | 2026-2036
Micro Robots Market Size, Share, and Industry Trends Forecast 2026-2036
Micro Robots Market Foresight
Aftermarket service revenue for legacy robotic platforms is narrowing as manufacturers shift toward integrated subscription models. Medtronic leverages its endovascular robotics portfolio to sustain recurring revenue from catheter-based procedures. Boston Scientific anchors its position through deep specialization in interventional micro-robotics for cardiac and peripheral vascular applications.
Micro robots are electromechanical devices typically measuring under one millimeter, fabricated through MEMS processes or soft lithography, designed to perform tasks in constrained environments inaccessible to conventional automation. Medical robots dominate current deployment, with Intuitive Surgical leading da Vinci-compatible micro-instrumentation while Stryker competes through its orthopedic navigation micro-tools; swarm robots represent the fastest-growing product category as distributed coordination algorithms mature for agricultural pollination and warehouse inventory applications.
FDA premarket notification requirements for Class II robotic surgical devices and ISO 13485 quality management standards shape product development cycles and market access timelines for manufacturers. EMA Medical Device Regulation compliance adds parallel certification burdens for European commercialization, particularly for AI-integrated navigation systems. Stakeholders must monitor evolving reimbursement codes for autonomous micro-robotic procedures across Medicare, NHS England, and Japan's MHLW to anticipate revenue model viability.
Market Dynamics
FDA premarket notification compression and EMA Medical Device Regulation streamlining are accelerating clearance timelines for autonomous micro-robotic surgical platforms, reshaping competitive entry velocity and R&D capitalization requirements across the sector.
Growth Catalysts
- Minimally Invasive Procedure Expansion:Hospital systems in Germany, Japan, and the United States are scaling catheter-based interventions, pulling demand for precision micro-instrumentation through da Vinci-compatible and endovascular platforms.
- EMA MDR Compliance Maturation:Parallel certification pathways for AI-integrated navigation systems are stabilizing, reducing European commercialization uncertainty for manufacturers with ISO 13485 quality management foundations.
- MEMS Fabrication Cost Curves:Soft lithography and electromechanical miniaturization processes are yielding sub-millimeter devices at unit economics viable for agricultural pollination and warehouse inventory swarms.
Market Restraints
- Platinum-Group Metal Input Volatility:MEMS electrode and actuator fabrication depends on palladium and platinum supply concentrated in South Africa and Russia, exposing cost structures to geopolitical disruption.
- Class II Device Regulatory Friction:FDA 510(k) substantial equivalence determinations for autonomous navigation features create timeline uncertainty distinct from predicate device pathways.
- Conventional Automation Substitution:Macro-scale robotic arms and fixed automation retain cost advantages for procedures and environments where workspace constraints do not mandate micro-scale deployment.
Strategic Opportunities
- India's PLI Scheme for Medical Devices:Production-linked incentives for precision manufacturing are attracting component fabrication and assembly investment outside established German and Japanese clusters.
- Swarm Coordination Algorithm Convergence:Distributed control systems combining reinforcement learning with edge computing are opening agricultural pollination and infrastructure inspection applications previously inaccessible to single-agent platforms.
- Japan MHLW Reimbursement Code Expansion:Autonomous micro-robotic procedure coverage under national health insurance is creating demand visibility for cardiac and peripheral vascular intervention systems.
Industry Challenges
- ISO 13485 Talent Scarcity:Quality management system auditors and regulatory affairs specialists with medical device micro-robotics experience command premium compensation, constraining mid-tier manufacturer scaling.
- Legacy Hospital IT Integration:Surgical navigation micro-robots require real-time interoperability with PACS, EMR, and imaging systems from incumbent vendors, extending deployment timelines and customization costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Micro Robots Market |
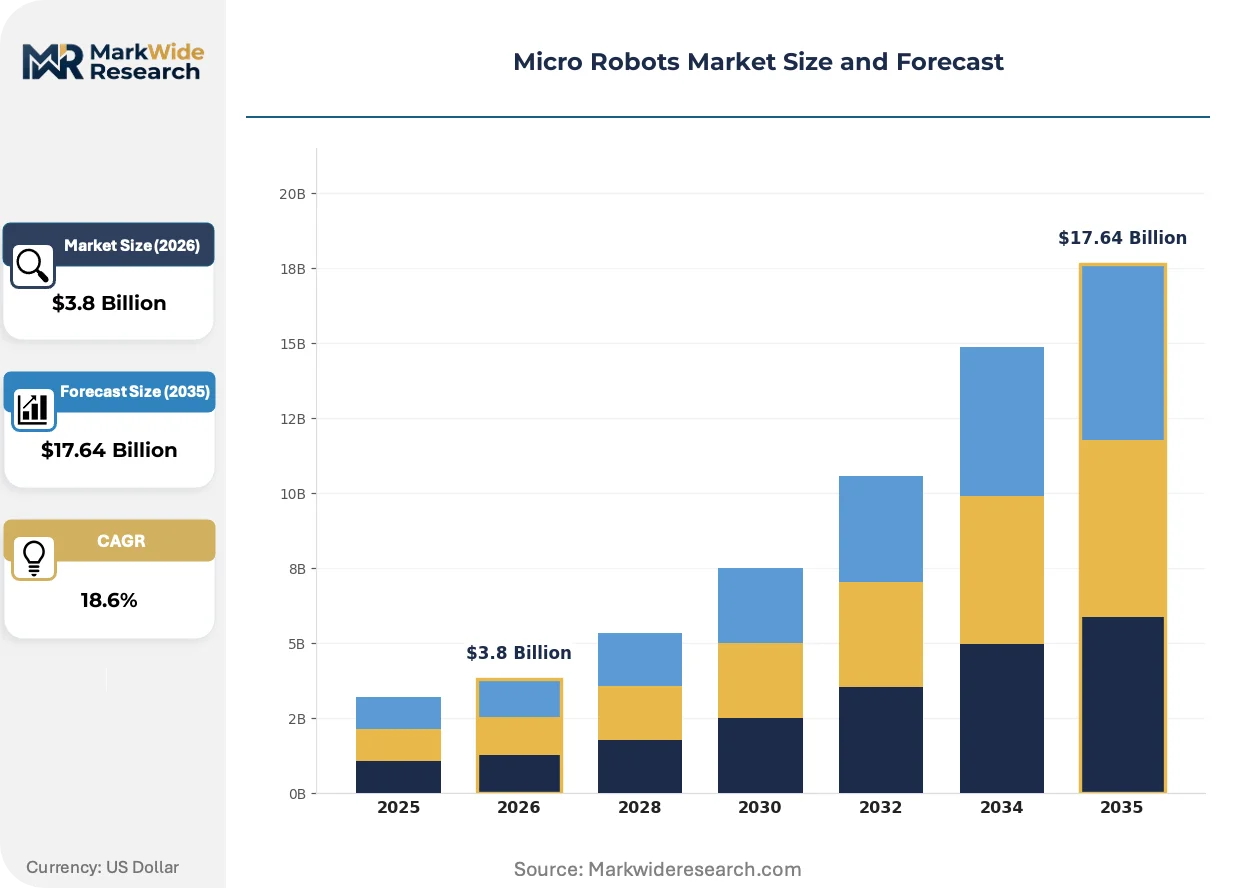
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $17.64 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Swarm Robots, Medical Robots, Industrial Robots, Autonomous Drones Application: Biomedical, Manufacturing, Agriculture, Surveillance End User: Healthcare, Entertainment, Defense, Education Technology: Robotics, AI Integration, Sensor Technology, Navigation Systems |
| Companies Covered | Medtronic, Boston Scientific, Stryker, Intuitive Surgical, Microbot Medical, Thermo Fisher Scientific, Seiko Epson Corporation, QinetiQ, ABB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Micro Robots Market Shifts & Advancements
Soft robotics and biomimetic locomotion systems are displacing rigid MEMS architectures in constrained biological environments, while regulatory frameworks for autonomous surgical action are codifying liability and certification standards.
Magnetic actuation combined with real-time imaging feedback is digitizing intraoperative navigation for endovascular procedures. Interventional cardiologists in tertiary hospital systems are adopting catheter-based micro-robotic platforms at accelerating pace for peripheral vascular interventions. This convergence is digitizing surgical workflow documentation and compressing training curves for complex anatomical access.
The EU AI Act's risk classification framework for autonomous medical decision-support systems is imposing conformity assessment requirements on navigation algorithms. Manufacturers must demonstrate explicability and human oversight protocols for real-time path planning functions. Cardiac ablation and neurointerventional systems face the steepest compliance investment, with German notified bodies establishing specialized review pathways.
Hospital procurement departments are unbundling after-sales service from capital equipment contracts, demanding subscription-based software update and predictive maintenance models. Integrated service agreements are displacing traditional time-and-materials support for da Vinci-compatible micro-instrumentation. This reconfiguration is most visible in United States IDN consolidation, where centralized sourcing mandates standardized platform ecosystems across multi-hospital networks.
Micro Robots Market Segmentation
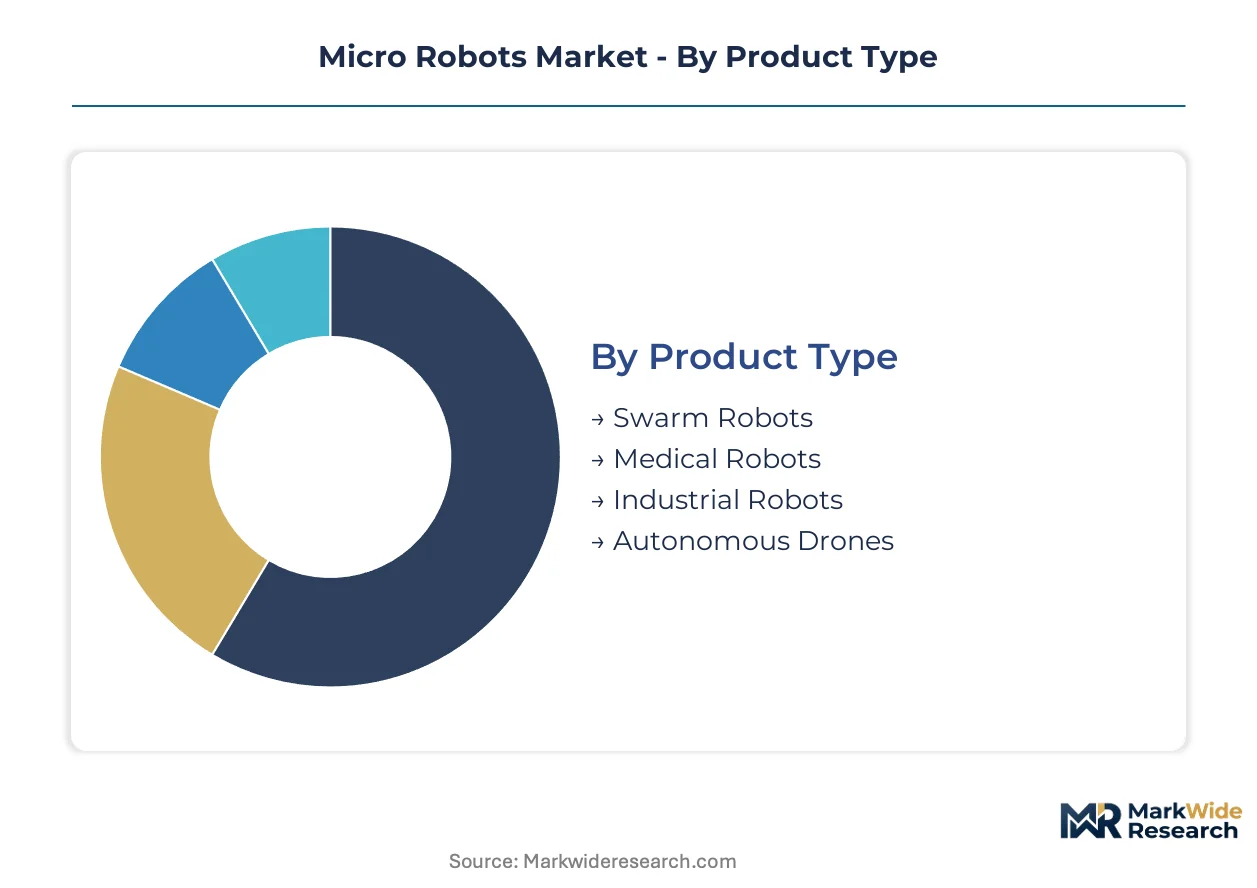
Micro robot architectures diverge sharply across deployment environments, with electromechanical constraints and regulatory pathways dictating viable commercial configurations. Manufacturers must align fabrication processes—MEMS lithography versus soft robotics—with specific end-use durability and precision requirements.
Product Type:
Cost tier stratification separates capital-intensive surgical platforms from disposable agricultural swarms and industrial inspection units.
- Swarm Robots:Distributed electromechanical agents under one millimeter, fabricated through soft lithography for agricultural pollination and warehouse inventory coordination. Demand concentrates in Japan's precision agriculture clusters and German logistics hubs, pulled by pollinator decline compensation and same-day fulfillment density requirements.
- Medical Robots:Catheter-based endovascular platforms and da Vinci-compatible micro-instrumentation dominate hospital procurement in the United States and Germany. FDA 510(k) clearance compression and EMA MDR streamlining are accelerating competitive entry velocity for autonomous navigation features.
- Industrial Robots:MEMS-fabricated inspection units for confined-space infrastructure assessment, with magnetic actuation enabling sub-millimeter maneuverability in pipeline and turbine applications.
- Autonomous Drones:Miniaturized aerial platforms for surveillance and environmental monitoring, constrained by FAA and EASA airspace integration timelines.
Medical robots hold installed capacity. Swarm robots are rotating up the share rankings.
Application:
Application maturity tracks reimbursement code availability and regulatory precedent density.
- Biomedical:Cardiac ablation, peripheral vascular intervention, and targeted drug delivery systems command premium pricing in tertiary hospital systems across the United States, Germany, and Japan. PMDA and FDA parallel review pathways are compressing development timelines for AI-integrated navigation.
- Manufacturing:Precision assembly and quality inspection in semiconductor and pharmaceutical cleanrooms, with ISO 14644 compliance dictating particulate contamination thresholds for micro-robot deployment.
- Agriculture:Pollination swarms and crop monitoring units, expanding most quickly in Japanese protected cultivation facilities and Dutch greenhouse complexes where labor scarcity intersects with pollination service monetization.
- Surveillance:Infrastructure perimeter monitoring and environmental sensing, constrained by GDPR and state-level privacy regulations governing autonomous data collection.
Biomedical applications anchor revenue concentration. Agriculture is climbing the fastest.
End User:
Customer procurement sophistication ranges from centralized IDN tender processes to discretionary educational institution budgets.
- Healthcare:Hospital systems and ambulatory surgical centers in the United States, Germany, and Japan drive demand for catheter-based platforms, with Japan MHLW reimbursement code expansion creating demand visibility for cardiac interventions.
- Defense:Covert surveillance and explosive ordnance disposal applications, with procurement concentrated through national security apparatuses and subject to ITAR and EU dual-use export controls.
- Entertainment:Consumer micro-drones and interactive exhibits, with demand fragmented across discretionary spending segments and trade show rental markets.
- Education:University research laboratories and technical training programs, with procurement cycles tied to grant funding availability and curriculum standardization timelines.
Healthcare dominates capital deployment. Defense is gaining share fastest.
Technology:
Technology stack integration determines regulatory classification and liability exposure under EU AI Act and FDA software-as-medical-device frameworks.
- Robotics:Core electromechanical architectures spanning rigid MEMS and soft biomimetic locomotion systems, with soft robotics displacing traditional fabrication in constrained biological environments.
- AI Integration:Real-time path planning and autonomous decision-support algorithms, subject to EMA MDR and EU AI Act conformity assessment for explicability and human oversight protocols.
- Sensor Technology:Miniaturized imaging, force feedback, and chemical detection modules enabling closed-loop control in surgical and agricultural deployments.
- Navigation Systems:Magnetic actuation combined with intraoperative imaging feedback, digitizing endovascular procedure workflows in United States tertiary hospital systems.
Robotics foundations hold process maturity. AI integration is rotating up the investment priority rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement in Japan shows the lowest price elasticity for micro-robotic surgical platforms, while agricultural swarm deployments in India exhibit acute sensitivity to unit economics. German precision manufacturing clusters absorb premium pricing for MEMS-fabricated inspection units. United States IDN consolidation is compressing vendor margins through standardized platform mandates.
United States
Tertiary hospital systems in Cleveland Clinic and Mayo Clinic networks are scaling catheter-based micro-robotic interventions for peripheral vascular procedures. FDA 510(k) clearance compression for autonomous navigation features is accelerating competitive entry timelines for new platform vendors. Boston Scientific and Medtronic anchor endovascular robotics development in Minneapolis and Marlborough corridors.
Germany
Precision manufacturing clusters around Stuttgart and Munich are absorbing MEMS-fabricated industrial inspection robots for turbine and pipeline applications. EMA MDR compliance maturation for AI-integrated navigation systems is stabilizing European commercialization pathways. Fraunhofer Institutes in Dresden and Berlin are advancing soft lithography processes for sub-millimeter swarm fabrication.
Japan
Protected cultivation facilities in Chiba and Ibaraki prefectures are deploying pollination swarms to compensate for managed honeybee decline. MHLW reimbursement code expansion for autonomous micro-robotic cardiac procedures is creating demand visibility for catheter-based platforms. Olympus and Terumo anchor medical robotics development in Tokyo and Kanagawa precision manufacturing zones.
India
Agricultural labor scarcity in Maharashtra and Gujarat is driving experimental pollination swarm pilots at unit economics below manual alternatives. PLI scheme production-linked incentives for precision medical device manufacturing are attracting component fabrication investment to Bangalore and Hyderabad. CDSCO regulatory harmonization with FDA pathways is compressing development timelines for domestic micro-robotic platform vendors.
United Kingdom
NHS England centralized procurement is mandating subscription-based service models for surgical robotics, displacing traditional capital equipment purchasing. MHRA post-Brexit regulatory autonomy is diverging from EMA MDR timelines for AI-integrated navigation systems. Cambridge and Oxford university spinouts are concentrating swarm coordination algorithm development for agricultural and infrastructure inspection applications.
Micro Robots Market Competitive Landscape
Capability concentration sits with specialized MEMS fabricators and soft robotics laboratories; scale advantage sits with diversified medical device conglomerates with established hospital system relationships. The market structures around three tiers: integrated surgical platform vendors, component specialists supplying catheter-based actuation systems, and emerging swarm robotics developers targeting agricultural and logistics applications. Dominant competitive moves include strategic partnerships between MEMS foundries and medical device OEMs, plus geographic expansion through India's PLI scheme for precision manufacturing.
Among diversified medical technology conglomerates, Medtronic and Boston Scientific exemplify the integrated platform archetype, combining endovascular robotics portfolios with recurring revenue from catheter-based procedures. Intuitive Surgical occupies a distinct position in da Vinci-compatible micro-instrumentation, sustaining installed base economics through proprietary ecosystem lock-in. Stryker represents orthopedic navigation specialization, competing through micro-tool integration with surgical navigation systems rather than standalone robotic platforms.
| Leading Market Players |
|---|
| Medtronic |
| Boston Scientific |
| Stryker |
| Intuitive Surgical |
| Microbot Medical |
| Thermo Fisher Scientific |
| Seiko Epson Corporation |
| QinetiQ |
| ABB |
| Others |
Supply & Pricing Matrix
Freight corridors connecting German precision manufacturing clusters to United States hospital systems transmit MEMS component costs into downstream surgical platform pricing, with platinum-group metal volatility from South African supply nodes compressing margins for catheter-based device manufacturers while subscription bundling shifts lifetime value capture toward software tiers.
Pricing Analysis
After-sales service contracts and predictive maintenance subscriptions generate disproportionate lifetime value compared to capital equipment sales. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared autonomous navigation systems from predicate-compatible devices and unbundled component sales. Pricing pressure stems from United States IDN procurement consolidation mandating standardized platform ecosystems. Agricultural swarm buyers in India exhibit acute unit economics sensitivity, while Japanese hospital systems absorb premium surgical robotics with minimal price elasticity.
Supply Chain Analysis
Taiwanese MEMS foundries and German precision manufacturing clusters hold concentrated fabrication capacity for sub-millimeter electromechanical components. Raw material dependencies center on palladium and platinum for electrode fabrication, soft lithography polymers for swarm robotics, and specialized magnetic alloys for actuation systems. Single-source vulnerability in South African platinum-group metal supply exposes cost structures to geopolitical disruption. Distribution runs through medical device OEM direct sales forces for surgical platforms and agricultural equipment distributors for pollination swarms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized ISO 13485 quality management expertise and regulatory affairs talent with micro-robotics experience command scarcity premiums, constraining scaling velocity for mid-tier manufacturers and fragmenting competitive capability distribution.
For Market Incumbents: Entrench hospital system relationships through integrated subscription models that bundle software updates with predictive maintenance, displacing time-and-materials service contracts. Deepen backward integration into MEMS fabrication capacity in German and Japanese precision manufacturing zones to secure component supply against platinum-group metal volatility. Fortify against emerging swarm robotics developers by acquiring soft lithography process capabilities before agricultural applications commoditize. For New Entrants and Emerging Players: Build out agricultural pollination swarm offerings targeting Japanese protected cultivation facilities and Dutch greenhouse complexes where labor scarcity intersects with pollinator decline compensation. India's PLI scheme for precision medical device manufacturing offers component fabrication entry points with compressed CDSCO regulatory timelines. Pursue hospital procurement through GPO channel partnerships rather than direct IDN sales forces. For Investors and Strategic Acquirers: FDA 510(k) clearance compression for autonomous navigation features reshapes the acquisition landscape toward platform vendors with predicate device pathways and established quality management foundations. Five-to-ten year viability favors diversified medical technology conglomerates with recurring revenue from catheter-based procedures over pure-play hardware manufacturers. Monitor Japan MHLW reimbursement code expansion for autonomous micro-robotic cardiac procedures as demand inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Submission Pathway Optimization | 510(k) substantial equivalence compression accelerates competitive entry for autonomous navigation platforms. |
| Hospital System Partnership | IDN consolidation mandates standardized ecosystems across multi-hospital networks in United States corridors. |
| Backward Integration into MEMS Fabrication | In-house production of sub-millimeter components insulates against platinum-group metal supply volatility. |
| Reimbursement Strategy Development | MHLW code expansion in Japan creates demand visibility for cardiac and peripheral vascular interventions. |
| Software Companion Development | EU AI Act conformity assessment for explicability protocols imposes compliance investment on navigation algorithms. |
Research Methodology
A spread of perspectives from biomedical engineers, hospital purchasing committees, MEMS fabrication specialists, and regulatory affairs leads converged on the working assumptions underlying this analysis. Primary fieldwork with GPO contracts managers and aftermarket service heads supplemented secondary validation through FDA 510(k) filings, EMA MDR submission databases, hospital procurement records, and CMS Medicare reimbursement code updates. Bottom-up segmentation modeling triangulated against top-down macroeconomic drivers.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, with segmentation dimensions spanning product architecture, application maturity, end-user procurement sophistication, and technology stack integration. CAGRs derived from installed base growth curves and replacement cycle dynamics in surgical robotics, cross-referenced with swarm robotics unit economics in agricultural pilots. Forecast inputs incorporated reimbursement code expansion trajectories and MEMS fabrication cost curve projections.
The forecast holds incumbent behavior within observed patterns; aggressive vertical integration moves by diversified medical technology conglomerates or rapid regulatory harmonization by CDSCO would shift outcomes. Quarterly review of FDA 510(k) clearance timelines, Japan MHLW reimbursement code publications, and platinum-group metal spot price movements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
Africa Agricultural Robots and Mechatronics Market
Robotics and Automation
AGV Dispatch Management Platforms Market
Robotics and Automation
Autonomous Mobile Manipulator Robots (AMMR) Market
Robotics and Automation
Robotics Sweeper Market
Robotics and Automation
Automated Liquid Handling Technologies Market
Robotics and Automation
Humanoid Robot Market
Robotics and Automation
LAMEA Waste Sorting Robots Market
Robotics and Automation
Pipetting Robots Market
Robotics and Automation
Mobile Cobots Market
Robotics and Automation
Global Automotive Gesture Recognition System Market
Robotics and Automation
Disinfectant Robot Market
Robotics and Automation
India Cloud Robotics Market
Robotics and Automation
Autonomous Mobile Robots for Logistics and Warehousing Market
Robotics and Automation
Robotic Flexible Washer Market
Robotics and Automation
Harvesting Robot Market
Robotics and Automation
Global Robot Teach Pendant Market