
 Vision Guided Robotics Market | 2026-2036
Vision Guided Robotics Market Size, Share, and Industry Trends Forecast 2026-2036
Vision Guided Robotics Market Intelligence
High-precision sub-millimeter vision systems is bifurcating the competitive landscape into premium sensor-integrated suppliers and cost-optimized module vendors. FANUC Corporation anchors its position through captive supply of optical encoders and proprietary vision controllers. ABB Ltd. competes across automotive and electronics end users with unified robot-vision software stacks. Cognex Corporation specializes in standalone machine vision hardware that third-party integrators embed into custom robotic workcells.
Vision guided robotics integrates machine vision cameras, AI processing units, and sensor fusion algorithms to enable robots to perceive, locate, and manipulate objects without fixed tooling or pre-programmed coordinates; systems typically operate at frame rates exceeding 60 Hz with spatial resolution below 0.1 mm for precision assembly tasks. Industrial robots retain the largest installed base due to established automotive demand for welding and material handling automation. Collaborative robots represent the fastest-expanding product category as ISO/TS 15066 safety standards enable unguarded human-robot interaction in electronics and food processing environments. Machine vision technology captures the dominant share of value as lens, lighting, and image processing hardware constitute the primary cost stack in most system configurations.
The EU AI Act classifies autonomous manufacturing robots as high-risk AI systems, mandating conformity assessments before CE marking and market entry. FDA regulates vision-guided surgical robots in the United States under 21 CFR 892, requiring premarket notification for computer-assisted detection functions. OSHA machine guarding standards influence sensor fusion architecture decisions, as manufacturers design systems that eliminate physical barriers without compromising worker safety. Stakeholders must monitor how evolving liability frameworks for autonomous decision-making reshape procurement criteria and vendor qualification processes across regulated industries.
Market Dynamics
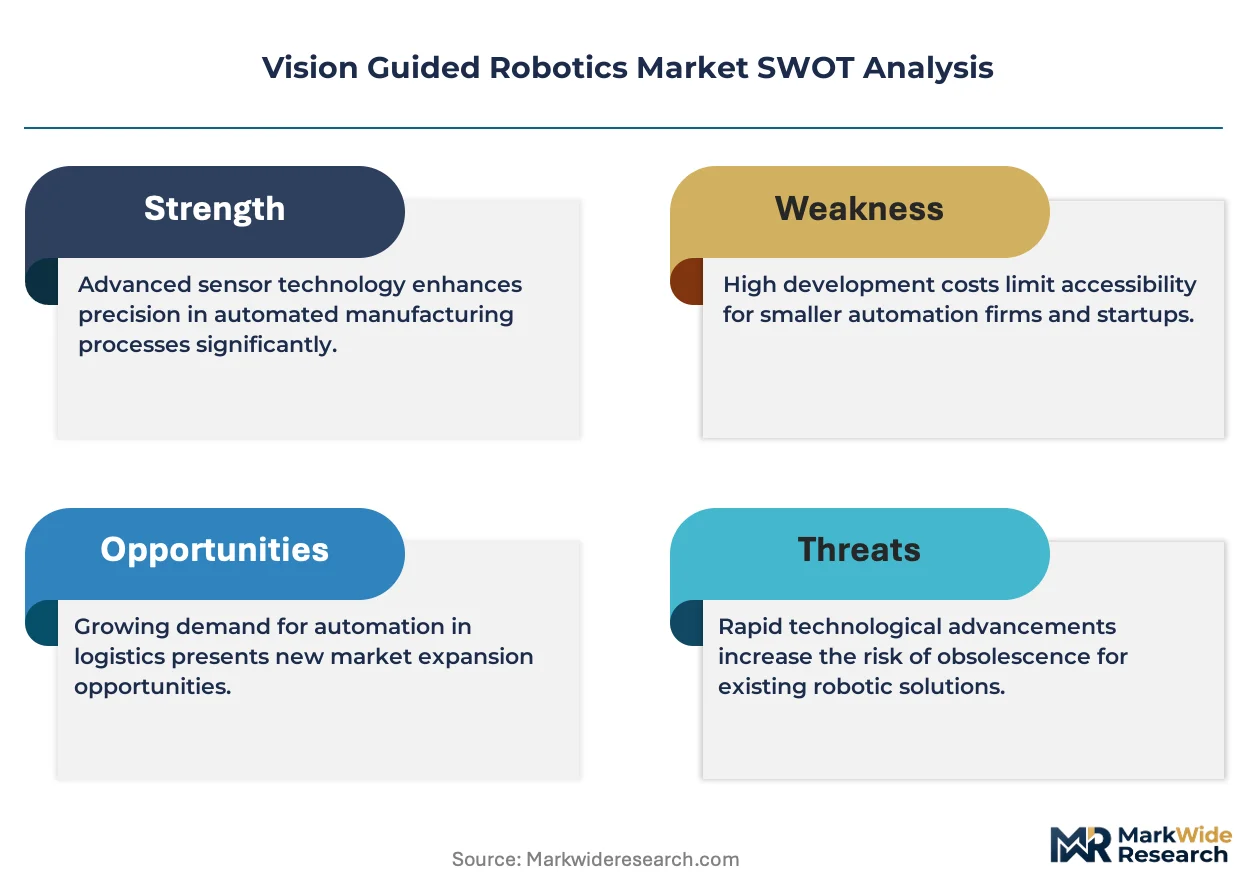
AI Act conformity assessments are compressing vendor qualification timelines while automotive OEMs demand sub-millimeter precision without fixed tooling infrastructure. This regulatory-technical tension is redrawing competitive boundaries between integrated system suppliers and modular component vendors.
Growth Catalysts
- EU AI Act high-risk classification:CE marking mandates for autonomous manufacturing robots are accelerating procurement of pre-certified vision systems from qualified vendors.
- Automotive precision assembly:German and Japanese OEMs require vision-guided welding and material handling to eliminate fixed jigs and reduce changeover downtime.
- Sensor fusion advancement:Multi-modal perception combining structured light, stereo vision, and tactile feedback enables handling of deformable and reflective surfaces previously requiring manual intervention.
Market Restraints
- Optical encoder supply concentration:Japanese and German suppliers control high-resolution encoder manufacturing, creating input bottlenecks for precision motion control subsystems.
- Computational hardware cost structure:GPU and FPGA prices for real-time image processing consume 35-45% of system bill-of-materials at volume.
- Legacy integration friction:Existing PLC and SCADA architectures in brownfield facilities resist seamless incorporation of AI-driven vision controllers without substantial middleware investment.
Strategic Opportunities
- Food processing collaborative deployment:ISO/TS 15066-compliant systems enable unguarded human-robot interaction in protein handling and packaging where sanitation requirements prohibit traditional guarding.
- India PLI scheme manufacturing:Electronics assembly incentives are attracting vision-guided robotics investment for smartphone and semiconductor packaging lines.
- Edge AI convergence:On-device neural network inference is reducing latency and eliminating cloud dependency for safety-critical pick-and-place operations.
Industry Challenges
- Multidisciplinary talent scarcity:System integrators struggle to hire engineers proficient simultaneously in optical physics, robotic kinematics, and production environment safety.
- Certification timeline compression:EU AI Act conformity assessments and FDA 21 CFR 892 premarket reviews for surgical applications extend product launch cycles by 12-18 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vision Guided Robotics Market |
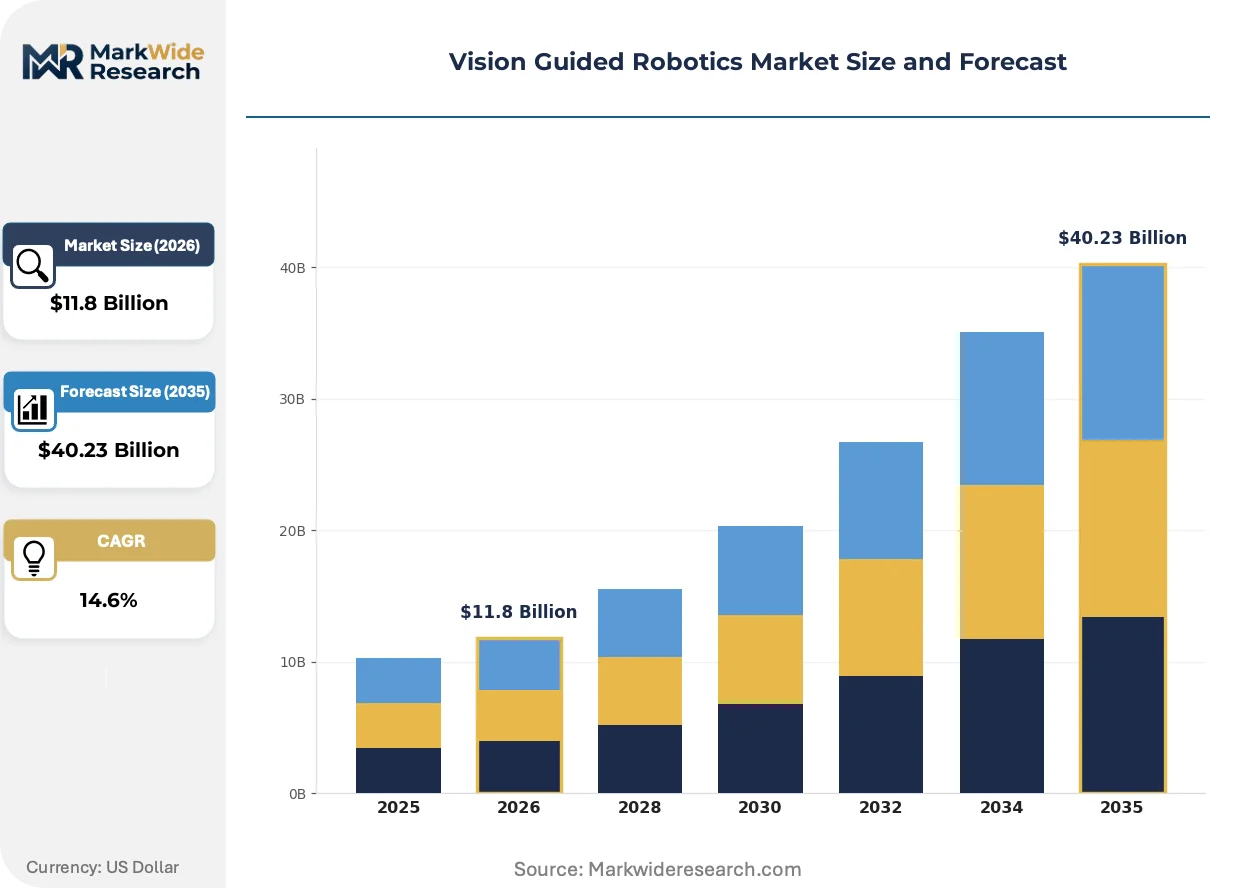
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $40.23 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mobile Robots, Industrial Robots, Collaborative Robots, Humanoid Robots Technology: Machine Vision, AI Processing, Sensor Fusion, Image Processing End User: Automotive Manufacturers, Electronics Producers, Food & Beverage Industries, Healthcare Facilities Application: Assembly Line Automation, Quality Inspection, Packaging, Material Handling |
| Companies Covered | FANUC Corporation, ABB Ltd., Yaskawa Electric Corporation, KUKA AG, Cognex Corporation, Denso Corporation, Omron Corporation, Universal Robots, Keyence Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vision Guided Robotics Market Strategic Shifts & Innovations
Vision processing architectures are migrating from centralized GPU clusters to distributed edge compute nodes. This decentralization is compressing latency budgets and enabling new safety architectures for human-robot collaboration.
Hyperspectral imaging is fragmenting quality inspection applications previously dominated by RGB and monochrome systems. Pharmaceutical manufacturers in Switzerland and Germany are deploying 400-1000nm spectral cameras to detect coating defects and foreign particulate contamination invisible to standard sensors. The technology is fragmenting the machine vision hardware tier into application-specific spectral configurations versus general-purpose platforms.
REACH substance restrictions and RoHS amendments are constraining illuminator component sourcing for European deployments. LED phosphor formulations containing restricted rare earth elements face substitution pressures, forcing lighting subsystem redesigns. Automotive Tier 1 suppliers in Stuttgart and Wolfsburg are qualifying alternative emitter technologies to maintain CE compliance without performance degradation.
Electronics contract manufacturers are unbundling vision system specification from robot procurement decisions. Foxconn and similar assemblers now source cameras, processors, and software from distinct vendors rather than accepting captive vision stacks from robot OEMs. This disintermediation is most pronounced in Shenzhen and Taipei, where integration expertise concentrates and price transparency pressures bundled margins.
Vision Guided Robotics Market Segmentation
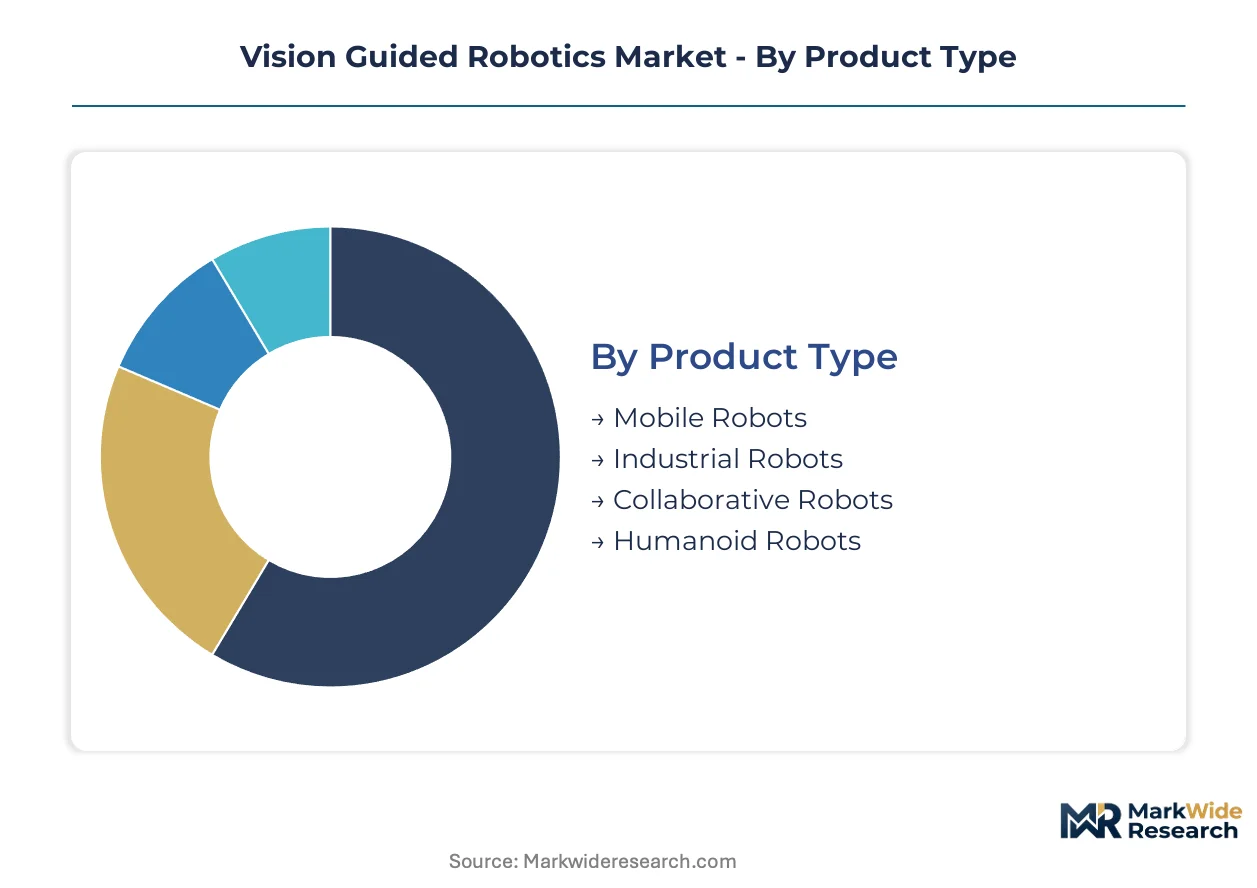
Segmentation in vision guided robotics reveals how technical specifications, regulatory boundaries, and end-use requirements partition procurement decisions. Product architecture, processing technology, and target industry each impose distinct qualification criteria that reshape vendor competitive boundaries.
Product Type:
Substitution pressure concentrates heaviest on legacy industrial robot configurations as collaborative and mobile platforms displace fixed-guarding installations.
- Industrial Robots:Six-axis articulated arms with integrated vision controllers dominate automotive welding and heavy-payload material handling. German OEMs in Stuttgart and Wolfsburg specify these for powertrain assembly where payload capacity exceeds 200 kg and cycle time tolerances sit below 50 milliseconds.
- Collaborative Robots:Force-limited articulated arms with embedded safety-rated vision systems enable unguarded human-robot interaction. ISO/TS 15066 compliance drives electronics assemblers in Japan and food processors in Denmark toward these platforms where sanitation or frequent changeover prohibits fixed barriers.
- Mobile Robots:Autonomous mobile platforms with SLAM-based navigation and overhead vision guidance for warehouse logistics and inter-facility transport.
- Humanoid Robots:Bipedal platforms with stereo vision and dexterous manipulation for research, logistics, and emerging service applications.
Industrial robots retain volume leadership; collaborative robots hold the steepest expansion curve.
Technology:
Cost tier stratification separates premium sensor-integrated stacks from modular processing units that third-party integrators assemble.
- Machine Vision:Camera, lens, and lighting subsystems capturing spatial data at sub-millimeter resolution for precision guidance. Lens and illuminator hardware constitutes the dominant cost stack in most configurations, with LED phosphor formulations facing REACH substitution pressures in European deployments.
- Sensor Fusion:Multi-modal perception combining structured light, stereo vision, and tactile feedback to handle deformable and reflective surfaces. Automotive Tier 1 suppliers in Japan deploy these systems for seam-sealing applications where specular reflection confuses single-mode sensors.
- AI Processing:GPU and FPGA hardware for real-time neural network inference, consuming 35-45% of system bill-of-materials at volume.
- Image Processing:Software algorithms for feature extraction, pattern matching, and geometric analysis running on edge or centralized compute.
Machine vision captures the dominant value share; sensor fusion is climbing the fastest as multi-modal requirements spread beyond automotive into food and electronics handling.
End User:
Application maturity varies sharply by sector, with automotive and electronics commanding established specification standards while healthcare and food processing build qualification frameworks.
- Automotive Manufacturers:Precision assembly of powertrain and body-in-white components with sub-millimeter tolerances. German and Japanese OEMs drive specification for welding and material handling applications that eliminate fixed jigs.
- Electronics Producers:High-speed pick-and-place and micro-assembly for semiconductor packaging and smartphone manufacturing. Foxconn and similar contract manufacturers in Shenzhen and Taipei unbundle vision specifications from robot procurement.
- Food & Beverage Industries:Protein handling, packaging, and palletizing where sanitation requirements and product variability demand adaptive vision systems.
- Healthcare Facilities:Surgical robotics and laboratory automation regulated under FDA 21 CFR 892 in the United States and requiring premarket notification for computer-assisted detection functions.
Automotive manufacturers retain procurement volume leadership; healthcare facilities present the steepest regulatory-gated expansion trajectory.
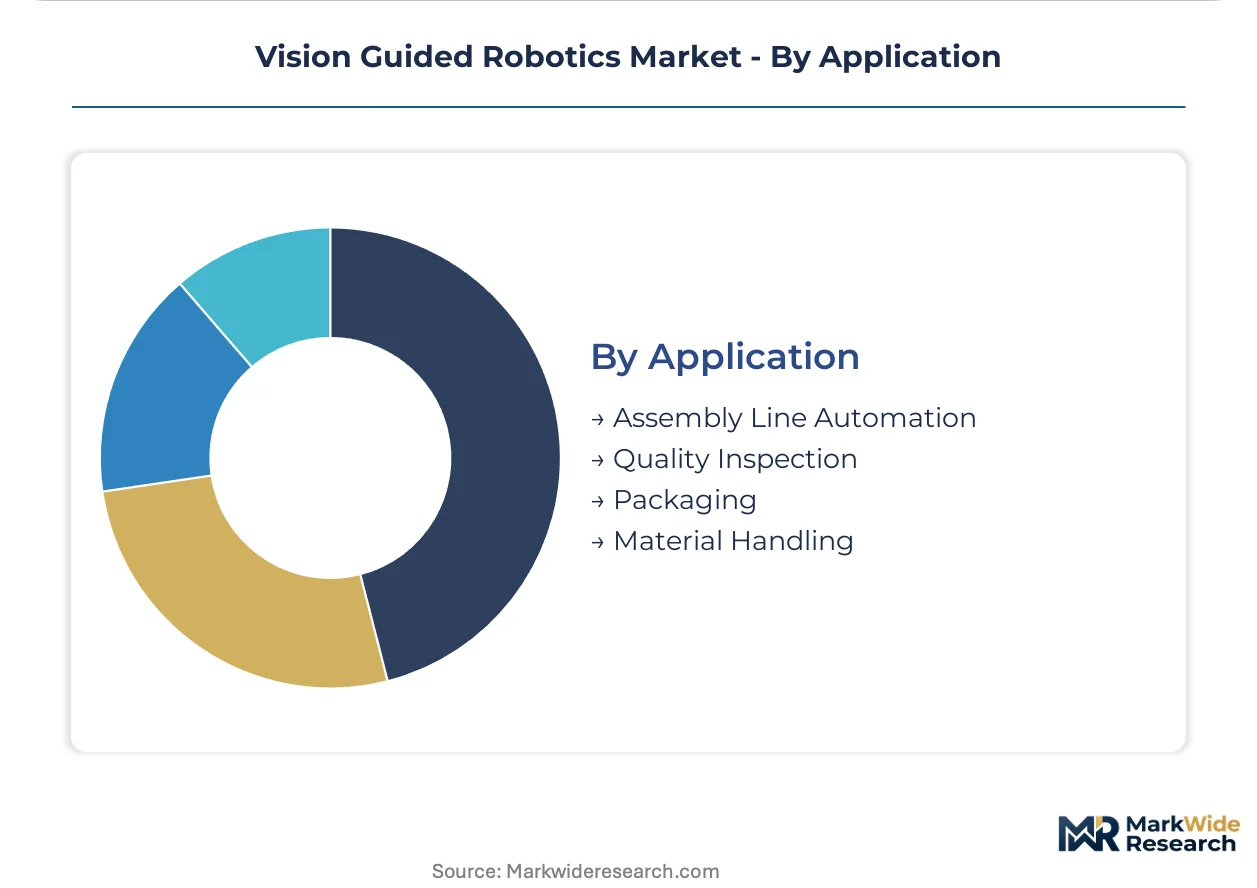
Application:
Customer type differentiation separates high-volume repetitive operations from adaptive tasks requiring real-time environmental response.
- Assembly Line Automation:Vision-guided robotic joining, fastening, and component placement with dynamic coordinate adjustment. German automotive plants deploy these systems to reduce changeover downtime when model variants shift.
- Quality Inspection:Dimensional verification and defect detection using hyperspectral imaging in pharmaceutical manufacturing. Swiss and German producers deploy 400-1000nm spectral cameras to detect coating defects invisible to standard RGB sensors.
- Material Handling:Bin picking, palletizing, and machine tending with unstructured object recognition.
- Packaging:Adaptive case packing and palletizing for variable product formats in consumer goods and food processing.
Assembly line automation retains installed base dominance; quality inspection is expanding most quickly as hyperspectral and AI-enhanced detection penetrates pharmaceutical and electronics verification.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German precision engineering exports supply automotive assembly lines across Stuttgart and Wolfsburg to Japanese electronics manufacturers in Osaka and Nagoya. This trade corridor concentrates high-resolution encoder demand in two manufacturing clusters.
Germany
Automotive OEMs in Stuttgart and Wolfsburg specify sub-millimeter vision systems for powertrain assembly without fixed jigs. EU AI Act conformity assessments apply to autonomous manufacturing robots before CE marking. Baden-Württemberg suppliers face REACH substitution pressures on LED phosphor formulations for illuminator hardware.
Japan
Electronics assemblers and automotive Tier 1 suppliers deploy sensor fusion for seam-sealing applications with specular reflection challenges. METI oversees industrial robot safety standards aligned with ISO frameworks. Nagoya and Osaka manufacturing clusters drive encoder demand for precision motion control subsystems.
United States
FDA regulates vision-guided surgical robots under 21 CFR 892 with premarket notification requirements for computer-assisted detection. OSHA machine guarding standards influence sensor fusion architecture decisions for unguarded human-robot collaboration. Michigan and Ohio automotive plants integrate vision controllers into brownfield PLC environments.
China
Electronics contract manufacturers in Shenzhen and Taipei unbundle vision specifications from robot procurement decisions. MIIT and SAMR administer GB standards for industrial automation equipment. Yangtze River Delta and Pearl River Delta clusters concentrate smartphone and semiconductor packaging investment.
India
PLI scheme incentives attract vision-guided robotics investment for electronics assembly and smartphone manufacturing. BIS certification applies to industrial robot safety components. Karnataka and Tamil Nadu manufacturing corridors expand precision assembly capacity for export markets.
Vision Guided Robotics Market Key Industry Players
Listed leaders compete with private specialists across captive supply chains and modular integration tiers. The market structure concentrates around integrated system suppliers controlling optical encoder production alongside independent machine vision hardware vendors. Three archetypes dominate: Japanese-German precision conglomerates with captive component supply, European robot OEMs with unified software stacks, and standalone vision hardware specialists serving third-party integrators. Competitive moves center on backward integration into encoder manufacturing and geographic expansion through qualification for EU AI Act conformity assessments.
Among Japanese precision conglomerates, FANUC Corporation and Yaskawa Electric Corporation exemplify the captive supply archetype through in-house production of motion control components. ABB Ltd. occupies a position representing European integrated system suppliers competing across automotive and electronics end users. Cognex Corporation anchors the standalone vision hardware tier that third-party integrators embed into custom robotic workcells.
| Leading Market Players |
|---|
| FANUC Corporation |
| ABB Ltd. |
| Yaskawa Electric Corporation |
| KUKA AG |
| Cognex Corporation |
| Denso Corporation |
| Omron Corporation |
| Universal Robots |
| Keyence Corporation |
| Others |
Cost & Logistics Intelligence
EU AI Act conformity assessments gate both supplier qualification timelines and price differentiation across certification tiers, compressing margins for uncertified vendors while enabling premium positioning for pre-qualified system integrators serving automotive and healthcare end users.
Pricing Analysis
Next-generation edge AI inference hardware commands 40-60% premiums over centralized GPU architectures, while legacy FPGA-based systems face accelerated depreciation. Pricing stratifies across premium sensor-integrated stacks, standard modular configurations, and economy camera-only tiers. Cost compression in the economy tier intensifies because contract manufacturers in Shenzhen unbundle vision specifications and source commoditized components directly. Automotive OEMs in Stuttgart exhibit lowest price sensitivity due to changeover downtime costs, while electronics assemblers in India show highest sensitivity under PLI scheme margin constraints.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes are extending lead times for GPU and FPGA shipments from Taiwan and South Korea. High-resolution optical encoder production concentrates in Japan and Germany, creating single-source vulnerability for precision motion control subsystems. LED phosphor formulations containing restricted rare earth elements face REACH substitution pressures, forcing illuminator redesigns for European deployments. Distribution runs through Tier 1 automotive suppliers in Stuttgart and Wolfsburg, electronics contract manufacturers in Shenzhen and Taipei, and system integrators serving pharmaceutical producers in Switzerland.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents must defend against modular disintermediation as electronics contract manufacturers unbundle vision specifications and source components from distinct vendors, eroding bundled margin structures.
For Market Incumbents: Secure captive encoder supply through backward integration into Japanese or German precision manufacturing clusters. Accelerate EU AI Act pre-certification to compress competitor qualification timelines. Defend against Foxconn-style unbundling by embedding proprietary vision controllers into robot firmware layers.
For New Entrants and Emerging Players: CE marking fast-tracks for collaborative robot platforms open white-space penetration in Danish food processing and Indian electronics assembly under PLI incentives. Target protein handling applications where ISO/TS 15066 compliance enables unguarded deployment and sanitation requirements exclude legacy guarding. Pursue edge AI partnerships with semiconductor packaging facilities in Karnataka seeking latency reduction.
For Investors and Strategic Acquirers: FDA 21 CFR 892 premarket notification requirements reshape the acquisition landscape toward surgical robotics specialists with regulatory dossiers already compiled. Long-term viability centers on platforms spanning both automotive precision assembly and healthcare regulated applications. Watch EU AI Act delegated act publications as the signal for which conformity assessment bodies gain recognition.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Encoder Manufacturing | FANUC and Yaskawa anchor competitive position through captive supply of high-resolution optical components. |
| EU AI Act Pre-Certification Investment | ABB and KUKA accelerate CE marking timelines to capture procurement from German automotive OEMs. |
| Edge AI Hardware Partnership | Cognex collaborates with NVIDIA on embedded inference modules reducing latency for pick-and-place operations. |
| Hyperspectral Imaging Platform Launch | Keyence targets pharmaceutical manufacturers in Switzerland with 400-1000nm spectral cameras for defect detection. |
| Food Processing Safety Certification | Universal Robots secures ISO/TS 15066 compliance for unguarded protein handling in Danish facilities. |
Research Approach
Operator-level perspectives from plant engineers at automotive OEMs, vision system integrators, procurement leads at electronics contract manufacturers, and regulatory affairs specialists at surgical robotics firms anchored the qualitative base. Primary interviews triangulated against secondary sources including FDA 510(k) filings for computer-assisted detection functions, EU AI Act delegated act drafts, METI industrial robot safety standards, and customs data on optical encoder trade flows. Bottom-up segment sizing across product types, processing technologies, and end-use industries validated top-down market estimates.
Sensitivity analysis tested forecast robustness across adoption rate scenarios for collaborative robots and edge AI inference hardware. The analytical framework modeled segmentation dimensions including robot architecture, perception technology stack, end-use industry maturity, and regional regulatory cluster across the projection horizon. CAGRs derived from installed base growth, replacement cycles, and technology substitution curves incorporated inputs from encoder supply constraints and GPU pricing volatility.
Decision-makers should treat outputs as directional under assumptions of sustained automotive demand, stable encoder supply from Japanese and German sources, and phased EU AI Act enforcement; material deviation in any assumption would warrant model refresh. Specific risks include REACH amendments constraining illuminator components, PLI scheme modifications affecting Indian electronics investment, and FDA enforcement shifts for surgical robotics. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
Underwater Exploration Robots Market
Robotics and Automation
Drone-Based NDT Inspection Systems for Energy and Infrastructure Assets Market
Robotics and Automation
Southeast Asia Industrial and Service Robot Market
Robotics and Automation
Global Demolition Robots Market
Robotics and Automation
Logistics Robots Market
Robotics and Automation
Japan Agricultural Robot Market
Robotics and Automation
Robotics and Automation Actuators Market
Robotics and Automation
Global IT Robotic Automation Market
Robotics and Automation
Global Indoor Robots Market
Robotics and Automation
Robot Operating System Market
Robotics and Automation
Industrial Robot Controllers Market
Robotics and Automation
Smart Curtain Robot Market
Robotics and Automation
Security and Law Enforcement Robot Market
Robotics and Automation
Robot Label Applicators Market
Robotics and Automation
Asia-Pacific Data Center Robotics Market
Robotics and Automation
Food Robotics Market