
 Mobile Cobots Market | 2026-2036
Mobile Cobots Market Size, Share, and Industry Trends Forecast 2026-2036
Mobile Cobots Market Outlook
Modular payload configurations is restructuring buyer choice in the mobile cobots space, as end users swap end-effectors and mobility bases rather than purchasing fixed-function units. KUKA leverages its automotive heritage to dominate heavy-payload assembly assistants. Universal Robots sustains broad appeal through lightweight, redeployable arms compatible with third-party AMR platforms. Techman Robot differentiates via integrated vision systems that reduce peripheral hardware costs for small-batch manufacturers.
Mobile cobots combine collaborative robot arms with autonomous mobile robot bases, typically incorporating force-torque sensors, safety-rated monitored stops, and variable payloads from three to twenty kilograms to enable safe human-robot interaction in shared workspaces. The primary industrial purpose is flexible material handling, machine tending, and quality inspection without fixed guarding or dedicated cell infrastructure. Assembly Assistants command the deepest margin pools where precision fastening and delicate component placement justify premium pricing. Delivery Robots within logistics applications represent the fastest-expanding segment as e-commerce fulfillment networks prioritize goods-to-person automation. Machine Learning technology sits at the center of vendor R&D roadmaps, enabling adaptive path planning and obstacle avoidance without pre-mapped environments.
FDA device regulations and OSHA workplace safety standards shape healthcare and manufacturing deployment timelines in the United States, while the EU Machinery Directive and CE marking requirements govern market access across European member states. ISO 10218 and ISO/TS 15066 provide the foundational safety architecture that determines sensor redundancy, speed limits, and collaborative workspace design. Stakeholders must monitor evolving national interpretations of liability frameworks for autonomous systems operating without constant human supervision.
Market Dynamics
Machine learning integration is compressing deployment timelines for mobile cobots by eliminating pre-mapping requirements and enabling adaptive obstacle avoidance in unstructured factory environments.
Growth Catalysts
- ISO/TS 15066 compliance mandates:European automotive plants in Germany and Czechia are accelerating fleet procurement to meet tightening safety certification requirements for human-robot collaboration zones.
- EV battery manufacturing concentration:China's Yangtze River Delta corridor is retrofitting assembly lines with mobile manipulation systems to handle volatile production schedules and cell chemistry variations.
- Force-torque sensor cost curves:Advances in MEMS-based tactile sensing are reducing peripheral hardware expenditure for small-batch manufacturers in Japan and South Korea.
Market Restraints
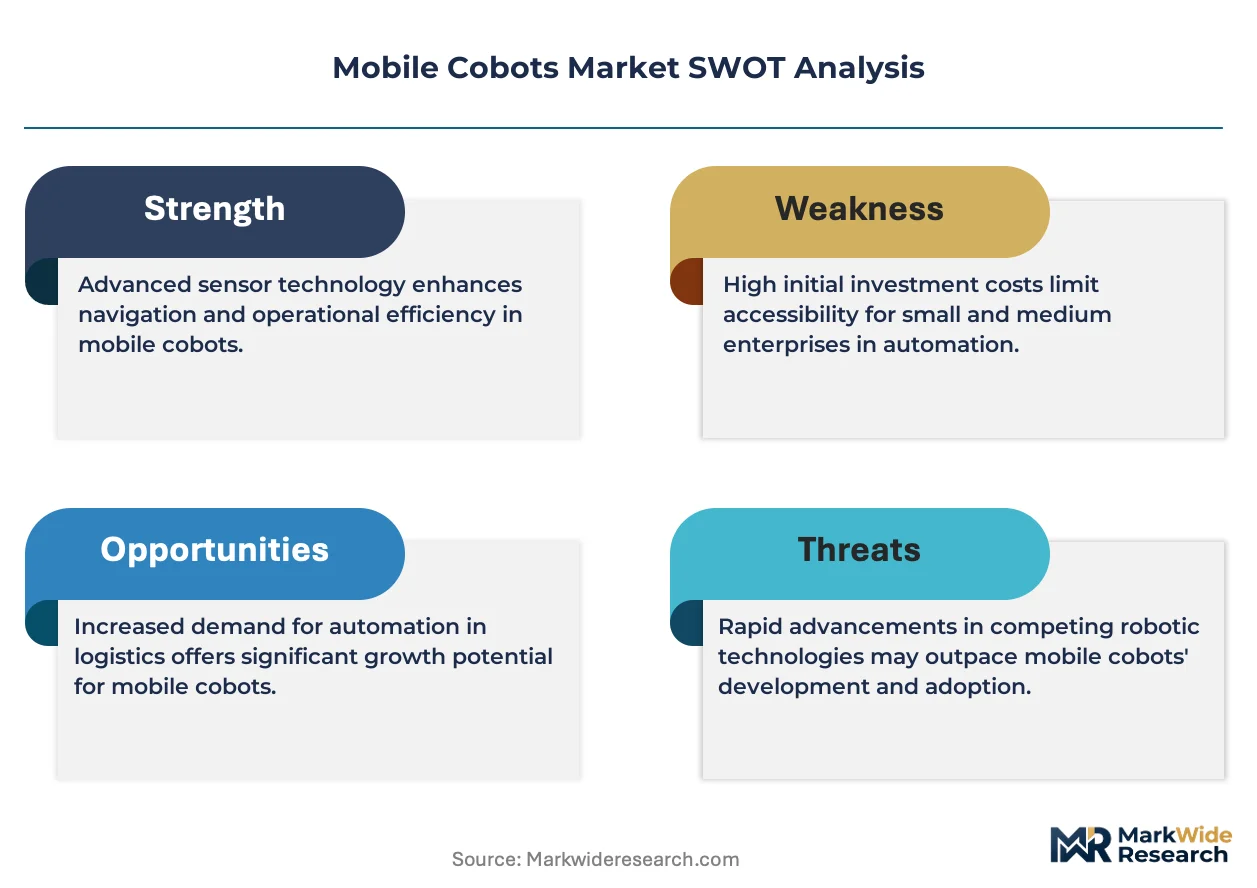
- Lithium-ion battery supply concentration:Cobalt and nickel processing bottlenecks in the Democratic Republic of Congo and Indonesia are creating input cost volatility for mobile base power systems.
- CE marking timeline friction:The EU Machinery Directive's evolving conformity assessment procedures are extending certification cycles by four to eight months for non-European vendors.
- Fixed industrial robot substitution:Traditional articulated arm installations in high-volume automotive stamping operations remain cost-competitive for single-task repetition cycles.
Strategic Opportunities
- Healthcare logistics automation:Hospital pharmacy and sterile supply chain operations in the United States present underpenetrated demand for FDA-compliant mobile delivery systems.
- 5G-private network convergence:Ultra-reliable low-latency communication is enabling real-time fleet coordination without on-premise edge computing infrastructure in German smart factories.
- India PLI scheme manufacturing incentives:Production-linked incentive frameworks for electronics assembly are attracting mobile cobot deployments to Tamil Nadu and Karnataka industrial corridors.
Industry Challenges
- Mechatronics technician scarcity:Maintenance and reprogramming of force-limited collaborative systems requires hybrid mechanical-electrical-software competencies that vocational training pipelines in the United States and Western Europe have not scaled.
- Legacy MES integration complexity:Proprietary communication protocols in decade-old manufacturing execution systems are forcing costly middleware development for mobile cobot fleet management.
- Functional safety certification backlog:Third-party notified body capacity constraints for ISO 10218-2 verification are delaying commercial deployment timelines for new market entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mobile Cobots Market |
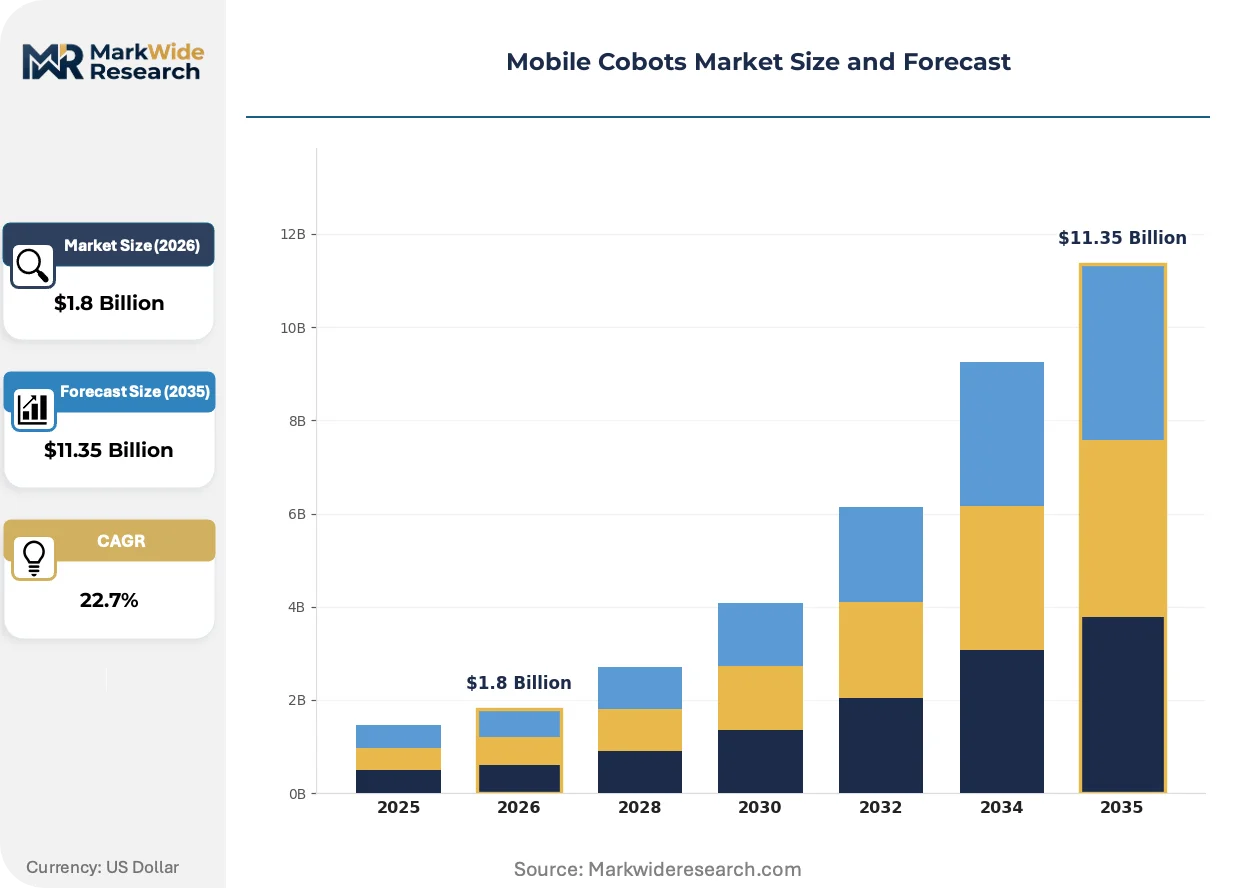
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $11.35 Billion |
| CAGR (2026 – 2036) | 22.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Autonomous Purifiers, Delivery Robots, Assembly Assistants, Inspection Drones Application: Manufacturing, Logistics, Healthcare, Construction End User: Retailers, Warehouses, Hospitals, Factories Technology: Machine Learning, Lidar, Computer Vision, Navigation Systems |
| Companies Covered | KUKA, Doosan Robotics, Universal Robots, Standard Bots, Techman Robot, FANUC, Yaskawa Motoman, Dobot, ABB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mobile Cobots Market Strategic Shifts
Adaptive path planning algorithms are eliminating the infrastructure dependency that previously constrained mobile cobot deployment to greenfield facilities with pre-mapped navigation grids.
Vision-guided manipulation is expanding into quality inspection and delicate component placement tasks previously reserved for fixed-gantry systems. Medical device manufacturers in Switzerland and Ireland are adopting integrated camera-arm configurations for sterile packaging verification. This convergence is compressing the traditional separation between mobile logistics and precision assembly equipment categories.
The EU AI Act's risk classification framework for autonomous industrial systems is reshaping vendor product architecture decisions. High-risk category designations for collaborative robots operating near human workers are mandating enhanced sensor redundancy and explainable decision logging. German and Italian automotive suppliers are front-loading compliance engineering to preempt 2026 enforcement timelines.
Buyers are unbundling after-sales service contracts from initial hardware procurement. Japanese electronics assemblers and Dutch semiconductor equipment manufacturers are negotiating separate maintenance agreements with third-party automation integrators rather than OEM service divisions. This disintermediation is compressing vendor margin pools while accelerating response times for line-down incidents in 24-hour production environments.
Mobile Cobots Market Segmentation
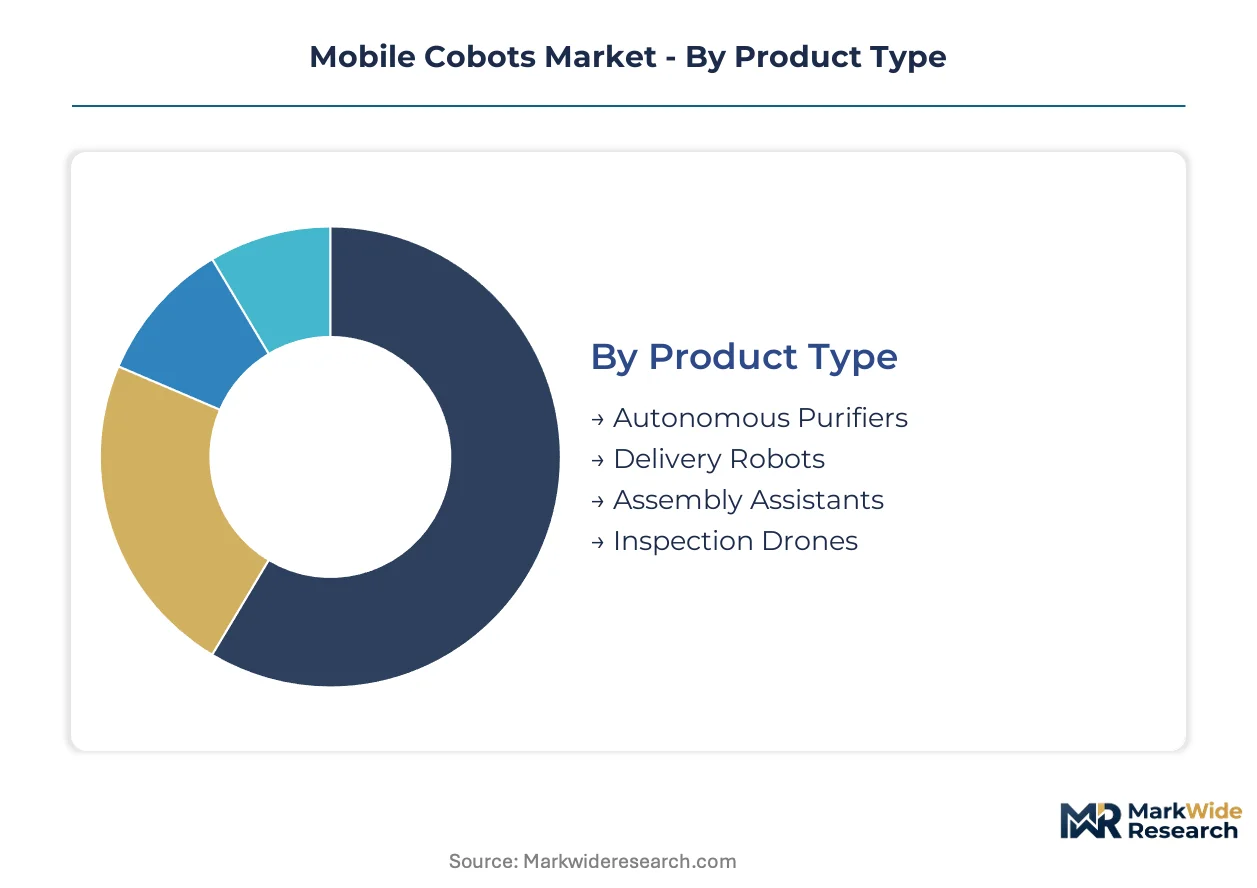
Mobile cobot procurement decisions hinge on payload requirements, safety certification tiers, and integration complexity with legacy factory infrastructure. Buyers prioritize redeployability over fixed automation, shifting vendor evaluation criteria toward modular architectures and software interoperability.
Product Type:
Payload capacity and precision requirements dominate buyer selection, with automotive and electronics manufacturers calibrating specifications to task complexity.
- Assembly Assistants:Force-torque limited arms mounted on mobile bases handle precision fastening and delicate component placement in German automotive plants. Premium pricing reflects ISO/TS 15066 certification overhead and sensor redundancy mandates for human-robot collaboration zones.
- Delivery Robots:Goods-to-person systems navigate warehouse aisles and hospital corridors without pre-mapped infrastructure, expanding most quickly in Chinese e-commerce fulfillment networks and US healthcare logistics where labor availability constrains overnight operations.
- Autonomous Purifiers:UV-C and HEPA-equipped mobile units sanitize healthcare and food processing environments.
- Inspection Drones:Aerial and ground-based platforms conduct structural monitoring in construction and energy infrastructure.
Volume sits with Assembly Assistants; growth tilts toward Delivery Robots.
Application:
Deployment velocity varies by regulatory maturity and union density, with manufacturing leading adoption while healthcare navigates FDA device pathways.
- Manufacturing:Machine tending and flexible material handling applications dominate procurement in Czechia and Japan, where small-batch production schedules reward rapid reprogramming over dedicated cells.
- Logistics:Peak-season volatility drives goods-to-person automation in Dutch distribution centers and Yangtze River Delta export hubs, compressing payback periods through labor substitution during demand surges.
- Healthcare:Sterile supply chain and pharmacy operations face elongated approval timelines under FDA and Swissmedic frameworks.
- Construction:Structural inspection and material transport applications encounter terrain variability and weather exposure constraints.
Revenue concentrates in Manufacturing; expansion accelerates fastest in Logistics.
End User:
Capital intensity and operational uptime requirements shape procurement patterns across facility types, with 24-hour operations justifying premium sensor configurations.
- Factories:Automotive and electronics producers in Germany and Japan deploy fleet-scale systems with centralized fleet management software, amortizing integration costs across high-volume production lines.
- Warehouses:Third-party logistics operators prioritize rapid deployment and minimal infrastructure modification, favoring machine learning-based navigation over fixed beacon installations.
- Hospitals:Pharmacy and sterile supply operations require FDA-compliant systems with audit trail documentation.
- Retailers:Inventory management and customer-facing applications remain exploratory due to public liability exposure.
Investment depth is greatest in Factories; deployment speed is fastest in Warehouses.
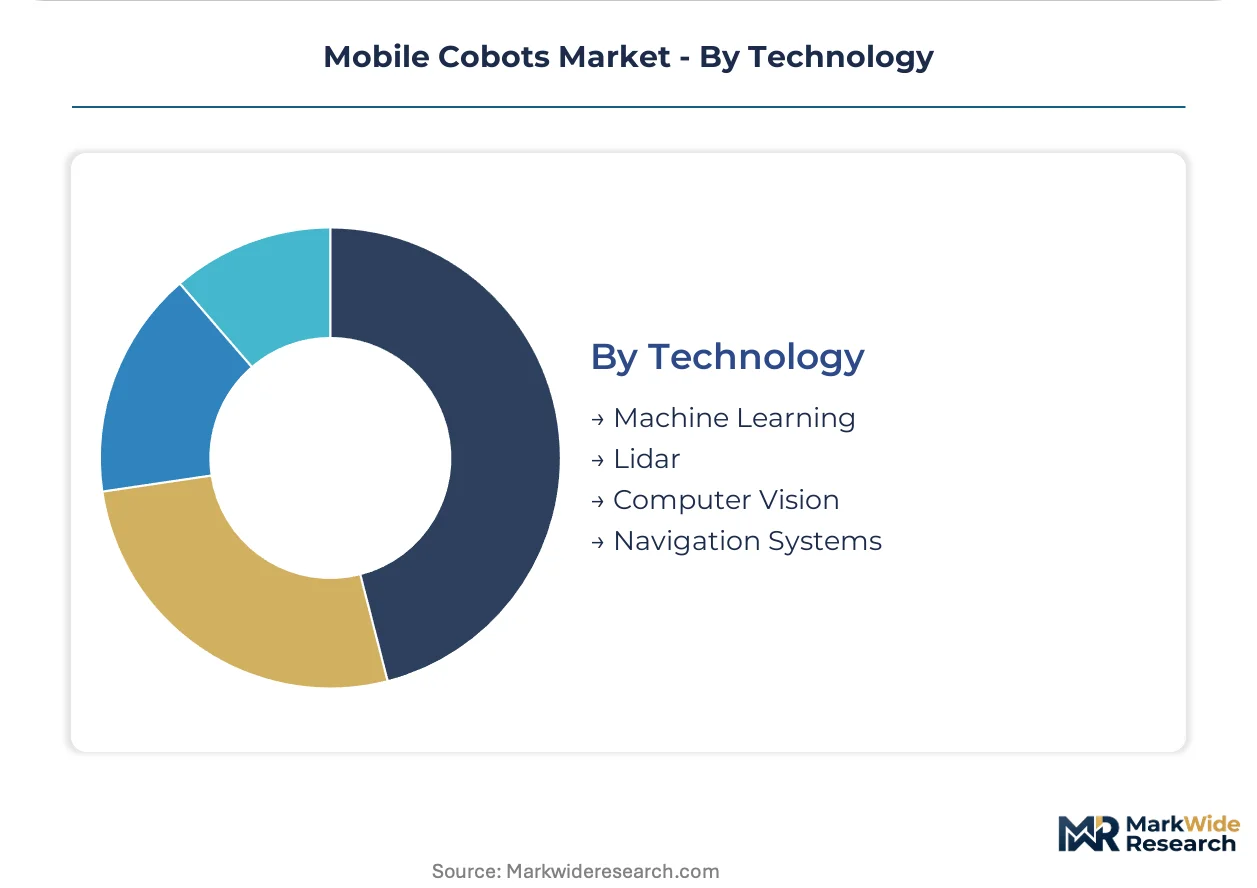
Technology:
Software differentiation increasingly determines competitive positioning, with sensor fusion and edge computing capabilities separating premium from commodity offerings.
- Machine Learning:Adaptive path planning and obstacle avoidance algorithms eliminate pre-mapping requirements, enabling deployment in brownfield Czech automotive plants and Indian electronics assembly corridors without navigation infrastructure investment.
- Computer Vision:Integrated camera-arm configurations perform quality inspection and delicate manipulation, compressing the traditional separation between logistics and precision assembly equipment in Swiss medical device manufacturing.
- Lidar:3D environmental mapping supports high-speed navigation in dynamic warehouse environments.
- Navigation Systems:SLAM and beacon-based positioning provide foundational mobility infrastructure.
R&D investment clusters in Machine Learning; commercial traction is broadest in Computer Vision.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Yangtze River Delta special economic zones concentrate mobile cobot deployment through EV battery incentives and export manufacturing infrastructure. Foxconn suppliers and CATL-aligned plants retrofit assembly lines with mobile manipulation systems to manage volatile production schedules.
China
MIIT smart manufacturing directives accelerate fleet procurement in Suzhou and Ningbo electronics corridors. The dual carbon goals mandate energy-efficient automation retrofits in brownfield facilities. BYD and CATL suppliers deploy machine learning-enabled systems for cell chemistry variation handling.
Germany
KBA automotive safety requirements and EU Machinery Directive compliance drive ISO/TS 15066 certification investments. Stuttgart and Wolfsburg assembly plants integrate heavy-payload assembly assistants for precision fastening. 5G-private network convergence enables real-time fleet coordination without edge computing infrastructure.
United States
OSHA workplace safety standards and FDA device regulations shape healthcare and manufacturing deployment timelines. Detroit automotive stamping operations and Boston-area medical device manufacturers navigate elongated approval pathways. Hospital pharmacy automation presents underpenetrated demand for compliant mobile delivery systems.
Japan
METI productivity enhancement programs subsidize SME automation in Aichi and Osaka manufacturing belts. MEMS-based force-torque sensor advances reduce peripheral hardware costs for small-batch producers. JIS standards alignment ensures interoperability with legacy factory infrastructure.
India
PLI scheme manufacturing incentives attract electronics assembly deployments to Tamil Nadu and Karnataka corridors. DGFT import substitution policies favor domestic system integrators. Foxconn and Dixon suppliers pilot machine learning navigation without pre-mapped infrastructure investment.
Mobile Cobots Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. The vendor base organizes around three strategic archetypes: automotive heritage heavy-payload providers, lightweight redeployable arm specialists, and integrated vision-embedded challengers. M&A activity concentrates on sensor fusion capabilities and AMR platform compatibility. Strategic partnerships between cobot arm OEMs and autonomous mobile robot base manufacturers accelerate bundled solution penetration.
Within the automotive heritage tier, KUKA exemplifies heavy-payload assembly assistant positioning. Among lightweight redeployable specialists, Universal Robots occupies a position compatible with third-party AMR platforms. Techman Robot represents the integrated vision-embedded archetype, reducing peripheral hardware requirements through camera-arm convergence. These three anchors illustrate divergent technology stack bets across force-limited collaboration, modularity, and sensor integration.
| Leading Market Players |
|---|
| KUKA |
| Doosan Robotics |
| Universal Robots |
| Standard Bots |
| Techman Robot |
| FANUC |
| Yaskawa Motoman |
| Dobot |
| ABB |
| Others |
Value Chain & Pricing Dynamics
Automotive fleet procurement mandates in Germany and Czechia are compressing lead-time tolerances, forcing supply chains to absorb premium logistics costs for ISO/TS 15066-certified components and compressing margins on non-certified inventory.
Pricing Analysis
Short lead-time premiums of fifteen to twenty percent separate certified assembly assistants from spot-market alternatives in European automotive corridors. Three-tier pricing structure across premium, standard, and economy levels reflects ISO/TS 15066 compliance grade, sensor redundancy configuration, and after-sales service bundling. Pricing pressure stems from MEMS-based force-torque sensor cost compression in Japanese and South Korean component markets. Small-batch manufacturers in Japan exhibit highest price sensitivity, while German automotive OEMs prioritize certification compliance over unit economics.
Supply Chain Analysis
Lithium-ion cell supply rests on cobalt and nickel processing concentration in the Democratic Republic of Congo and Indonesia, tethering mobile base power systems to volatile commodity corridors. MEMS sensors draw from Taiwanese foundry capacity, while precision gearboxes source from German and Japanese machine tool specialists. Single-source vulnerability in Congolese cobalt refining exposes tier-one vendors to input cost spikes. Distribution runs through authorized system integrators in Stuttgart, Suzhou, and Detroit manufacturing clusters, with direct OEM relationships reserved for fleet-scale procurement above fifty units.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Third-party notified body capacity constraints for ISO 10218-2 verification are propping effective pricing power among incumbent vendors with pre-certified product architectures.
For Market Incumbents: Acquire machine learning navigation software assets to neutralize adaptive path planning advantages held by AMR-native entrants. Consolidate force-torque sensor supply through backward integration into MEMS fabrication partnerships, buffering against Taiwanese foundry allocation constraints. Defensive positioning requires front-loading EU AI Act compliance engineering ahead of enforcement timelines. For New Entrants and Emerging Players: Enter via FDA-compliant healthcare logistics configurations in Boston-area hospital systems, where elongated approval timelines have suppressed incumbent penetration. Target Indian electronics assembly corridors under PLI scheme incentives, leveraging machine learning navigation to bypass pre-mapped infrastructure requirements. Go-to-market execution should emphasize third-party maintenance contract disintermediation. For Investors and Strategic Acquirers: The window for entry favors integrated vision-embedded specialists with camera-arm convergence capabilities, as Swiss and Irish medical device manufacturers accelerate sterile packaging verification adoption. Long-term viability hinges on software differentiation moats rather than hardware scale. Watch CE marking timeline friction as inflection indicator for European market access competitiveness.| Strategic Initiative | Industry Significance |
|---|---|
| Sensor Fusion Acquisition | Camera-arm convergence reduces peripheral hardware costs for Swiss medical device manufacturers. |
| 5G-Private Network Partnership | Ultra-reliable low-latency coordination eliminates edge computing infrastructure in German smart factories. |
| ISO/TS 15066 Certification Front-Loading | Preemptive compliance engineering locks in European automotive procurement ahead of enforcement. |
| Healthcare Logistics FDA Submission | Hospital pharmacy automation in Boston presents underpenetrated demand for compliant delivery systems. |
| India PLI Scheme Manufacturing Deployment | Tamil Nadu and Karnataka electronics corridors attract machine learning-enabled pilot installations. |
Study Parameters
Multi-period observation of fleet procurement volumes, certification timeline data, and sensor cost curves anchored the trend analysis, supplemented by interviews with automotive plant engineers, cobot OEM product managers, and third-party automation integrators. Secondary validation drew from EU Machinery Directive filings, FDA device registration databases, MIIT smart manufacturing directives, and SEC filings of publicly traded automation vendors. Bottom-up unit shipment estimates triangulated against top-down manufacturing automation capex data.
Segment-weighting applied differential growth assumptions across assembly assistants, delivery robots, and inspection platforms, with payload capacity and certification tier as cross-cutting dimensions. CAGRs derived from logistic curve fitting to adoption velocity patterns in German automotive and Chinese EV battery manufacturing. Forecast inputs incorporated force-torque sensor cost trajectories and notified body certification capacity constraints.
Forecast precision tightens around the base case; tail outcomes carry wider variance under EU AI Act risk reclassification and lithium-ion supply disruption scenarios. Assumptions reflect current regulatory interpretations and commodity supply configurations. A small set of triggers—CE marking timeline extensions, Congolese cobalt export restrictions, and 5G spectrum allocation delays—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
Global Underwater Robotics Market
Robotics and Automation
Global Enterprise Robotic Process Automation Market
Robotics and Automation
Global Indoor Robots Market
Robotics and Automation
Global Soft Robotics Market
Robotics and Automation
Global Rescue Robot Market
Robotics and Automation
Global AI Based Surgical Robots Market
Robotics and Automation
Robotics in Shipbuilding Market
Robotics and Automation
Global Entertainment Robots Market
Robotics and Automation
Automated Guided Vehicle (AGV) Market
Robotics and Automation
Spain Cloud Robotics Market
Robotics and Automation
Europe Logistics Robotics Market
Robotics and Automation
Human-Robot Collaborative Picking Optimization Platforms Market
Robotics and Automation
Asia Pacific Warehouse Robotics Market
Robotics and Automation
Europe Underwater Robotics Market
Robotics and Automation
Global Demolition Robots Market
Robotics and Automation
France Cloud Robotics Market