
 Home Energy Management System Market | 2026-2036
Home Energy Management System Market Size, Share, and Industry Trends Forecast 2026-2036
Home Energy Management System Market Intelligence
The shift toward open, interoperable communication protocols like Matter is narrowing the gap between previously siloed smart home ecosystems. Schneider Electric leverages its expertise in electrical distribution to offer integrated solutions from the panel to the plug. Alphabet Inc., through its Nest products, dominates the smart thermostat segment with data-driven, AI-powered learning capabilities. Meanwhile, Siemens positions its offerings for more complex residential and light commercial integrations.
A home energy management system (HEMS) is a network of interconnected hardware and software that actively monitors and controls a household's total energy consumption. These systems utilize wireless communication protocols like Wi-Fi or Zigbee to link devices and process real-time data for automated optimization. Within product types, smart thermostats represent the largest segment, often serving as the system's central hub. The DIY installation segment shows significant growth, particularly among homeowners aiming to reduce professional installation costs.
In the United States, programs supported by the Department of Energy and incentives within the IRA encourage HEMS adoption for grid balancing. Concurrently, the EU's Ecodesign Directive and CE marking standards mandate energy efficiency and safety for connected devices. The key strategic decision for vendors involves balancing investment in proprietary features against the benefits of adhering to emerging open interoperability standards.
Market Dynamics
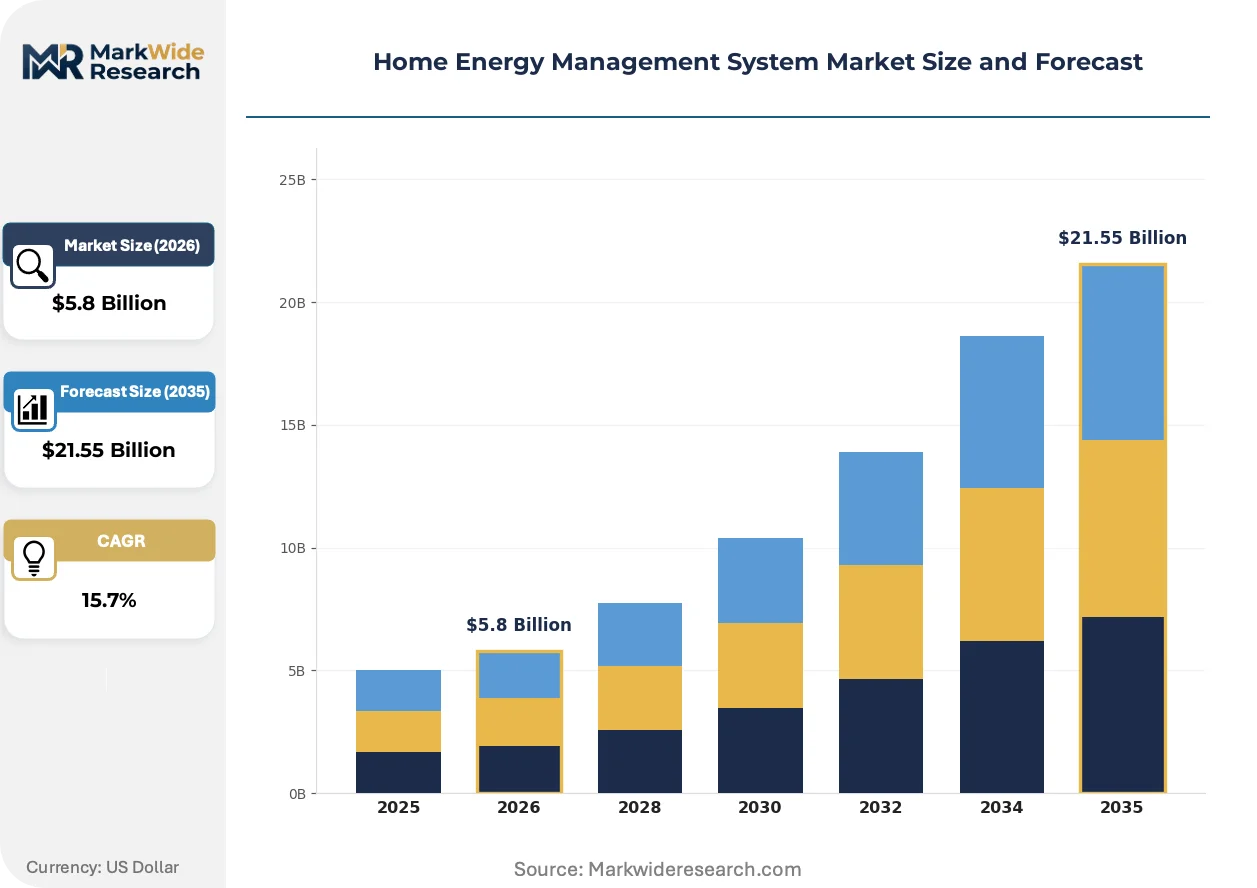
The market's trajectory is defined by the convergence of consumer-driven demand for utility cost management and government mandates for grid stabilization. This dual pressure accelerates HEMS adoption as a critical link between residential energy assets and broader utility infrastructure.
Growth Catalysts
- Government Incentives:Policy frameworks like the EU Green Deal and tax credits within the US Inflation Reduction Act (IRA) directly subsidize the purchase and installation of HEMS, lowering the barrier to entry for homeowners.
- Smart Grid Deployment:The expansion of advanced metering infrastructure and smart grids in countries like Germany and Japan provides the necessary communication backbone for HEMS to perform demand response and grid-balancing functions.
- Volatile Utility Costs:Persistently high and unpredictable electricity prices in many OECD countries push consumers to adopt systems that provide granular control over consumption and enable participation in time-of-use pricing programs.
Market Restraints
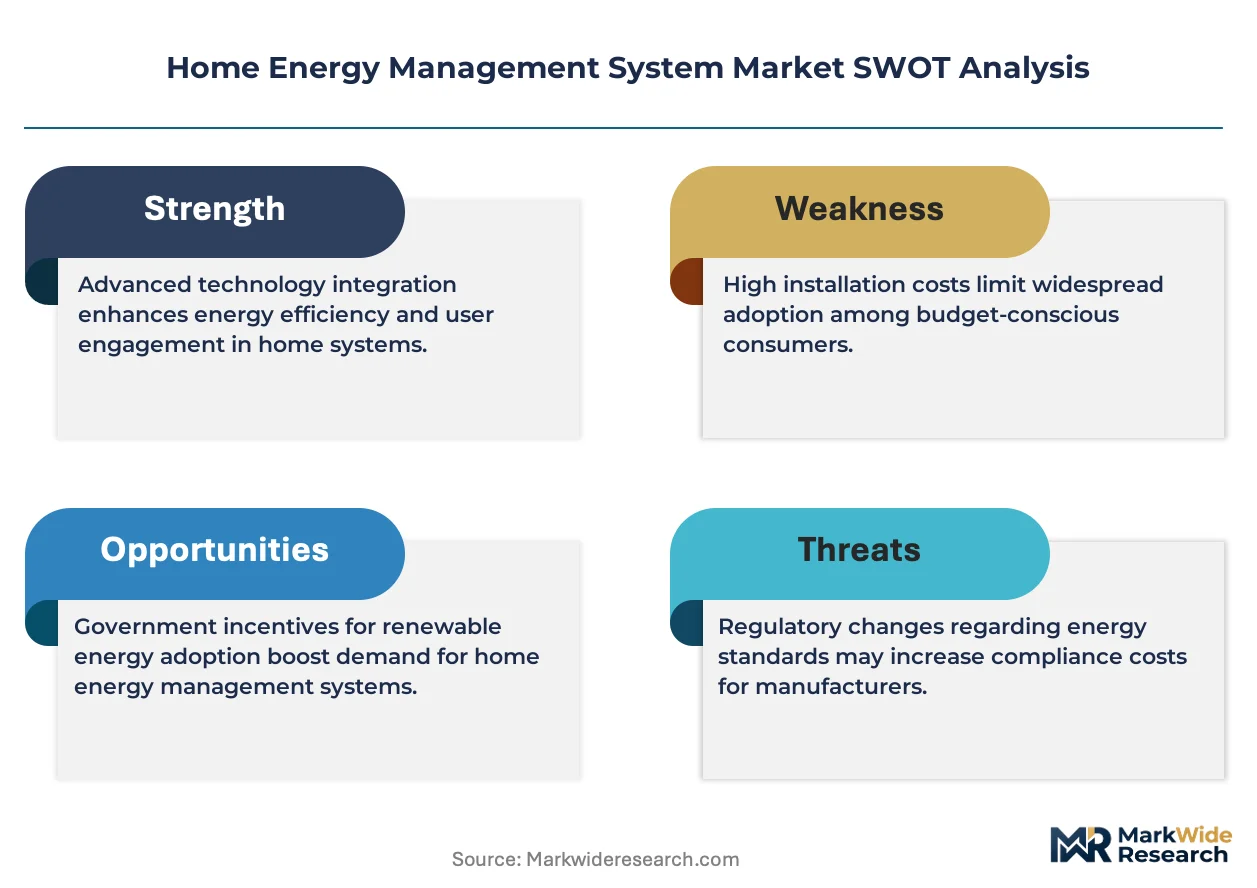
- High Initial Investment:The significant upfront cost for comprehensive HEMS hardware, coupled with professional installation fees, remains a primary deterrent for many homeowners, particularly in markets without substantial government subsidies.
- Fragmented Standards:Despite progress with protocols like Matter, the persistence of proprietary ecosystems creates integration challenges, limiting consumer choice and complicating the creation of a truly unified home energy network.
- Component Bottlenecks:The industry's reliance on a concentrated supply chain for specific microcontrollers and wireless communication chips creates vulnerability to shortages and price volatility, impacting production schedules for HEMS device manufacturers.
Strategic Opportunities
- EV Charging Integration:Developing HEMS that intelligently manage electric vehicle charging to align with off-peak electricity rates or solar generation presents a major growth vector, especially in markets with high EV penetration.
- Emerging Market Penetration:Targeting middle-class households in rapidly urbanizing countries like India and Brazil, where grid reliability is a concern and smart meter rollouts are accelerating, offers significant expansion potential.
- AI-Driven Predictive Control:Leveraging artificial intelligence to move beyond simple automation to predictive energy management, forecasting consumption based on weather and utility price signals, creates a new value proposition.
Industry Challenges
- Legacy System Integration:The complexity of interfacing new HEMS devices with older, non-smart appliances and HVAC systems presents a significant technical hurdle, often requiring costly workarounds or premature appliance replacement.
- Skilled Installer Scarcity:A shortage of technicians proficient in both electrical work and IT networking complicates professional installations, leading to longer wait times and higher labor costs for consumers.
- Data Privacy and Security:Ensuring the security of sensitive household energy data against cyber threats and navigating complex data privacy regulations like GDPR in Europe are critical operational challenges for system vendors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Home Energy Management System Market |
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $21.55 Billion |
| CAGR (2026 – 2036) | 15.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart Thermostats, Energy Monitors, Smart Plugs, Home Automation Systems Technology: Wi-Fi, Zigbee, Z-Wave, Bluetooth Installation Type: DIY, Professional, Integrated, Standalone End User: Residential, Homeowners, Tenants, Property Managers |
| Companies Covered | Vivint, Inc., Schneider Electric, Honeywell International Inc., Panasonic Holdings Corporation, Siemens, Alphabet Inc., Ecobee Inc., Ecofactor, Inc., General Electric, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Home Energy Management System Market Strategic Shifts & Innovations
A fundamental shift from hardware-centric control to software-defined energy orchestration is underway in the HEMS market. Intelligence, connectivity, and data analytics are becoming the primary sources of value, transforming how energy is managed within the home.
Cloud-based platforms and edge computing provide the core processing power for modern HEMS. Residential homeowners and property managers adopt these software-centric solutions to gain remote access and control. This trend is virtualizing the traditional hardware controller, shifting intelligence from a dedicated device on the wall to distributed software and cloud services.
The EU's Ecodesign Directive is imposing stricter energy efficiency and standby power consumption requirements on connected devices. This regulation forces manufacturers to redesign hardware, from smart plugs to thermostats, to comply with CE marking standards. The home appliance segment is most affected, compelling deeper integration with HEMS to demonstrate compliance and efficiency gains.
Direct-to-consumer sales channels are gaining traction, fueled by the rise of the do-it-yourself (DIY) installation model. This trend disrupts the traditional professional installer channel, as tech-savvy homeowners purchase modular, plug-and-play devices directly from online retailers. This shift is most prominent in the North American market for single-component additions like smart thermostats and plugs.
Home Energy Management System Market Segmentation
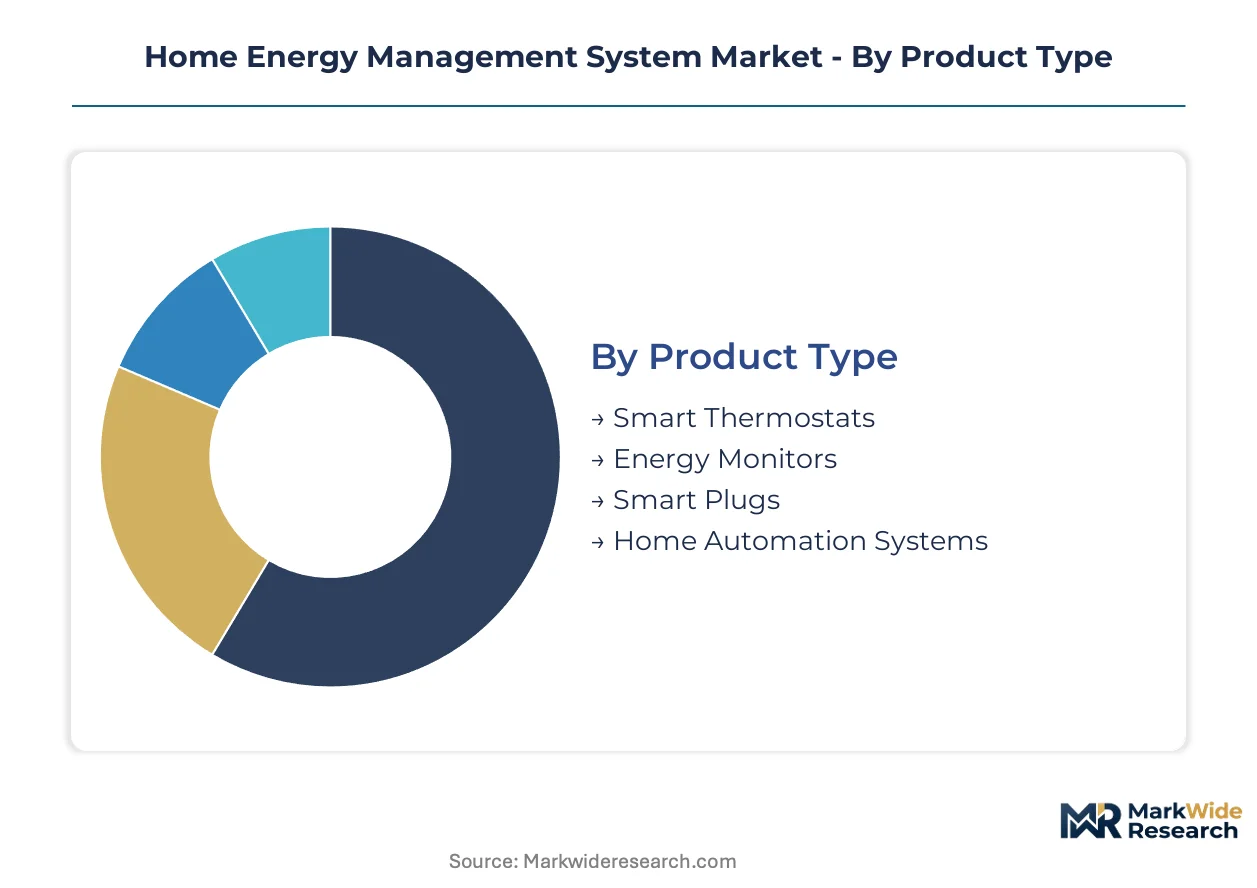
The Home Energy Management System market demonstrates diverse segmentation, reflecting varied consumer needs and technological advancements. Understanding these distinctions is critical for vendors to tailor product development and market entry strategies effectively. Market segmentation reveals where investment is flowing across different system components and user groups.
Product Type:
Product types within HEMS vary significantly in their development cycles and replacement frequencies.
- Smart Thermostats:These devices offer intelligent climate control, often incorporating AI-powered learning algorithms to optimize heating and cooling schedules. Demand concentrates in the United States and Germany, driven by consumer desire for utility cost management and comfort.
- Home Automation Systems:These integrated hardware and software platforms provide comprehensive control over multiple household devices for energy optimization and convenience. Adoption is strong in the EU and specific US states, spurred by efficiency mandates and smart grid initiatives.
- Energy Monitors:These systems provide real-time data on household electricity consumption, offering insights into energy usage patterns.
- Smart Plugs:These devices enable remote control and scheduling for individual appliances, helping to reduce phantom load and manage device-level energy.
Smart Thermostats anchors the volume base while Home Automation Systems gains share at the steepest rate.
Technology:
The underlying communication technologies define the interoperability and application scope of HEMS components.
- Wi-Fi:Leveraging existing home network infrastructure, Wi-Fi offers high bandwidth connectivity for a wide range of smart home devices and cloud services. Residential homeowners in North America favor Wi-Fi due to its ubiquitous presence and ease of integration.
- Zigbee:This low-power, mesh networking protocol facilitates reliable communication between numerous smart home devices, forming robust local ecosystems. Adoption is significant in the EU for device interoperability and Matter protocol support.
- Z-Wave:Z-Wave is a wireless mesh network technology primarily used for smart home devices, offering reliable, low-power communication.
- Bluetooth:Bluetooth supports short-range, point-to-point communication, commonly found in individual smart devices and for initial setup procedures.
Ubiquitous Wi-Fi connectivity dominates the installed base, yet mesh network protocols like Zigbee are experiencing rapid expansion in new device deployments.
Installation Type:
Customer preferences and cost considerations heavily influence the choice of HEMS installation methods.
- DIY:Do-it-yourself installation involves homeowners setting up modular, plug-and-play HEMS components without professional assistance. This segment is prominent in the North American market, appealing to tech-savvy consumers aiming to reduce professional installation costs.
- Professional:Professional installation involves certified technicians setting up complex HEMS, often integrating with existing electrical infrastructure and HVAC systems. This approach is preferred for integrated solutions and light commercial applications, ensuring optimal system performance and warranty compliance.
- Integrated:Integrated installations involve HEMS being pre-installed or seamlessly incorporated into new home construction or major renovation projects.
- Standalone:Standalone installations refer to single-function HEMS devices, such as smart thermostats or energy monitors, added independently to an existing home setup.
DIY solutions attract cost-conscious homeowners, while professional installation remains crucial for complex, whole-home energy management systems.
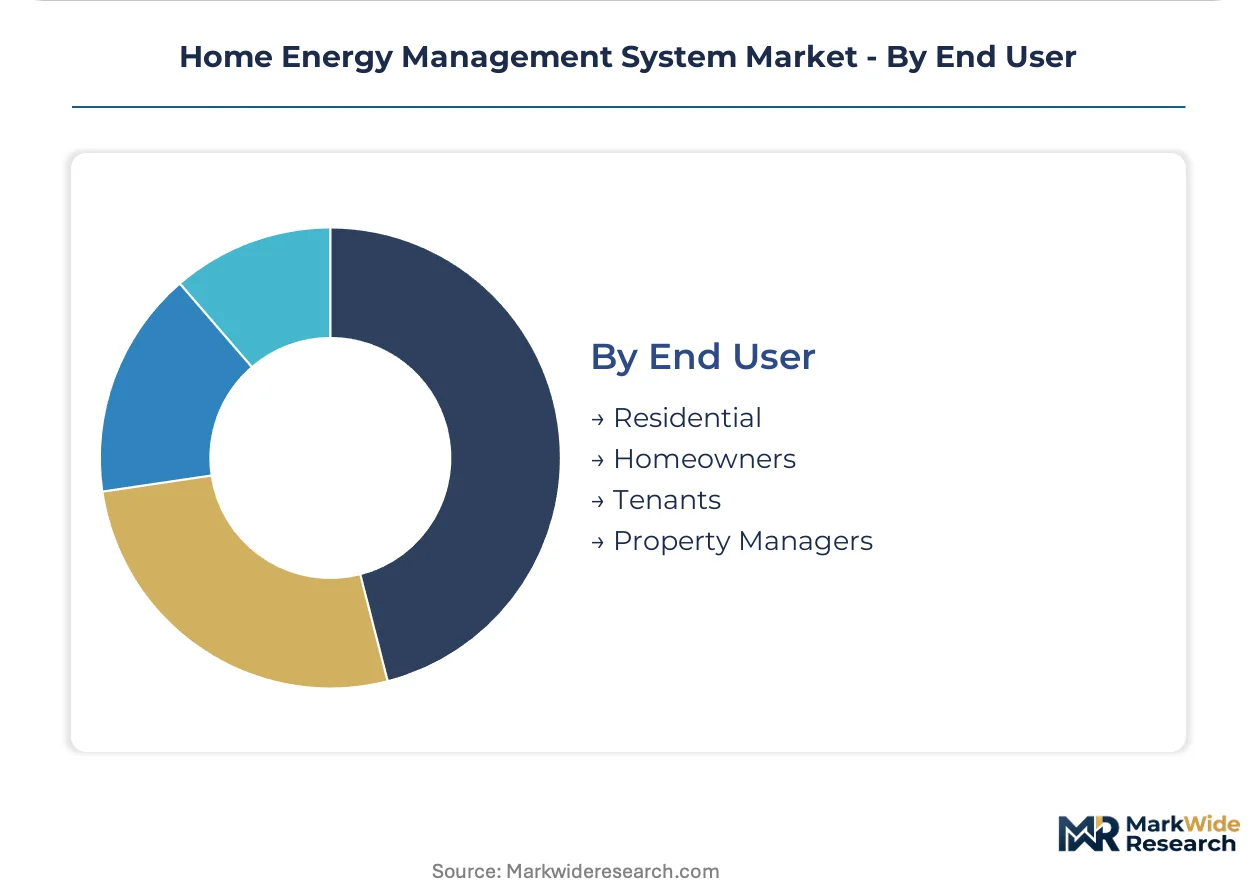
End User:
Different end-user segments exhibit distinct motivations and requirements for adopting Home Energy Management Systems.
- Homeowners:Individual homeowners seek HEMS primarily for personal comfort, utility cost reduction, and environmental impact management. This segment drives demand in countries with high electricity prices like Germany and specific US states.
- Property Managers:Property managers utilize HEMS to optimize energy consumption across multiple residential units, enhancing operational efficiency and tenant satisfaction. This segment is growing in urban areas with rental properties and energy efficiency mandates.
- Residential:This broad category encompasses all household users, including both homeowners and tenants, seeking to manage home energy.
- Tenants:Tenants typically adopt simpler, plug-and-play HEMS solutions due to limitations on modifying rented properties.
Homeowners constitute the largest consumer base, with property managers increasingly adopting HEMS for portfolio-wide energy optimization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Home Energy Management System market sees innovation flowing from developed economies, particularly the United States, to emerging markets seeking energy efficiency. This global trajectory is shaped by localized demand and regulatory frameworks. Utility cost management and grid stability remain primary motivators across diverse geographies.
United States
Homeowners in the United States seek HEMS for utility cost reduction and grid balancing. The Inflation Reduction Act (IRA) encourages HEMS adoption through various incentives. California's advanced grid initiatives and high electricity prices drive significant demand in the state.
Germany
Germany exhibits strong demand for HEMS due to persistently high electricity prices and efficiency mandates. The EU Green Deal incentivizes efficiency upgrades, directly benefiting system sales. Urban centers like Berlin integrate HEMS into smart city infrastructure for energy optimization.
Japan
Japan's advanced smart grid deployment fuels HEMS demand for energy resilience and efficiency. The Ministry of Economy, Trade and Industry (METI) actively promotes energy efficiency technologies. Densely populated areas like Tokyo adopt HEMS for demand response programs.
India
India's rapidly urbanizing population and concerns over grid reliability drive HEMS interest. Government initiatives, including PLI schemes, support smart meter rollouts and related energy technologies. Tech-savvy consumers in Bengaluru are early adopters, integrating HEMS for better energy control.
Brazil
Brazil's middle-class households seek HEMS for utility cost management and grid stability. The national electricity regulator, ANEEL, incentivizes smart grid investments. Large urban centers such as São Paulo present significant opportunities for HEMS penetration.
Home Energy Management System Market Key Industry Players
Channel-controlling players compete with product-specialist players in the Home Energy Management System market. The landscape is characterized by a mix of established electrical distribution giants and agile smart home technology firms. Strategic archetypes include integrated system providers, component manufacturers, and software platform developers. Companies pursue portfolio diversification through M&A and forge strategic partnerships to expand their market reach and integrate new functionalities.
Specialists in integrated energy management solutions include Schneider Electric, which leverages its electrical distribution heritage to offer comprehensive systems. Alphabet Inc., through its Nest products, exemplifies a data-driven approach, anchoring the smart thermostat segment with AI-powered learning capabilities. Siemens positions its offerings for complex residential and light commercial integrations, representing another facet of the integrated systems archetype. These prominent firms navigate the balance between developing proprietary features and adhering to emerging open interoperability standards, shaping the ecosystem's future.
| Leading Market Players |
|---|
| Vivint, Inc. |
| Schneider Electric |
| Honeywell International Inc. |
| Panasonic Holdings Corporation |
| Siemens |
| Alphabet Inc. |
| Ecobee Inc. |
| Ecofactor, Inc. |
| General Electric |
Cost & Logistics Intelligence
Underutilized manufacturing capacity in East Asian electronics production influences HEMS component pricing, driving supplier competition and shaping market entry strategies for new device manufacturers. This dynamic directly impacts the cost structure for finished Home Energy Management Systems.
Pricing Analysis
Current-generation HEMS devices exhibit distinct pricing from their prior-generation counterparts, primarily due to advanced AI capabilities and Matter protocol integration. The dominant pricing model is a hybrid of per-unit transactional costs for hardware and subscription-based fees for cloud services and premium features. Price differentiation stems from brand premium and the level of after-sales service offered to homeowners. Pricing softness in basic smart plugs reflects intense competition, while complex home automation systems command higher prices due to integration expertise.
Supply Chain Analysis
Export-control regimes on high-performance microcontrollers and wireless communication chips limit technology flows, impacting the HEMS supply chain. Geographic supply concentrates heavily in Taiwan, South Korea, and China for these critical electronic components, and the industry draws from a concentrated supplier base for specialized sensors. Single-source vulnerability for specific chipsets presents a structural risk, potentially disrupting production schedules for HEMS device manufacturers. Distribution runs through both direct-to-consumer online channels and established professional installer networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Home Energy Management System market is experiencing a significant buyer-power shift, driven by the fragmentation of the DIY homeowner segment. This segment increasingly dictates product features and pricing, challenging traditional professional installation models.
For Market Incumbents: Insulate core offerings by investing in comprehensive software platforms that integrate diverse smart home ecosystems, countering fragmentation. Companies like Schneider Electric should acquire specialized AI-driven predictive control firms to enhance their integrated solutions, mitigating the threat from agile software-centric entrants. Deepening channel control with certified professional installers for complex whole-home systems remains a lever against commoditization. Focus R&D on seamless EV charging integration to capture new growth vectors.
For New Entrants and Emerging Players: Build out modular, plug-and-play HEMS solutions targeting the underserved DIY segment in North America. Focus on AI-driven predictive control capabilities as a unique value proposition, differentiating from basic smart thermostats. The most penetrable segment lies within middle-class households in rapidly urbanizing countries like India, where grid reliability is a concern. A direct-to-consumer online sales channel with robust customer support provides a cost-effective go-to-market angle.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting in an upward direction across the advanced sensor and communication chip manufacturing sub-segment, signaling long-term market maturation. The HEMS market presents a viable investment horizon over the next 5-10 years, driven by electrification trends. Target acquisition archetypes include software platform developers specializing in AI-driven energy optimization or firms with strong intellectual property in open interoperability standards like Matter. Smart grid expansion rates in countries like Germany serve as a critical signal to watch for accelerated adoption.
| Strategic Initiative | Industry Significance |
|---|---|
| EV Charging Integration | Aligns residential energy management with growing electric vehicle adoption and grid balancing needs. |
| AI-Driven Predictive Control | Enhances system intelligence for proactive energy optimization based on real-time data and forecasts. |
| Open Interoperability Standard Adoption | Reduces ecosystem fragmentation, boosting consumer choice and market penetration for connected devices. |
| Emerging Market Penetration | Captures new demand from urbanizing populations in countries like India and Brazil seeking grid stability. |
| Direct-to-Consumer Channel Expansion | Lowers customer acquisition costs and caters to the growing DIY installation segment among homeowners. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through extensive primary interviews for this analysis. Insights from HEMS manufacturers, utility providers, smart home integrators, and residential homeowners were combined with secondary validation. This involved synthesizing data from Department of Energy reports, the EU Ecodesign Directive, and company financial filings. Bottom-up data aggregation and top-down market sizing ensured robust triangulation.
Calibration of the quantitative model involved rigorous cross-validation of historical market trends and future projections across the analysis window. Segmentation dimensions modeled included product type, underlying technology, installation method, and end-user segment. Compound Annual Growth Rates were derived from multi-variable regression analysis, incorporating smart meter rollout rates and electricity price volatility as key forecast inputs.
Stress conditions across policy incentives and component supply were modeled; outcomes beyond those bands fall outside the analytical envelope. Forecasts reflect assumptions on regulatory stability and technological progression. Material shifts in government energy policy or major technological breakthroughs would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Energy Management Systems
India Home Ventilation System Market
Energy Management Systems
Asia-Pacific Home Energy Management System Market
Energy Management Systems
Global Smart Air Conditioning Market
Energy Management Systems
Smart Utilities Management Market
Energy Management Systems
Outage Management System (OMS) Market
Energy Management Systems
US Energy Management Systems Market
Energy Management Systems
Airflow Management Market
Energy Management Systems
USA and Canada Portable Air Conditioner Market
Energy Management Systems
Energy Management in Data Centers Market
Energy Management Systems
Global Personal Cooling Device Market
Energy Management Systems
Portable Air Cooler Market
Energy Management Systems
Smart Programmable Thermostat Market
Energy Management Systems
Peltier Chillers Market
Energy Management Systems
Global Thermal Management Technologies Market
Energy Management Systems
Grid Operations Management Software Market
Energy Management Systems
Europe Advanced Distribution Management System Market