
 Robot Market | 2026-2036
Robot Market Size, Share, and Industry Trends Forecast 2026-2036
Robot Market Analysis
Healthcare robotics is shifting toward disinfection and surgical assistance as hospital administrators prioritize infection control and labor substitution. FANUC CORPORATION dominates heavy-payload industrial installations across automotive stamping lines. Universal Robots A/S specializes in lightweight collaborative arms that small and mid-sized manufacturers deploy without safety cages. ABB extends its position through integrated vision-guided systems that merge hardware with proprietary software stacks.
A robot is a programmable electromechanical system with articulated joints, servo motors, and payload capacities ranging from sub-kilogram cobots to over one-ton industrial units, designed to execute repetitive or hazardous tasks with precision exceeding human capability. Industrial robots anchor the revenue base through mature automotive and electronics assembly demand, while autonomous mobile robots represent the fastest-expanding category as warehouses retrofit for goods-to-person fulfillment. Vision systems command premium margins because they enable real-time defect detection and adaptive path planning that basic positional robots cannot perform.
The EU AI Act classifies certain autonomous robots as high-risk AI systems, mandating conformity assessments before CE marking and market entry. ISO 10218 and OSHA workplace safety rules govern collaborative robot speed limits, force thresholds, and emergency stop protocols that manufacturers must embed at the design stage. Stakeholders should monitor how the FDA's evolving framework for surgical robots and Japan's METI subsidies for next-generation manufacturing equipment reshape competitive access across priority territories.
Market Dynamics
Electric vehicle battery assembly lines are forcing automotive manufacturers to reconfigure production layouts around collaborative robot workcells that handle volatile lithium-ion cells without human exposure. This structural shift compresses deployment timelines and rewrites safety certification requirements across Tier 1 supplier networks.
Growth Catalysts
- EU AI Act compliance mandates:High-risk autonomous system classifications are accelerating third-party conformity assessments for vision-guided robots before CE marking, creating certified product differentiation.
- Semiconductor cleanroom expansion:Wafer handling robots with ISO Class 1 ratings are penetrating foundry retrofits in Taiwan and South Korea as chip fabrication capacity scales.
- Small-batch manufacturing resurgence:Germany's Mittelstand firms are purchasing lightweight cobots without safety cages to maintain flexibility against Asian volume competitors.
Market Restraints
- Rare earth magnet dependency:Neodymium supply from Chinese processing facilities concentrates servo motor production risk and exposes OEMs to export quota volatility.
- Force-limiting sensor cost structure:Torque sensors required for ISO 10218 collaborative compliance add 15-25% to arm bill-of-materials, compressing margin at entry price points.
- Legacy PLC integration friction:Proprietary fieldbus protocols from incumbent automation vendors lock out newer robot controllers from brownfield assembly lines.
Strategic Opportunities
- Indian pharmaceutical packaging:Sterile fill-finish lines under CDSCO oversight remain underpenetrated by autonomous vial handling systems despite export volume growth.
- 5G private network convergence:Ultra-reliable low-latency connectivity is enabling real-time cloud-based path planning that offloads compute from robot controllers.
- Japan METI manufacturing subsidies:Next-generation equipment grants are covering 30-50% of cobot deployment costs for SMEs in precision component sectors.
Industry Challenges
- Multi-axis calibration expertise gap:Kinematic parameter tuning for seven-degree-of-freedom arms requires specialized technicians that vocational programs have not scaled.
- FDA 510(k) surgical robot timelines:Software-as-medical-device classifications extend premarket notification reviews for autonomous tissue manipulation systems.
- End-of-arm tooling standardization:Proprietary mechanical interfaces between arm OEMs and gripper suppliers force redundant engineering across integrator portfolios.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Robot Market |
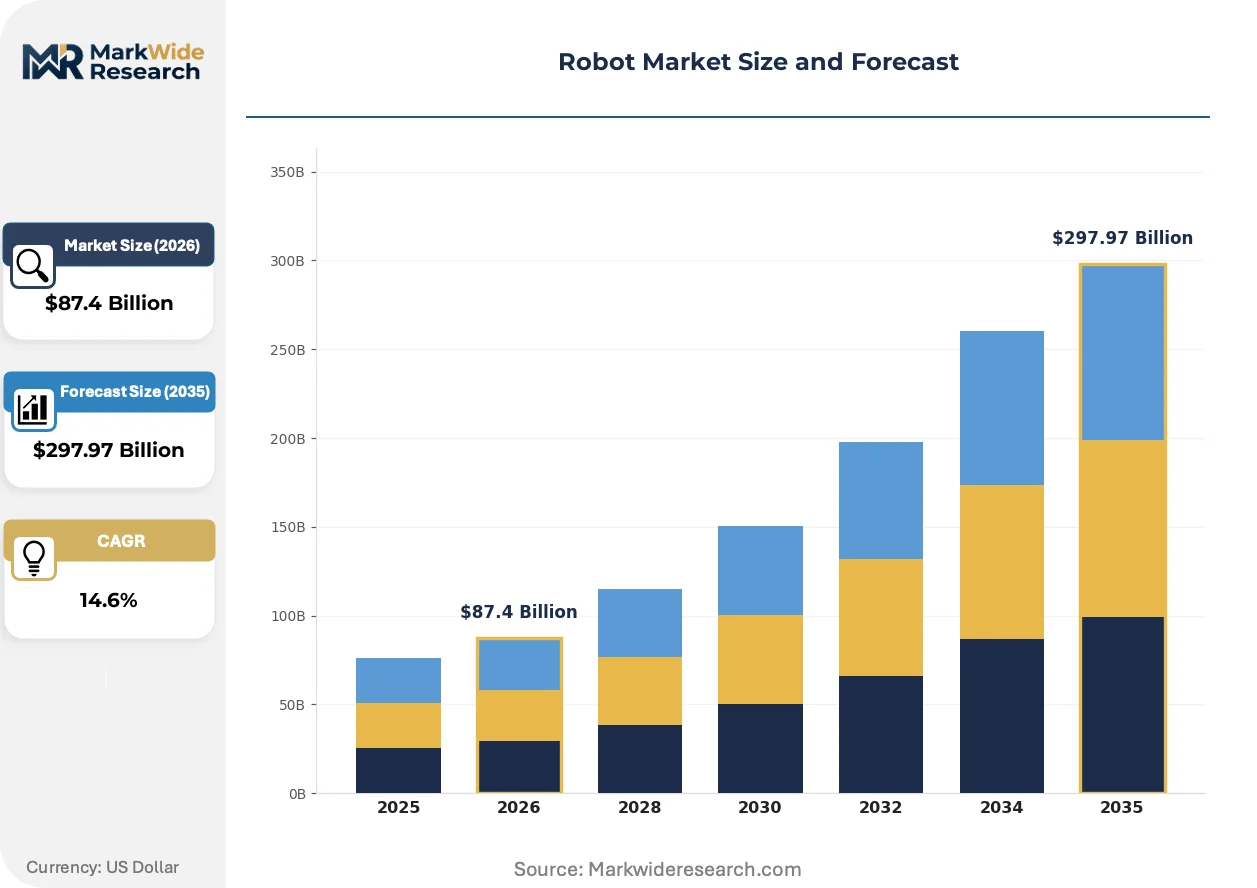
| Market Size in 2026 | $87.4 Billion |
| Market Size in 2035 | $297.97 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Robot Type: Industrial Robots, Service Robots, Collaborative Robots, Autonomous Mobile Robots End User: Manufacturing, Healthcare, Logistics, Agriculture Technology: AI-Based Automation, Sensor Technologies, Machine Learning, Vision Systems Application: Assembly, Disinfection, Packing, Inspection |
| Companies Covered | ABB, FANUC CORPORATION, Epson, Yaskawa Electric Corporation, KUKA AG, Universal Robots A/S, DENSO CORPORATION, Kawasaki Robotics, TECHMAN ROBOT INC., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Robot Market Emerging Trajectories
Edge computing architectures are redistributing intelligence from centralized controllers to individual robot joints, enabling millisecond-loop responses without network dependency. This architectural shift is compressing hardware footprints and rewriting software stack hierarchies.
Reinforcement learning from human demonstration is decentralizing programming workflows across automotive stamping and electronics assembly floors. Floor engineers at BMW and Hyundai facilities are training pick-and-place sequences through physical guidance rather than code. This capability is collapsing deployment timelines from weeks to days and shifting technical skill requirements from software specialists to production technicians.
The EU AI Act's high-risk system classification is mandating technical documentation and risk management systems for autonomous mobile robots in public spaces. Warehouse operators deploying AMRs with pedestrian zone overlap must now maintain conformity assessment files for market surveillance authorities. German logistics hubs are responding by segregating robot-only corridors to reduce classification exposure.
After-sales service unbundling is fragmenting traditional robot OEM revenue models as third-party maintenance providers capture calibration and spare parts markets. Automotive Tier 1 suppliers in Michigan and Bavaria are contracting independent integrators for preventive maintenance rather than manufacturer service agreements. This shift is most visible in high-robot-density welding shops where downtime costs exceed premium OEM service premiums.
Robot Market Segmentation
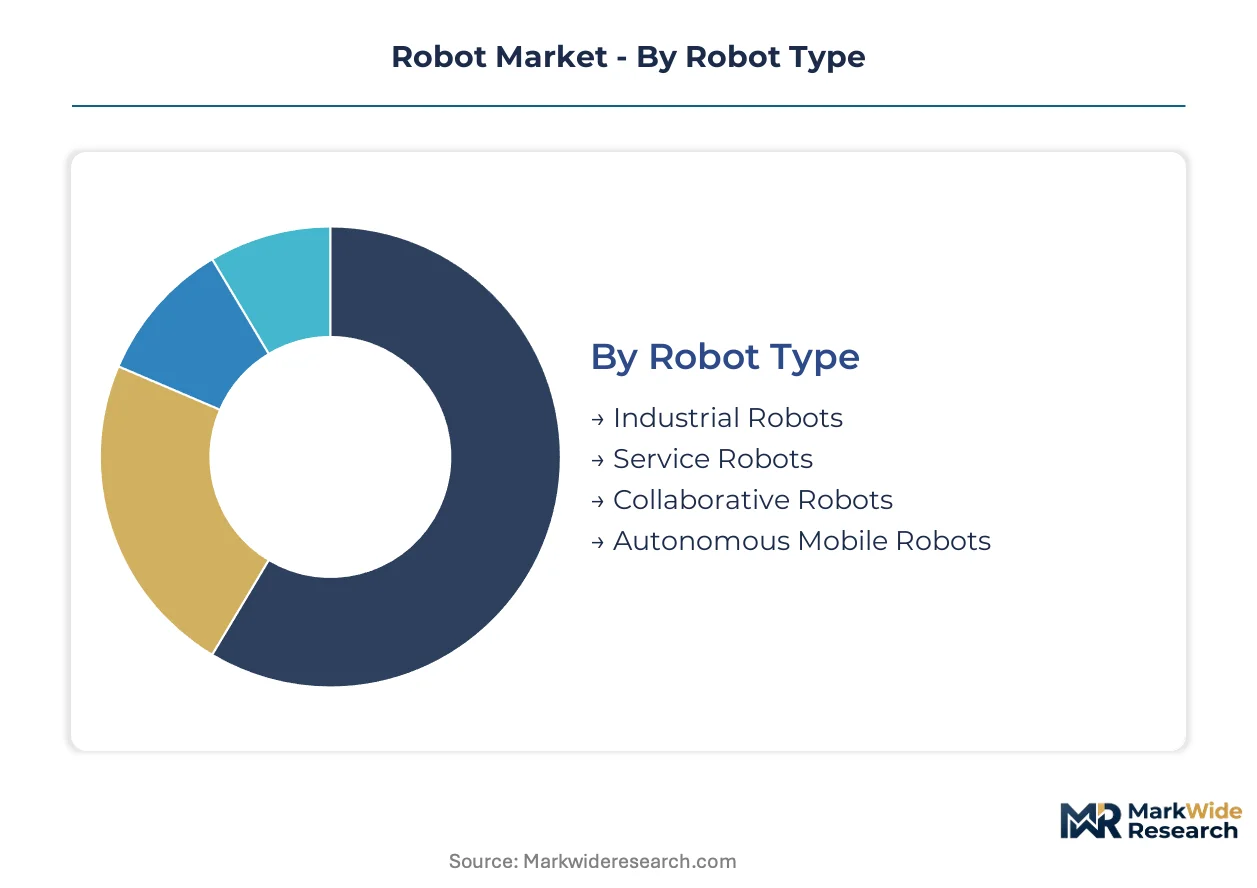
Robot market segmentation reveals how hardware specifications, software intelligence, and deployment environments shape procurement decisions. Buyers prioritize payload capacity, safety certification tiers, and integration complexity based on facility constraints and labor substitution goals.
Robot Type:
Standardized heavy-payload units dominate automotive lines while configurable lightweight systems attract small-batch manufacturers seeking rapid redeployment.
- Industrial Robots:Articulated six-axis arms with servo motor drives handle welding, stamping, and material handling across automotive final assembly. Demand concentrates in Germany's industrial corridor where OEMs retrofit electric vehicle battery lines around sub-millimeter precision requirements.
- Service Robots:Semi-autonomous platforms perform non-industrial tasks including facility cleaning, security patrol, and customer assistance in retail environments. Deployment accelerates in Japanese eldercare facilities facing acute nursing shortages.
- Collaborative Robots:Force-limited arms with ISO 10218-compliant torque sensors enable fenceless operation alongside human workers.
- Autonomous Mobile Robots:Lidar-guided platforms navigate warehouse floors for goods-to-person fulfillment without fixed infrastructure.
Leading the category by volume: Industrial Robots. Expanding most quickly: Autonomous Mobile Robots.
End User:
Capital intensity and regulatory burden separate high-automation environments from sectors still piloting mechanization.
- Manufacturing:Automotive stamping lines and electronics assembly floors deploy the highest robot densities globally. Taiwanese semiconductor foundries drive wafer-handling robot demand as cleanroom capacity scales.
- Healthcare:Surgical suites and sterilization departments prioritize infection control through UV-C disinfection robots and teleoperated surgical systems.
- Logistics:E-commerce fulfillment centers retrofit for AMR-driven sortation and pallet transport.
- Agriculture:Precision harvesting platforms and autonomous spraying drones address seasonal labor gaps in specialty crop regions.
Highest deployment density: Manufacturing. Steepest adoption trajectory: Healthcare.
Technology:
Software stack differentiation increasingly determines system value as hardware commoditizes across arm OEMs.
- AI-Based Automation:Reinforcement learning from human demonstration collapses programming timelines at BMW and Hyundai facilities.
- Sensor Technologies:Force-torque arrays and proximity detectors enable collaborative safety compliance without physical guarding.
- Machine Learning:Predictive maintenance algorithms reduce unplanned downtime in high-robot-density welding shops.
- Vision Systems:Real-time defect detection and adaptive path planning command premium pricing through proprietary software-hardware integration.
Widest margin capture: Vision Systems. Fastest capability expansion: AI-Based Automation.
Application:
Task complexity and cycle time requirements dictate whether standardized or custom-engineered solutions prevail.
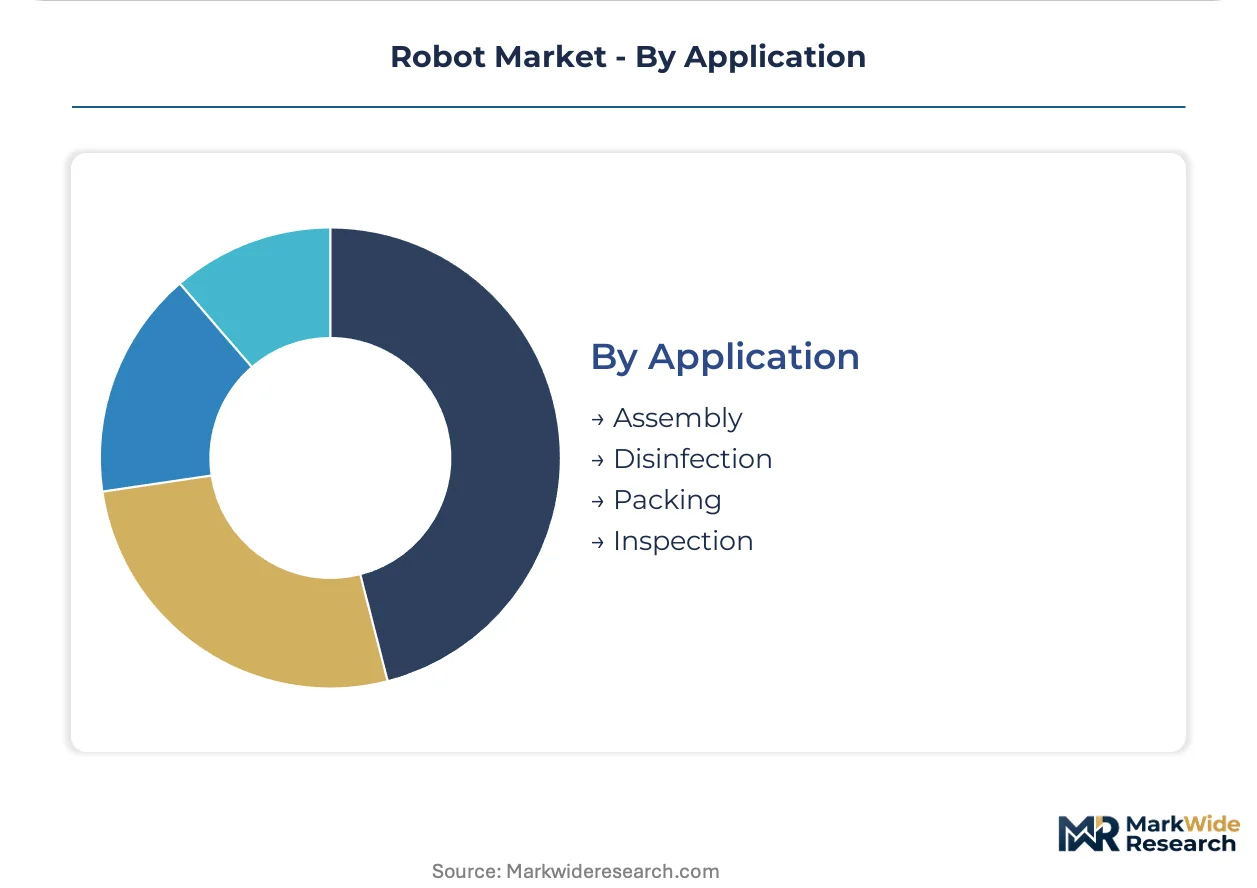
- Assembly:Multi-axis coordination for component mating dominates automotive and electronics manufacturing.
- Disinfection:UV-C and hydrogen peroxide vapor systems penetrate hospital environments under strict infection control protocols.
- Packing:End-of-line case packing and palletizing attracts collaborative robot deployment in food and pharmaceutical facilities.
- Inspection:Machine vision-guided quality verification replaces manual sampling in high-volume production.
Deepest installed base: Assembly. Fastest regulatory tailwind: Disinfection.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shenzhen's Qianhai Special Economic Zone concentrates collaborative robot R&D tax incentives, pulling venture capital toward Guangdong-Hong Kong-Macao Greater Bay Area automation clusters.
United States
Michigan automotive stamping lines and Texas semiconductor fabs drive heavy-payload robot procurement for EV battery assembly and wafer handling. OSHA workplace safety rules govern collaborative robot force thresholds and emergency stop protocols in fenceless workcells. Detroit-Warren-Dearborn metro area hosts the densest robot installation base for automotive spot welding and material handling applications.
Germany
Mittelstand precision manufacturers in Baden-Württemberg purchase ISO 10218-compliant cobots for small-batch flexibility against Asian volume competitors. EU AI Act high-risk system classifications mandate conformity assessments for vision-guided autonomous mobile robots before CE marking. Stuttgart industrial corridor anchors global demand for six-axis articulated arms in automotive powertrain assembly.
China
Yangtze River Delta electronics contract manufacturers deploy SCARA robots for smartphone assembly at scale unmatched elsewhere. MIIT smart manufacturing subsidies and GB standards for industrial robot safety accelerate domestic controller and servo motor production. Shanghai Pudong robotics industrial park concentrates domestic arm OEMs and precision reducer suppliers serving regional foundry and flat-panel display sectors.
Japan
Chubu region automotive suppliers and Aichi prefecture machine tool builders integrate force-limited collaborative arms for mixed-model production lines. METI next-generation manufacturing equipment grants cover 30-50% of cobot deployment costs for SMEs in precision component sectors. Nagoya-Toyohashi industrial belt maintains the highest robot density per manufacturing worker globally, anchored by automotive and electronics assembly demand.
South Korea
Gyeonggi-do semiconductor cleanrooms and Incheon battery gigafactories expand ISO Class 1 wafer handling robot installations as foundry capacity scales. MFDS medical device regulations and KOSHA industrial safety standards shape surgical robot and collaborative arm certification pathways. Songdo smart city zone pilots autonomous mobile robots for last-mile logistics under regulatory sandbox exemptions.
Robot Market Vendor Landscape
Top-tier vendors anchor premium-tier system integration, while mid-scale specialists occupy component and regional service niches. The vendor base stratifies across three tiers: full-stack platform providers with proprietary controller architectures, application-focused integrators with vertical expertise, and component suppliers specializing in reducers, servo motors, or end-of-arm tooling. Two dominant competitive moves are reshaping positioning: strategic partnerships between arm OEMs and cloud software providers for AI-based path planning, and backward integration into precision reducer manufacturing to secure supply chain control.
Within the full-stack platform tier, ABB and FANUC CORPORATION exemplify integrated hardware-software positioning, while Universal Robots A/S occupies a distinct archetype as the collaborative arm specialist enabling fenceless deployment for small and mid-sized manufacturers. KUKA AG represents European-centric system integration capabilities with automotive line expertise. These three anchors illustrate how competitive positioning diverges across payload range, safety certification tier, and customer scale focus.
| Leading Market Players |
|---|
| ABB |
| FANUC CORPORATION |
| Epson |
| Yaskawa Electric Corporation |
| KUKA AG |
| Universal Robots A/S |
| DENSO CORPORATION |
| Kawasaki Robotics |
| TECHMAN ROBOT INC. |
| Others |
Supply Flow & Price Mechanics
Neodymium price indices on the Shanghai Metals Market cascade through servo motor production into three-tier pricing structures across premium, standard, and economy robot tiers. Chinese rare earth processing quotas transmit volatility downstream, forcing OEMs to index long-term supply agreements against spot magnet prices while Tier 1 automotive buyers negotiate fixed-price contracts for EV battery line deployments.
Pricing Analysis
Short lead-time premiums of 12-18% separate expedited collaborative robot deliveries from standard 14-week production slots. Three-tier pricing structure across premium, standard, and economy levels reflects ISO 10218 certification grade and force-torque sensor integration depth. Cost compression in entry-level cobots is intensifying because Chinese domestic controller manufacturers are undercutting Japanese servo motor bundles. Small-batch Mittelstand manufacturers exhibit highest price sensitivity, while automotive OEMs prioritize uptime guarantees over unit economics.
Supply Chain Analysis
ISO 10218 and EU AI Act conformity assessment requirements gate supplier qualification for European AMR deployments, extending vendor onboarding to 8-12 months. Precision reducer production concentrates in Japan, Germany, and China, while neodymium magnet processing and servo motor winding draw from Chinese and Taiwanese facilities. Single-source vulnerability in harmonic drive reducers from Nabtesco and Harmonic Drive Systems exposes integrators to 6-month allocation delays. Distribution runs through authorized integrator networks for complex installations, with direct OEM sales dominating high-volume automotive contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Neodymium magnet supply constraints and ISO 10218 certification bottlenecks prop pricing power for qualified vendors. Capacity scarcity in precision reducer manufacturing limits competitor entry regardless of capital availability.
For Market Incumbents: Anticipate margin compression from Chinese servo motor entrants by securing captive neodymium supply through offtake agreements with Australian and Vietnamese rare earth projects. Reinforce certification moats through early EU AI Act high-risk system compliance investments ahead of 2025 enforcement windows. Prioritize backward integration into torque sensor production to offset 15-25% bill-of-materials inflation from force-limiting component suppliers.
For New Entrants and Emerging Players: The premium-to-economy price gap in collaborative robots exceeds 40% for equivalent payload ranges, creating white-space for mid-tier challengers with ISO 10218 compliance but stripped-down software stacks. Target Indian pharmaceutical packaging lines under CDSCO oversight, where sterile fill-finish automation remains underpenetrated despite export volume growth. Pursue 5G private network partnerships as a go-to-market wedge, offering cloud-based path planning that offloads compute costs from robot controllers.
For Investors and Strategic Acquirers: Distressed-cycle entries favor precision reducer specialists with Japanese or German manufacturing footprints and established automotive Tier 1 relationships. Long-term viability hinges on 5-10 year positioning for next-generation manufacturing equipment subsidy capture in Japan and Germany. Monitor Japan METI grant disbursement velocity as an inflection indicator for SME cobot deployment acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precision Reducers | Secures supply chain control against Nabtesco allocation constraints for automotive line deployments. |
| EU AI Act Conformity Pre-Certification | Accelerates CE marking timelines for vision-guided AMRs in German logistics corridors. |
| 5G Private Network Partnership | Enables real-time cloud path planning that reduces controller hardware costs for warehouse operators. |
| Indian Pharmaceutical Packaging Entry | Captures CDSCO-regulated sterile fill-finish automation demand from export-oriented generic manufacturers. |
| Reinforcement Learning Platform Launch | Collapses programming timelines at BMW-scale facilities through physical demonstration workflows. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with plant engineers at automotive OEMs, procurement leads at Tier 1 suppliers, aftermarket service heads at integrator networks, and regulatory affairs managers at arm OEMs validated demand assumptions. Secondary sources included IFR World Robotics reports, EU AI Act implementation guidance, FDA 510(k) surgical robot filings, and Japan METI subsidy disbursement records. Bottom-up unit shipment modeling triangulated against top-down value estimates from customs trade databases.
Granularity-level modeling distinguished payload capacity tiers, safety certification grades, and end-use industry verticals across the projection horizon. The analytical framework projected industrial robot, collaborative robot, service robot, and autonomous mobile robot segments separately, with cross-elasticity parameters capturing substitution effects. CAGRs derived from regression against macroeconomic indicators and capital expenditure cycles specific to automotive and semiconductor fabrication equipment investment. Forecast inputs incorporated EU AI Act compliance cost assumptions and rare earth magnet price trajectory scenarios.
Inputs from Japanese METI grant programs and EU conformity assessment registries were available through the study window; gaps in private 5G deployment timelines for warehouse automation introduce uncertainty bands for AMR adoption curves. Forecasts reflect assumptions on neodymium supply stability and ISO 10218 revision schedules. A model refresh is warranted upon material change in China rare earth export quota policy or EU AI Act high-risk system classification scope expansion.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
Europe Agricultural Robots and Mechatronics Market
Robotics and Automation
Telepresence Robot Market
Robotics and Automation
South America AUV Market
Robotics and Automation
Robotic Air Purifier Market
Robotics and Automation
AI Assisted Robots Market
Robotics and Automation
Robot Charging Station Market
Robotics and Automation
AGV Dispatch Management Platforms Market
Robotics and Automation
Robot Coffee Kiosk Market
Robotics and Automation
Global Robot Kitchen Market
Robotics and Automation
Malaysia Robotics Market
Robotics and Automation
Drone-Based NDT Inspection Systems for Energy and Infrastructure Assets Market
Robotics and Automation
Autonomous Polishing Machine Market
Robotics and Automation
Asrs and Ruos Market
Robotics and Automation
Nano Robots Market
Robotics and Automation
Healthcare Companion Robots Market
Robotics and Automation
Global Exoskeleton Market