
 Robotic Waste Sorting System Market | 2026-2036
Robotic Waste Sorting System Market Size, Share, and Industry Trends Forecast 2026-2036
Robotic Waste Sorting System Market Analytics
Aftermarket service revenue is narrowing as manufacturers shift toward subscription-based AI vision licensing. Bulk Handling Systems leverages its installed base of optical sorters to extend software update contracts. AMP Robotics Corporation anchors North American deployments with cloud-trained neural networks that improve pick accuracy. ZenRobotics Ltd dominates the construction and demolition waste niche through heavy-payload robotic arms.
Robotic waste sorting systems integrate articulated manipulators, hyperspectral cameras, and pneumatic ejectors to identify and separate heterogeneous material streams at throughput rates exceeding human manual sorting. These systems serve material recovery facilities and recycling plants seeking contamination reduction and labor cost stabilization. The automated system type captures the largest installed base while hybrid configurations represent the fastest-growing category as retrofits bridge legacy conveyor lines with robotic cells. AI-driven technology leads R&D investment intensity, though computer vision hardware margins remain concentrated among specialized sensor suppliers serving integrators like TOMRA Systems ASA and Machinex Industries Inc.
The EU Green Deal and REACH framework mandate extended producer responsibility and hazardous substance disclosure that elevate sorting purity requirements. EPA landfill diversion targets in the United States and China's MEE circular economy enforcement both tighten residue specifications for exported recyclables. Stakeholders must monitor regulatory threshold evolution rather than current compliance baselines when sizing equipment capacity and sensor resolution investments.
Market Dynamics
Subscription-based AI vision licensing is compressing aftermarket service revenue streams while manufacturers pivot toward recurring software contracts to capture lifetime value from installed robotic sorting hardware.
Growth Catalysts
- EU Green Deal binding targets:Extended producer responsibility mandates elevate sorting purity requirements across material recovery facilities in Germany, the Netherlands, and France.
- Hyperspectral imaging integration:Next-generation sensor fusion enables real-time polymer identification at throughput rates that manual sorting cannot match.
- Rotterdam port-adjacent cluster density:Concentrated waste volumes in the Netherlands create economies of scale for multi-robot cell deployments.
Market Restraints
- Specialized sensor supply concentration:Hyperspectral camera modules rely on a limited supplier base concentrated in German and Japanese optical component manufacturers.
- Capital intensity for retrofits:Hybrid system integration demands simultaneous conveyor line modification and robotic cell installation.
- REACH hazardous substance disclosure:Complex material stream characterization requirements slow equipment qualification timelines for mixed construction debris.
Strategic Opportunities
- Construction and demolition waste automation:Heavy-payload robotic arms remain underdeployed in concrete and wood fraction recovery outside Nordic markets.
- Cloud-trained neural network convergence:Edge computing hardware paired with centralized model refinement enables rapid accuracy improvement without on-site retraining.
- China MEE circular economy enforcement:Stricter residue specifications for imported recyclables create demand for higher-resolution sorting systems in export-oriented facilities.
Industry Challenges
- Mechatronics technician scarcity:Maintenance of articulated manipulators and pneumatic ejector arrays requires specialized skills that vocational pipelines have not scaled.
- Legacy optical sorter integration:Retrofitting robotic cells alongside existing near-infrared systems demands custom mechanical interfaces and control software bridging.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Robotic Waste Sorting System Market |
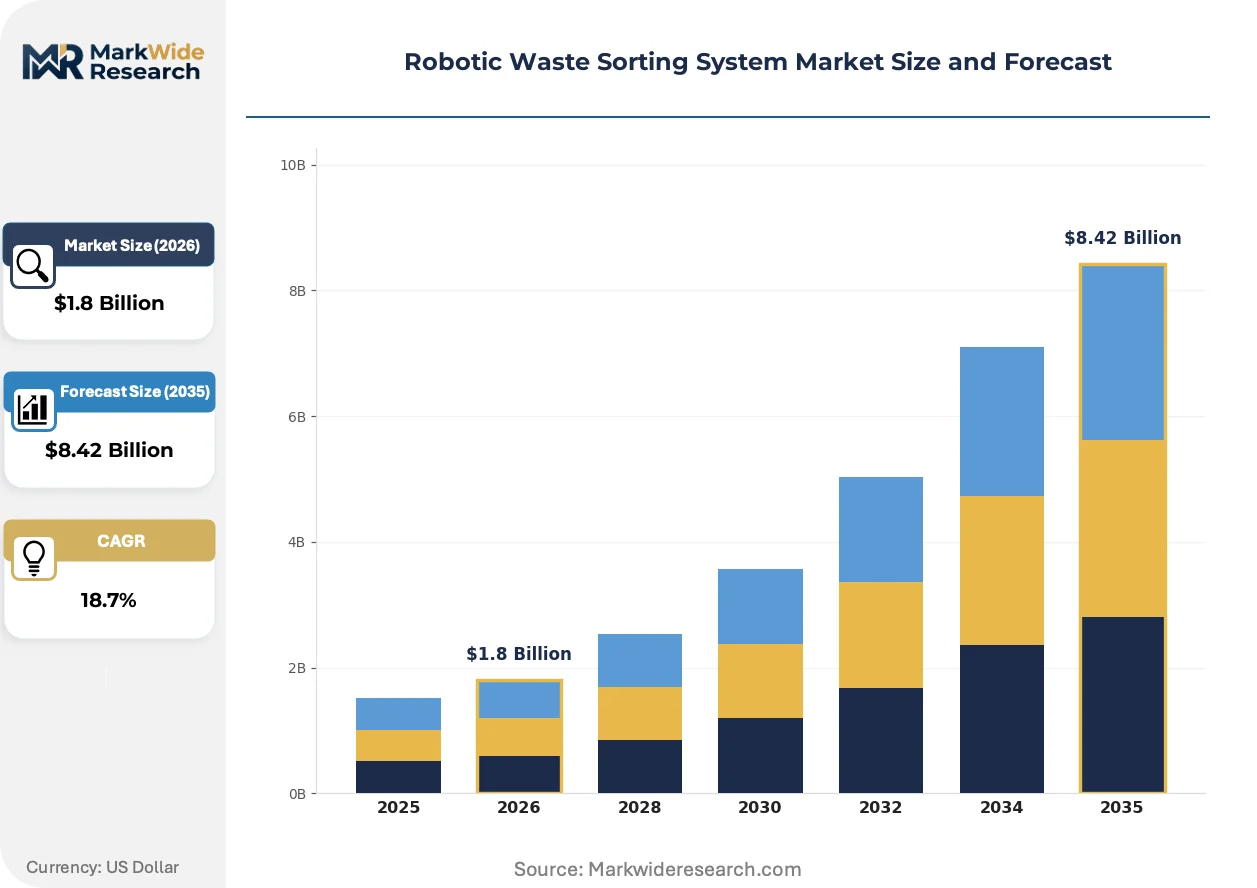
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $8.42 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | System Type: Automated, Semi-Automated, Manual, Hybrid Technology: AI, Computer Vision, Machine Learning, Robotics End User: MRFs, Municipalities, Recycling Facilities, Industries Application: Plastic Recycling, Metal Sorting, Organic Waste, E-Waste |
| Companies Covered | Bulk Handling Systems, Sadako Technologies, AMP Robotics Corporation, Pellenc ST, Everest Labs, ZenRobotics Ltd, Waste Robotics Inc, TOMRA Systems ASA, Machinex Industries Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Robotic Waste Sorting System Market Evolving Landscape
Deep learning architectures and sensor fusion are compressing the gap between laboratory classification accuracy and production-line throughput, reshaping how material recovery facilities evaluate equipment procurement.
Computer vision hardware is hybridizing with pneumatic sorting actuation to enable real-time decision-to-ejection cycles under 100 milliseconds. Municipal solid waste operators in Germany are adopting these integrated cells at pace to meet purity thresholds. The convergence is compressing equipment vendor margins as specialized sensor suppliers capture value upstream from system integrators.
EPA landfill diversion targets are tightening residue specifications for exported recyclables across United States material recovery facilities. Facilities must now document contamination rates below three percent to maintain export permits. California and Northeast corridor operators are responding with denser robot deployments and secondary quality control stations.
Service contract unbundling is fragmenting how buyers procure maintenance and software updates. Large waste management groups now negotiate AI vision licenses separately from mechanical service agreements. This pattern is most visible in Dutch and German markets where municipal procurement rules favor modular contracting.
Robotic Waste Sorting System Market Segmentation
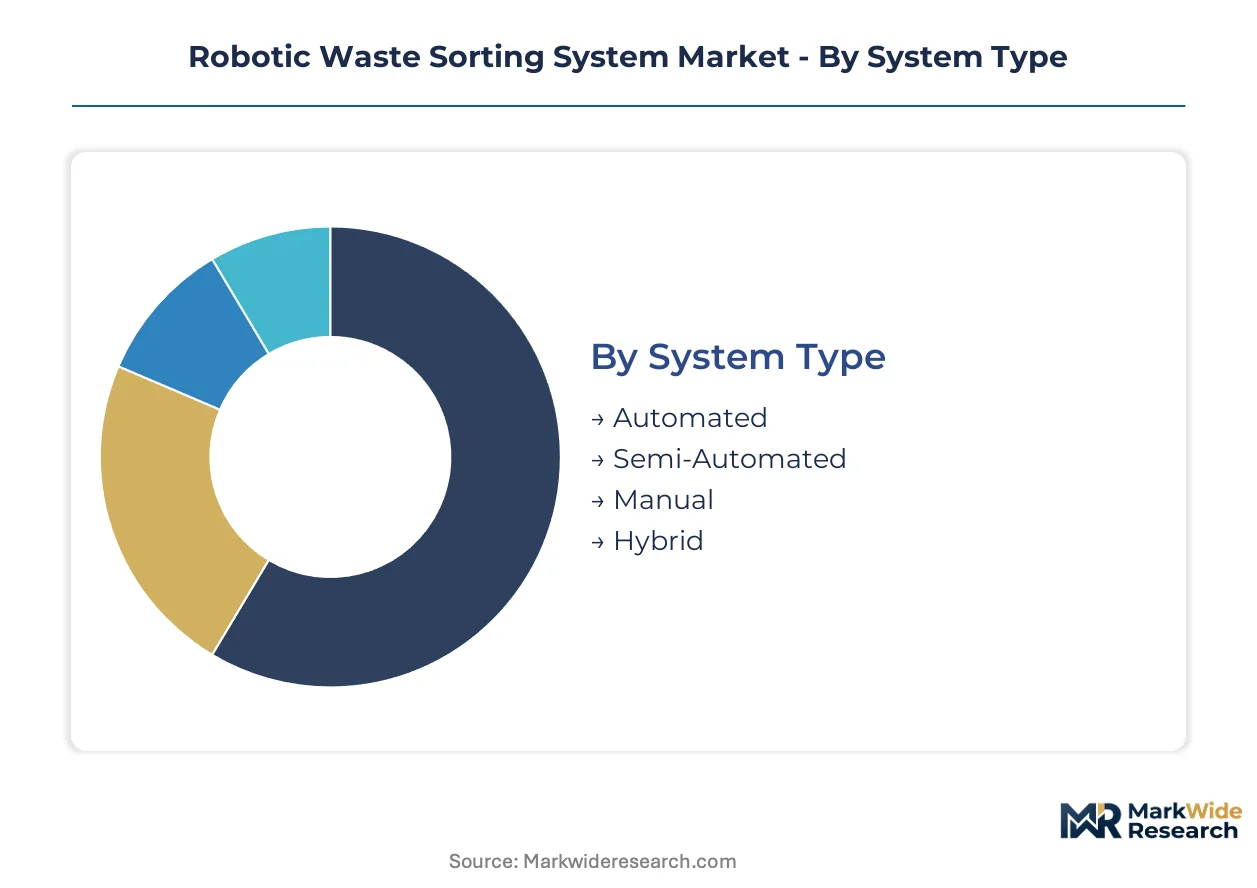
Segmentation in robotic waste sorting systems reflects divergent capital deployment strategies across facility types and material streams. Procurement patterns vary sharply between municipal operators optimizing for labor substitution and industrial recyclers targeting purity premiums for export compliance.
System Type:
Mature configurations dominate current installed capacity while emerging hybrid architectures reshape retrofit economics for legacy facilities.
- Automated:Fully integrated cells combine articulated manipulators, hyperspectral cameras, and pneumatic ejectors into turnkey installations. German municipal solid waste programs anchor demand as binding EU Green Deal targets mandate contamination thresholds below three percent residue.
- Hybrid:Bridging configurations retrofit robotic cells alongside existing conveyor infrastructure, preserving near-infrared optical sorter investments while adding AI-driven pick stations. Dutch procurement rules favor modular contracting that separates mechanical service from software licensing, accelerating adoption in Rotterdam's port-adjacent recycling cluster.
- Semi-Automated:Human-robot collaborative stations handle pre-sorting or quality control with partial mechanization.
- Manual:Legacy operations without robotic integration persist in smaller facilities or developing markets with lower labor costs.
Automated systems retain volume leadership; hybrid configurations hold the steepest expansion curve.
Technology:
Cost tier stratification separates capital-intensive sensor hardware from software licensing models that compress upfront expenditure.
- Computer Vision:Hyperspectral imaging modules enable real-time polymer identification at throughput rates exceeding human sorting capacity. Specialized sensor suppliers in Germany and Japan concentrate upstream margins, creating supply bottlenecks for system integrators serving material recovery facilities.
- AI:Cloud-trained neural networks refine pick accuracy through centralized model updates without on-site retraining. North American deployments leverage this architecture to meet EPA landfill diversion targets tightening residue specifications for exported recyclables.
- Machine Learning:Edge computing implementations process classification algorithms locally, reducing latency for facilities with limited connectivity.
- Robotics:Articulated manipulator and pneumatic actuator hardware forms the mechanical substrate for all technology stacks.
Computer vision captures the highest hardware margins; AI licensing is expanding most quickly.
End User:
Customer type determines procurement sophistication, with volume scale and regulatory exposure driving technology selection.
- MRFs:Material recovery facilities process heterogeneous municipal streams requiring contamination reduction for resale value. California and Northeast corridor operators deploy denser robot arrays and secondary quality control stations to maintain export permits under tightening EPA specifications.
- Recycling Facilities:Specialized operators target single-stream or commercial waste with higher purity requirements. China's MEE circular economy enforcement creates demand for higher-resolution sorting systems in export-oriented facilities serving Asian markets.
- Municipalities:Public procurement favors modular contracting that unbundles AI vision licenses from mechanical service agreements.
- Industries:Manufacturing waste streams with predictable composition enable customized robotic configurations.
MRFs dominate current installations; recycling facilities are gaining share fastest.
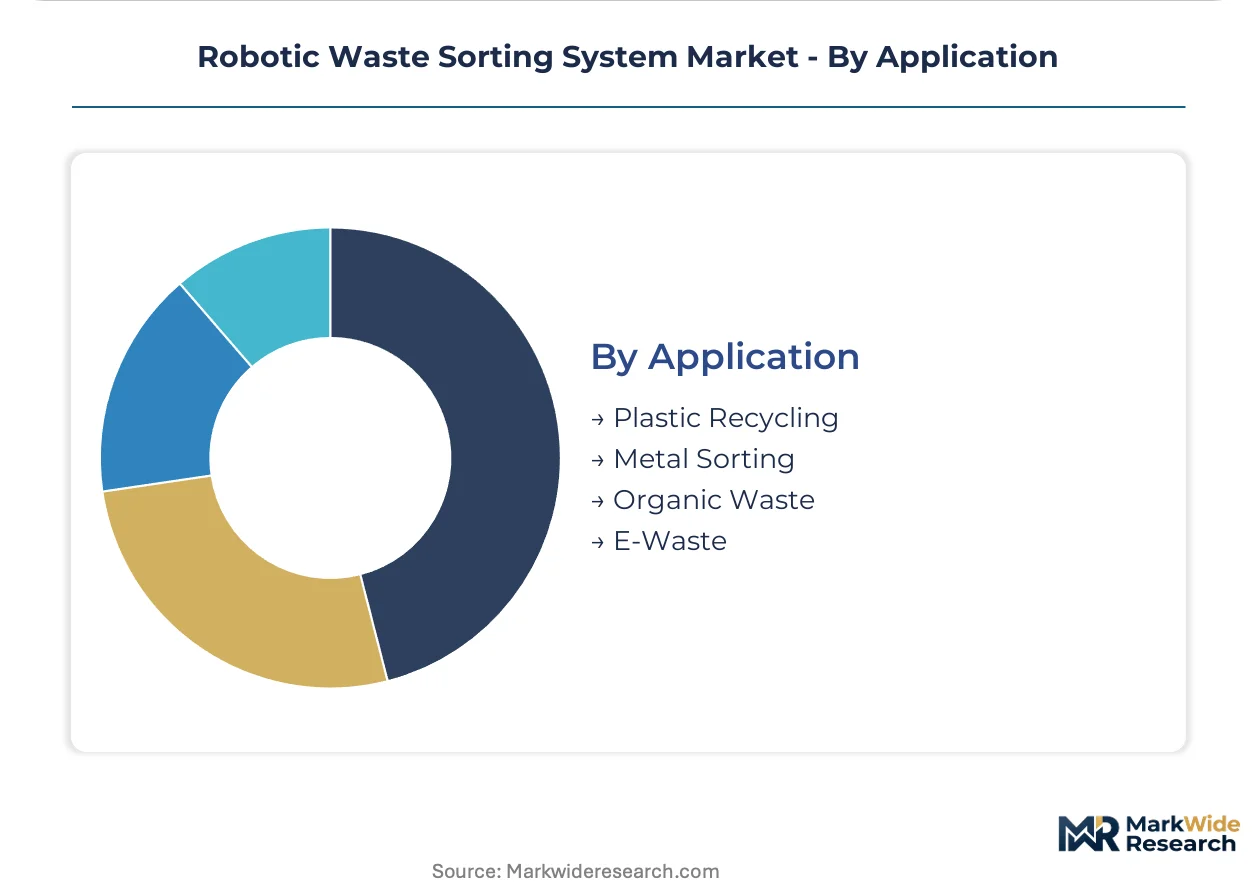
Application:
Application segmentation tracks material value recovery potential and regulatory scrutiny intensity across waste categories.
- Plastic Recycling:Polymer identification demands drive hyperspectral camera adoption for separating PET, HDPE, and mixed fractions. REACH hazardous substance disclosure requirements complicate equipment qualification timelines for mixed post-consumer streams.
- Construction and Demolition Waste:Heavy-payload robotic arms recover concrete and wood fractions where manual sorting faces safety constraints. Nordic markets lead deployment; underpenetration persists in Southern and Eastern European markets despite EU Green Deal circular economy mandates.
- Metal Sorting:Ferrous and non-ferrous separation leverages electromagnetic sensing paired with robotic extraction for complex shapes.
- Organic Waste:Contamination removal from compost streams requires moisture-resistant sensor configurations and gentle handling protocols.
- E-Waste:Hazardous component recovery demands precision manipulation and substance characterization for regulatory compliance.
Plastic recycling maintains the largest addressable volume; construction and demolition waste shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany deploys fully integrated robotic cells for municipal purity mandates, while the United States favors hybrid retrofits that preserve legacy optical sorter investments. The Netherlands concentrates multi-robot deployments at port-adjacent clusters, and China enforces stricter residue specifications for import compliance. Japan and France represent emerging demand pockets with diverging procurement sophistication.
Germany
Municipal solid waste programs anchor European demand through binding EU Green Deal contamination thresholds. The country's national environmental regulator enforces extended producer responsibility mandates that elevate sorting purity requirements. North Rhine-Westphalia's dense recycling infrastructure drives turnkey automated system procurement at scale.
United States
EPA landfill diversion targets tighten residue specifications below three percent for export permit maintenance. California and Northeast corridor operators respond with denser robot arrays and secondary quality control stations. The Pacific Northwest clusters around Seattle-Tacoma concentrate retrofit demand for hybrid configurations.
Netherlands
Rotterdam's port-adjacent recycling cluster creates economies of scale for multi-robot cell deployment unmatched elsewhere in Europe. Municipal procurement rules favor modular contracting that unbundles AI vision licenses from mechanical service agreements. The Randstad metropolitan concentration drives dense equipment utilization rates.
China
MEE circular economy enforcement tightens residue specifications for imported recyclables, forcing export-oriented facilities to upgrade sensor resolution. Yangtze River Delta material recovery facilities invest in higher-resolution sorting systems to maintain Asian market access. Pearl River Delta operators face parallel compliance pressure for polymer purity documentation.
Japan
Construction and demolition waste automation lags Nordic penetration despite METI circular economy guidance. Tokyo-Osaka industrial corridors show emerging interest in heavy-payload robotic arms for concrete fraction recovery. Kansai region pilot programs test cloud-trained neural network integration for real-time polymer identification.
Robotic Waste Sorting System Market Competitive Landscape
Capability concentration sits with one tier; scale advantage sits with another. Specialized sensor suppliers in Germany and Japan capture upstream margins from hyperspectral imaging modules, while system integrators compete on deployment velocity and software licensing terms. Three archetypes dominate: optical component specialists, AI-vision software licensors, and full-stack turnkey integrators. Competitive moves center on strategic partnerships for sensor supply security and geographic expansion into underpenetrated construction waste markets.
Within the full-stack integrator tier, Bulk Handling Systems and TOMRA Systems ASA exemplify scale-driven positioning through installed base leverage for software update contracts. AMP Robotics Corporation occupies a distinct archetype as a North American anchor for cloud-trained neural network deployment. ZenRobotics Ltd represents the heavy-payload specialization vector for construction and demolition waste applications.
| Leading Market Players |
|---|
| Bulk Handling Systems |
| Sadako Technologies |
| AMP Robotics Corporation |
| Pellenc ST |
| Everest Labs |
| ZenRobotics Ltd |
| Waste Robotics Inc |
| TOMRA Systems ASA |
| Machinex Industries Inc |
| Others |
Value Network & Pricing Analysis
North Rhine-Westphalia's dense optical component manufacturing cluster shapes downstream pricing power for system integrators serving material recovery facilities. German and Japanese sensor suppliers command upstream margins that compress hardware vendor profitability, while subscription-based AI vision licensing shifts value capture toward recurring software contracts.
Pricing Analysis
Long-term software licensing contracts dominate procurement patterns, with AI vision subscriptions displacing traditional hardware-plus-service bundles. Three-tier pricing structure across premium hyperspectral configurations, standard optical fusion systems, and economy retrofit kits differentiates by sensor resolution and after-sales support intensity. Cost compression in economy-tier retrofits is intensifying because municipal procurement rules favor modular contracting that unbundles mechanical service from software licensing. Municipal operators exhibit highest price sensitivity due to budget cycle constraints, while export-oriented recycling facilities demonstrate lowest sensitivity given compliance-driven upgrade mandates.
Supply Chain Analysis
Extended payment terms from German and Japanese optical component manufacturers strain working capital for system integrators assembling turnkey robotic cells. Hyperspectral camera modules draw from concentrated sensor fabrication capacity in Germany, Japan, and South Korea, with specialized lens arrays and CMOS detectors feeding from semiconductor foundries. Single-source vulnerability persists for short-wave infrared detectors used in polymer identification applications. Distribution runs through direct OEM sales for large municipal contracts and regional integrator networks for mid-scale facility retrofits.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Robotic waste sorting hardware is commoditizing while AI vision licensing and predictive maintenance contracts expand at multiples of equipment sales growth. The service-attach opportunity concentrates in cloud-trained model refinement and sensor calibration subscriptions that lock in lifetime customer value.
For Market Incumbents: Entrench installed base relationships through mandatory sensor calibration subscriptions that preempt third-party service entry. Secure exclusive supply agreements with German and Japanese hyperspectral component manufacturers to defend against emerging AI-software-only entrants. Vertical integration into edge computing hardware production mitigates margin pressure from specialized sensor suppliers capturing upstream value. For New Entrants and Emerging Players: Pursue construction and demolition waste automation in Southern and Eastern European markets where heavy-payload robotic arm penetration lags Nordic benchmarks. Target hybrid retrofit configurations for legacy material recovery facilities seeking to preserve near-infrared optical sorter investments while adding AI-driven quality control stations. Partner with established waste management groups for pilot deployments that demonstrate throughput improvement against manual sorting baselines. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors AI-vision software licensors with cloud-trained neural network architectures over hardware-centric integrators facing component cost pressure. Five-to-ten year viability hinges on recurring revenue mix and customer switching costs rather than one-time equipment sales. Monitor EU Green Deal recycling target enforcement intensity as the inflection indicator for upgrade cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| AI Vision Licensing Expansion | Subscription revenue from cloud-trained neural networks displaces transactional hardware margins for integrators. |
| Sensor Supply Security Partnerships | Exclusive agreements with German and Japanese optical component manufacturers reduce single-source vulnerability. |
| Construction Waste Market Entry | Heavy-payload robotic arm deployment in Southern Europe addresses underpenetrated concrete fraction recovery. |
| Hybrid Retrofit Configuration Development | Bridging solutions preserve legacy near-infrared investments while adding AI-driven pick stations. |
| Predictive Maintenance Service Launch | Sensor calibration and mechatronics technician dispatch contracts lock in recurring facility relationships. |
Research Methodology
Cross-validation between primary interviews with material recovery facility operators and secondary trade data anchors the qualitative findings. Plant managers at German and Dutch municipal solid waste programs, procurement leads at export-oriented recycling facilities, aftermarket service heads at system integrators, and optical component R&D directors provided operational perspective. Customs records, EPA landfill diversion compliance filings, EU Green Deal implementation progress reports, and hyperspectral sensor patent databases supplied quantitative validation. Bottom-up facility deployment tallies and top-down equipment vendor revenue estimates were reconciled through iterative triangulation.
Calibration against historical adoption curves for optical sorter technology and near-infrared polymer identification systems informed the projection framework. Segmentation dimensions modeled include system type configuration, technology stack composition, end-user facility category, and application material stream across the analysis window. CAGRs were derived from elasticity-adjusted demand functions incorporating regulatory threshold evolution and labor cost substitution economics. Sensor resolution upgrade cycles and cloud-trained neural network accuracy improvement trajectories served as industry-specific forecast inputs.
Sensitivities concentrate around EU Green Deal target enforcement timing, MEE circular economy residue specification revisions, and mechatronics technician training pipeline expansion. Forecasts reflect documented assumptions regarding regulatory compliance cost pass-through and municipal procurement cycle stability. Macroeconomic contraction affecting capital expenditure budgets, regulatory deviation from announced recycling thresholds, or breakthrough advances in autonomous sorting accuracy would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
China Autonomous Mobile Robot Market
Robotics and Automation
Smart Machines Market
Robotics and Automation
Airport Robots Market
Robotics and Automation
Latin America Cloud Robotics Market
Robotics and Automation
Robotics and Automation Actuators Market
Robotics and Automation
Agricultural Robots and Mechatronics Market
Robotics and Automation
Global Robotic Grippers Market
Robotics and Automation
Medical Automation Technologies Market
Robotics and Automation
Solar Panel Cleaning Robot Market
Robotics and Automation
Lab Robotics Market
Robotics and Automation
Collaborative Robots Market
Robotics and Automation
Pharmaceutical Collaborative Robots Market
Robotics and Automation
Clean Room Robot Market
Robotics and Automation
Global Molecular Robotics Market
Robotics and Automation
Global Agriculture Robots Market
Robotics and Automation
Hospital Logistics Robots Market