
 Self-Driving Delivery Robot Market | 2026-2036
Self-Driving Delivery Robot Market Size, Share, and Industry Trends Forecast 2026-2036
Self-Driving Delivery Robot Market Insights
Fragmentation across quick-commerce platforms and campus logistics operators is repositioning procurement patterns toward smaller, multi-vendor fleets. Nuro, Inc. anchors its strategy around neighborhood-scale autonomous vehicles designed for regulated street access. Starship Technologies dominates sidewalk delivery through dense campus and urban deployments across multiple countries. JD.com, Inc. leverages its integrated e-commerce infrastructure to control robot deployment within captive logistics networks.
Self-driving delivery robots are autonomous ground-based vehicles typically operating at speeds below 25 km/h, utilizing sensor fusion arrays combining LiDAR, computer vision, and GPS navigation to traverse pedestrian walkways, bike lanes, or low-speed roadways for goods transport. Their primary commercial purpose is to execute last-mile delivery without human drivers, reducing per-drop labor costs in high-frequency, short-radius fulfillment scenarios. Outdoor robots lead current deployment volumes due to their direct substitution potential for conventional van-based delivery in suburban and urban environments. Machine learning capabilities are expanding fastest as operators train navigation models on diverse sidewalk geometries, traffic behaviors, and weather conditions. Indoor robots occupy concentrated margin pools within controlled environments such as hospitals, hotels, and corporate campuses where navigation complexity remains low and repeatability stays high.
The National Highway Traffic Safety Administration in the United States evaluates street-operating delivery vehicles under evolving low-speed autonomous vehicle exemptions, while the EU AI Act imposes risk-classification requirements on automated decision systems including delivery routing algorithms. The Federal Communications Commission regulates the wireless communication bands that enable real-time fleet coordination and remote monitoring capabilities. Stakeholders must monitor how municipal permitting processes in cities like San Francisco, Phoenix, and Austin diverge from federal guidelines, as local sidewalk ordinances and insurance mandates will determine viable operating territories before national frameworks consolidate.
Market Dynamics
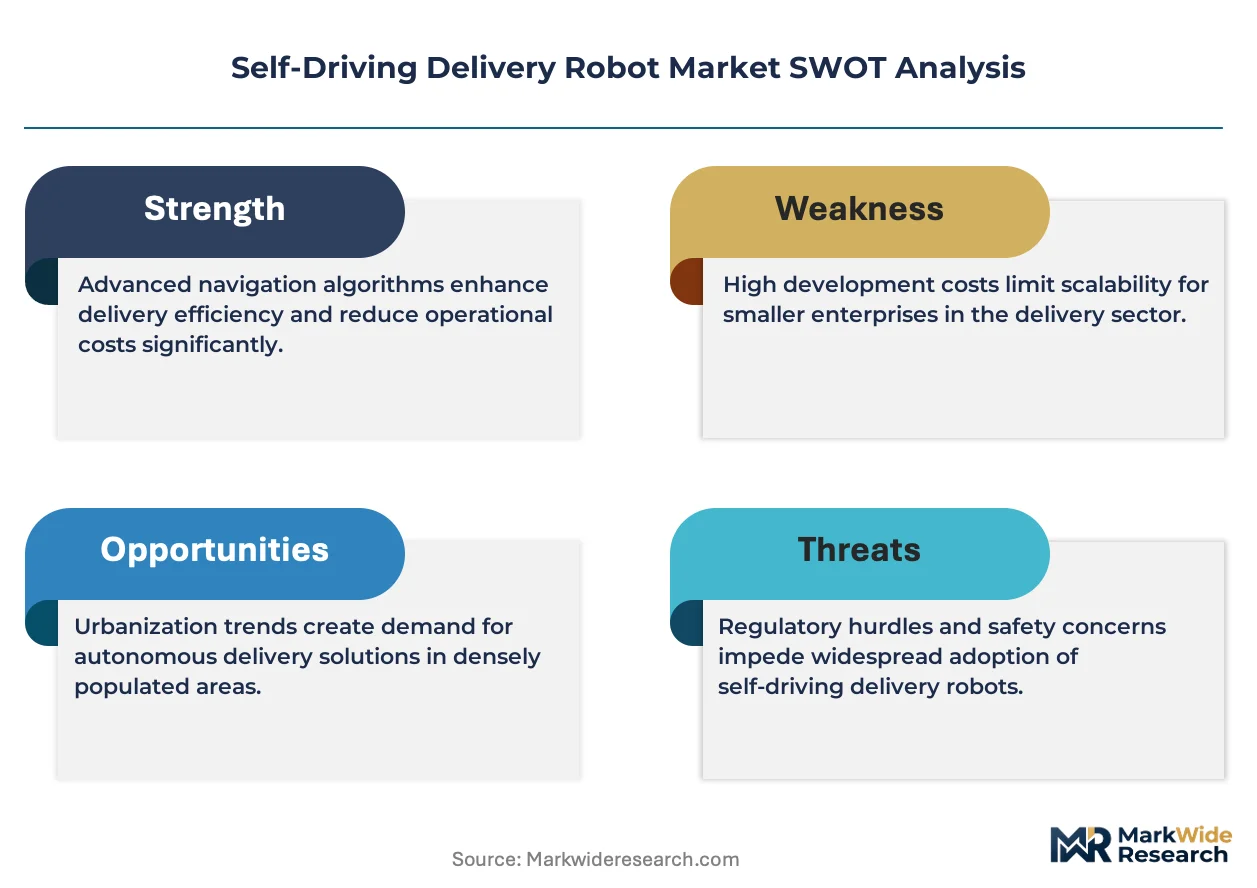
Regulatory fragmentation between municipal sidewalk ordinances and national autonomous vehicle frameworks is forcing operators to navigate patchwork compliance environments while scaling fleet deployments.
Growth Catalysts
- EU AI Act risk-classification framework:The regulation provides clarity on algorithmic decision-making standards, reducing legal uncertainty for operators deploying automated routing systems across European cities.
- Quick-commerce platform expansion:Ultra-fast grocery delivery services are integrating robot fleets into 15-minute fulfillment networks, creating sustained demand for high-frequency last-mile automation.
- LiDAR sensor cost compression:Manufacturing scale in automotive supply chains is driving down perception hardware expenses, improving unit economics for sidewalk and roadway robot deployments.
Market Restraints
- Lithium-ion battery supply concentration:Cathode material processing and cell manufacturing cluster in China, exposing fleet operators to geopolitical supply disruptions and input cost volatility.
- NHTSA low-speed exemption delays:Street-operating robots face prolonged federal safety review timelines, constraining deployment velocity in suburban roadway environments.
- Manual last-mile labor substitution:Gig economy delivery networks maintain cost advantages in low-density zones, limiting robot viability outside concentrated urban corridors.
Strategic Opportunities
- Hospital and hotel indoor logistics:Controlled-environment deployments in healthcare and hospitality facilities offer margin-rich applications with minimal regulatory friction.
- 5G-V2X communication convergence:Integration of cellular vehicle-to-everything networks with edge computing infrastructure enables real-time fleet coordination and remote intervention capabilities.
- Japan METI autonomous mobility incentives:National funding programs for robotics testing zones create favorable conditions for pilot expansion in dense Tokyo and Osaka districts.
Industry Challenges
- Autonomy software talent scarcity:Computer vision and sensor fusion engineering expertise concentrates at technology companies, constraining recruitment for fleet operators.
- Municipal permitting heterogeneity:Cities like San Francisco, Phoenix, and Austin maintain divergent insurance mandates and sidewalk speed limits, multiplying compliance overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Self-Driving Delivery Robot Market |
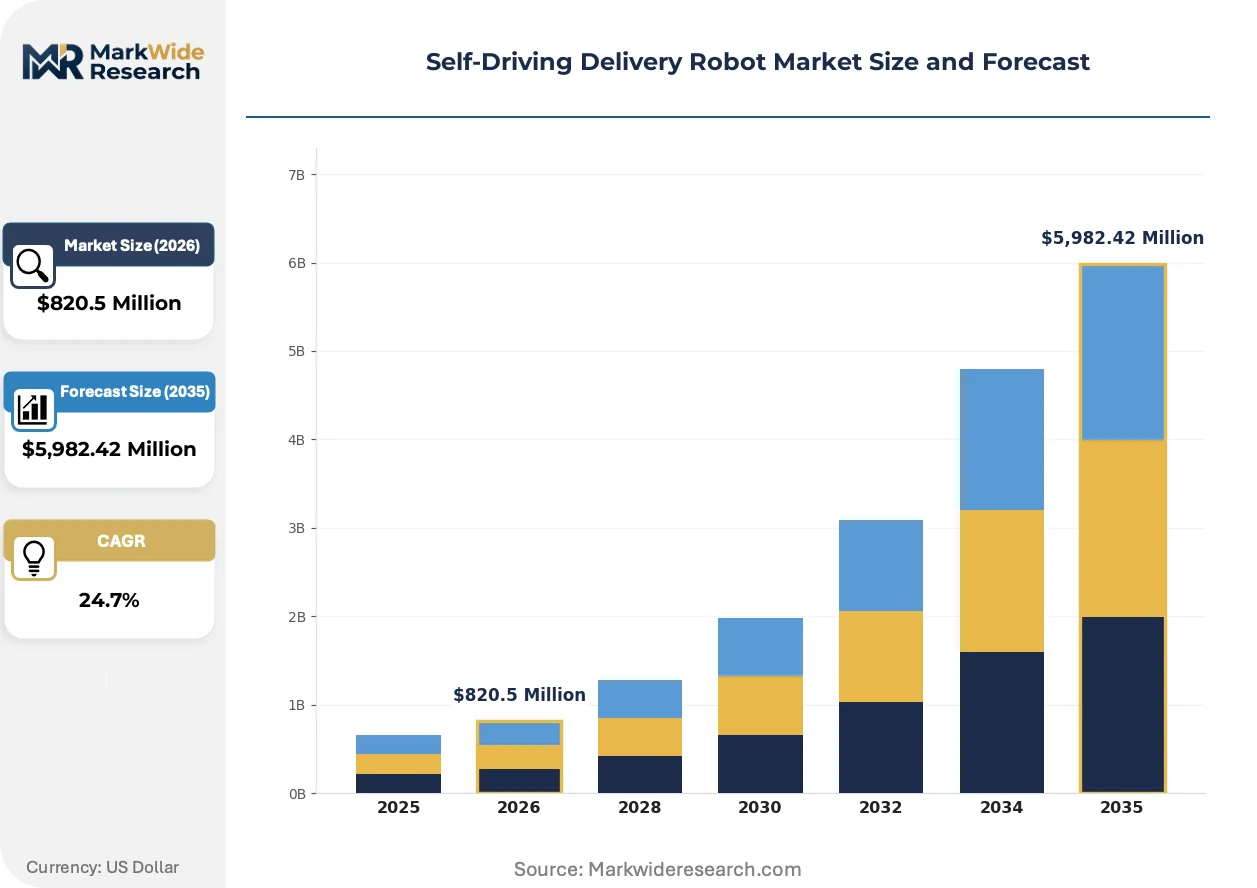
| Market Size in 2026 | $820.5 Million |
| Market Size in 2035 | $5,982.42 Million |
| CAGR (2026 – 2036) | 24.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Indoor Robots, Outdoor Robots, Autonomous Drones, Delivery Robots Technology: Computer Vision, LiDAR, GPS Navigation, Machine Learning End User: E-Commerce, Food Delivery Services, Logistics Providers, Retailers Deployment Model: On-Premise, Cloud-Based, Hybrid, Remote Control |
| Companies Covered | Starship Technologies, Nuro, Inc., JD.com, Inc., Serve Robotics Inc., Kiwibot, Ottonomy.IO, Relay Robotics, Inc., Panasonic Holdings Corporation, Meituan, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Self-Driving Delivery Robot Market Trends and Innovations
Machine learning training pipelines and edge computing architectures are compressing development cycles for navigation systems while regulatory bodies race to establish safety benchmarks.
Sensor fusion architectures are unifying LiDAR point clouds, camera feeds, and ultrasonic data into single perception models. Campus logistics operators and quick-commerce platforms are adopting these integrated systems fastest. This convergence is unifying previously separate hardware procurement decisions into consolidated vendor relationships.
The EU AI Act imposes conformity assessment requirements on automated decision systems governing delivery routing and obstacle avoidance. Industrial consequence includes mandatory documentation of training data provenance and algorithmic bias testing. Street-operating robot categories face the steepest compliance burdens, prompting operators to establish dedicated regulatory affairs functions in Brussels.
Buyer concentration among quick-commerce platforms is compressing vendor negotiation cycles and demanding outcome-based fleet performance guarantees. Traditional equipment purchasing models are yielding to robot-as-a-service contracts with uptime commitments. California and Texas represent the most advanced markets for this contractual evolution, reflecting the concentration of pilot program operators in those states.
Self-Driving Delivery Robot Market Segmentation
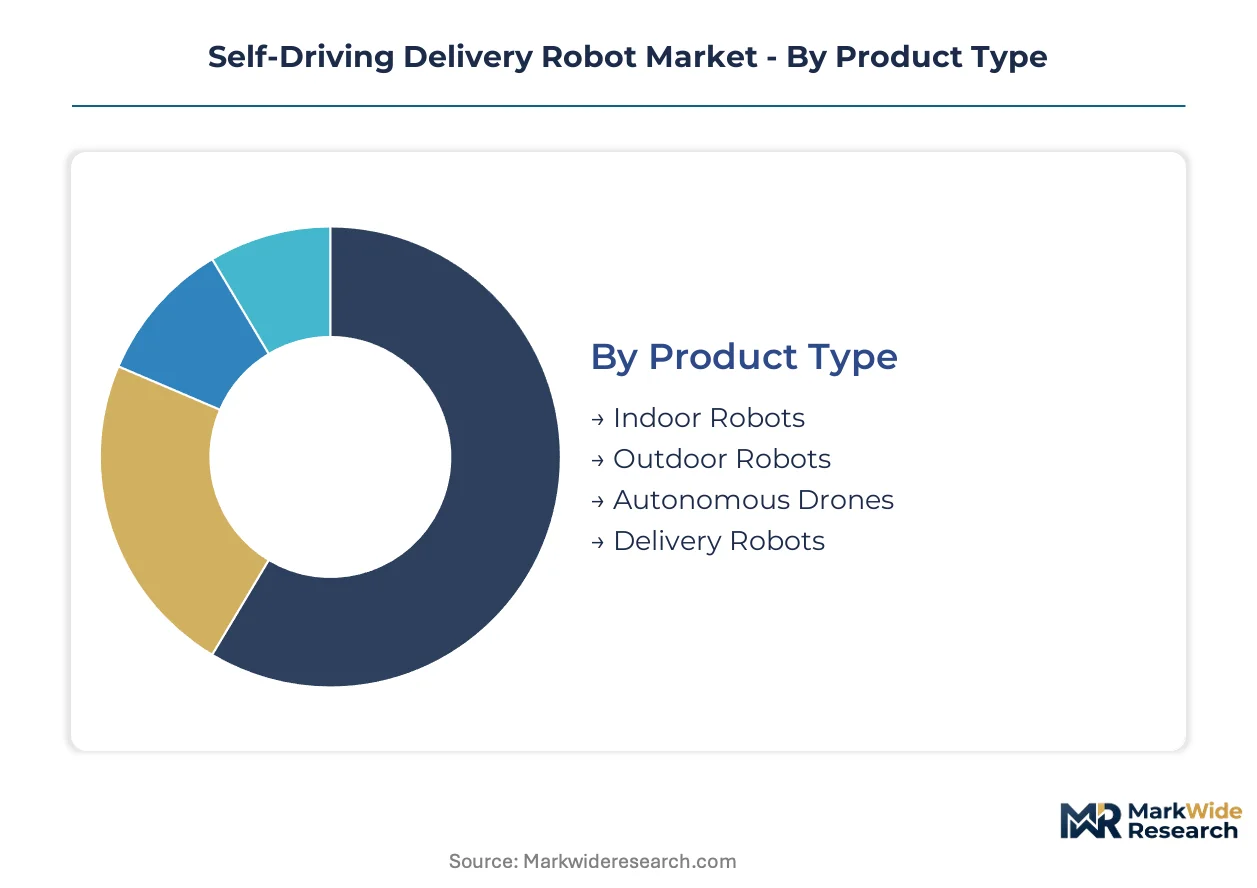
Segmentation in the Self-Driving Delivery Robot Market reveals how technical specifications, operational environments, and buyer economics fragment procurement patterns across the value chain. Operators must align hardware configurations with specific regulatory constraints and fulfillment density requirements.
Product Type:
Speed capabilities and environmental exposure define the product architecture choices facing fleet operators and facility managers.
- Outdoor Robots:These units operate on sidewalks and low-speed roadways at speeds up to 25 km/h, utilizing weather-sealed sensor housings and all-terrain wheel configurations. Demand concentrates in California, Texas, and Arizona where NHTSA low-speed exemptions and municipal pilot programs have cleared regulatory pathways for suburban and urban last-mile substitution.
- Indoor Robots:Designed for controlled environments with flat flooring and minimal navigation complexity, these systems prioritize payload capacity over environmental ruggedness. Healthcare facilities and hospitality operators in Japan and Germany represent the most active procurement segments, driven by labor cost pressures and 24-hour operational requirements.
- Autonomous Drones:Aerial delivery systems bypass ground infrastructure constraints entirely, though regulatory frameworks from the FAA and EASA limit commercial deployment to specific corridors and altitude bands.
- Delivery Robots:General-purpose ground-based units span both indoor and outdoor applications through modular sensor packages and interchangeable wheel systems.
Outdoor robots lead on scale; indoor robots lead on momentum.
Technology:
Perception and decision-making capabilities determine competitive differentiation and unit cost structures across vendor portfolios.
- LiDAR:Point-cloud generation enables centimeter-precision obstacle detection in variable lighting conditions. Automotive supply chain scale is compressing sensor costs, improving unit economics for fleet operators deploying neighborhood-scale coverage in Phoenix and Austin.
- Machine Learning:Neural network training on diverse sidewalk geometries and traffic behaviors enables adaptive navigation without explicit mapping. Quick-commerce platforms in South Korea and Singapore are adopting these capabilities fastest, driven by high-frequency fulfillment demands and dense urban topology.
- Computer Vision:Camera-based perception systems offer lower hardware costs but require substantial training data to achieve reliability across weather conditions.
- GPS Navigation:Satellite positioning provides coarse localization for route planning, though urban canyon effects limit standalone utility in dense metropolitan cores.
LiDAR dominates current procurement volumes; machine learning commands the steepest expansion trajectory.
End User:
Buyer concentration patterns reshape contract structures and fleet performance requirements across commercial segments.
- Food Delivery Services:Ultra-fast grocery and meal platforms require 15-minute fulfillment radii with 99.9% uptime guarantees. These operators in California and Texas are driving robot-as-a-service contract adoption, replacing capital expenditure models with outcome-based fleet leasing.
- E-Commerce:Integrated logistics networks prioritize captive robot deployment within owned fulfillment infrastructure. JD.com's controlled deployment across Chinese urban districts exemplifies this vertical integration strategy.
- Logistics Providers:Third-party carriers seek multi-tenant fleet configurations serving heterogeneous client requirements.
- Retailers:Brick-and-mortar operators deploy robots for curbside pickup and micro-fulfillment from store-based inventory.
Food delivery services anchor current demand; e-commerce platforms are gaining share fastest.
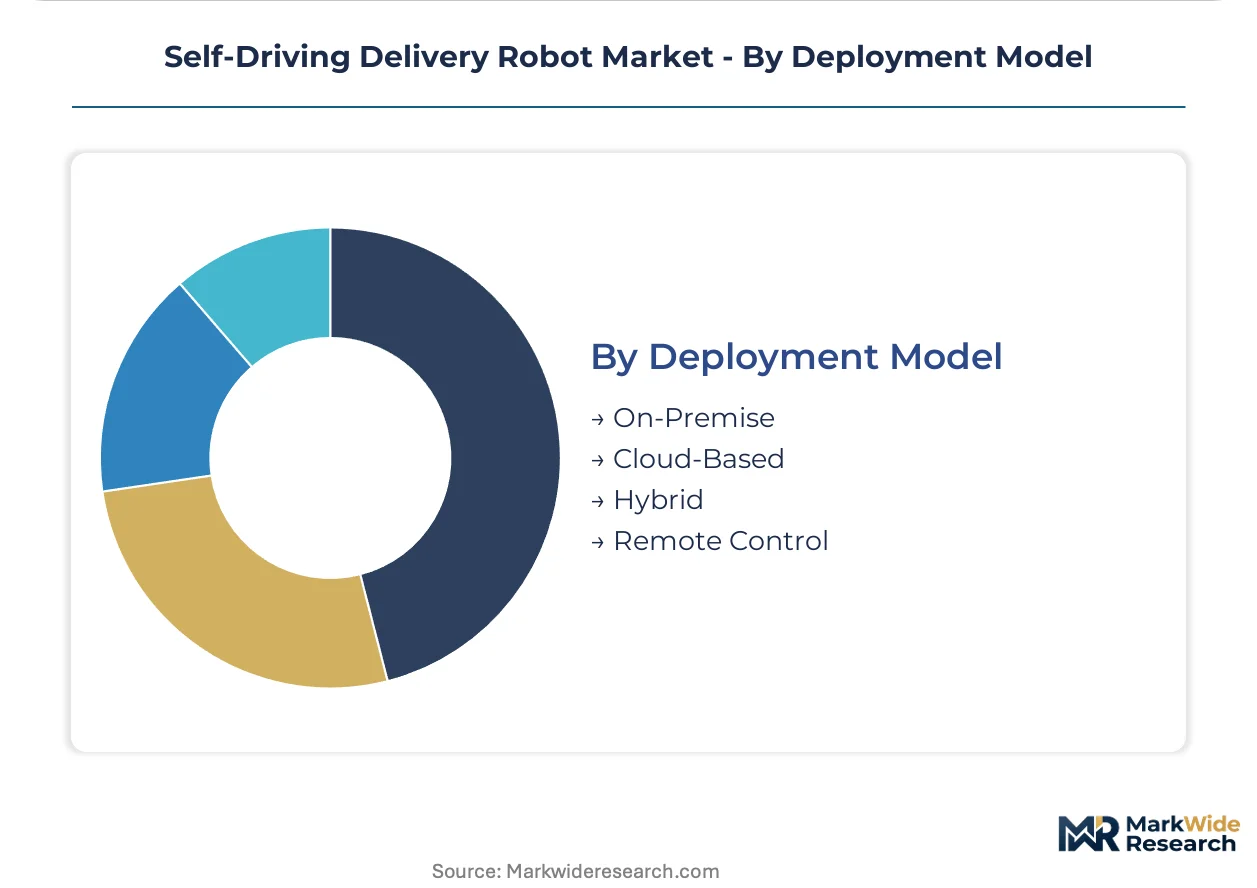
Deployment Model:
Compute architecture choices balance latency requirements against capital intensity and regulatory compliance burdens.
- Cloud-Based:Centralized processing enables fleet-wide model updates and real-time traffic integration, though wireless dependency creates vulnerability in tunnel and basement delivery scenarios. European operators under EU AI Act requirements favor this architecture for audit trail centralization and algorithmic bias documentation.
- On-Premise:Edge computing within the robot chassis eliminates connectivity dependencies and reduces latency for obstacle avoidance decisions. Hospital and hotel operators in Japan prioritize this model for data sovereignty and operational continuity.
- Hybrid:Split architectures process safety-critical functions locally while delegating route optimization to cloud resources.
- Remote Control:Teleoperation backup systems enable human intervention during edge-case navigation failures, required by municipal ordinances in San Francisco and Austin.
Cloud-based systems lead on scale; on-premise configurations are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States maintains regulatory momentum through municipal pilot programs while Germany enforces stricter conformity assessments under EU AI Act frameworks. Deployment density diverges sharply between permissive state-level jurisdictions and cautious national regulators.
United States
Quick-commerce platforms and campus logistics operators drive fleet procurement across California, Texas, and Arizona. The National Highway Traffic Safety Administration evaluates street-operating vehicles under evolving low-speed autonomous vehicle exemptions. Phoenix and Austin host the densest operational clusters where municipal ordinances permit sidewalk and roadway robot coexistence.
China
Integrated e-commerce infrastructure enables captive robot deployment within owned fulfillment networks across urban districts. The Ministry of Industry and Information Technology coordinates robotics testing standards through national GB frameworks. Shenzhen and Beijing concentrate development activity where platform operators control end-to-end logistics automation.
Germany
Industrial automation expertise translates into precision engineering for controlled-environment hospital and hotel logistics. The EU AI Act imposes mandatory conformity assessments on automated decision systems governing delivery routing. Munich and Berlin anchor pilot programs where operators establish dedicated regulatory affairs functions.
Japan
Aging demographics and labor shortages accelerate indoor robot adoption within healthcare and hospitality facilities. The Ministry of Economy, Trade and Industry funds autonomous mobility testing zones through national incentive programs. Tokyo and Osaka districts concentrate deployment where dense urban topology favors high-frequency fulfillment automation.
South Korea
Ultra-fast grocery delivery services integrate robot fleets into 15-minute fulfillment networks across metropolitan cores. The country's national telecommunications regulator coordinates 5G-V2X spectrum allocation for real-time fleet coordination. Seoul Capital Area hosts the most advanced machine learning training pipelines on diverse sidewalk geometries.
Self-Driving Delivery Robot Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across hardware fabrication, autonomy software, and fleet operation layers. The vendor base stratifies between integrated technology platforms, component suppliers, and logistics operators running captive deployments. Three archetypes dominate: e-commerce platforms with vertical logistics control, pure-play robot manufacturers selling to third-party fleets, and technology licensors supplying perception systems. Competitive moves concentrate on strategic partnerships between autonomy software developers and fleet operators, plus geographic expansion into permissive regulatory jurisdictions.
Within the pure-play specialist tier, Starship Technologies and Nuro, Inc. exemplify divergent architectural bets on sidewalk versus roadway access. JD.com, Inc. anchors the integrated platform archetype through captive deployment within owned fulfillment infrastructure. These three occupy positions that illustrate how vendor strategy fragments across regulatory tolerance, capital intensity, and operational scale vectors.
| Leading Market Players |
|---|
| Starship Technologies |
| Nuro, Inc. |
| JD.com, Inc. |
| Serve Robotics Inc. |
| Kiwibot |
| Ottonomy.IO |
| Relay Robotics, Inc. |
| Panasonic Holdings Corporation |
| Meituan |
| Others |
Pricing and Supply Chain Analysis
Automotive-grade LiDAR manufacturing scale in South Korea and China is compressing perception hardware costs while simultaneously concentrating supplier power among tier-one sensor vendors. This dual effect reshapes fleet operator procurement economics and vendor negotiation leverage across sidewalk and roadway deployment categories.
Pricing Analysis
Capacity additions in China and South Korea are reshaping price floors for LiDAR and compute modules, enabling robot-as-a-service providers to offer uptime-guaranteed contracts at lower per-drop rates. Pricing stratifies across premium sensor configurations, standard mid-tier packages, and economy-grade computer vision alternatives. Cost compression in the standard tier is intensifying because automotive supply chain spillover is flooding the market with surplus 905nm LiDAR units. Quick-commerce platforms exhibit the highest price sensitivity due to thin per-order margins, while hospital logistics operators accept premium pricing for zero-failure reliability commitments.
Supply Chain Analysis
Direct-to-fleet channels handle hyperscale buyer demand from quick-commerce platforms, while component distributors serve smaller campus operators and indoor facility managers. Cathode material processing clusters in China, cell manufacturing in South Korea, and semiconductor fabrication in Taiwan anchor the battery and compute supply base. Lithium carbonate and nickel sulfate feedstock dependencies expose operators to commodity price volatility. Single-source vulnerability in solid-state LiDAR emitters presents the most acute structural risk. Distribution runs through tier-one automotive electronics distributors with established NHTSA compliance documentation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU AI Act conformity assessment deadline functions as a regulatory compounder, accelerating procurement decisions among European fleet operators seeking deployment certainty before mandatory documentation requirements take effect.
For Market Incumbents: Cement regulatory affairs capabilities in Brussels and Washington to preempt NHTSA exemption delays and EU algorithmic bias audit requirements. Starship Technologies and Nuro must deepen backward integration into perception hardware to defend margins against automotive supplier margin capture. Priority investment in 5G-V2X edge computing partnerships secures latency advantages for remote intervention capabilities.
For New Entrants and Emerging Players: Campus logistics operators represent the most penetrable channel partner type for indoor robot specialists seeking recurring revenue without street-level regulatory friction. Target hospital networks in Japan and Germany where labor shortages and 24-hour operational requirements create urgent demand. White-space opportunities concentrate in hybrid deployment models combining on-premise safety processing with cloud-based fleet optimization.
For Investors and Strategic Acquirers: Valuations sit cheapest among pure-play autonomy software vendors lacking captive fleet deployments. Long-term viability hinges on five-to-ten-year regulatory clarity trajectories across municipal, national, and supranational jurisdictions. Acquisition targets should demonstrate proven navigation performance across three-plus sidewalk geometry categories. The signal to watch is NHTSA low-speed exemption velocity as an inflection indicator for suburban roadway robot scalability.
| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Compliance Certification | Mandatory conformity assessments in Brussels unlock European deployment corridors for street-operating robots. |
| LiDAR Supplier Partnership | Automotive-tier sensor agreements secure volume pricing and NHTSA documentation packages for fleet scale. |
| 5G-V2X Infrastructure Integration | Cellular vehicle-to-everything networks enable real-time coordination in Phoenix and Austin pilot zones. |
| Hospital Logistics Pilot Expansion | Controlled-environment deployments in Tokyo and Munich generate margin-rich reference contracts. |
| Robot-as-a-Service Platform Launch | Uptime-guaranteed contracts replace capital expenditure models for California quick-commerce platforms. |
Research Methodology
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combining structured interviews with fleet operations directors, autonomy software engineers, municipal permitting officers, and hospital logistics procurement managers. Secondary validation draws from NHTSA exemption filings, EU AI Act implementation guidance, FCC spectrum allocation records, and automotive supplier SEC disclosures. Bottom-up unit deployment estimates triangulate against top-down market sizing derived from quick-commerce platform fleet announcements and venture funding disclosures.
Granularity-level modeling extends to robot category, sensor technology tier, deployment architecture, and end-use vertical across the projection horizon. Segment-level CAGRs derive from adoption curve analysis calibrated against regulatory milestone timelines and infrastructure readiness indicators. Forecast inputs incorporate LiDAR cost decline trajectories, battery chemistry substitution patterns, and municipal permitting velocity differentials between Phoenix, Austin, and San Francisco.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to NHTSA exemption velocity, EU AI Act enforcement consistency, and lithium-ion supply chain geopolitical disruption. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
Agricultural Robots Market
Robotics and Automation
Spain Cloud Robotics Market
Robotics and Automation
Household Robots Market
Robotics and Automation
Gantry (Cartesian) Robot Market
Robotics and Automation
Southeast Asia Industrial and Service Robot Market
Robotics and Automation
Clean Room Robot Market
Robotics and Automation
Service Robotics Market
Robotics and Automation
Telepresence Robotics Market
Robotics and Automation
Global Automated Parcel Delivery Terminals Market
Robotics and Automation
Global Mobile Robots Market
Robotics and Automation
Healthcare Mobile Robots Market
Robotics and Automation
Cognitive Robotics Market
Robotics and Automation
Industrial Robots Market
Robotics and Automation
Top Robotics Market
Robotics and Automation
Robotics Technology Market
Robotics and Automation
Smart Worker Market