
 Canada Cloud Robotics Market | 2026-2036
Canada Cloud Robotics Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Cloud Robotics Market Insights
The Canada cloud robotics landscape is restructuring around a sharp split between premium AI-native platforms and commodity hardware-as-a-service offerings. C2RO leverages cloud-native architecture for multi-robot orchestration in industrial settings. V3 Smart Technologies anchors its position through edge-cloud hybrid systems serving logistics clients. Mecademic specializes in precision micro-robotics for laboratory automation, competing on repeatability metrics rather than scale.
Canada cloud robotics denotes distributed robotic systems where computation, data storage, and AI model training occur on remote servers rather than onboard controllers, relying on sub-50ms latency links and 5G or fiber connectivity for real-time task execution. The primary purpose centers on enabling smaller enterprises to access advanced autonomy without capital-intensive edge hardware investments. Service robots dominate current deployment volumes across Canadian healthcare and retail settings. Machine learning algorithms represent the fastest-expanding technology layer as natural language processing capabilities mature for human-robot collaboration. Hybrid cloud deployments capture disproportionate margin pools by balancing data sovereignty requirements with computational elasticity.
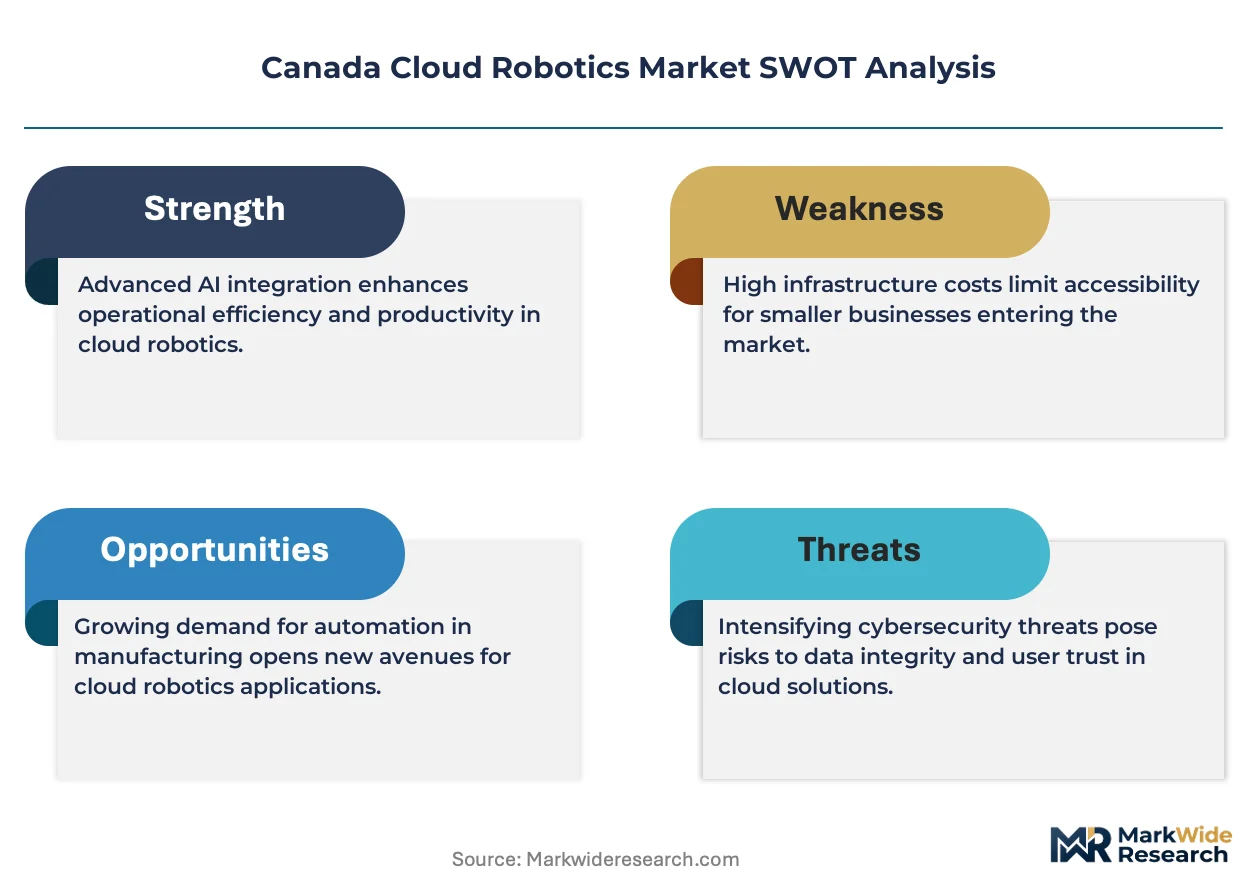
Health Canada and the Canadian Standards Association shape device approval pathways and operational safety benchmarks for cloud-connected robots in clinical environments. The Personal Information Protection and Electronic Documents Act constrains cross-border data flows, pushing vendors toward domestic cloud infrastructure partnerships. Stakeholders must weigh federal AI governance proposals against provincial procurement preferences when scaling deployment footprints.
Market Dynamics
The Canada cloud robotics market is reconfiguring around latency-sensitive edge-cloud partitioning, where Health Canada's Medical Devices Directorate approval timelines for clinical robot deployments now dictate vendor architecture decisions and partnership strategies with domestic data center operators.
Growth Catalysts
- Ontario's automation clusters:The Toronto-Waterloo technology corridor concentrates venture funding and talent pipelines, drawing cloud robotics vendors seeking proximity to manufacturing and healthcare anchor customers.
- PIPEDA data residency requirements:The Personal Information Protection and Electronic Documents Act constrains cross-border data flows, compelling infrastructure investment in Canadian cloud regions and creating captive demand for domestic service providers.
- 5G private network deployment:Telecommunications carriers are rolling out dedicated industrial spectrum in Alberta's oil sands and British Columbia's port logistics zones, enabling sub-20ms control loops for remote robotic operation.
Market Restraints
- Compute hardware cost volatility:GPU and specialized AI accelerator pricing swings compress margins for cloud robotics platform operators dependent on NVIDIA and AMD supply allocations.
- Single-province vendor concentration:Quebec's limited cloud infrastructure relative to Ontario creates geographic dependency risk for national deployment footprints requiring low-latency coverage.
- Health Canada certification timelines:The Medical Devices Directorate's 18-24 month approval cycles for Class II and III robotic systems delay revenue recognition and strain startup runway financing.
Strategic Opportunities
- Atlantic Canada underpenetration:Nova Scotia and New Brunswick harbor significant manufacturing and seafood processing automation gaps with limited incumbent cloud robotics presence.
- Federal AI governance tailwinds:Proposed Algorithmic Impact Assessment frameworks may mandate cloud-based audit trails, creating compliance-driven demand for domestic platform vendors.
- Digital twin convergence:Integration of physics simulation engines with cloud robotics control planes enables predictive scenario testing for resource extraction operations in remote northern territories.
Industry Challenges
- Robotics-software hybrid talent scarcity:Canadian universities produce limited graduates with simultaneous expertise in distributed systems architecture and real-time control theory.
- Legacy manufacturing system integration:Brownfield industrial facilities in the Prairie provinces operate decades-old SCADA infrastructure incompatible with cloud-native robot middleware without expensive gateway retrofits.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Cloud Robotics Market |
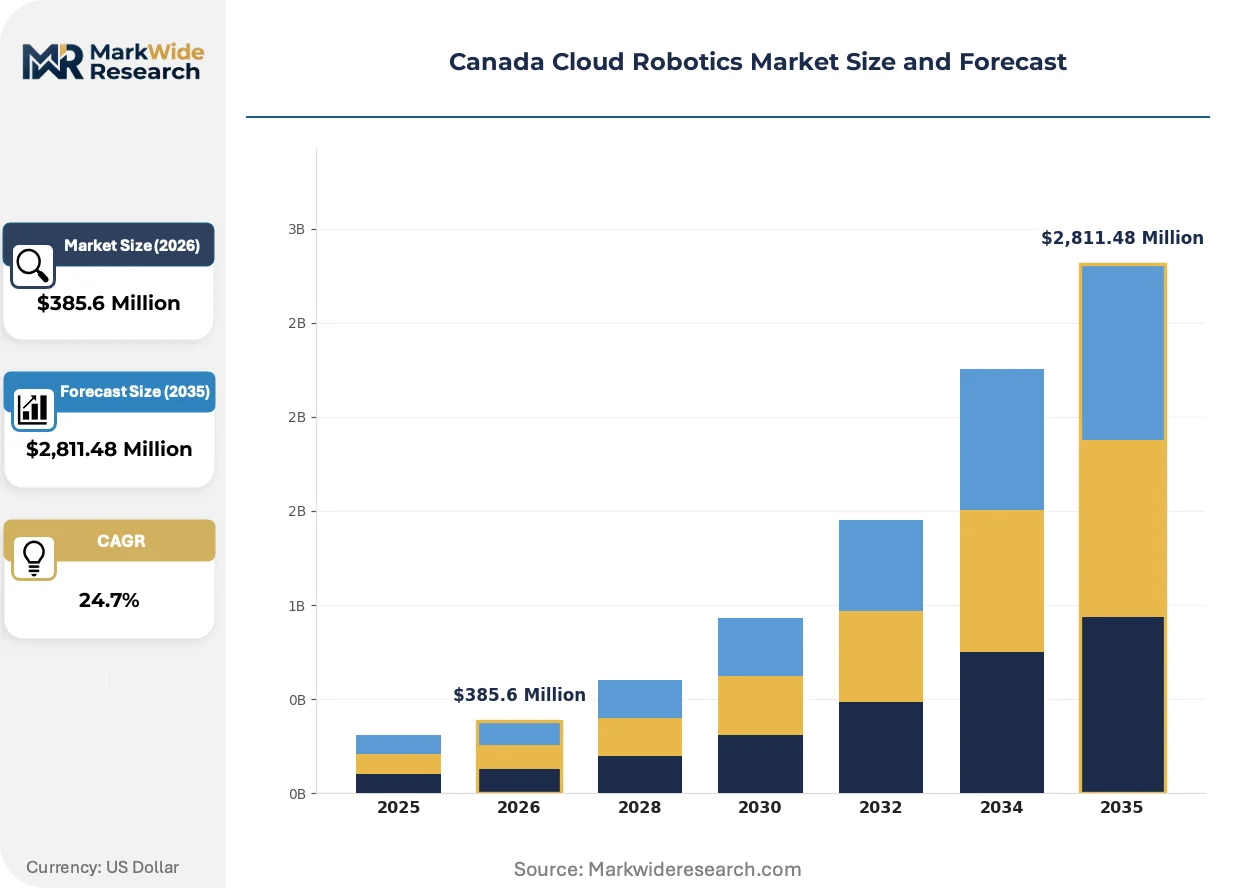
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $2,811.48 Million |
| CAGR (2026 – 2036) | 24.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Service Robots, Industrial Robots, Medical Robots, Agricultural Robots Technology: Machine Learning, Natural Language Processing, Computer Vision, AI Algorithms End User: Manufacturing, Healthcare, Agriculture, Retail Deployment: Public Cloud, Private Cloud, Hybrid Cloud, Edge Computing |
| Companies Covered | C2RO, V3 Smart Technologies, Mecademic, Haply Robotics, 4AG Robotics, Point.Laz, Upside Robotics, Nexera Robotics, Swap Robotics, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Cloud Robotics Market Trends and Innovations
Canadian cloud robotics vendors are pivoting from monolithic platform offerings toward composable service layers, responding to buyer demand for selective capability procurement rather than full-stack dependency.
Containerized robot operating system (ROS) deployments are modularizing previously integrated perception-planning-control stacks. Automotive parts suppliers in Windsor and Oshawa are adopting these decomposed architectures fastest, purchasing only navigation or manipulation modules as needed. This modularizing trend compresses vendor lock-in and accelerates multi-supplier fleet heterogeneity.
Health Canada's anticipated alignment with the EU AI Act's risk classification framework is reshaping clinical robot validation protocols. Manufacturers must now document training data provenance and model drift monitoring for cloud-hosted medical algorithms. Surgical robotics developers in Toronto are responding by establishing dedicated Canadian cloud tenancy with domestic audit logging.
Capital equipment purchasing committees now favor operational expenditure models over upfront robot acquisition. Healthcare systems in Calgary and Edmonton are leasing cloud-connected service robots through equipment-as-a-service contracts with performance-based monthly billing. This consumption-pattern shift transfers obsolescence risk to vendors and demands residual value forecasting capabilities most domestic players lack.
Canada Cloud Robotics Market Segmentation
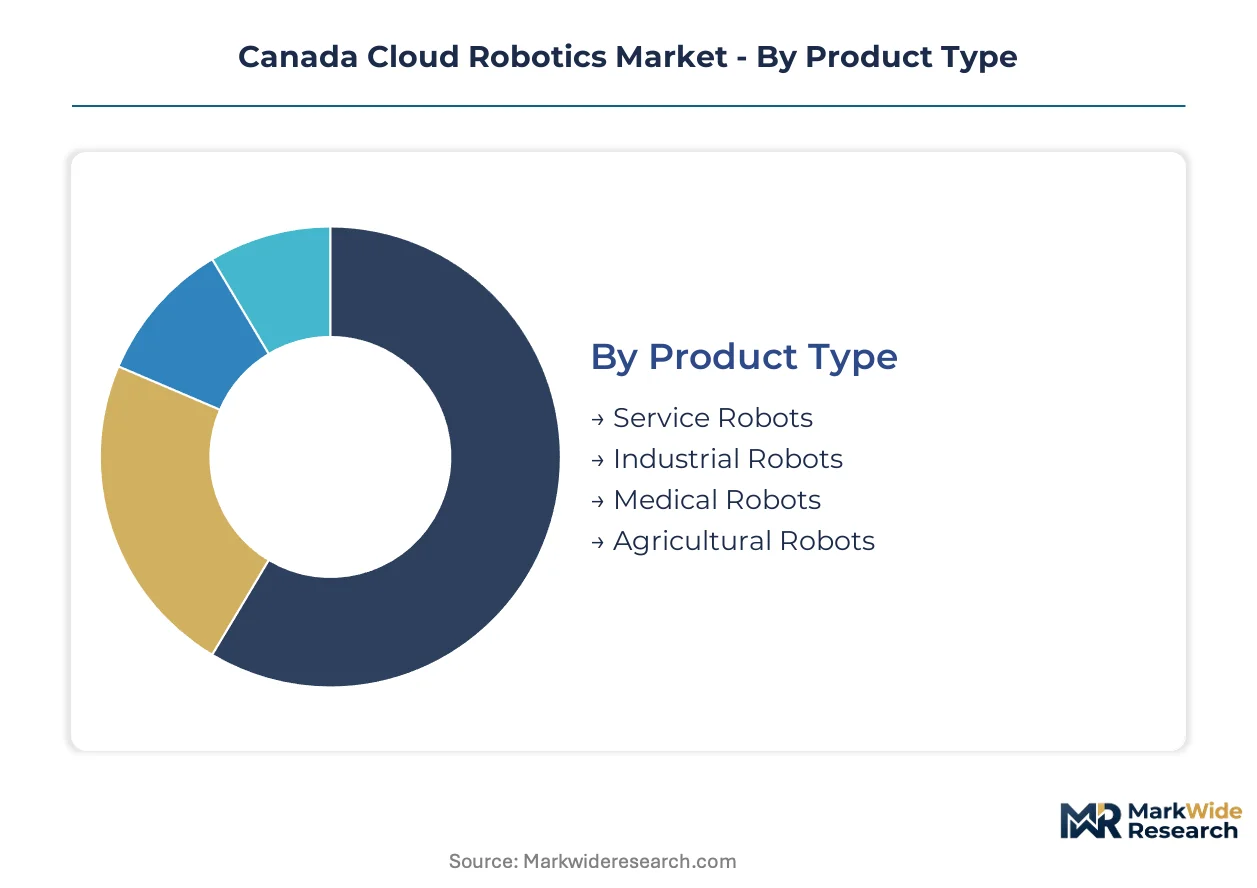
Cloud robotics buyers in Canada segment procurement decisions across four critical dimensions: product capability requirements, underlying AI technology stack, operational deployment constraints, and end-use application environment. Each segmentation axis reveals distinct margin pools, regulatory exposure, and infrastructure partnership requirements that vendors must navigate.
Product Type:
Capital intensity and operational complexity drive buyer selection across robot categories, with healthcare and industrial applications demanding divergent reliability certifications.
- Service Robots:Mobile platforms integrate navigation, manipulation, and human-interaction modules for facility management and customer-facing roles. Healthcare systems in Calgary and Edmonton lease these units through equipment-as-a-service contracts, transferring obsolescence risk to vendors while demanding 99.9% uptime guarantees.
- Industrial Robots:Articulated arms and collaborative cobots execute material handling, welding, and assembly tasks with cloud-hosted path planning. Ontario's automotive parts suppliers in Windsor and Oshawa represent the densest demand concentration, purchasing decomposed ROS modules rather than integrated platforms to preserve multi-vendor flexibility.
- Medical Robots:Surgical and diagnostic systems require Health Canada Medical Devices Directorate approval cycles spanning 18-24 months. Toronto-based developers establish dedicated Canadian cloud tenancy with domestic audit logging to satisfy anticipated EU AI Act alignment requirements.
- Agricultural Robots:Precision planting, harvesting, and monitoring platforms operate across Prairie province grain operations and British Columbia vineyard estates. Connectivity limitations in remote farmland push deployments toward edge-cloud hybrid architectures.
Industrial robots lead on scale; service robots lead on momentum.
Technology:
AI capability layering determines competitive differentiation, with natural language and vision systems commanding premium pricing over foundational machine learning infrastructure.
- Machine Learning:Predictive maintenance algorithms and fleet optimization models train on aggregated operational data across multi-tenant cloud environments. Canadian vendors compete on model accuracy metrics and data sovereignty compliance rather than raw computational scale.
- Natural Language Processing:Voice command interfaces and semantic understanding engines enable human-robot collaboration in healthcare and retail settings. This capability layer is expanding most quickly as large language model integration matures for real-time task instruction.
- Computer Vision:Object detection, semantic segmentation, and spatial mapping algorithms process sensor feeds for navigation and manipulation. Logistics clients in British Columbia port zones prioritize sub-50ms inference latency for safety-critical obstacle avoidance.
- AI Algorithms:Proprietary optimization routines and control policies differentiate vendor platforms at the application layer. Procurement committees increasingly demand transparency into training data provenance and model drift monitoring protocols.
Machine learning anchors current deployment volumes; natural language processing demonstrates the steepest expansion trajectory.
End User:
Industry-specific regulatory exposure and legacy system integration burdens shape customer willingness-to-pay for cloud-native versus hybrid deployment options.
- Manufacturing:Brownfield facilities across the Prairie provinces operate decades-old SCADA infrastructure requiring expensive gateway retrofits for cloud connectivity. Tier-1 suppliers near Toronto-Waterloo adopt fastest due to greenfield automation investments and venture-backed capital availability.
- Healthcare:Hospitals and long-term care facilities deploy service robots for medication delivery, patient monitoring, and sanitation tasks. PIPEDA data residency requirements compel infrastructure investment in Canadian cloud regions, creating captive demand for domestic platform partnerships.
- Agriculture:Grain elevators, dairy operations, and greenhouse facilities automate labor-intensive seasonal tasks. Atlantic Canada harbors significant underpenetration in seafood processing automation with limited incumbent vendor presence.
- Retail:Inventory management, customer assistance, and fulfillment center robots operate across grocery chains and e-commerce distribution networks. Consumption-based billing models transfer capital risk to vendors while demanding residual value forecasting capabilities.
Manufacturing captures the largest revenue pool; healthcare exhibits the most stringent compliance-driven vendor selection criteria.
Deployment:
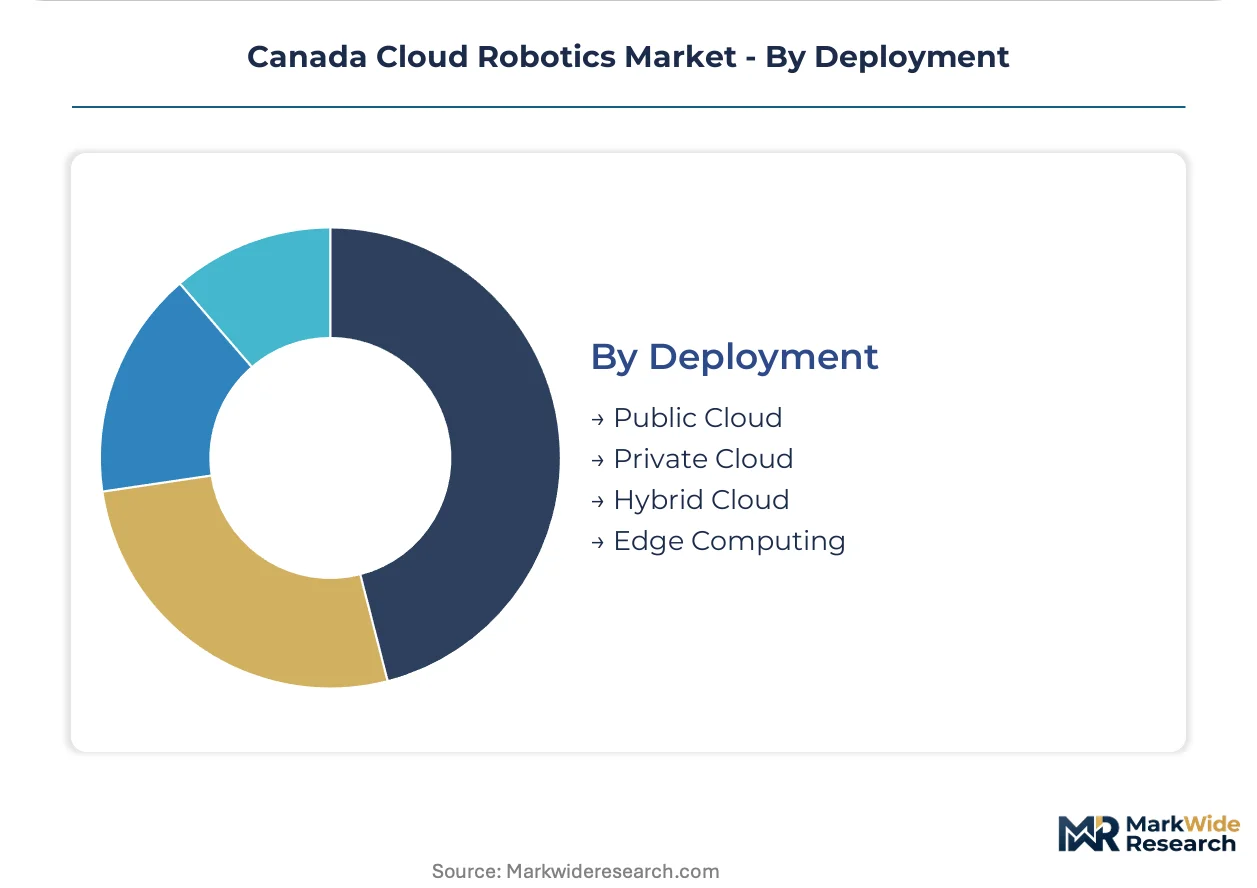
Latency sensitivity and data sovereignty requirements partition the market between public cloud elasticity and controlled private infrastructure.
- Public Cloud:Shared-tenant environments offer computational elasticity for model training and non-real-time analytics. PIPEDA constraints on cross-border data flows limit applicability for personal information processing workloads.
- Private Cloud:Dedicated infrastructure satisfies Health Canada audit requirements and financial services compliance mandates. Higher capital commitments restrict adoption to enterprise-scale buyers with internal platform engineering capabilities.
- Hybrid Cloud:Edge-cloud partitioning balances real-time control loop execution with centralized model refinement. This architecture captures disproportionate margin pools by addressing data sovereignty requirements without sacrificing computational scalability.
- Edge Computing:Onboard processing units execute time-critical perception and control tasks with cloud fallback for complex planning. 5G private network deployment in Alberta oil sands and BC port logistics enables sub-20ms control loops previously requiring full edge autonomy.
Hybrid cloud leads on margin capture; edge computing is gaining share fastest as telecommunications infrastructure matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ontario concentrates venture deployment while Alberta channels energy-sector automation spending, revealing how provincial industrial bases shape cloud robotics demand patterns across Canadian markets.
Ontario
The Toronto-Waterloo technology corridor anchors national cloud robotics development with dense automation clusters and venture funding pipelines. Health Canada's Medical Devices Directorate maintains its headquarters in Ottawa, streamlining regulatory consultation for surgical robotics developers. Windsor and Oshawa automotive suppliers purchase decomposed ROS modules for flexible manufacturing lines.
Quebec
Montreal's AI research institutes generate talent pipelines for cloud-native robotics engineering while provincial procurement favors French-language platform interfaces. The Commission d'accès à l'information du Québec enforces data localization mandates that complement federal PIPEDA constraints. Precision manufacturing in Quebec City and Sherbrooke drives demand for micro-robotics in laboratory automation settings.
Alberta
Oil sands operators deploy remote robotic inspection systems across Fort McMurray extraction sites with 5G private network coverage enabling sub-20ms control loops. The Alberta Energy Regulator mandates continuous monitoring protocols that cloud-connected systems satisfy more cost-effectively than manned rotations. Calgary healthcare systems lease service robots through equipment-as-a-service contracts with performance-based billing structures.
British Columbia
Vancouver port logistics zones represent Canada's densest concentration of edge-cloud hybrid deployments for container handling automation. The British Columbia Personal Information Protection Act layers additional provincial constraints atop PIPEDA for cross-border data flows. Okanagan vineyard estates test agricultural robotics for precision harvesting amid connectivity-challenged terrain.
Atlantic Canada
Nova Scotia and New Brunswick harbor significant underpenetration in seafood processing automation with limited incumbent vendor presence. The Atlantic Canada Opportunities Agency funds pilot programs for manufacturing modernization that reduce adoption barriers for cloud robotics platforms. Halifax emerging technology clusters attract remote-first robotics startups seeking lower operational costs than Ontario or Quebec.
Canada Cloud Robotics Market Competitive Landscape
Top-tier vendors anchor multi-robot orchestration platforms, while specialized micro-robotics developers occupy defensible niche positions. The vendor base stratifies across three tiers: cloud-native platform operators with industrial scale, edge-cloud hybrid specialists serving latency-sensitive applications, and precision hardware manufacturers competing on repeatability metrics. Strategic archetypes include infrastructure-anchored platforms, research-spinout precision specialists, and logistics-focused automation integrators. Competitive moves concentrate on domestic data center partnerships for PIPEDA compliance and modular service layer unbundling to reduce customer lock-in.
Within the cloud-native platform tier, C2RO exemplifies multi-robot orchestration architecture for industrial settings. V3 Smart Technologies occupies a position among edge-cloud hybrid specialists serving logistics clients with latency-optimized deployments. Mecademic represents the precision micro-robotics archetype, anchoring laboratory automation segments where repeatability specifications outweigh scale considerations. These three company structures illustrate how Canadian cloud robotics competition fragments across architectural approaches rather than consolidating around unified technology stacks.
| Leading Market Players |
|---|
| C2RO |
| V3 Smart Technologies |
| Mecademic |
| Haply Robotics |
| 4AG Robotics |
| Point.Laz |
| Upside Robotics |
| Nexera Robotics |
| Swap Robotics |
| Others |
Pricing and Supply Chain Analysis
GPU and specialized AI accelerator procurement costs cascade through cloud robotics platform tiers, compressing margins for vendors dependent on NVIDIA and AMD supply allocations while pushing buyers toward equipment-as-a-service models that transfer hardware obsolescence risk.
Pricing Analysis
Capacity additions in domestic Canadian cloud regions are reshaping price floors for PIPEDA-compliant deployments. Three-tier pricing structure across premium, standard, and economy levels differentiates vendors by Health Canada certification status and data residency guarantees. Pricing pressure stems from compute hardware cost volatility as GPU allocation constraints tighten vendor margins. Healthcare systems in Calgary and Edmonton exhibit highest price sensitivity due to equipment-as-a-service contract structures, while oil sands operators in Alberta demonstrate lowest sensitivity given operational expenditure preference for remote inspection systems.
Supply Chain Analysis
Cross-border freight costs for precision robotics components from Germany, Japan, and Taiwan elevate landed costs for Canadian integrators. The supply chain draws from Taiwanese semiconductor foundries, German precision actuator manufacturers, and Japanese sensor specialists for core subsystems. Single-source vulnerability concentrates in NVIDIA GPU allocations for cloud training workloads. Distribution runs through Toronto-Waterloo automation cluster distributors serving Ontario manufacturing anchor customers, with direct vendor relationships dominating healthcare and energy sector procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in Canadian cloud robotics hinges on modular service layer unbundling that reduces customer lock-in while capturing recurring revenue from software subscriptions, offsetting hardware margin compression.
For Market Incumbents: Cement multi-robot orchestration dominance by deepening edge-cloud hybrid infrastructure partnerships with domestic data center operators. Counter emerging modular ROS vendors by certifying decomposed service layers under Health Canada's anticipated EU AI Act alignment protocols. Prioritize backward integration into Canadian cloud tenancy operations to satisfy PIPEDA data residency mandates without third-party margin leakage.
For New Entrants and Emerging Players: Atlantic Canada seafood processing automation represents the most penetrable vertical given limited incumbent presence and federal pilot program funding. Nova Scotia manufacturing modernization gaps offer second-mover advantage without Ontario's talent competition intensity. Pursue equipment-as-a-service contract structures with performance-based billing to bypass capital equipment purchasing committee resistance.
For Investors and Strategic Acquirers: Consolidation pressure builds where edge-cloud hybrid specialists lack residual value forecasting capabilities for leased robotics fleets. Long-term viability favors vendors with domestic data center tenancy and Health Canada regulatory pathway expertise. Acquisition target archetype: precision micro-robotics developers with laboratory automation repeatability specifications. Monitor Health Canada Medical Devices Directorate approval timeline acceleration as inflection signal for clinical robotics revenue recognition.
| Strategic Initiative | Industry Significance |
|---|---|
| Domestic Cloud Tenancy Establishment | PIPEDA compliance creates captive demand for Canadian infrastructure partnerships with data center operators. |
| Modular ROS Service Unbundling | Decomposed navigation and manipulation modules reduce vendor lock-in for Windsor automotive suppliers. |
| Health Canada Certification Investment | Anticipated EU AI Act alignment mandates training data provenance documentation for surgical robotics. |
| 5G Private Network Partnership | Telecommunications carrier alliances enable sub-20ms control loops for Alberta oil sands remote operations. |
| Atlantic Canada Geographic Expansion | Nova Scotia and New Brunswick seafood processing gaps offer first-mover positioning with federal funding support. |
Research Methodology
Multiple input streams — primary interviews with cloud robotics platform executives, hospital biomedical engineers, and automotive plant automation directors; secondary validation through Health Canada Medical Devices Directorate filings, Canadian Standards Association safety benchmarks, and PIPEDA compliance documentation; plus customs data on robotics component imports — were reconciled through bottom-up deployment volume modeling and top-down venture funding triangulation.
Segment-level CAGRs across the analysis window were derived from reconciling vendor revenue disclosures, equipment-as-a-service contract values, and provincial procurement database records across product type, technology stack, deployment architecture, and end-use industry dimensions. Cloud infrastructure capacity expansion timelines and 5G private network rollout schedules informed connectivity-enabled adoption curve assumptions.
Underlying measurement precision varies by segment; Ontario manufacturing and Alberta energy deployments carry tighter precision than Atlantic Canada emerging verticals given data availability. Forecasts reflect assumptions about Health Canada regulatory timeline stability and telecommunications infrastructure investment continuity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
Deep Sea Robot Market
Robotics and Automation
High-Precision Truss Robot Market
Robotics and Automation
Europe Automated Guided Vehicle (AGV) Market
Robotics and Automation
Global Entertainment Robots Market
Robotics and Automation
Logistics Robots Market
Robotics and Automation
Healthcare Mobile Robots Market
Robotics and Automation
Biaxial Mobile Phone Stabilizer Market
Robotics and Automation
Human-Robot Collaborative Picking Optimization Platforms Market
Robotics and Automation
Automated Facade Contact Cleaning Robot Market
Robotics and Automation
Europe Robotics and Automation Actuators Market
Robotics and Automation
Humanoid Robot Market
Robotics and Automation
Simultaneous Localization and Mapping (SLAM) Technology Market
Robotics and Automation
Case and Box Handling Robots Market
Robotics and Automation
Industrial Robotics Market
Robotics and Automation
Africa Agricultural Robots and Mechatronics Market
Robotics and Automation
Latin America Warehouse Robotics Market