
 APAC Robotic Process Automation (RPA) Market | 2026-2036
APAC Robotic Process Automation (RPA) Market Size, Share, and Industry Trends Forecast 2026-2036
APAC Robotic Process Automation (RPA) Market Insights
Platform licensing revenue is rewriting margin economics across the APAC RPA landscape. UiPath Inc. leverages its partner ecosystem to sustain deployment velocity across Southeast Asian banks. Automation Anywhere Inc. anchors cloud-native bot architectures for mid-market manufacturers in India and Vietnam. Laiye competes aggressively on Mandarin-language document understanding for mainland Chinese insurers and state enterprises.
Robotic Process Automation in APAC deploys software bots that emulate human interactions with digital systems through structured workflow scripts, API orchestration, and computer vision-based screen scraping, typically executing rule-based tasks at throughput rates exceeding manual processing by an order of magnitude. The technology serves primarily to reduce operational expenditure in high-volume, low-variance administrative processes while improving audit trails and cycle-time predictability. Cloud-based deployment is capturing the fastest expansion as hyperscaler availability zones proliferate across Singapore, Sydney, and Mumbai, though on-premises installations retain dominance among Japanese financial institutions with stringent data residency requirements. Intelligent Automation solutions incorporating machine learning and natural language processing command premium pricing relative to task automation offerings, reflecting the structural migration from scripted bots toward adaptive cognitive systems.
India's TRAI data localization guidelines, Japan's METI cybersecurity frameworks for critical infrastructure, and Singapore's MAS technology risk management principles collectively shape product architecture decisions and go-to-market compliance burdens for RPA vendors operating across APAC. China's SAMR algorithm governance provisions and GB standards for financial software interoperability create additional certification requirements for foreign platforms seeking mainland market access. Stakeholders must monitor evolving AI liability allocations as regulators distinguish between deterministic automation and probabilistic cognitive systems when assigning accountability for bot-driven errors.
Market Dynamics
Cloud-native bot architectures are compressing deployment cycles across APAC financial institutions, while India's PLI scheme for IT hardware manufacturing forces software vendors to localize automation infrastructure or forfeit public sector contracts.
Growth Catalysts
- TRAI data localization guidelines:India's mandate for domestic data storage compels foreign RPA vendors to establish local cloud infrastructure, accelerating indigenous platform development.
- Banking compliance automation:Japanese financial institutions deploy software bots for transaction reconciliation and audit documentation to satisfy METI cybersecurity frameworks.
- Intelligent document processing:Mandarin-language natural language understanding capabilities unlock automation penetration in mainland Chinese insurers and state-owned enterprises.
Market Restraints
- Technical limitation:Rule-based bots struggle with unstructured data formats prevalent in legacy paper documentation across Southeast Asian SMEs.
- Regulatory friction:China's SAMR algorithm governance provisions impose certification delays on foreign cognitive automation platforms seeking mainland market access.
- Supply concentration risk:Hyperscaler cloud infrastructure dependence concentrates in Singapore and Mumbai availability zones, creating single-point vulnerability.
Strategic Opportunities
- Vietnam manufacturing automation:Mid-market electronics assemblers represent underpenetrated demand for cloud-native bot architectures as regional supply chains diversify from China.
- Technology convergence:Computer vision-based screen scraping combined with API orchestration enables end-to-end process automation without legacy system replacement.
- MAS technology risk management principles:Singapore's regulatory clarity on bot accountability standards creates first-mover advantage for certified platforms serving ASEAN banks.
Industry Challenges
- Skill scarcity in bot architecture:Shortage of certified developers fluent in both legacy mainframe protocols and modern API frameworks constrains deployment velocity in Japanese institutions.
- Integration complexity:Cobol-based core banking systems in Australian regional banks resist API connectivity, forcing expensive middleware development for bot deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | APAC Robotic Process Automation (RPA) Market |
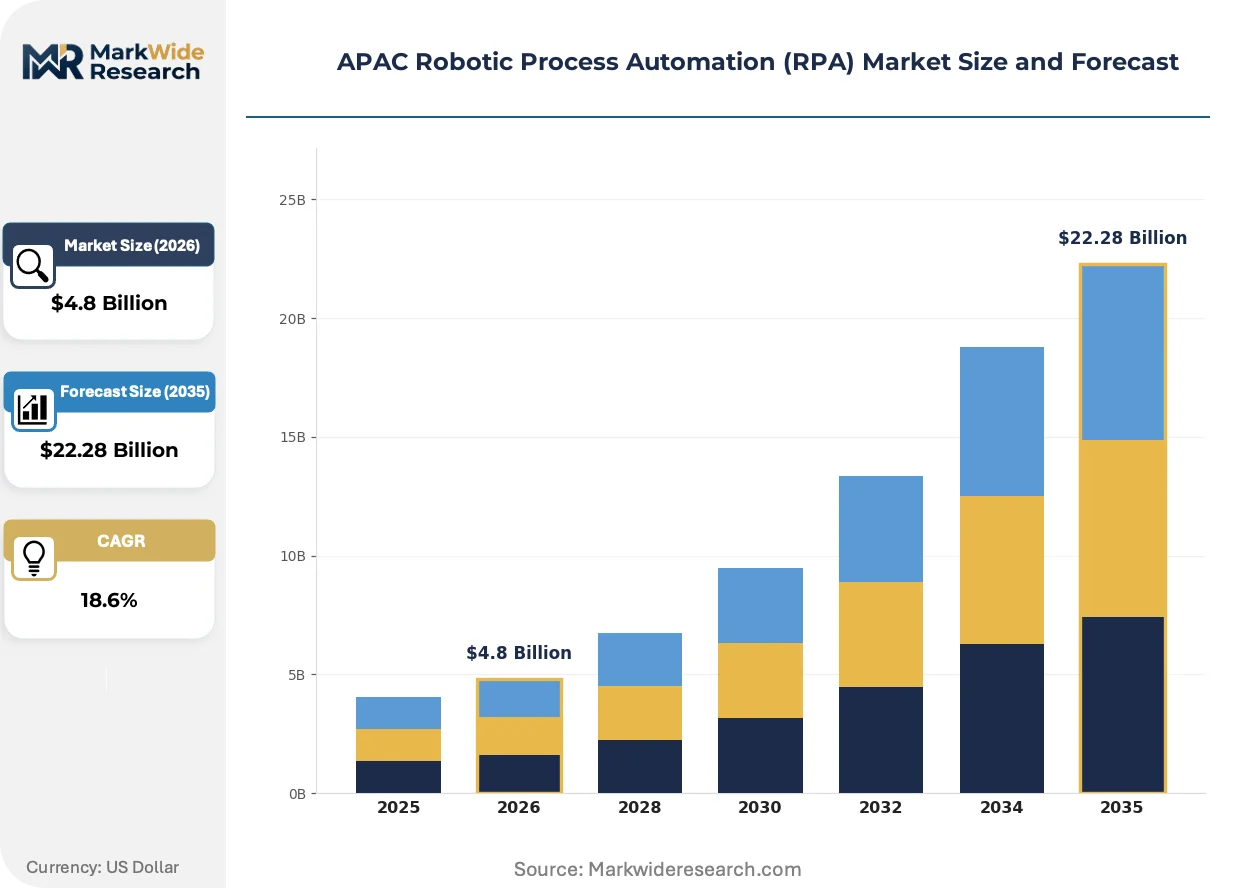
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $22.28 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premises, Cloud-based, Hybrid, Managed Services End User: BFSI, Healthcare, Retail, Manufacturing Solution: Task Automation, Process Automation, Software Robotics, Intelligent Automation Application: Invoice Processing, Customer Support, Data Entry, Compliance Monitoring |
| Companies Covered | Automation Anywhere Inc., UiPath Inc., Blue Prism Group PLC, Pegasystems Inc., AntWorks Pte Ltd., Datamatics Global Services Limited, Laiye, NICE Ltd., Kofax Inc., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
APAC Robotic Process Automation (RPA) Market Trends and Innovations
Adaptive cognitive systems are displacing deterministic scripted bots across APAC enterprise automation portfolios, compressing pricing premiums and forcing architectural pivots among incumbent platform vendors.
Intelligent Automation solutions incorporating machine learning and natural language processing are migrating from premium enterprise tiers toward mid-market accessibility as API orchestration matures. Southeast Asian banks and Indian manufacturers adopt these capabilities at accelerating pace, collapsing the historical eighteen-month pilot-to-production cycle. The technology is migrating from proof-of-concept experimentation toward production-grade deployment, enabling real-time exception handling in high-volume transaction processing.
Japan's METI cybersecurity frameworks for critical infrastructure mandate granular audit trails and human-in-the-loop protocols for bot-driven financial transactions. These provisions force RPA vendors to rearchitect logging capabilities and access controls, increasing compliance engineering overhead. Japanese megabanks and insurance groups absorb these costs through captive development centers, while foreign platforms struggle to satisfy certification timelines.
Subscription-based consumption models displace perpetual licensing across APAC mid-market buyers, unbundling implementation services from platform fees. Regional system integrators in Bengaluru and Hyderabad capture recurring revenue through managed bot operations, while direct vendor relationships concentrate among top-tier financial institutions. This bifurcation is most visible in India's enterprise services corridor, where SaaS-native procurement preferences accelerate cloud migration timelines.
APAC Robotic Process Automation (RPA) Market Segmentation
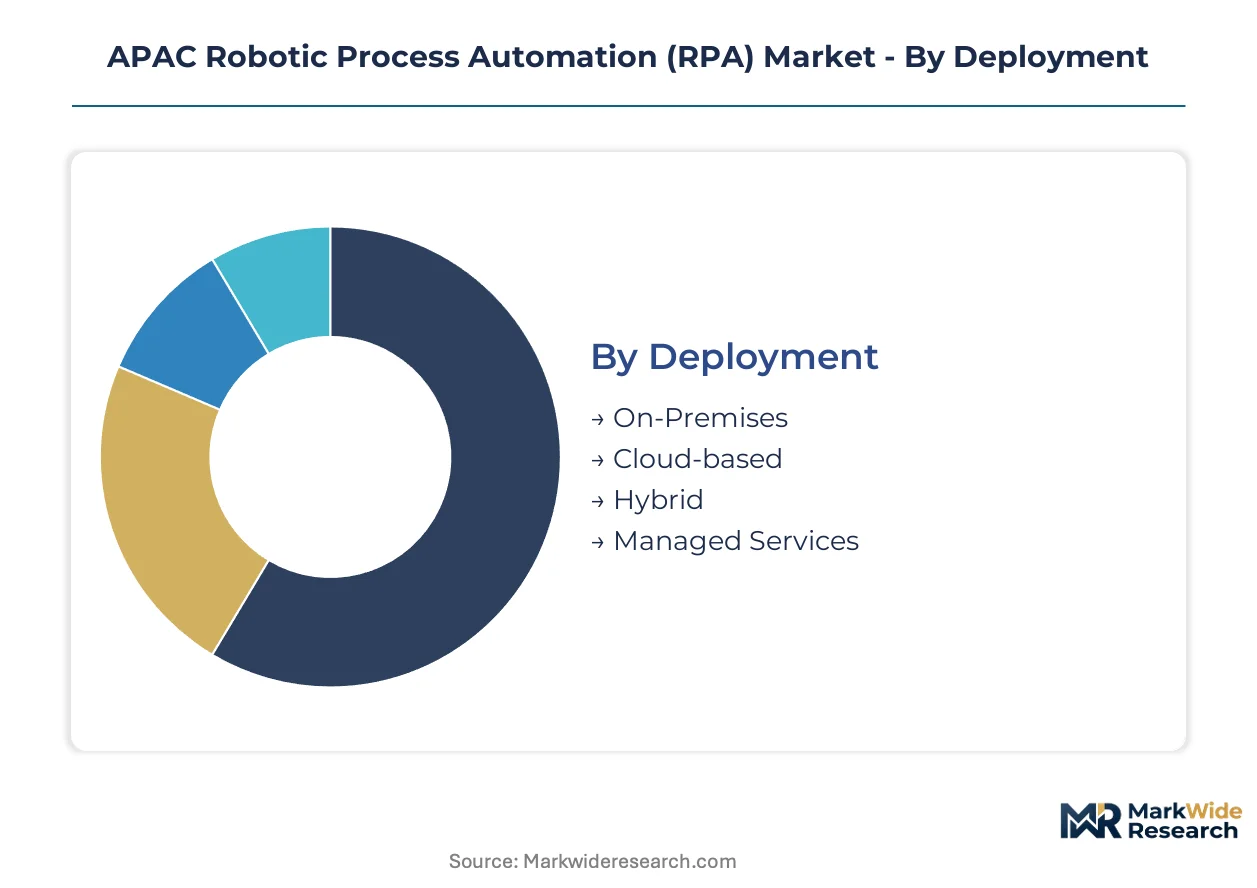
Segmentation reveals how APAC RPA demand fragments across infrastructure maturity, regulatory tolerance, and cognitive sophistication. Each dimension exposes distinct procurement patterns and vendor positioning strategies.
Deployment:
Mature on-premises installations coexist with emerging cloud-native architectures as data residency requirements diverge across the region.
- On-Premises:Legacy installations persist where data sovereignty mandates dominate. Japanese financial institutions under METI cybersecurity frameworks maintain captive infrastructure for transaction reconciliation bots, absorbing higher capital expenditure to satisfy audit granularity requirements.
- Cloud-based:Hyperscaler availability zones in Singapore, Sydney, and Mumbai compress provisioning cycles. Southeast Asian banks adopt these architectures fastest where regulatory latency permits cross-border data flows.
- Hybrid:Split deployments separate sensitive core processes from edge automation. Indian manufacturers under TRAI guidelines localize compliance workflows while offloading analytics to cloud tiers.
- Managed Services:Third-party bot operations transfer operational risk to regional system integrators. Bengaluru and Hyderabad specialists capture recurring revenue through SLA-governed automation.
On-Premises retains volume leadership; Cloud-based holds the steepest expansion curve.
End User:
Cost tier stratification separates compliance-heavy institutional buyers from margin-sensitive industrial adopters.
- BFSI:Banking and financial services institutions deploy software bots for transaction reconciliation and regulatory documentation. Japanese megabanks and Singaporean wealth managers drive premium pricing for intelligent automation with embedded audit trails.
- Healthcare:Patient data processing and claims administration automation accelerates where interoperability standards mature. Australian hospital networks and Indian diagnostic chains invest in HIPAA-aligned and local-equivalent compliant platforms.
- Retail:Inventory reconciliation and order management bots serve omnichannel fulfillment networks. Vietnamese and Indonesian e-commerce operators adopt task automation for last-mile logistics coordination.
- Manufacturing:Production line quality assurance and supply chain visibility bots penetrate electronics assemblers. Mid-market Vietnamese manufacturers represent underpenetrated demand as regional supply chains diversify.
BFSI commands the highest platform spend per seat; Manufacturing is expanding most quickly as PLI scheme incentives deepen automation penetration.
Solution:
Customer type differentiation separates deterministic rule-followers from adaptive cognitive system adopters.
- Task Automation:Scripted bots execute single-step, rule-based workflows without contextual adaptation. Southeast Asian SMEs deploy these for invoice matching and data migration where process variance remains minimal.
- Process Automation:Multi-step workflow orchestration connects disparate systems through API integration. Indian IT services corridors in Bengaluru and Pune standardize on these platforms for enterprise back-office consolidation.
- Software Robotics:Computer vision-enabled screen scraping emulates human interface interactions with legacy systems. Australian regional banks rely on these for Cobol-based core banking connectivity without middleware replacement.
- Intelligent Automation:Machine learning and natural language processing enable exception handling and unstructured data interpretation. Mainland Chinese insurers and state enterprises under SAMR governance provisions pay premiums for Mandarin-language document understanding capabilities.
Process Automation retains volume leadership; Intelligent Automation is climbing the fastest as cognitive capabilities migrate toward mid-market accessibility.
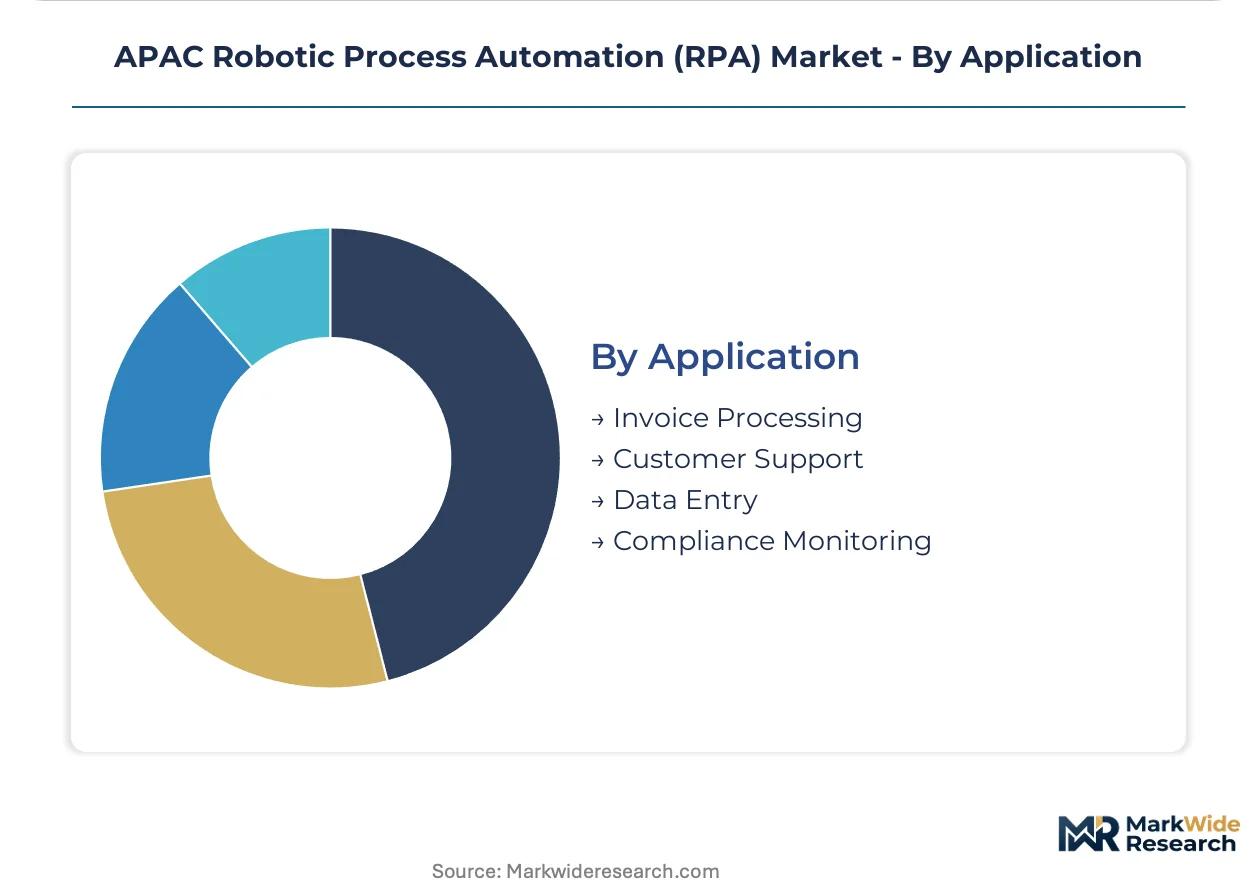
Application:
Geography shapes which use cases dominate as regulatory frameworks and legacy infrastructure density vary.
- Invoice Processing:Optical character recognition and validation bots extract structured data from supplier documentation. Indian manufacturing clusters automate three-way matching to satisfy GST compliance automation requirements.
- Customer Support:Chatbot and ticket routing automation deflects routine inquiries from human agents. Southeast Asian digital banks deploy these for 24/7 Mandarin and English multilingual service coverage.
- Data Entry:Form population and system synchronization bots eliminate manual transcription errors. Japanese insurance groups under METI mandates deploy these with human-in-the-loop protocols for critical field validation.
- Compliance Monitoring:Continuous audit trail generation and anomaly detection satisfy regulatory surveillance requirements. Singaporean banks under MAS technology risk management principles certify these platforms for algorithmic accountability.
Invoice Processing retains volume leadership; Compliance Monitoring is gaining share fastest as regulatory scrutiny intensifies across APAC financial centers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japanese financial institutions absorb premium pricing for METI-compliant audit architectures, while Vietnamese manufacturers demand cloud-native bot deployments at mid-market price points. India's PLI scheme for IT hardware manufacturing forces foreign vendors to localize automation infrastructure or surrender public sector procurement eligibility.
India
Enterprise services corridors in Bengaluru, Hyderabad, and Pune concentrate deployment velocity for back-office consolidation bots. TRAI data localization guidelines compel foreign RPA vendors to establish domestic cloud infrastructure or forfeit government contracts. The PLI scheme for IT hardware manufacturing prompts software vendors to localize automation infrastructure within the country's manufacturing clusters.
Japan
METI cybersecurity frameworks for critical infrastructure mandate granular audit trails and human-in-the-loop protocols for bot-driven financial transactions. Japanese megabanks and insurance groups absorb compliance engineering costs through captive development centers, while foreign platforms struggle to satisfy certification timelines. Tokyo and Osaka anchor demand for transaction reconciliation and regulatory documentation automation.
China
SAMR algorithm governance provisions impose certification delays on foreign cognitive automation platforms seeking mainland market access. State-owned enterprises and insurers pay premiums for Mandarin-language document understanding capabilities from domestic platforms. Beijing and Shanghai concentrate intelligent automation procurement for compliance monitoring and unstructured data interpretation.
Singapore
MAS technology risk management principles create first-mover advantage for certified platforms serving ASEAN banks with clear algorithmic accountability standards. The city-state's hyperscaler availability zones compress provisioning cycles for cloud-native bot architectures. Regional headquarters for global financial institutions anchor demand for 24/7 multilingual customer support automation.
Vietnam
Mid-market electronics assemblers represent underpenetrated demand for cloud-native bot architectures as regional supply chains diversify from China. Manufacturing automation procurement concentrates in Ho Chi Minh City and Hanoi industrial parks. Cost-sensitive buyers prioritize subscription-based consumption models over perpetual licensing for inventory reconciliation and order management bots.
APAC Robotic Process Automation (RPA) Market Competitive Landscape
Capability concentration sits with cognitive automation specialists; scale advantage sits with cloud-native platform vendors with established partner ecosystems. The vendor base organizes into three strategic archetypes: hyperscaler-aligned platform vendors, regional system integrators with managed services capabilities, and Mandarin-language document processing specialists. Competitive moves concentrate on M&A for API orchestration capabilities and strategic partnerships with regional system integrators for deployment velocity.
Within the cloud-native tier, UiPath Inc. and Automation Anywhere Inc. occupy positions as scale-driven platform anchors with partner ecosystems sustaining deployment velocity across Southeast Asian banks. Laiye exemplifies the cognitive specialization archetype competing on Mandarin-language document understanding for mainland Chinese insurers and state enterprises.
| Leading Market Players |
|---|
| Automation Anywhere Inc. |
| UiPath Inc. |
| Blue Prism Group PLC |
| Pegasystems Inc. |
| AntWorks Pte Ltd. |
| Datamatics Global Services Limited |
| Laiye |
| NICE Ltd. |
| Kofax Inc. |
| Others |
Pricing and Supply Chain Analysis
Hyperscaler cloud infrastructure concentration in Singapore and Mumbai availability zones anchors downstream margin capture for platform vendors, while subscription-based consumption models shift revenue recognition toward recurring service tiers across APAC mid-market buyers.
Pricing Analysis
Managed bot operations and SLA-governed support contracts drive lifetime value expansion beyond initial platform licensing. Three-tier pricing structure across premium, standard, and economy levels segments by cognitive sophistication and audit granularity, with Japanese financial institutions absorbing METI-compliant premiums while Vietnamese manufacturers seek entry-level cloud-native tiers. Cost compression in standard-tier SaaS offerings is intensifying because regional system integrators in Bengaluru and Hyderabad bundle implementation services at compressed margins. Mid-market electronics assemblers in Vietnam exhibit highest price sensitivity; Singaporean wealth managers under MAS accountability mandates demonstrate lowest.
Supply Chain Analysis
Tata Consultancy Services, Wipro, and Infosys hold dominant contract-manufacturing capacity for bot deployment and managed operations across the APAC region. Platform development concentrates in India, the United States, and Israel, while cloud infrastructure provisioning draws from hyperscaler availability zones in Singapore, Sydney, and Mumbai. Supply chain risk centers on single-source vulnerability for Mandarin-language natural language processing engines subject to SAMR certification delays. Distribution runs through regional system integrators for mid-market penetration and direct vendor relationships for top-tier financial institutions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity runs through cognitive automation specialization as deterministic scripted bots lose pricing power and adaptive systems create niche margin pools across compliance-heavy and language-specific segments.
For Market Incumbents: Entrench platform stickiness through captive API orchestration capabilities and deepen vertical integration into partner certification programs. Defend against Mandarin-language document processing specialists by accelerating METI-compliant audit architecture investments. Channel control through regional system integrator exclusivity agreements in Bengaluru and Hyderabad represents the critical defensive lever. For New Entrants and Emerging Players: Establish a beachhead in Vietnamese mid-market electronics assembly automation where cloud-native bot architectures face limited incumbent saturation. White-space targets include Ho Chi Minh City industrial parks for inventory reconciliation bots and Hanoi manufacturing clusters for supply chain visibility automation. Go-to-market angle centers on subscription-based consumption models displacing perpetual licensing among cost-sensitive regional supply chain diversifiers. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional system integrators possessing managed services capabilities and SLA-governed automation contracts. Long-term viability over the analysis window favors platforms with demonstrated SAMR certification navigation or METI-compliant audit architectures. Signal to monitor: algorithmic accountability standard adoption rates across ASEAN banking regulators.| Strategic Initiative | Industry Significance |
|---|---|
| API Orchestration Acquisition | Consolidates connectivity capabilities for Cobol-based core banking systems in Australian regional institutions. |
| Mandarin NLP Capability Buildout | Unlocks mainland Chinese insurer and state enterprise procurement subject to SAMR governance provisions. |
| Managed Services Partnership | Captures recurring revenue through SLA-governed bot operations in India's enterprise services corridor. |
| METI Compliance Certification | Enables premium pricing for audit-granular platforms serving Japanese megabanks and insurance groups. |
| Cloud-Native Architecture Migration | Compresses provisioning cycles for Southeast Asian banks leveraging Singapore hyperscaler availability zones. |
Research Methodology
Desk research of vendor SEC filings, hyperscaler capex disclosures, and regulatory framework documentation preceded structured interviews with CTOs, IT procurement officers, platform engineers, and regional system integrator delivery heads. Primary fieldwork captured deployment velocity metrics, pilot-to-production cycle compression, and certification timeline experiences across Japanese, Indian, and Southeast Asian implementations. Secondary validation drew from TRAI guideline releases, METI cybersecurity framework updates, SAMR algorithm governance provisions, and MAS technology risk management principle amendments. Bottom-up segment sizing triangulated against top-down market envelope estimates from platform vendor reported metrics and regional system integrator contract disclosures.
Assumptions held fixed include prevailing data localization mandates, hyperscaler availability zone expansion timelines, and regulatory certification processing durations; variables tested include cognitive automation adoption elasticity and mid-market SaaS procurement acceleration. Segmentation dimensions modeled span deployment model, organization size, vertical concentration, integration complexity, and regional regulatory cluster. CAGRs were derived from logistic diffusion curves fitted to historical adoption rates and adjusted for compliance-driven procurement acceleration. Industry-specific forecast inputs incorporated PLI scheme incentive disbursement patterns and METI audit granularity mandate enforcement intensity.
Sensitivities concentrate around SAMR certification timeline extensions, TRAI data localization guideline amendments, and hyperscaler availability zone concentration risk. Forecasts reflect these assumptions and acknowledge revision potential from algorithmic accountability liability reallocations or cognitive system error attribution framework shifts. Quarterly review of regulatory filing patterns, hyperscaler infrastructure expansion announcements, and regional system integrator contract backlog indicators is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
Sweden Robotic Lawn Mower Market
Robotics and Automation
Personal Robots Market
Robotics and Automation
Africa Cloud Robotics Market
Robotics and Automation
Global Entertainment Robots Market
Robotics and Automation
Robotic Process Automation (RPA) Market
Robotics and Automation
Wearable Robotic Exoskeleton Market
Robotics and Automation
Robot As a Service Market
Robotics and Automation
Asia-Pacific Logistics Robotics Market
Robotics and Automation
North America AUV and ROV Market
Robotics and Automation
Marine Robots Market
Robotics and Automation
Latin America Warehouse Robotics Market
Robotics and Automation
Italy Cloud Robotics Market
Robotics and Automation
Eldercare-Assistive Robots Market
Robotics and Automation
Robotics and Automation Actuators Market
Robotics and Automation
Biaxial Mobile Phone Stabilizer Market
Robotics and Automation
Robotic Welding Market