
 Asia Pacific Warehouse Robotics Market | 2026-2036
Asia Pacific Warehouse Robotics Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Warehouse Robotics Market Outlook
The third-party logistics channel is rewriting fulfillment economics across the Asia Pacific warehouse robotics landscape. Daifuku Co., Limited anchors automated storage and retrieval systems across Japan's automotive supplier parks. Geek+ Inc. dominates autonomous mobile robot deployments in China's e-commerce mega-warehouses. Yaskawa Electric Corporation leverages its servo-motor heritage to sustain precision control in high-speed sorting applications.
Asia Pacific warehouse robotics encompasses electromechanical systems engineered for material transport, storage retrieval, and order fulfillment within distribution and production facilities, typically operating with payload capacities from 50 kg to 1,500 kg and navigation accuracies within ±10 mm. These systems integrate servo drives, programmable logic controllers, and sensor arrays to execute repetitive material-handling tasks with cycle times measured in seconds rather than minutes. Autonomous Mobile Robots capture expanding capital allocation as facilities prioritize flexible routing over fixed infrastructure. Robotic Arms concentrate margin pools in palletizing and depalletizing cells where repeatability requirements exceed human capability. Sorting Systems face accelerating replacement cycles as parcel volumes outstrip legacy belt-conveyor throughput.
Japan's METI collaborative robot safety standards, China's GB/T industrial robot certification framework, and Australia's WHS regulations for autonomous systems collectively shape product design requirements and market access protocols across the region. Compliance with METI's force-limiting specifications adds engineering cost but unlocks deployment in human-occupied zones previously restricted to caged automation. Stakeholders must weigh certification pathway complexity against the operational flexibility that collaborative architectures enable in labor-constrained markets.
Market Dynamics
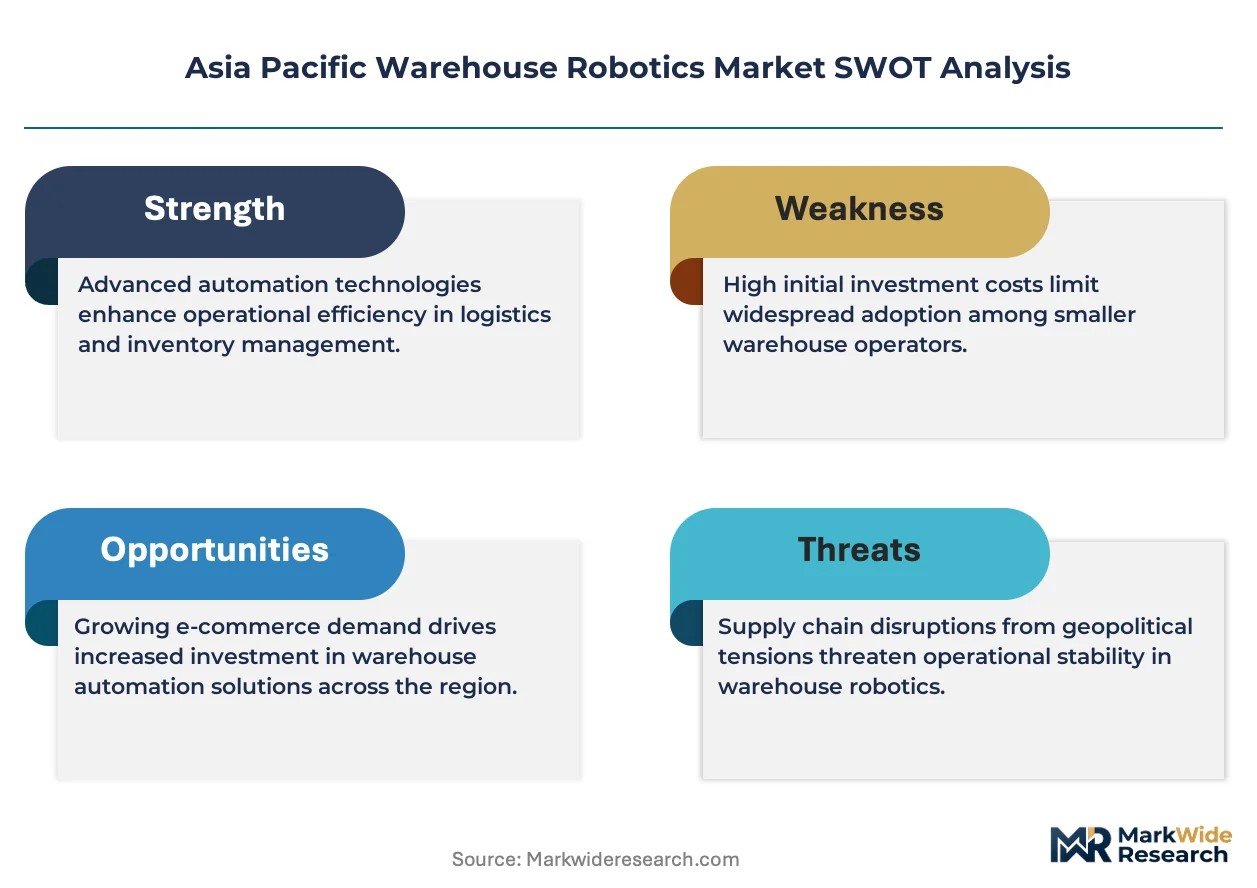
Japan's METI force-limiting specifications for collaborative robots are compressing certification timelines while expanding addressable deployment zones into human-occupied warehouse floors previously restricted to caged automation.
Growth Catalysts
- E-commerce fulfillment density:Southeast Asian mega-warehouses are deploying autonomous mobile robots to manage parcel volumes exceeding legacy belt-conveyor throughput.
- METI safety framework:Japan's collaborative robot standards unlock deployment in mixed human-machine zones without physical guarding barriers.
- GB/T certification pathway:China's industrial robot certification framework accelerates product registration for domestic and export markets.
Market Restraints
- Precision servo motor supply:Concentrated sourcing from Japanese and German suppliers creates input cost volatility for high-accuracy navigation systems.
- Dual carbon compliance:China's MEE emissions standards add engineering overhead to battery-powered fleet charging infrastructure.
- Legacy WMS integration:Proprietary warehouse management software architectures limit API accessibility for multi-vendor robot orchestration.
Strategic Opportunities
- Vietnam manufacturing corridor:Greenfield facility construction in northern industrial zones enables native collaborative robot deployment without retrofit constraints.
- 5G-private network convergence:Ultra-reliable low-latency connectivity is digitizing real-time fleet coordination in high-density sorting facilities.
- Australia WHS autonomous regulations:Updated workplace health and safety frameworks create compliance-driven replacement cycles for legacy material handling equipment.
Industry Challenges
- Mechatronics talent scarcity:Shortages of technicians fluent in both PLC programming and mechanical maintenance extend commissioning timelines.
- Multi-vendor interoperability:Absence of unified fleet management protocols forces custom integration layers for mixed-automation environments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Warehouse Robotics Market |
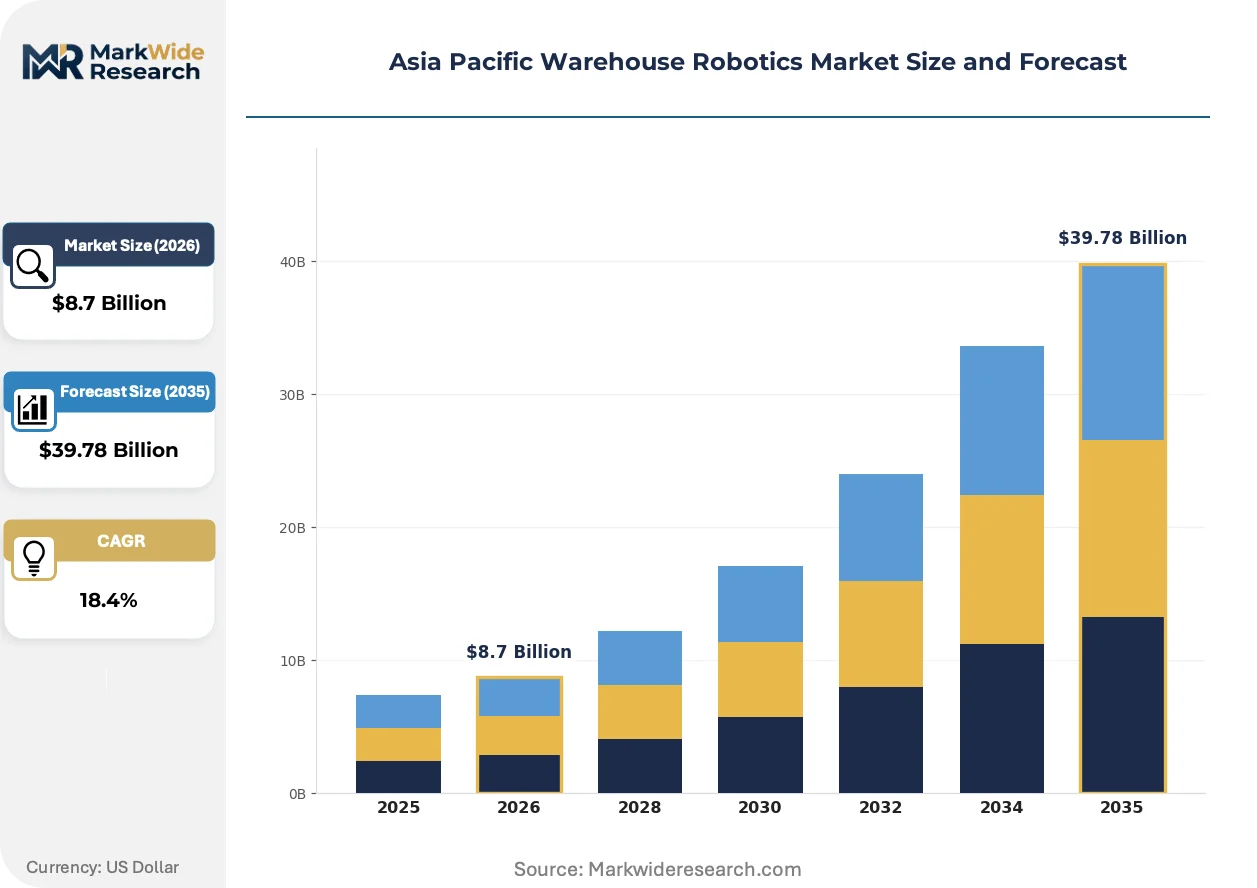
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $39.78 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Autonomous Mobile Robots, Automated Guided Vehicles, Robotic Arms, Sorting Systems End User: E-commerce, Retail, Manufacturing, Food & Beverage Technology: Machine Learning, Computer Vision, Sensor Technology, Cloud Computing Deployment: On-premises, Cloud-based, Hybrid, Edge |
| Companies Covered | Daifuku Co., Limited, Yaskawa Electric Corporation, Fanuc Corporation, Omron Corporation, ABB Ltd, Kuka AG, Honeywell International, Inc., GreyOrange, Geek+ Inc., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Warehouse Robotics Market Strategic Shifts
Warehousing automation across Asia Pacific is pivoting from fixed infrastructure toward adaptive routing architectures that reconfigure floor plans without structural modification.
Swarm intelligence algorithms for autonomous mobile robot coordination are digitizing warehouse traffic management. Third-party logistics operators in China's Yangtze River Delta are deploying hundred-unit fleets with decentralized pathfinding. This architecture compresses facility reconfiguration cycles from weeks to hours.
METI's updated collaborative robot safety circulars are mandating force-torque sensor integration for all new human-zone deployments. Japanese automotive supplier parks are retrofitting existing cells with compliant end-effectors. High-speed sorting applications in Osaka and Nagoya face the steepest compliance timelines.
Consumption-pattern shifts toward same-day delivery are compressing buyer switching cycles for robotics-as-a-service contracts. E-commerce platforms in Indonesia and Thailand are unbundling after-sales maintenance from capital leases. This preference shift is most visible in Jakarta's fulfillment network expansion.
Asia Pacific Warehouse Robotics Market Segmentation
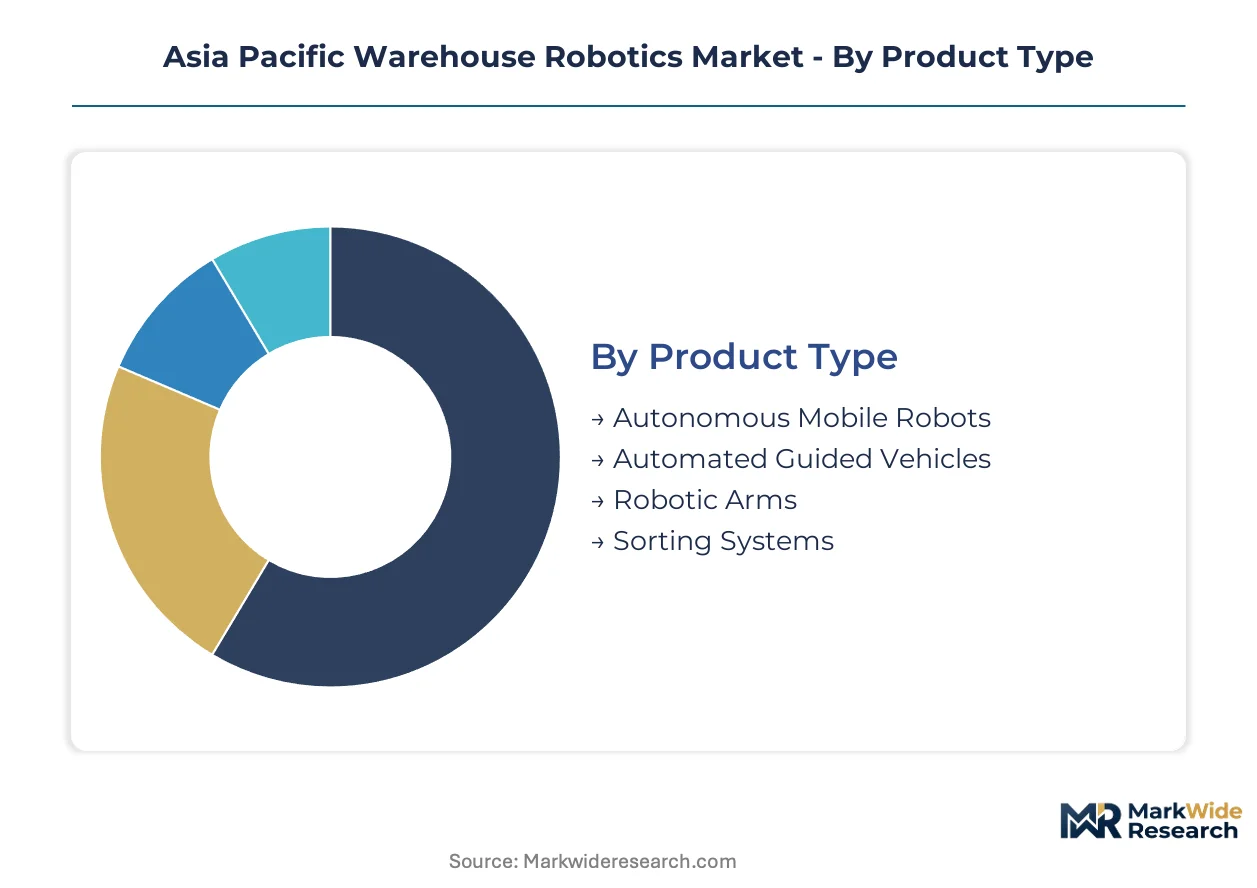
Warehouse robotics segmentation in Asia Pacific reflects divergent capital deployment strategies across facility types. E-commerce fulfillment centers prioritize flexible routing systems while automotive manufacturing corridors demand precision repeatability in fixed cells.
Product Type:
Mature electromechanical systems anchor installed base volumes while emerging adaptive architectures capture greenfield capital allocation.
- Autonomous Mobile Robots:Battery-powered units navigate via LiDAR and SLAM algorithms without floor-mounted guidance infrastructure. China's Yangtze River Delta e-commerce mega-warehouses deploy hundred-unit fleets with decentralized traffic management to compress reconfiguration cycles.
- Robotic Arms:Articulated manipulators with six or more degrees of freedom execute palletizing and depalletizing operations. Japan's automotive supplier parks concentrate demand where METI force-limiting specifications now mandate collaborative variants for mixed human-machine zones.
- Automated Guided Vehicles:Wire-guided or magnetic-tape-following transporters handle repetitive point-to-point material movement. Legacy installations in South Korean electronics assembly plants face replacement pressure from more flexible alternatives.
- Sorting Systems:High-throughput parcel diversion mechanisms integrate belt conveyors with robotic diverters. Southeast Asian third-party logistics operators upgrade legacy belt infrastructure as parcel volumes exceed mechanical throughput limits.
Autonomous Mobile Robots retain volume leadership; Robotic Arms hold the steepest expansion curve.
End User:
Customer archetypes span from velocity-driven fulfillment networks to precision-manufacturing environments with divergent performance specifications.
- E-commerce:Same-day delivery commitments compress order cycle times to minutes. Indonesian and Thai platforms unbundle robotics-as-a-service contracts from capital leases to accelerate Jakarta fulfillment network expansion.
- Manufacturing:Production-line integration demands sub-millimeter positioning accuracy. China's Yangtze River Delta electronics and automotive corridors deploy collaborative units for component sequencing and finished-goods transfer.
- Retail:Store-backroom automation addresses labor scarcity in urban distribution nodes. Australian supermarket chains pilot micro-fulfillment centers with compact robotic storage retrieval.
- Food & Beverage:Cold-chain compatibility and washdown-rated enclosures dominate specification sheets. Japanese chilled logistics providers deploy AMRs with IP67 protection for seafood processing facilities.
E-commerce commands capital deployment scale; Food & Beverage climbs fastest as cold-chain robotics penetration deepens.
Technology:
Software-defined capabilities are displacing hardware-centric differentiation as primary vendor selection criteria.
- Machine Learning:Predictive algorithms optimize pick-path sequencing and fleet charging schedules. Chinese warehouse operators deploy reinforcement learning for dynamic slotting in high-SKU-density environments.
- Computer Vision:Camera arrays enable object recognition and damage detection without mechanical probing. Japanese parcel sortation hubs implement 3D vision for irregular package handling.
- Sensor Technology:Force-torque, proximity, and environmental sensors feed real-time safety systems. METI collaborative robot circulars mandate sensor integration for all new human-zone deployments.
- Cloud Computing:Centralized fleet orchestration and predictive maintenance analytics reduce on-site IT overhead. Australian third-party logistics providers favor cloud-native architectures for multi-site visibility.
Computer Vision anchors differentiation; Cloud Computing expands most quickly as connectivity infrastructure matures.
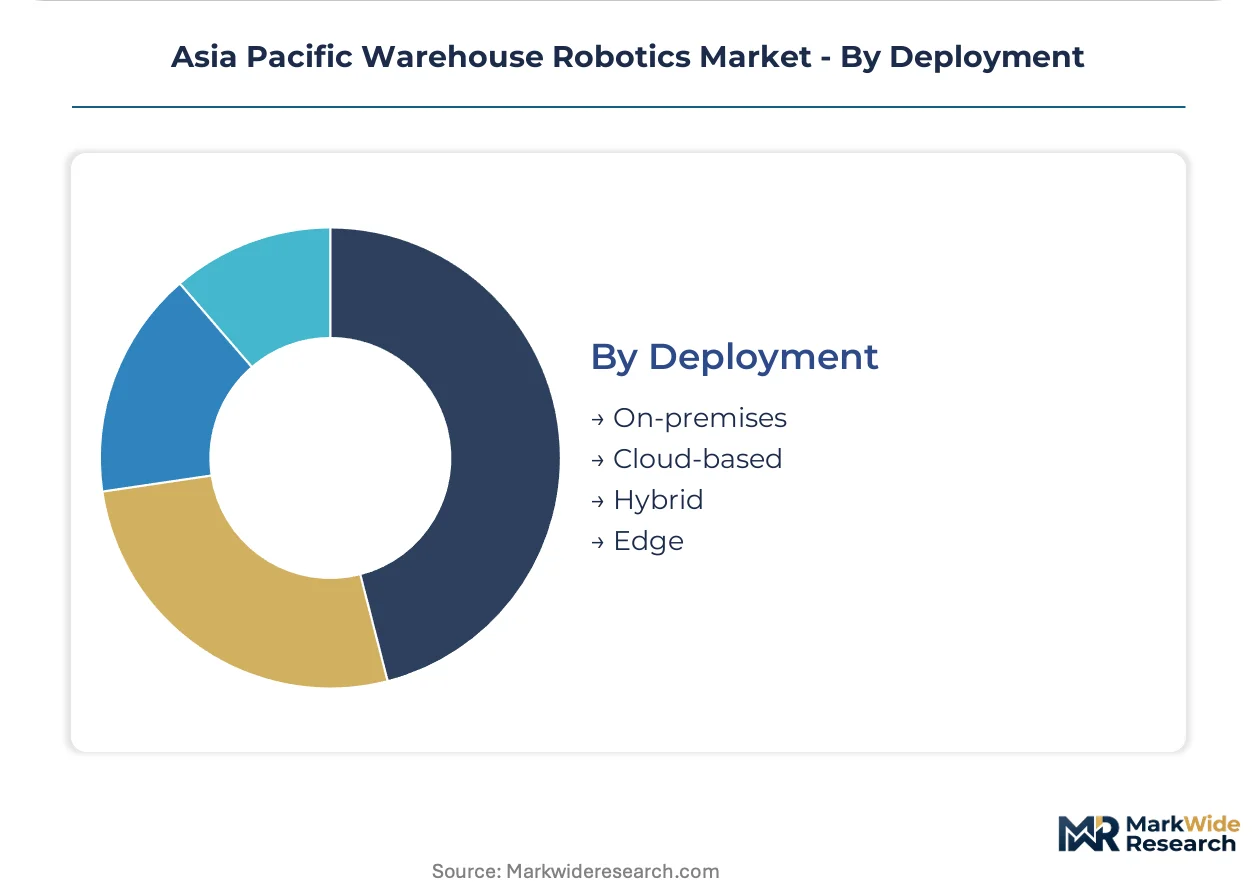
Deployment:
Architecture choices trade latency sensitivity against capital efficiency and data sovereignty requirements.
- On-premises:Local server infrastructure hosts fleet management and warehouse execution software. South Korean defense-sensitive supply chains mandate air-gapped deployment for security compliance.
- Cloud-based:Vendor-hosted platforms enable rapid scaling without facility-level IT investment. Southeast Asian startups prioritize this model to conserve working capital.
- Hybrid:Critical control loops run locally while analytics and optimization reside off-site. Chinese operators balance GB/T data localization requirements against cloud scalability.
- Edge:Compute nodes collocated with robot fleets minimize millisecond-scale latency for safety-critical decisions. Japan's high-speed sortation facilities deploy edge architectures for real-time collision avoidance.
Hybrid architectures dominate new installations; Edge deployment gains share fastest as 5G-private network convergence accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Japan's precision-motor supply base while Chinese system integrators compete on deployment velocity. This asymmetry shapes procurement patterns across Southeast Asian fulfillment networks and Australian cold-chain operators.
China
E-commerce mega-warehouses in the Yangtze River Delta drive hundred-unit AMR fleet orders. GB/T industrial robot certification accelerates product registration for domestic and export markets. Shenzhen and Hangzhou logistics hubs prioritize cloud-native orchestration platforms for multi-site visibility.
Japan
Automotive supplier parks demand METI-compliant collaborative robots for mixed human-machine zones. METI force-limiting specifications mandate torque-sensor integration for all new human-zone deployments. Osaka and Nagoya sortation facilities face compressed compliance timelines for high-speed retrofit cycles.
South Korea
Electronics assembly plants seek flexible routing alternatives to legacy magnetic-tape AGV infrastructure. Defense-sensitive supply chains mandate air-gapped on-premises deployment for security compliance. Seoul Capital Area and Busan-Ulsan corridors concentrate greenfield collaborative robot commissioning.
Australia
Supermarket chains pilot micro-fulfillment centers with compact robotic storage retrieval. Updated WHS autonomous regulations create compliance-driven replacement cycles for legacy material handling equipment. New South Wales and Victoria distribution nodes lead cold-chain AMR penetration with IP67-rated fleet deployments.
Vietnam
Northern industrial zones attract greenfield facility construction without retrofit constraints. Government manufacturing incentives accelerate native collaborative robot deployment in export-oriented electronics parks. Hanoi and Hai Phong logistics corridors prioritize 5G-private network convergence for real-time fleet coordination.
Asia Pacific Warehouse Robotics Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in servo drives and sensor arrays. The vendor base stratifies across three tiers: full-stack solution providers, modular subsystem suppliers, and precision component fabricators. Japanese and German motor specialists occupy the premium component niche. Chinese deployment specialists compete on fleet-scale implementation velocity. Consolidation pressure intensifies as e-commerce operators demand single-vendor accountability for hundred-unit installations.
Within the full-stack integrator tier, Daifuku Co., Limited and Geek+ Inc. exemplify divergent geographic anchoring strategies. Daifuku represents the precision-engineering archetype rooted in automated storage and retrieval heritage. Geek+ occupies a position as the deployment-scale specialist serving high-velocity fulfillment networks. Yaskawa Electric Corporation sits within the component-to-systems migration path, leveraging servo-motor lineage to sustain precision control positioning. These three patterns—engineering heritage, deployment velocity, and vertical capability extension—define competitive positioning across procurement cycles.
| Leading Market Players |
|---|
| Daifuku Co., Limited |
| Yaskawa Electric Corporation |
| Fanuc Corporation |
| Omron Corporation |
| ABB Ltd |
| Kuka AG |
| Honeywell International, Inc. |
| GreyOrange |
| Geek+ Inc. |
| Others |
Value Chain & Pricing Dynamics
Japanese precision servo motor suppliers anchor upstream pricing power for high-accuracy navigation systems, concentrating margin capture in electromechanical component tiers while Chinese system integrators compete downstream on deployment velocity and fleet-scale implementation economics.
Pricing Analysis
Configured-to-order AMR fleets command 25-40% premiums over standard catalog units due to facility-specific SLAM mapping and WMS integration requirements. Three-tier pricing structure across premium, standard, and economy levels separates METI-certified collaborative robots from uncertified industrial variants and refurbished legacy units. Price differentiation hinges on certification grade and after-sales service bundling. Cost compression in economy-tier AGV replacements is intensifying because Southeast Asian third-party logistics operators prioritize capital conservation over performance specifications. E-commerce mega-warehouse operators exhibit lowest price sensitivity due to same-day delivery ROI timelines.
Supply Chain Analysis
Upstream feedstock dependencies for precision motion control center on rare-earth magnet processing concentrated in China, servo motor manufacturing anchored in Japan and Germany, and LiDAR sensor fabrication split between China and the United States. Critical inputs include neodymium-iron-boron magnets, high-resolution optical encoders, and silicon carbide power modules. Single-source vulnerability in Japanese torque-sensor supply creates bottleneck exposure for METI-compliant collaborative robot production. Distribution runs through direct OEM relationships for hundred-unit fleet orders and regional system integrator networks for mid-scale deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hardware margins are compressing across Asia Pacific warehouse robotics as robotics-as-a-service contracts expand three times faster than capital equipment sales, making software-defined fleet orchestration and predictive maintenance attach rates the primary value capture mechanism.
For Market Incumbents: Pre-empt emerging Chinese deployment specialists by acquiring certified collaborative robot subsystem suppliers before GB/T export pathways mature. Anchor backward integration into servo drive production to offset Japanese and German input cost volatility. METI compliance timelines for existing installed base retrofits represent immediate margin defense priority. For New Entrants and Emerging Players: Build out cloud-native fleet orchestration platforms targeting Australian supermarket micro-fulfillment pilots where incumbent WMS integration complexity creates white-space vulnerability. Vietnam's northern industrial zones offer greenfield collaborative robot deployment without retrofit constraints. Lead with 5G-private network convergence as technical differentiation wedge. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed warehouse execution software vendors lacking hardware integration capabilities. Five-to-ten year viability favors full-stack providers with captive servo motor supply or exclusive METI certification pathways. Watch for inflection when Indonesian e-commerce operators consolidate hundred-unit AMR procurement under single-vendor accountability frameworks.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Servo Motor Production | Yaskawa Electric Corporation's captive supply of precision drives insulates against Japanese-German supplier concentration. |
| 5G-Private Network Convergence | Vietnam's Hanoi logistics corridors deploy ultra-reliable low-latency connectivity for real-time fleet coordination. |
| Robotics-as-a-Service Unbundling | Indonesian platforms separate after-sales maintenance from capital leases to accelerate Jakarta fulfillment expansion. |
| METI Certification Pre-emption | Daifuku Co., Limited retrofits existing cells with force-torque sensor integration before compliance deadlines. |
| Cloud-Native Orchestration Platform | Australian third-party logistics providers prioritize multi-site visibility without facility-level IT investment. |
Study Parameters
A standing panel of warehouse operations directors, robotics procurement leads at third-party logistics providers, system integrator technical architects, and aftermarket service heads provided ongoing calibration against secondary validation from customs trade data, METI certification registries, GB/T industrial robot filings, and e-commerce operator capex disclosures. Bottom-up unit deployment tracking across Yangtze River Delta mega-warehouses combined with top-down market sizing from regional automation investment surveys.
Scenario-bracketing around e-commerce fulfillment density trajectories and collaborative robot certification timeline compression shaped analytical framework development across the analysis window. Segmentation dimensions modeled include product type, end-user vertical, deployment architecture, and technology layer. CAGRs derived from logistic curve adoption modeling against historical AGV-to-AMR replacement cycles and 5G infrastructure rollout schedules.
Sensitivities concentrate around METI regulatory amendment timelines, rare-earth magnet export restriction scenarios, and WMS API standardization progress. Forecasts reflect documented assumptions on fleet-scale implementation velocity and software attach rate expansion. Cross-checking against IHS Markit industrial automation equipment databases and RBR50 robotics company revenue disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
SCARA Robots Market
Robotics and Automation
Top Robotics Market
Robotics and Automation
Smart Sweeper Market
Robotics and Automation
Robot Charging Station Market
Robotics and Automation
Asia-Pacific Robotic Process Automation Market
Robotics and Automation
Underwater Jetpack Market
Robotics and Automation
Robotic Flexible Washer Market
Robotics and Automation
Robot End-Effector Market
Robotics and Automation
Sweeper Robot Market
Robotics and Automation
Virtual 3D Nanorobots Market
Robotics and Automation
Cyber-Physical System Market
Robotics and Automation
APAC Robotic Process Automation (RPA) Market
Robotics and Automation
North America Collaborative Robots Market
Robotics and Automation
Global Robotics Market
Robotics and Automation
Self-Driving Floor Scrubbers Market
Robotics and Automation
Automated Liquid Handling Technologies Market