
 Middle East Cloud Robotics Market | 2026-2036
Middle East Cloud Robotics Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East Cloud Robotics Market Analytics
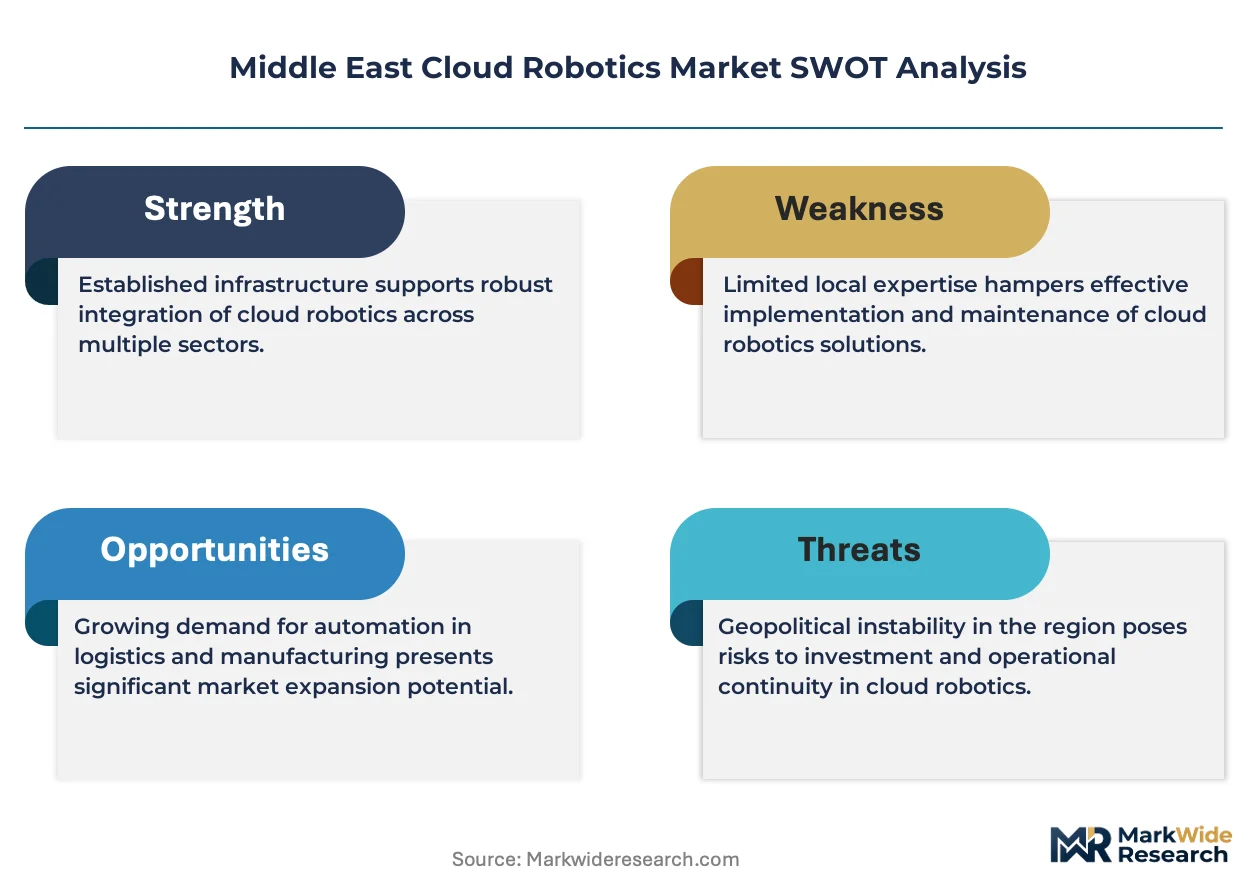
Subscription-based fleet management software is hardening as the primary revenue layer in Middle East cloud robotics, shifting vendor economics from hardware sales to recurring service contracts. Huawei Technologies leverages its regional telecom infrastructure to anchor cloud connectivity for deployed robot fleets. G42 competes through AI-native orchestration platforms trained on Arabic-language operational data. ABB extends its industrial installed base into cloud-connected predictive maintenance services across Gulf manufacturing zones.
Cloud robotics fuses physical robotic systems with distributed cloud computing architectures, enabling real-time data processing, centralized fleet learning, and remote task orchestration through 5G or fiber backhaul with sub-50ms latency requirements. The technology serves industrial automation, healthcare delivery, and logistics coordination where on-device compute proves insufficient for complex perception or multi-robot collaboration. Industrial robots retain the dominant installed base across Middle East petrochemical and metal fabrication facilities, while autonomous mobile robots represent the fastest-expanding category as e-commerce fulfillment centers proliferate in Jebel Ali and Riyadh. Artificial intelligence and computer vision technologies concentrate margin pools in software licensing, though hardware-integrated edge-cloud hybrid architectures capture premium pricing for mission-critical deployments.
MOHAP in the UAE and Saudi FDA regulate healthcare robot safety and data sovereignty requirements, compelling vendors to establish in-country cloud infrastructure rather than rely on foreign data centers. BIS-equivalent conformity assessment procedures in Gulf Cooperation Council member states shape product certification timelines and technical documentation burdens for imported systems. Stakeholders must monitor evolving data localization mandates and spectrum allocation decisions for private 5G networks that determine where cloud robotics architectures can achieve operational viability.
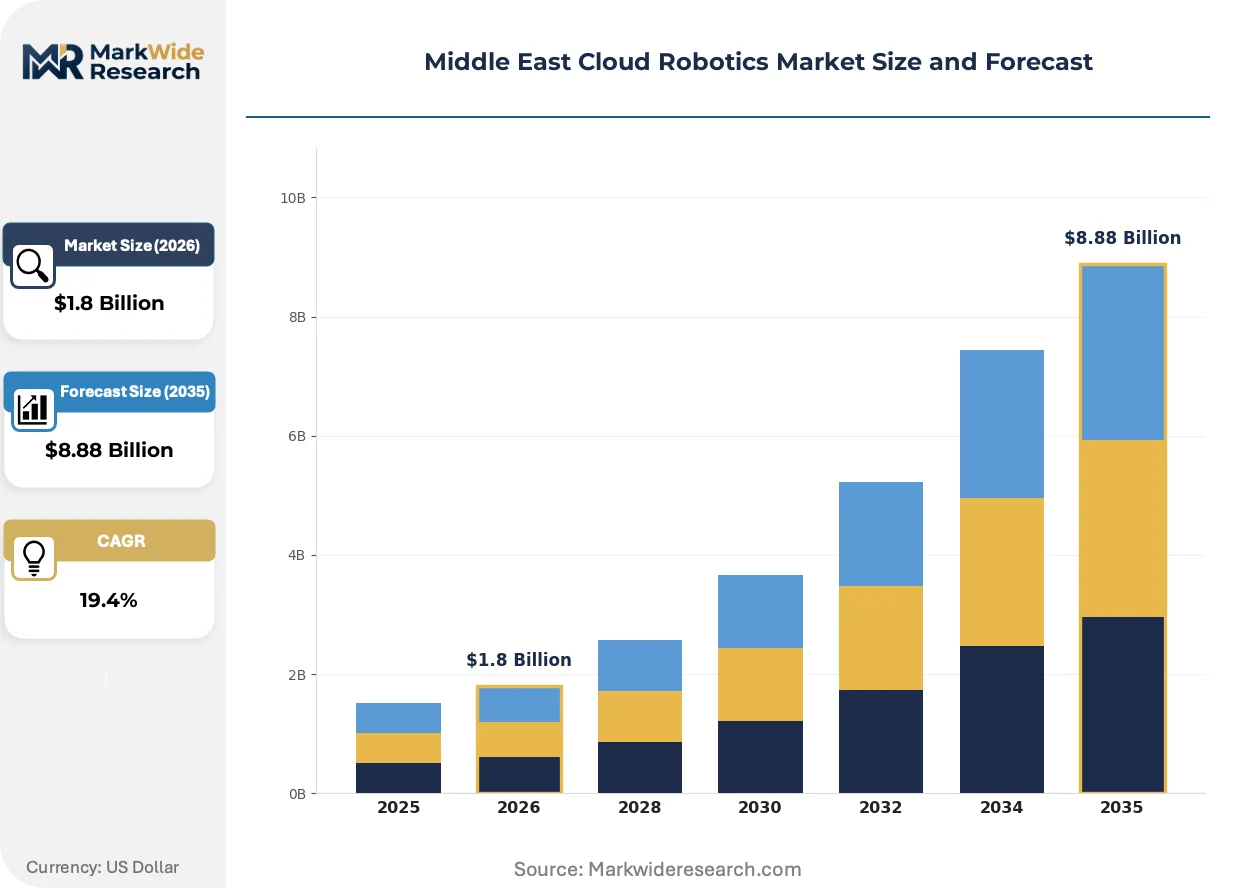
Market Dynamics
Saudi Arabia's Vision 2030 industrial transformation programs and the UAE's logistics hub concentration in Dubai are compressing cloud robotics deployment cycles from pilot to production. Vendors now face compressed procurement timelines as Gulf state-backed entities demand operational technology integration within 12-month windows.
Growth Catalysts
- Private 5G network rollouts:Gulf telecommunications regulators are allocating dedicated spectrum for industrial automation, enabling sub-50ms latency connectivity required for real-time robot fleet coordination in petrochemical facilities.
- Saudi Vision 2030 localization mandates:Domestic content requirements for industrial equipment procurement are compelling international vendors to establish in-country cloud infrastructure and technical support centers.
- E-commerce fulfillment center proliferation:Warehouse automation demand in Jebel Ali and Riyadh logistics zones is accelerating autonomous mobile robot deployments for goods-to-person picking operations.
Market Restraints
- Data sovereignty compliance costs:MOHAP in the UAE and Saudi FDA healthcare robot regulations require in-country cloud infrastructure, doubling initial deployment capital versus foreign-hosted alternatives.
- Edge hardware import dependencies:Industrial robot controller and sensor supply chains concentrate in East Asian manufacturing clusters, exposing Gulf deployers to shipping volatility and customs clearance delays.
- Technical workforce scarcity:Cloud-native robotics engineering talent pools remain shallow across Gulf Cooperation Council labor markets, extending integration timelines for complex multi-robot orchestration.
Strategic Opportunities
- Underpenetrated Omani industrial zones:Sohar and Duqm port and manufacturing clusters lack deployed cloud robotics infrastructure, creating first-mover positioning for warehouse and inspection automation vendors.
- Healthcare robot regulatory tailwinds:MOHAP's streamlined medical device registration pathways for surgical and rehabilitation robots are reducing time-to-market for cloud-connected therapeutic systems.
- AI-vision convergence with digital twin platforms:Real-time sensor fusion and virtual facility modeling are enabling predictive maintenance services that extend contract values beyond hardware sales.
Industry Challenges
- Multi-vendor integration complexity:Cloud robotics deployments must coordinate legacy SCADA systems, proprietary robot operating systems, and heterogeneous fleet management software without standardized middleware.
- BIS-equivalent conformity assessment timelines:Gulf Cooperation Council technical documentation requirements and product certification procedures extend import approval cycles by four to eight months versus European CE marking.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East Cloud Robotics Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $8.88 Billion |
| CAGR (2026 – 2036) | 19.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Service Robots, Autonomous Mobile Robots, Industrial Robots, Collaborative Robots Application: Healthcare, Manufacturing, Logistics, Agriculture End User: Entertainment, Manufacturing Facilities, Hospitals, Retail Technology: Artificial Intelligence, Machine Learning, Computer Vision, Internet of Things |
| Companies Covered | CloudMinds, Huawei Technologies, Rockwell Automation, ABB, Fanuc Corporation, KUKA, Omron Corporation, Yaskawa Electric Corporation, G42, Others |
| Regions Covered | Middle East: Saudi Arabia, UAE, Qatar, Israel, Kuwait, Oman, Bahrain, Iran, Iraq, Rest of Middle East |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East Cloud Robotics Market Evolving Landscape
Cloud robotics architectures are fragmenting into composable software layers that decouple perception, planning, and control functions from proprietary hardware. This decomposition is enabling vendor-agnostic fleet management and compressing switching costs for industrial buyers.
Edge-cloud hybrid compute is modularizing robot system architectures across Middle East petrochemical and metal fabrication facilities. Operators are adopting containerized perception modules that swap between on-device inference and cloud-based model refinement based on latency tolerance. This flexibility is compressing hardware refresh cycles and enabling incremental capability upgrades without full system replacement.
MOHAP and Saudi FDA data localization mandates are hardening requirements for in-country cloud infrastructure hosting healthcare robot operational data. Medical device manufacturers are establishing Dubai and Riyadh data centers to comply with patient information sovereignty rules. Rehabilitation and surgical robot segments are absorbing the highest compliance costs, passing infrastructure investments through to hospital procurement contracts.
Subscription-based fleet management software is displacing perpetual licensing for warehouse automation in Jebel Ali and Riyadh logistics zones. Third-party logistics operators prefer operational expenditure models that align robot costs with seasonal volume fluctuations. E-commerce fulfillment centers in the UAE are driving this transition fastest, negotiating multi-year service contracts that bundle hardware, software, and maintenance into unit-per-pick pricing structures.
Middle East Cloud Robotics Market Segmentation
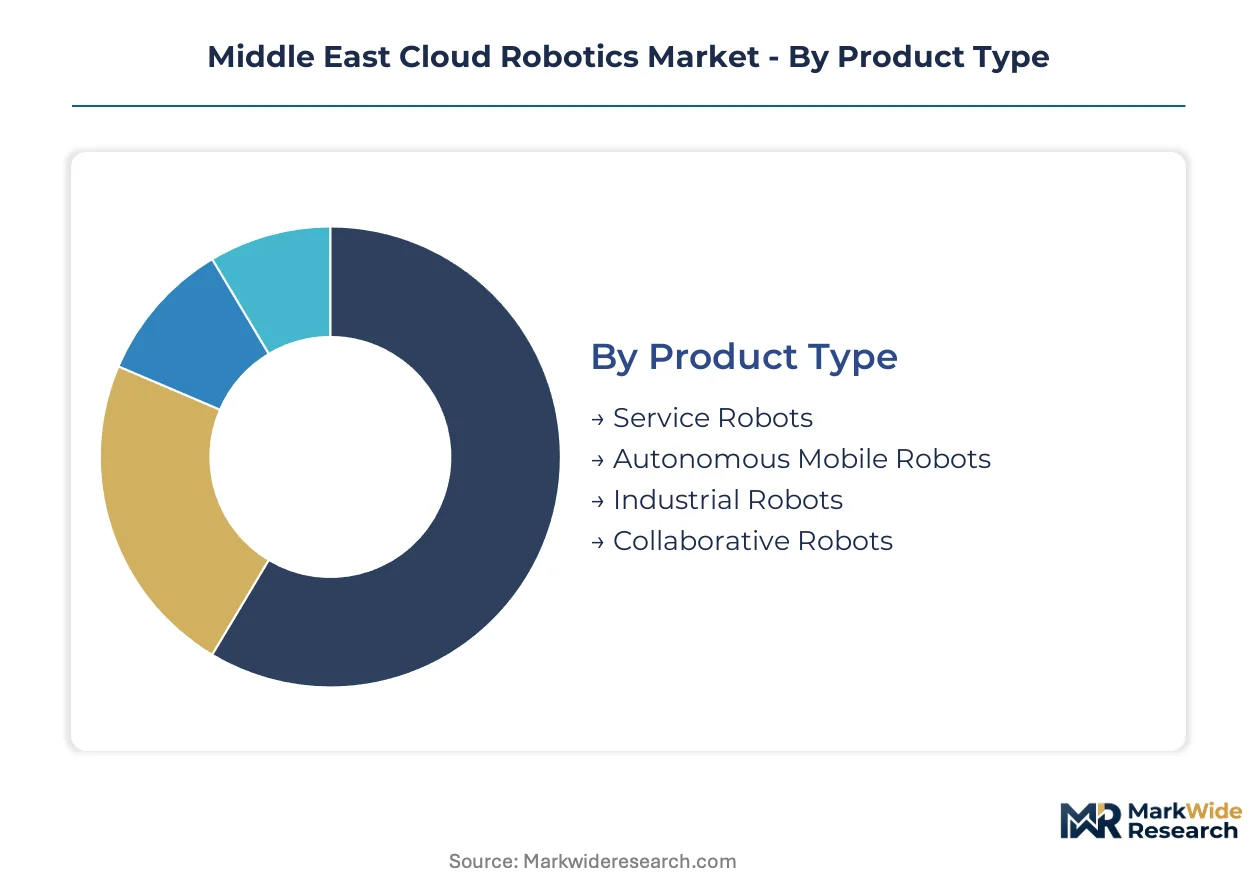
Cloud robotics segmentation in the Middle East reveals how regulatory requirements fragment across use cases. Product certification timelines, data sovereignty mandates, and latency specifications determine which segments achieve commercial traction first.
Product Type:
Certification burdens vary sharply: Industrial robots face BIS-equivalent conformity assessment cycles extending four to eight months, while healthcare service robots trigger MOHAP and Saudi FDA data localization requirements doubling deployment capital.
- Industrial Robots:Heavy-duty articulated arms and Cartesian systems dominate petrochemical and metal fabrication installations across Gulf Cooperation Council states. Saudi Aramco and SABIC facilities anchor demand for cloud-connected predictive maintenance, though East Asian controller supply chains expose operators to shipping volatility.
- Autonomous Mobile Robots:Warehouse automation fleets navigate dynamic fulfillment environments through LiDAR and camera fusion. Jebel Ali and Riyadh logistics zones compress procurement timelines as e-commerce operators demand goods-to-person picking within twelve-month integration windows.
- Service Robots:Disinfection and delivery units serve hospital and hospitality settings under MOHAP medical device pathways.
- Collaborative Robots:Force-limited arms enable human-robot interaction in small-batch manufacturing without protective fencing.
Leading the category by volume: Industrial Robots. Growing fastest: Autonomous Mobile Robots.
Application:
Application segments stratify by operational expenditure tolerance and integration complexity, with logistics operators preferring subscription fleet models and manufacturing favoring capital purchases.
- Logistics:Third-party operators in Dubai and Riyadh negotiate unit-per-pick pricing bundling hardware, software, and maintenance. Seasonal volume fluctuations drive preference for operational expenditure alignment over perpetual licensing.
- Healthcare:Surgical and rehabilitation robots absorb the highest data sovereignty compliance costs as MOHAP and Saudi FDA mandate in-country cloud infrastructure. Dubai and Riyadh data center investments pass through to hospital procurement contracts.
- Manufacturing:Petrochemical and metal fabrication facilities deploy edge-cloud hybrid architectures for mission-critical perception.
- Agriculture:Precision spraying and harvesting automation remains nascent across Gulf desert agriculture projects.
Highest contract values concentrate in Healthcare. Steepest expansion trajectory: Logistics.
End User:
End user economics diverge by procurement authority structure, with state-backed entities compressing vendor timelines and private retail operators demanding flexible scaling.
- Hospitals:Ministry of Health and Prevention (MOHAP) registration pathways streamline medical device approval for cloud-connected therapeutic systems. Saudi FDA parallel tracks extend compliance documentation for cross-border deployments.
- Manufacturing Facilities:Vision 2030 localization mandates compel international vendors to establish in-country cloud infrastructure and technical support centers, reshaping vendor economics toward recurring service contracts.
- Retail:E-commerce fulfillment centers drive subscription-based fleet management displacement of perpetual licensing.
- Entertainment:Theme park and hospitality robotics face lighter regulatory burdens but fragmented procurement authority.
Deepest regulatory complexity: Hospitals. Fastest procurement cycle compression: Manufacturing Facilities.
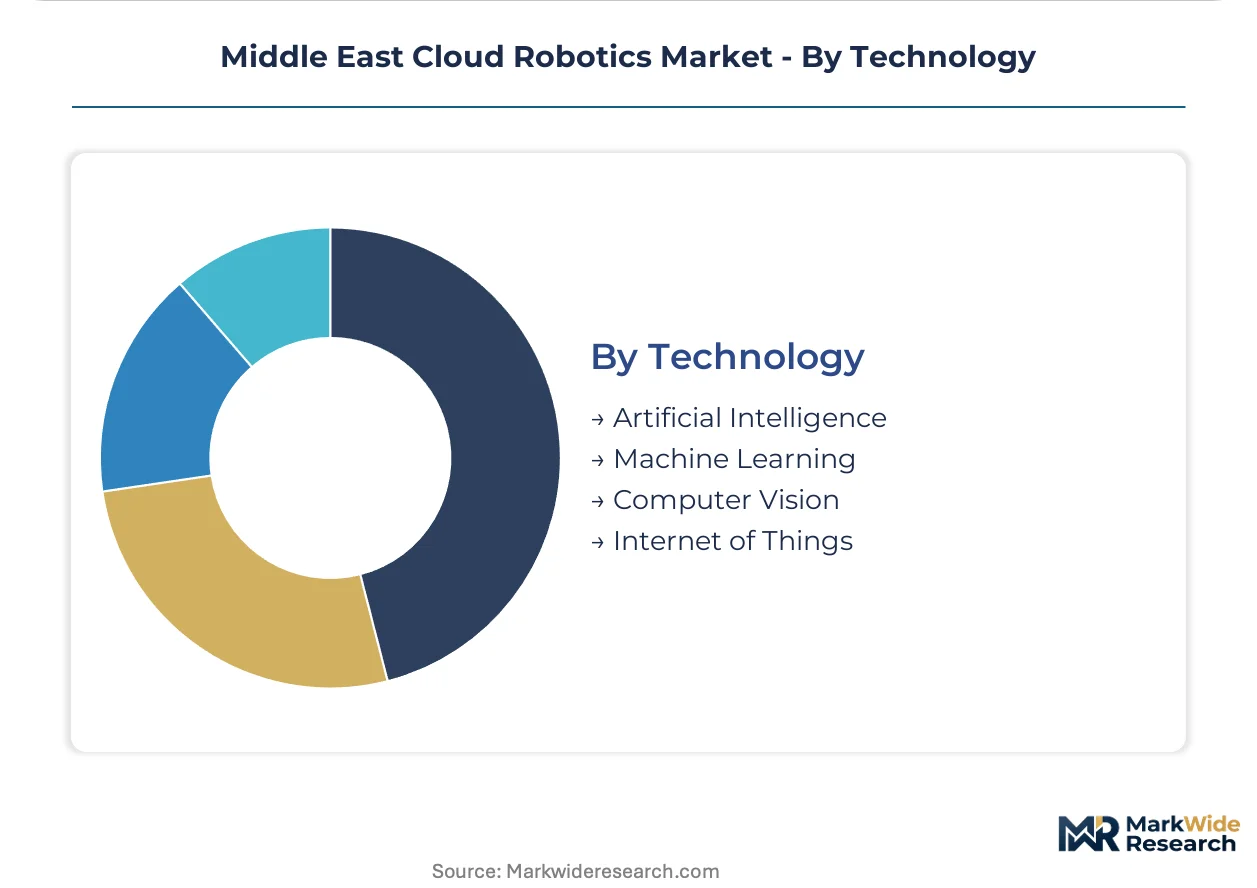
Technology:
Technology layers concentrate margin pools in software licensing, with hardware-integrated edge-cloud hybrids capturing premium pricing for sub-50ms latency requirements.
- Artificial Intelligence:Arabic-language operational data training creates competitive differentiation for regional orchestration platforms. G42 and similar vendors compete through AI-native fleet management trained on Gulf-specific logistics patterns.
- Computer Vision:Real-time sensor fusion enables predictive maintenance services extending contract values beyond hardware sales. Containerized perception modules swap between on-device inference and cloud-based model refinement based on latency tolerance.
- Machine Learning:Centralized fleet learning architectures improve pick accuracy and path planning across distributed warehouse deployments.
- Internet of Things:5G and fiber backhaul connectivity modules enable real-time robot coordination in private network environments.
Widest margin capture: Artificial Intelligence. Fastest capability iteration: Computer Vision.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Middle East consumes cloud robotics systems faster than regional production capacity can supply, creating dependency on East Asian controller manufacturing and European industrial software licensing.
Saudi Arabia
Vision 2030 localization mandates compel international vendors to establish Riyadh-based cloud infrastructure and technical support centers. Saudi FDA data sovereignty requirements for healthcare robots double deployment capital versus foreign-hosted alternatives. Jubail Industrial City and King Abdullah Economic City anchor petrochemical and logistics automation clusters where state-backed entities compress procurement timelines to twelve-month windows.
United Arab Emirates
Dubai's Jebel Ali logistics zone drives warehouse automation demand through e-commerce fulfillment center proliferation. MOHAP medical device registration pathways streamline surgical and rehabilitation robot approvals while mandating in-country cloud hosting for patient data. Abu Dhabi's KIZAD industrial zone concentrates manufacturing automation investments alongside sovereign wealth fund-backed technology partnerships.
Qatar
Mesaieed Industrial City and Ras Laffan anchor energy sector robot deployments for remote pipeline inspection and predictive maintenance. The country's national communications regulator allocates private 5G spectrum for industrial automation, enabling sub-50ms latency connectivity for real-time fleet coordination. Lusail smart city infrastructure creates demand for service robots in hospitality and municipal applications.
Oman
Sohar and Duqm port and manufacturing clusters remain underpenetrated by cloud robotics infrastructure, creating first-mover positioning for warehouse and inspection automation vendors. The Special Economic Zone Authority at Duqm offers streamlined customs procedures that reduce East Asian hardware import delays. Salalah Free Zone logistics operators are piloting autonomous mobile robots for transshipment cargo handling.
Kuwait
Al-Zour refinery and Northern Gateway logistics zone projects generate industrial automation procurement from state oil and transport entities. The national industrial development authority promotes domestic manufacturing diversification that extends robot deployment beyond hydrocarbon sectors. Shuwaikh Port modernization plans include automated container handling systems requiring cloud-connected coordination architectures.
Middle East Cloud Robotics Market Competitive Landscape
Top-tier vendors anchor industrial automation portfolios, while regional AI specialists and telecom infrastructure providers compete through localized service capabilities. The market structure stratifies across three tiers: multinational industrial conglomerates with decades of installed base, Gulf-based technology groups leveraging sovereign partnerships, and emerging orchestration software vendors. Strategic differentiation concentrates in AI-native fleet management, private 5G network integration, and predictive maintenance service bundling. Competitive moves center on in-country data center establishment to satisfy MOHAP and Saudi FDA localization mandates, plus subscription-based pricing transitions that displace perpetual licensing.
Within the industrial automation tier, ABB and Fanuc Corporation exemplify hardware-integrated service models extending predictive maintenance contracts beyond equipment sales. Huawei Technologies anchors cloud connectivity infrastructure through regional telecom assets. G42 occupies a distinct position as an AI-native orchestration specialist trained on Arabic-language operational data. These three represent the competitive archetypes—industrial incumbent, infrastructure-anchored platform, and regional AI pure-play—that shape vendor selection criteria across Saudi and Emirati procurement processes.
| Leading Market Players |
|---|
| CloudMinds |
| Huawei Technologies |
| Rockwell Automation |
| ABB |
| Fanuc Corporation |
| KUKA |
| Omron Corporation |
| Yaskawa Electric Corporation |
| G42 |
| Others |
Value Network & Pricing Analysis
East Asian controller component indices cascade through Middle East cloud robotics procurement, compressing margin pools for Gulf deployers while amplifying pricing power for vendors with captive manufacturing. Subscription-based fleet management software partially offsets hardware margin erosion, though data sovereignty compliance costs double deployment capital for healthcare segments.
Pricing Analysis
Margin tightening in healthcare robotics reflects MOHAP and Saudi FDA in-country cloud infrastructure mandates. Three-tier pricing structure across mission-critical, standard, and economy levels stratifies by latency tolerance and certification grade. Cost compression in industrial segments accelerates because East Asian supply chain volatility extends lead times. Third-party logistics operators exhibit highest price sensitivity, negotiating unit-per-pick operational expenditure models.
Supply Chain Analysis
Single-source vulnerability sits with Taiwan and South Korea for industrial robot controllers and LiDAR sensors. Robot system architectures draw from Japanese servo motors, German precision gearboxes, and Chinese battery modules. Tariff exposure concentrates on customs clearance delays through Jebel Ali and Dammam ports. Distribution runs through regional system integrators with sovereign wealth fund partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a cost-of-compliance story where MOHAP data localization mandates erect barrier-to-entry moats for healthcare robotics vendors with established Dubai and Riyadh infrastructure.
For Market Incumbents: Extend predictive maintenance service contracts beyond hardware sales to capture recurring revenue from Saudi Aramco and SABIC installations. Deepen backward integration into edge computing modules to offset East Asian controller supply volatility. Certify additional product lines under BIS-equivalent conformity assessment procedures before Gulf Cooperation Council regulatory tightening accelerates. For New Entrants and Emerging Players: AI-native Arabic-language orchestration platforms offer technology-first positioning against multinational industrial conglomerates. Underpenetrated Omani industrial zones at Sohar and Duqm present lowest competitive density for warehouse automation first-movers. Pursue direct partnerships with Special Economic Zone Authority at Duqm for streamlined hardware import pathways. For Investors and Strategic Acquirers: Distressed-cycle entries favor regional AI pure-plays with sovereign wealth fund relationships in Abu Dhabi and Riyadh. Long-term viability hinges on in-country data center establishment ahead of Saudi FDA enforcement expansion. Watch private 5G spectrum allocation decisions as inflection indicator for real-time fleet coordination viability.| Strategic Initiative | Industry Significance |
|---|---|
| In-Country Data Center Establishment | MOHAP compliance enables healthcare robot procurement from Dubai hospital systems. |
| AI-Native Fleet Management Platform | Arabic-language training differentiates G42 against Huawei's infrastructure-anchored position. |
| Private 5G Network Partnership | Sub-50ms latency connectivity unlocks petrochemical facility multi-robot coordination contracts. |
| Subscription Pricing Transition | Unit-per-pick models align Jebel Ali logistics operator costs with seasonal e-commerce volumes. |
| Predictive Maintenance Service Bundle | Edge-cloud hybrid architectures extend ABB contract values beyond industrial robot hardware sales. |
Research Methodology
Multi-period observation of private 5G spectrum allocations, MOHAP registration pathway timelines, and Vision 2030 localization mandate progress anchored the trend analysis, supplemented by interviews with robotics procurement officers at Saudi Aramco, biomedical engineers at Dubai Health Authority facilities, warehouse operations directors at Jebel Ali third-party logistics providers, and system integration specialists with Gulf sovereign wealth fund partnerships. Secondary validation drew from Saudi FDA medical device filings, UAE Telecommunications and Digital Government Regulatory Authority spectrum disclosures, GCC customs trade data, and industrial automation vendor SEC filings. Bottom-up deployment volume estimates triangulated against top-down addressable facility counts across Jubail Industrial City, King Abdullah Economic City, KIZAD, and Mesaieed Industrial City.
Input-output matrices mapped robot controller supply constraints against fulfillment center automation demand curves across the projection horizon. Segmentation dimensions modeled include product type, application, end user, and technology layer alongside deployment latency tolerance thresholds. CAGRs were derived from S-curve adoption modeling fitted to historical industrial automation penetration patterns. Forecast inputs incorporated East Asian shipping volatility indices and Gulf Cooperation Council data localization enforcement probability assessments.
Several conditions sit outside the modeled scope, including potential relaxation of Saudi FDA data sovereignty requirements, breakthroughs in on-device inference eliminating cloud dependency, and geopolitical disruptions to Taiwan semiconductor supply chains. Forecasts reflect documented assumptions about private 5G rollout schedules and regulatory enforcement consistency. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
GCC AUV Market
Robotics and Automation
North America Agricultural Robots and Mechatronics Market
Robotics and Automation
Automated Facade Contact Cleaning Robot Market
Robotics and Automation
AI Powered Robot Market
Robotics and Automation
Canada Cloud Robotics Market
Robotics and Automation
Drone Package Delivery Market
Robotics and Automation
Household Robots Market
Robotics and Automation
APAC Service Robots Market
Robotics and Automation
Asia Pacific Industrial Robots Market
Robotics and Automation
AGV Dispatch Management Platforms Market
Robotics and Automation
Global Indoor Robots Market
Robotics and Automation
Robotic Process Automation in BFSI Market
Robotics and Automation
Robot Operating System Market
Robotics and Automation
Retail Robotics Market
Robotics and Automation
Professional Service Robots Market
Robotics and Automation
Industrial Robotics Market