
 Global Automotive Gesture Recognition System Market | 2026-2036
Global Automotive Gesture Recognition System Market Size, Share, and Industry Trends Forecast 2026-2036
Global Automotive Gesture Recognition System Market Intelligence
Revenue from physical button and dial interfaces is narrowing as gesture recognition systems become standard in mid-range and luxury vehicles. Continental AG leverages its deep integration with OEMs to secure long-term supply contracts for sensor modules. Visteon Corporation differentiates through its focus on integrated human-machine interface (HMI) platforms. NXP Semiconductors sustains its market position by providing powerful processing chips essential for real-time gesture interpretation.
An automotive gesture recognition system is a human-machine interface using sensors to interpret occupant hand movements as commands. These systems typically employ Time-of-Flight (ToF) sensors to capture 3D spatial data for controlling vehicle functions. In-car infotainment control commands the largest application share, while safety-related gesture use is expanding. Machine learning technology is foundational for system accuracy, displacing older signal processing methods.
Europe's General Safety Regulation influences HMI design to minimize driver distraction, shaping system development. In the United States, NHTSA guidelines on distracted driving provide a framework for implementation. Functional safety standards like ISO 26262 are critical for systems linked to core vehicle controls. The key decision for suppliers and OEMs is how to balance feature richness with the imperative to avoid driver cognitive overload.
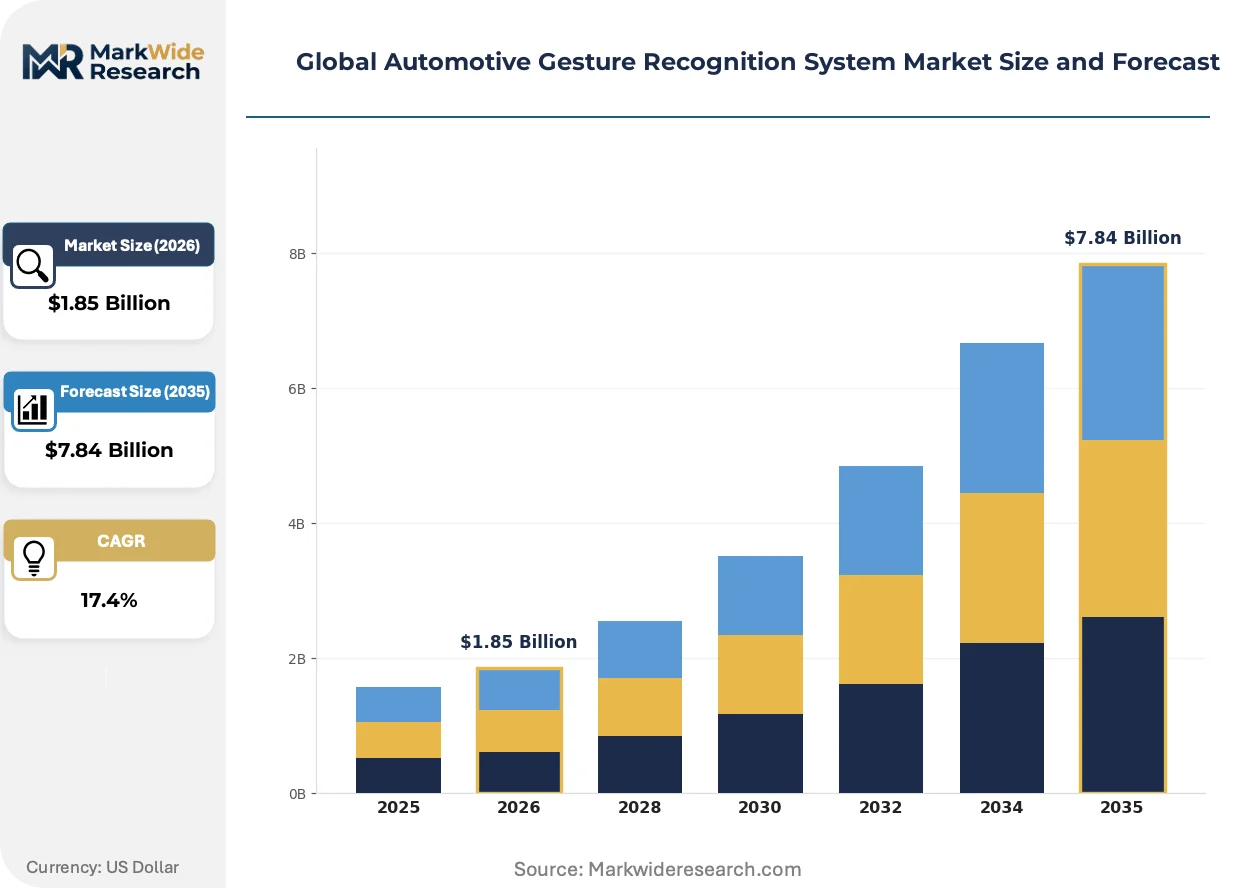
Market Dynamics
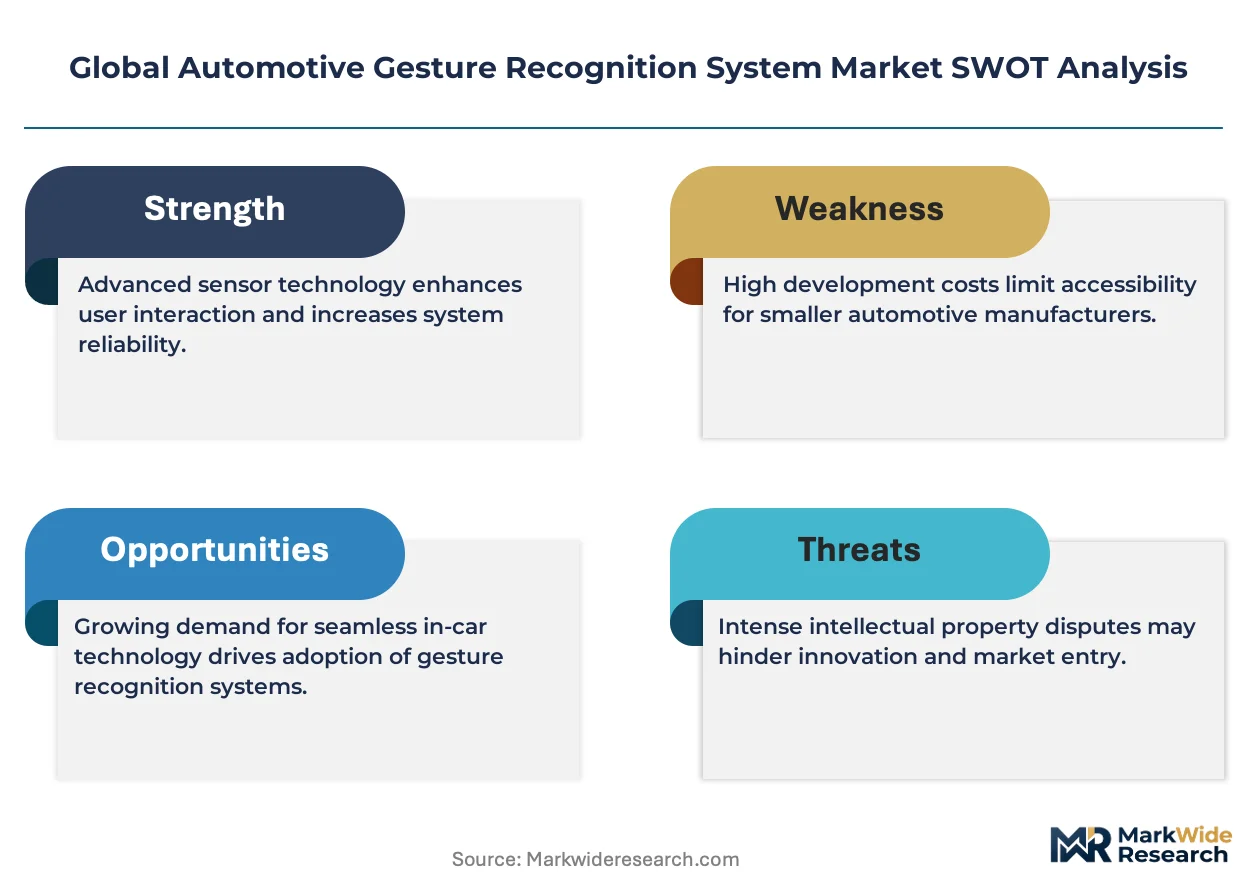
The central force shaping the market is the imperative for automakers to balance the integration of feature-rich HMI against stringent safety regulations designed to minimize driver distraction, such as those from the United States' NHTSA and Germany's KBA.
Growth Catalysts
- Machine Learning Advancement:Improvements in neural network models are enhancing gesture interpretation accuracy and speed, making systems more reliable and intuitive for drivers to use across various in-cabin environments.
- Consumer UX Expectations:Demand from buyers in the luxury and premium vehicle segments for sophisticated, seamless in-cabin technology is compelling automakers to standardize gesture control as a key feature.
- Safety Regulation Influence:Europe's General Safety Regulation encourages HMI designs that reduce the need for drivers to look away from the road, favoring hands-free control systems for infotainment and secondary functions.
Market Restraints
- High System Costs:The requisite Time-of-Flight sensors and powerful processors add significant cost, limiting the economic viability of these systems in mass-market, economy vehicle segments.
- Gesture Inconsistency:A lack of standardized gesture commands across different vehicle brands leads to user confusion and a steep learning curve, hindering widespread consumer acceptance and creating usability friction.
- Performance in Variable Conditions:System accuracy can be compromised by challenging lighting, occupant occlusions, or rapid movements, leading to frustrating false positives or missed commands for the user.
Strategic Opportunities
- Commercial Vehicle Integration:A significant opportunity exists to adapt gesture recognition for cockpits in long-haul trucks and buses, enhancing safety and operational efficiency by reducing driver physical and cognitive load.
- Interior Occupant Monitoring:Systems can be expanded beyond simple commands to monitor driver drowsiness or passenger well-being, creating new safety and comfort-related value propositions for OEMs.
- Augmented Reality HUDs:Combining gesture controls with augmented reality heads-up displays allows for more intuitive, direct manipulation of virtual information overlaid on the driver's real-world view.
Industry Challenges
- ISO 26262 Compliance:Achieving the necessary Automotive Safety Integrity Level (ASIL) for gesture systems that control critical functions is a complex, costly, and lengthy validation process for suppliers.
- Software Integration Complexity:Ensuring flawless interoperability between the gesture recognition software stack and the diverse, often proprietary, infotainment systems of various OEMs is a persistent engineering challenge.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Automotive Gesture Recognition System Market |
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $7.84 Billion |
| CAGR (2026 – 2036) | 17.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Infrared Sensors, Ultrasonic Sensors, Capacitive Sensors, Time-of-Flight Sensors, Radar Sensors Technology: Machine Learning, Deep Learning, Computer Vision, Sensor Fusion, Signal Processing Application: In-Car Infotainment Control, Navigation Adjustment, Climate Control, Safety and Security, Gesture-Based Communication End User: OEMs, Automotive Tier-1 Suppliers, Dealerships, Aftermarket Providers |
| Companies Covered | Continental AG, Synaptics Incorporated, Visteon Corporation, NXP Semiconductors, Harman International, Robert Bosch GmbH, Denso Corporation, Valeo S.A., Sony Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Automotive Gesture Recognition System Market Strategic Shifts & Innovations
The convergence of multi-modal sensor inputs and sophisticated machine learning models is defining the next generation of in-cabin human-machine interfaces. This evolution moves beyond simple commands toward creating a more intuitive and context-aware interaction between the driver and the vehicle.
Multi-modal HMI is a key product evolution, combining gesture recognition with voice commands and haptic feedback. Luxury and premium automakers are rapidly adopting this approach to create a more robust and redundant user interface. This multi-sensory input strategy is hybridizing the user experience, reducing reliance on any single interaction method and improving overall system reliability and user trust.
Forthcoming regulations like the EU AI Act introduce a risk-based framework for artificial intelligence systems, directly impacting gesture recognition development. This regulation compels developers to ensure and document system transparency, robustness, and human oversight, particularly for functions tied to vehicle control. Tier 1 suppliers are most affected, now embedding compliance-by-design principles into their machine learning pipelines to meet European market requirements.
Automakers are increasingly unbundling gesture functionalities from the initial vehicle purchase, offering them as upgradable software features. This shift, enabled by over-the-air (OTA) update capabilities, disrupts the traditional fixed-feature sales model and creates new subscription-based revenue streams. This trend is most prominent in the software-defined electric vehicle segment, led by manufacturers in the United States and China.
Global Automotive Gesture Recognition System Market Segmentation
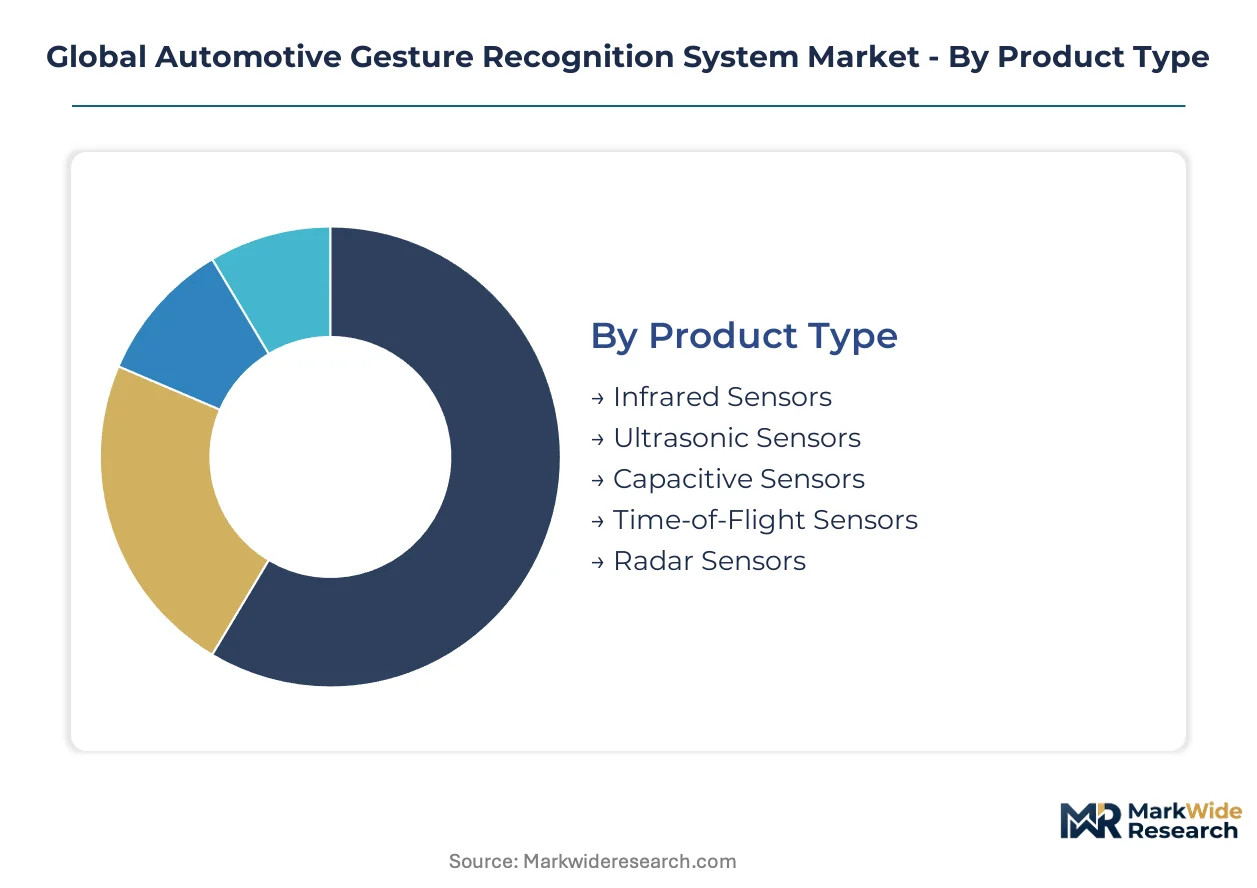
The segmentation of the global automotive gesture recognition system market reveals distinct pathways for technological advancement, application growth, and value chain participation. Understanding these classifications provides clarity on where innovation is concentrated and how market participants are differentiating their offerings.
Product Type:
The maturity spectrum of sensor technologies dictates their current adoption and future potential within automotive gesture recognition systems.
- Time-of-Flight Sensors:These sensors capture 3D spatial data by measuring the time light takes to travel to an object and back, forming the backbone for precise hand movement interpretation. Demand for ToF sensors concentrates in luxury vehicle segments, where their accuracy supports sophisticated in-cabin infotainment control systems.
- Radar Sensors:Utilizing radio waves to detect motion and distance, radar sensors offer robust performance in challenging lighting and environmental conditions, extending gesture recognition capabilities beyond visible light. Their integration is expanding in premium vehicles for advanced driver assistance systems (ADAS) and enhanced HMI functions.
- Infrared Sensors:These sensors detect heat signatures or reflect infrared light to identify hand positions, offering a cost-effective solution for basic gesture commands.
- Ultrasonic Sensors:Employing sound waves to measure distance, ultrasonic sensors provide proximity detection for simple gesture interactions, particularly in less demanding applications.
- Capacitive Sensors:Responding to changes in electrical fields caused by human touch or proximity, capacitive sensors are suitable for touch-sensitive surfaces and basic gesture inputs.
Time-of-Flight Sensors retains volume leadership; Radar Sensors holds the steepest expansion curve.
Technology:
The concentration of processing power and algorithmic sophistication defines the efficacy and responsiveness of gesture recognition technologies.
- Machine Learning:This technology enables systems to learn and adapt to diverse gesture patterns and user behaviors through data analysis, significantly improving interpretation accuracy over time. Machine learning is foundational for current generation systems, enhancing user experience in infotainment and climate control applications.
- Deep Learning:A subset of machine learning using neural networks with multiple layers, deep learning algorithms excel at processing complex visual data for highly nuanced gesture interpretation. Automakers are integrating deep learning to achieve superior recognition rates, even with partial occlusions or varied hand sizes.
- Computer Vision:Utilizing cameras and image processing algorithms, computer vision identifies and tracks hand movements, forming the visual input for many gesture systems.
- Sensor Fusion:This method combines data from multiple sensor types (e.g., ToF and radar) to create a more robust and reliable understanding of gestures, mitigating individual sensor limitations.
- Signal Processing:Traditional signal processing techniques filter and analyze raw sensor data to extract meaningful patterns, providing the initial layer of gesture detection.
Machine Learning drives the core functionality; Deep Learning represents a significant leap in system intelligence.
Application:
Customer type influences the feature set and priority of gesture recognition system applications within the vehicle cabin.
- In-Car Infotainment Control:This application allows occupants to manage media, navigation, and communication functions with hand gestures, minimizing physical contact with screens and buttons. The luxury vehicle segment drives demand for sophisticated infotainment gesture controls, integrating them as standard features.
- Safety and Security:Gesture systems can interpret driver states, such as drowsiness or distraction, or activate emergency functions with specific commands, enhancing occupant protection. Expanding use cases include driver monitoring and hands-free activation of critical alerts.
- Navigation Adjustment:Drivers can zoom, pan, or select destinations on navigation displays using specific hand movements, reducing visual distraction from the road.
- Climate Control:Gestures enable adjustments to temperature, fan speed, and air distribution, offering a touchless interface for cabin comfort settings.
- Gesture-Based Communication:This application facilitates interactions with virtual assistants or external vehicle systems through predefined hand signals.
In-Car Infotainment Control commands the largest market share; Safety and Security applications are gaining strategic importance.
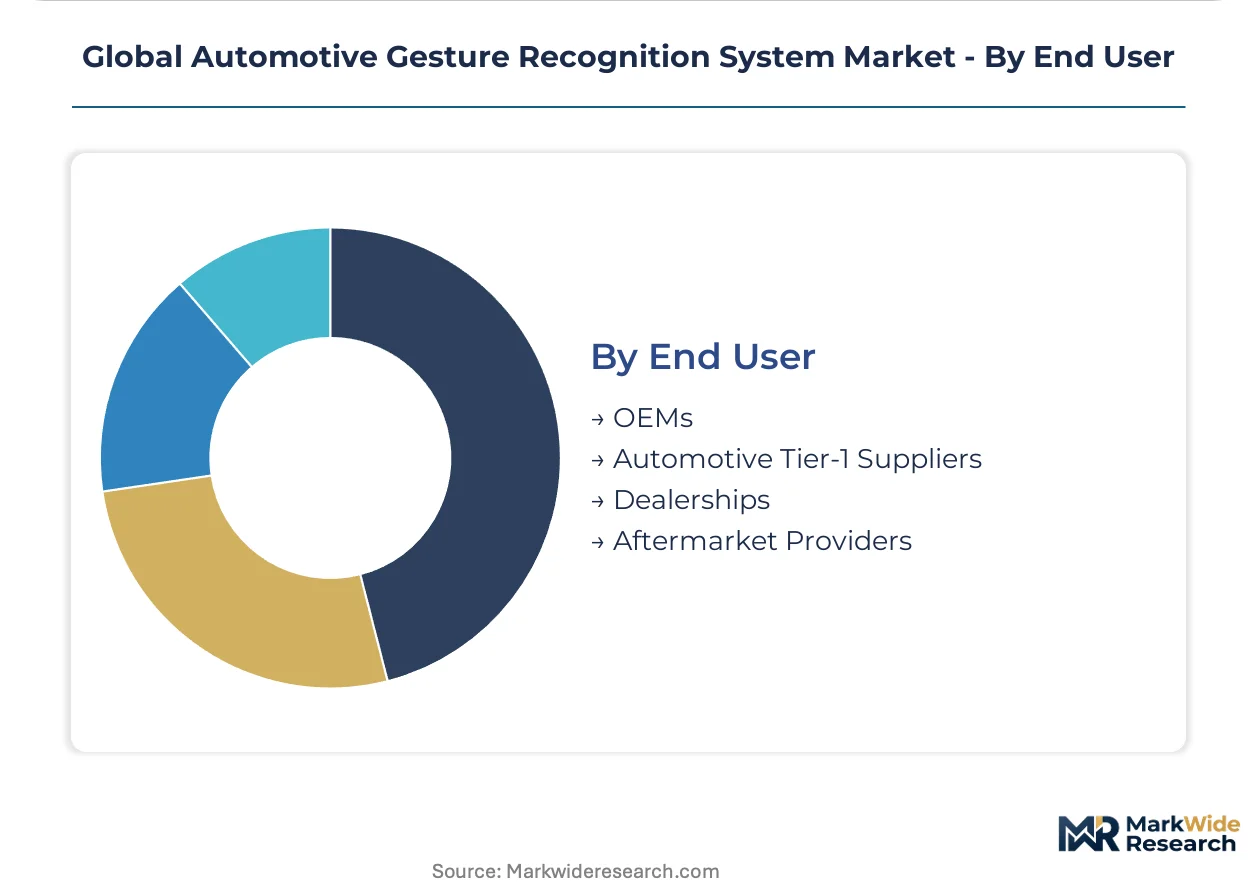
End User:
Margin structures across the automotive value chain determine the investment and integration strategies for gesture recognition systems.
- OEMs:Original Equipment Manufacturers integrate gesture recognition systems directly into vehicle designs during the production phase, often as standard or optional features. OEMs prioritize seamless integration with existing HMI platforms and compliance with global safety regulations like Europe's General Safety Regulation.
- Automotive Tier-1 Suppliers:These suppliers develop and manufacture complete gesture recognition modules and components for OEMs, leveraging their expertise in sensor technology and software integration. Tier-1 suppliers like Continental AG secure long-term supply contracts by offering robust, validated systems.
- Dealerships:Dealerships primarily sell vehicles equipped with pre-installed gesture recognition systems, providing customer education and initial support.
- Aftermarket Providers:Aftermarket companies offer retrofit gesture recognition solutions for older vehicles or specialized enhancements, catering to specific consumer demands.
OEMs drive initial system integration; Automotive Tier-1 Suppliers are crucial for technological development and supply chain stability.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for automotive gesture recognition systems exhibits varying price elasticity across global markets. Luxury vehicle segments in established economies demonstrate lower price sensitivity, readily integrating advanced features. Emerging markets, however, prioritize cost-effectiveness, influencing regional adoption patterns and technology deployment strategies.
Germany
Demand for sophisticated in-cabin technology is high among luxury vehicle manufacturers. The KBA influences HMI design to minimize driver distraction, shaping system development for new vehicle models. Stuttgart's automotive cluster focuses on integrating gesture systems as standard features in new premium models.
United States
Consumer UX expectations for seamless in-cabin technology drive adoption, particularly in software-defined electric vehicles. NHTSA guidelines on distracted driving provide a framework for safe implementation of advanced HMI. Silicon Valley and Detroit collaborate on developing next-generation gesture systems for autonomous vehicle integration.
China
The rapid growth of the software-defined electric vehicle segment fuels demand for advanced HMI solutions. Government initiatives support the domestic automotive industry's push for technological leadership, including AI-driven HMI. Shanghai and Shenzhen are hubs for EV manufacturers integrating gesture functionalities as upgradable software features.
Japan
Automakers prioritize precision and reliability in gesture recognition systems for premium vehicles. METI promotes innovation in automotive electronics, encouraging the development of robust sensor technologies. Toyota City and Yokohama's R&D centers focus on multi-modal HMI combining gestures with voice and haptic feedback.
South Korea
High consumer expectations for cutting-edge technology drive the integration of advanced gesture controls in new vehicle models. The country's strong focus on smart mobility solutions encourages the development of context-aware HMI. Seoul's tech ecosystem collaborates with major automotive OEMs on deep learning algorithms for superior gesture interpretation.
Global Automotive Gesture Recognition System Market Key Industry Players
Capability concentration sits with one tier; scale advantage sits with another, creating a tiered market structure. The automotive gesture recognition system market sees consolidation around established Tier-1 suppliers and semiconductor manufacturers. Key strategic archetypes include integrated HMI solution providers, sensor technology specialists, and processing chip developers. These entities primarily engage in strategic partnerships with OEMs and continuous technology licensing to maintain their market positions.
Within the integrated HMI solution provider archetype, Continental AG and Visteon Corporation exemplify established Tier-1 suppliers. Continental AG, a German stock corporation, represents those with deep OEM integration, securing long-term supply contracts for sensor modules. Visteon Corporation, an American entity, anchors the segment focused on comprehensive human-machine interface platforms, differentiating through their integrated approach. NXP Semiconductors, a Netherlands-based public limited company, sits within the critical processing chip developer category, providing powerful components essential for real-time gesture interpretation across various vehicle models.
| Leading Market Players |
|---|
| Continental AG |
| Synaptics Incorporated |
| Visteon Corporation |
| NXP Semiconductors |
| Harman International |
| Robert Bosch GmbH |
| Denso Corporation |
| Valeo S.A. |
| Sony Corporation |
| Others |
Cost & Logistics Intelligence
NXP Semiconductors' concentrated supply of powerful processing chips influences margin structures, benefiting Tier-1 suppliers who secure long-term contracts for integrated gesture modules. This upstream dependency shapes pricing power throughout the automotive value chain.
Pricing Analysis
Extended software feature subscriptions drive lifetime value for automotive gesture recognition systems. The dominant pricing model combines per-unit transactional sales for hardware modules with subscription-based access for advanced software functionalities. Price differentiation stems from the customization level offered to OEMs and the brand premium associated with luxury vehicle integration. Cost compression in mass-market segments intensifies due to the high system costs of Time-of-Flight sensors and powerful processors. Luxury vehicle manufacturers exhibit the lowest price sensitivity, while economy vehicle segments are highly price-sensitive.
Supply Chain Analysis
Specialized Time-of-Flight sensors and high-performance processing chips form the critical upstream feedstock for gesture recognition systems. Geographic supply concentration centers on semiconductor hubs in the Netherlands and sensor manufacturing in Japan, alongside Tier-1 integration in Germany and the United States. Single-source vulnerability for advanced AI-driven processing chips poses a structural risk for the automotive supply chain. Distribution runs directly from Automotive Tier-1 Suppliers to Original Equipment Manufacturers for seamless integration into vehicle platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The automotive gesture recognition market represents a high-growth disruption, driven by advancements in machine learning algorithms that enhance accuracy and user experience. This technological inflection is reshaping in-cabin human-machine interfaces.
For Market Incumbents: Build deep OEM integration through long-term supply contracts for sensor modules and integrated HMI platforms. Invest heavily in achieving ISO 26262 ASIL compliance for critical functions to counter regulatory threats from the EU AI Act. Expand multi-modal HMI offerings, combining gesture with voice and haptic feedback, to differentiate against emerging software specialists. This strategy leverages existing relationships and R&D in sensor fusion.
For New Entrants and Emerging Players: Build out specialized software solutions for commercial vehicle integration, enhancing safety and operational efficiency in long-haul trucks. Target the software-defined electric vehicle segment by offering gesture functionalities as upgradable software features via over-the-air updates. Focus on interior occupant monitoring applications, which offer new safety and comfort value propositions. A go-to-market angle could involve partnering with smaller EV manufacturers in China and the United States.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with technology specialists focused on advanced machine learning algorithms for gesture interpretation. Long-term viability for this market is strong over a 5-10 year window, driven by the continuous evolution of in-cabin HMI. Acquisition targets should include niche software developers excelling in deep learning for nuanced gesture recognition or sensor fusion capabilities. The signal to watch is the increasing adoption of multi-modal HMI solutions and the formalization of global gesture command standards.
| Strategic Initiative | Industry Significance |
|---|---|
| Software-Defined Vehicle Investment | OEMs prioritize software capabilities for new revenue streams and feature upgrades via OTA updates. |
| Sensor Fusion Technology Development | Tier-1 suppliers combine ToF and radar data to enhance system reliability and accuracy. |
| ISO 26262 ASIL Compliance | Suppliers invest in rigorous validation to integrate gesture systems into critical vehicle controls. |
| Multi-Modal HMI Platform Integration | Automakers blend gesture, voice, and haptic feedback for a more intuitive user experience. |
| Commercial Vehicle Application Pilot | Technology providers adapt gesture systems for long-haul trucks to improve driver safety and efficiency. |
Research Approach
Cross-validation between primary interviews and extensive secondary validation anchors the qualitative findings of this study. Primary data was gathered from OEM platform engineers, Tier-1 procurement leads, semiconductor R&D directors, and automotive software architects. Secondary sources included NHTSA guidelines, the EU General Safety Regulation, ISO 26262 standards, and corporate financial filings. A rigorous bottom-up and top-down triangulation approach ensured data consistency and accuracy.
Market size estimates were calibrated against historical data and industry benchmarks across the analysis window. The analytical framework modeled segmentation dimensions including product type, technology, application, end user, and specific vehicle segments. Compound annual growth rates were derived from regression analysis of historical trends and projected market drivers. Key forecast inputs included global vehicle production forecasts and HMI technology adoption rates.
Stress conditions across regulatory changes, technological breakthroughs, and macroeconomic shifts were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions, but unexpected shifts in consumer preferences or supply chain disruptions could revise projections. Cross-checking against industry association reports is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
Robotic Coffee Bars Market
Robotics and Automation
AGV Dispatch Management Platforms Market
Robotics and Automation
Global Smart Robots Market
Robotics and Automation
United Kingdom Cloud Robotics Market
Robotics and Automation
Automotive Robotics Market
Robotics and Automation
Household Robots Market
Robotics and Automation
Case and Box Handling Robots Market
Robotics and Automation
Asia-Pacific AUV Market
Robotics and Automation
Cybersecurity in Robotics Market
Robotics and Automation
Cordless Router Market
Robotics and Automation
Drone-Based NDT Inspection Systems for Energy and Infrastructure Assets Market
Robotics and Automation
Healthcare Mobile Robots Market
Robotics and Automation
Nanorobots in Healthcare Market
Robotics and Automation
Wearable Robotic Exoskeleton Market
Robotics and Automation
Europe Agricultural Robots and Mechatronics Market
Robotics and Automation
Robot Operating System Market