
 Latin America Cloud Robotics Market | 2026-2036
Latin America Cloud Robotics Market Size, Share, and Industry Trends Forecast 2026-2036
Latin America Cloud Robotics Market Analytics
Buyer concentration among Latin American automotive and electronics manufacturers is hardening as tier-one suppliers consolidate cloud robotics procurement under centralized IT governance. NVIDIA leverages its GPU-accelerated simulation platforms to dominate digital twin development for robotic fleets across Mexican maquiladoras. ABB sustains its installed base advantage through backward integration into motion control hardware that reduces latency for cloud-connected industrial arms. FANUC competes by anchoring its FIELD system architecture to local edge nodes in Brazilian foundries.
Latin America Cloud Robotics denotes distributed robotic systems that offload compute, storage, and AI inference to remote cloud infrastructure via low-latency connectivity, typically requiring sub-50ms response thresholds for real-time motion planning and sensor fusion processing. These systems serve industrial automation by enabling centralized fleet management, predictive maintenance analytics, and collaborative task allocation across geographically dispersed facilities. Industrial Robots retain the largest revenue share due to established deployment in automotive stamping and welding lines, while Collaborative Robots represent the fastest-expanding product category as small and mid-sized manufacturers in Mexico and Colombia adopt flexible human-robot workstations. Public Cloud deployment leads volume adoption among cost-sensitive enterprises, though Hybrid Cloud configurations are capturing margin pools from regulated sectors such as healthcare and aerospace that require on-premises data residency for sensitive operational telemetry.
Brazil's ANATEL spectrum policies and LGPD data localization mandates, alongside Mexico's NOM-001-SCFI cybersecurity standards and COFEPRIS guidelines for medical robotic systems, collectively elevate compliance costs for foreign platform providers while creating protected demand zones for localized cloud infrastructure operators. Argentina's CNDC data sovereignty requirements and Chile's SUBTEL 5G allocation frameworks further fragment the regulatory landscape across the region's largest economies. Stakeholders must monitor evolving national cloud certification regimes and spectrum auction timelines to determine optimal data center placement and partnership structures for robotic edge computing nodes.
Market Dynamics
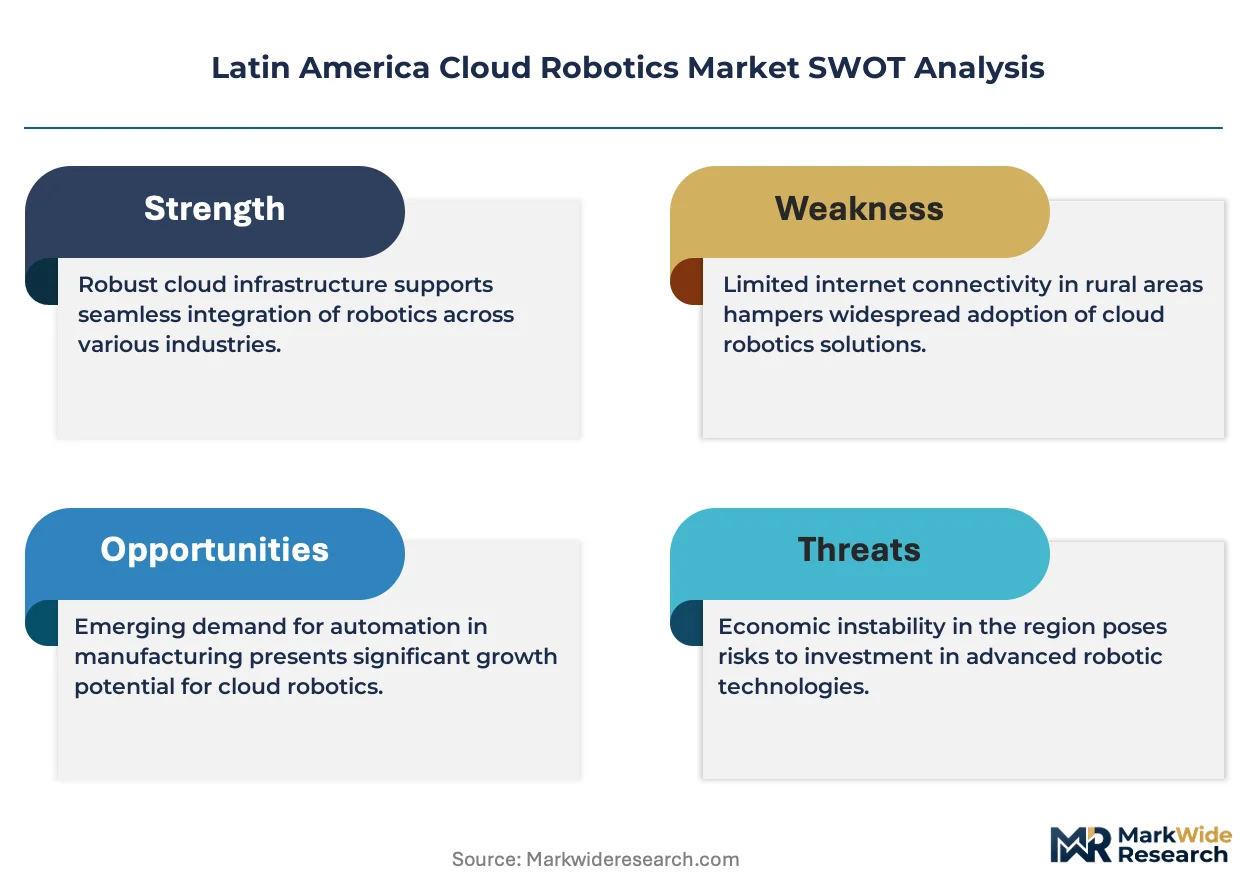
Data localization mandates across Brazil and Mexico are fragmenting cloud infrastructure requirements, forcing robotic fleet operators to deploy hybrid edge architectures that comply with national sovereignty frameworks while maintaining sub-50ms latency thresholds for real-time motion control.
Growth Catalysts
- 5G spectrum allocation:Brazil's ANATEL millimeter-wave auctions in São Paulo industrial corridors are enabling deterministic connectivity for cloud-connected collaborative robots in automotive stamping facilities.
- LGPD compliance infrastructure:Brazilian manufacturers are procuring localized cloud nodes to process robotic telemetry without cross-border data transfer, creating protected demand zones for domestic data center operators.
- Aerospace cluster concentration:Mexico's Querétaro precision manufacturing hub is consolidating cloud robotics procurement for turbine blade machining, driving fleet standardization among tier-one suppliers.
Market Restraints
- Edge hardware import dependencies:GPU-accelerated inference accelerators face concentrated supply from East Asian foundries, exposing Brazilian integrators to extended lead times for real-time motion planning modules.
- LGPD-NOM regulatory misalignment:Divergent data residency requirements between Brazil and Mexico prevent unified cloud architectures across Andean manufacturing networks, inflating compliance overhead for multi-country operators.
- Industrial Ethernet substitution:Proprietary fieldbus protocols in legacy Brazilian foundries resist cloud-native retrofitting, delaying fleet virtualization projects.
Strategic Opportunities
- Colombian mid-market penetration:Bogotá's emerging electronics assembly sector remains underserved by cloud-native collaborative workstations, offering first-mover positioning for flexible human-robot cell providers.
- AI Act convergence:Anticipated alignment between EU AI Act risk classifications and Chilean SUBTEL guidelines could streamline certification for European cloud robotics vendors entering Santiago's mining equipment automation market.
- Edge-cloud orchestration:Convergence of containerized ROS2 middleware with serverless inference platforms is opening margin pools for hybrid deployment specialists serving Argentine CNDC-regulated pharmaceutical packaging lines.
Industry Challenges
- Multi-protocol integration:Brazilian integrators struggle to harmonize OPC-UA telemetry streams from legacy Siemens PLCs with cloud-native MQTT brokers for predictive maintenance analytics.
- Certification timeline compression:COFEPRIS medical device pathways for surgical cloud robotics in Mexican hospitals extend validation cycles beyond typical venture capital runway horizons.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latin America Cloud Robotics Market |
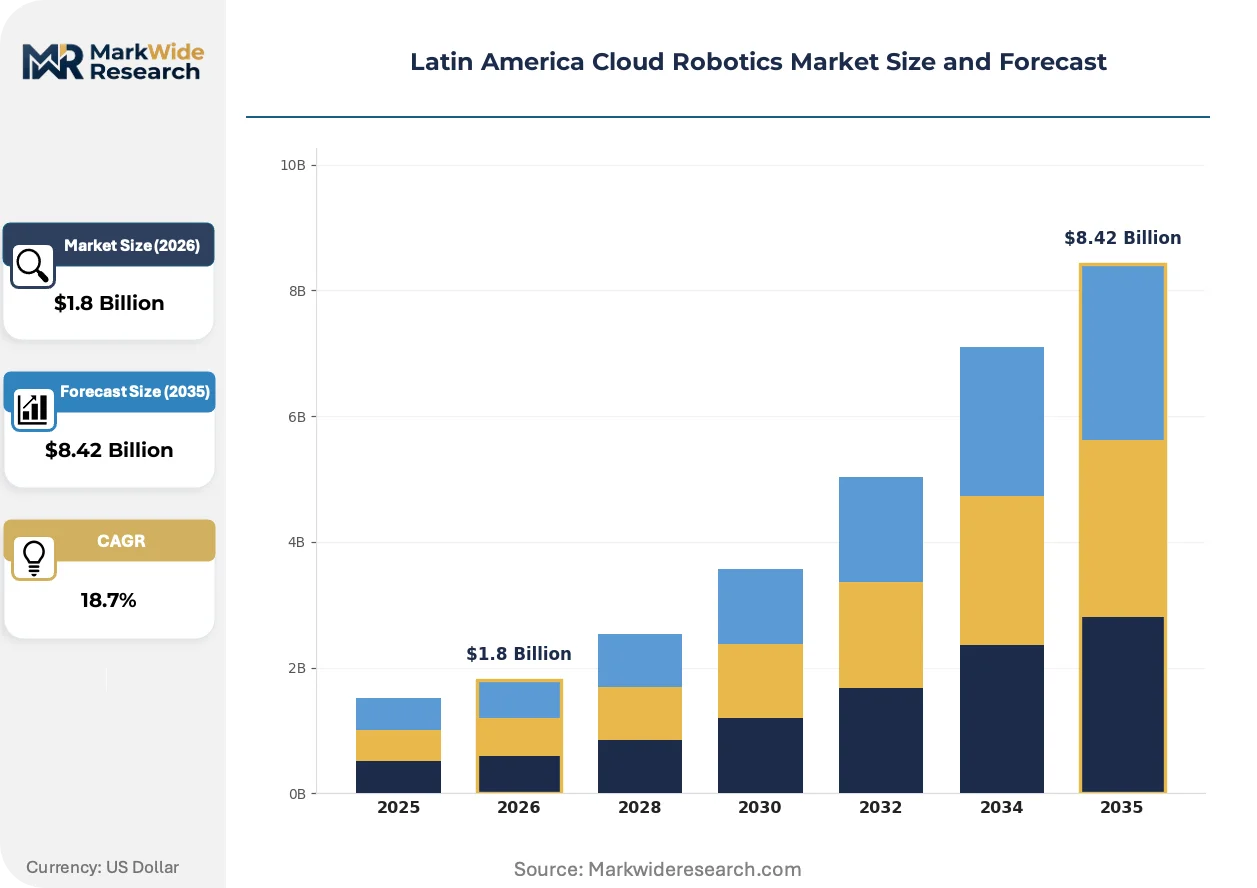
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $8.42 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Industrial Robots, Service Robots, Collaborative Robots, AGVs Technology: AI, Machine Learning, Computer Vision, Sensor Fusion End User: Manufacturing, Healthcare, Retail, Logistics Deployment: Public Cloud, Private Cloud, Hybrid Cloud, Multi-Cloud |
| Companies Covered | ABB, CloudMinds, NVIDIA, FANUC, IBM, Microsoft Corporation, Clearpath Robotics, Rapyuta Robotics, Rockwell Automation, Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latin America Cloud Robotics Market Evolving Landscape
Containerized robot operating system middleware is displacing monolithic control architectures, enabling modular software updates across geographically dispersed industrial fleets without production line downtime.
Digital twin simulation platforms are automating offline programming for cloud-connected robotic arms in Mexican maquiladoras, compressing deployment timelines from weeks to days. Tier-one automotive suppliers in Querétaro are adopting these tools at accelerating pace. The technology is automating validation workflows that previously required physical prototype iterations.
Brazil's LGPD enforcement actions against unauthorized cross-border data transfers are compelling cloud robotics operators to deploy sovereign edge nodes within ANATEL-licensed facilities. Industrial automation vendors must now maintain separate infrastructure stacks for Brazilian versus Mexican deployments. Healthcare and aerospace sectors in São Paulo are responding by procuring certified local cloud capacity at premium pricing.
Consolidated IT governance models among Latin American automotive OEMs are displacing decentralized plant-level robotics procurement. Centralized technology committees in Brazil's southeast manufacturing belt now mandate cloud platform standardization across supplier networks. Electronics contract manufacturers in Guadalajara are adapting by certifying single-vendor fleet management solutions to maintain preferred supplier status.
Latin America Cloud Robotics Market Segmentation
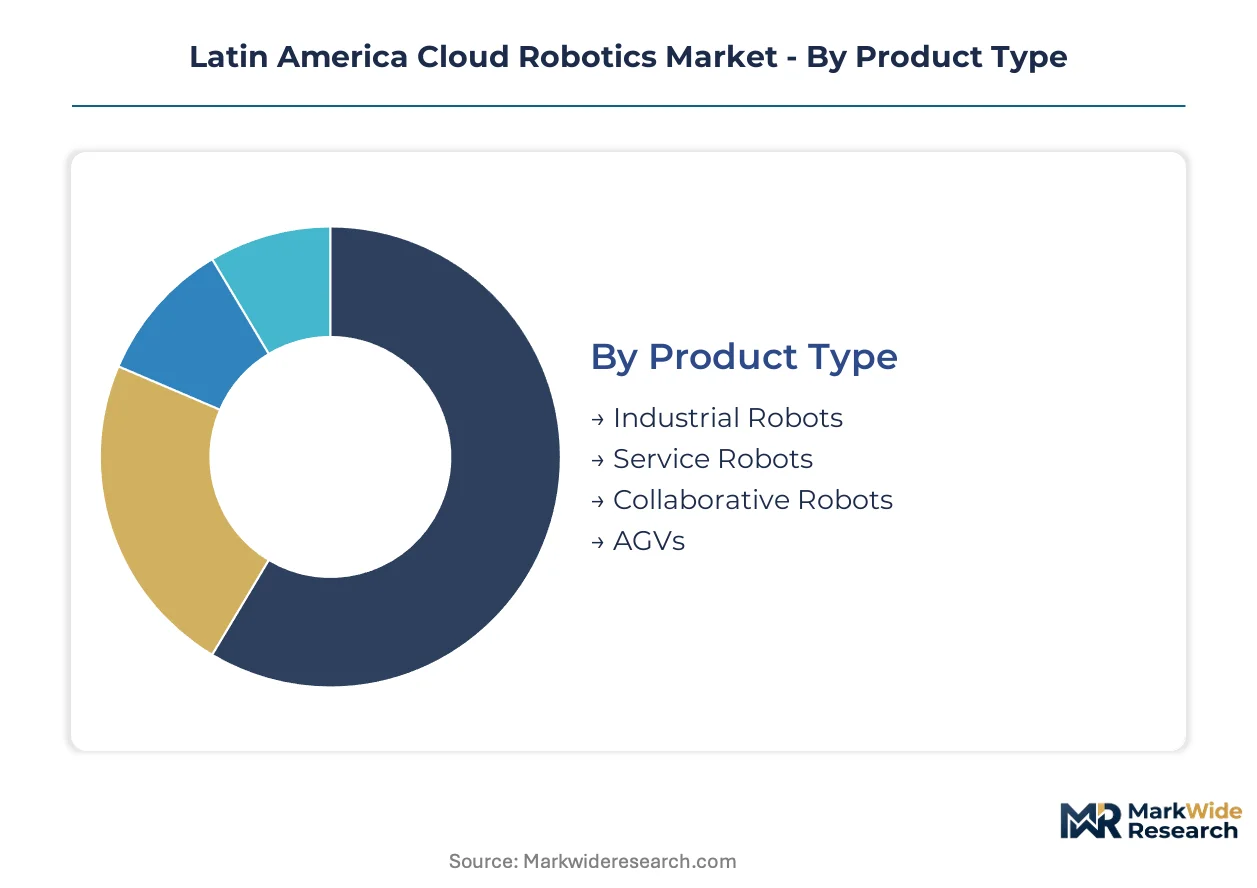
Cloud robotics segmentation in Latin America reveals divergent capital requirements across hardware, software, and infrastructure layers. Procurement committees weigh upfront robot costs against recurring cloud compute commitments when standardizing fleet architectures across Brazilian and Mexican facilities.
Product Type:
Capital intensity varies sharply across robot categories, with industrial arms demanding the highest upfront investment in motion control hardware and cloud-edge integration.
- Industrial Robots:Heavy-payload articulated arms with six-plus degrees of freedom dominate automotive stamping lines in São Paulo's ABC industrial corridor. Brazilian OEMs consolidate procurement of these systems under centralized IT governance to ensure cloud platform compatibility across supplier networks.
- Collaborative Robots:Force-limited manipulators with integrated torque sensors enable fenceless human-robot workstations in Guadalajara electronics assembly plants. Mexican mid-market manufacturers favor these systems for flexible redeployment without extensive safety infrastructure.
- Service Robots:Autonomous mobile platforms for facility inspection and cleaning operate in Brazilian hospital complexes under LGPD-regulated data processing constraints.
- AGVs:Laser-guided transport vehicles navigate warehouse aisles in Santiago distribution centers, offloading path planning to cloud-based fleet management systems.
Most installed capacity flows through Industrial Robots. Expansion is steepest in Collaborative Robots.
Technology:
Software layer investments concentrate on inference acceleration and real-time sensor integration, with compute costs scaling nonlinearly with fleet size.
- AI:Deep learning models for predictive maintenance run on GPU clusters in Mexican maquiladora cloud nodes, processing vibration telemetry from CNC-adjacent robotic arms. Argentine pharmaceutical packers deploy these capabilities under CNDC data sovereignty requirements.
- Machine Learning:Supervised learning pipelines optimize pick-and-place cycle times in Bogotá electronics assembly, training on historical motion traces stored in regional cloud instances.
- Computer Vision:Convolutional neural networks inspect turbine blade surface defects in Querétaro aerospace facilities, with inference latency constrained by NOM cybersecurity filtering.
- Sensor Fusion:Kalman-filtered integration of LiDAR, IMU, and encoder data enables centimeter-precision localization for cloud-coordinated AGV fleets in Brazilian retail distribution hubs.
AI commands the largest share of technology spending. Computer Vision is climbing the fastest as quality inspection demands intensify.
End User:
Application-specific compliance requirements fragment procurement patterns, with regulated sectors absorbing premium infrastructure costs.
- Manufacturing:Automotive and electronics producers in Brazil's southeast and Mexico's Bajío region drive volume demand, standardizing on hybrid cloud architectures to balance latency against LGPD-NOM data residency mandates.
- Healthcare:Surgical and rehabilitation robotics in Mexican hospitals face extended COFEPRIS certification timelines, compressing venture capital runway horizons for cloud-native system developers.
- Retail:Inventory-scanning mobile robots in Santiago and São Paulo shopping centers process visual data through public cloud pipelines with minimal regulatory friction.
- Logistics:Last-mile sortation facilities in Colombian free trade zones deploy cloud-coordinated robotic arms for parcel handling, prioritizing throughput over precision.
Manufacturing absorbs the majority of deployment investment. Healthcare is expanding most quickly despite regulatory headwinds.
Deployment:
Infrastructure model selection hinges on data sovereignty exposure and latency tolerance, with hybrid configurations capturing margin from compliance-sensitive buyers.
- Public Cloud:Shared-tenant compute resources serve cost-sensitive manufacturers in Colombia and Chile, with ANATEL-licensed facilities in São Paulo meeting Brazilian data localization requirements.
- Private Cloud:Dedicated infrastructure supports aerospace and medical device producers in Querétaro with guaranteed resource isolation for sensitive operational telemetry.
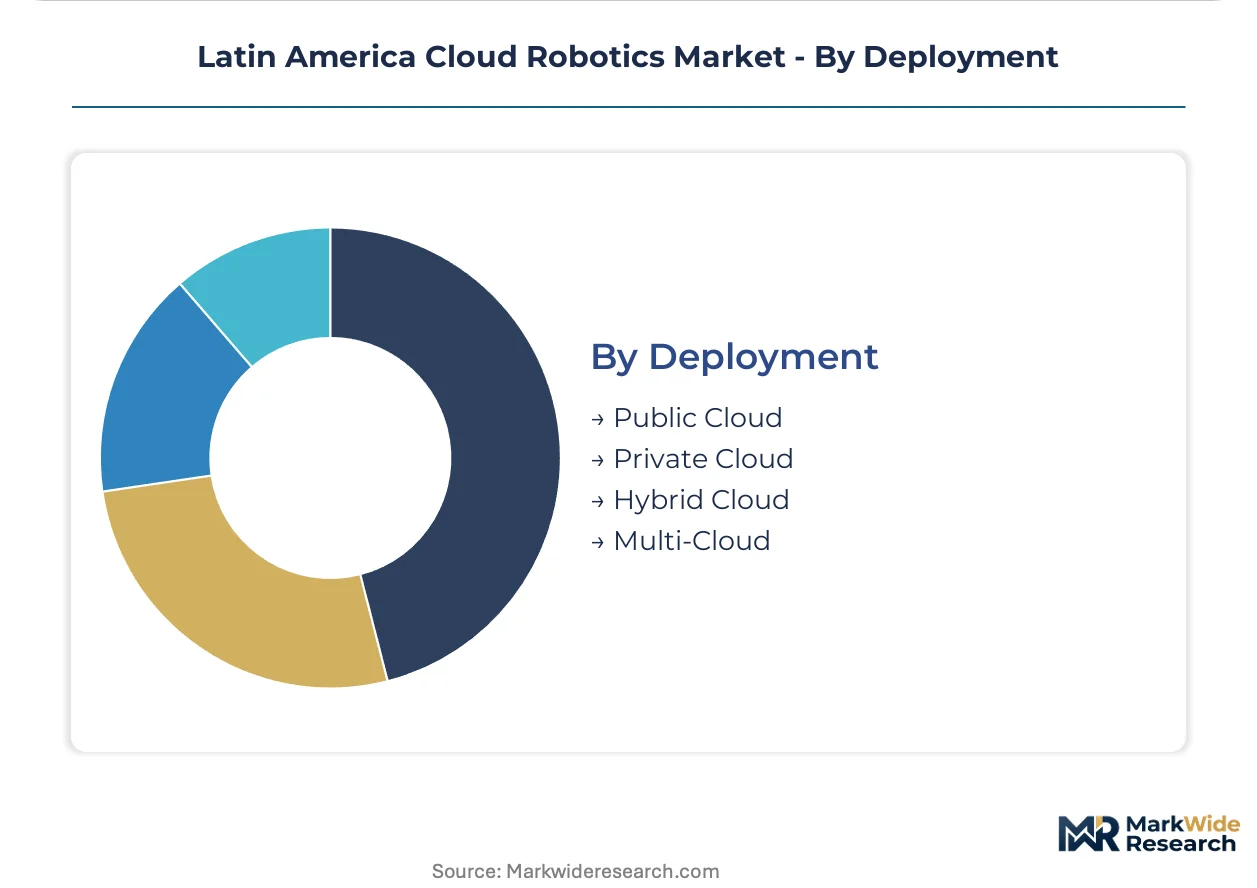
- Hybrid Cloud:Split processing architectures place real-time motion control on local edge nodes while archiving analytics workloads to regional cloud instances, satisfying both LGPD and NOM frameworks.
- Multi-Cloud:Redundant provider configurations mitigate concentration risk for tier-one automotive suppliers operating across Brazil-Mexico-Argentina manufacturing networks.
Public Cloud carries the largest installed base. Hybrid Cloud is gaining share fastest among regulated sector buyers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil absorbs larger cloud robotics investment than Mexico despite Mexico's aerospace concentration, while Argentina and Chile trail with nascent regulatory frameworks still crystallizing.
Brazil
Automotive stamping lines and electronics contract manufacturers drive procurement volume in São Paulo's ABC industrial corridor. ANATEL millimeter-wave spectrum auctions enable deterministic 5G connectivity for collaborative robot fleets. LGPD data localization mandates force cloud robotics operators to deploy sovereign edge nodes within licensed domestic facilities, elevating infrastructure costs.
Mexico
Precision turbine blade machining in Querétaro's aerospace cluster consolidates demand for cloud-coordinated robotic arms among tier-one suppliers. NOM-001-SCFI cybersecurity standards filter inference latency for computer vision quality inspection systems. Guadalajara electronics assemblers adopt fenceless human-robot workstations to maintain preferred supplier status under centralized OEM procurement governance.
Argentina
Pharmaceutical packaging lines under CNDC data sovereignty requirements create protected demand for hybrid edge-cloud orchestration specialists. The national pharmaceutical regulator enforces strict operational telemetry residency rules. Buenos Aires industrial zones witness tentative adoption of containerized ROS2 middleware for localized predictive maintenance analytics.
Chile
Mining equipment automation in Santiago drives demand for cloud-coordinated robotic inspection systems. SUBTEL 5G allocation frameworks shape spectrum availability for autonomous mobile platforms in retail distribution hubs. Anticipated convergence between EU AI Act risk classifications and national guidelines could streamline certification for European vendors entering this market.
Colombia
Bogotá's emerging electronics assembly sector remains underserved by cloud-native collaborative workstations, offering positioning opportunities for flexible human-robot cell providers. The national spectrum regulator manages 5G deployment timelines affecting industrial connectivity. Free trade zone logistics facilities prioritize throughput-driven parcel handling automation over precision applications.
Latin America Cloud Robotics Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across hardware, software, and infrastructure layers. The vendor base organizes into three tiers: integrated automation giants with motion control hardware captive supply, GPU-accelerated simulation platform operators, and cloud-native middleware specialists. Consolidation pressure intensifies as automotive OEMs mandate centralized fleet management standardization. Dominant competitive moves include backward integration into edge hardware production and strategic partnerships with domestic data center operators to satisfy data residency mandates.
Among the integrated automation tier, ABB and FANUC anchor established positions through installed base advantages and localized edge node deployments. NVIDIA exemplifies the simulation platform archetype with GPU-accelerated digital twin development. CloudMinds and Rapyuta Robotics occupy positions within the cloud-native middleware specialist tier. IBM and Microsoft Corporation represent diversified technology conglomerates extending enterprise cloud infrastructure into robotic workloads. These six entities collectively span the strategic archetypes defining competitive positioning in this market.
| Leading Market Players |
|---|
| ABB |
| CloudMinds |
| NVIDIA |
| FANUC |
| IBM |
| Microsoft Corporation |
| Clearpath Robotics |
| Rapyuta Robotics |
| Rockwell Automation |
| Others |
Value Network & Pricing Analysis
Centralized IT governance among Brazilian automotive OEMs is mandating cloud platform standardization across supplier networks, forcing hardware vendors to absorb certification costs for LGPD-compliant edge nodes while maintaining competitive unit economics against Mexican maquiladora procurement committees.
Pricing Analysis
Capacity additions in São Paulo's ANATEL-licensed data center facilities are reshaping price floors for sovereign cloud robotics deployments. Three-tier pricing structure across premium certified, standard compliant, and economy non-resident tiers dominates procurement negotiations. Price differentiation hinges on LGPD certification grade and volume scale commitments from tier-one automotive suppliers. Cost compression in the economy tier is intensifying because Colombian mid-market manufacturers lack bargaining leverage against consolidated platform providers. Electronics contract manufacturers in Guadalajara exhibit highest price sensitivity; aerospace clusters in Querétaro absorb premium pricing for guaranteed NOM-compliant infrastructure isolation.
Supply Chain Analysis
GPU-accelerated inference accelerators for real-time motion planning rest on concentrated foundry capacity in Taiwan, South Korea, and mainland China. Supply draws from advanced packaging substrates, high-bandwidth memory modules, and precision torque sensors for collaborative robot joints. Single-source vulnerability in East Asian semiconductor fabrication exposes Brazilian integrators to extended lead times for edge hardware deployments. Distribution runs through authorized industrial automation distributors with certified integration capabilities, bypassing direct procurement channels for complex fleet management configurations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Latin America cloud robotics functions as a geographic-arbitrage play where data localization mandates in Brazil create protected margin pools unavailable in Mexico's more permissive cross-border processing environment, rewarding infrastructure positioning in São Paulo over Guadalajara for compliance-sensitive buyers.
For Market Incumbents: Hedge against regulatory fragmentation by maintaining parallel infrastructure stacks certified for both LGPD and NOM frameworks rather than pursuing unified architectures. Backward integration into edge hardware production reduces exposure to GPU accelerator supply bottlenecks from East Asian foundries. ANATEL spectrum auction timelines determine optimal timing for sovereign node deployment commitments. For New Entrants and Emerging Players: Containerized ROS2 middleware with serverless orchestration capabilities offers entry positioning into Argentine pharmaceutical packaging lines where CNDC data sovereignty requirements have kept incumbent platforms at bay. Bogotá's electronics assembly sector remains the most penetrable geography for flexible human-robot workstations. Partner with domestic data center operators to satisfy certification requirements without capital-intensive facility builds. For Investors and Strategic Acquirers: Asymmetric upside sits with hybrid edge-cloud orchestration specialists serving regulated sectors where compliance overhead has suppressed competitive entry. Long-term viability centers on five-to-ten year data residency regime stability across Brazil, Mexico, and Argentina. Acquisition target archetype: containerized middleware vendors with existing ANATEL-licensed node deployments. The signal to watch is convergence between EU AI Act risk classifications and Chilean SUBTEL guidelines as certification harmonization catalyst.| Strategic Initiative | Industry Significance |
|---|---|
| Domestic Edge Node Certification | ANATEL-licensed sovereign infrastructure creates protected demand zones for LGPD-compliant robotic telemetry processing. |
| GPU-Accelerated Simulation Platform Integration | NVIDIA digital twin capabilities compress deployment timelines for Mexican maquiladora fleet standardization projects. |
| Containerized Middleware Partnership | ROS2 serverless orchestration opens margin pools in Argentine CNDC-regulated pharmaceutical packaging automation. |
| Backward Integration into Motion Control Hardware | Captive supply of precision torque sensors reduces latency for cloud-connected collaborative robot deployments. |
| Multi-Cloud Redundancy Configuration | Tier-one automotive suppliers mitigate concentration risk across Brazil-Mexico-Argentina manufacturing networks. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with plant engineers at Brazilian automotive stamping facilities, IT procurement officers at Mexican electronics contract manufacturers, cloud infrastructure architects at ANATEL-licensed data center operators, and regulatory compliance leads navigating LGPD-NOM framework alignment. Secondary validation drew from ANATEL spectrum auction records, COFEPRIS medical device pathway documentation, NOM-001-SCFI cybersecurity standard filings, and customs data on industrial automation equipment imports. Bottom-up installation tracking and top-down cloud compute demand modeling triangulated market size estimates.
Historical reference periods anchored the projection horizon to observed adoption curves across prior industrial automation technology cycles. Segmentation modeling captured robot category, deployment architecture, end-use industry vertical, and national regulatory cluster dimensions. CAGRs derived from logistic diffusion curves fitted to early-adopter penetration rates in São Paulo and Querétaro manufacturing corridors. Industry-specific forecast inputs included ANATEL millimeter-wave auction timelines and COFEPRIS certification backlog estimates for surgical robotics.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to LGPD enforcement intensity, East Asian semiconductor supply continuity, and convergence between EU AI Act and Chilean SUBTEL guideline alignment. Forecasts reflect documented assumptions on spectrum allocation schedules and data center licensing velocity. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
Consumer and Office Robot Market
Robotics and Automation
Global Wafer Handling Robots Market
Robotics and Automation
Mobile Robotics Market
Robotics and Automation
Nano Robots Market
Robotics and Automation
Healthcare Companion Robots Market
Robotics and Automation
Europe Automated Guided Vehicle (AGV) Market
Robotics and Automation
Africa Agricultural Robots and Mechatronics Market
Robotics and Automation
Europe Articulated Robot Market
Robotics and Automation
Claytronics Market
Robotics and Automation
China Industrial Robots Market
Robotics and Automation
Hospital Robots Market
Robotics and Automation
Microsurgery Robot Market
Robotics and Automation
Europe Underwater Robotics Market
Robotics and Automation
Global Medical Robotic Systems Market
Robotics and Automation
Global Robotics Parking System Market
Robotics and Automation
Nanorobots in Healthcare Market