
 Healthcare Robots Market | 2026-2036
Healthcare Robots Market Size, Share, and Industry Trends Forecast 2026-2036
Healthcare Robots Market Outlook
EU MDR is restructuring the cost-of-entry calculus for robotic surgical platforms across European markets. Intuitive Surgical leverages decades of clinical data to sustain its installed-base dominance in minimally invasive procedures. Stryker Corporation anchors its position through dedicated robotics divisions focused on orthopedic navigation systems. Medtronic competes via integrated surgical ecosystems that combine hardware with proprietary software stacks.
Healthcare robots encompass electromechanical systems designed to perform clinical tasks with precision exceeding human capability, typically operating at sub-millimeter accuracy thresholds in surgical environments while incorporating force-feedback sensors for tissue interaction. Their primary purpose spans diagnostic augmentation, therapeutic intervention, and logistical automation within care delivery networks. Surgical robots occupy the largest revenue pool given capital intensity and recurring instrument revenues, while disinfection robots represent the fastest-expanding category as infection-control protocols tighten across acute-care facilities. Rehabilitation robots command premium pricing in post-stroke neurorecovery applications where biofeedback integration drives measurable functional outcomes.
The FDA's premarket notification and De Novo pathways govern US commercialization timelines, while EU MDR technical documentation requirements extend certification cycles for novel robotic platforms. Japan's PMDA maintains distinct software-as-medical-device classifications that affect AI-enabled surgical planning modules differently than hardware-centric systems. Stakeholders must monitor evolving software validation standards as autonomous decision-making capabilities expand beyond physician-supervised execution frameworks.
Market Dynamics
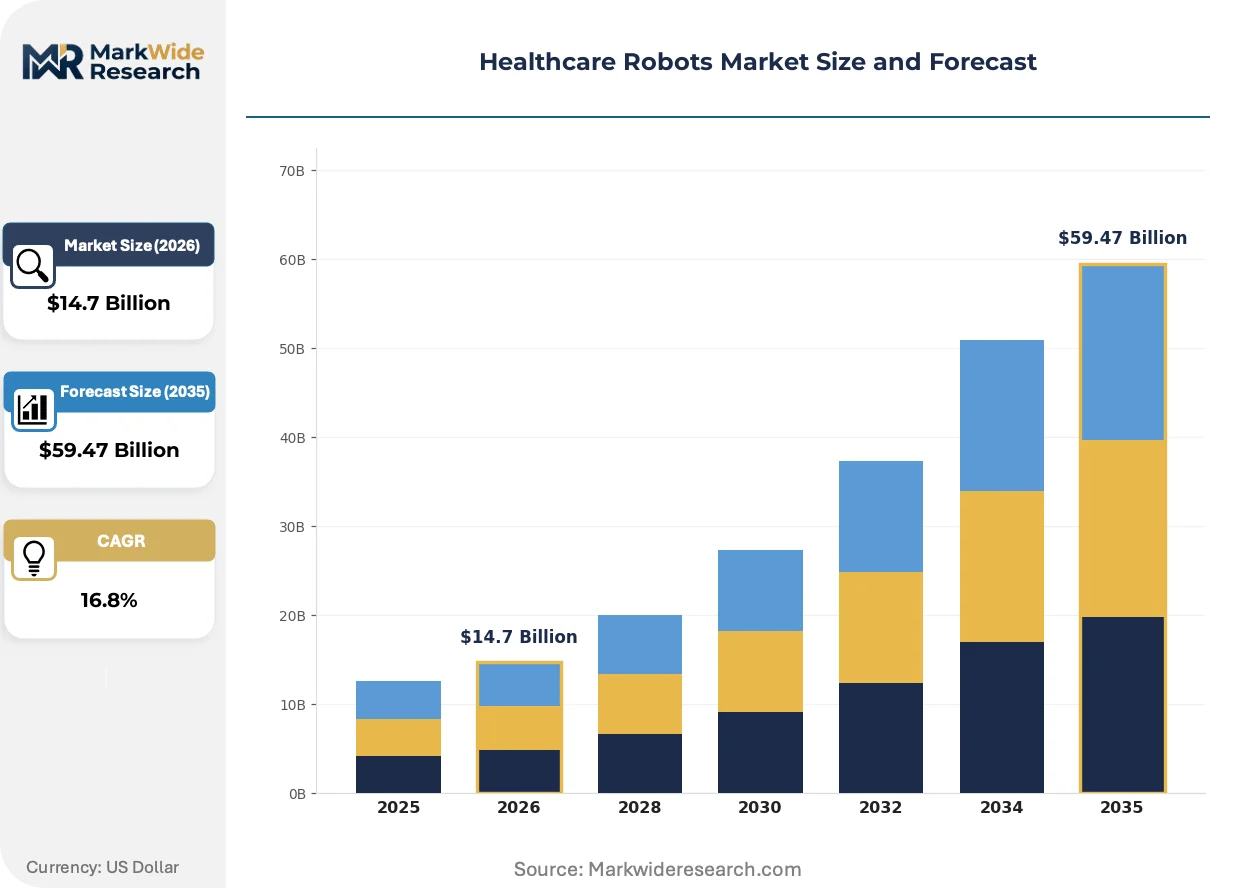
Labor shortages across acute-care facilities are accelerating capital deployment into autonomous systems that substitute for nursing and surgical support staff. The FDA's evolving premarket review frameworks for autonomous surgical platforms are simultaneously extending commercialization timelines and raising barriers for new hardware entrants.
Growth Catalysts
- EU MDR compliance mandates:European hospitals face mandatory equipment upgrades under tightened infection-control protocols, forcing replacement cycles for aging surgical infrastructure and creating immediate demand for certified robotic platforms.
- Japan's PMDA software-as-medical-device pathway:Tokyo's regulatory clarity for AI-enabled surgical planning modules accelerates commercialization timelines for intelligent navigation systems beyond hardware-centric competitors.
- Post-acute rehabilitation centers:Stroke recovery facilities in Germany and the United States are expanding biofeedback-integrated neurorecovery programs, driving premium-priced robotic exoskeleton procurement.
Market Restraints
- Sensor component concentration:Force-feedback haptic sensors for tissue interaction rely on specialized manufacturing concentrated in Japanese and German supplier networks, exposing procurement to single-source vulnerability.
- Capital intensity thresholds:Multi-million dollar installed-base requirements for surgical robotics exclude community hospitals and ambulatory surgical centers from market participation.
- EU MDR technical documentation burdens:Extended certification cycles for novel robotic platforms delay revenue recognition by 18-24 months versus previous Medical Device Directive timelines.
Strategic Opportunities
- India's surgical robotics underpenetration:Tier-2 and Tier-3 cities lack robotic-assisted surgery infrastructure, creating first-mover advantage for modular, lower-capital platforms adapted to variable power and sterilization conditions.
- 5G-enabled telesurgery networks:Convergence of low-latency connectivity with haptic feedback systems enables remote surgical assistance from urban tertiary centers to rural hospitals.
- Disinfection robotics in long-term care:Japan's Ministry of Health mandates automated environmental cleaning in aged-care facilities, opening channel expansion beyond acute-care hospital procurement.
Industry Challenges
- Surgical robotics technician scarcity:Biomedical engineering programs produce insufficient graduates trained in electromechanical maintenance of capital-intensive da Vinci and competitor systems.
- Legacy EMR integration friction:Proprietary software stacks from incumbent surgical robot manufacturers resist interoperability with hospital-wide electronic medical record architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Healthcare Robots Market |
| Market Size in 2026 | $14.7 Billion |
| Market Size in 2035 | $59.47 Billion |
| CAGR (2026 – 2036) | 16.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Surgical Robots, Rehabilitation Robots, Telepresence Robots, Disinfection Robots Technology: Artificial Intelligence, Machine Learning, Computer Vision, Biofeedback Application: Patient Care, Surgery Assistance, Chronic Disease Management, Remote Monitoring End User: Hospitals, Rehabilitation Centers, Home Healthcare, Nursing Facilities |
| Companies Covered | Intuitive Surgical, Stryker Corporation, Medtronic, Johnson & Johnson, Zimmer Biomet, Smith & Nephew, Toyota Motor Corp., Panasonic, Aethon, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Healthcare Robots Market Strategic Shifts
Autonomous decision-making capabilities are migrating from physician-supervised execution toward semi-independent surgical action, forcing recalibration of liability frameworks and training protocols. Hardware manufacturers are repositioning around recurring software revenue streams.
Soft robotics and compliant mechanisms are rewriting tissue interaction paradigms in minimally invasive procedures. Cardiac and pediatric surgical teams at Cleveland Clinic and Charité Berlin are piloting continuum robots that navigate anatomical constraints impossible for rigid instruments. This technology is compressing the boundary between diagnostic imaging and therapeutic intervention into single-session workflows.
EU MDR's post-market surveillance requirements are restructuring clinical evidence obligations for robotic surgical platforms. Manufacturers must now maintain active implant registries and real-world performance databases, shifting competitive advantage toward incumbents with decades of accumulated procedure data. Orthopedic navigation systems face the steepest compliance cost escalation.
Hospital procurement committees are unbundling after-sales service contracts from capital equipment purchases, pressuring manufacturers to compete on transparent per-procedure pricing. German hospital networks led by University Hospital Heidelberg are pioneering this model, with United States IDNs following. The shift compresses vendor margins while accelerating platform switching cycles.
Healthcare Robots Market Segmentation
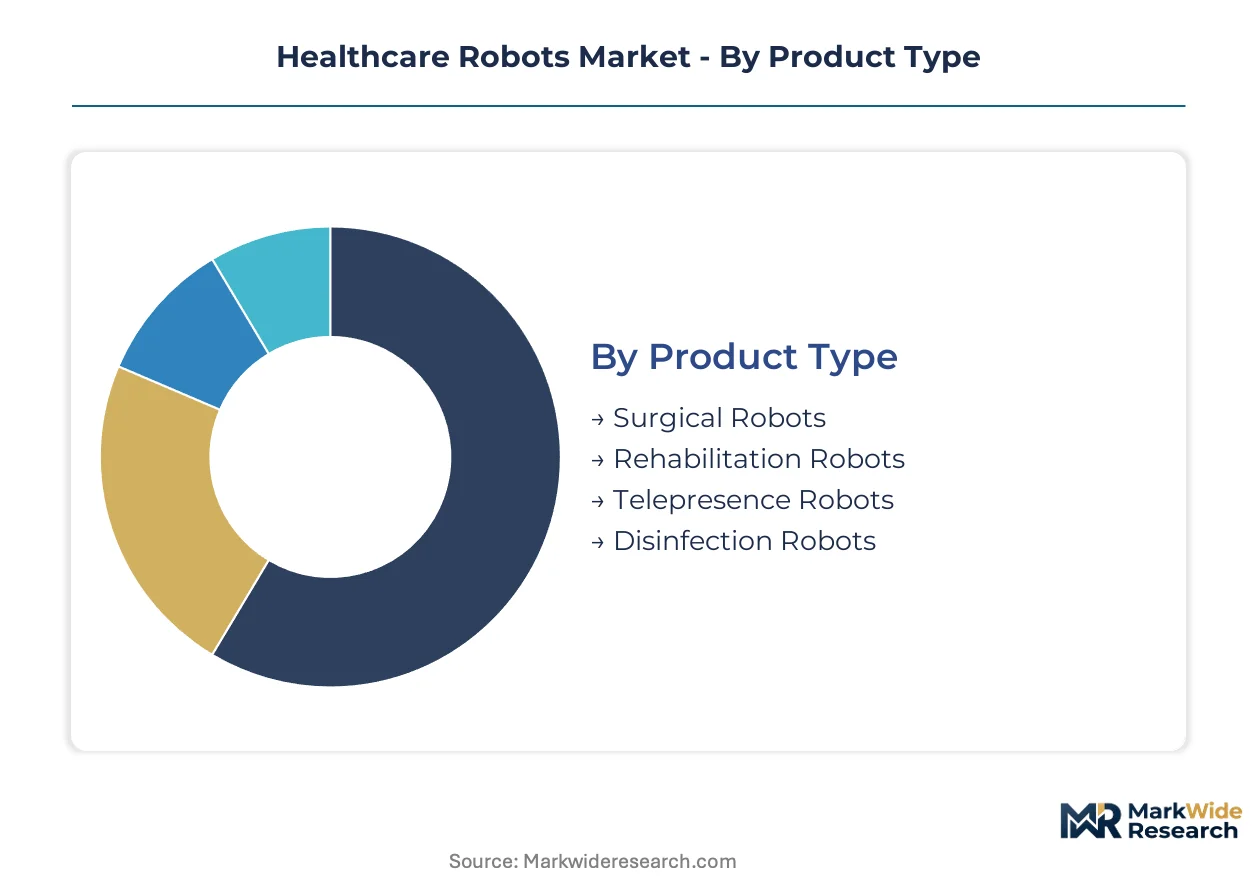
Healthcare robots span electromechanical systems with divergent capital requirements, regulatory pathways, and replacement cycles. Segmentation reveals where procurement budgets concentrate and which technology trajectories command R&D investment.
Product Type:
Upgrade and replacement cycles vary dramatically across product categories, with capital-intensive surgical platforms demanding decade-long amortization schedules while disinfection units turn over every 3-5 years.
- Surgical Robots:Multi-arm electromechanical systems with sub-millimeter precision and force-feedback haptic control dominate capital expenditure in tertiary hospitals. Demand concentrates in the United States and Germany where reimbursement frameworks for robotic-assisted procedures have matured, though procurement committees increasingly unbundle service contracts from equipment purchases.
- Disinfection Robots:Autonomous UV-C and hydrogen peroxide vapor systems navigate hospital corridors using LiDAR mapping. Infection-control protocol tightening across acute-care facilities in Japan and the United States drives fastest-category expansion, with Japan's Ministry of Health mandating automated environmental cleaning in aged-care facilities beyond hospital procurement.
- Rehabilitation Robots:Exoskeleton and end-effector devices for neurorecovery integrate biofeedback sensors measuring patient effort and movement quality.
- Telepresence Robots:Mobile platforms with audiovisual links enable remote physician consultation and family visitation in isolated care settings.
Surgical robots sit at the top of the volume ranking, with disinfection robots climbing the fastest.
Technology:
Cost tiers separate foundational sensing technologies from premium AI-enabled decision systems, with hardware-centric platforms facing margin compression against software-recurring revenue models.
- Artificial Intelligence:Deep learning models for surgical planning and autonomous navigation require extensive validation under FDA De Novo and Japan PMDA software-as-medical-device pathways. Germany's Charité Berlin and Cleveland Clinic pilot AI-guided continuum robots that compress diagnostic and therapeutic workflows into single sessions.
- Computer Vision:Real-time anatomical recognition and instrument tracking enable augmented reality overlays for surgical guidance.
- Machine Learning:Adaptive algorithms personalize rehabilitation protocols based on patient progress data captured during exoskeleton sessions.
- Biofeedback:Surface electromyography and force sensors measure patient neuromuscular engagement, driving premium pricing in post-stroke recovery applications where functional outcomes are quantifiable.
Artificial intelligence commands the steepest R&D investment trajectory, while biofeedback integration delivers the highest per-unit margins in rehabilitation applications.
Application:
Customer type and procedure volume determine technology deployment, with high-acuity surgical assistance commanding capital budgets while remote monitoring scales through lower-cost telepresence units.
- Surgery Assistance:Robotic platforms execute minimally invasive procedures across cardiac, orthopedic, and urological specialties. EU MDR post-market surveillance requirements now mandate active implant registries, shifting competitive advantage toward manufacturers with decades of accumulated clinical data.
- Patient Care:Automated medication dispensing, patient lifting, and mobility assistance address nursing labor shortages in the United States and European acute-care facilities.
- Chronic Disease Management:Home-based robots monitor vital signs and medication adherence for diabetes and congestive heart failure patients.
- Remote Monitoring:5G-enabled telesurgery networks from urban tertiary centers to rural hospitals in India and the United States leverage low-latency connectivity with haptic feedback.
Surgery assistance generates the largest revenue pool, with remote monitoring expanding most quickly through connectivity infrastructure convergence.
End User:
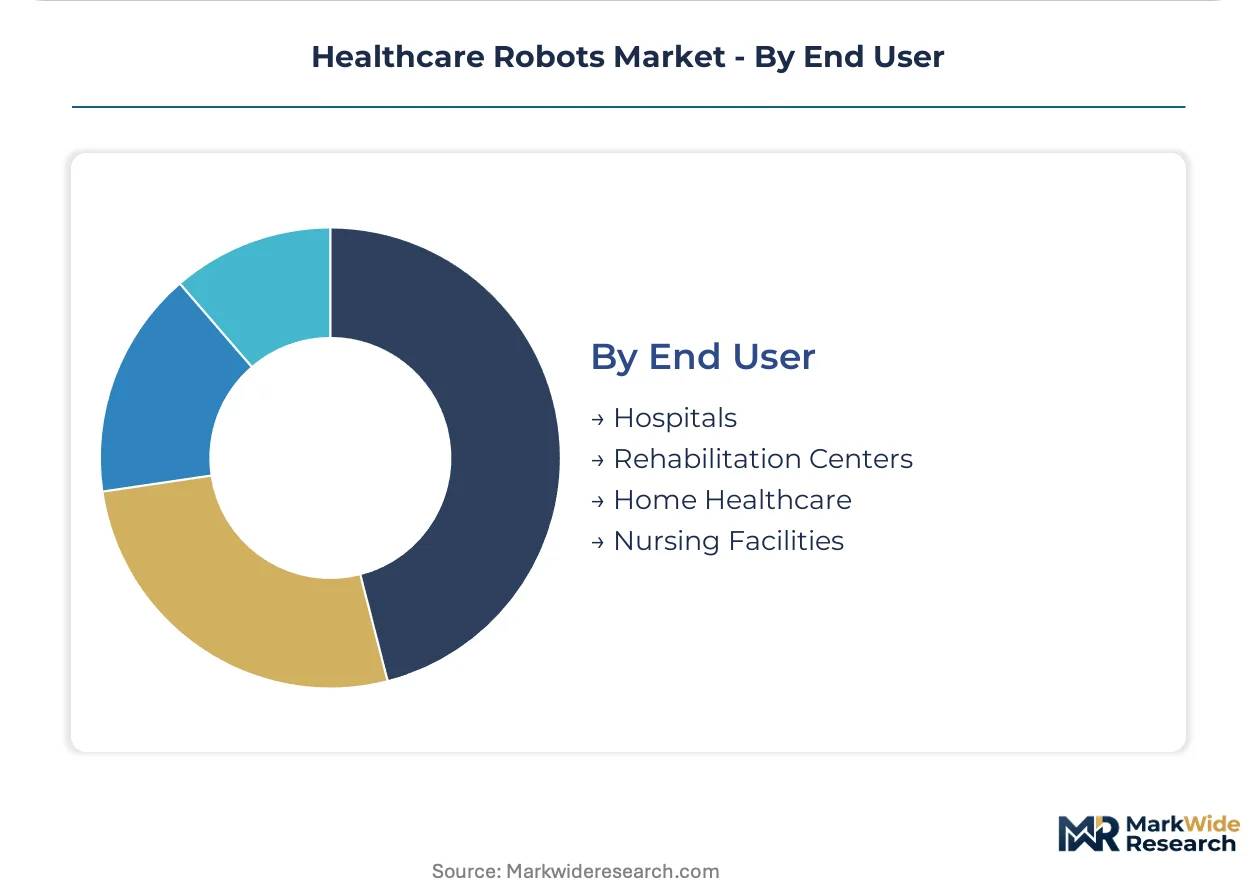
Procurement authority and reimbursement frameworks segment the customer base, with hospital IDNs leveraging volume scale against fragmented nursing facility purchasing.
- Hospitals:Tertiary and community acute-care facilities in the United States, Germany, and Japan concentrate surgical robot installed bases. German hospital networks led by University Hospital Heidelberg pioneer transparent per-procedure pricing models that compress vendor margins while accelerating platform switching.
- Rehabilitation Centers:Post-acute stroke recovery facilities in Germany and the United States expand biofeedback-integrated neurorecovery programs.
- Home Healthcare:Aging-in-place demographics in Japan and the United States drive demand for assistive robots for medication management and fall detection.
- Nursing Facilities:Long-term care operators face staffing shortages that autonomous systems address, though capital constraints limit penetration compared to hospital systems.
Hospitals anchor procurement volume, with rehabilitation centers gaining share fastest through outcome-based reimbursement pilots.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Biomedical engineering talent clusters in Germany, the United States, and Japan anchor healthcare robot development, with surgical robotics technician training programs expanding at Johns Hopkins University, Technical University of Munich, and University of Tokyo.
United States
Hospital procurement committees at Cleveland Clinic and Mayo Clinic accelerate da Vinci system deployments as nursing labor shortages intensify. FDA premarket notification and De Novo pathways govern commercialization timelines for autonomous surgical platforms. Boston's Route 128 corridor concentrates surgical robotics startups alongside established manufacturers.
Germany
University Hospital Heidelberg pioneers transparent per-procedure pricing models that compress vendor margins while accelerating platform switching. EU MDR technical documentation requirements extend certification cycles for novel robotic platforms by 18-24 months. Charité Berlin pilots continuum robots that compress diagnostic and therapeutic workflows into single sessions.
Japan
Post-acute stroke recovery facilities expand biofeedback-integrated neurorecovery programs driving premium-priced exoskeleton procurement. PMDA software-as-medical-device classifications accelerate commercialization timelines for AI-enabled surgical planning modules. Tokyo's Shinagawa district hosts concentrated surgical robotics R&D operations.
India
Tier-2 and Tier-3 cities lack robotic-assisted surgery infrastructure creating first-mover advantage for modular lower-capital platforms. CDSCO medical device regulations govern import and local manufacturing approvals for capital equipment. Bangalore's medical technology corridor attracts domestic assembly operations for cost-adapted surgical systems.
United Kingdom
NHS procurement frameworks prioritize outcome-based reimbursement pilots for rehabilitation robotics in post-stroke care. MHRA post-Brexit regulatory autonomy maintains alignment with EU MDR technical standards while streamlining national approval pathways. London's Imperial College Healthcare NHS Trust operates concentrated surgical robotics training centers.
Healthcare Robots Market Competitive Environment
The competitive structure tilts toward installed-base incumbents with decades of accumulated clinical data. Surgical robotics concentrates around multi-arm electromechanical platform specialists, while disinfection and rehabilitation segments fragment across automation-focused entrants. Dominant competitive moves include unbundling after-sales service contracts from capital equipment purchases and repositioning around recurring software revenue streams.
Within the integrated surgical ecosystem tier, Intuitive Surgical, Stryker Corporation, and Medtronic represent archetypes of contrasting strategic positioning. Intuitive Surgical exemplifies installed-base dominance through accumulated procedure databases. Stryker Corporation occupies a position anchored through dedicated robotics divisions. Medtronic sits within the integrated hardware-software convergence vector.
| Leading Market Players |
|---|
| Intuitive Surgical |
| Stryker Corporation |
| Medtronic |
| Johnson & Johnson |
| Zimmer Biomet |
| Smith & Nephew |
| Toyota Motor Corp. |
| Panasonic |
| Aethon |
| Others |
Value Chain & Pricing Dynamics
Private-equity-rolled-up service networks in surgical robotics aftermarket support are consolidating regional repair specialists and tightening pricing discipline on per-procedure contracts, compressing margins for capital-equipment manufacturers while locking in multi-year service revenue streams.
Pricing Analysis
The bundled-versus-unbundled service split is restructuring revenue recognition across surgical robotics procurement. Three-tier pricing structure across premium, standard, and economy levels separates academic medical centers with full-service contracts from community hospitals purchasing stripped hardware-only configurations. Cost compression in standard-tier surgical platforms is intensifying because German hospital networks pioneered transparent per-procedure pricing that accelerates platform switching. Ambulatory surgical centers exhibit the highest price sensitivity, while tertiary academic medical centers absorb premium pricing for accumulated clinical data access.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from United States and German hospital IDNs, while regional distributors serve fragmented rehabilitation center procurement in Japan. Force-feedback haptic sensors for tissue interaction draw from specialized manufacturing concentrated in Japan and Germany, exposing procurement to single-source vulnerability. Supply chain risk centers on tariff exposure for semiconductor components in navigation systems. Distribution runs through manufacturer-direct sales teams for capital-intensive surgical platforms and third-party logistics for disinfection robot consumables.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The healthcare robots market reads as a late-cycle quality story where procurement committees now prioritize accumulated clinical evidence and FDA-validated autonomous capabilities over first-generation hardware specifications.
For Market Incumbents: Acquire decades-deep procedure databases that EU MDR post-market surveillance now mandates for competitive positioning. Consolidate regional surgical robotics technician training programs to address biomedical engineering graduate scarcity threatening installed-base maintenance revenue. Vertical integration into force-feedback sensor manufacturing mitigates Japanese and German supplier concentration risk. For New Entrants and Emerging Players: AI-enabled surgical planning modules validated under Japan's PMDA software-as-medical-device pathway offer the most penetrable entry vector against hardware-centric incumbents. Target India's Tier-2 and Tier-3 cities with modular platforms adapted to variable power and sterilization infrastructure absent in current market coverage. Pursue 5G-enabled telesurgery network partnerships with urban tertiary centers as the primary go-to-market angle. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-cap rehabilitation robotics specialists with biofeedback-integrated exoskeleton platforms and outcome-based reimbursement pilots in Germany and the United States. Long-term viability hinges on software-recurring revenue transition away from capital-equipment dependence. Watch FDA De Novo pathway approval velocity for autonomous surgical platforms as the primary inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| FDA De Novo Submission | Accelerates commercialization timelines for autonomous surgical planning modules beyond predicate device pathways. |
| CE Marking Pathway | EU MDR technical documentation requirements extend certification cycles but lock in post-market surveillance data advantages. |
| Hospital System Partnership | University Hospital Heidelberg's transparent per-procedure pricing model compresses vendor margins while accelerating platform switching. |
| Software Companion Development | PMDA software-as-medical-device classifications in Japan enable recurring revenue streams from AI-enabled navigation systems. |
| Reimbursement Strategy | Cleveland Clinic and Charité Berlin pilot outcome-based contracts for biofeedback-integrated neurorecovery programs. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with hospital purchasing committees, biomedical engineers, GPO contracts managers, and surgical robotics technicians with secondary validation against FDA 510(k) and De Novo filings, EU MDR technical documentation databases, hospital procurement records, and CMS Medicare reimbursement data. Bottom-up installed-base modeling and top-down expenditure triangulation anchored market sizing.
Historical reference periods spanning pre-pandemic, acute disruption, and stabilization phases anchored the forecast window across product type, technology tier, application setting, and end-user category dimensions. CAGRs were derived from procedure volume elasticity against reimbursement rate trajectories and capital expenditure cycle analysis. Surgical robotics technician training program expansion rates and 5G infrastructure deployment timelines served as industry-specific forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to FDA autonomous surgical platform approval velocity, EU MDR certification cycle extensions, and Japan's PMDA software-as-medical-device pathway evolution. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
Cloud Robotics Market
Robotics and Automation
Global All Terrain Robots Market
Robotics and Automation
South America AUV and ROV Market
Robotics and Automation
Industrial Control Robotics Market
Robotics and Automation
Global Indoor Robots Market
Robotics and Automation
Intelligent Vending Machines Market
Robotics and Automation
Global Automated Guided Vehicle (AGV) Software Market
Robotics and Automation
Asia-Pacific Cloud Robotics Market
Robotics and Automation
Motion Control Software in Robotics Market
Robotics and Automation
Snake Robots Market
Robotics and Automation
Micro Robots Market
Robotics and Automation
Japan Agricultural Robot Market
Robotics and Automation
Underwater Drone Market
Robotics and Automation
Global IT Robotic Automation Market
Robotics and Automation
Japan Articulated Robot Market
Robotics and Automation
Healthcare Mobile Robots Market