
 Construction Enterprise Resource Planning (ERP) Software Market | 2026-2036
Construction Enterprise Resource Planning (ERP) Software Market Size, Share, and Industry Trends Forecast 2026-2036
Construction Enterprise Resource Planning (ERP) Software Market Insights
The Construction ERP Software market is pivoting between premium integrated suites and commodity point solutions as buyers split between full-platform consolidation and modular best-of-breed procurement. Sage Intacct leverages deep financial management DNA to anchor mid-market contractor loyalty. Procore competes through construction-native field-to-office workflows that dominate commercial building verticals. Oracle Cloud extends enterprise-grade project controls into heavy infrastructure accounts with complex multi-entity reporting demands.
Construction Enterprise Resource Planning (ERP) Software denotes integrated systems that unify project cost accounting, resource scheduling, procurement tracking, and compliance documentation through centralized databases with real-time field-data synchronization. These platforms serve to eliminate siloed spreadsheets and paper-based approvals across distributed job sites and back-office operations. Cloud-based deployment leads segment momentum as general contractors abandon server maintenance for browser-native accessibility across tablet-equipped field supervisors. Project Management solution offerings capture disproportionate R&D investment as stakeholders prioritize schedule-risk analytics and subcontractor coordination portals over standalone accounting modules.
FDA oversight intersects indirectly where ERP systems manage pharmaceutical facility construction, while OSHA recordkeeping mandates drive safety-module integration within contractor platforms. The EPA's stormwater and emissions tracking requirements shape environmental compliance features in infrastructure-focused deployments. Stakeholders must monitor how emerging building performance standards and carbon disclosure frameworks will force retrofitting of legacy ERP data architectures to capture embodied material emissions and energy benchmarking across project portfolios.
Market Dynamics
Cloud-native architectures are compressing the traditional five-year ERP replacement cycle for construction firms, as browser-based platforms eliminate server maintenance burdens and enable real-time field-to-office synchronization across distributed job sites.
Growth Catalysts
- Prevailing wage mandates:Certified payroll requirements in United States federal infrastructure projects force contractors toward automated compliance tracking. ERP modules that integrate Davis-Bacon Act calculations reduce audit exposure.
- Building energy codes:Australia's National Construction Code tightening thermal performance standards drives demand for material traceability and embodied carbon accounting within project cost systems.
- Mobile field-data capture:Tablet-equipped supervisors now expect offline-capable apps that synchronize cost codes, daily logs, and safety observations upon connectivity restoration.
Market Restraints
- Legacy data migration friction:Decades of project history trapped in on-premises databases creates switching costs that extend implementation timelines by twelve to eighteen months.
- Specialized subcontractor fragmentation:Trade contractors operating on slim margins resist ERP subscription fees, limiting platform penetration below the general contractor tier.
- Input cost volatility:Steel and lumber price swings between 2021 and 2023 exposed limitations in standard cost-accounting modules, eroding confidence in forecasting tools.
Strategic Opportunities
- German infrastructure stimulus:The Bundesrepublik's climate and transformation fund allocates capital toward railway and grid modernization, creating demand for multi-entity project controls among Mittelstand contractors.
- AI-assisted schedule-risk analytics:Machine learning convergence with critical-path methodology offers early-warning systems for delay propagation across subcontractor interfaces.
- Environmental compliance modules:EPA stormwater and emissions tracking requirements create attach-rate opportunities for environmental add-ons within infrastructure-focused deployments.
Industry Challenges
- Construction technologist scarcity:Firms struggle to hire personnel who bridge field operations knowledge with ERP configuration expertise, extending implementation phases.
- Multi-platform integration complexity:Best-of-breed procurement strategies create API maintenance burdens as contractors stitch together estimating, project management, and accounting systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Construction Enterprise Resource Planning (ERP) Software Market |
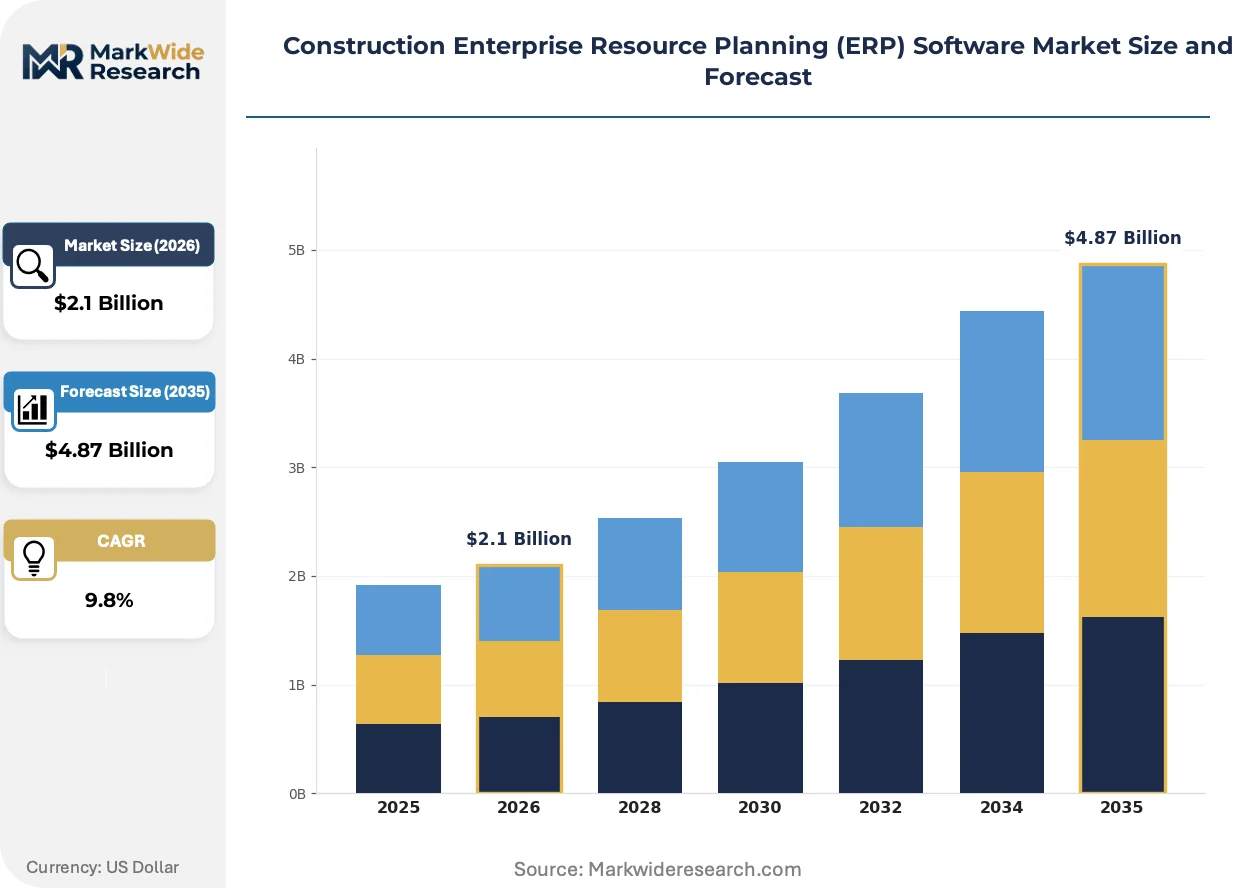
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $4.87 Billion |
| CAGR (2026 – 2036) | 9.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premises, Cloud-Based, Hybrid, Hosted Solution Offering: Project Management, Financial Management, Procurement Management, Asset Management, Compliance Management Application: Infrastructure Development, Residential Buildings, Commercial Complexes, Industrial Facilities, Institutional Projects End User: General Contractors, Subcontractors, Engineering Firms, Architectural Studios, Property Developers |
| Companies Covered | Sage Intacct, Viewpoint Vista, CMiC, Jonas ERP, Archdesk, Procore, SAP S/4HANA, Oracle Cloud, Acumatica, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Construction Enterprise Resource Planning (ERP) Software Market Trends and Innovations
Artificial intelligence and edge computing are rewriting how construction data flows from equipment telematics to financial forecasts, compressing the latency between field events and management visibility.
Generative AI is rewriting contract review and change-order documentation workflows. Mid-market contractors in commercial building verticals deploy natural-language tools to extract risk clauses from subcontractor agreements. The technology is rewriting how project administrators allocate time, shifting hours from manual document scanning to exception-based oversight.
The EPA's proposed greenhouse gas reporting requirements for federal construction contracts are mandating granular fuel-consumption tracking. Heavy civil contractors must retrofit equipment telematics into cost-accounting hierarchies. Infrastructure specialists in the United States face the steepest compliance curve as diesel-powered fleets dominate their asset bases.
Subscription fatigue among trade contractors is fragmenting procurement authority. General contractors now bundle ERP access into project overhead rather than pushing direct licenses downstream. This shift is most visible in Australia, where head-contractor consolidation has concentrated buying power among tier-one builders who dictate technology standards to their supply chains.
Construction Enterprise Resource Planning (ERP) Software Market Segmentation
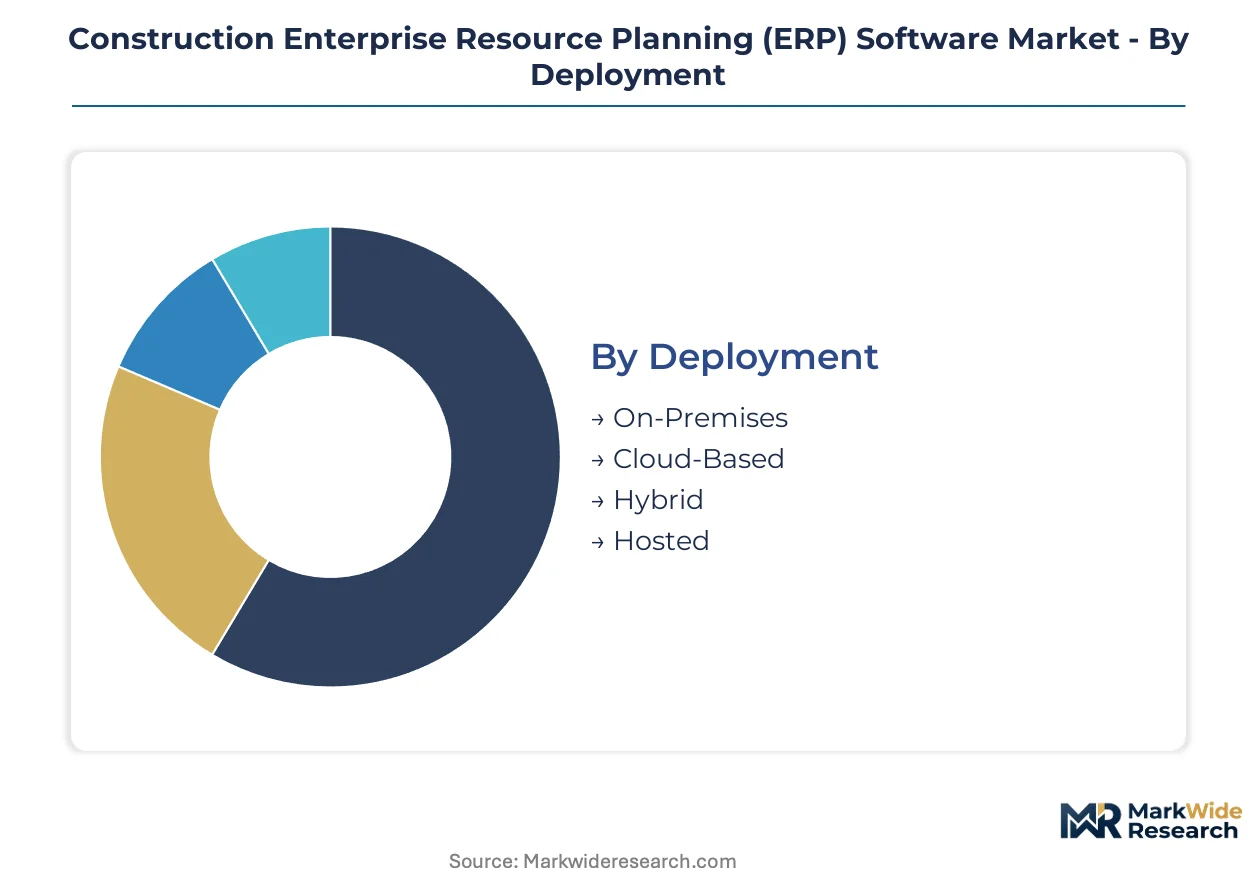
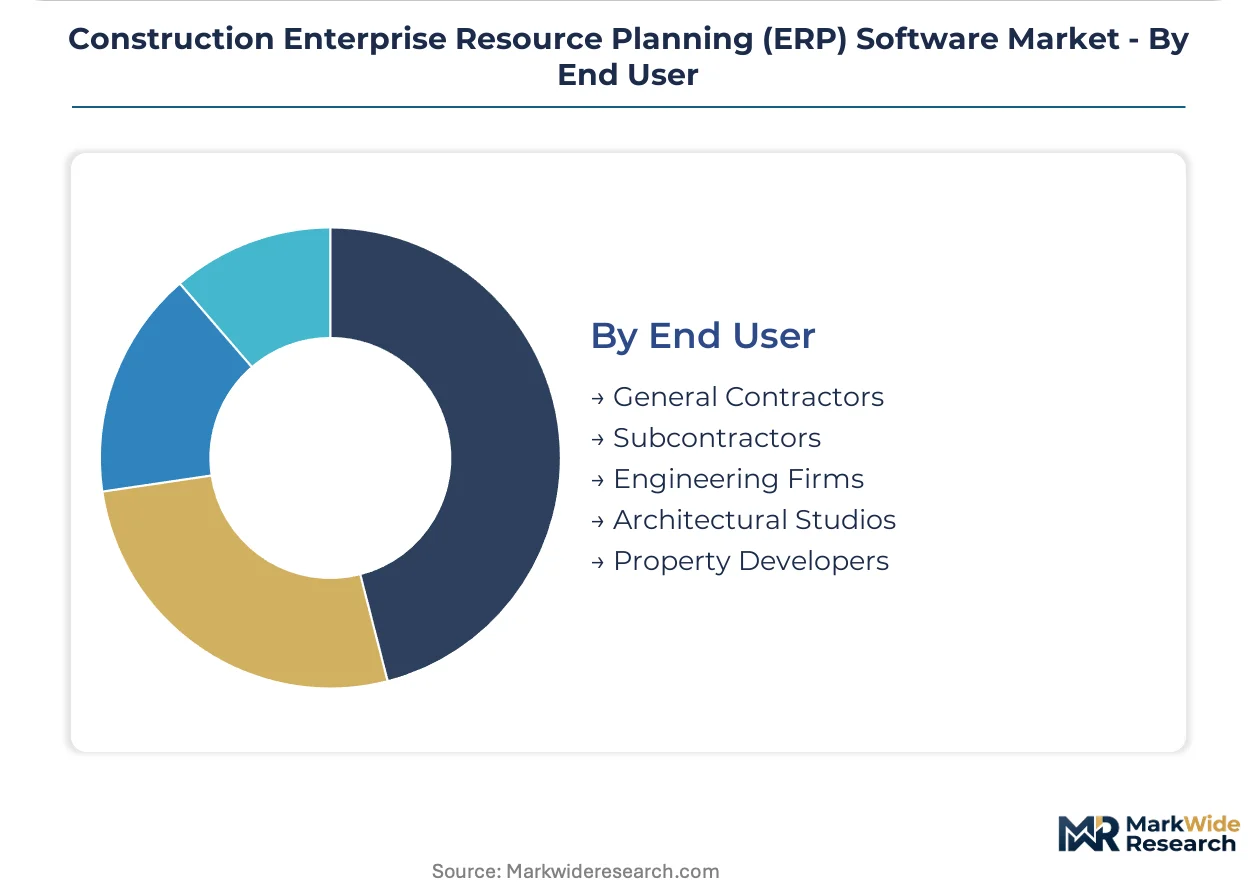
Construction ERP procurement splits sharply between capital-rich general contractors pursuing full-platform consolidation and trade specialists seeking modular entry points. Deployment architecture, solution breadth, and end-user sophistication create four distinct purchasing cohorts with diverging implementation timelines and integration complexity.
Deployment:
Buyer risk tolerance and IT staffing levels separate cloud adopters from infrastructure traditionalists.
- Cloud-Based:Browser-native platforms eliminate server maintenance burdens while enabling real-time synchronization across tablet-equipped field supervisors. Demand concentrates among mid-market commercial builders in the United States and Australia where rapid scaling requirements outpace internal IT capacity.
- On-Premises:Legacy server installations persist where data sovereignty mandates or bonded project security protocols restrict external hosting. Heavy civil contractors managing federal infrastructure portfolios in Germany favor this architecture for audit trail control.
- Hybrid:Split configurations maintain sensitive financial data on local servers while pushing field operations to cloud nodes. Engineering firms with classified government contracts adopt this posture.
- Hosted:Third-party managed infrastructure offers middle-ground outsourcing without full SaaS subscription models. Property developers with seasonal project volatility find this flexibility attractive.
Volume sits with Cloud-Based deployments; growth tilts toward Hybrid configurations as compliance complexity rises.
Solution Offering:
Module selection tracks contractor specialization depth and project portfolio diversity.
- Project Management:Schedule-risk analytics, subcontractor coordination portals, and critical-path visualization anchor commercial building workflows. United States general contractors prioritize these capabilities for multi-prime project delivery.
- Financial Management:Job-cost accounting, certified payroll automation, and prevailing wage calculation engines serve bonded public infrastructure mandates. Australian contractors face National Construction Code compliance pressures here.
- Procurement Management:Material traceability and embodied carbon tracking modules address tightening building energy codes. German Mittelstand contractors leverage these for railway and grid modernization projects.
- Asset Management:Equipment telematics integration and maintenance scheduling optimize fleet utilization. Heavy civil operators with diesel-intensive asset bases require EPA-aligned fuel-consumption tracking.
- Compliance Management:OSHA recordkeeping, stormwater documentation, and emissions reporting consolidate regulatory exposure. Infrastructure specialists in the United States face the steepest configuration demands.
Revenue concentrates in Project Management; expansion accelerates most quickly in Compliance Management as environmental reporting obligations multiply.
Application:
Project scale and regulatory exposure determine platform sophistication requirements.
- Infrastructure Development:Multi-entity project controls, certified payroll engines, and federal compliance documentation support bonded heavy civil portfolios. German climate and transformation fund allocations drive demand here.
- Commercial Complexes:Schedule coordination across subcontractor tiers and change-order workflow automation dominate mid-rise and high-rise construction. United States urban developers prioritize field-to-office synchronization.
- Residential Buildings:Production homebuilders seek volume-scalable estimating and purchasing modules. Australian head-contractor consolidation pushes technology standards downstream to trade partners.
- Industrial Facilities:Pharmaceutical and food-processing construction requires FDA-aligned documentation and cleanroom certification tracking. Specialized engineering firms serve this niche.
- Institutional Projects:University and healthcare construction demands long-term capital planning integration with facilities management handoff protocols.
Deal flow centers on Infrastructure Development; fastest adoption gains appear in Industrial Facilities as process industry capital expenditure revives.
End User:
Organizational scale and margin structure create divergent procurement authority patterns.
- General Contractors:Full-suite ERP consolidation eliminates spreadsheet silos across distributed job sites and back-office operations. Tier-one builders increasingly bundle platform access into project overhead rather than pushing direct licenses downstream.
- Subcontractors:Trade contractors operating on slim margins resist standalone subscription fees, limiting penetration below the general contractor tier. Electrical and mechanical specialists in Australia accept technology mandates from head contractors.
- Engineering Firms:Design-build integration requirements push these organizations toward estimating-to-operations workflow continuity. German railway modernization projects demand multi-entity reporting capabilities.
- Architectural Studios:Smaller practices prioritize document management and client billing modules over full construction operations platforms.
- Property Developers:Investment tracking, pro forma integration, and lease-up management distinguish developer-focused deployments from contractor-centric systems.
License volume aggregates with General Contractors; fastest expansion occurs among Engineering Firms as design-build delivery models proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
San Francisco anchors North American construction ERP demand as cloud-native platforms proliferate among venture-backed commercial builders. Heavy civil contractors in Chicago and Houston drive prevailing wage compliance adoption. Infrastructure stimulus in Berlin and Sydney accelerates multi-entity project controls deployment.
United States
Federal infrastructure stimulus and Davis-Bacon Act mandates drive certified payroll automation demand. OSHA recordkeeping requirements push safety-module integration into contractor platforms. Heavy civil operators in Texas and California retrofit ERP systems for EPA stormwater compliance tracking.
Germany
Climate and transformation fund allocations toward railway modernization create Mittelstand contractor demand. REACH chemical documentation requirements shape material traceability features in procurement modules. Engineering clusters in Munich and Stuttgart deploy multi-entity controls for cross-border project delivery.
Australia
National Construction Code thermal performance tightening drives embodied carbon accounting adoption. Head-contractor consolidation in Sydney and Melbourne bundles ERP access into project overhead. TGA-aligned pharmaceutical facility construction demands specialized compliance documentation tracking.
United Kingdom
CSRD carbon disclosure frameworks force retrofitting of legacy data architectures for emissions capture. London commercial developers prioritize field-to-office synchronization for high-rise project coordination. Midlands infrastructure contractors integrate CE marking documentation into procurement workflows.
Japan
METI digital construction promotion drives cloud migration among mid-market general contractors. JIS standards compliance shapes quality documentation modules in industrial facility builds. Osaka and Nagoya engineering firms adopt design-build integration for railway modernization projects.
Construction Enterprise Resource Planning (ERP) Software Market Competitive Landscape
Premium-margin players sit above commodity-margin players across deployment architecture sophistication. Consolidation pressures intensify as cloud-native platforms displace on-premises legacy installations. Three archetypes dominate: construction-native specialists with field-to-office workflow DNA, enterprise software incumbents extending project controls, and mid-market financial management anchors. Strategic moves concentrate on API ecosystem expansion and vertical feature acquisition.
Within the construction-native tier, Procore and CMiC exemplify field-centric platform architecture. Oracle Cloud and SAP S/4HANA occupy positions as enterprise-grade incumbents leveraging multi-entity reporting capabilities. Sage Intacct anchors the financial-management-focused segment with deep accounting module integration.
| Leading Market Players |
|---|
| Sage Intacct |
| Viewpoint Vista |
| CMiC |
| Jonas ERP |
| Archdesk |
| Procore |
| SAP S/4HANA |
| Oracle Cloud |
| Acumatica |
| Others |
Pricing and Supply Chain Analysis
Premium-to-commodity bifurcation between cloud-native suites and legacy on-premises systems splits both pricing power and vendor sourcing strategies across the construction ERP landscape. Tier-one general contractors in the United States pay subscription premiums for certified payroll automation under Davis-Bacon Act mandates, while mid-market trade contractors in Australia resist direct licensing fees and accept technology bundled through head-contractor project overhead.
Pricing Analysis
Outcome-based pricing tied to project portfolio throughput anchors premium tiers, with general contractors paying per-seat subscriptions scaled to bonded project volume and compliance module depth. Price differentiation separates Oracle Cloud and SAP S/4HANA enterprise deployments from Sage Intacct mid-market offerings through multi-entity reporting complexity and field-to-office synchronization granularity. Cost compression in the trade contractor tier intensifies because subscription fatigue limits standalone penetration, pushing general contractors to absorb platform costs into project overhead rather than enforce downstream licensing.
Supply Chain Analysis
Cloud infrastructure supply rests on hyperscale data center operators concentrated in the United States, Germany, and Australia where regional compliance mandates dictate data residency requirements. Software development labor pools feed from India and Eastern European engineering hubs, while specialized construction-technology talent for implementation and configuration remains anchored in North American and Western European metropolitan clusters. Single-source vulnerability concentrates in API ecosystem dependencies as best-of-breed procurement strategies multiply integration touchpoints. Distribution runs through direct enterprise sales teams for tier-one accounts and value-added reseller networks serving mid-market contractors with limited internal IT capacity.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a cost-of-compliance story where EPA stormwater tracking mandates and certified payroll automation under the Davis-Bacon Act erect barrier-to-entry moats favoring vendors with pre-built regulatory modules.
For Market Incumbents: Deploy API ecosystem expansion as the primary lever to capture best-of-breed procurement momentum and neutralize point-solution challengers. Incumbents should deepen certified payroll automation capabilities to defend against emerging cloud-native entrants targeting prevailing wage compliance gaps. Capacity addition in Australian and German implementation partner networks addresses construction technologist scarcity extending deployment timelines. For New Entrants and Emerging Players: Digital-native distribution through head-contractor bundled offerings bypasses trade contractor subscription resistance and unlocks penetration below the general contractor tier. New entrants should target Australian residential builders where technology mandates from consolidated tier-one builders create forced-adoption pathways. A compliance-first go-to-market angle emphasizing rapid Davis-Bacon Act configuration differentiates against incumbent implementation complexity. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by enterprise software incumbents seeking construction-native workflow DNA and field-to-office synchronization capabilities. Long-term viability favors vendors with multi-entity project controls depth serving heavy civil infrastructure portfolios across the United States and Germany. The signal to watch is EPA greenhouse gas reporting finalization for federal construction contracts, which would force retrofit demand and accelerate legacy displacement.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | API ecosystem expansion captures best-of-breed procurement momentum among mid-market contractors stitching together estimating and accounting systems. |
| Acquisition of Specialist Firm | Targeted purchases of certified payroll automation providers accelerate Davis-Bacon Act compliance module deployment for federal infrastructure portfolios. |
| Geographic Expansion | Australian head-contractor consolidation creates bundled distribution pathways penetrating trade contractors resistant to standalone subscriptions. |
| Strategic Partnership | Equipment telematics alliances with diesel fleet operators address EPA fuel-consumption tracking mandates for heavy civil contractors. |
| Product Launch | AI-assisted schedule-risk analytics modules target multi-prime project delivery complexity dominating United States commercial building verticals. |
Research Methodology
Document review covered SEC filings from publicly traded construction technology vendors, EPA regulatory dockets on stormwater and emissions tracking, and Davis-Bacon Act enforcement guidance, complemented by interviews with ERP implementation specialists at value-added resellers, construction technologists at tier-one general contractors, procurement officers at Australian head-contractor firms, and compliance managers at heavy civil operators. Secondary validation drew from customs data on software services trade, hyperscaler data center expansion disclosures, and federal infrastructure stimulus allocation reports. Bottom-up triangulation across deployment model adoption rates and top-down reconciliation against aggregate construction IT spending estimates anchored market sizing.
Cross-referencing historical replacement cycle compression against panel input from vendor sales leadership and implementation partner capacity constraints shaped the analytical framework. Segmentation dimensions modeled include deployment architecture, solution offering breadth, application vertical, and end-user organizational scale across the projection horizon. CAGRs derived from regression analysis of cloud adoption velocity and compliance mandate expansion. Industry-specific forecast inputs incorporated prevailing wage enforcement intensity and building energy code tightening trajectories in key jurisdictions.
The model holds under steady regulatory enforcement and infrastructure stimulus continuity; deviation in EPA rulemaking timelines or federal funding appropriations would shift replacement cycle assumptions. Forecasts reflect documented assumptions about cloud migration velocity and construction technologist labor pool expansion. Regulatory acceleration in greenhouse gas reporting and carbon disclosure frameworks warrants ongoing watch as potential demand inflection triggers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Voice to Text on Mobile Devices Market
Software & Services
Illustration Software Market
Software & Services
Enterprise Software Market
Software & Services
Saas-Based SCM Market
Software & Services
Global Electronic Design Automation Tools (EDA) Market
Software & Services
Winery Management Software Market
Software & Services
Productivity Software Publishing Market
Software & Services
Asia-Pacific IT Services Market
Software & Services
Global Pre-Employment Testing Software Market
Software & Services
Global Policy Management Software Market
Software & Services
Output Management Software Market
Software & Services
Mobile Device Management (MDM) Market
Software & Services
Meditation Software Market
Software & Services
Global Online Form Builder Software Market
Software & Services
Construction Software As A Service Market
Software & Services
Global Mobile Middleware Market