
 Spain Cloud Robotics Market | 2026-2036
Spain Cloud Robotics Market Size, Share, and Industry Trends Forecast 2026-2036
Spain Cloud Robotics Market Insights
Aftermarket service revenue is tilting toward cloud-native predictive maintenance platforms as manufacturers seek recurring income beyond hardware sales. Robotnik Automation SLL leverages its Barcelona engineering base to dominate mobile robot deployments across Iberian logistics networks. FANUC sustains its position through deep integration of cloud analytics into CNC and robotic controller ecosystems. NVIDIA competes by supplying GPU-accelerated edge-to-cloud inference stacks that power real-time robot learning.
Cloud robotics fuses distributed computing architectures with physical automation systems, enabling robots to offload computation, storage, and machine learning model updates to remote data centers while maintaining sub-100ms latency for time-critical control loops. Its primary purpose is to decouple cognitive intelligence from onboard hardware constraints, allowing smaller, cheaper robots to perform complex tasks. Autonomous mobile robots capture expanding margin pools as warehouse operators prioritize fleet orchestration over fixed automation, while machine learning and computer vision technologies lead adoption curves by enabling adaptive pick-and-place in unstructured environments. Collaborative robots remain a smaller but structurally important segment where safety-certified cloud monitoring reduces deployment costs.
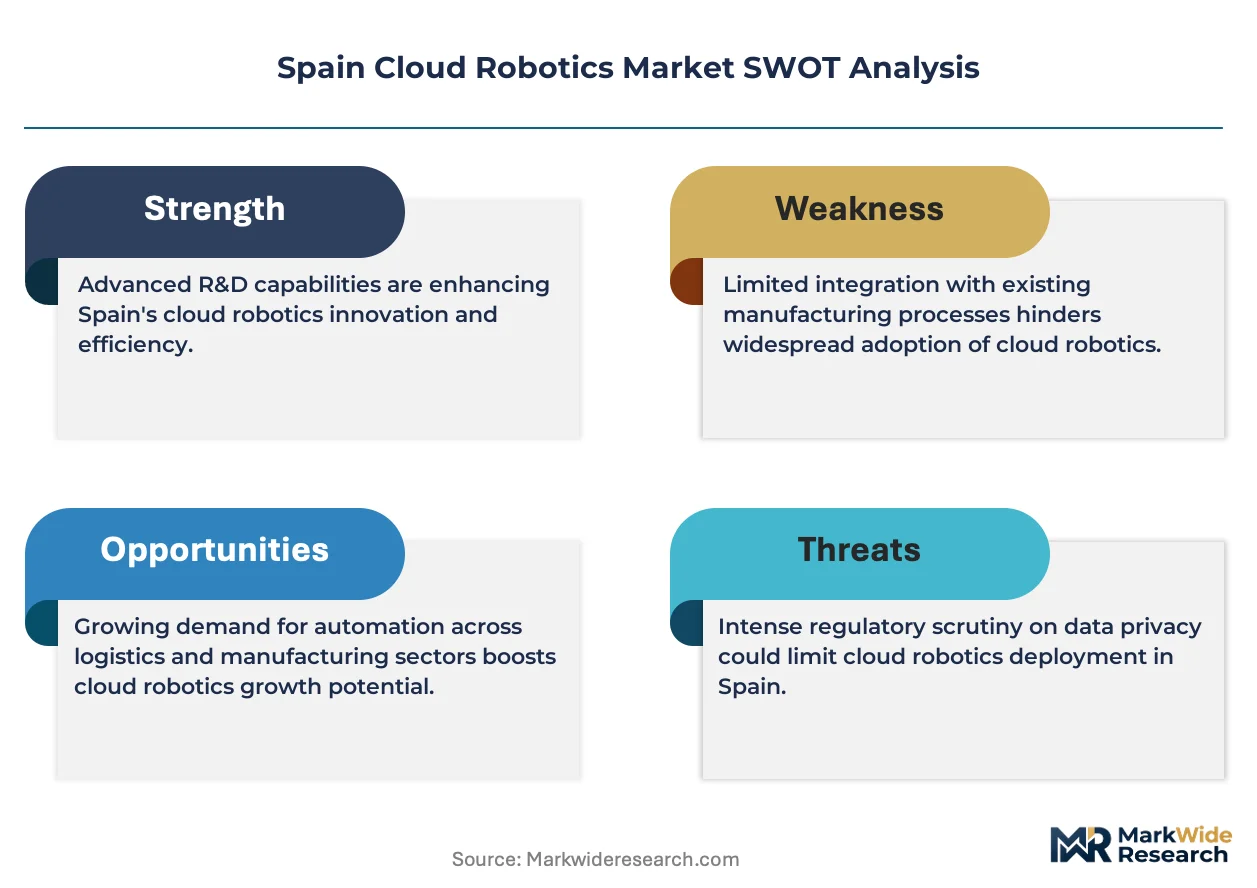
Spain's cloud robotics sector operates under the EU AI Act's risk-based classification system for autonomous systems, with additional oversight from the Spanish Data Protection Agency enforcing GDPR-compliant data flows between edge devices and cloud infrastructure. The Spanish Ministry of Digital Transformation and Public Function administers national AI strategy grants that condition funding on algorithmic transparency and cybersecurity certifications. Stakeholders must monitor how forthcoming EU product liability revisions assign responsibility between robot manufacturers, cloud platform providers, and end-user operators when AI-driven decisions cause operational failures.
Market Dynamics
The EU AI Act's risk-based classification system is compressing deployment timelines for autonomous systems across Spanish manufacturing corridors, forcing vendors to re-architect cloud-to-edge data flows before enforcement deadlines crystallize.
Growth Catalysts
- EU AI Act compliance mandates:High-risk autonomous system categories require algorithmic transparency documentation that cloud-native robotics platforms can generate automatically, pulling manufacturers toward subscription-based intelligence stacks.
- Automotive assembly automation:Spanish OEMs are retrofitting welding and painting lines with cloud-connected collaborative robots to reduce changeover times between electric and combustion vehicle production runs.
- Barcelona-Madrid logistics corridor concentration:Warehouse operators across this axis are consolidating robot procurement through fleet orchestration platforms that optimize cross-dock throughput.
Market Restraints
- Edge-to-cloud latency constraints:Sub-100 millisecond control loop requirements limit offloading of real-time motor control to distant data centers, preserving expensive onboard compute for safety-critical functions.
- German industrial controller dominance:Spanish integrators remain dependent on imported CNC and PLC ecosystems that resist open cloud APIs, creating vendor lock-in friction.
- GDPR data residency requirements:The Spanish Data Protection Agency enforces strict geographic boundaries on biometric and operational data generated by warehouse robots, complicating multi-tenant cloud architectures.
Strategic Opportunities
- Valencia port automation:Mediterranean container terminals are underpenetrated by cloud-orchestrated yard tractors compared to Rotterdam and Hamburg, creating first-mover space for fleet management vendors.
- 5G private network convergence:Telefónica's industrial 5G deployments in Basque Country manufacturing zones enable ultra-reliable low-latency communication that collapses the boundary between edge inference and cloud training.
- National AI strategy grants:The Spanish Ministry of Digital Transformation conditions funding on cybersecurity certifications, creating a subsidized on-ramp for compliant robotics startups.
Industry Challenges
- ROS 2 migration complexity:Legacy Robot Operating System installations in Spanish automotive plants require expensive refactoring to support secure DDS middleware and cloud-native node distribution.
- Functional safety engineer scarcity:ISO 13849 and IEC 62061 certification expertise concentrates in Stuttgart and Munich, forcing Spanish system integrators to import talent or delay collaborative robot deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spain Cloud Robotics Market |
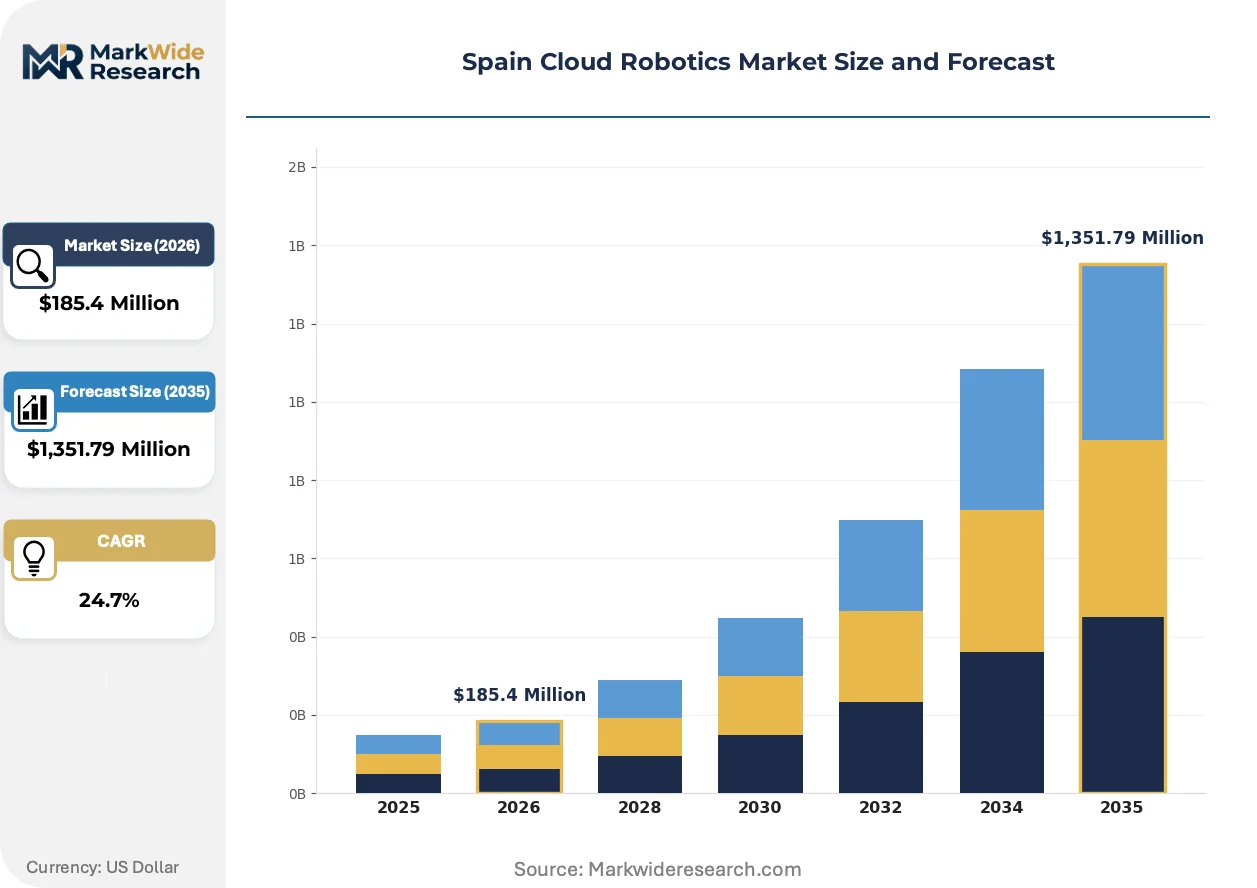
| Market Size in 2026 | $185.4 Million |
| Market Size in 2035 | $1,351.79 Million |
| CAGR (2026 – 2036) | 24.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Service Robots, Industrial Robots, Collaborative Robots, Autonomous Mobile Robots Application: Manufacturing, Logistics, Healthcare, Agriculture End User: Retail, Construction, Automotive, Defence Technology: Machine Learning, Computer Vision, NLP, Cloud Computing |
| Companies Covered | Robotnik Automation SLL, FANUC, IBM, Brain Corp, Teradyne, Inc., NVIDIA, CloudMinds, H2O.ai, ABB Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spain Cloud Robotics Market Trends and Innovations
Cloud-native predictive maintenance is displacing scheduled service contracts across Iberian logistics networks, compressing vendor revenue models toward continuous software monetization and away from hardware margins.
Digital twin technology is collapsing the cost of robot fleet simulation and path optimization. Automotive manufacturers in Pamplona and Vitoria-Gasteiz are deploying virtual commissioning environments that reduce physical prototype iterations by half. The technology compresses deployment risk and accelerates payback periods for multi-robot installations.
The EU AI Act's high-risk system obligations are forcing re-architecture of cloud robotics platforms. Spanish vendors must now implement human oversight interfaces and algorithmic change logging that satisfy notified body scrutiny. Collaborative robot deployments face the steepest compliance burden, driving consolidation toward larger platform providers with dedicated regulatory affairs functions.
Warehouse operators are unbundling after-sales service from hardware procurement, demanding API-first fleet management platforms that interoperate across robot brands. This procurement pattern shift disrupts traditional integrator relationships and elevates software-native vendors in Madrid's logistics hub. The trend concentrates buying power among multi-site operators running heterogeneous robot populations.
Spain Cloud Robotics Market Segmentation
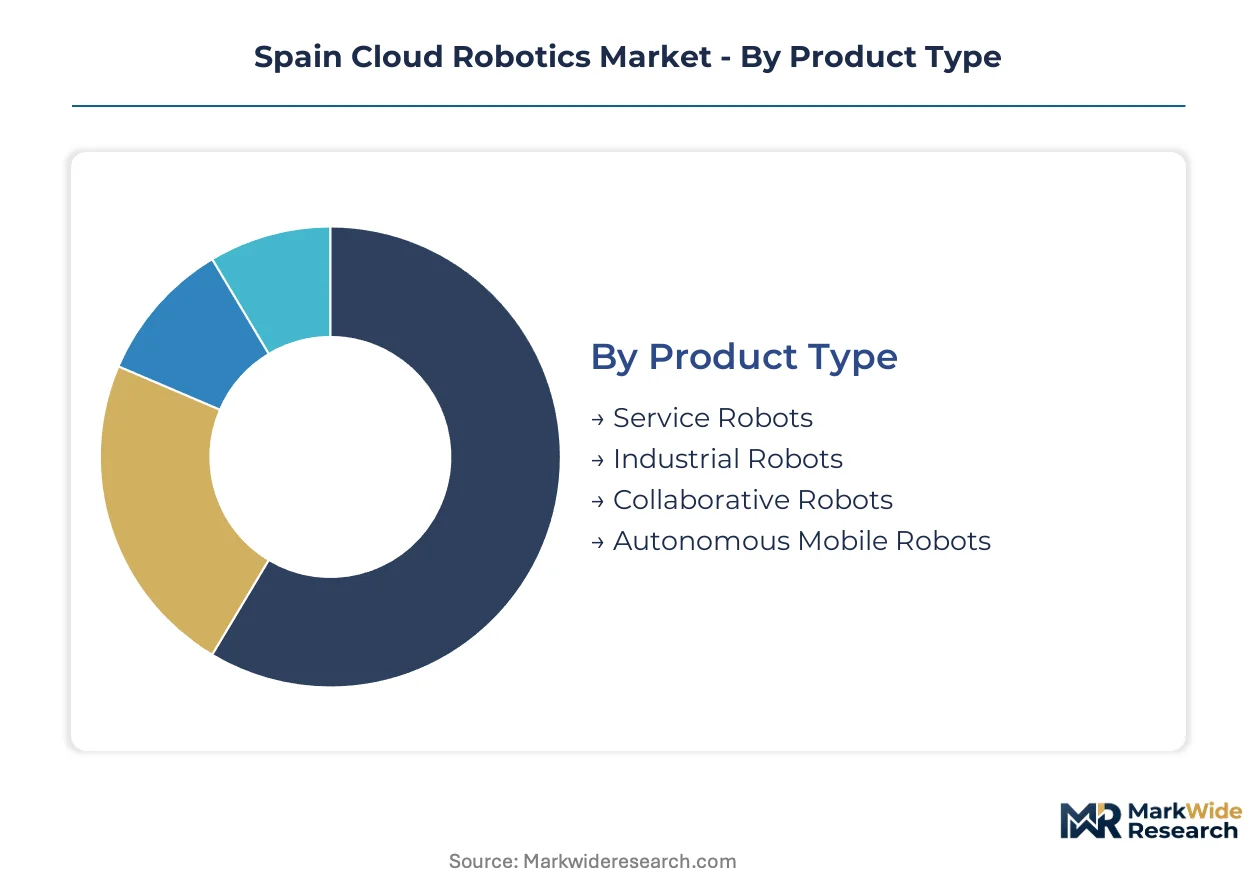
Cloud robotics segmentation in Spain reveals how computational offloading requirements vary sharply across physical form factors and operational environments. Distinct latency tolerances, safety certification burdens, and data residency obligations shape procurement patterns within each category.
Product Type:
Mature industrial installations coexist with emerging autonomous formats across Spanish manufacturing corridors.
- Industrial Robots:Fixed-position articulated arms with cloud-connected predictive maintenance modules dominate automotive welding and painting lines. Spanish OEMs in Pamplona and Vitoria-Gasteiz prioritize these systems for electric vehicle retooling flexibility.
- Autonomous Mobile Robots:Warehouse fleet orchestration platforms enable dynamic path planning across Barcelona-Madrid logistics hubs. Cloud-native navigation reduces onboard compute costs while GDPR-compliant data routing satisfies Spanish Data Protection Agency requirements.
- Service Robots:Hospitality and facility management deployments in Madrid's commercial districts leverage cloud speech recognition and remote monitoring.
- Collaborative Robots:Safety-certified force-limited arms with cloud-based human oversight interfaces face steepest EU AI Act compliance burdens.
Industrial robots handle the majority of throughput; autonomous mobile robots are expanding most quickly on share.
Application:
Cost tier stratification separates capital-intensive manufacturing deployments from lighter logistics implementations.
- Logistics:Cross-dock automation and last-mile fulfillment centers drive cloud robotics demand across the Barcelona-Madrid corridor. Fleet orchestration platforms optimize heterogeneous robot populations while unbundling after-sales service from hardware procurement.
- Manufacturing:Automotive assembly lines in Basque Country integrate cloud analytics for welding quality prediction and paint defect detection. 5G private networks from Telefónica collapse latency boundaries between edge inference and cloud model retraining.
- Healthcare:Surgical assistance and patient monitoring systems face stringent GDPR biometric data residency constraints.
- Agriculture:Precision harvesting robots in Andalusia and Murcia deploy cloud-based crop recognition with intermittent connectivity tolerance.
Logistics captures the steepest investment trajectory; manufacturing maintains the installed base concentration.
End User:
Customer type differentiation separates volume-driven automotive procurement from fragmented construction site requirements.
- Automotive:Spanish OEMs and tier-one suppliers mandate cloud-native predictive maintenance to compress total cost of ownership across multi-site robot fleets. Algorithmic transparency documentation required by EU AI Act high-risk system categories favors subscription-based intelligence stacks.
- Retail:Warehouse operators and last-mile delivery networks prioritize API-first fleet management that interoperates across robot brands.
- Construction:Project-based deployments in Madrid and Barcelona face intermittent connectivity and harsh environmental conditions limiting cloud dependency.
- Defence:Secure edge-to-cloud architectures with classified data handling requirements operate under national security procurement frameworks.
Automotive anchors procurement volume; retail is climbing the fastest on deployment share.
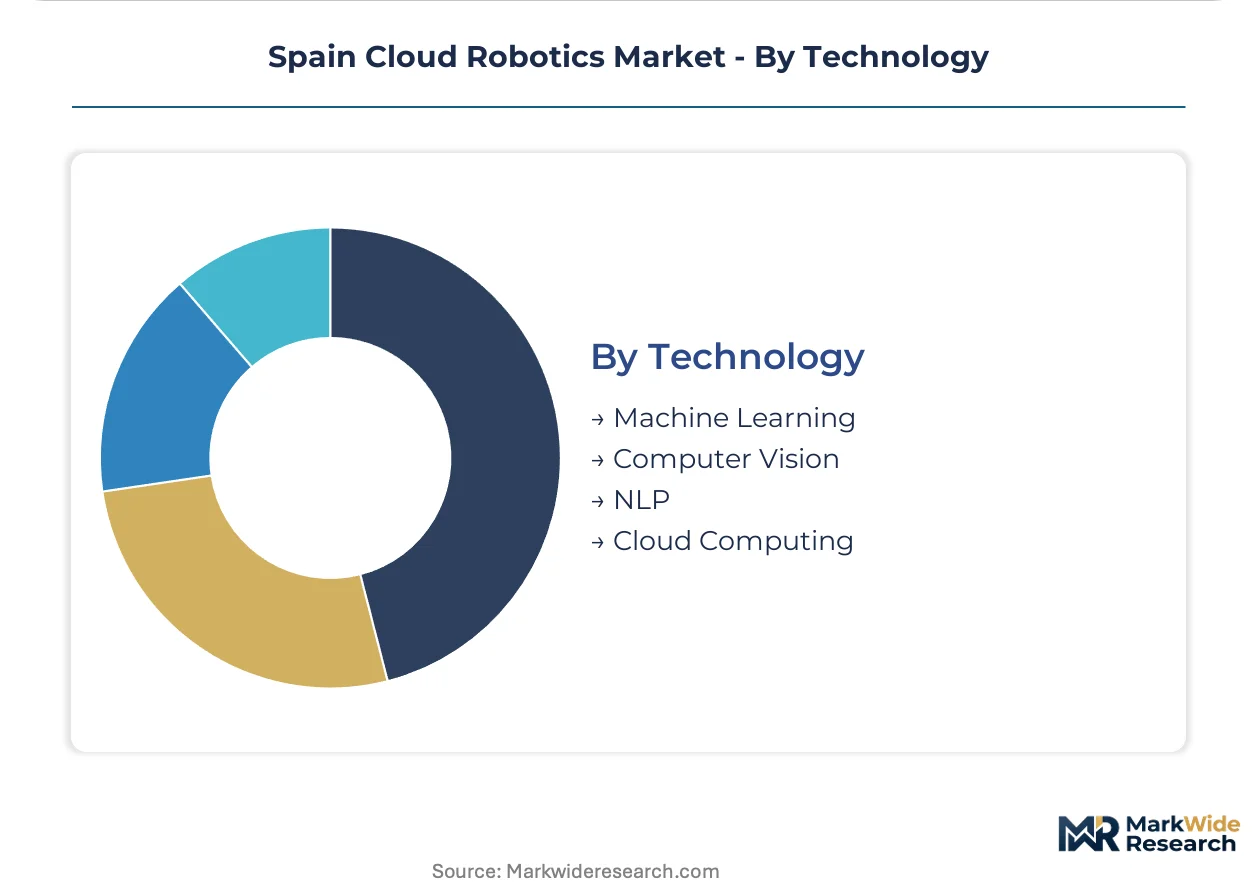
Technology:
Supply concentration in GPU acceleration and distributed computing architectures shapes competitive positioning.
- Machine Learning:Cloud-based model training and edge inference pipelines enable adaptive pick-and-place in unstructured warehouse environments. Spanish vendors leverage national AI strategy grants conditioned on cybersecurity certifications.
- Computer Vision:Real-time object detection and quality inspection systems process video streams through hybrid edge-cloud pipelines. GDPR constraints on biometric data force geographic containment of certain inference workloads.
- Cloud Computing:Distributed storage and containerized robotics middleware support multi-tenant fleet management platforms.
- NLP:Voice-directed warehouse operations and human-robot interaction modules require low-latency cloud speech synthesis.
Machine learning handles the majority of computational offload; computer vision is gaining share fastest on adoption curves.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Procurement elasticity varies sharply across Spain's industrial geography. Basque Country automotive buyers absorb premium pricing for safety-certified systems, while Andalusian agricultural operators demand cost-optimized edge computing. Madrid logistics clusters occupy the middle ground, trading off latency guarantees against subscription economics.
Madrid
Central Spain's logistics corridor drives fleet orchestration demand as warehouse operators consolidate multi-site robot procurement through API-first platforms. The Spanish Ministry of Digital Transformation administers national AI strategy grants that condition funding on algorithmic transparency. Madrid's commercial districts concentrate hospitality service robot deployments leveraging cloud speech recognition.
Catalonia
Barcelona's industrial corridor anchors mobile robot manufacturing with Robotnik Automation engineering mobile platforms for Iberian distribution networks. EU AI Act high-risk system categories force re-architecture of collaborative robot architectures for automotive suppliers. The Port of Barcelona presents underpenetrated opportunity for cloud-orchestrated yard automation relative to northern European terminals.
Basque Country
Automotive assembly automation concentrates in Pamplona and Vitoria-Gasteiz where OEMs retrofit welding lines with cloud-connected predictive maintenance. Telefónica's industrial 5G deployments collapse latency boundaries between edge inference and cloud model retraining. Spanish Data Protection Agency GDPR enforcement shapes data residency architectures for biometric quality inspection systems.
Valencia
Mediterranean container terminals lag Rotterdam and Hamburg in cloud-orchestrated yard tractor penetration, creating first-mover space for fleet management vendors. Valencia's automotive tier-one suppliers adopt digital twin virtual commissioning to compress multi-robot deployment timelines. The regional port authority pilots autonomous guided vehicles with hybrid edge-cloud navigation.
Andalusia
Precision agriculture robotics in Andalusia and Murcia deploy intermittent-tolerance crop recognition with cloud-based model updates during connectivity windows. Farm operators prioritize cost-optimized edge compute over low-latency guarantees for harvesting automation. The Spanish Ministry of Agriculture coordinates with digital transformation programs on rural 5G infrastructure subsidies.
Spain Cloud Robotics Market Competitive Landscape
Industrial incumbents and cloud-native specialists split the market across divergent capability stacks. The vendor base organizes around three strategic archetypes: safety-certified hardware manufacturers, GPU-accelerated inference platform suppliers, and mobile robot fleet orchestrators. Dominant competitive moves include M&A to acquire edge-to-cloud middleware expertise and strategic partnerships to embed predictive maintenance into existing controller ecosystems.
Within the mobile robot tier, Robotnik Automation exemplifies the Barcelona-engineering archetype anchoring Iberian logistics deployments. FANUC occupies the industrial controller position with deep CNC and robotic controller integration. NVIDIA represents the accelerated computing vector supplying GPU stacks that power real-time robot learning pipelines. These three anchors illustrate how competitive positioning fragments across hardware, software, and silicon layers rather than consolidating around end-to-end platforms.
| Leading Market Players |
|---|
| Robotnik Automation SLL |
| FANUC |
| IBM |
| Brain Corp |
| Teradyne, Inc. |
| NVIDIA |
| CloudMinds |
| H2O.ai |
| ABB Ltd. |
| Others |
Pricing and Supply Chain Analysis
The Barcelona-Madrid logistics corridor's freight cost dynamics concentrate supply-side power among German industrial controller manufacturers while forcing Spanish integrators into three-tier pricing structures across premium, standard, and economy certification levels.
Pricing Analysis
Aftermarket service revenue tiers now drive lifetime value as cloud-native predictive maintenance platforms displace scheduled hardware contracts. Subscription-based intelligence stacks command premium positioning against transactional robot sales, with EU AI Act algorithmic transparency documentation becoming a price differentiation driver. Pricing pressure stems from warehouse operators unbundling service procurement from hardware, compressing integrator margins. Small-to-mid logistics operators exhibit highest price sensitivity while automotive OEMs absorb premium positioning for safety-certified systems.
Supply Chain Analysis
Supplier-financing facilities from German CNC and PLC vendors extend payment terms that lock Spanish integrators into proprietary ecosystems. Component sourcing concentrates in Germany, Japan, and Taiwan for precision servo motors, industrial GPUs, and sensor arrays. The supply chain rests on single-source vulnerability for safety-certified collaborative robot controllers. Distribution runs through Madrid-based system integrators serving the Barcelona-Madrid logistics corridor with aftermarket service networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Spain's cloud robotics sector sits at a platform-economics inflection where API-first fleet orchestration unbundles traditional hardware-service bundles, collapsing procurement power toward software-native vendors capable of cross-brand interoperability.
For Market Incumbents: Insulate controller ecosystem dominance by embedding cloud analytics deeper into CNC and robotic controller firmware before open ROS 2 middleware erodes proprietary API control. Acquire edge-to-cloud middleware specialists to defend against software-native fleet orchestration platforms. Prioritize cybersecurity certification investment to capture national AI strategy grant flows.
For New Entrants and Emerging Players: Pursue Valencia port automation as the most penetrable geography, where Mediterranean container terminals lag northern European yard tractor deployment by half. Target agricultural robotics in Andalusia with intermittent-tolerance crop recognition priced below premium industrial tiers. Lead with 5G private network integration as the go-to-market angle through Telefónica partnership channels.
For Investors and Strategic Acquirers: The EU AI Act's high-risk system enforcement deadlines reshape the acquisition landscape toward platform providers with dedicated regulatory affairs functions and existing notified body relationships. Position for five-to-ten year consolidation around end-to-end cloud robotics stacks. Target mobile robot fleet orchestrators with GDPR-compliant data routing architectures. Watch for algorithmic transparency documentation automation as the inflection signal separating scalable platform investments from stranded hardware assets.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | API-first fleet orchestration collapses procurement power toward software-native vendors in Madrid logistics clusters. |
| Acquisition of Specialist Firm | Edge-to-cloud middleware expertise addresses ROS 2 migration complexity plaguing Spanish automotive plants. |
| Strategic Partnership | Telefónica 5G private network deployment enables ultra-reliable low-latency communication for Basque Country manufacturers. |
| Product Launch | Cloud-native predictive maintenance platforms displace scheduled service contracts across Iberian logistics networks. |
| Geographic Expansion | Valencia port automation presents first-mover space for fleet management vendors against Rotterdam and Hamburg benchmarks. |
Research Methodology
A spread of perspectives from robotics platform engineers, automotive manufacturing directors, warehouse fleet operators, and cloud infrastructure specialists converged on the working assumptions underlying this analysis. Primary fieldwork combined structured interviews with secondary validation against EU AI Act implementation guidance, Spanish Data Protection Agency enforcement patterns, and national AI strategy grant disbursement records. Bottom-up installation data triangulated with top-down industrial automation spending estimates.
Demand-supply-balance framing anchored the forecast framework across the analysis window, modeling robot population growth against cloud infrastructure capacity expansion. Segmentation dimensions included product type, application vertical, end-user industry, and technology stack. CAGRs derived from installation trajectory analysis and software subscription monetization curves. Key inputs incorporated 5G private network deployment timelines and EU AI Act compliance cost assumptions.
Sensitivities concentrate around EU AI Act enforcement timeline acceleration, Telefónica 5G coverage expansion rates, and German controller vendor API opening decisions. Forecasts reflect documented assumptions on interoperability standards adoption. Macroeconomic contraction, regulatory delay, or breakthrough edge compute autonomy would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
Logistics Robots Market
Robotics and Automation
Robotic Process Automation in BFSI Market
Robotics and Automation
United States Articulated Robot Market
Robotics and Automation
Professional Service Robots Market
Robotics and Automation
Construction Robotics Market
Robotics and Automation
Global Robotic Process Automation in Healthcare Market
Robotics and Automation
Latin America Warehouse Robotics Market
Robotics and Automation
Global Medical Robotic Systems Market
Robotics and Automation
Autonomous Mobile Robots for Logistics and Warehousing Market
Robotics and Automation
Automated Liquid Handling Technologies Market
Robotics and Automation
Robotic Tool Changer Market
Robotics and Automation
Global Demolition Robots Market
Robotics and Automation
Laboratory Robotics Market
Robotics and Automation
United States Agricultural Robots Market
Robotics and Automation
Robotics in Shipbuilding Market
Robotics and Automation
Robot Market