
 Global Wafer Handling Robots Market | 2026-2036
Global Wafer Handling Robots Market Size, Share, and Industry Trends Forecast 2026-2036
Global Wafer Handling Robots Market Outlook
The EU F-Gas Regulation is shifting procurement priorities across European semiconductor fabs toward hermetic wafer handling systems that eliminate process gas venting. Brooks Automation leverages its vacuum-integrated atmospheric robot portfolio to anchor fab automation retrofits across Germany and France. Yaskawa Electric Corporation competes through high-purity SCARA architectures optimized for 300mm wafer transfer in nitrogen-purged environments. Nidec Corporation specializes in direct-drive motors that sustain particle-free operation across extended duty cycles in Taiwanese foundry installations.
Wafer handling robots are precision electromechanical systems engineered for sub-micron repeatability in vacuum or inert-gas environments, typically employing harmonic drive transmissions and ceramic or aluminum alloy end-effectors to prevent metallic contamination during silicon wafer transport between process chambers. Robotic Arms dominate technology adoption due to their established kinematic reliability in lithography and etch tool integration, while Autonomous Mobile Robots represent the fastest-expanding segment as fabs adopt fleet-based AMHS architectures for inter-bay wafer logistics. OEMs capture the largest end-user value pool through captive integration into deposition and inspection equipment, whereas Contract Manufacturers are gaining share by supplying refurbished and legacy-compatible handling units for mature-node capacity expansions.
FDA oversight of semiconductor manufacturing equipment used in medical device fabrication imposes traceability requirements on robot motion logging and contamination protocols. EPA emissions standards and REACH chemical restrictions in Europe compel manufacturers to certify lubricants and seal materials for cleanroom compatibility. Japan's METI semiconductor revitalization subsidies and South Korea's K-Semiconductor Belt incentives are redirecting capital toward domestic robot supply chain localization. Stakeholders must monitor how divergent national subsidy structures reshape procurement geography and supplier qualification timelines.
Market Dynamics
The EU F-Gas Regulation is compressing equipment replacement cycles as fabs abandon open-loop atmospheric handlers in favor of hermetic vacuum-integrated architectures that eliminate fluorinated compound venting. This single regulatory pressure is restructuring procurement specifications across Taiwanese, South Korean, and German semiconductor clusters simultaneously.
Growth Catalysts
- Sub-7nm node proliferation:Advanced lithography and etch tools in Taiwanese foundries require vacuum-compatible robots with sub-micron positioning repeatability, pulling demand for harmonic drive transmissions and ceramic end-effectors.
- METI semiconductor subsidies:Japan's revitalization incentives redirect domestic capital toward localized robot supply chains, accelerating captive production of direct-drive motors and cleanroom-compatible actuators.
- Closed-loop handling mandates:REACH chemical restrictions and EPA emissions standards compel fabs to retrofit atmospheric systems with nitrogen-purged transfer chambers that minimize wafer exposure and lubricant contamination.
Market Restraints
- Neodymium magnet supply concentration:Rare-earth permanent magnets for direct-drive motors concentrate in Chinese processing facilities, exposing robot OEMs to export quota volatility and forced technology transfer requirements.
- Vacuum seal material incompatibility:Fluorocarbon elastomers face ECHA scrutiny under REACH candidate list expansion, forcing qualification of perfluoroether alternatives with unproven duty-cycle longevity.
- Cleanroom construction lead times:ISO 14644 Class 1 facility certification for robot validation requires 18-24 month buildouts in South Korea and the United States, throttling capacity expansion velocity.
Strategic Opportunities
- Legacy node refurbishment:Contract manufacturers in Malaysia and Vietnam capture value from mature-node capacity expansions by supplying rebuilt atmospheric robots with updated motion controllers.
- Fleet-based AMHS architectures:Autonomous Mobile Robots enable inter-bay logistics in sprawling Arizona and Texas fab campuses where fixed-track systems prove inflexible.
- K-Semiconductor Belt localization:South Korea's domestic incentive structure favors qualified local integrators for 300mm wafer handling retrofits, creating protected procurement channels for regional suppliers.
Industry Challenges
- Mechatronics talent scarcity:Vacuum dynamics expertise and harmonic drive calibration skills concentrate in aging Japanese and German engineering workforces, constraining fab automation deployment timelines.
- Multi-vendor integration complexity:Semiconductor OEMs cobble together lithography, deposition, and inspection tools from competing suppliers, forcing robot vendors to maintain backward-compatible communication protocols across generations.
- ISO 9283 repeatability certification:Sub-micron positioning validation requires specialized interferometry facilities that concentrate in Stuttgart, Dresden, and Yokohama, creating testing bottlenecks for new market entrants.
Report Scope
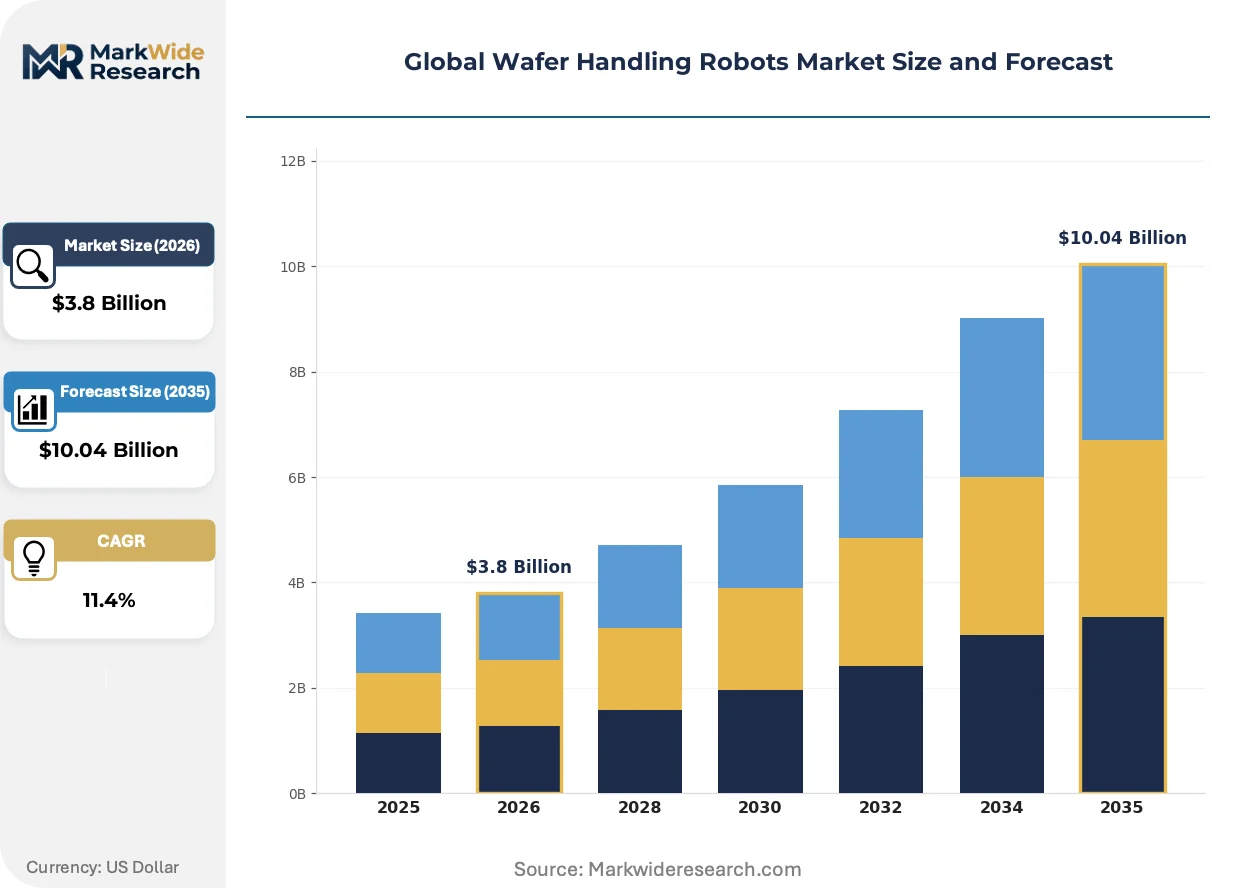
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Wafer Handling Robots Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Semiconductor Manufacturing, Flat Panel Display, Photovoltaics, Optoelectronics End User: OEMs, Tier-1 Suppliers, Research Institutes, Contract Manufacturers Technology: Robotic Arms, Autonomous Mobile Robots, Collaborative Robots, Cartesian Robots Deployment: In-Fab, Out-Fab, Automated Material Handling, Manual Handling |
| Companies Covered | Yaskawa Electric Corporation, DAIHEN Corporation, Brooks Automation, Hirata Corporation, Nidec Corporation, Kawasaki Robotics, Kensington Laboratories, JEL Corporation, RORZE Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Wafer Handling Robots Market Strategic Shifts
Wafer handling architectures are bifurcating between vacuum-integrated fixed automation and mobile fleet systems, with material science and regulatory chemistry dictating the pace of displacement across fab generations.
Magnetic levitation transport modules are absorbing linear motor stages in lithography tool integration. TSMC and Samsung Foundry deploy these frictionless systems for 300mm wafer shuttle between exposure and metrology chambers. The technology is absorbing market share from belt-driven atmospheric handlers by eliminating particle-generating mechanical contact surfaces.
The EU F-Gas Regulation bans hydrofluorocarbon venting from semiconductor process equipment starting 2027. Equipment makers accelerate hermetic robot designs that recirculate inert gases rather than exhausting to atmosphere. German fabs in Dresden and Saxony lead retrofit procurement, compressing qualification timelines for European suppliers with existing vacuum-integrated portfolios.
Foundry buyers now unbundle after-sales service from initial robot procurement, contracting third-party maintenance specialists for harmonic drive replacement and encoder recalibration. This disintermediation pressures OEM service margins while expanding independent technical service providers in Hsinchu and Pyeongtaek cluster zones.
Global Wafer Handling Robots Market Segmentation
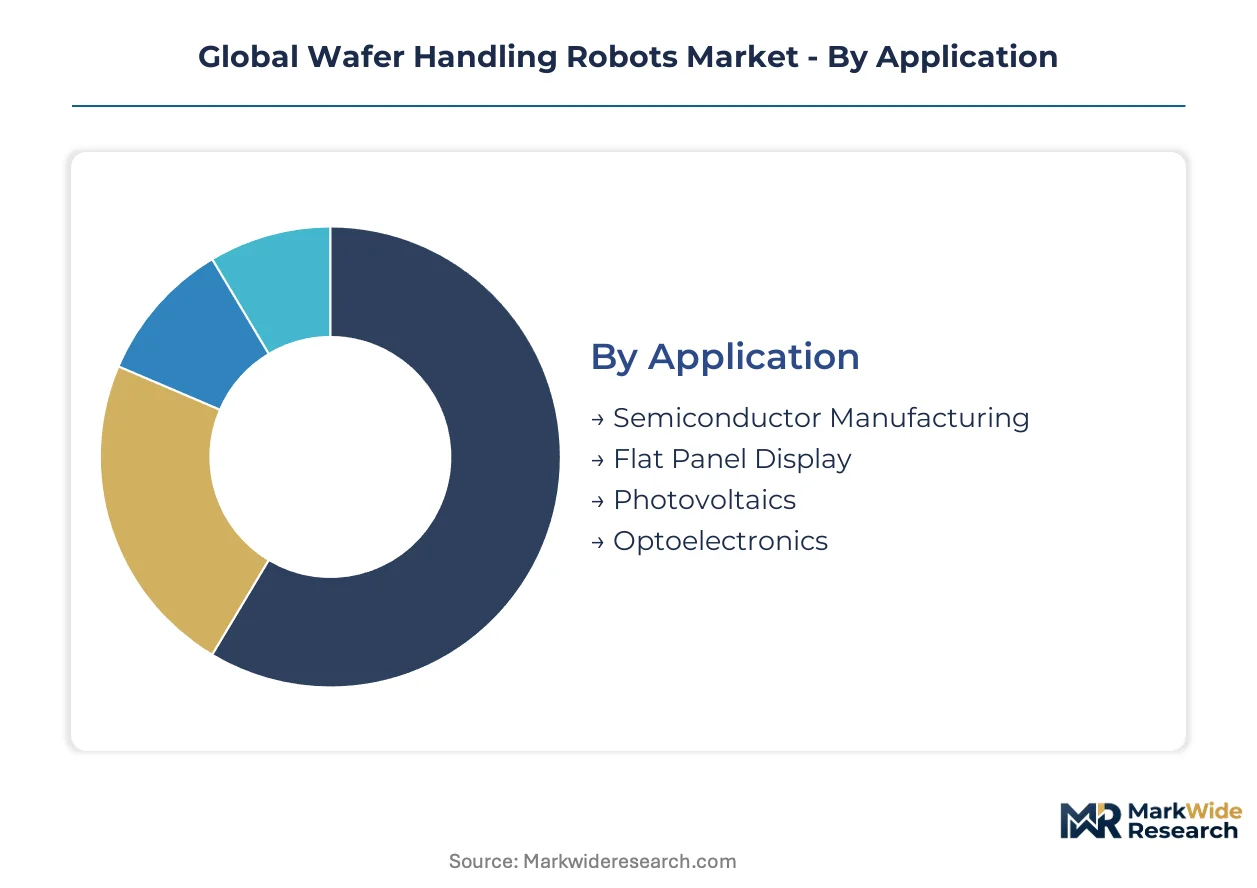
Wafer handling robot procurement patterns diverge sharply across fab generations and process architectures. Segmentation reveals how equipment specifications map to node maturity, cleanroom class, and integration depth.
Application:
Upgrade cycles in semiconductor manufacturing are compressing as EU F-Gas Regulation deadlines force hermetic system retrofits across Taiwanese and German fabs.
- Semiconductor Manufacturing:Vacuum-integrated robots with harmonic drive transmissions dominate lithography and etch tool integration. TSMC and Samsung Foundry in Hsinchu and Pyeongtaek drive demand for sub-micron repeatability in advanced node production below 7nm.
- Flat Panel Display:Atmospheric SCARA architectures handle large-format glass substrates in nitrogen-purged environments. Korean display fabs in Gumi prioritize particle-free operation over vacuum compatibility.
- Photovoltaics:Cost-optimized Cartesian systems serve silicon wafer sorting in Chinese solar cell plants.
- Optoelectronics:Precision pick-and-place units support LED and laser diode packaging in Japanese compound semiconductor facilities.
Semiconductor Manufacturing sits at the top of the volume ranking, with Flat Panel Display climbing the fastest.
End User:
Customer type dictates pricing tolerance and service contract structures across the procurement landscape.
- OEMs:Captive integration into deposition and inspection equipment creates locked-in supply relationships. Applied Materials and Tokyo Electron specify custom end-effector geometries that robot vendors must accommodate.
- Contract Manufacturers:Refurbished atmospheric robots with updated motion controllers serve mature-node expansions in Malaysia and Vietnam. These buyers prioritize lead time over specification breadth.
- Tier-1 Suppliers:Subsystem integrators in South Korea's K-Semiconductor Belt qualify local handling units for 300mm retrofits.
- Research Institutes:Low-volume, high-flexibility procurement from imec in Belgium and CEA-Leti in France emphasizes protocol adaptability.
OEMs command the largest value pool, with Contract Manufacturers gaining share fastest through refurbishment economics.
Technology:
Architecture choice hinges on contamination control requirements and fab layout constraints.
- Robotic Arms:Established kinematic reliability in vacuum and atmospheric variants dominates lithography tool integration. Ceramic end-effectors and aluminum alloy linkages prevent metallic contamination during wafer transport.
- Autonomous Mobile Robots:Fleet-based AMHS architectures enable inter-bay logistics in sprawling Arizona and Texas fab campuses. Intel and TSMC deploy these where fixed-track systems prove inflexible.
- Collaborative Robots:Emerging deployment in metrology and packaging applications where human-robot proximity is unavoidable.
- Cartesian Robots:Linear motor stages persist in legacy atmospheric handlers facing replacement pressure from magnetic levitation alternatives.
Robotic Arms anchor current deployment volumes, with Autonomous Mobile Robots posting the steepest expansion trajectory.
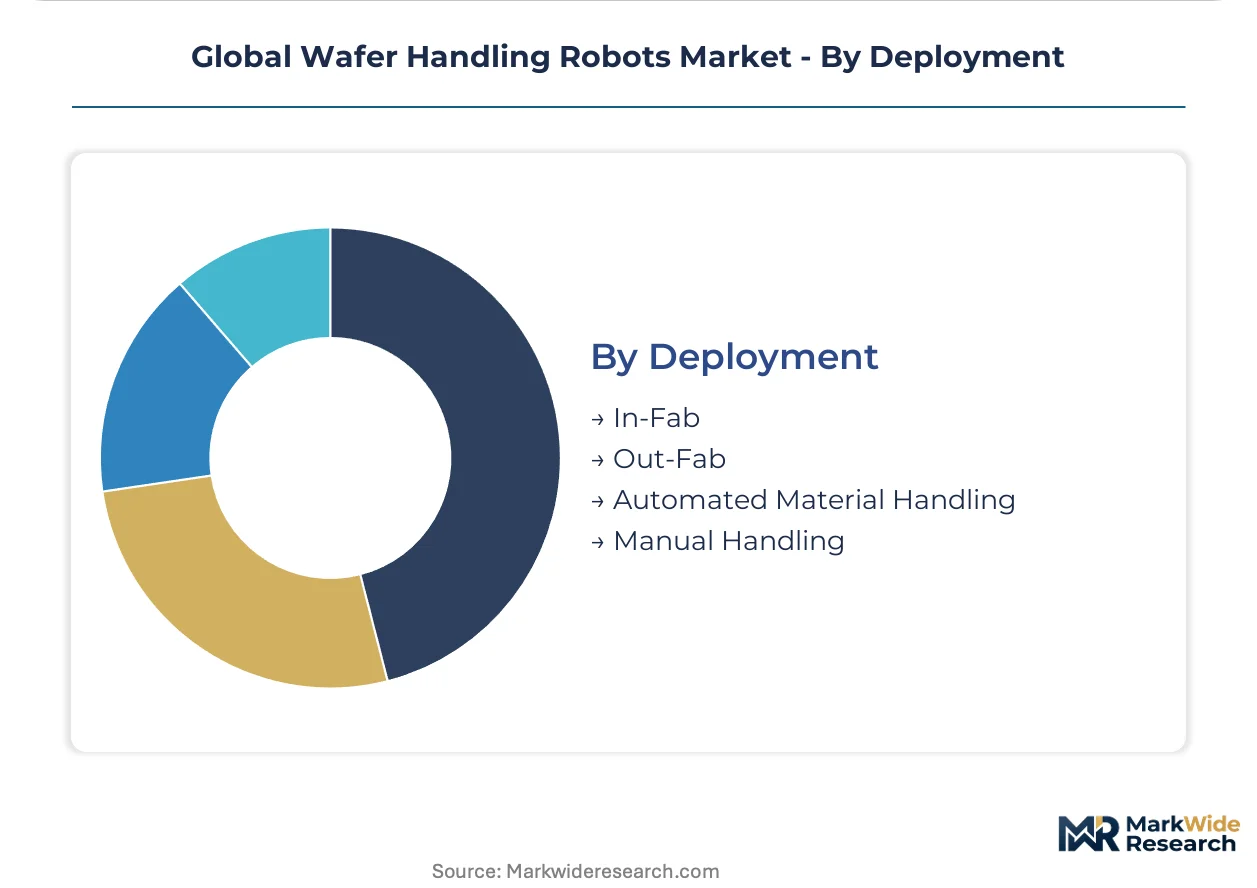
Deployment:
Physical integration depth determines cleanroom classification and regulatory exposure.
- In-Fab:Vacuum-integrated robots operate inside process chambers with ISO 14644 Class 1 certification. German fabs in Dresden lead retrofit procurement of hermetic systems eliminating fluorinated compound venting.
- Automated Material Handling:Inter-bay and intra-bay logistics systems connect lithography, deposition, and inspection tools. Fleet management software from Japanese vendors coordinates 300mm wafer shuttle.
- Out-Fab:External storage and shipping preparation robots face less stringent contamination protocols.
- Manual Handling:Declining share as OSHA and EU ergonomics directives drive automation in US and European facilities.
In-Fab systems absorb the dominant equipment budget, with Automated Material Handling expanding most quickly as fab footprints grow.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The wafer handling robot industry traces its commercial origins to Japanese precision engineering clusters in the 1980s, where harmonic drive technology and vacuum-compatible actuators first achieved semiconductor-grade reliability. Production scaling subsequently concentrated in East Asian foundry ecosystems, with German engineering centers later specializing in hermetic system architectures for European regulatory compliance.
Taiwan
TSMC's Hsinchu and Tainan Science Park fabs drive demand for sub-micron positioning systems in advanced node production below 7nm. The island's Industrial Development Bureau subsidizes automation upgrades under the Smart Machinery Program. Kaohsiung's emerging semiconductor cluster is attracting vacuum robot suppliers for mature-node capacity expansions.
South Korea
Samsung Foundry and SK Hynix operate Pyeongtaek and Icheon fabs requiring vacuum-integrated handling for EUV lithography integration. The K-Semiconductor Belt initiative redirects procurement toward domestic integrators for 300mm retrofits. Sejong's special economic zone hosts qualification facilities for local robot vendors seeking foundry certification.
United States
Intel's Arizona and Ohio fab campuses deploy fleet-based AMHS architectures where fixed-track systems prove inflexible. EPA emissions standards and OSHA cleanroom directives compel nitrogen-purged transfer chamber retrofits. Texas Instruments' Richardson and Sherman facilities anchor mature-node demand for refurbished atmospheric handlers.
Germany
GlobalFoundries' Dresden fab leads European retrofit procurement of hermetic systems eliminating fluorinated compound venting. The EU F-Gas Regulation compresses equipment replacement cycles across Saxony and Bavaria semiconductor clusters. Stuttgart maintains specialized interferometry facilities for ISO 9283 repeatability certification.
Japan
Tokyo Electron and Shin-Etsu Chemical anchor Nagoya and Kyushu demand for captive integration of handling subsystems. METI semiconductor revitalization subsidies redirect capital toward localized direct-drive motor production. Yokohama's precision engineering workforce sustains vacuum dynamics expertise for harmonic drive calibration.
Global Wafer Handling Robots Market Competitive Environment
Premium-margin players sit above commodity-margin players across vacuum-integrated versus atmospheric handler architectures, with hermetic system specialists commanding pricing power under EU F-Gas regulatory pressure. The vendor base spans Japanese precision engineering conglomerates, European vacuum technology specialists, and emerging Asian integrators. Three archetypes dominate: captive subsystem suppliers integrated into deposition equipment, independent robot OEMs selling to contract manufacturers, and refurbishment specialists serving mature-node expansions. Competitive moves concentrate on strategic partnerships for fleet management software and geographic expansion into subsidy-protected South Korean procurement channels.
Among Japanese precision engineering conglomerates, Yaskawa Electric Corporation and Nidec Corporation exemplify the captive technology tier, with the former representing high-purity SCARA architectures and the latter anchoring direct-drive motor specialization. Brooks Automation occupies a position within the vacuum-integrated portfolio segment, reflecting North American hermetic system capabilities. These three names illustrate how supplier qualification timelines and regulatory chemistry expertise create defensive positioning against commodity-margin competition.
| Leading Market Players |
|---|
| Yaskawa Electric Corporation |
| DAIHEN Corporation |
| Brooks Automation |
| Hirata Corporation |
| Nidec Corporation |
| Kawasaki Robotics |
| Kensington Laboratories |
| JEL Corporation |
| RORZE Corporation |
| Others |
Value Chain & Pricing Dynamics
Harmonic drive calibration expertise concentrates in Yokohama and Stuttgart engineering workforces, creating labor-cost differentials that separate premium vacuum-integrated systems from refurbished atmospheric handlers serving mature-node expansions.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates procurement, with vacuum-integrated architectures commanding spreads based on ISO 9283 certification tier and after-sales service bundling. Price differentiation hinges on sub-micron repeatability grade and geographic delivery cost to Hsinchu or Dresden clusters. Cost compression in the economy tier is intensifying because contract manufacturers in Malaysia and Vietnam compete on refurbished unit lead times. Contract manufacturers exhibit highest price sensitivity, while OEMs purchasing captive integration show lowest sensitivity due to locked-in tool specifications.
Supply Chain Analysis
ISO 9283 certification and foundry qualification timelines gate supply access, with component sourcing drawing from Japan, Germany, and Taiwan for harmonic drive transmissions, ceramic end-effectors, and direct-drive motors. Rare-earth permanent magnets for motor assemblies rest on Chinese processing concentration. Single-source vulnerability in neodymium magnet supply exposes OEMs to export quota volatility. Distribution runs through Tier-1 subsystem integrators in South Korea's K-Semiconductor Belt and captive supply channels at Tokyo Electron and Applied Materials.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Wafer Handling Robots Market functions as a stable compounder, with EU F-Gas Regulation mandates forcing continuous retrofit demand across European and East Asian fab clusters.
For Market Incumbents: Anticipate margin compression from magnetic levitation transport modules displacing belt-driven atmospheric handlers in lithography tool integration. Prioritize backward integration into direct-drive motor production to offset rare-earth supply concentration. Deepen certification investments at Stuttgart and Yokohama interferometry facilities to extend qualification timeline advantages over emerging Asian integrators. For New Entrants and Emerging Players: The EU F-Gas Regulation in Germany and France opens a window for hermetic system specialists without legacy atmospheric handler portfolios. Target refurbishment economics serving Texas Instruments' Richardson mature-node expansions and Arizona AMHS fleet deployments. Pursue third-party maintenance service contracts as foundry buyers unbundle after-sales support from initial procurement. For Investors and Strategic Acquirers: Semiconductor OEMs with captive handling subsystem integration represent the most active acquirer in this space, seeking vacuum dynamics expertise unavailable through hiring. Position for five-to-ten year holding periods as node migration below 3nm sustains replacement cycle velocity. Monitor METI subsidy disbursement rates as inflection indicator for Japanese supply chain localization momentum.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Direct-Drive Motors | METI subsidies accelerate captive motor production, reducing rare-earth exposure for Japanese robot OEMs. |
| Hermetic System Retrofit Certification | ECHA REACH scrutiny on fluorocarbon elastomers forces perfluoroether alternative qualification at Dresden fabs. |
| Fleet Management Software Partnership | Intel's Arizona campus deploys Japanese-coordinated AMHS architectures for inter-bay 300mm wafer logistics. |
| Refurbishment Capacity Expansion | Malaysian contract manufacturers capture value from Texas Instruments' Sherman mature-node equipment upgrades. |
| Magnetic Levitation Transport Deployment | TSMC and Samsung Foundry absorb frictionless systems for lithography-to-metrology chamber shuttle. |
Study Parameters
Coverage spans East Asia, North America, and Europe, with primary inputs from each region combined through bottom-up and top-down triangulation. Primary interviews engaged fab automation directors, OEM procurement teams at deposition equipment suppliers, Tier-1 subsystem integrators in South Korea, and aftermarket service heads in Hsinchu and Pyeongtaek. Secondary validation drew from SEC filings of listed robot OEMs, METI subsidy disbursement records, ECHA REACH candidate list updates, and customs data on harmonic drive component trade flows.
Granularity-level modeling operated at technology-architecture, end-user-category, and regional-cluster dimensions across the analysis window. Segment-level CAGRs were derived from equipment replacement cycle compression rates and fab capacity expansion pipelines. Industry-specific forecast inputs incorporated EU F-Gas Regulation compliance deadlines and K-Semiconductor Belt localization incentive structures without year-specific anchoring.
Forecast precision tightens around the base case; tail outcomes carry wider variance under neodymium export quota disruptions or ECHA fluorocarbon elastomer bans. Forecasts reflect documented assumptions on node migration velocity and subsidy program continuity. A model refresh is warranted upon material change in EU F-Gas Regulation enforcement timelines or METI semiconductor revitalization funding levels.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
Pipe Inspection Robot Market
Robotics and Automation
Logistics Robotics Market
Robotics and Automation
Snake Robots Market
Robotics and Automation
Short-Range Drone Package Delivery Market
Robotics and Automation
Security and Law Enforcement Robot Market
Robotics and Automation
Middle East and Africa Medical Robots Market
Robotics and Automation
Delta Robotics Market
Robotics and Automation
Europe Cloud Robotics Market
Robotics and Automation
Latin America Automated Guided Vehicle (AGV) Market
Robotics and Automation
Deep Sea Robot Market
Robotics and Automation
Singapore Cloud Robotics Market
Robotics and Automation
Smart Sweeper Market
Robotics and Automation
Automated Plate Handlers Market
Robotics and Automation
Claytronics Market
Robotics and Automation
Global Medical Robotic Systems Market
Robotics and Automation
Intelligent Vending Machines Market