
 Risk Analytics Market | 2026-2036
Risk Analytics Market Size, Share, and Industry Trends Forecast 2026-2036
Risk Analytics Market Intelligence
The transition toward cloud-based and SaaS deployment models is reshaping competitive positioning for risk analytics software providers. This shift allows for greater scalability and accessibility for a wider range of clients. Legacy providers like Oracle Corporation are adapting by integrating cloud-native risk tools into their enterprise suites. IBM leverages its extensive AI and cognitive computing capabilities to offer advanced predictive analytics. Meanwhile, specialists like SAS Institute sustain their market position through deep expertise in statistical modeling for complex risk scenarios.
Risk analytics involves the application of quantitative techniques, including statistical modeling and machine learning algorithms, to evaluate and manage uncertainty in business decisions. These systems utilize predictive models and stochastic simulations to forecast potential outcomes and their associated probabilities. The primary purpose is to provide decision-makers with a data-driven basis for mitigating financial, operational, and strategic risks. While Credit Risk Analytics remains a mature and foundational solution type, Cyber Risk Analytics is experiencing rapid adoption. BFSI institutions constitute the largest end-user segment, with growing use cases in telecommunications.
Regulatory mandates are a significant catalyst for market development. Frameworks like the Basel III accords for banking, the Sarbanes-Oxley Act (SOX) in the United States, and the EU's GDPR impose strict requirements for risk management, data security, and compliance reporting. These regulations compel organizations to invest in robust analytics platforms to ensure transparency and avoid penalties. The key decision for adopters now involves balancing the power of advanced AI-driven models with the growing regulatory demand for model explainability and algorithmic fairness.
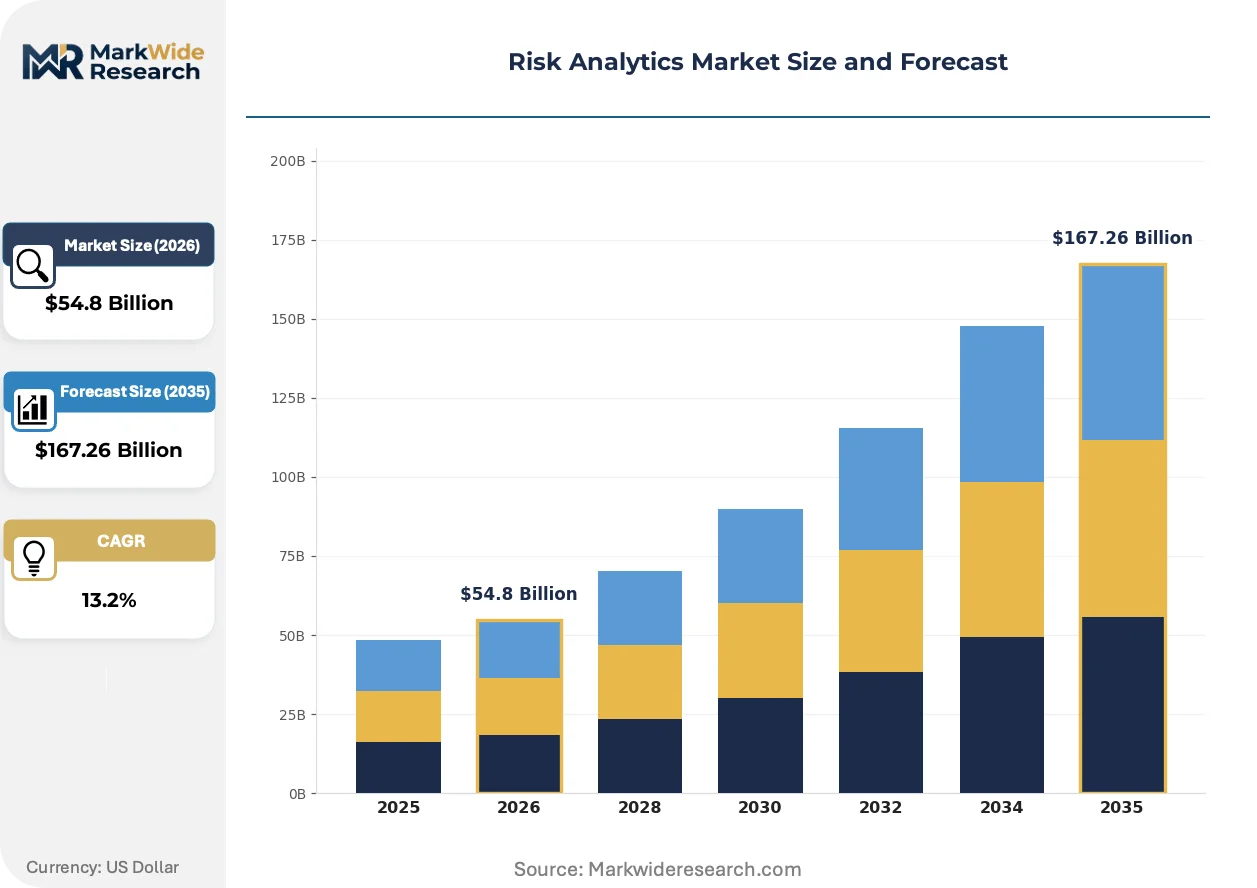
Market Dynamics
The central tension in the risk analytics market is the conflict between the increasing complexity of AI-driven predictive models and the growing regulatory demand for model explainability and algorithmic fairness, particularly within the BFSI sector.
Growth Catalysts
- Regulatory Mandates:Frameworks such as the EU's GDPR and the Basel III accords compel organizations, especially in banking and finance, to invest in sophisticated risk analytics for compliance, data governance, and transparent reporting.
- Advanced Fraud Detection:The proliferation of digital transactions across the BFSI and telecommunications sectors creates a strong need for AI and machine learning-based analytics to identify and mitigate complex, real-time fraudulent activities.
- Cyber Risk Proliferation:Escalating frequency and sophistication of cyberattacks are pushing enterprises in all sectors to adopt specialized cyber risk analytics solutions to quantify potential financial and operational impacts and prioritize security investments.
Market Restraints
- Model Explainability Challenges:The "black box" nature of advanced machine learning algorithms creates a significant restraint, as regulated industries like banking require transparent, interpretable models to satisfy auditors and bodies like the US Federal Reserve.
- High Implementation Costs:The substantial initial investment required for software licensing, system integration with legacy IT infrastructure, and the high cost of hiring specialized data science talent can deter adoption among smaller enterprises.
- Data Quality and Integration Issues:The effectiveness of risk analytics tools depends on high-quality, integrated data, but many organizations struggle with data silos, inconsistent formats, and poor data governance, limiting analytical accuracy and ROI.
Strategic Opportunities
- Supply Chain Risk Analytics:Geopolitical and climate-related disruptions create a significant opportunity for solutions that model and predict supply chain vulnerabilities, an area of underpenetration outside of large manufacturing enterprises.
- Expansion in Emerging Economies:The expanding financial services and telecommunications sectors in Southeast Asian and Latin American countries present a substantial growth opportunity for scalable, cloud-based risk analytics solutions.
- Insurance Technology (Insurtech) Integration:There is a growing opportunity to embed dynamic risk analytics into insurtech platforms for personalized underwriting, real-time risk assessment using IoT data, and automated claims processing.
Industry Challenges
- Specialized Talent Scarcity:A persistent challenge is the shortage of professionals who possess the dual expertise of deep industry-specific risk knowledge and advanced data science and machine learning skills, hindering effective model development and validation.
- Algorithmic Bias and Fairness:Ensuring that predictive models are free from biases related to gender, race, or other protected characteristics is a major operational and ethical challenge, exposing firms to significant reputational and legal risks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Risk Analytics Market |
| Market Size in 2026 | $54.8 Billion |
| Market Size in 2035 | $167.26 Billion |
| CAGR (2026 – 2036) | 13.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Type: Credit Risk Analytics, Market Risk Analytics, Operational Risk Analytics, Enterprise Risk Management, Cyber Risk Analytics Deployment Model: On-Premises, Cloud-Based, Hybrid Cloud, SaaS, Private Cloud End User Industry: BFSI Institutions, Telecommunications, Energy Providers, Manufacturing Firms, Transportation Operators Application Area: Fraud Detection, Regulatory Compliance, Credit Scoring, Portfolio Optimization, Risk Monitoring |
| Companies Covered | IBM, Oracle Corporation, Moody's Analytics, SAS Institute, SAP SE, Accenture, Verisk Analytics, Aon, Marsh McLennan, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Risk Analytics Market Strategic Shifts & Innovations
A new performance frontier is emerging as vendors integrate generative AI for synthetic data creation and scenario modeling. This innovation directly addresses the dual market pressures for more powerful predictive capabilities and greater model validation demanded by regulators.
Generative AI is being applied to create high-fidelity synthetic data, which is used to train and stress-test risk models without compromising real customer privacy. Financial services and insurance firms are the primary adopters, using it to simulate black swan events and test model resilience. This application of advanced AI is collapsing the time and data requirements for building and validating robust predictive risk models.
Regulatory frameworks like the European Union's AI Act are introducing risk-based classifications for artificial intelligence systems. This legislation imposes strict transparency and explainability requirements for high-risk applications, including credit scoring and employee management tools. Consequently, analytics providers are embedding enhanced model risk management (MRM) and algorithmic fairness auditing tools directly into their platforms to ensure client compliance.
Demand is shifting from monolithic, all-in-one risk management platforms toward a more modular, API-first procurement strategy. Large enterprises now prefer to integrate specialized, best-of-breed microservices for specific functions like cyber or credit risk into their existing data architecture. This unbundling of capabilities is most visible within the technology-forward financial institutions of North America and Western Europe.
Risk Analytics Market Segmentation
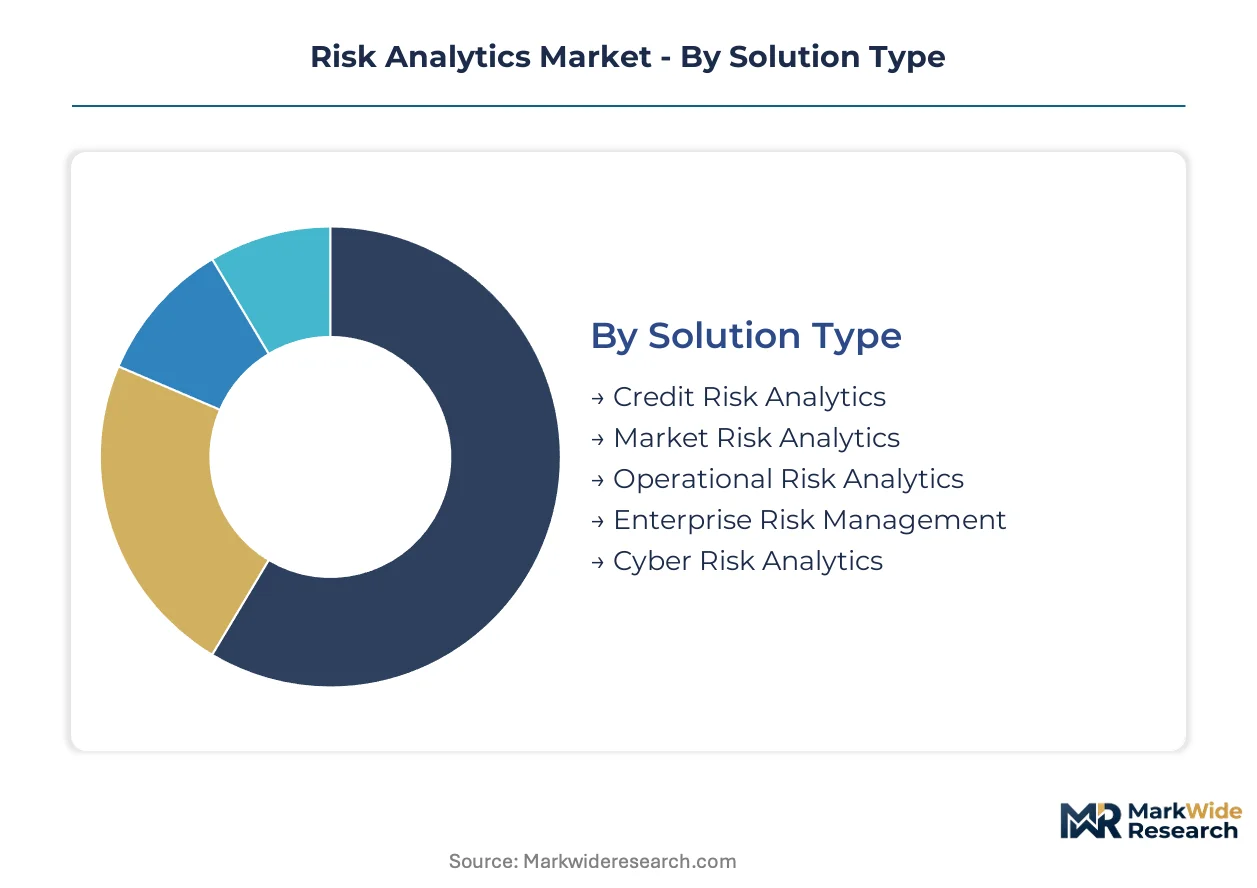
The Risk Analytics market categorizes solutions and deployment models to address diverse industry requirements for managing uncertainty. This segmentation highlights where technological advancements and regulatory pressures are driving demand for specialized analytical capabilities. Understanding these distinctions helps stakeholders identify specific areas for investment and strategic development.
Solution Type:
The solution type spectrum spans from mature, foundational offerings to rapidly emerging, specialized analytics.
- Credit Risk Analytics:This established solution assesses the likelihood of a borrower defaulting on financial obligations, utilizing historical data and predictive models. Demand concentrates within BFSI institutions, driven by stringent capital adequacy requirements like Basel III accords.
- Cyber Risk Analytics:This emerging segment quantifies potential financial and operational impacts from cyberattacks, enabling organizations to prioritize security investments. Telecommunications operators and financial services firms are primary adopters, responding to escalating threat sophistication.
- Market Risk Analytics:These tools evaluate the potential for losses in portfolios due to fluctuations in market prices, interest rates, and foreign exchange rates. Investment banks and asset management firms utilize these systems for real-time portfolio adjustments.
- Operational Risk Analytics:This category identifies, assesses, and mitigates risks arising from internal processes, people, and systems or from external events. Large enterprises across manufacturing and energy sectors deploy these solutions for process optimization.
- Enterprise Risk Management:These integrated platforms provide a holistic view of all risks across an organization, facilitating strategic decision-making and compliance. Multinational corporations leverage ERM to consolidate risk reporting.
Credit Risk Analytics handles the majority of throughput; Cyber Risk Analytics is the fastest mover on share.
Deployment Model:
Deployment model preferences reflect varying organizational needs for scalability, accessibility, and data control.
- Cloud-Based:Solutions hosted on remote servers and accessed over the internet, offering significant scalability and reduced infrastructure overhead. Financial technology firms and mid-sized enterprises often prefer this model for its agility.
- SaaS:Software as a Service models provide risk analytics applications on a subscription basis, managed entirely by the vendor, ensuring easy updates and maintenance. Startups and organizations seeking rapid deployment without extensive IT resources adopt SaaS.
- On-Premises:Software installed and run on an organization's own servers, providing maximum control over data security and customization. Large banking institutions with strict data governance policies frequently opt for on-premises deployments.
- Hybrid Cloud:This model combines elements of both public and private cloud environments, allowing data and applications to be shared between them. Enterprises with sensitive data often use hybrid clouds to balance security with flexibility.
- Private Cloud:A cloud computing environment dedicated exclusively to a single organization, offering enhanced security and control. Government agencies and highly regulated industries choose private cloud for critical risk applications.
Cloud-based solutions dominate new deployments, and SaaS models are expanding most quickly in market penetration.
End User Industry:
End-user industry segmentation highlights the sectors with the most pronounced demand for risk analytics capabilities.
- BFSI Institutions:Banking, Financial Services, and Insurance entities use risk analytics for fraud detection, credit scoring, and regulatory compliance. The US financial services sector represents a significant concentration of demand for these solutions.
- Telecommunications:Telecom companies deploy analytics for fraud prevention, revenue assurance, and customer churn prediction. Growing use cases in Southeast Asian countries are expanding this segment's footprint.
- Energy Providers:These firms utilize risk analytics to manage operational risks, supply chain disruptions, and compliance with environmental regulations. Utility companies in Europe adopt these tools for grid stability analysis.
- Manufacturing Firms:Manufacturers apply risk analytics for supply chain resilience, quality control, and forecasting market demand fluctuations. Large automotive and aerospace manufacturers use these systems globally.
- Transportation Operators:This segment employs analytics for fleet management, route optimization, and assessing geopolitical risks impacting logistics. Airlines and shipping companies leverage these tools for operational efficiency.
BFSI institutions represent the largest revenue contributor, with telecommunications showing significant expansion.
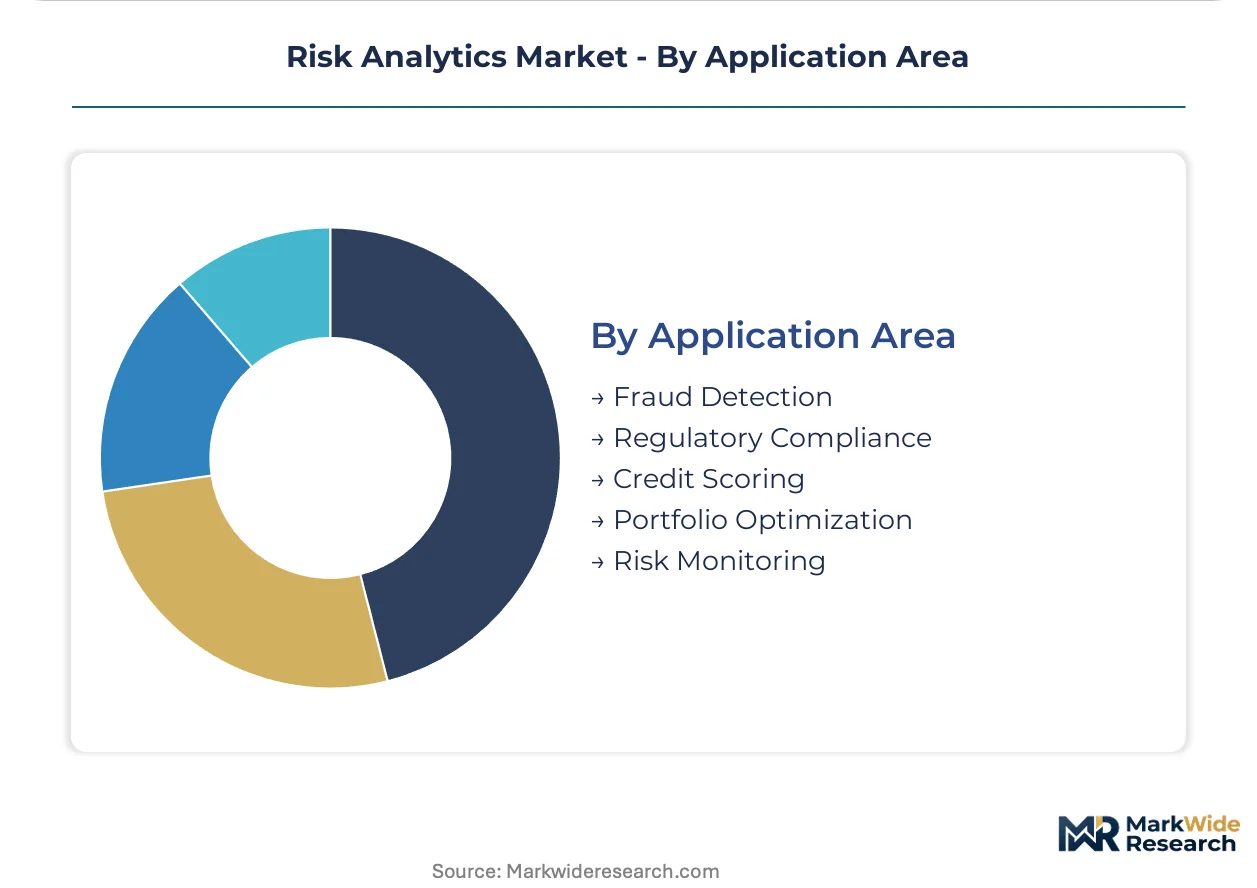
Application Area:
Application areas define the specific business problems that risk analytics solutions are designed to solve.
- Fraud Detection:These applications identify and prevent fraudulent activities in real-time across various transaction channels using AI and machine learning algorithms. Financial institutions in North America prioritize advanced fraud detection systems.
- Regulatory Compliance:Solutions that ensure adherence to industry-specific regulations, such as Basel III, GDPR, and Sarbanes-Oxley Act, by automating reporting and monitoring processes. European banks invest heavily in compliance analytics.
- Credit Scoring:Systems that evaluate the creditworthiness of individuals and businesses, informing lending decisions and managing loan portfolios. Retail banks globally rely on sophisticated credit scoring models.
- Portfolio Optimization:Tools that help manage and balance investment portfolios to maximize returns while minimizing risk exposure. Asset managers and wealth management firms use these for strategic allocation.
- Risk Monitoring:Continuous surveillance of risk metrics and indicators to provide early warnings of potential threats or emerging issues. Enterprise-level organizations deploy these for proactive risk management.
Fraud detection drives immediate value, and regulatory compliance underpins foundational investment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power for risk analytics solutions exhibits asymmetry, with the United States commanding higher value due to advanced financial sector demand, contrasting with more price-sensitive markets like India. This regional divergence influences deployment models and feature sets, as vendors adapt offerings to local economic conditions and regulatory maturity. Emerging economies increasingly prioritize scalable, cloud-based solutions for cost-effectiveness.
United States
Demand for risk analytics in the United States concentrates within its vast financial services sector, driven by complex fraud detection and portfolio optimization needs. Regulatory frameworks such as the Sarbanes-Oxley Act (SOX) and oversight from the US Federal Reserve compel significant investment in robust platforms. Financial hubs like New York City and Chicago actively integrate AI-driven models for real-time risk assessment.
Germany
German enterprises, particularly in banking and manufacturing, require advanced risk analytics for operational resilience and compliance with European regulations. The EU's GDPR and the Basel III accords necessitate stringent data governance and transparent risk reporting. Industrial clusters in Bavaria and North Rhine-Westphalia leverage these tools for supply chain risk management and financial stability.
India
India's expanding financial services and telecommunications sectors drive demand for scalable risk analytics, focusing on fraud prevention and credit scoring. The Reserve Bank of India (RBI) mandates robust risk management practices, particularly for digital lending and payment systems. Technology hubs in Bengaluru and Hyderabad are witnessing increased adoption of cloud-based solutions by fintech startups.
Singapore
Singapore serves as a regional hub for financial technology and innovation, generating strong demand for sophisticated cyber risk analytics and regulatory compliance tools. The Monetary Authority of Singapore (MAS) implements strict guidelines for financial institutions regarding data security and operational resilience. The city-state’s vibrant fintech ecosystem actively pilots AI-driven risk solutions.
Brazil
Brazilian financial institutions and telecommunications operators increasingly adopt risk analytics to manage market volatility and detect fraud. Regulations from the Central Bank of Brazil (BACEN) and data protection laws like LGPD necessitate comprehensive risk assessment capabilities. Sao Paulo's financial district and technology centers in Rio de Janeiro are key areas for market expansion.
Risk Analytics Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream, supplying niche analytical tools and data services. The market structure exhibits a tiered consolidation, where large enterprise software vendors offer comprehensive suites alongside specialized analytics firms. Strategic archetypes include enterprise solution providers, domain-specific experts, and cloud-native innovators. Dominant competitive moves involve strategic partnerships to enhance ecosystem capabilities and continuous portfolio diversification into emerging risk areas.
Within the enterprise solution archetype, IBM and Oracle Corporation provide broad risk management platforms, integrating various analytical capabilities into their extensive software ecosystems. SAS Institute exemplifies a specialist archetype, sustaining its market position through deep expertise in statistical modeling for complex risk scenarios. These companies anchor different segments of the market, catering to varying client needs for integration, customization, and specialized analytical depth.
| Leading Market Players |
|---|
| IBM |
| Oracle Corporation |
| Moody's Analytics |
| SAS Institute |
| SAP SE |
| Accenture |
| Verisk Analytics |
| Aon |
| Marsh McLennan |
| Others |
Cost & Logistics Intelligence
The concentration of specialized data science talent in North America directly influences the premium pricing for advanced risk analytics solutions across global markets.
Pricing Analysis
The customization-premium spread defines pricing in risk analytics, with highly tailored solutions commanding higher rates than standardized offerings. Subscription-based and SaaS-tiered models dominate, reflecting ongoing service and continuous updates. Price differentiation stems from customization levels and the depth of integrated after-sales support for model validation. Pricing softness reflects the increasing availability of cloud-based, scalable solutions, particularly for mid-sized enterprises. Large financial institutions, driven by stringent regulatory needs, exhibit lower price sensitivity for critical compliance platforms.
Supply Chain Analysis
Extended payment terms for large enterprise software licenses are common, reflecting the long-term value proposition and implementation cycles for risk analytics platforms. The supply chain draws heavily from specialized AI/ML expertise concentrated in the United States and India for software development. Cloud computing resources, often hosted in major data center hubs like Ireland or Singapore, form a critical dependency. Specialized talent scarcity represents a significant structural risk. Distribution runs primarily through direct sales to large enterprises and cloud marketplaces for agile solutions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The risk analytics market presents a significant service-attach opportunity, with ongoing model validation and algorithmic fairness auditing services expanding faster than initial software deployments.
For Market Incumbents: Harden existing enterprise platforms by integrating advanced generative AI capabilities for synthetic data generation and robust model validation. Acquire specialized AI explainability firms to counter the threat from cloud-native innovators offering modular solutions. Invest in R&D for explainable AI and MLOps to meet evolving regulatory demands from bodies like the US Federal Reserve. Control over critical data governance frameworks will ensure long-term client retention.
For New Entrants and Emerging Players: Mid-market enterprises in Southeast Asia represent a highly penetrable entry point for specialized cyber risk analytics solutions. Focus on developing API-first, SaaS-based microservices that integrate seamlessly into existing IT architectures. Target the burgeoning Insurtech sector with real-time risk assessment tools leveraging IoT data. A go-to-market angle emphasizing rapid deployment and cost-effectiveness will attract agile fintech startups.
For Investors and Strategic Acquirers: Capital is best deployed toward cloud-native specialists developing explainable AI for regulated industries, offering long-term viability as regulatory scrutiny intensifies. Seek firms with proven expertise in synthetic data generation and algorithmic fairness auditing. The acquisition target archetype should be agile, technology-forward companies with strong intellectual property in niche risk areas. A signal to watch is the regulatory clarity and enforcement trends emerging from the EU AI Act.
| Strategic Initiative | Industry Significance |
|---|---|
| Product Launch: AI-powered Model Explainability Module | Enhances transparency for complex predictive models, addressing critical regulatory demands from the Basel III accords. |
| Platform Integration: API-first Integration with Core Banking Systems | Facilitates seamless data flow and reduces implementation friction for financial institutions like those in New York City. |
| Strategic Partnership: Collaboration with Specialized Data Providers | Expands access to high-fidelity, real-time data for more accurate risk assessments across diverse industries. |
| Acquisition of Specialist Firm: Purchase of a Cyber Risk Analytics Startup | Bolsters capabilities in a rapidly growing segment, particularly for telecommunications operators and financial services firms. |
| Geographic Expansion: Entry into Southeast Asian Fintech Markets | Captures demand from expanding financial services and telecommunications sectors in countries like Singapore and India. |
Research Approach
Two parallel data streams informed the analysis: extensive primary interviews with industry stakeholders and rigorous secondary validation from published sources. Primary research engaged chief risk officers, chief data scientists, compliance heads, and IT procurement managers across various sectors. Secondary data sources included SEC filings of public technology firms, central bank reports from the Reserve Bank of India and the US Federal Reserve, and industry association whitepapers. This approach utilized both bottom-up market sizing and top-down validation.
Forecast inputs considered historical market performance, technological adoption curves, and evolving regulatory landscapes across the analysis window. The analytical framework integrated cross-sectional and time-series analysis to project market trajectories. Segmentation dimensions modeled included solution type, deployment model, end-user industry, application area, and regional regulatory maturity. Compound Annual Growth Rates were derived from historical growth trends and projected market dynamics, incorporating regulatory mandate timelines and AI adoption rates within BFSI.
Macroeconomic conditions sit as an overlay; deviation in global interest rates or geopolitical stability would shift the trajectory of investment in risk analytics platforms. Forecasts reflect assumptions regarding technological advancements and consistent regulatory enforcement. Regulatory changes, especially concerning AI governance, or new cyber threats could also prompt forecast revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Risk Management and Compliance
Asia-Pacific Compliance and Traceability Solutions Market
Risk Management and Compliance
Risk-Based Monitoring Software Market
Risk Management and Compliance
Global Management Decision Market
Risk Management and Compliance
Europe Strategy Consulting Market
Risk Management and Compliance
Regtech Market
Risk Management and Compliance
Global Credit Risk Rating Software Market
Risk Management and Compliance
Financial Services Security Software Market
Risk Management and Compliance
Risk Assessment Software Market
Risk Management and Compliance
Global Regulatory Reporting and Compliance Market
Risk Management and Compliance
Fraud Detection and Prevention (FDP) Market
Risk Management and Compliance
Employee Benefits Strategy and Consulting Market
Risk Management and Compliance
Medical Device Cyber Risk Quantification Market
Risk Management and Compliance
Third Party Risk Management Market
Risk Management and Compliance
Risk Management Market
Risk Management and Compliance
Enterprise Governance, Risk, and Compliance (Egrc) Market
Risk Management and Compliance
North America BFSI Biometrics Market