
 Global Credit Risk Rating Software Market | 2026-2036
Global Credit Risk Rating Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Credit Risk Rating Software Market Foresight
ISO 27001 certification is reorganizing competitive entry in credit risk rating software, as data security standards gate procurement decisions at tier-one financial institutions. Moody's Analytics leverages its heritage in credit research to sustain platform credibility among institutional underwriters. FICO anchors its position through proprietary scoring algorithms that dominate consumer lending decisions. Experian competes by extending real-time data ingestion capabilities across alternative credit sources.
Credit risk rating software comprises algorithmic platforms that aggregate borrower financials, behavioral data, and macroeconomic indicators to generate probability-of-default estimates and loss-given-default calculations. These systems employ machine learning pipelines, stress-testing engines, and API-first architectures to automate underwriting workflows and regulatory capital reporting for lenders and asset managers. Cloud-based deployment leads solution uptake as banks retire legacy mainframe installations, while fraud detection modules capture expanding margin pools from real-time transaction monitoring mandates. Portfolio management analytics represents the fastest-growing solution type as institutional investors demand granular concentration risk visibility across sovereign, corporate, and structured credit exposures.
The European Banking Authority's ECB guidance on internal ratings-based approaches shapes product development timelines for vendors serving EU lenders, while the US Federal Reserve's CCAR stress-testing regime dictates model governance requirements that filter software procurement specifications. India's RBI mandates on expected credit loss provisioning are accelerating localized platform customization for emerging-market loan books. Stakeholders must monitor how generative AI model interpretability standards from the EU AI Act reshape algorithmic transparency requirements in automated credit decisions.
Market Dynamics
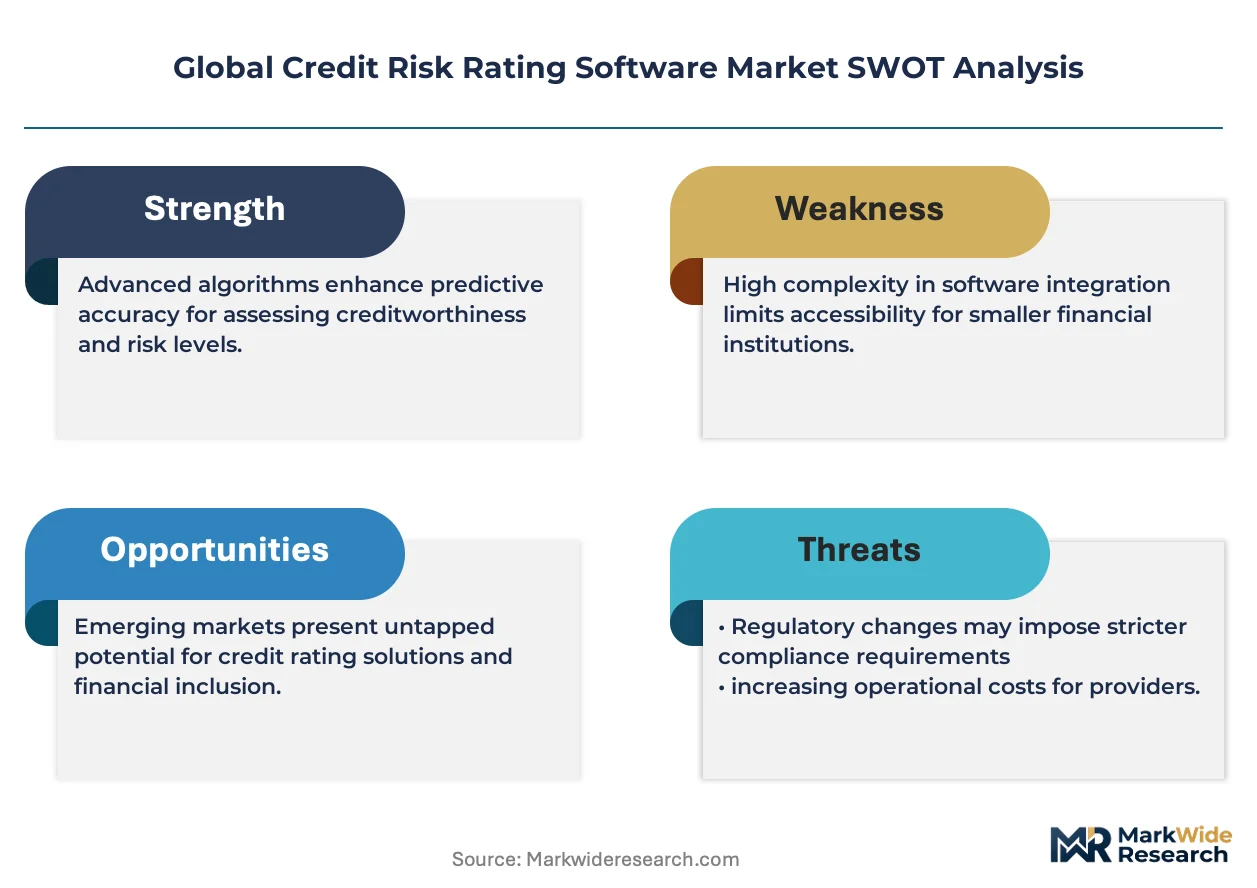
Machine learning pipelines are supplanting legacy statistical scoring models as tier-one banks face Basel III capital adequacy recalibration deadlines and pressure to automate expected credit loss calculations across sovereign, corporate, and structured portfolios.
Growth Catalysts
- Basel III Finalization:The Basel Committee's revised standardized approach to credit risk is compelling US and EU banks to upgrade internal ratings-based systems for regulatory capital optimization.
- Real-time data infrastructure:API-first architectures enable continuous borrower monitoring, allowing lenders to recalculate probability-of-default estimates as macroeconomic conditions shift.
- Singapore's financial hub expansion:The Monetary Authority of Singapore's fintech licensing framework is attracting credit analytics vendors to establish Asia-Pacific development centers.
Market Restraints
- Cloud concentration risk:Three hyperscalers dominate financial services cloud infrastructure, creating systemic dependency for mission-critical risk calculation engines.
- Model interpretability mandates:The EU AI Act's requirements for algorithmic transparency in automated credit decisions impose architectural constraints on deep learning implementations.
- Specialized talent scarcity:Quantitative risk modelers with dual expertise in regulatory frameworks and machine learning engineering command compensation premiums that compress vendor margins.
Strategic Opportunities
- India's ECL provisioning wave:The Reserve Bank of India's phased implementation of expected credit loss accounting standards creates localized platform customization demand for emerging-market loan books.
- Alternative data convergence:Satellite imagery and supply chain transaction feeds are integrating with traditional financial statements to score thin-file borrowers in agricultural and SME segments.
- Subscription pricing penetration:Tier-two regional banks are migrating from perpetual license models to SaaS consumption, expanding addressable market depth beyond top-tier institutions.
Industry Challenges
- Legacy system integration complexity:Mainframe-hosted core banking systems require costly middleware development to feed real-time data into modern risk calculation engines.
- ISO 27001 certification timelines:Six-to-twelve month security audit cycles delay vendor onboarding at institutional procurement gates, extending sales cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Credit Risk Rating Software Market |
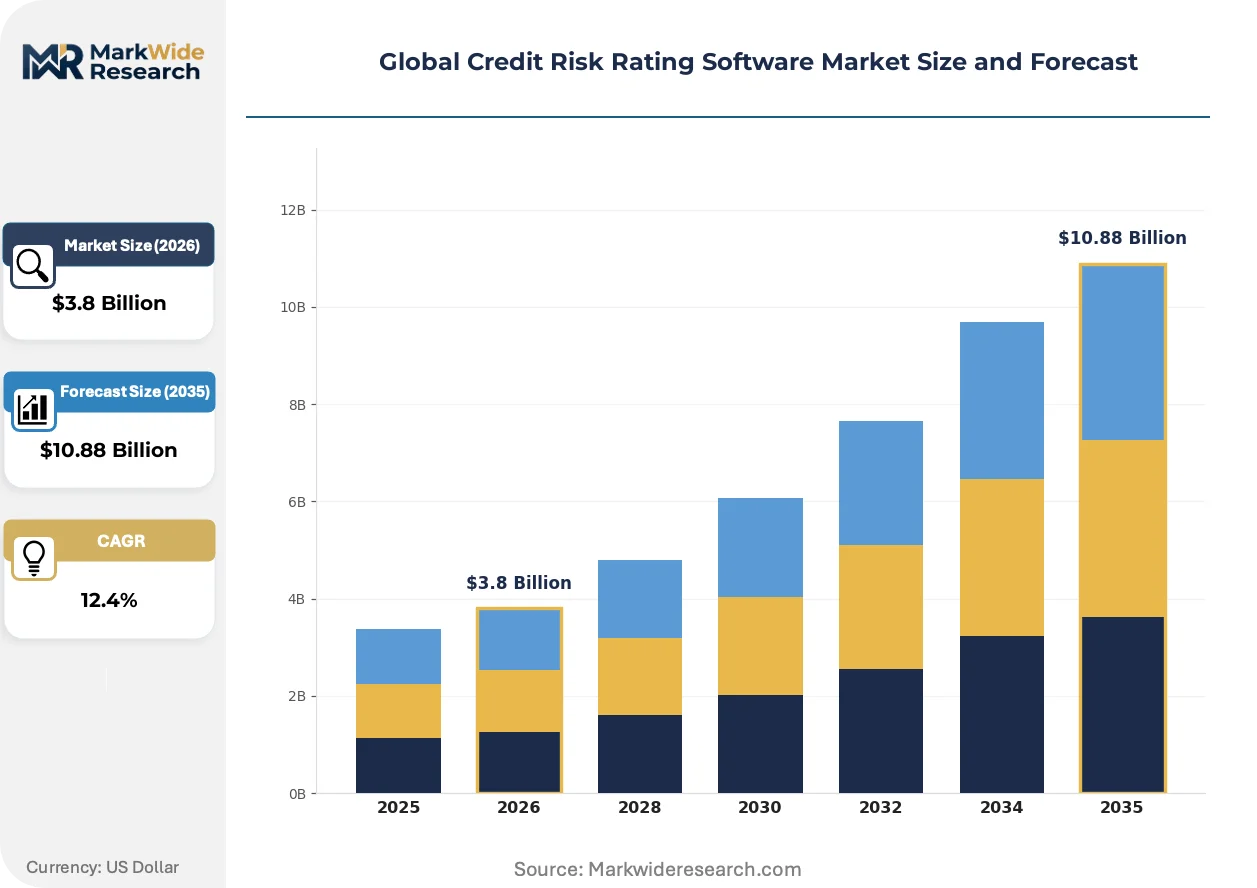
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.88 Billion |
| CAGR (2026 – 2036) | 12.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premises, Hybrid, Hosted, SaaS, Managed Solution Type: Credit Scoring, Risk Assessment, Portfolio Management, Fraud Detection, Compliance Monitoring, Analytics End User: Banking Institutions, Investment Firms, Credit Unions, Insurance Providers, Microfinance Entities, Payment Processors Customer Size: Small Enterprises, Medium Enterprises, Large Enterprises, Startups, Government Agencies, Nonprofit Organizations |
| Companies Covered | Moody's Analytics, Equifax, Experian, FICO, SAS Institute, Oracle, FIS, Salesforce, S&P Global, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Credit Risk Rating Software Market Shifts & Advancements
Explainable AI frameworks are restructuring algorithmic transparency requirements, while open banking data standards and climate risk stress-testing mandates are creating new functional modules that vendors must integrate into platform roadmaps.
Neural network architectures for credit scoring are supplanting logistic regression and linear discriminant analysis in consumer and SME lending segments. Tier-one US banks and German Landesbanks are deploying these models for probability-of-default estimation, compressing model development cycles from quarters to weeks while demanding new governance tooling for regulatory submission.
The EU AI Act's risk-based classification system categorizes automated credit decisions as high-risk applications, mandating human oversight interfaces and bias audit trails. Vendors serving EU lenders are reengineering model documentation pipelines to satisfy conformity assessment requirements, with product teams prioritizing interpretability dashboards over raw predictive accuracy improvements.
Chief risk officers are consolidating vendor relationships around platforms offering integrated portfolio management, stress-testing, and regulatory reporting capabilities. Point solutions for isolated credit scoring functions are losing procurement contests to full-stack providers, a pattern most visible in US regional bank RFP processes where evaluation committees penalize fragmented system architectures.
Global Credit Risk Rating Software Market Segmentation
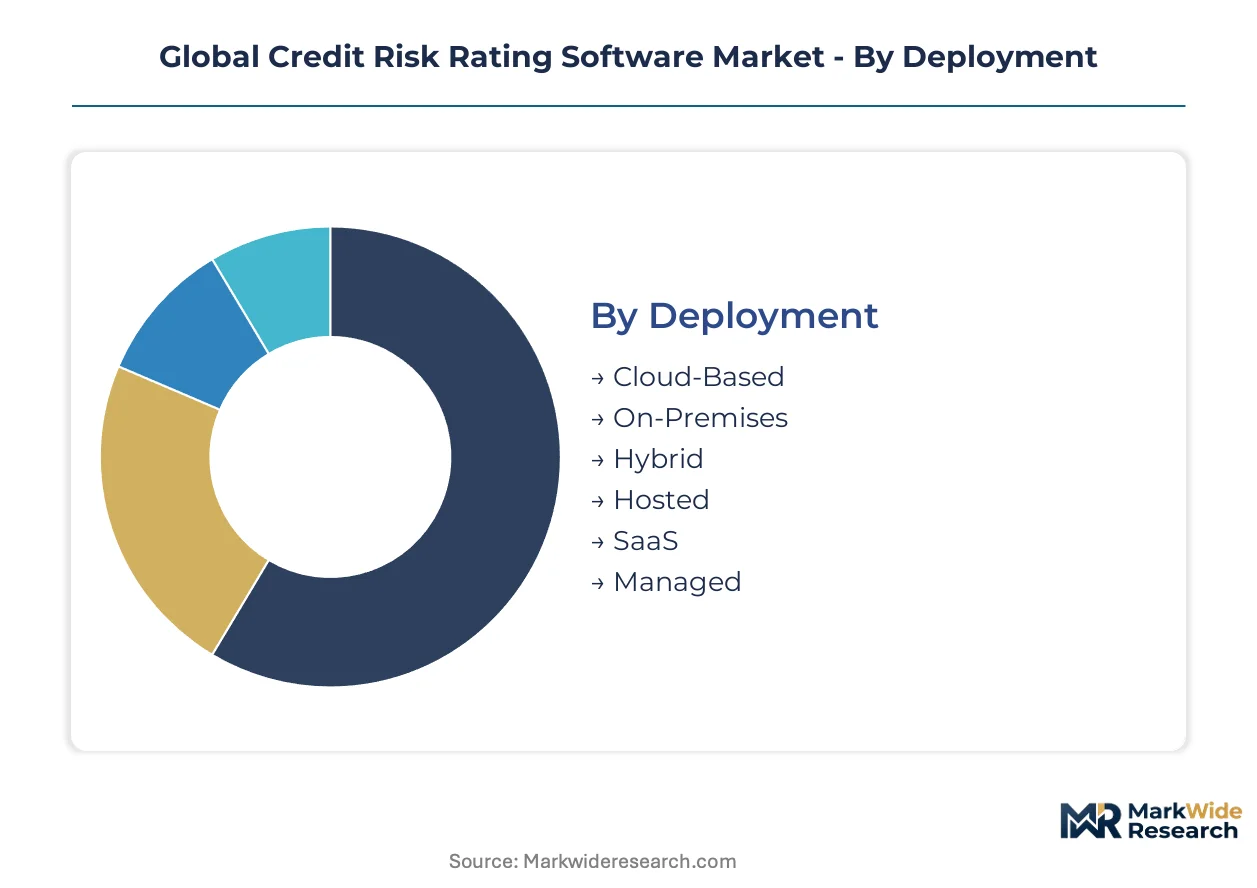
Credit risk rating software vendors architect product portfolios around deployment flexibility, solution depth, and institutional scale. Segmentation choices directly determine pricing architecture, sales cycle length, and regulatory compliance burden across buyer categories.
Deployment:
Cloud-native architectures dominate procurement in financial hubs with mature data sovereignty frameworks, while on-premises retention concentrates in jurisdictions with strict localization mandates.
- Cloud-Based:Multi-tenant SaaS platforms with elastic compute for stress-testing workloads. Demand clusters in Singapore and Germany where MAS and BaFin guidelines permit cross-border data flows for risk analytics.
- On-Premises:Air-gapped installations on bank-owned infrastructure serving sovereign wealth funds and defense-sector lenders in India and the United States with classified portfolio requirements.
- Hybrid:Split architectures keeping sensitive borrower data on-premises while pushing model training to cloud GPU clusters. Indian private banks favor this pattern for RBI-mandated data localization compliance.
- Hosted:Single-tenant private cloud deployments managed by vendor operations teams. Credit unions in the United States select this model to avoid internal IT expansion.
- SaaS:Subscription consumption with API-first integration into core banking systems. Microfinance entities across Southeast Asia adopt this for minimal upfront capital commitment.
- Managed:Fully outsourced risk calculation operations including model validation and regulatory submission. Emerging-market banks in India leverage this to bridge quantitative talent gaps.
On-Premises commands the established base. The steepest expansion runs through Cloud-Based deployment as tier-one banks retire mainframe installations.
Solution Type:
Functional modules align with organizational maturity — point solutions for specialized lenders, integrated suites for universal banks managing diversified credit books.
- Credit Scoring:Algorithmic engines generating probability-of-default estimates from borrower financials and behavioral data. United States consumer lenders drive refinement of alternative data ingestion pipelines.
- Risk Assessment:Comprehensive underwriting workflows combining quantitative models with qualitative analyst overrides. German Landesbanks prioritize this segment for internal ratings-based capital calculations under ECB guidance.
- Portfolio Management:Concentration risk analytics across sovereign, corporate, and structured exposures. Institutional investors in Singapore demand granular visibility into correlation risk across ASEAN loan books.
- Fraud Detection:Real-time transaction monitoring with anomaly detection for synthetic identity and first-party fraud. Payment processors in the United States integrate this module to satisfy Fed-mandated surveillance requirements.
- Compliance Monitoring:Automated regulatory capital reporting and model governance documentation. EU lenders invest here to streamline ECB and EBA submission workflows.
- Analytics:Exploratory data platforms for stress-testing scenario design and macroeconomic sensitivity analysis. Insurance providers in Germany use these tools for climate risk integration into credit portfolios.
Credit Scoring anchors vendor revenue. Portfolio Management gains share fastest as asset managers deepen fixed-income analytics capabilities.
End User:
Institutional type shapes procurement authority — regulated banks require ISO 27001 certification, while fintech lenders prioritize API velocity over legacy compliance depth.
- Banking Institutions:Universal banks, commercial lenders, and development finance institutions with Basel III capital adequacy obligations. United States money-center banks represent the most demanding buyer segment for model explainability features.
- Investment Firms:Asset managers and private credit funds requiring portfolio-level risk aggregation across illiquid holdings. Singapore-based alternatives funds drive demand for bespoke structured credit analytics.
- Credit Unions:Member-owned cooperatives with constrained IT budgets and regulatory examination schedules. United States state-chartered credit unions favor SaaS deployment to preserve capital for member dividends.
- Insurance Providers:Life and property-casualty carriers integrating credit risk into investment portfolio and counterparty exposure management. German insurers lead climate risk stress-testing adoption.
- Microfinance Entities:Small-ticket lenders serving thin-file borrowers with alternative data scoring needs. Indian MFIs customize platforms for RBI-mandated expected credit loss provisioning.
- Payment Processors:Real-time settlement networks requiring embedded risk scoring for merchant underwriting and transaction monitoring. United States fintech infrastructure providers embed these capabilities into onboarding flows.
Banking Institutions dominate current deployment. Payment Processors expand most quickly as real-time settlement networks proliferate.
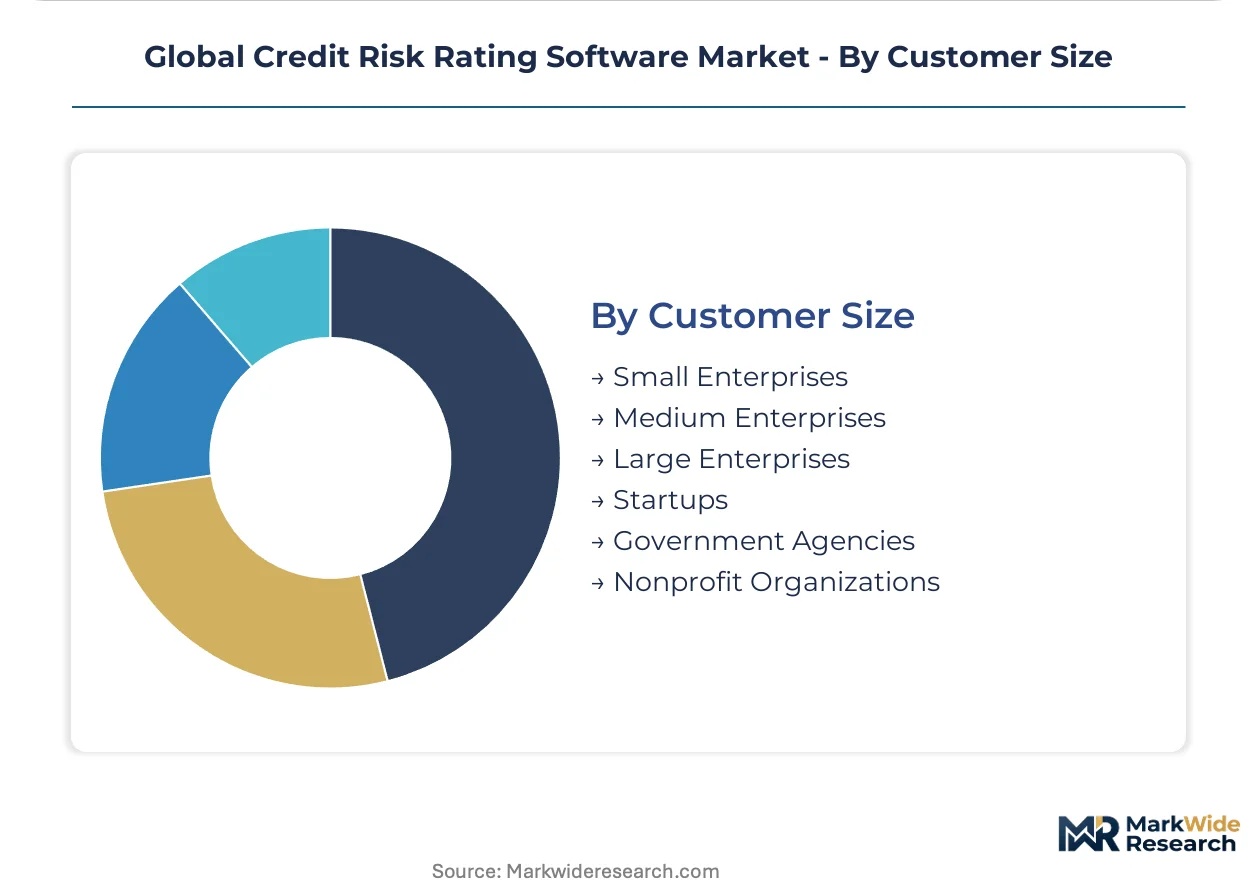
Customer Size:
Organizational scale determines implementation complexity — enterprise deployments require change management at thousands of underwriting desks, while startup adoption demands zero-configuration onboarding.
- Small Enterprises:Regional lenders with sub-$1 billion loan books seeking standardized risk models without internal quant teams. United States community banks in the Southeast concentrate demand here.
- Medium Enterprises:Mid-cap banks and specialty finance companies building competitive differentiation through custom scorecards. Indian NBFCs in the SME lending segment drive localized platform development.
- Large Enterprises:Global systemically important banks with multi-jurisdictional regulatory submission requirements. German and United States institutions set the standard for model governance tooling.
- Startups:Neobanks and fintech lenders launching with cloud-native risk infrastructure from inception. Singapore's MAS licensing framework attracts venture-backed credit platforms.
- Government Agencies:Development banks and export credit agencies with sovereign-guaranteed portfolio mandates. India's SIDBI customizes platforms for priority sector lending tracking.
- Nonprofit Organizations:Mission-driven lenders incorporating social impact metrics alongside financial risk indicators. United States CDFIs pilot alternative data models for financial inclusion objectives.
Large Enterprises retain the deepest vendor relationships. Startups represent the fastest-climbing customer category as digital lending licenses multiply across financial hubs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU AI Act's algorithmic transparency mandates are reshaping procurement specifications across financial hubs, while Basel III finalization deadlines in the United States and Germany accelerate internal ratings-based system upgrades.
United States
The Federal Reserve's CCAR stress-testing regime dictates model governance requirements that filter software procurement at money-center banks. New York and Chicago host the densest vendor-client relationships, with regional banks in the Southeast migrating to SaaS consumption models.
Germany
BaFin guidelines permit cross-border data flows for risk analytics, enabling cloud-native deployment among Landesbanks. Frankfurt anchors development activity for internal ratings-based capital calculation platforms serving ECB-regulated institutions.
Singapore
The Monetary Authority of Singapore's fintech licensing framework attracts credit analytics vendors establishing Asia-Pacific development centers. The city-state's financial hub expansion concentrates demand for portfolio management analytics across ASEAN loan books.
India
The Reserve Bank of India's phased expected credit loss provisioning mandates accelerate localized platform customization for emerging-market loan books. Mumbai and Bangalore private banks favor hybrid architectures for RBI-mandated data localization compliance.
United Kingdom
The Prudential Regulation Authority's model risk management guidelines shape vendor selection criteria for UK-headquartered universal banks. London's alternatives funds drive demand for bespoke structured credit analytics and concentration risk visibility tools.
Global Credit Risk Rating Software Market Competitive Landscape
Listed leaders compete with private specialists across platform credibility and deployment flexibility. The vendor base clusters around three tiers: heritage credit research firms with institutional underwriting relationships, proprietary scoring algorithm providers dominating consumer lending decisions, and cloud-native challengers emphasizing API velocity. Strategic moves concentrate on M&A for alternative data ingestion capabilities and geographic expansion into MAS-licensed Singapore development centers.
Within the heritage research tier, Moody's Analytics and S&P Global exemplify platform credibility anchored in decades of institutional credit research relationships. FICO occupies a position as the proprietary scoring archetype, its algorithms embedded across consumer lending infrastructure. Experian represents the real-time data convergence play, extending ingestion capabilities across alternative credit sources. These three anchors illustrate how competitive positioning stratifies between research heritage, algorithmic lock-in, and data network effects.
| Leading Market Players |
|---|
| Moody's Analytics |
| Equifax |
| Experian |
| FICO |
| SAS Institute |
| Oracle |
| FIS |
| Salesforce |
| S&P Global |
| Others |
Supply & Pricing Matrix
ISO 27001 certification gates procurement at tier-one financial institutions while simultaneously stratifying vendor pricing power, as six-to-twelve month audit cycles compress margins for aspirants and sustain premiums for accredited incumbents serving Basel III-regulated banks.
Pricing Analysis
Certification level creates the primary spread between premium and standard tiers, with ISO 27001-accredited vendors commanding subscription premiums from US money-center banks while non-certified challengers compete on per-seat SaaS pricing for regional credit unions. Three-tier pricing structure across enterprise, mid-market, and startup levels reflects deployment complexity and regulatory submission support bundling. Pricing pressure stems from hyperscaler cloud infrastructure commoditization, which forces independent software vendors to absorb compute cost inflation. Regional banks in the United States Southeast exhibit highest price sensitivity, whereas German Landesbanks prioritize model governance depth over license cost.
Supply Chain Analysis
Quantitative risk modeling talent concentration in the United States, United Kingdom, and Singapore underwrites vendor development velocity and support quality differentiation. Cloud compute capacity draws from Amazon Web Services, Microsoft Azure, and Google Cloud Platform hyperscaler networks, while API middleware and alternative data feeds rest on specialized fintech infrastructure providers. Single-source vulnerability concentrates in machine learning framework dependencies, where TensorFlow and PyTorch ecosystems dominate model development pipelines. Distribution runs through direct enterprise sales teams for large banking institutions and channel partnerships for mid-market credit unions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is consolidating around full-stack platform providers as chief risk officers at US regional banks penalize fragmented point-solution architectures in procurement evaluations.
For Market Incumbents: Shield platform credibility by accelerating ISO 27701 privacy certification alongside ISO 27001 security credentials to preempt EU AI Act procurement gates. Deepen vertical integration into alternative data ingestion pipelines, particularly satellite imagery and supply chain transaction feeds, to defend against cloud-native challengers emphasizing API velocity. Prioritize human-in-the-loop interpretability dashboards over raw predictive accuracy to align with ECB and BaFin model documentation requirements. For New Entrants and Emerging Players: ISO 27001 fast-track programs through Singapore MAS fintech licensing frameworks enable accelerated tier-one bank procurement eligibility. White-space opportunity concentrates in Indian private bank hybrid deployment architectures, where RBI-mandated data localization compliance creates customization demand underserved by global incumbents. Target microfinance entities across Southeast Asia with zero-configuration SaaS onboarding to bypass legacy system integration complexity that slows enterprise sales cycles. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed credit scoring specialists possessing ECB-regulated client relationships but lacking cloud-native platform architecture. Long-term viability favors vendors with integrated portfolio management, stress-testing, and regulatory reporting capabilities as chief risk officers consolidate vendor relationships. Signal to watch is MAS licensing framework expansion into digital wholesale banking, which would validate Singapore as Asia-Pacific development center gravity.| Strategic Initiative | Industry Significance |
|---|---|
| Alternative Data Partnership | Satellite imagery integration enables agricultural SME scoring in thin-file emerging markets. |
| Regulatory Certification Acceleration | EU AI Act conformity assessment investment secures procurement eligibility at ECB-regulated Landesbanks. |
| Hybrid Deployment Architecture | Split on-premises data localization with cloud model training satisfies RBI mandates for Indian private banks. |
| API-First Platform Integration | Real-time probability-of-default recalculation capabilities attract US payment processor embedded finance demand. |
| Geographic Development Center Expansion | Singapore MAS licensing hub establishment captures ASEAN portfolio management analytics growth. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of regulatory filings, vendor technical documentation, and financial institution procurement records. Chief risk officers, quantitative model validation leads, and fintech platform engineers at banking institutions across the United States, Germany, Singapore, and India provided structured input on procurement criteria and implementation constraints. Secondary validation drew from ECB internal ratings-based approach guidance, US Federal Reserve CCAR documentation, MAS fintech licensing frameworks, and RBI expected credit loss circulars. Bottom-up deployment estimates triangulated against top-down market sizing from banking IT spend disclosures.
Segmentation dimensions modeled encompass deployment architecture, solution type functional module, end-user institutional category, and customer size tier across the analysis window. CAGRs derived from regression analysis of historical adoption curves against regulatory deadline schedules and cloud infrastructure cost trajectories. Forecast inputs incorporated Basel III finalization implementation timelines, EU AI Act enforcement phase transitions, and alternative data source availability expansion.
Underlying assumptions cover regulatory deadline adherence, cloud infrastructure cost stability, and quantitative talent supply elasticity, with deviation risk concentrated in generative AI interpretability standard evolution and hyperscaler concentration policy intervention. Practitioners should keep alternative scenarios live as ECB guidance on machine learning model governance and US Federal Reserve climate risk stress-testing mandates evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Risk Management and Compliance
Travel Risk Management Services Market
Risk Management and Compliance
Artificial Intelligence and Regtech Market
Risk Management and Compliance
Operational Risk Management Consulting Services in Manufacturing Market
Risk Management and Compliance
Surety Market
Risk Management and Compliance
Europe Strategic Consulting Services Market
Risk Management and Compliance
United States Governance, Risk and Compliance Platform Market
Risk Management and Compliance
Europe Governance, Risk and Compliance Platform Market
Risk Management and Compliance
Asset Liability Management (ALM) Solution Market
Risk Management and Compliance
Legal Advisory Service Market
Risk Management and Compliance
Medical Device Cyber Risk Quantification Market
Risk Management and Compliance
China Enterprise Risk Management Market
Risk Management and Compliance
Stress Testing Solutions Market
Risk Management and Compliance
United States Strategic Consulting Services Market
Risk Management and Compliance
Risk-Based Monitoring Software Market
Risk Management and Compliance
Global Backstop Netting Systems Market
Risk Management and Compliance
Treasury and Risk Management Application Market