

Employee Benefits Strategy and Consulting Market Size, Share, and Industry Trends Forecast 2026-2036
Employee Benefits Strategy and Consulting Market Insights
Multi-sourced advisory engagement is rebalancing how employers structure their benefits procurement, with organizations blending boutique specialists alongside large brokerage houses. Mercer leverages its actuarial depth to anchor complex self-funded health plan designs for Fortune 500 clients. Aon competes through proprietary benchmarking databases that sustain pricing advantages in competitive renewal cycles. Gallagher differentiates via integrated property-casualty and benefits platforms that control cross-selling pathways into mid-market accounts.
Employee benefits strategy and consulting encompasses the systematic design, financing, and administration of employer-sponsored health, retirement, and welfare programs, typically requiring actuarial certification, ERISA fiduciary compliance, and plan document drafting under federal and state insurance codes. Its primary commercial purpose centers on optimizing the total rewards cost structure while maintaining regulatory adherence and workforce retention outcomes. Health benefits design and compliance advisory represent the most mature service lines with established margin pools, while software-enabled advisory and hybrid delivery models capture the fastest expansion as employers demand real-time plan analytics alongside traditional broker relationships. Large corporations and mid-sized firms constitute the dominant client tiers, though small enterprises represent an underpenetrated segment where automated enrollment platforms and standardized plan templates reduce traditional consulting unit economics.
The US Department of Labor enforces ERISA fiduciary standards that shape how consultants structure fee disclosures and avoid prohibited transactions, while the IRS and Treasury Department regulate qualified plan tax treatment through annual contribution limits and nondiscrimination testing requirements. State insurance commissioners in California, New York, and Texas impose additional network adequacy and premium review standards that consultants must navigate during plan selection processes. Stakeholders should monitor how emerging state-level public option frameworks and federal mental health parity enforcement actions will reshape the technical competencies required for advisory licensure and client retention.
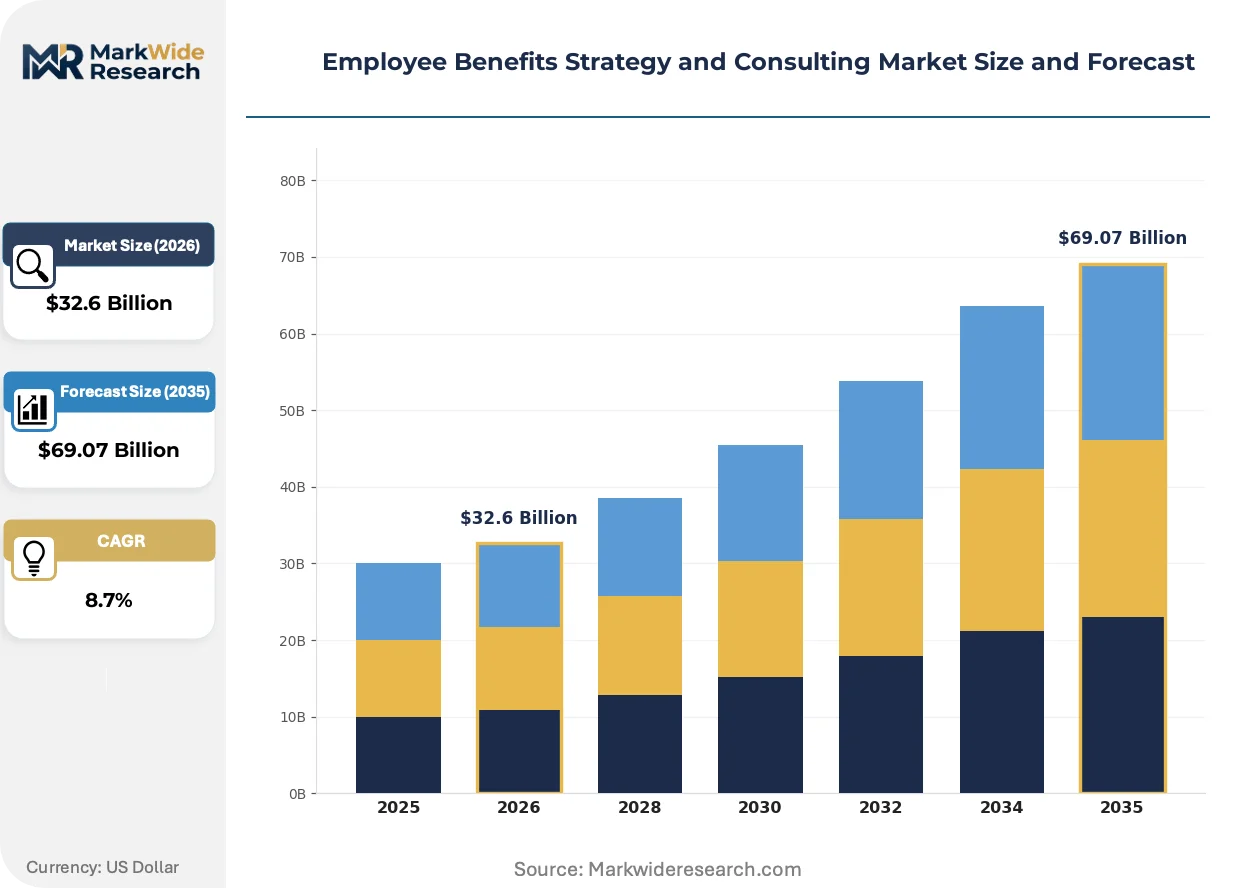
Market Dynamics
Hybrid consulting delivery models are compressing traditional advisory economics as employers demand real-time analytics alongside broker relationships, forcing incumbents to rebuild cost structures around software-enabled service tiers.
Growth Catalysts
- ACA Reporting Mandates:Mid-sized firms across the United States face expanding federal documentation requirements that drive outsourced advisory engagement. Compliance complexity sustains retainer relationships beyond annual renewal cycles.
- State-Level Insurance Mandates:California, New York, and Texas impose network adequacy standards that require specialized navigation during plan selection. Multi-state employers multiply advisory touchpoints.
- Self-Funded Health Plan Migration:Large employers shift from fully insured arrangements toward captive funding structures. Actuarial certification demand concentrates among boutique specialists.
Market Restraints
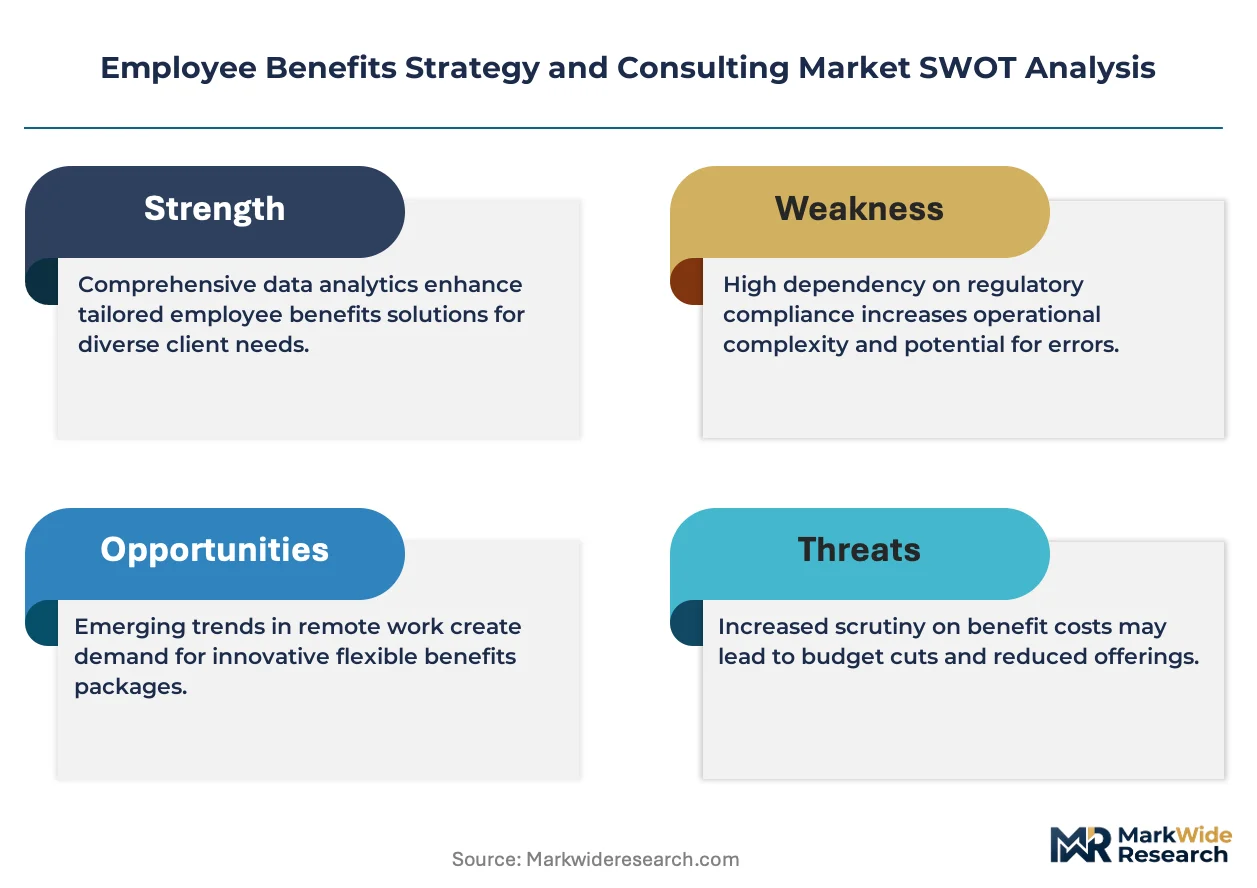
- Fee Compression from Automated Platforms:Standardized enrollment software and plan templates reduce traditional consulting unit economics in the small enterprise segment. Pricing power erodes where automation replicates core advisory functions.
- Regulatory Fragmentation:The US Department of Labor enforces ERISA fiduciary standards while state insurance commissioners impose divergent network adequacy rules. Multi-jurisdictional compliance multiplies licensure overhead.
- Talent Scarcity in Actuarial Certification:Qualified actuaries command premium compensation that constrains margin expansion. Supply bottlenecks limit boutique firm scale.
Strategic Opportunities
- Small Enterprise Automation:Underpenetrated businesses below 100 employees lack dedicated benefits staff. Automated enrollment platforms with embedded compliance checks capture this white space.
- Mental Health Parity Enforcement:Federal parity actions create new technical competency requirements. Advisory firms that build specialized mental health plan design capabilities differentiate retention.
- Property-Casualty Convergence:Integrated platforms that combine employee benefits with commercial risk coverage control cross-selling pathways. Mid-market accounts respond to single-source consolidation.
Industry Challenges
- Legacy System Integration Friction:Real-time analytics platforms must interface with employer HRIS and payroll systems. Data standardization gaps delay implementation timelines.
- ERISA Fiduciary Liability Exposure:Consultants face prohibited transaction scrutiny around fee disclosures and revenue sharing. Litigation risk elevates professional liability insurance costs.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Employee Benefits Strategy and Consulting Market Trends and Innovations
Advisory delivery is bifurcating between high-touch strategic consulting and algorithmic plan optimization, with technology convergence compressing the middle tier of traditional brokerage services.
Artificial intelligence-powered predictive analytics is integrating actuarial modeling with real-time claims data streams. Large employers and sophisticated mid-sized firms adopt these platforms to simulate plan design scenarios before renewal cycles. The technology is integrating underwriting precision into advisory conversations that previously relied on historical benchmarking.
The Mental Health Parity and Addiction Equity Act enforcement actions are reshaping plan documentation requirements. The US Department of Labor and Treasury Department coordinate audits that demand comparative analysis of mental health benefit limitations against medical-surgical coverage. Self-funded plan sponsors face the steepest compliance burden, driving specialized advisory demand.
Employer procurement of benefits advisory is fragmenting across multiple specialist relationships rather than consolidating with single brokers. Large corporations retain strategic consultants for plan design while deploying automated platforms for enrollment administration. This pattern concentrates most visibly in technology and professional services sectors where internal benefits staff possess sufficient sophistication to manage vendor coordination.
Employee Benefits Strategy and Consulting Market Segmentation
Segmentation in employee benefits consulting determines how advisory firms allocate technical resources and price engagement models. Client sophistication, regulatory exposure, and technology integration requirements vary sharply across service lines and delivery formats.
Service Type:
Standalone advisory services operate independently from employer HR systems, while embedded services require real-time data integration with payroll and benefits administration platforms.
- Health Benefits Design:Self-funded plan architecture, network adequacy analysis, and pharmacy benefit management constitute the technical core. Large corporations in California and Texas drive demand as state-level mandates multiply. ACA compliance complexity sustains retainer relationships beyond annual renewal cycles.
- Compliance Advisory:ERISA fiduciary documentation, nondiscrimination testing, and IRS filing preparation require actuarial certification. Mid-sized firms facing federal reporting mandates generate the fastest advisory engagement growth. Multi-state employers multiply touchpoints as state insurance commissioners impose divergent standards.
- Retirement Planning:Qualified plan design and investment menu construction.
- Wellness Programs:Biometric screening integration and incentive structure design.
- Risk Management:Captive funding feasibility and stop-loss placement.
Volume placements concentrate in Health Benefits Design; the faster expansion belongs to Compliance Advisory.
Client Type:
Pricing power and service intensity diverge sharply by organizational scale, with enterprise complexity subsidizing standardized offerings for smaller accounts.
- Large Corporations:Fortune 500 employers demand actuarial depth for self-funded health plan designs and captive funding structures. Sophisticated internal benefits staff enable multi-sourced advisory relationships. Mercer and Aon compete through proprietary benchmarking databases and strategic plan architecture.
- Mid-Sized Firms:Organizations with 100 to 999 employees lack dedicated benefits staff but face identical ACA reporting requirements. Gallagher captures share through integrated property-casualty and benefits platforms. Hybrid consulting delivery models compress traditional advisory economics while expanding access.
- Small Enterprises:Automated enrollment platforms reduce traditional consulting unit economics.
- Non-Profit Organizations:Mission constraints and board governance requirements shape procurement.
- Government Agencies:Public sector procurement rules and political oversight cycles.
Revenue concentration sits with Large Corporations; Mid-Sized Firms are climbing the fastest as ACA mandates expand.
Consulting Delivery Model:
Technology intensity and labor substitution potential define margin structures across engagement formats.
- Hybrid Solutions:Remote actuarial support combined with onsite employee education sessions captures employer demand for cost efficiency without sacrificing relationship depth. Technology and professional services sectors lead adoption where internal staff coordinate vendor ecosystems. Real-time analytics platforms interface with employer HRIS systems.
- Software-Enabled Advisory:Algorithmic plan optimization and predictive claims analytics embed consulting into subscription platforms. Small enterprises below 100 employees represent underpenetrated demand where automation replicates core advisory functions.
- Onsite Engagements:High-touch strategic consulting for complex plan redesigns.
- Remote Consulting:Virtual actuarial support and compliance documentation.
Advisory hours concentrate in Hybrid Solutions; Software-Enabled Advisory is gaining share fastest as employers demand real-time plan analytics.
Investment Strategy:
Plan structure selection determines actuarial certification requirements and ongoing fiduciary exposure for plan sponsors.
- Defined Contribution:401(k) plan design with auto-enrollment features and target-date fund menus dominates new plan formation. Large corporations shift pension liabilities through plan freezes and cash balance conversions. IRS nondiscrimination testing requirements sustain annual advisory engagement.
- Health Savings Accounts:Triple tax-advantaged savings vehicles paired with high-deductible health plans. Mid-sized firms adopt HSA-compatible designs to manage premium escalation. State tax treatment variations require localized compliance navigation.
- Defined Benefit:Traditional pension plan administration for legacy obligations.
- Cash Balance:Hybrid structures combining defined benefit security with defined contribution portability.
- Hybrid Plans:Combination designs blending multiple retirement income sources.
Plan formations concentrate in Defined Contribution; Health Savings Accounts show the steepest expansion trajectory as employers manage cost escalation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States employers generate the dominant share of outsourced benefits advisory demand as ACA reporting mandates and state-level insurance regulations multiply compliance complexity. Large corporations and mid-sized firms across multiple states drive retainer relationships beyond annual renewal cycles.
United States
Mid-sized firms with 100 to 999 employees lack dedicated benefits staff but face identical federal documentation requirements as Fortune 500 employers. The US Department of Labor enforces ERISA fiduciary standards that shape how consultants structure fee disclosures and avoid prohibited transactions. Texas and California impose divergent network adequacy standards that multi-state employers must navigate, multiplying advisory touchpoints in Dallas-Fort Worth and Los Angeles metro clusters.
United Kingdom
Defined contribution pension auto-enrollment mandates sustain ongoing advisory engagement for plan design and investment menu construction. The Pensions Regulator oversees compliance with automatic enrollment duties and contribution rate escalations. London-based financial services and professional services firms lead adoption of hybrid consulting delivery models that blend remote actuarial support with onsite employee education.
Germany
Corporate pension reform discussions and bAV (betriebliche Altersvorsorge) expansion proposals drive demand for retirement plan restructuring advisory. BaFin regulates insurance-based pension products and fiduciary standards for occupational retirement provision. Frankfurt and Munich house the densest concentrations of employer-sponsored pension consulting as manufacturing and automotive sectors evaluate pension liability transfers.
Canada
Provincial health care cost-shifting to employers intensifies demand for private benefits design to supplement public coverage gaps. Health Canada and provincial insurance regulators oversee supplemental health product standards and pricing review processes. Toronto and Vancouver metro areas concentrate advisory activity as technology and financial services sectors expand total rewards programs.
Australia
Superannuation guarantee rate increases and stapling reforms reshape employer compliance obligations for retirement contributions. The Australian Prudential Regulation Authority supervises superannuation fund governance and member outcomes tests. Sydney and Melbourne financial districts anchor benefits consulting demand as professional services firms navigate default fund selection and insurance in superannuation regulations.
Employee Benefits Strategy and Consulting Market Competitive Landscape
Multi-sourced advisory engagement dominates the current landscape as employers fragment procurement across boutique specialists and large brokerage houses. The vendor base clusters around three strategic archetypes: global brokers with proprietary benchmarking databases, integrated property-casualty platforms, and actuarial boutiques serving self-funded plan migration. Consolidation pressure and hybrid delivery model investments represent the two dominant competitive moves reshaping cost structures.
Among global advisory networks, Mercer, Aon, and Willis Towers Watson occupy positions that exemplify distinct competitive vectors. Mercer anchors actuarial depth for complex self-funded health plan architecture. Aon sustains pricing advantages through proprietary benchmarking databases in competitive renewal cycles. Willis Towers Watson sits within the integrated risk and benefits advisory tier where cross-selling pathways into mid-market accounts concentrate retention economics.
| Leading Market Players |
|---|
| Mercer |
| Aon |
| Willis Towers Watson |
| Marsh McLennan |
| Gallagher |
| WTW |
| Lockton |
| Alliant Insurance Services |
| Brown & Brown |
| Others |
Pricing and Supply Chain Analysis
Mid-sized firms demanding hybrid consulting delivery models with embedded real-time analytics are forcing advisory firms to restructure cost bases around software-enabled service tiers, compressing traditional hourly billing rates while elevating platform subscription pricing. This procurement shift concentrates pricing power with vendors that control proprietary benchmarking databases and actuarial certification pipelines.
Pricing Analysis
Volume placements concentrate in project-based health benefits design engagements, while margin expansion sits with software-enabled advisory subscriptions that embed algorithmic plan optimization. Price differentiation hinges on actuarial certification depth and proprietary data asset access, with Fortune 500 clients least sensitive to fee escalation and small enterprises below 100 employees driving cost compression through automated platform adoption. Pricing pressure stems from fee compression in standardized compliance advisory as enrollment software replicates core documentation functions.
Supply Chain Analysis
Freight costs for in-person employee education sessions and onsite strategic consulting engagements concentrate supply chain pressure in Dallas-Fort Worth and Los Angeles metro clusters where multi-state employers multiply advisory touchpoints. Talent sourcing draws from actuarial certification pipelines in the United States, United Kingdom, and Canada, with qualified actuary scarcity creating single-source vulnerability for boutique specialist firms. Distribution runs through direct employer relationships brokered by large advisory networks and regional property-casualty platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a supply-constrained environment where actuarial certification bottlenecks prop pricing power for firms that control credential pipelines and proprietary benchmarking databases.
For Market Incumbents: Cement retention economics by deepening captive actuarial talent pipelines through university partnership programs and credential sponsorships. Build defensive moats around proprietary claims data assets that automated platforms cannot replicate, while accelerating hybrid delivery model investments to capture mid-sized firm demand before boutique competitors scale. For New Entrants and Emerging Players: AI-powered predictive analytics platforms offer the most penetrable wedge for technology-first entrants targeting small enterprises below 100 employees where traditional consulting unit economics have collapsed. White-space concentration sits in automated enrollment platforms with embedded ACA compliance checks, with go-to-market traction achievable through channel partnerships with payroll processors and HRIS vendors. For Investors and Strategic Acquirers: Re-rating potential sits with actuarial boutiques possessing specialized mental health parity compliance capabilities given federal enforcement action acceleration. Long-term viability across the analysis window favors platforms combining benefits advisory with property-casualty integration, with acquisition screens prioritizing firms showing sustained client retention above renewal cycles. Monitor state-level public option framework developments as the signal indicating regulatory complexity inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Delivery Model Investment | Blends remote actuarial support with onsite education to capture mid-sized firm demand in Texas and California. |
| Proprietary Benchmarking Database Expansion | Sustains pricing advantages in competitive renewal cycles for self-funded health plan designs. |
| Actuarial Certification Pipeline Development | Addresses talent scarcity constraints that limit boutique firm scale and margin expansion. |
| Mental Health Parity Compliance Specialization | Differentiates retention as US Department of Labor enforcement actions reshape plan documentation requirements. |
| Property-Casualty Platform Integration | Controls cross-selling pathways into mid-market accounts seeking single-source risk consolidation. |
Research Methodology
SEC 10-K filings, ERISA plan document databases, and state insurance commissioner regulatory filings formed the secondary backbone, supplemented by trade association surveys from the Self-Insurance Institute of America and the National Association of Insurance Commissioners. Primary fieldwork encompassed benefits directors at Fortune 500 employers, actuarial consultants at global brokerage houses, compliance officers at mid-sized firms, and HR technology procurement leads. Bottom-up and top-down triangulation validated service line revenue allocations and client segment penetration rates across the analysis window.
Bottom-up modeling anchored forecasts in employer count projections by size tier and advisory engagement intensity assumptions, while top-down validation cross-checked against total rewards expenditure trends and benefits outsourcing penetration patterns. Segmentation dimensions spanned service type, client scale, delivery model technology intensity, and investment strategy plan structure. CAGRs derived from trend extrapolation of ACA mandate expansion trajectories and self-funded plan migration rates, with mental health parity enforcement timelines and state-level public option developments serving as scenario sensitivity inputs.
Several conditions sit outside the modeled scope, including potential federal preemption of state insurance mandates, structural shifts in employer-sponsored coverage toward defined contribution health arrangements, and macroeconomic recession impacts on benefits advisory discretionary spending. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.