
 Regtech Market | 2026-2036
Regtech Market Size, Share, and Industry Trends Forecast 2026-2036
Regtech Market Intelligence
North American software development capacity is rebalancing toward real-time regulatory tooling as financial institutions confront escalating compliance costs. IBM leverages its hybrid cloud infrastructure to anchor enterprise-grade risk management deployments across Tier-1 banks. Thomson Reuters sustains dominant positioning in regulatory change management through its proprietary content feeds and rule-monitoring engines. Chainalysis specializes in blockchain analytics, competing for law enforcement and exchange-monitoring contracts with forensic-level transaction tracing capabilities.
Regtech encompasses software systems that automate regulatory compliance, risk assessment, and reporting obligations through machine-readable rule engines, API-based data aggregation, and continuous monitoring protocols. These platforms process structured and unstructured regulatory text, map obligations to internal controls, and generate audit trails for supervisors. Cloud-based deployment models now capture the fastest-growing share of new implementations as banks exit capital-intensive on-premise estates. Compliance monitoring solutions command the deepest margin pools due to recurring subscription structures and high switching costs embedded in rule-engine customization. Fraud detection segments are expanding rapidly within payment processors confronting real-time settlement mandates from the European Central Bank and the Federal Reserve.
The US Securities and Exchange Commission and the Financial Crimes Enforcement Network are expanding reporting requirements for investment advisors and cryptocurrency intermediaries, directly enlarging addressable demand for automated filing and surveillance tools. The European Banking Authority and the EU AI Act compliance deadlines are forcing cross-border banks to consolidate fragmented national compliance stacks into unified platforms. Stakeholders must monitor how divergent US and EU supervisory technology standards reshape vendor product roadmaps and certification requirements.
Market Dynamics
Real-time transaction surveillance mandates from US and EU regulators are compressing deployment timelines for automated compliance infrastructure, forcing financial institutions to consolidate fragmented monitoring stacks into unified cloud-native platforms.
Growth Catalysts
- EU AI Act enforcement:Cross-border banks face binding algorithmic audit requirements that mandate machine-readable risk documentation, directly expanding demand for automated rule-mapping engines.
- Cryptocurrency exchange oversight:The US Financial Crimes Enforcement Network has intensified suspicious activity reporting obligations for virtual asset service providers, enlarging the addressable market for blockchain surveillance tooling.
- Real-time payment settlement:The European Central Bank's T2 and the Federal Reserve's FedNow instant payment rails require continuous fraud detection, pulling payment processors toward embedded compliance modules.
Market Restraints
- Cloud infrastructure concentration:Tier-1 banks remain dependent on three dominant hyperscale providers for elastic compute, creating systemic vulnerability during regulatory examination periods.
- Rule-engine customization lock-in:Proprietary ontology mapping between regulatory text and internal controls generates switching costs that suppress vendor competition.
- Cross-border data localization:Divergent US CLOUD Act and EU GDPR data sovereignty requirements fragment platform architectures, inflating operational overhead.
Strategic Opportunities
- Embedded compliance APIs:Fintech infrastructure providers are white-labeling modular KYC and transaction monitoring components, enabling neobanks to launch with pre-certified regulatory stacks.
- Climate risk disclosure convergence:The EU Corporate Sustainability Reporting Directive and proposed US SEC climate rules are creating unified ESG data aggregation demand across asset managers.
- India:The Reserve Bank of India's phased implementation of digital lending guidelines and account aggregator frameworks is opening greenfield procurement for automated credit underwriting compliance.
Industry Challenges
- Machine-readable regulatory text scarcity:Supervisory agencies publish obligations in unstructured PDF formats, forcing vendors to maintain expensive manual annotation pipelines for rule extraction.
- Legacy core banking integration:Decades-old COBOL-based transaction systems resist API connectivity, delaying real-time monitoring deployment at systemically important institutions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Regtech Market |
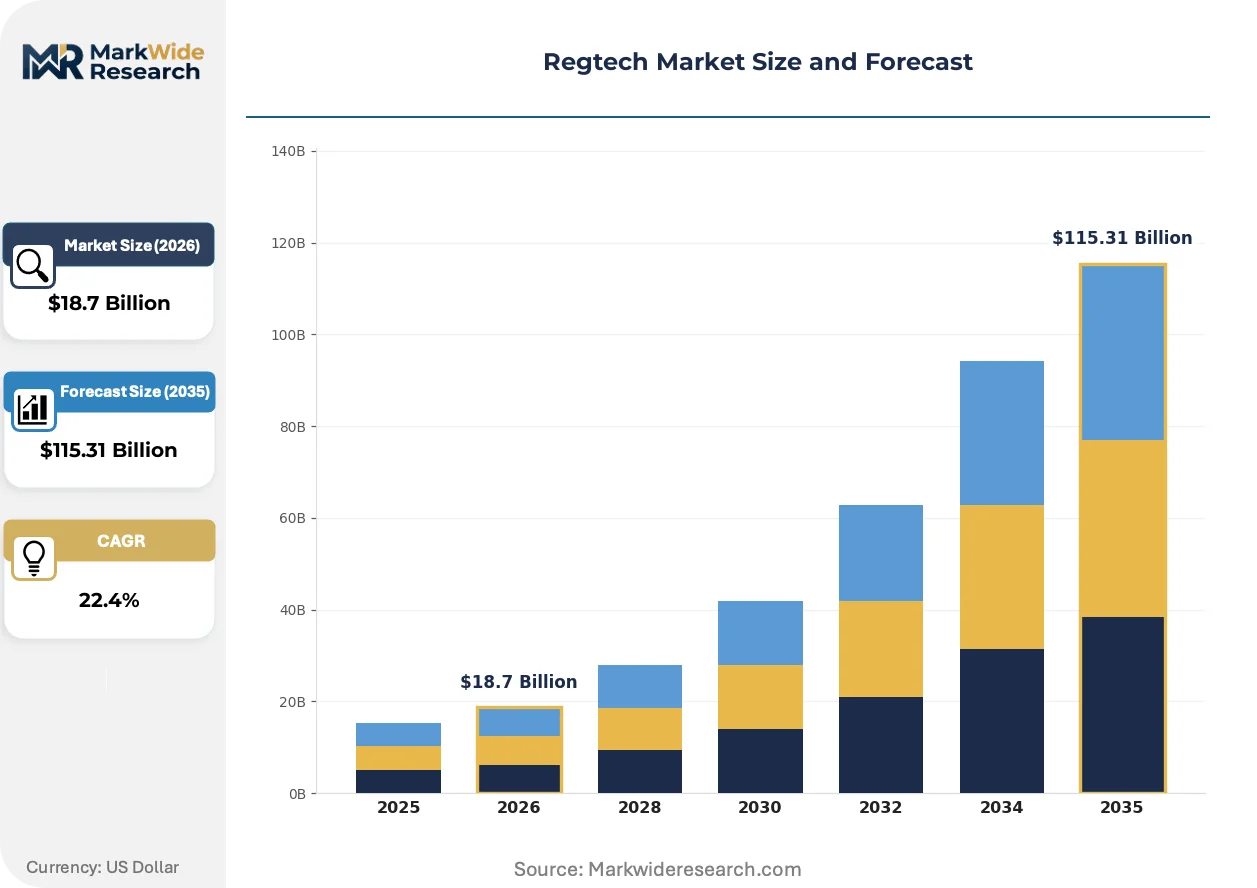
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $115.31 Billion |
| CAGR (2026 – 2036) | 22.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Type: Risk Management, Compliance Monitoring, Fraud Detection, Regulatory Reporting, Identity Verification, Data Protection Deployment Model: Cloud-Based, On-Premise, Hybrid, Software-as-a-Service, Platform-as-a-Service Customer Type: Financial Institutions, Insurance Providers, Payment Processors, Investment Managers, Credit Unions, Wealth Managers Application Area: Anti-Money Laundering, Know Your Customer, Transaction Monitoring, Regulatory Change Management, Audit & Reporting |
| Companies Covered | IBM, Thomson Reuters, Broadridge Financial Solutions, Deloitte Touche Tohmatsu, ACTICO GmbH, Ascent Technologies, Chainalysis, ComplyAdvantage, Fenergo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Regtech Market Strategic Shifts & Innovations
Natural language processing engines trained on regulatory corpora are compressing the lag between rule publication and operational implementation, collapsing what previously required quarters into weeks.
Large language models fine-tuned on enforcement actions and supervisory guidance are integrating directly into compliance workflow platforms, enabling risk officers to query obligation interpretations through conversational interfaces rather than static rule libraries. Regional banks lacking dedicated legal technology teams are adopting these tools fastest, outsourcing interpretive complexity to algorithmic systems. The structural consequence is a compression in headcount growth at compliance functions even as regulatory volume expands.
The EU AI Act's risk classification framework for algorithmic decision systems is mandating technical documentation standards that exceed current audit capabilities at most financial institutions, forcing procurement of external model validation platforms. Asset managers deploying systematic trading strategies face particular exposure given the Act's strictures on high-frequency automation. Vendors are responding with pre-certified algorithmic impact assessment modules that map directly to notified body requirements.
Subscription-based compliance monitoring is displacing perpetual license models as buyers prioritize operational expenditure treatment and vendor accountability for regulatory update velocity. Tier-2 banks and credit unions are driving this transition, lacking capital reserves for upfront enterprise software commitments. The shift is most visible in the United States, where regional institutions face identical examination intensity to money-center banks with fractionally smaller technology budgets.
Regtech Market Segmentation
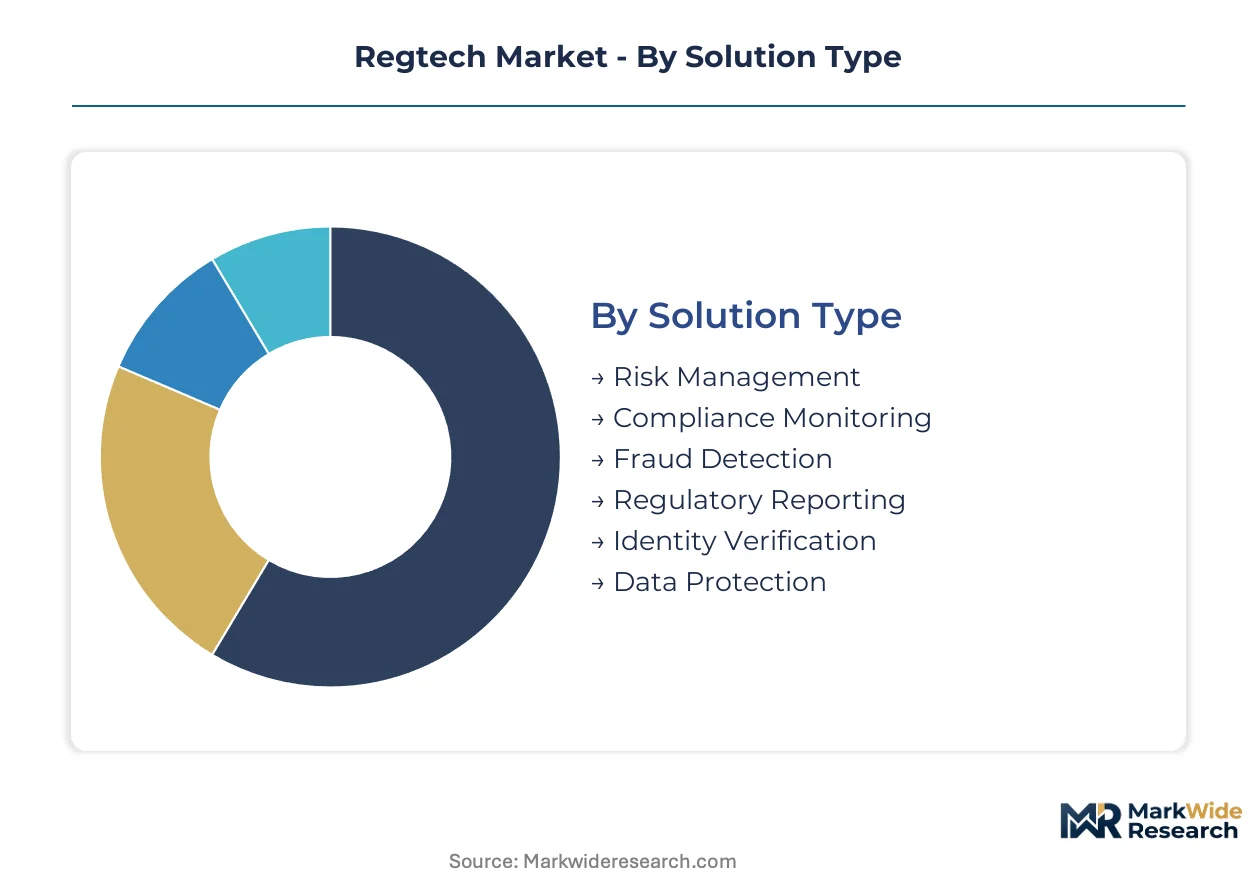
Regtech procurement patterns diverge sharply across solution architectures and buyer sophistication. Deployment decisions hinge on legacy infrastructure maturity, regulatory examination intensity, and cloud risk tolerance.
Solution Type:
Functional capabilities separate high-margin recurring revenue streams from project-based implementation fees.
- Compliance Monitoring:Continuous surveillance platforms ingest regulatory feeds and map obligations to internal controls through machine-readable rule engines. United States Tier-1 banks dominate procurement as SEC and FinCEN examination cycles intensify, compressing vendor sales timelines and embedding switching costs through proprietary ontology customization.
- Fraud Detection:Real-time transaction scoring systems deploy adaptive behavioral models to flag anomalous payment flows. European payment processors facing ECB T2 instant settlement mandates represent the steepest expansion trajectory, pulling embedded compliance modules into core infrastructure stacks.
- Risk Management:Quantitative engines aggregate exposure metrics across asset classes and geographies for capital adequacy reporting.
- Regulatory Reporting:Automated filing systems structure supervisory submissions from fragmented source systems.
- Identity Verification:Biometric and document-authentication pipelines streamline KYC onboarding for digital-first institutions.
- Data Protection:Encryption and access-control frameworks address GDPR and sector-specific privacy mandates.
Mature deployment sits with Compliance Monitoring. Newer deployment is concentrated in Fraud Detection.
Deployment Model:
Cost tier structures separate capital-constrained buyers from institutions with elastic infrastructure budgets.
- Cloud-Based:Elastic compute environments enable rapid scaling during examination periods without fixed capital commitments. United States regional banks and credit unions are migrating fastest, prioritizing operational expenditure treatment over depreciating on-premise estates.
- Software-as-a-Service:Subscription delivery models shift regulatory update liability to vendors. European cross-border banks consolidating fragmented national stacks are climbing the fastest, driven by EU AI Act unified platform mandates.
- Hybrid:Split architectures retain sensitive data on-premise while pushing compute-intensive analytics to cloud nodes.
- On-Premise:Dedicated hardware deployments persist at systemically important institutions with legacy COBOL core dependencies.
- Platform-as-a-Service:Developer-centric environments enable custom compliance application construction.
Established volume concentrates in Cloud-Based. Emerging procurement favors Software-as-a-Service.
Customer Type:
Application sophistication varies with regulatory examination intensity and technology budget scale.
- Financial Institutions:Universal banks deploy comprehensive stacks spanning risk, compliance, and reporting functions. United States money-center banks anchor demand, confronting simultaneous SEC, FinCEN, and Federal Reserve oversight expansion.
- Payment Processors:Real-time settlement infrastructure demands continuous fraud surveillance. European acquirers facing ECB instant payment mandates are gaining share fastest, embedding compliance modules directly into transaction rails.
- Insurance Providers:Solvency II and state-level filing requirements drive actuarial reporting automation.
- Investment Managers:SEC adviser registration and Form PF obligations shape surveillance procurement.
- Credit Unions:Shared service models and consortium purchasing compress per-institution technology spend.
- Wealth Managers:High-net-worth client confidentiality requirements favor private cloud deployments.
Deep customization concentrates with Financial Institutions. Rapid standardization is accelerating among Payment Processors.
Application Area:
Regulatory mandate specificity determines automation feasibility and vendor pricing power.
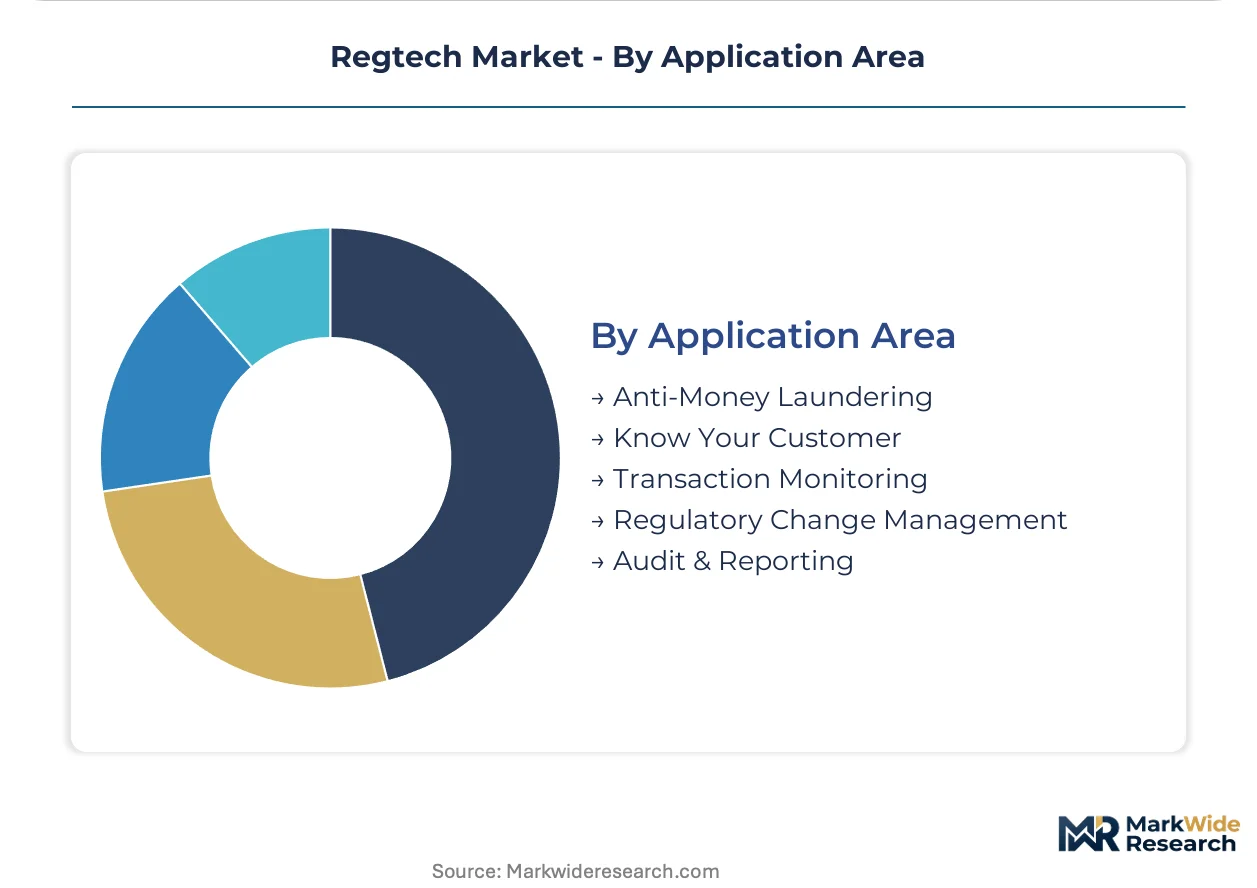
- Anti-Money Laundering:Suspicious activity monitoring systems deploy network analytics to trace layered transactions. United States cryptocurrency exchanges facing intensified FinCEN enforcement represent the steepest expansion trajectory, mandating blockchain-native surveillance tooling.
- Know Your Customer:Identity verification pipelines integrate document authentication, biometric matching, and sanctions screening. European neobanks leveraging white-label API components are climbing the fastest, launching with pre-certified regulatory stacks.
- Transaction Monitoring:Real-time payment surveillance flags structuring and velocity anomalies.
- Regulatory Change Management:Rule-monitoring engines track jurisdictional obligation evolution.
- Audit & Reporting:Automated documentation systems generate examination-ready evidence trails.
Mature automation sits with Anti-Money Laundering. Emerging standardization is concentrated in Know Your Customer.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Financial services density and regulatory intensity concentrate procurement demand in jurisdictions with active supervisory technology mandates. Capital markets infrastructure and enforcement capacity determine platform deployment velocity.
United States
SEC examination cycles and FinCEN cryptocurrency surveillance mandates compress vendor sales timelines for automated filing systems. The Federal Reserve's FedNow instant payment rails require continuous fraud detection, pulling regional banks toward cloud-native compliance stacks. New York and Chicago anchor procurement concentration, with money-center banks deploying unified risk management platforms.
United Kingdom
FCA operational resilience requirements and Prudential Regulation Authority supervisory technology expectations drive consolidation of fragmented monitoring systems. The Financial Services and Markets Act reforms expand algorithmic trading oversight, mandating machine-readable risk documentation. London's regulatory technology cluster concentrates vendor development and Tier-1 bank procurement decisions.
Germany
BaFin enforcement of EU AI Act risk classifications for credit scoring algorithms forces procurement of external model validation platforms. Bundesbank real-time payment surveillance requirements align with ECB T2 settlement mandates. Frankfurt's banking concentration hosts the deepest European demand for regulatory change management tooling.
Singapore
Monetary Authority of Singapore digital banking license frameworks and payment services oversight expand addressable demand for embedded compliance APIs. The country's fintech sandbox programs accelerate neobank launches with pre-certified KYC stacks. The Marina Bay financial district concentrates procurement for Asia-Pacific cross-border transaction monitoring.
India
RBI digital lending guidelines and account aggregator frameworks open greenfield procurement for automated credit underwriting compliance. SEBI investment adviser registration expansion enlarges surveillance tooling demand. Mumbai and Bengaluru anchor development, with payment processors embedding real-time transaction monitoring into UPI infrastructure.
Regtech Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue specialized blockchain analytics and AI-powered interpretation tools. The vendor base stratifies across three maturity tiers: legacy technology conglomerates with hybrid cloud infrastructure, regulatory content specialists with proprietary rule-monitoring engines, and niche forensic platforms with transaction tracing capabilities. Competitive positioning depends on regulatory update velocity, ontology customization depth, and examination period responsiveness. Dominant moves include strategic partnerships with hyperscale cloud providers and portfolio diversification into climate risk disclosure modules.
Within the legacy technology tier, IBM leverages hybrid cloud infrastructure to anchor enterprise-grade deployments. Thomson Reuters sustains positioning through proprietary content feeds and rule-monitoring engines. Chainalysis occupies the forensic analytics vector, competing for law enforcement and exchange-monitoring contracts with blockchain-native surveillance capabilities.
| Leading Market Players |
|---|
| IBM |
| Thomson Reuters |
| Broadridge Financial Solutions |
| Deloitte Touche Tohmatsu |
| ACTICO GmbH |
| Ascent Technologies |
| Chainalysis |
| ComplyAdvantage |
| Fenergo |
| Others |
Cost & Logistics Intelligence
Cloud compute capacity costs cascade through Regtech pricing tiers, with hyperscale infrastructure fees from United States-based providers feeding into subscription rates for compliance monitoring platforms sold to regional banks and credit unions.
Pricing Analysis
Regulatory update warranty bundling separates premium compliance monitoring tiers from standard offerings, with vendors absorbing rule-engine refresh costs in top-tier contracts while mid-market buyers pay per-update fees. Pricing stratifies across enterprise-grade customization, configurable SaaS modules, and entry-level API access points. Cost compression in the mid-market tier is intensifying because European neobanks demand pre-certified KYC stacks at fractional money-center bank budgets. Credit unions exhibit the highest price sensitivity, while Tier-1 banks prioritize examination-period responsiveness over unit cost.
Supply Chain Analysis
Reverse-logistics flows for on-premise hardware refreshes are diminishing as United States, United Kingdom, and German financial institutions accelerate cloud-native migrations, reducing refurbishment demand for legacy compliance servers. The supply chain draws from hyperscale compute providers in the United States, specialized NLP engineering talent in India, and regulatory content aggregators in the United Kingdom. Single-source vulnerability concentrates in cloud infrastructure concentration among three dominant providers. Distribution runs through direct enterprise sales teams for Tier-1 banks and channel partners for regional institutions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
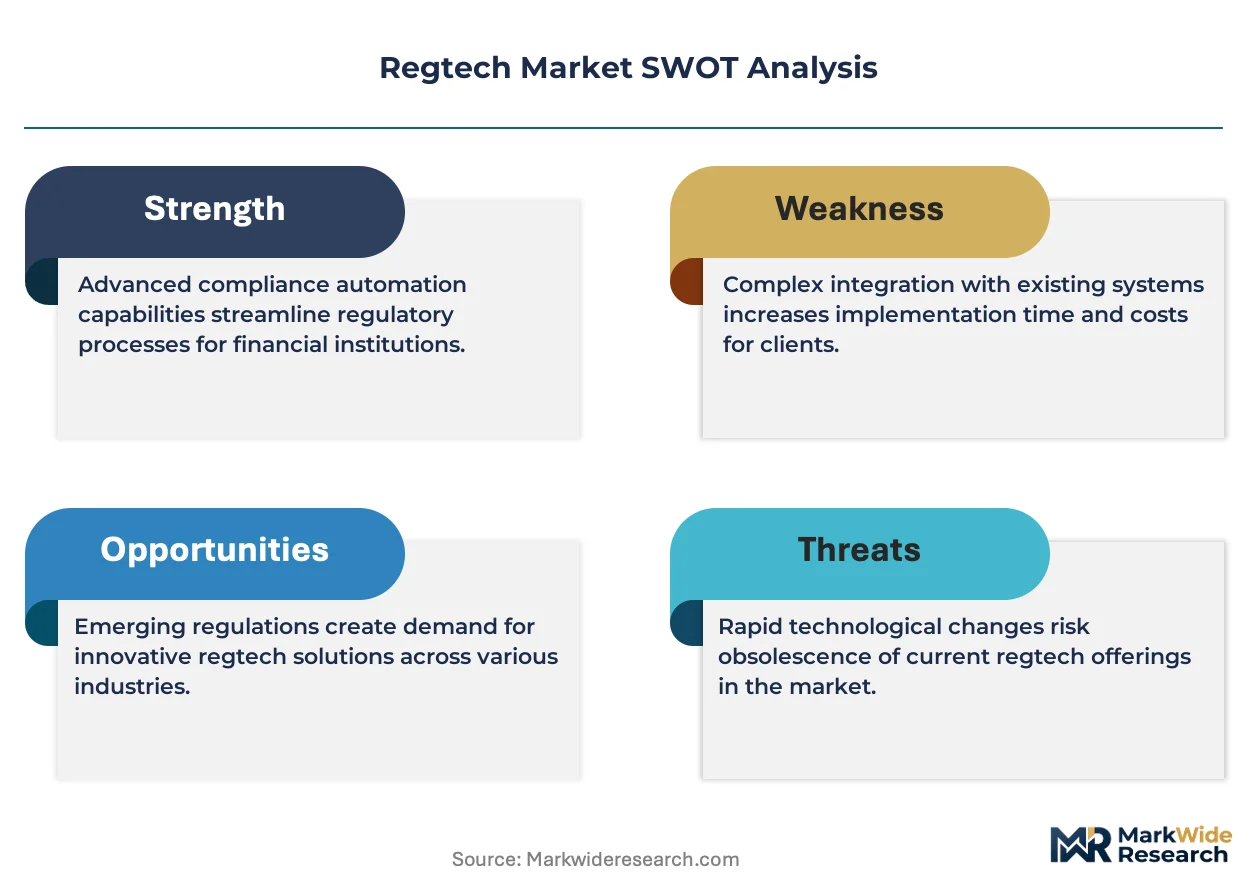
Regtech is undergoing a machine-readable rule engine transition, with NLP-powered obligation mapping displacing manual legal technology teams at regional banks.
For Market Incumbents: To counter embedded compliance API commoditization by fintech infrastructure providers, IBM and Thomson Reuters should deepen ontology customization capabilities and anchor multi-year enterprise contracts through examination-period SLA guarantees. Certification investment in EU AI Act pre-validated modules offers defensive positioning against niche model validation entrants. For New Entrants and Emerging Players: Begin with white-label KYC components for Indian neobanks launching under RBI digital lending guidelines, where regulatory stack certification creates procurement urgency without incumbent lock-in. Target payment processors embedding real-time fraud detection into UPI infrastructure as the most penetrable application area. Pursue channel partnerships with hyperscale cloud marketplaces to bypass direct sales overhead. For Investors and Strategic Acquirers: RBI account aggregator framework implementation timelines are the leading indicator that automated credit underwriting compliance demand will accelerate in India. Five-to-ten year viability favors vendors with proprietary regulatory content feeds and rule-monitoring engines over pure-play analytics tools. Acquire specialists with forensic blockchain tracing capabilities as cryptocurrency exchange oversight intensifies. Monitor FinCEN enforcement action velocity for early signals of addressable market expansion.| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Pre-Certification | Pre-validated algorithmic impact assessment modules map directly to notified body requirements in Germany. |
| Embedded Compliance API Launch | White-label KYC components enable Indian neobanks to launch with RBI-compliant regulatory stacks. |
| Hyperscale Cloud Partnership | Strategic alliances with AWS, Azure, or GCP anchor elastic compute for FedNow fraud detection workloads. |
| Regulatory Content Feed Expansion | Proprietary rule-monitoring engines tracking SEC and EBA obligation evolution sustain recurring revenue. |
| Blockchain Forensic Capability Buildout | Transaction tracing tooling captures law enforcement and cryptocurrency exchange surveillance contracts. |
Research Approach
Independent corroboration across chief compliance officers, risk technology leads, regulatory affairs directors, and fintech infrastructure procurement managers underwrites the qualitative findings in this study. Primary interviews with United States Tier-1 bank technology executives, European payment processor operations heads, and Indian neobank founders combined with secondary validation from SEC enforcement action databases, ECB supervisory guidance publications, RBI circular archives, and vendor SEC filings. Bottom-up deployment estimates and top-down market sizing triangulate to segment-level outputs.
Comparable-period anchoring to historical procurement cycles across the projection horizon informed growth trajectory calibration. The analytical framework models solution type, deployment model, customer type, and application area segmentation alongside jurisdictional regulatory intensity scoring. CAGRs derive from elasticity-adjusted adoption curves and examination mandate enforcement velocity. NLP engine training data scale and rule-engine customization depth serve as forecast sensitivity inputs.
Underlying measurement precision varies by segment; compliance monitoring and fraud detection carry tighter precision than emerging climate risk disclosure modules. Forecasts reflect assumptions regarding regulatory enforcement continuity and cloud migration velocity. Practitioners should monitor EU AI Act notified body accreditation timelines and FinCEN cryptocurrency exchange examination frequency for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Risk Management and Compliance
BFSI Crisis Management Market
Risk Management and Compliance
Travel Risk Management Services Market
Risk Management and Compliance
Operational Risk Management Consulting Services in Manufacturing Market
Risk Management and Compliance
Pre Trade Risk Management Solution Market
Risk Management and Compliance
Corporate Investigation Services Market
Risk Management and Compliance
Fraud Detection and Prevention (FDP) Market
Risk Management and Compliance
Oil and Gas Risk Management Market
Risk Management and Compliance
Healthcare Fraud Detection Market
Risk Management and Compliance
Revenue Assurance Market
Risk Management and Compliance
Global Risk and Compliance Consulting Services Market
Risk Management and Compliance
Europe Governance, Risk and Compliance Platform Market
Risk Management and Compliance
Global Risk Management Software Market
Risk Management and Compliance
Third Party Risk Management Market
Risk Management and Compliance
North America BFSI Biometrics Market
Risk Management and Compliance
Anti-Money Laundering (AML) Market
Risk Management and Compliance
Disclosure Management Market