
 Enterprise Governance, Risk, and Compliance (Egrc) Market | 2026-2036
Enterprise Governance, Risk, and Compliance (Egrc) Market Size, Share, and Industry Trends Forecast 2026-2036
Enterprise Governance, Risk, and Compliance (Egrc) Market Intelligence
The European Union's General Data Protection Regulation (GDPR) is decoupling data privacy compliance from IT security budgets, creating a distinct C-suite risk category. IBM Corporation leverages its AI capabilities within OpenPages to automate risk assessment. SAP SE integrates GRC functions directly into its core ERP systems for a unified experience. ServiceNow positions its platform to manage digital transformation risks across enterprise workflows.
Enterprise Governance, Risk, and Compliance is a capability that enables an organization to reliably achieve objectives, address uncertainty, and act with integrity. These software platforms use a common framework and a single data repository to align activities around performance and risk. Cloud-based deployments are the fastest-growing segment, offering scalability for large enterprises and SMEs. Within solution types, risk management and compliance management modules represent the largest share, especially in the financial services industry.
Regulatory frameworks like the Sarbanes-Oxley Act (SOX) in the United States and the EU's CSRD directly mandate the processes that eGRC solutions automate. International standards such as ISO 31000 for risk management and China's GB standards for data security provide methodologies that shape platform features. Stakeholder focus now turns to integrating ESG metrics and AI-driven predictive risk analytics into existing GRC frameworks.
Market Dynamics
The convergence of financial compliance with non-financial reporting mandates, particularly Environmental, Social, and Governance (ESG) criteria, is the central force shaping the eGRC market. This integration compels organizations to expand their risk frameworks beyond traditional boundaries, driving investment in more holistic platforms.
Growth Catalysts
- Regulatory Expansion:Directives like the European Union's Corporate Sustainability Reporting Directive (CSRD) and the Sarbanes-Oxley Act (SOX) in the United States create non-negotiable requirements for auditable controls and transparent reporting, directly fueling demand for automated eGRC solutions.
- AI in Risk Assessment:The embedding of artificial intelligence and machine learning into eGRC platforms enables predictive risk analytics and automates control testing. This technological shift attracts organizations seeking to move from reactive compliance to proactive risk mitigation.
- Financial Services Demand:The financial services industry, facing a dense web of regulations from entities like the SEC and central banks, requires integrated frameworks to manage operational, credit, and compliance risks cohesively, acting as a primary demand driver.
Market Restraints
- High Implementation Costs:The significant upfront investment required for licensing, customization, and integration of enterprise-wide eGRC platforms presents a substantial barrier for small and medium-sized enterprises (SMEs) with limited capital budgets.
- Legacy System Integration:Difficulty in integrating modern cloud-based eGRC software with entrenched, legacy on-premise systems creates data silos and operational friction, limiting the effectiveness of a unified risk management strategy.
- Regulatory Fragmentation:A complex and evolving landscape of disparate regulations across different jurisdictions, such as varying data privacy laws at the state level in the United States, complicates the development of a single, universally compliant framework.
Strategic Opportunities
- SME-Focused Solutions:Developing scalable, modular, and cloud-native eGRC solutions tailored to the budget and complexity needs of small and medium-sized enterprises represents a significant area for market penetration.
- Operational Technology (OT) Risk Management:Extending eGRC capabilities to include the governance and security of OT environments offers a new growth vector, particularly within the manufacturing, energy, and critical infrastructure sectors. *Supply Chain Risk Integration: There is a clear opportunity to merge third-party risk management (TPRM) and supply chain resilience functionalities into core eGRC platforms, providing a 360-degree view of external and internal enterprise risks.
Industry Challenges
- Hybrid Skill Scarcity:A persistent shortage of professionals possessing a combined expertise in regulatory compliance, data analytics, and IT security hinders the ability of organizations to fully leverage the advanced capabilities of modern eGRC platforms.
- Data Unification Complexity:Consolidating disparate and often unstructured data from various business functions like finance, legal, and operations into a single, reliable data repository for risk analysis remains a major operational hurdle for many enterprises.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Enterprise Governance, Risk, and Compliance (Egrc) Market |
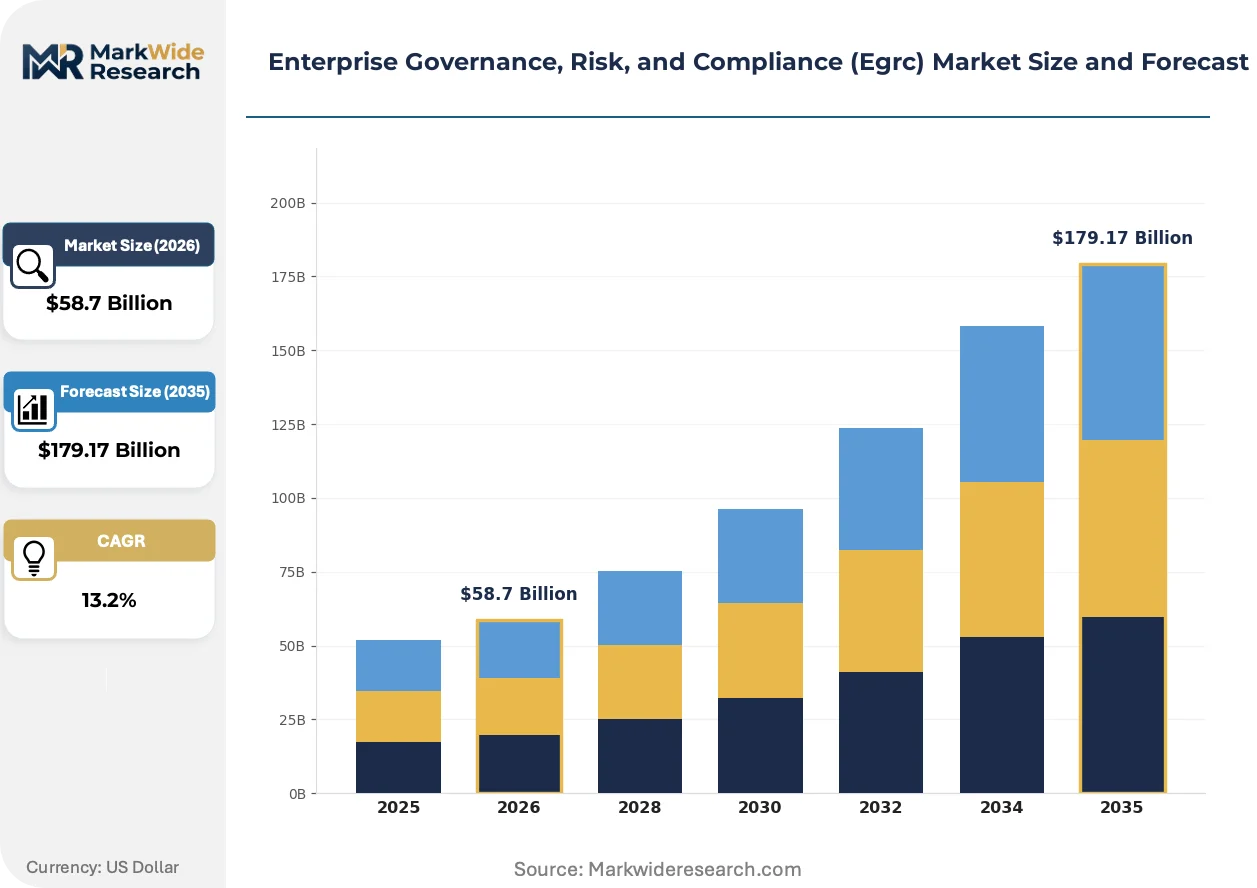
| Market Size in 2026 | $58.7 Billion |
| Market Size in 2035 | $179.17 Billion |
| CAGR (2026 – 2036) | 13.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premises, Cloud-Based, Hybrid, Private Cloud Solution Type: Risk Management, Compliance Management, Policy Management, Audit Management, Incident Management Industry Vertical: Manufacturing, Financial Services, Telecommunications, Energy & Utilities, Government Agencies End User Type: Small & Medium Enterprises, Large Enterprises, Managed Service Providers, System Integrators |
| Companies Covered | IBM Corporation, Microsoft Corporation, SAP SE, Oracle Corporation, Wolters Kluwer, ServiceNow, MetricStream, SAS Institute, FIS, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Enterprise Governance, Risk, and Compliance (Egrc) Market Strategic Shifts & Innovations
The eGRC market is transitioning from a focus on siloed, check-the-box compliance activities toward an integrated, predictive approach to risk management. This evolution is driven by the fusion of advanced analytics with core GRC processes and an expanding definition of enterprise risk.
Artificial intelligence is being embedded into platform workflows to automate the identification and prioritization of emerging risks. Highly regulated sectors like banking and life sciences are adopting these tools to analyze vast datasets for control deficiencies and potential compliance breaches. This analytical capability is converging with business intelligence tools, enabling leadership to view risk exposure as a direct input into strategic planning and performance management.
New regulations targeting technology itself are creating specific compliance modules within eGRC suites. The European Union's AI Act, for instance, establishes a risk-based framework for artificial intelligence systems, compelling developers and users to ensure transparency and accountability. In response, eGRC solutions are incorporating features for AI model inventory, risk assessment, and continuous monitoring to help organizations demonstrate compliance with these emerging rules.
Buyer behavior is shifting from the procurement of separate point solutions toward the adoption of unified platforms that provide a single view of risk. This trend is displacing the traditional best-of-breed purchasing strategy for individual audit, policy, and compliance management tools. The demand for consolidated Integrated Risk Management (IRM) suites is most visible within large, multinational corporations aiming to reduce vendor complexity and enforce consistent risk taxonomies globally.
Enterprise Governance, Risk, and Compliance (Egrc) Market Segmentation
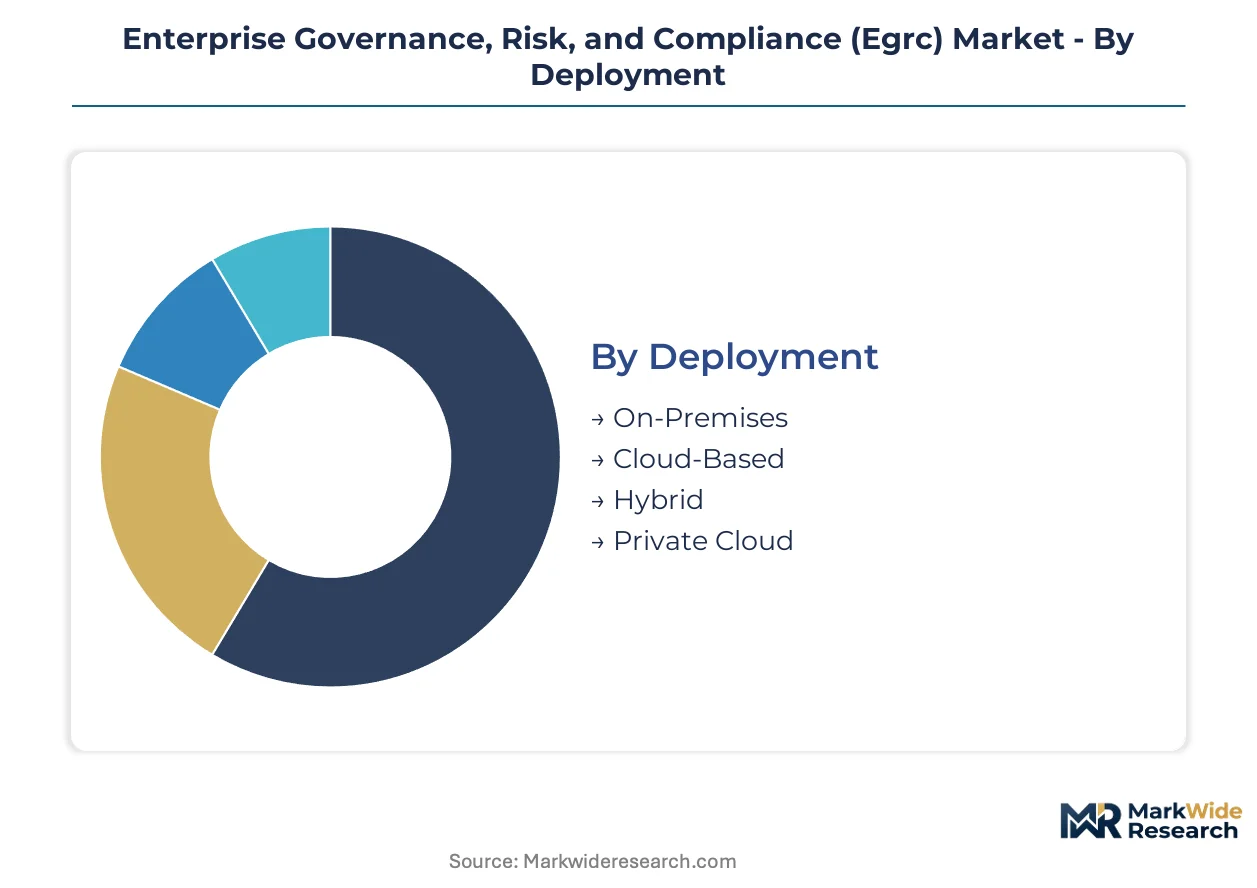
The Enterprise Governance, Risk, and Compliance (EGRC) market segments based on deployment, solution type, industry vertical, and end-user type. This granular classification helps organizations select platforms that align with their operational models, regulatory burdens, and strategic objectives for risk management.
Deployment:
The customization versus standardization spectrum defines how organizations implement eGRC solutions, influencing integration complexity and scalability.
- Cloud-Based:These solutions are hosted by a third-party provider and accessed via the internet, offering scalability and reduced infrastructure costs. Demand concentrates in large enterprises and SMEs seeking flexible, rapidly deployable compliance frameworks.
- Hybrid:This model combines elements of both on-premises and cloud deployments, allowing organizations to maintain sensitive data locally while leveraging cloud resources for other functions. Financial services firms often adopt hybrid models to balance data sovereignty with operational agility.
- On-Premises:Software is installed and run on computers located at the organization's own premises, providing maximum control over data security and customization. Highly regulated sectors like government agencies with strict data residency requirements often favor this approach.
- Private Cloud:Dedicated cloud infrastructure provisioned for exclusive use by a single organization, offering enhanced security and control compared to public cloud. Large corporations in Europe utilize private cloud for managing sensitive regulatory data under GDPR.
Leading the category by volume: Cloud-Based. Growing fastest: Hybrid.
Solution Type:
The functional focus of eGRC platforms varies, addressing specific facets of an organization's governance and risk landscape.
- Risk Management:These modules identify, assess, and mitigate various operational, financial, and strategic risks across the enterprise. Financial services organizations heavily invest in risk management solutions to navigate complex market volatility and credit exposures.
- Compliance Management:Solutions automate the process of adhering to external laws, regulations, and internal policies, ensuring auditable adherence. The European Union's CSRD mandates comprehensive compliance reporting, driving significant demand in this segment.
- Policy Management:Software centralizes the creation, distribution, and enforcement of internal policies and procedures across an organization. Government agencies use policy management tools to ensure consistent application of internal directives.
- Audit Management:Tools streamline internal and external audit processes, from planning and execution to reporting and remediation tracking. Manufacturing companies leverage audit management to maintain quality standards and supply chain integrity.
- Incident Management:This segment focuses on detecting, reporting, and resolving security breaches, operational failures, or compliance violations. Telecommunications providers utilize incident management to quickly address service disruptions and data compromises.
The segment composition reflects the core needs of regulated industries, with Risk Management and Compliance Management forming the largest shares.
Industry Vertical:
The intensity of regulatory oversight and the nature of operational risks shape eGRC adoption across different economic sectors.
- Financial Services:This sector faces an exceptionally dense and evolving regulatory environment from entities like the SEC and central banks, requiring integrated GRC platforms for operational, credit, and compliance risks.
- Government Agencies:Public sector entities contend with stringent mandates for transparency, data security, and accountability, necessitating robust eGRC solutions to manage public funds and sensitive citizen data.
- Manufacturing:Manufacturers employ eGRC for supply chain risk management, quality control compliance, and environmental regulations across their global operations. China's GB standards influence GRC requirements for manufacturers operating there.
- Telecommunications:This industry navigates complex data privacy laws, network security regulations, and service level agreements, driving demand for eGRC platforms to ensure continuous compliance.
- Energy & Utilities:Critical infrastructure operators require eGRC for managing operational technology risks, environmental compliance, and safety regulations.
The demand landscape for eGRC solutions is largely defined by the regulatory burden and operational complexity inherent in each industry vertical.
End User Type:
The scale of operations and internal resource availability dictate the type of eGRC solutions preferred by different organizational structures.
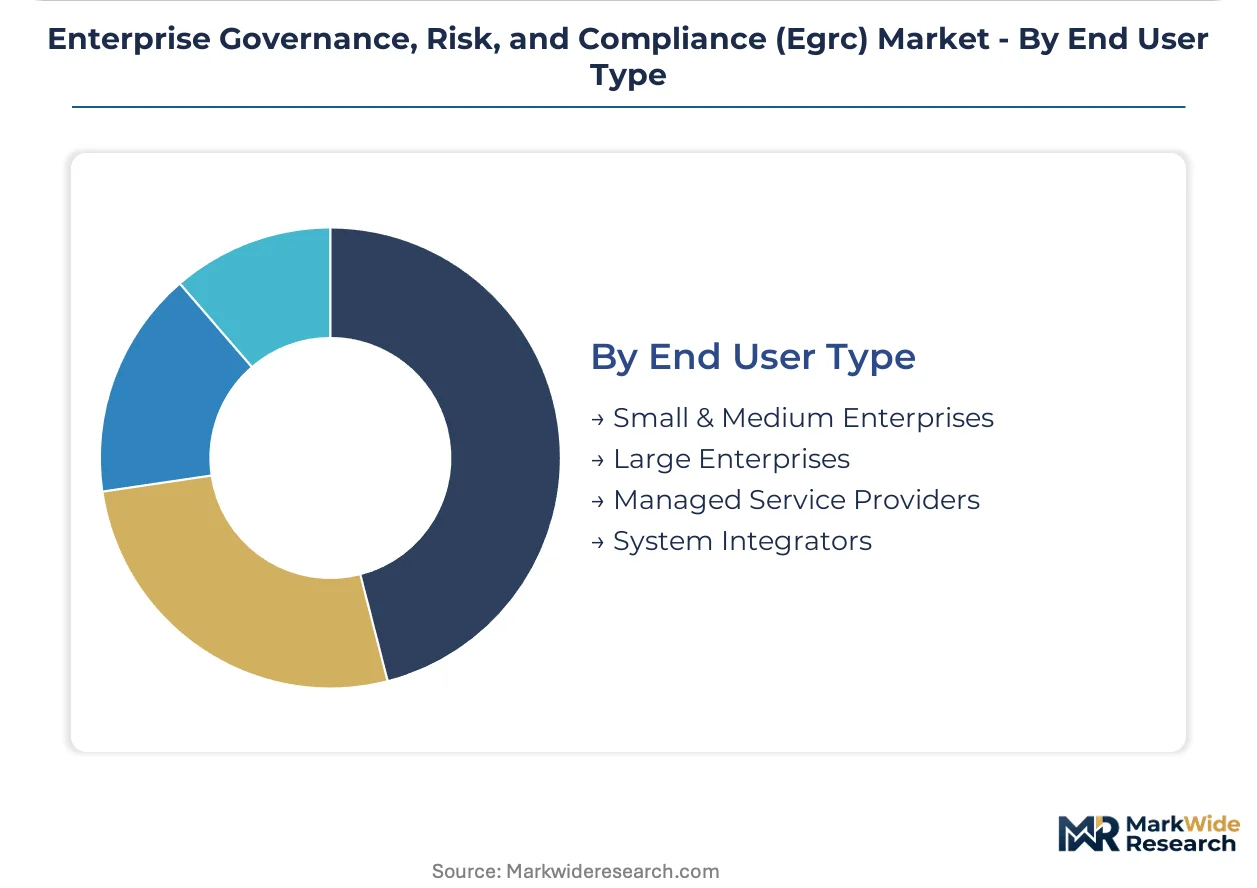
- Large Enterprises:These organizations require comprehensive, scalable eGRC platforms capable of integrating diverse data sources and managing complex regulatory frameworks across multiple geographies. Multinational corporations in the United States prioritize unified risk taxonomies.
- Small & Medium Enterprises:SMEs seek cost-effective, modular, and cloud-native eGRC solutions that address core compliance needs without extensive upfront investment or dedicated IT resources.
- Managed Service Providers:MSPs offer eGRC as a service to their clients, leveraging their expertise and shared infrastructure to deliver compliance and risk management capabilities.
- System Integrators:SIs specialize in implementing and customizing eGRC platforms for enterprises, ensuring seamless integration with existing IT infrastructure and business processes.
Large Enterprises consistently drive significant investment in eGRC platforms, while Small & Medium Enterprises are gaining share fastest through tailored solutions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States' complex federal and state-level regulatory landscape acts as a primary concentration zone for Enterprise GRC solutions. Organizations there navigate a web of mandates, driving significant demand for integrated platforms. This regulatory density compels continuous investment in advanced GRC capabilities.
United States
Organizations in the United States face intense pressure from federal agencies like the SEC and state-level mandates. The Sarbanes-Oxley Act (SOX) continues to drive demand for auditable financial controls across public companies. Silicon Valley and New York City financial hubs actively integrate AI-driven risk analytics into their GRC frameworks.
Germany
German enterprises prioritize data privacy and operational resilience amidst strict European regulations. The EU's GDPR mandates robust data governance, influencing platform adoption across industries. Frankfurt's financial sector and Munich's industrial giants implement comprehensive eGRC systems to ensure compliance.
China
Chinese companies navigate evolving national data security and environmental compliance standards. China's GB standards for data security shape GRC feature requirements for domestic and international businesses. The Yangtze River Delta region, with its extensive manufacturing base, focuses on supply chain risk integration.
India
India's rapidly digitizing economy drives demand for eGRC solutions to manage cyber risks and regulatory adherence. The Reserve Bank of India (RBI) mandates stringent financial compliance for banks and non-banking financial companies. Bengaluru's tech industry and Mumbai's financial institutions are adopting cloud-based GRC platforms.
Japan
Japanese businesses emphasize robust corporate governance and risk management in a highly structured environment. METI guidelines encourage digital transformation initiatives, including GRC adoption for operational efficiency. Tokyo's large corporations implement integrated risk management suites for complex global operations.
Enterprise Governance, Risk, and Compliance (Egrc) Market Key Industry Players
North American software giants anchor one tier of the eGRC market; European and Asian specialists hold distinct niches. The market structure is moderately fragmented, with a mix of established enterprise software vendors and specialized GRC providers. Strategic archetypes include comprehensive platform providers, niche compliance specialists, and AI-driven analytics innovators. Dominant competitive moves involve strategic partnerships for market reach and continuous portfolio diversification through feature enhancements.
Leading platform providers such as IBM Corporation exemplify the trend towards integrating artificial intelligence capabilities into GRC workflows, offering advanced automation for risk assessment and predictive analytics. SAP SE represents the archetype of a major ERP vendor, extending GRC functions directly into core business systems for a unified enterprise experience across various modules. ServiceNow occupies a position as a cloud-native specialist, focusing on managing digital transformation risks across enterprise workflows and providing scalable solutions for diverse enterprise needs, particularly for large enterprises.
| Leading Market Players |
|---|
| IBM Corporation |
| Microsoft Corporation |
| SAP SE |
| Oracle Corporation |
| Wolters Kluwer |
| ServiceNow |
| MetricStream |
| SAS Institute |
| FIS |
| Others |
Cost & Logistics Intelligence
Skilled labor costs for software development directly influence the pricing of advanced eGRC platforms, impacting subscription tiers for large enterprises and the accessibility for small and medium-sized businesses. This cost component feeds into the overall platform development and maintenance, ultimately affecting the final price point for various solution types.
Pricing Analysis
Rapid deployment services for eGRC solutions command a premium, reflecting the urgency organizations attach to compliance deadlines and immediate risk mitigation. Pricing primarily follows a SaaS-tiered subscription model, scaling with user count, feature sets, and data volume. Customization level and after-sales support significantly differentiate pricing among vendors. Pricing pressure stems from the increasing availability of modular, cloud-native solutions for SMEs. Large enterprises exhibit lower price sensitivity for comprehensive Integrated Risk Management suites.
Supply Chain Analysis
Cloud-based distribution models deliver eGRC platforms directly to end-users, bypassing traditional physical logistics and enabling rapid global deployment. The supply chain for eGRC software concentrates in technology hubs like the United States, Germany, and India, where skilled software engineers and robust cloud infrastructure providers are prevalent. Raw material dependencies include access to high-performance data centers and a continuous supply of specialized software development talent. A structural supply chain risk is the hybrid skill scarcity, which can delay product development and implementation. System integrators and Managed Service Providers form critical downstream distribution channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Enterprise GRC market is fundamentally a cost-of-compliance narrative, with directives like the EU's CSRD creating a significant barrier-to-entry moat for organizations capable of comprehensive, auditable reporting.
For Market Incumbents: Extend core GRC platform capabilities to encompass emerging non-financial reporting mandates, such as comprehensive ESG data integration. Invest heavily in AI-driven predictive analytics to move beyond reactive compliance, countering threats from specialized analytics innovators. Consolidate market position through strategic acquisitions of niche technology firms. Reinforce platform integration with existing ERP systems to reduce customer friction.
For New Entrants and Emerging Players: Capture market share within the underserved SME segment by offering modular, cloud-native eGRC solutions with lower upfront investment requirements. Focus on specific white-space opportunities like Operational Technology (OT) risk management or integrated supply chain risk functionalities. A go-to-market angle emphasizing rapid deployment and simplified user experience can penetrate new customer bases. Target specific regional compliance needs, such as China's GB standards or India's RBI mandates.
For Investors and Strategic Acquirers: The consistent integration of AI-driven predictive analytics into core GRC platforms is the leading indicator that the market is maturing towards proactive risk management. Long-term viability remains strong, driven by perpetual regulatory evolution and the expanding definition of enterprise risk over the next 5-10 years. Acquisition targets should include specialized AI risk analytics firms or cloud-native providers with strong vertical expertise. Increased M&A activity for specialized AI risk analytics firms signals market consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Enhances data unification across diverse business functions, reducing operational friction for large enterprises. |
| AI Capability Development | Automates risk assessment and predictive analytics, offering proactive risk mitigation for highly regulated sectors. |
| SME Solution Tailoring | Expands market penetration by addressing budget and complexity needs of small and medium-sized enterprises. |
| Operational Technology (OT) GRC Extension | Opens new growth vectors in manufacturing and energy by covering industrial control system risks. |
| Strategic Partnerships | Accelerates market reach and expands solution portfolios through collaboration with complementary technology providers. |
Research Approach
Regulatory filings from financial bodies, industry association reports, and enterprise software vendor disclosures anchored secondary inputs for this market assessment. This approach combined extensive secondary research with primary interviews conducted with GRC officers, IT procurement managers, compliance specialists, and CIOs across various industries. Bottom-up and top-down triangulation ensured data accuracy and comprehensive market coverage.
Data-stream reconciliation across historical market performance and projected technological adoption informed the quantitative analysis over the projection horizon. The forecast framework modeled segmentation dimensions including deployment type, solution type, industry vertical, end-user type, and regulatory impact. Compound annual growth rates were derived from competitive landscape analysis and market trend extrapolation. Regulatory pipeline developments and AI adoption rates served as key industry-specific forecast inputs.
The model holds under current regulatory stability and projected technological advancements; deviation in major geopolitical shifts or rapid, unforeseen regulatory overhauls would shift market trajectories. Forecasts reflect assumptions regarding the continued expansion of compliance mandates and the integration of advanced technologies within GRC frameworks. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Risk Management and Compliance
Global Risk and Compliance Consulting Services Market
Risk Management and Compliance
Sell-Side Due Diligence Services Market
Risk Management and Compliance
Anti-Money Laundering (AML) Market
Risk Management and Compliance
Loan Compliance Management Software Market
Risk Management and Compliance
Asia-Pacific Sustainable Finance Market
Risk Management and Compliance
Europe Strategic Consulting Services Market
Risk Management and Compliance
Artificial Intelligence and Regtech Market
Risk Management and Compliance
Trade Surveillance Market
Risk Management and Compliance
Enterprise Risk Management Market
Risk Management and Compliance
Healthcare Fraud Detection Market
Risk Management and Compliance
Risk Management Market
Risk Management and Compliance
Treasury and Risk Management Market
Risk Management and Compliance
Sustainable Finance Market
Risk Management and Compliance
Southeast Asia Credit and Risk Management Market
Risk Management and Compliance
Certificates Market
Risk Management and Compliance
Global Management Decision Market