
 Europe Strategy Consulting Market | 2026-2036
Europe Strategy Consulting Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Strategy Consulting Market Insights
Germany's industrial decarbonization advisory capacity is reshaping how European strategy consultancies deploy talent and build sector-specific practices. Roland Berger leverages its Munich-rooted automotive heritage to anchor industrial transformation mandates across the continent. McKinsey & Company competes through deep public-sector digitization benches in Brussels and Berlin. Oliver Wyman specializes in financial services regulatory response, particularly around ECB climate risk guidance and stress-testing protocols.
Europe strategy consulting encompasses advisory services that diagnose competitive positioning, redesign operating models, and orchestrate large-scale organizational change across multinational enterprises. Practitioners apply structured analytical frameworks—market entry matrices, cost-curve diagnostics, capability-gap assessments—to reduce strategic uncertainty and accelerate executive decision velocity. Management consulting and operations consulting together occupy the mature revenue core, while IT strategy commands premium pricing as cybersecurity, cloud migration, and AI governance mandates intensify. The project-based engagement model dominates complex transformation programs, though retainer relationships sustain recurring advisory access for corporations navigating prolonged regulatory uncertainty.
The EU Green Deal, CSRD disclosure rules, and ECB climate risk expectations are forcing strategy consultancies to embed sustainability analytics and double-materiality assessment capabilities into standard engagement architectures. EMA pharmaceutical pricing negotiations and REACH chemical compliance deadlines further expand the regulatory advisory surface for healthcare and manufacturing verticals. Stakeholders must decide whether to build specialized regulatory practices in-house or deepen partnerships with boutique compliance-advisory hybrids as Brussels accelerates enforcement timelines.
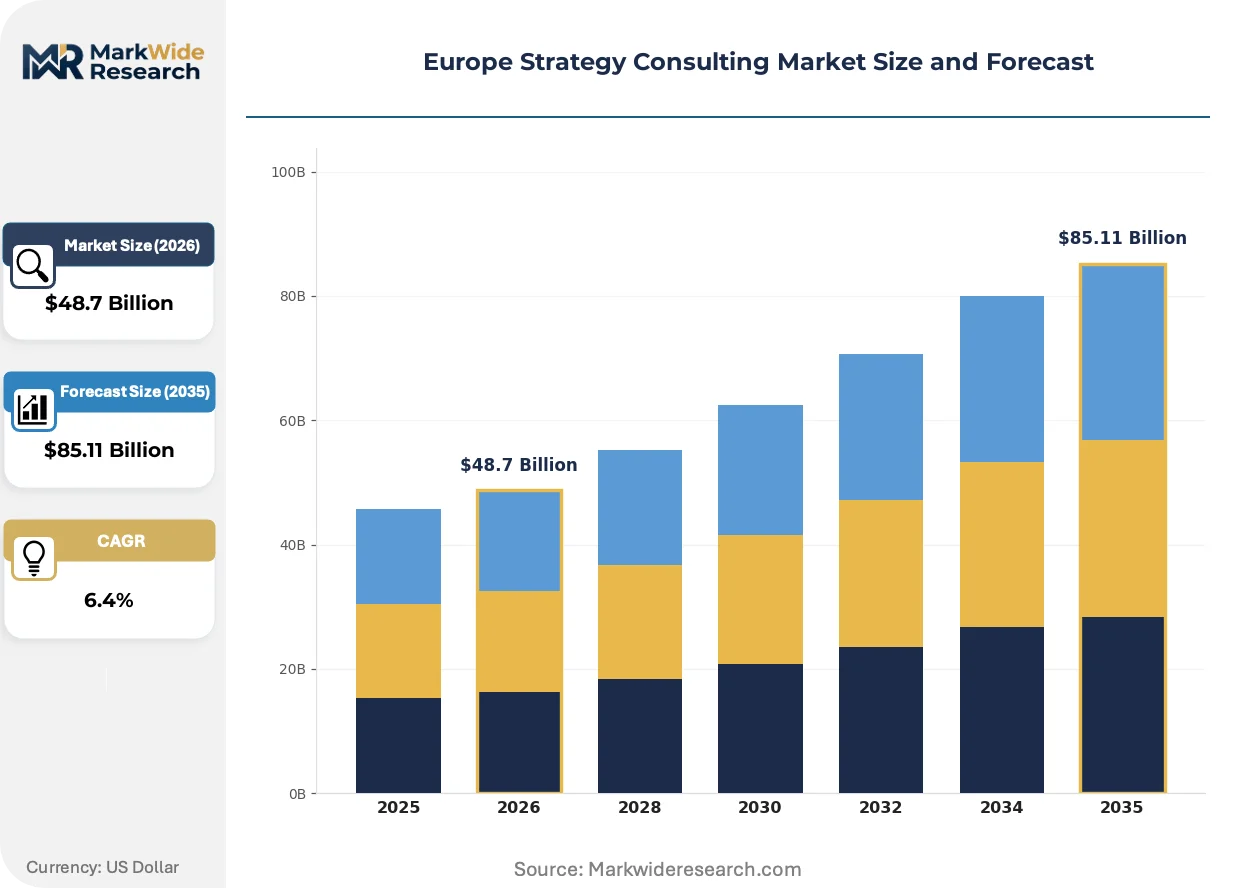
Market Dynamics
EU Green Deal compliance deadlines and ECB climate risk disclosure mandates are forcing European corporations to restructure operating models faster than internal capabilities allow, creating sustained advisory demand across industrial and financial verticals.
Growth Catalysts
- CSRD disclosure mandates:Corporations across France and Germany must embed double-materiality assessment into strategic planning, requiring external advisory support for data architecture and stakeholder mapping.
- Automotive electrification:Battery supply-base localization in Germany's industrial corridor demands consulting intervention for supplier qualification and capital reallocation.
- ECB stress-testing protocols:Frankfurt-based financial institutions face iterative climate risk modeling requirements that outpace internal analytics capacity.
Market Restraints
- Talent scarcity in sustainability analytics:The shallow pool of consultants trained in EU Taxonomy alignment and carbon accounting limits practice expansion velocity.
- Procurement cycle elongation:Corporate purchasing departments in Southern Europe apply extended vendor diligence for transformation mandates exceeding five million euros.
- Regulatory fragmentation:Divergent national implementations of the EU AI Act create compliance complexity that slows cross-border engagement standardization.
Strategic Opportunities
- Central and Eastern Europe expansion:Poland and Czech manufacturing hubs lack mature advisory infrastructure for REACH chemical compliance and supply-base restructuring.
- AI governance advisory:Convergence of machine learning deployment and EU AI Act risk classification creates white-space demand for algorithmic audit capabilities.
- Pharmaceutical pricing defense:EMA negotiation frameworks in France's Ile-de-France corridor require specialized market access strategy support.
Industry Challenges
- Knowledge codification bottlenecks:Senior partners retain sector expertise in informal networks, impeding junior consultant deployment speed on specialized mandates.
- Client capability building resistance:Corporations increasingly demand technology transfer and in-house upskilling, compressing traditional advisory margins.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Strategy Consulting Market |
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $85.11 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Management Consulting, IT Strategy, Operations Consulting, Financial Advisory Client Type: Corporations, Startups, Non-Profits, Public Sector Engagement Model: Retainer, Project-Based, Hourly Consulting, Subscription Service Industry Vertical: Healthcare, Manufacturing, Telecommunications, Consumer Goods |
| Companies Covered | Roland Berger, Oliver Wyman, McKinsey & Company, OC&C Strategy Consultants, Simon-Kucher & Partners, Boston Consulting Group, Kearney, Capgemini Invent, Bain & Company, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Strategy Consulting Market Trends and Innovations
Advisory delivery models are fragmenting as clients reject generic frameworks in favor of embedded, sector-specific expertise delivered through flexible engagement architectures.
Generative AI tools for scenario modeling and executive brief generation are hybridizing traditional consultant workflows. Mid-cap industrial clients in Germany's Baden-Württemberg region pilot these capabilities for capital allocation decisions. The technology is compressing diagnostic phase timelines from twelve weeks to four, forcing consultancies to reprice discovery work or absorb margin erosion.
The EU AI Act's risk-tier classification system is mandating algorithmic governance infrastructure across financial services and healthcare verticals. Institutions must document conformity assessments and maintain human oversight protocols for high-risk applications. Brussels-based banks and Parisian health-tech clusters are prioritizing advisory partnerships that combine legal interpretation with technical implementation.
Corporate procurement functions are unbundling transformation programs into modular workstreams awarded to specialized boutiques. France's aerospace supply chain and Netherlands agritech sectors now source regulatory advisory, change management, and technology implementation from separate providers. This fragmentation rewards consultancies with narrow credential depth over generalist breadth.
Europe Strategy Consulting Market Segmentation
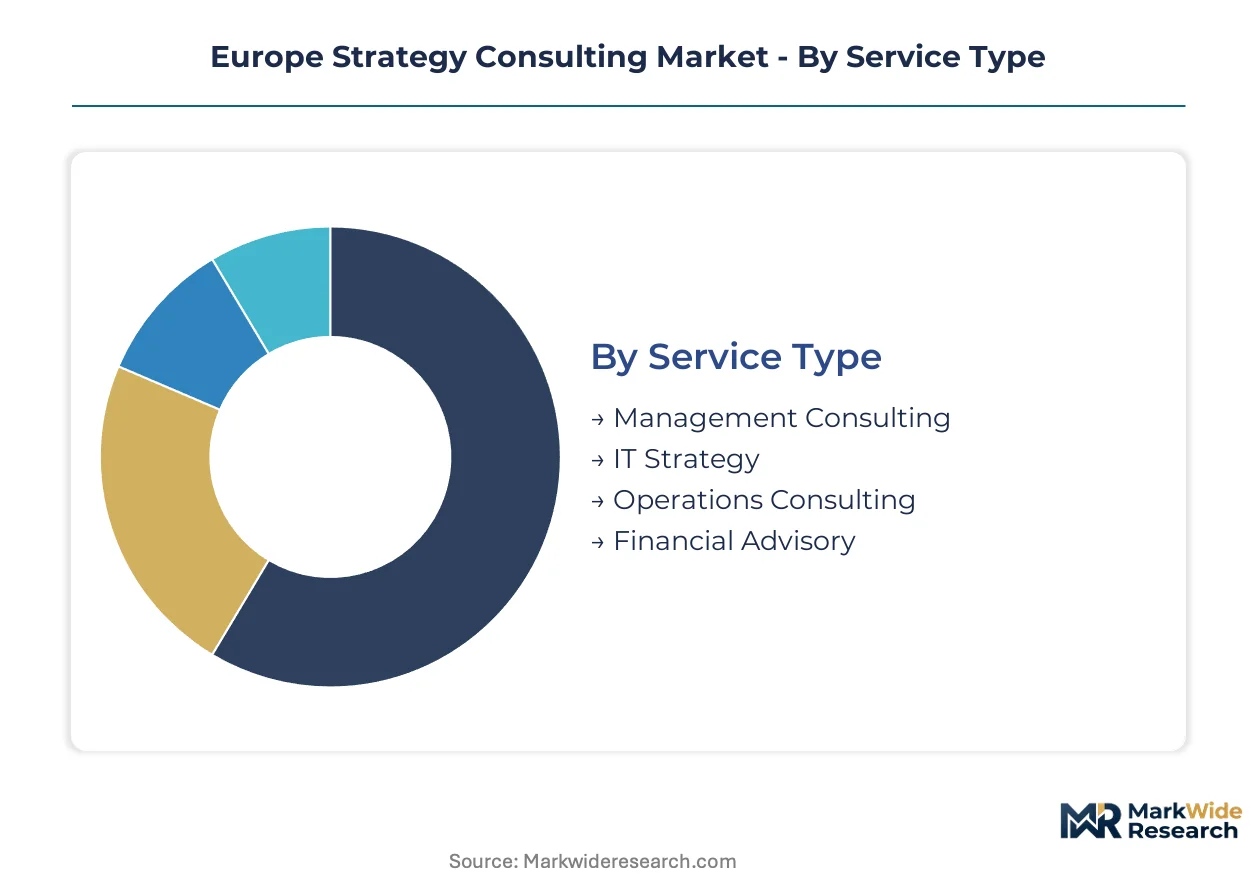
Advisory demand across Europe fragments sharply by service maturity and client sophistication. Procurement patterns diverge between legacy transformation mandates and emerging regulatory-response engagements.
Service Type:
Mature advisory categories dominate revenue capture while emerging specializations command premium pricing.
- Management Consulting:Encompasses competitive positioning diagnostics, operating model redesign, and M&A strategy. German automotive OEMs and French pharmaceutical conglomerates anchor demand as CSRD disclosure mandates force board-level strategy refreshes.
- IT Strategy:Covers cloud migration roadmapping, cybersecurity governance, and AI deployment architecture. Brussels-based financial institutions and Amsterdam health-tech clusters drive intake as ECB climate risk protocols and EU AI Act compliance deadlines converge.
- Operations Consulting:Delivers supply chain restructuring and lean manufacturing implementation. Baden-Württemberg industrial clients prioritize battery supply-base localization advisory.
- Financial Advisory:Provides capital allocation strategy, valuation support, and restructuring guidance. Frankfurt banking headquarters sustain retainer relationships for stress-testing preparation.
Management Consulting handles the majority of throughput; IT Strategy is expanding most quickly on share.
Client Type:
Contract structures and pricing power vary dramatically across organizational scale and funding source.
- Corporations:Multinational enterprises with annual advisory budgets exceeding institutional procurement thresholds. German industrial conglomerates and French aerospace groups dominate project-based transformation mandates.
- Startups:Venture-backed scale-ups requiring market entry strategy and investor readiness support. Berlin and Paris fintech corridors generate concentrated demand for regulatory navigation.
- Non-Profits:Foundations and NGOs seeking operational efficiency and impact measurement frameworks. Brussels-based climate advocacy organizations access specialized sustainability advisory.
- Public Sector:National ministries and municipal authorities pursuing digitization and policy implementation. Berlin and Paris government clients sustain long-term retainer relationships.
Corporations generate the deepest project pipelines; Startups are climbing the fastest on advisory spend intensity.
Engagement Model:
Delivery architecture determines margin structure and talent deployment cadence.
- Retainer:Recurring monthly access to partner-level advisory for sustained regulatory uncertainty. Frankfurt financial institutions and Paris healthcare conglomerates favor this structure for ECB and EMA deadline navigation.
- Project-Based:Defined-scope transformation programs with milestone-based deliverables. German automotive electrification mandates and French aerospace supply-base restructuring fit this model.
- Hourly Consulting:On-demand specialist access for discrete diagnostic or due-diligence support. Netherlands agritech and Czech manufacturing clients use this for REACH compliance spot-checks.
- Subscription Service:Platform-based access to benchmark databases and self-service analytics tools. Mid-cap industrial clients in Poland and Hungary pilot these for capital allocation decisions.
Project-Based engagements absorb the largest talent deployment; Subscription Service is gaining share fastest among cost-conscious mid-caps.
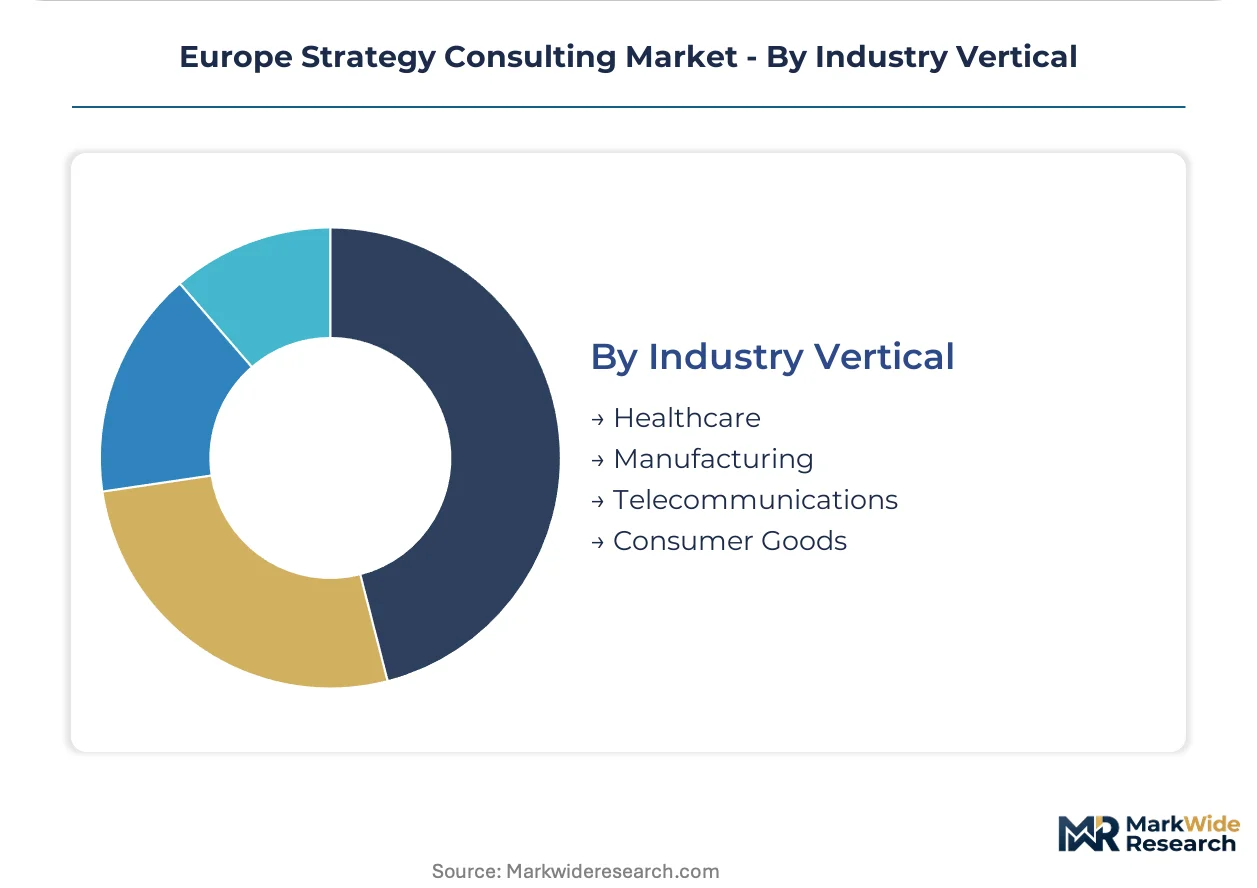
Industry Vertical:
Sector-specific regulatory intensity shapes practice specialization and partner credential requirements.
- Healthcare:Pharmaceutical pricing defense, EMA negotiation preparation, and market access strategy. France's Ile-de-France corridor concentrates demand as centralized procurement pressures intensify.
- Manufacturing:Industrial decarbonization, supply-base localization, and REACH chemical compliance. Germany's automotive battery belt and Czech industrial hubs drive transformation advisory.
- Telecommunications:5G deployment strategy, spectrum auction preparation, and digital infrastructure monetization. German and Spanish operators seek regulatory navigation support.
- Consumer Goods:Sustainability positioning, circular economy transition, and DTC channel strategy. Netherlands agritech and Danish food processing clusters access specialized advisory.
Manufacturing commands the deepest partner specialization; Healthcare shows the steepest expansion trajectory on regulatory complexity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Main-Danube waterway corridor underwrites Central Europe's advisory density, connecting Frankfurt's financial command centers to Bavaria's industrial transformation zones and enabling rapid consultant deployment across the continent's economic core.
Germany
Frankfurt's banking headquarters and Munich's automotive belt generate concentrated demand for ECB climate risk modeling and battery supply-base localization advisory. CSRD disclosure mandates force DAX-listed conglomerates to refresh board-level strategy frameworks. Stuttgart's industrial corridor anchors electrification transformation programs.
France
Parisian healthcare conglomerates and Toulouse's aerospace cluster drive EMA negotiation preparation and supply-base restructuring mandates. The EU AI Act's risk-tier classification creates compliance demand among Île-de-France health-tech operators. Lyon-based pharmaceutical groups access specialized market access strategy support.
United Kingdom
London's financial services ecosystem sustains retainer relationships for regulatory navigation, though Brexit divergence complicates cross-border engagement standardization. The FCA's operational resilience requirements drive IT strategy advisory for City institutions. Cambridge's biotech corridor generates specialized due-diligence demand.
Netherlands
Amsterdam's health-tech clusters and Rotterdam's port-linked agritech sector prioritize REACH chemical compliance and circular economy transition advisory. The country's digital infrastructure monetization creates 5G deployment strategy demand among telecommunications operators. Eindhoven's high-tech manufacturing belt accesses supply chain restructuring support.
Poland
Warsaw's emerging financial center and Wrocław's manufacturing hub lack mature advisory infrastructure for EU Taxonomy alignment and industrial decarbonization. German automotive suppliers extending eastward create localization advisory demand. Kraków's shared service centers pilot subscription-based analytics tools for capital allocation decisions.
Europe Strategy Consulting Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in regulatory niches. The Europe strategy consulting market structures around a concentrated top tier with deep sector-specific benches, supported by mid-cap boutiques that anchor discrete regulatory specializations. Three archetypes dominate: heritage-rooted industrial transformation advisors, public-sector digitization platforms, and financial services regulatory response specialists. Competitive moves center on sustainability analytics capability acquisition and Central European geographic expansion.
Among heritage-rooted advisors, Roland Berger exemplifies the industrial transformation archetype through its Munich-anchored automotive heritage. Oliver Wyman occupies a position within the financial services regulatory response tier, while McKinsey & Company represents the public-sector digitization platform archetype with established Brussels and Berlin benches. These three entities illustrate how geographic origin and historical sector focus shape competitive positioning across the European advisory landscape.
| Leading Market Players |
|---|
| Roland Berger |
| Oliver Wyman |
| McKinsey & Company |
| OC&C Strategy Consultants |
| Simon-Kucher & Partners |
| Boston Consulting Group |
| Kearney |
| Capgemini Invent |
| Bain & Company |
| Others |
Pricing and Supply Chain Analysis
Overcapacity in Central European sustainability analytics benches is compressing day-rate premiums for CSRD compliance advisory while simultaneously forcing consultancies to absorb talent-retention costs that clients refuse to pass through.
Pricing Analysis
Volume-discount tiering structures separate global strategy houses from mid-cap boutiques and solo practitioners across the European advisory landscape. Three-tier pricing stratifies across premium partner-led transformation mandates, standard manager-staffed implementation programs, and economy-tier subscription analytics platforms. Price differentiation hinges on certification depth in EU Taxonomy alignment and geographic delivery cost differentials between Frankfurt-London corridors versus Warsaw-Kraków satellite offices. Pricing pressure stems from generative AI tools compressing diagnostic timelines, with mid-cap industrial clients in Baden-Württemberg demanding rate reductions for commoditized discovery phases. Startups exhibit highest price sensitivity, while Frankfurt banking headquarters sustain premium tolerance for regulatory deadline navigation.
Supply Chain Analysis
Extended payment terms from French aerospace conglomerates and German automotive OEMs are forcing consultancies to carry 90-120 day receivables, accelerating working capital strain across partnership structures. Geographic supply concentration draws from Germany's industrial corridor, France's pharmaceutical belt, and Poland's emerging shared-service hubs for cost-optimized delivery. Raw material dependencies rest on specialized talent pipelines from INSEAD, HEC Paris, and WHU Otto Beisheim for EU regulatory expertise. Supply chain risk centers on single-source vulnerability for sustainability analytics practitioners trained in double-materiality assessment. Distribution runs through direct partner relationships for transformation mandates, with platform-based subscription tools penetrating mid-cap manufacturing clients in Central Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
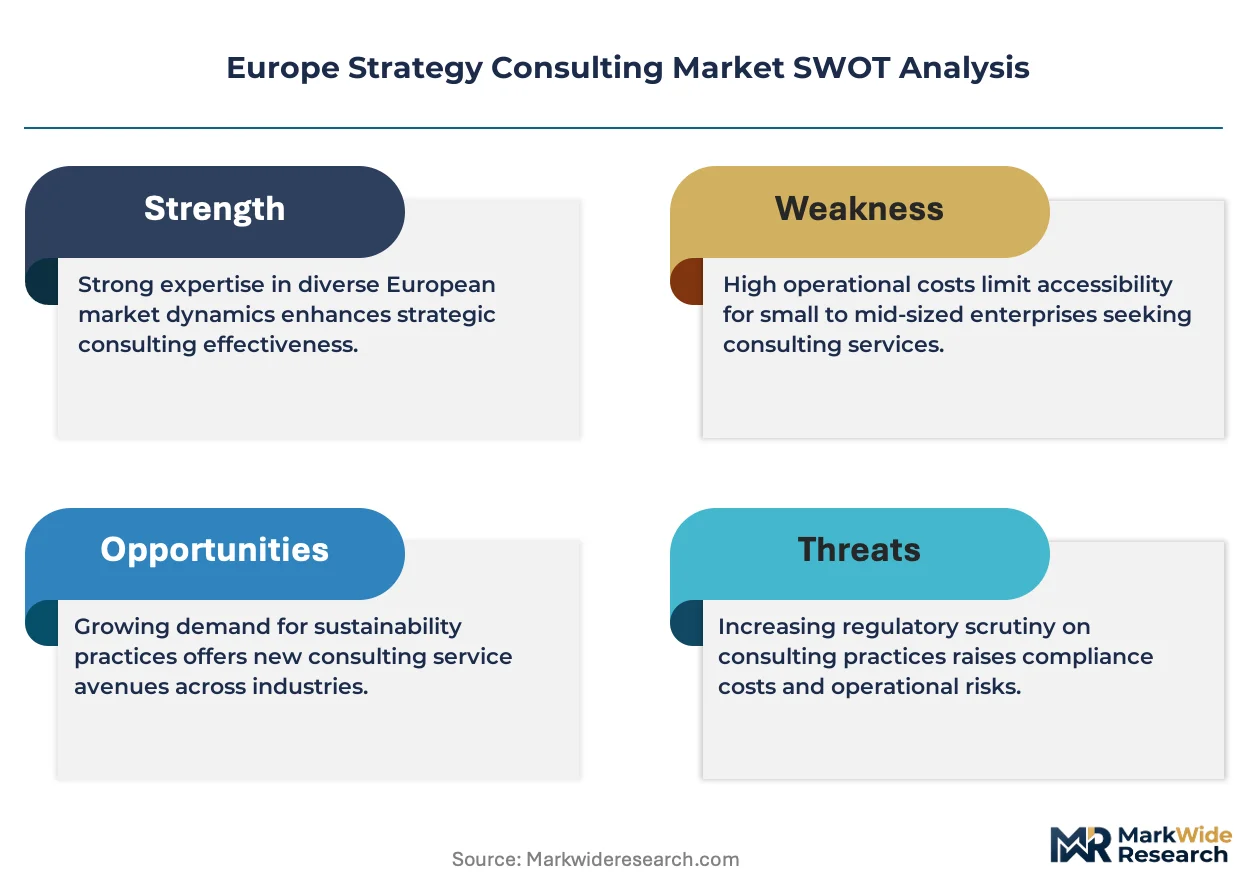
The Europe strategy consulting market rewards scarce capabilities in EU regulatory interpretation and sustainability data architecture, with advisory firms unable to staff these competencies facing margin compression and client defection.
For Market Incumbents: Insulate partner-level expertise in CSRD disclosure and ECB climate risk modeling through formal knowledge-codification systems and junior-consultant apprenticeship structures. Acquire boutique regulatory hybrids in Brussels and Berlin to preempt client unbundling of transformation programs into modular workstreams. Defend against procurement-cycle elongation in Southern Europe by embedding subscription analytics tools that reduce per-project fee exposure. For New Entrants and Emerging Players: Pursue white-space positioning in algorithmic governance advisory for EU AI Act risk-tier classification, where Brussels-based banks and Parisian health-tech clusters lack mature technical-legal hybrid capabilities. Target Poland and Czech manufacturing hubs for REACH chemical compliance and supply-base restructuring mandates, where German automotive suppliers extending eastward generate localization advisory demand. Lead with outcome-based pricing tied to regulatory approval milestones rather than time-and-materials structures. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among regulatory-response specialists with retainer relationships to Frankfurt financial institutions and Paris healthcare conglomerates navigating ECB and EMA deadlines. Long-term viability favors boutiques with narrow credential depth in sustainability analytics over generalist transformation practices facing AI-driven margin erosion. Watch for inflection signals in Brussels enforcement timelines that would trigger surge demand for compliance advisory capacity.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Capability Acquisition | Absorbing boutique EU Taxonomy specialists in Brussels accelerates CSRD service deployment for German DAX clients. |
| Central European Geographic Expansion | Establishing Warsaw and Prague delivery hubs captures battery supply-base localization advisory from German automotive OEMs. |
| AI Governance Practice Buildout | Recruiting technical-legal hybrid talent addresses EU AI Act algorithmic audit demand from Parisian health-tech clusters. |
| Knowledge Codification Investment | Formalizing partner expertise in sustainability analytics reduces deployment bottlenecks on specialized mandates. |
| Subscription Platform Launch | Self-service benchmarking tools penetrate cost-conscious mid-cap manufacturers in Poland and Hungary. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with strategy consulting partners, managing directors, corporate procurement officers at German industrial conglomerates, regulatory affairs leads at Frankfurt banking headquarters, and sustainability officers at French pharmaceutical groups. Secondary validation drew from ECB climate risk disclosure guidelines, EMA negotiation framework documents, EU AI Act regulatory texts, CSRD implementation guidance, and corporate advisory procurement databases. Bottom-up engagement-value estimates were triangulated against top-down market-size benchmarks.
Calibration across the analysis window employed scenario-weighted growth assumptions with explicit sensitivity testing for regulatory enforcement acceleration and AI-driven service automation. Segmentation dimensions modeled include service type, client scale, engagement architecture, and industry vertical with regulatory intensity scoring. CAGRs were derived from historical advisory spend patterns and forward-looking procurement intention surveys. Forecast inputs incorporated EU Green Deal compliance deadline schedules and ECB stress-testing protocol iteration timelines.
The forecast holds incumbent behavior within observed patterns; aggressive capability acquisitions by mid-tier consultancies or sudden regulatory enforcement acceleration by Brussels would shift outcomes beyond modeled ranges. Macroeconomic contraction in German manufacturing, delayed CSRD implementation timelines, or breakthrough generative AI automation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Risk Management and Compliance
Financial Risk Management Software Market
Risk Management and Compliance
Global Risk Management Software Market
Risk Management and Compliance
Artificial Intelligence and Regtech Market
Risk Management and Compliance
Asia-Pacific Compliance and Traceability Solutions Market
Risk Management and Compliance
Corporate Investigation Services Market
Risk Management and Compliance
Risk Analytics Market
Risk Management and Compliance
Stress Testing Solutions Market
Risk Management and Compliance
Stress Testing Services Market
Risk Management and Compliance
Pre Trade Risk Management Solution Market
Risk Management and Compliance
North America BFSI Biometrics Market
Risk Management and Compliance
Enterprise Risk Management Market
Risk Management and Compliance
China Enterprise Risk Management Market
Risk Management and Compliance
Risk Management Market
Risk Management and Compliance
Risk-Based Monitoring Software Market
Risk Management and Compliance
Global Asset Integrity Management Market
Risk Management and Compliance
Asset Liability Management (ALM) Solution Market