
 Risk-Based Monitoring Software Market | 2026-2036
Risk-Based Monitoring Software Market Size, Share, and Industry Trends Forecast 2026-2036
Risk-Based Monitoring Software Market Analysis
Biotechnology firms is recalibrating their clinical trial oversight strategies, intensifying demand for adaptive monitoring platforms. Oracle leverages its enterprise cloud infrastructure to anchor large-scale pharma deployments across multiple continents. Medidata Solutions sustains technology leadership through specialized data capture and analytics integration for complex trials.
Risk-based monitoring software comprises configurable platforms that apply statistical algorithms and centralized data review to identify protocol deviations, safety signals, and site-level risks in clinical research. These systems aggregate electronic data capture, laboratory results, and adverse event reports to enable targeted on-site monitoring rather than universal 100% source data verification. Cloud-based deployment leads adoption among mid-size sponsors seeking scalable infrastructure without capital expenditure, while AI-driven analytics represents the fastest-expanding technology layer as sponsors automate signal detection. Data management solutions occupy the mature core of the solution stack, whereas analytics tools command expanding margin pools as predictive capabilities deepen.
FDA guidance on risk-based monitoring and ICH E6(R2) quality standards shape product requirements and sponsor procurement criteria across North America and Europe. EMA's clinical trial regulation and GDPR data governance rules further constrain platform architecture and cross-border data flows for European deployments. Stakeholders must weigh regulatory divergence between FDA adaptive trial frameworks and emerging EU clinical trial information system mandates when selecting platform architectures.
Market Dynamics
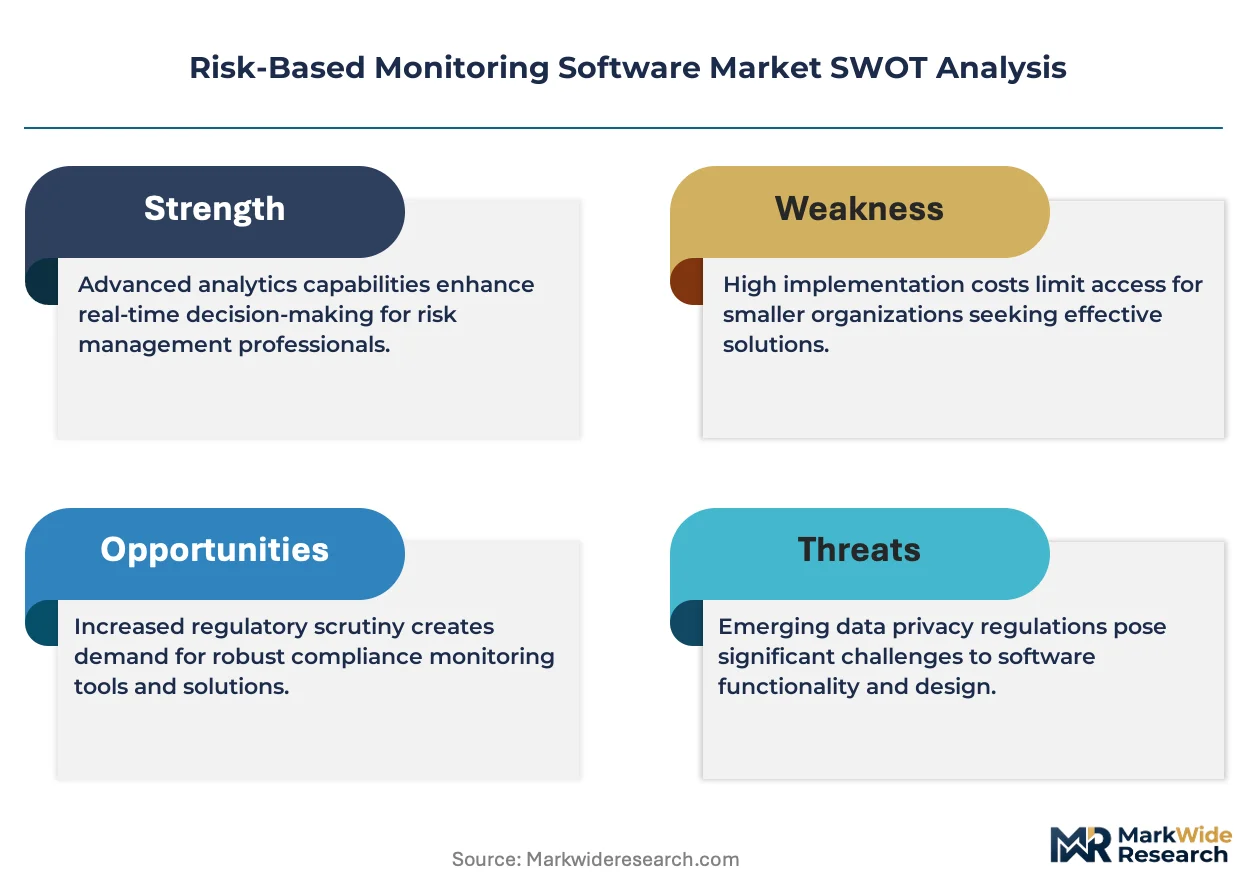
The FDA's 2013 risk-based monitoring guidance and ICH E6(R2) quality standards have permanently altered how sponsors allocate oversight resources, compressing traditional source data verification while elevating statistical algorithms to core compliance infrastructure.
Growth Catalysts
- Adaptive Trial Frameworks:FDA's guidance on adaptive designs permits protocol modifications mid-study, requiring real-time risk detection platforms that flag deviations without halting enrollment.
- Cloud Infrastructure Maturation:Mid-size biotechnology sponsors now access enterprise-grade monitoring capabilities through SaaS models, eliminating capital barriers that previously constrained adoption.
- GCP Inspection Modernization:EMA's updated good clinical practice standards explicitly recognize centralized monitoring as equivalent to on-site source verification for low-risk data points.
Market Restraints
- Cross-Border Data Architecture:GDPR's data localization requirements and Schrems II rulings fragment cloud deployments, forcing sponsors to maintain separate European instances or accept compliance uncertainty.
- Specialized Talent Scarcity:Clinical data scientists combining biostatistics expertise with regulatory knowledge command premium compensation, constraining platform vendor expansion timelines.
- Legacy System Interoperability:Proprietary electronic data capture formats from established vendors resist standardized API integration, extending implementation cycles for multi-platform environments.
Strategic Opportunities
- Decentralized Trial Expansion:Direct-to-patient data collection through wearable devices and telemedicine visits creates demand for risk algorithms that monitor compliance without physical site presence.
- Artificial Intelligence Convergence:Machine learning models trained on historical protocol deviation patterns enable predictive site selection, reducing monitoring resource allocation to high-risk locations.
- Emerging Market Penetration:India's CDSCO and China's NMPA are harmonizing inspection standards with ICH guidelines, opening procurement pathways for platforms previously confined to North American and European sponsors.
Industry Challenges
- Validation Documentation Burden:FDA 21 CFR Part 11 and EMA Annex 11 requirements for computerized system validation demand extensive documentation that extends implementation timelines and consumes technical resources.
- Multi-Stakeholder Data Governance:Contract research organizations, academic medical centers, and sponsor organizations maintain conflicting data ownership policies, complicating centralized monitoring agreements and access provisioning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Risk-Based Monitoring Software Market |
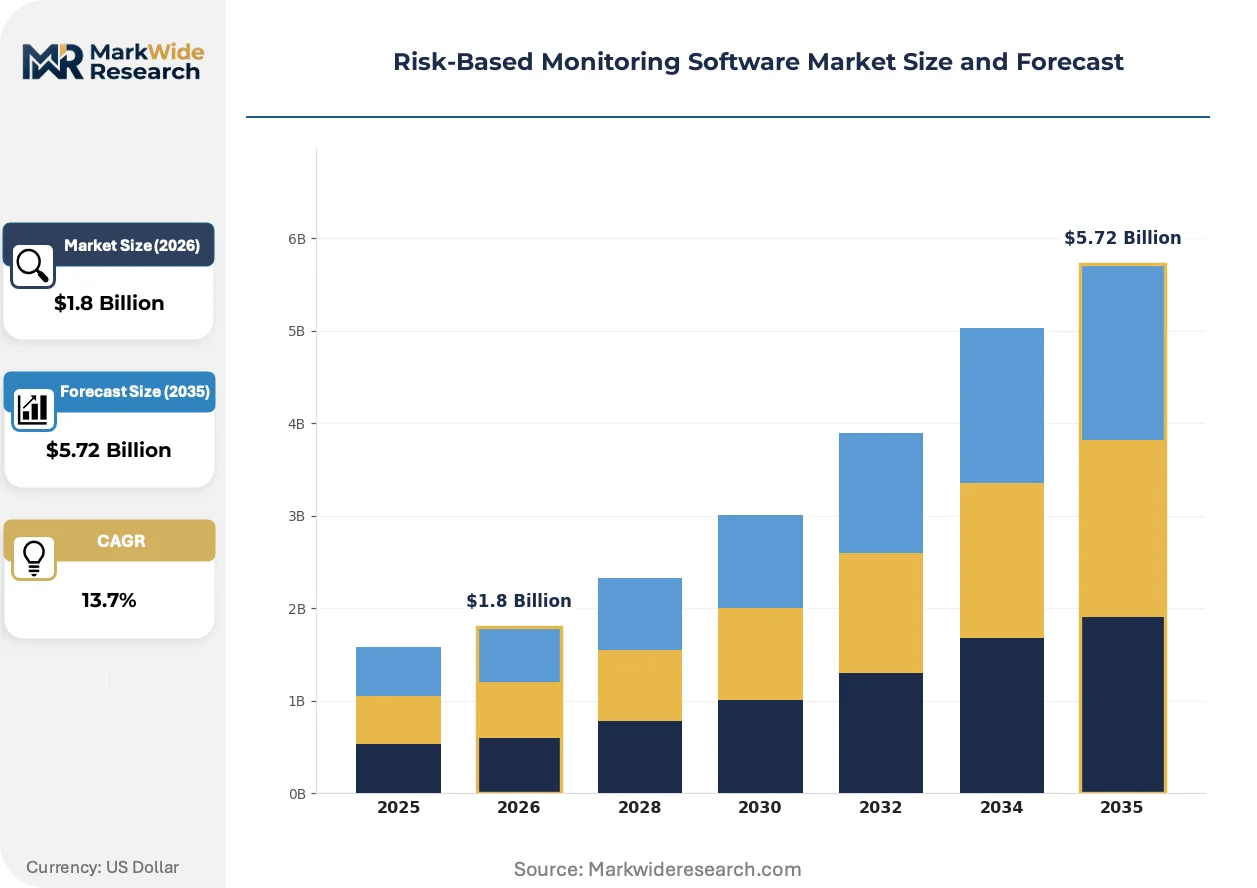
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $5.72 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premises, Cloud-Based, Hybrid, Full SaaS End User: Pharmaceutical Companies, Biotechnology Firms, Clinical Research Organizations, Medical Device Manufacturers Solution: Data Management, Analytics Tools, Risk Assessment, Reporting Modules Technology: AI-Driven Analytics, Machine Learning, Data Visualization, Workflow Automation |
| Companies Covered | Oracle, Medidata Solutions, Parexel International, Veeva Systems, IBM Corporation, IQVIA, CluePoints, Saama Technologies, Signant Health, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Risk-Based Monitoring Software Market Emerging Trajectories
Artificial intelligence and distributed data architectures are restructuring how clinical trial oversight functions are performed, with automation displacing manual review tasks and cloud platforms enabling sponsor oversight across geographically dispersed research sites.
Statistical monitoring algorithms is modularizing into configurable components that sponsors integrate with existing electronic data capture systems rather than replacing entire technology stacks. Large pharmaceutical organizations deploy these modules through containerized architectures, allowing site risk scoring to operate alongside legacy infrastructure. This modularization is compressing vendor switching costs and enabling best-of-breed procurement strategies that were previously impractical under monolithic platform models.
EMA's clinical trial information system mandates under the EU Clinical Trials Regulation are forcing platform architecture redesigns for sponsors conducting transatlantic studies. The regulation's requirement for structured data submission to a centralized EU portal conflicts with FDA's more flexible eCTD framework, creating compliance engineering overhead. European biotechnology sponsors are responding by demanding dual-validation capabilities from platform vendors, while North American sponsors with limited EU exposure delay feature investment.
Site selection criteria now weight historical compliance data more heavily than geographic convenience or patient access, compressing the traditional site qualification timeline. Contract research organizations are unbundling monitoring services from full-service contracts, allowing sponsors to purchase risk-based oversight as a standalone capability. This unbundling is most visible in oncology trials, where adaptive protocols require rapid site performance assessment that legacy full-service models cannot deliver.
Risk-Based Monitoring Software Market Segmentation
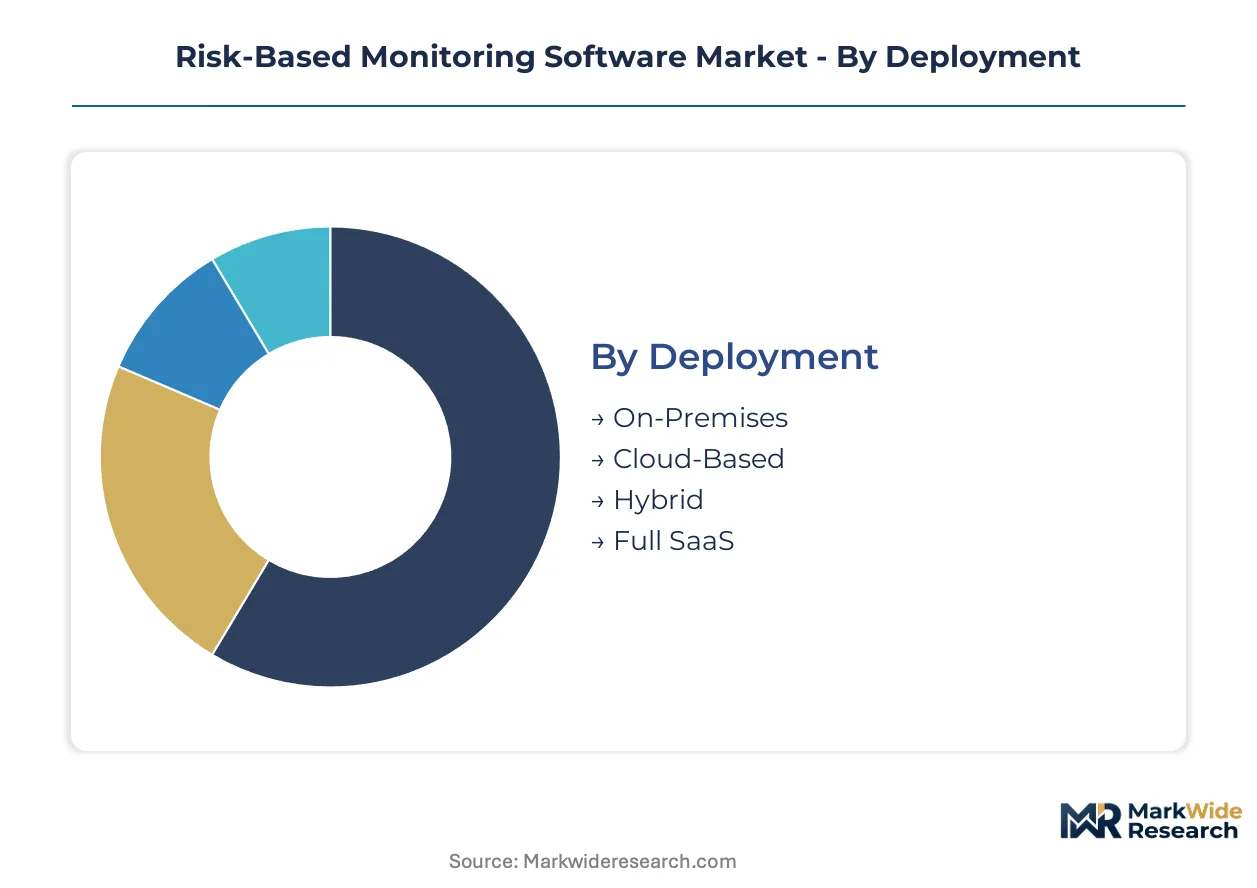
Risk-based monitoring software segments reflect divergent buyer capabilities and regulatory postures. Deployment mode determines capital commitment and validation burden, while end-user type shapes feature prioritization and integration complexity.
Deployment:
Cloud infrastructure commands volume leadership while hybrid configurations capture premium pricing for complex multi-study environments.
- On-Premises:Installed within sponsor data centers with direct hardware control. Large pharmaceutical organizations in Germany and Switzerland maintain these deployments for studies involving sensitive genetic data where GDPR localization requirements are non-negotiable.
- Cloud-Based:Hosted on vendor-managed infrastructure with elastic scaling. Mid-size biotechnology sponsors across Massachusetts and California access enterprise-grade capabilities without capital expenditure, compressing procurement cycles from quarters to weeks.
- Hybrid:Combines on-premises core systems with cloud burst capacity for peak enrollment periods. Contract research organizations running simultaneous oncology trials across multiple continents deploy this architecture to balance data sovereignty with computational elasticity.
- Full SaaS:Complete platform delivery through subscription models with continuous feature updates. Emerging biotechnology firms in India's Bengaluru and Hyderabad clusters favor this option for rapid study startup without dedicated IT staff.
Today's leader: Cloud-Based. Tomorrow's challenger: Hybrid.
End User:
Pharmaceutical sponsors drive standardization while biotechnology firms push innovation boundaries on analytics integration.
- Pharmaceutical Companies:Global trial sponsors with established quality management systems. FDA inspection history and prior 483 observations shape their platform selection criteria, favoring vendors with documented Part 11 compliance packages.
- Biotechnology Firms:Venture-backed developers of novel therapeutics with limited quality infrastructure. These organizations prioritize rapid deployment and adaptive protocol support over extensive customization, concentrating demand in Boston and San Francisco metro areas.
- Clinical Research Organizations:Full-service and functional providers managing outsourced trials. EMA's updated GCP standards recognizing centralized monitoring equivalence have accelerated their platform investments across European operations.
- Medical Device Manufacturers:Developers of diagnostics and therapeutic devices with distinct adverse event reporting requirements. Their demand concentrates among cardiovascular and orthopedic device sponsors navigating FDA's unique device identification mandates.
Pharmaceutical Companies anchor current procurement volume. Biotechnology Firms are gaining share fastest as venture funding flows into adaptive trial designs.
Solution:
Mature data management functions subsidize analytics development as predictive capabilities command expanding margin pools.
- Data Management:Core electronic data capture integration and query resolution workflows. This segment represents the installed base majority, with sponsors in Japan's Kanto region maintaining long-term contracts for stable study operations.
- Analytics Tools:Statistical algorithms and predictive modeling for site risk scoring. Machine learning integration is displacing rule-based flagging systems among sponsors running complex immuno-oncology protocols with frequent protocol amendments.
- Risk Assessment:Centralized monitoring dashboards and automated signal detection. FDA's 2013 guidance acceptance has normalized these capabilities as standard infrastructure rather than premium add-ons.
- Reporting Modules:Regulatory submission packages and investigator communication portals. EMA's clinical trial information system mandates are forcing architecture redesigns for transatlantic study sponsors.
Data Management holds current revenue concentration. Analytics Tools show the steepest expansion trajectory as AI integration deepens.
Technology:
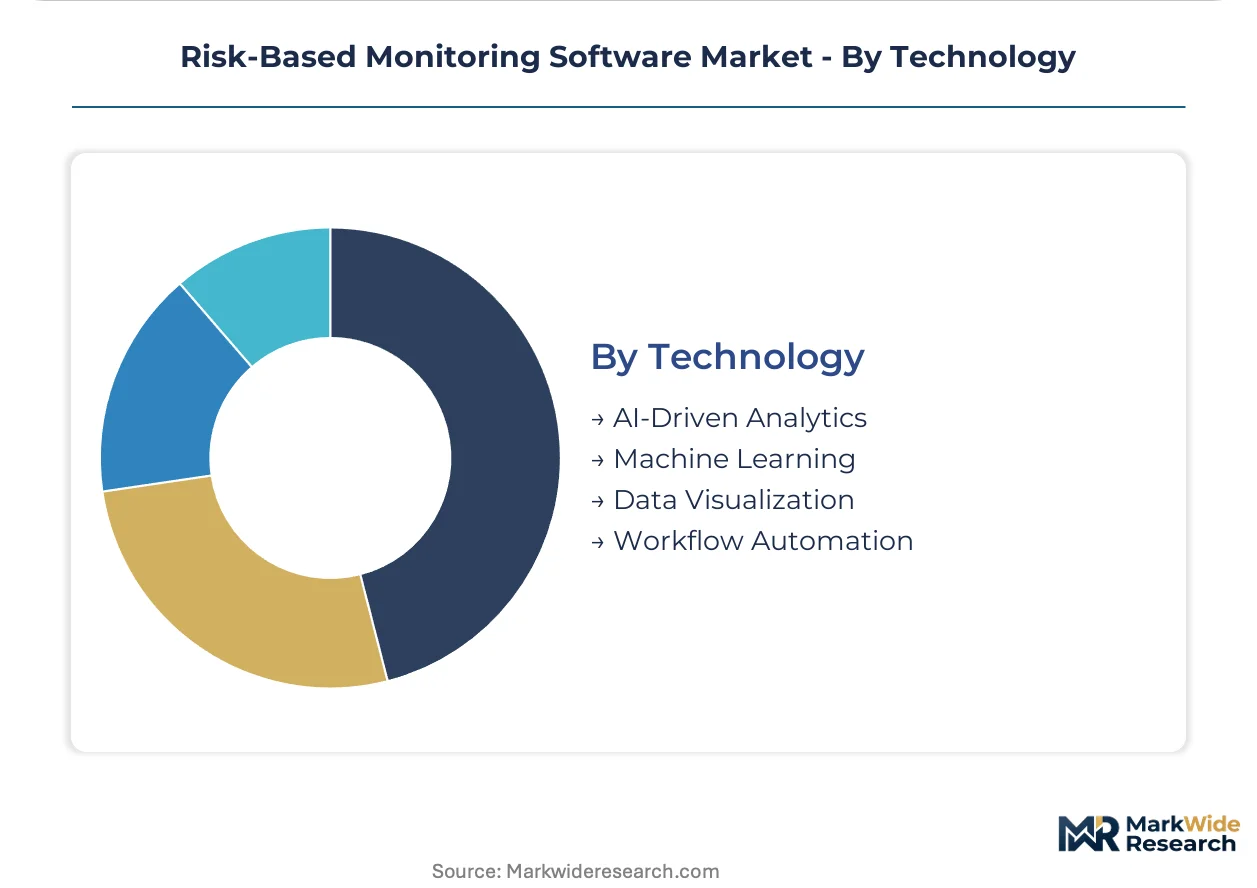
Workflow automation delivers immediate productivity gains while AI layers promise transformational oversight efficiency.
- AI-Driven Analytics:Neural network models trained on historical protocol deviation patterns. These systems enable predictive site selection, reducing monitoring allocation to high-risk locations in multisite cardiovascular outcomes trials.
- Machine Learning:Supervised learning algorithms for anomaly detection in laboratory and safety data. China's NMPA harmonization with ICH guidelines has opened procurement pathways for these capabilities among domestic sponsors.
- Data Visualization:Interactive dashboards and geospatial site performance mapping. Real-time enrollment tracking across decentralized trial networks depends on these interfaces for sponsor oversight without physical site presence.
- Workflow Automation:Robotic process automation for query generation and regulatory correspondence. This technology delivers immediate productivity returns with lower validation burden than AI systems, appealing to quality-constrained mid-market sponsors.
Workflow Automation dominates near-term deployment. AI-Driven Analytics represents the emerging technology layer with highest strategic priority.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping platform deployment patterns as sponsors migrate monitoring infrastructure toward jurisdictions with clearer validation pathways and lower compliance documentation burdens. The United States maintains the steepest cost-of-compliance gradient, while emerging clusters in India and China attract mid-size sponsors seeking faster study startup timelines.
United States
FDA's 2013 risk-based monitoring guidance and ICH E6(R2) adoption created the foundational compliance framework for centralized oversight platforms. Massachusetts and California biotechnology clusters concentrate demand for adaptive trial support, with Boston-area sponsors driving fastest procurement cycles for cloud-native deployments.
Germany
German pharmaceutical sponsors prioritize GDPR-compliant data architectures for multi-site cardiovascular trials requiring strict genetic data localization. Bavaria's Munich biotech corridor and North Rhine-Westphalia's industrial pharma base sustain demand for hybrid cloud configurations balancing sovereignty with computational scale.
United Kingdom
Post-Brexit regulatory divergence from EMA frameworks has compressed UK-based sponsors' platform procurement timelines as they navigate dual-validation requirements. London's contract research organization density and Cambridge's biotech concentration generate concentrated demand for analytics-integrated monitoring modules.
India
CDSCO harmonization with ICH GCP standards and cost-competitive clinical operations attract North American sponsors seeking offshore monitoring capabilities. Bengaluru and Hyderabad technology corridors host emerging domestic biotechnology firms adopting full SaaS models for rapid study initiation without dedicated IT infrastructure.
China
NMPA alignment with ICH guidelines and domestic innovation policy acceleration are opening procurement pathways for risk-based platforms previously confined to Western sponsors. Shanghai and Beijing biotech clusters demonstrate fastest adoption velocity for AI-driven site risk scoring in immuno-oncology protocols.
Risk-Based Monitoring Software Market Vendor Landscape
Portfolio diversification dominates the current landscape as legacy data management vendors extend into analytics layers and specialized monitoring platforms broaden into full clinical trial infrastructure. The vendor base clusters around three strategic archetypes: enterprise software conglomerates with cloud infrastructure depth, clinical research specialists with regulatory validation expertise, and emerging AI-native platforms with predictive analytics capabilities. Horizontal consolidation through technology licensing and vertical integration into data capture systems represent the most visible competitive vectors.
Within the enterprise infrastructure tier, Oracle and IBM Corporation anchor large-scale deployments through existing cloud relationships and validation documentation libraries. Medidata Solutions occupies a specialized position exemplifying the clinical research pure-play archetype, while IQVIA represents the contract research organization convergence model integrating software with service delivery. These three patterns illustrate how competitive positioning stratifies across infrastructure depth, regulatory specialization, and service integration intensity.
| Leading Market Players |
|---|
| Oracle |
| Medidata Solutions |
| Parexel International |
| Veeva Systems |
| IBM Corporation |
| IQVIA |
| CluePoints |
| Saama Technologies |
| Signant Health |
| Others |
Supply Flow & Price Mechanics
Cloud infrastructure cost indices from hyperscale providers cascade through vendor pricing tiers, compressing margins for mid-market SaaS offerings while amplifying differentiation premiums for AI-augmented platforms. This cost transmission reshapes procurement patterns as biotechnology sponsors trade capital expenditure avoidance against long-term subscription commitments.
Pricing Analysis
Direct-to-sponsor subscription models dominate, bypassing distributor markups that characterized legacy enterprise software channels. Three-tier pricing structure across premium, standard, and economy levels segments by validation documentation depth and AI integration intensity. Pricing pressure stems from open-source statistical libraries commoditizing baseline risk-scoring algorithms. Mid-size biotechnology firms exhibit highest price sensitivity, prioritizing rapid deployment over customization depth.
Supply Chain Analysis
Freight costs for on-premises hardware deployments to German and Swiss data centers inflate total cost of ownership for sovereignty-compliant configurations. Software development concentrates in the United States, India, and Ireland, with Bengaluru and Hyderabad engineering centers feeding platform maintenance operations. Cloud compute capacity draws from hyperscale regions in Virginia, Frankfurt, and Singapore. Single-source vulnerability attaches to proprietary electronic data capture API specifications. Distribution runs through vendor direct sales organizations supplemented by clinical research organization partnership channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Risk-Based Monitoring Software Market compounds steadily as regulatory harmonization across FDA, EMA, and NMPA frameworks mandates platform adoption for trial compliance. This structural demand driver insulates revenue trajectories from cyclical pharmaceutical R&D budget fluctuations.
For Market Incumbents: Extend AI-driven analytics modules through containerized architectures that interoperate with legacy electronic data capture systems, neutralizing substitute threats from pure-play monitoring startups. Deepen vertical integration into data capture infrastructure to control API specifications that determine switching costs. Prioritize dual-validation capabilities for EMA clinical trial information system and FDA eCTD framework convergence.
For New Entrants and Emerging Players: Launch via full SaaS delivery models targeting India's domestic biotechnology corridor, where CDSCO harmonization with ICH guidelines creates procurement pathways without entrenched vendor relationships. Concentrate development resources on predictive site selection algorithms for immuno-oncology protocols, the fastest-expanding therapeutic application. Penetrate through channel partnerships with Bengaluru-based contract research organizations seeking unbundled monitoring capabilities.
For Investors and Strategic Acquirers: Asymmetric upside sits with AI-native platforms possessing training datasets from historical protocol deviations across multiple therapeutic areas. Long-term viability hinges on regulatory validation documentation libraries that compress implementation timelines for new sponsor deployments. Monitor NMPA inspection standard harmonization progress as the inflection signal for China market entry viability.
| Strategic Initiative | Industry Significance |
|---|---|
| AI-Driven Analytics Integration | Machine learning modules trained on FDA 483 observation patterns automate site risk scoring for adaptive trials. |
| Dual-Validation Architecture Development | Parallel EMA CTIS and FDA eCTD compliance capabilities capture transatlantic sponsor procurement budgets. |
| Hybrid Cloud Deployment Expansion | GDPR-compliant on-premises cores with cloud burst capacity address German genetic data localization mandates. |
| Contract Research Organization Partnership | Unbundled monitoring service agreements with IQVIA and Parexel accelerate platform adoption in oncology trials. |
| Emerging Market Regulatory Harmonization | CDSCO and NMPA alignment with ICH GCP standards opens procurement pathways in India and China. |
Methodological Framework
Bottom-up biotechnology sponsor modeling reconciled against top-down cloud infrastructure deployment tracking forms the analytical core of this study. Primary interviews with clinical data scientists, regulatory affairs directors, contract research organization procurement leads, and hospital site coordinators informed platform adoption drivers. Secondary validation drew from FDA guidance documents, EMA clinical trial regulation filings, ClinicalTrials.gov protocol records, and hyperscaler capex disclosures. Triangulation across these sources anchored segmentation-specific demand estimates.
Historical trendline analysis of electronic data capture system replacements and centralized monitoring adoption rates established baseline growth patterns across the projection horizon. The forecast framework models deployment mode, end-user organization size, solution component mix, and regional regulatory cluster as primary segmentation dimensions. CAGRs derive from sponsor IT budget elasticity coefficients and regulatory compliance deadline clustering. AI integration intensity and decentralized trial protocol frequency serve as industry-specific forecast modifiers.
Forecast precision tightens around the base case; tail outcomes carry wider variance under regulatory divergence scenarios or Schrems II data localization enforcement shifts. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Risk Management and Compliance
Europe Strategy Consulting Market
Risk Management and Compliance
Global Management Decision Market
Risk Management and Compliance
Travel Risk Management Services Market
Risk Management and Compliance
Asia-Pacific Compliance and Traceability Solutions Market
Risk Management and Compliance
Global Backstop Netting Systems Market
Risk Management and Compliance
Europe BFSI Biometrics Market
Risk Management and Compliance
Global Liquidity Asset Liability Management Solutions Market
Risk Management and Compliance
Stress Testing Solutions Market
Risk Management and Compliance
Asia-Pacific Sustainable Finance Market
Risk Management and Compliance
Southeast Asia Credit and Risk Management Market
Risk Management and Compliance
Anti-Money Laundering (AML) Market
Risk Management and Compliance
Digital Risk Management Market
Risk Management and Compliance
Enterprise Governance, Risk, and Compliance (Egrc) Market
Risk Management and Compliance
Global Compliance Management Software Market
Risk Management and Compliance
United States Governance, Risk and Compliance Platform Market
Risk Management and Compliance
Fraud Detection and Prevention (FDP) Market