
 North America BFSI Biometrics Market | 2026-2036
North America BFSI Biometrics Market Size, Share, and Industry Trends Forecast 2026-2036
North America BFSI Biometrics Market Insights
FFIEC authentication guidance is broadening compliance costs for smaller financial institutions across the United States and Canada. IDEMIA leverages its government credentialing heritage to anchor high-assurance banking contracts. NEC Corporation competes through deep specialization in iris recognition for vault and data center access. Thales Group extends its defense-grade security portfolio into cloud-based biometric platforms for investment firms.
North America BFSI biometrics encompasses fingerprint, iris, facial, and voice recognition systems engineered for financial identity verification, typically operating with false acceptance rates below 0.001% and liveness detection to prevent spoofing. These systems authenticate customers, secure transactions, and control physical and logical access across banking infrastructure. Fingerprint technology dominates current deployment volumes due to mature sensor economics and consumer familiarity, while facial recognition captures expanding share through smartphone-integrated onboarding workflows. Cloud-based deployment is accelerating fastest as credit unions and regional banks shed capital-intensive on-premise infrastructure for subscription identity platforms.
US banking regulators including the FFIEC and OCC mandate multi-factor authentication for electronic banking access, directly shaping product requirements for liveness detection and template encryption. Canada's Office of the Superintendent of Financial Institutions and FINTRAC enforce parallel anti-money-laundering identity standards that sustain cross-border vendor qualification demands. Stakeholders must monitor how state-level biometric privacy laws in Illinois, Texas, and California fragment compliance obligations and influence procurement specifications for consent management and data retention.
Market Dynamics
Real-time payment infrastructure mandates from US banking regulators are compressing authentication timelines and forcing biometric vendors to embed liveness detection directly into transaction flows rather than treating identity verification as a separate onboarding step.
Growth Catalysts
- FFIEC Multi-Factor Mandates:Federal guidance requiring stepped-up authentication for high-risk transactions compels regional banks and credit unions to upgrade legacy password systems with biometric overlays.
- Canada's FINTRAC Identity Standards:Anti-money-laundering rule tightening sustains cross-border procurement of high-assurance biometric platforms that satisfy both US and Canadian compliance audits.
- Smartphone-Native Facial Recognition:Consumer familiarity with device-integrated face unlock lowers adoption friction for mobile banking onboarding workflows across the Northeast corridor.
Market Restraints
- Silicon Supply Concentration:Fingerprint sensor fabrication depends on concentrated East Asian foundry capacity, exposing North American integrators to geopolitical supply shocks.
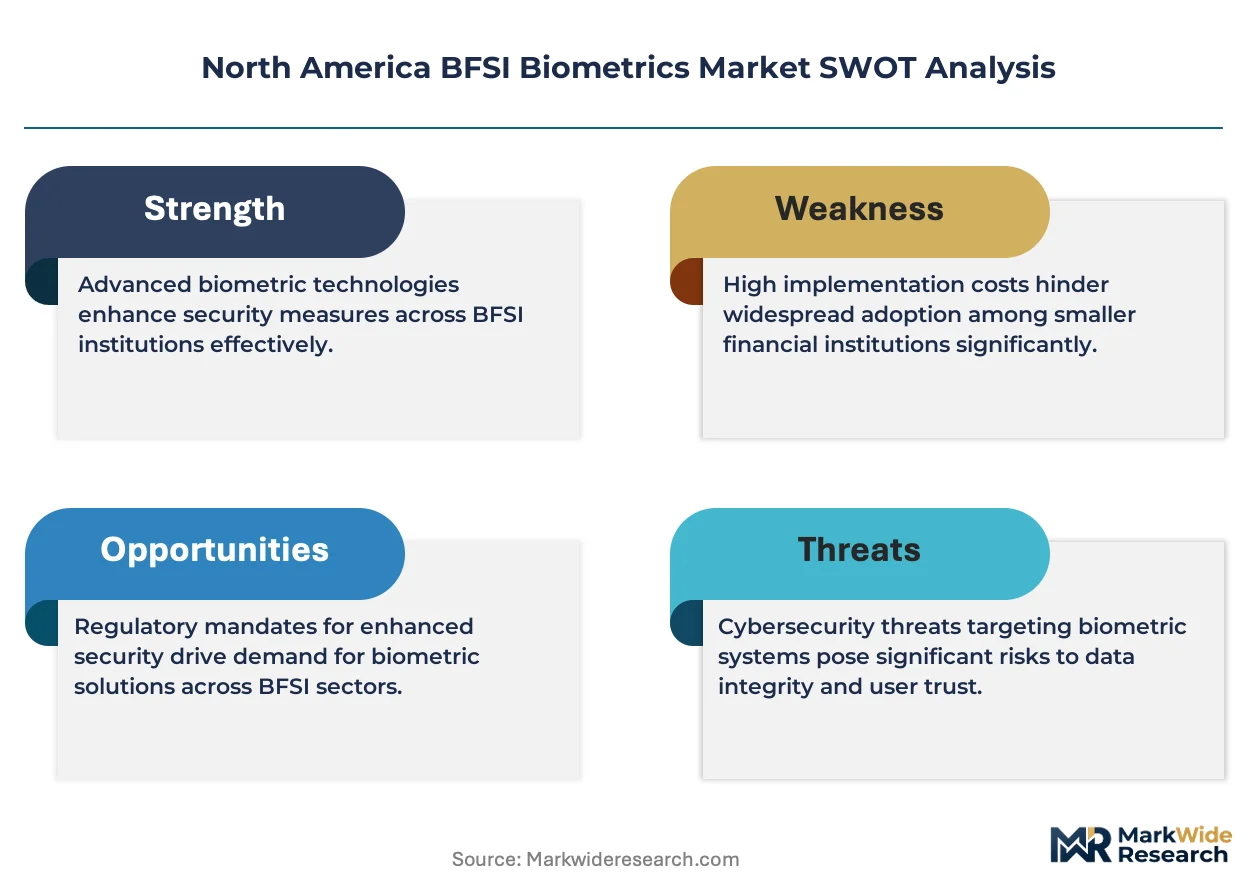
- State-Level Privacy Fragmentation:Illinois BIPA, Texas CUBI, and California CCPA create conflicting consent and retention obligations that inflate legal review costs for multi-state deployments.
- Template Storage Liability:Irreversible biometric data breaches expose financial institutions to class-action exposure that property-casualty insurers increasingly exclude from cyber policies.
Strategic Opportunities
- Mexico Nearshoring Banking:US-Mexico-Canada Agreement financial services provisions open procurement pathways for biometric vendors to serve Mexican retail banking expansion.
- Voice Recognition for Call Centers:Passive authentication during customer service interactions reduces average handle time while satisfying OCC consumer protection scrutiny.
- Cloud Template Federation:Interoperable biometric credentialing across credit union networks enables shared infrastructure investment that individual institutions cannot fund independently.
Industry Challenges
- Algorithm Bias Audit Expertise:NIST testing protocols for demographic performance differentials require specialized data science talent that regional banks struggle to recruit and retain.
- Core Banking Integration Complexity:Biometric middleware must interface with decades-old COBOL-based transaction processing systems without disrupting sub-second authorization latency requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America BFSI Biometrics Market |
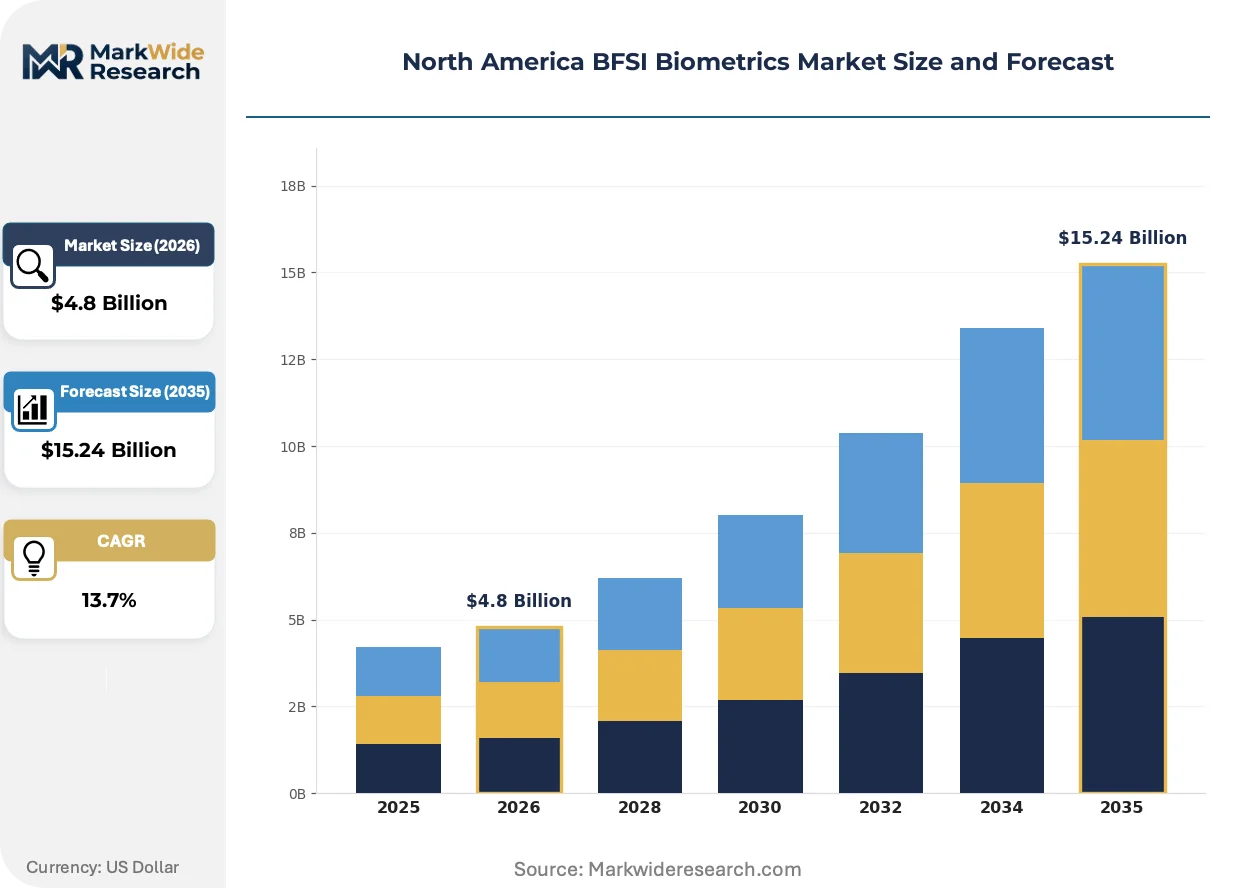
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $15.24 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Fingerprint, Iris Recognition, Facial Recognition, Voice Recognition Application: Identification, Authentication, Fraud Prevention, Access Control End User: Banks, Credit Unions, Insurance Companies, Investment Firms Deployment: On-Premise, Cloud-Based, Hybrid, Mobile Solutions |
| Companies Covered | Thales Group, Fujitsu, Veridium, Aware, Inc., AllTrust Networks, NEC Corporation, IDEMIA, HID Global, Fingerprint Cards AB, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America BFSI Biometrics Market Trends and Innovations
Behavioral biometrics and continuous authentication are displacing static one-time verification events, embedding identity assurance throughout the entire customer session rather than isolating it to login moments.
Passive behavioral biometrics analyzing keystroke dynamics, mouse movements, and touchscreen pressure patterns is converging with transaction monitoring systems to enable frictionless risk scoring without explicit user action. Mid-tier investment firms are piloting these overlays for high-net-worth client portals. This convergence is compressing the boundary between fraud prevention and identity management into unified risk engines.
The OCC's heightened scrutiny of third-party fintech partnerships is forcing banks to demand SOC 2 Type II and ISO 27001 certifications from biometric SaaS providers before contract execution. Procurement teams now embed audit rights and data localization clauses into standard RFP templates. Community banks in the Midwest are responding by favoring domestic-hosted identity platforms over offshore alternatives.
Credit unions are unbundling biometric implementation from core banking vendor relationships, directly contracting specialized identity firms rather than accepting packaged modules from legacy core providers. This disintermediation fragments purchasing authority between CIOs and CISOs. The shift is most visible among institutions with assets between $500 million and $5 billion seeking differentiation from larger competitors.
North America BFSI Biometrics Market Segmentation
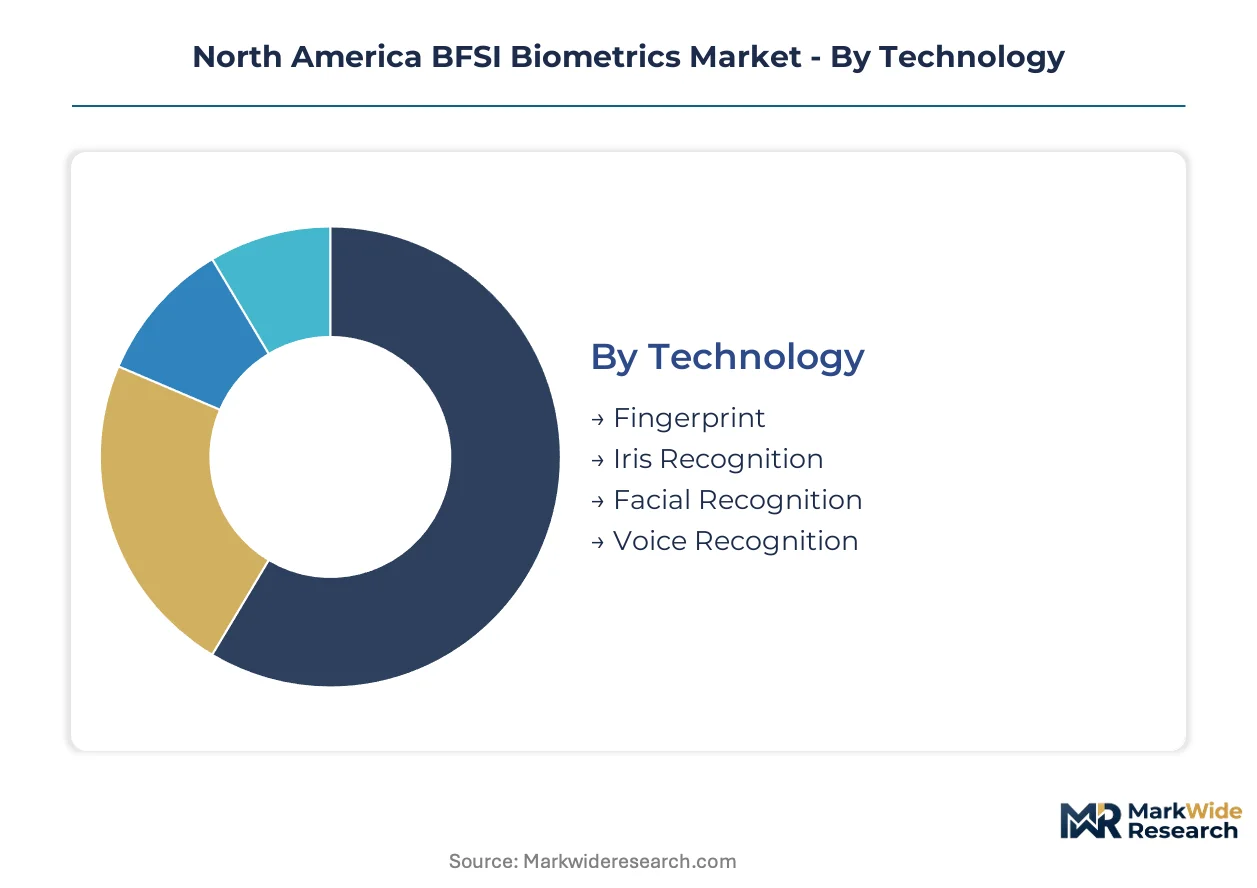
Biometric segmentation in North American financial services reflects divergent risk appetites across physical and digital channels. Technology choices cascade through deployment architecture and compliance obligations, while application priorities shift with real-time payment mandates and fraud vectors.
Technology:
Sensor economics and liveness detection standards differentiate biometric modalities competing for banking infrastructure slots.
- Facial Recognition:Smartphone-native face unlock protocols integrate directly with mobile banking onboarding workflows. Northeast corridor financial centers prioritize this modality for remote account origination where FFIEC guidance demands stepped-up identity assurance without branch visits.
- Fingerprint:Capacitive and ultrasonic sensors dominate branch-based authentication with false acceptance rates below 0.001%. Mature foundry economics sustain volume deployment across credit union networks seeking capital-efficient hardware refresh cycles.
- Iris Recognition:NEC Corporation specializes in vault and data center physical access applications requiring contactless high-assurance verification.
- Voice Recognition:Passive authentication during call center interactions reduces average handle time while satisfying OCC consumer protection scrutiny.
Fingerprint leads on scale; facial recognition leads on momentum.
Application:
Functional use cases segment by whether identity verification occurs at session initiation or persists throughout transaction flows.
- Authentication:Multi-factor biometric overlays replace legacy password systems for electronic banking access, with liveness detection embedded directly into transaction flows rather than isolated onboarding steps. Regional banks allocate procurement budget here first.
- Fraud Prevention:Behavioral biometrics analyzing keystroke dynamics and touchscreen pressure patterns converge with transaction monitoring for frictionless risk scoring. Mid-tier investment firms pilot these overlays for high-net-worth client portals.
- Identification:One-to-many matching for watchlist screening and account recovery sustains demand from institutions under FINTRAC anti-money-laundering audit pressure.
- Access Control:Physical and logical perimeter security for data centers and vault facilities employs iris and fingerprint modalities with defense-grade encryption standards.
Authentication commands the largest deployment base; fraud prevention exhibits the steepest expansion trajectory.
End User:
Institutional scale and regulatory exposure shape biometric procurement specifications across financial subsectors.
- Banks:Tier-one institutions demand SOC 2 Type II and ISO 27001 certifications from biometric SaaS providers, embedding audit rights and data localization clauses into standard RFP templates. Domestic-hosted identity platforms win preference over offshore alternatives.
- Credit Unions:Institutions with assets between $500 million and $5 billion unbundle biometric implementation from core banking vendor relationships, directly contracting specialized identity firms rather than accepting packaged modules from legacy core providers.
- Insurance Companies:Claims verification and beneficiary authentication drive demand for high-assurance modalities with template encryption meeting state-level privacy fragmentation requirements.
- Investment Firms:Cloud-based biometric platforms from defense-grade security portfolios serve high-frequency trading infrastructure and client portal access.
Banks anchor procurement volume; credit unions are climbing the fastest in deployment velocity.
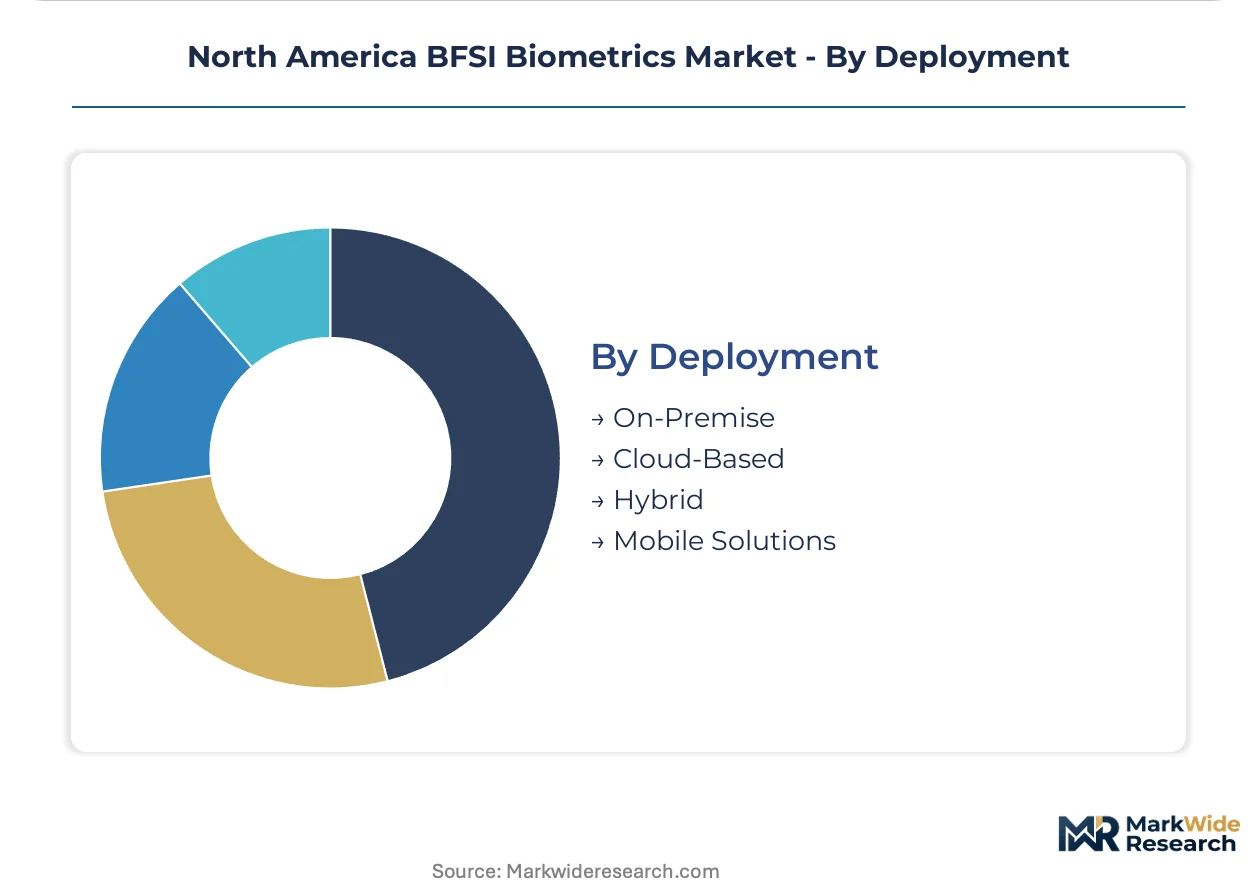
Deployment:
Infrastructure ownership models segment by capital intensity tolerance and core banking integration complexity.
- Cloud-Based:Subscription identity platforms enable credit unions and regional banks to shed capital-intensive on-premise infrastructure. Interoperable biometric credentialing across credit union networks enables shared infrastructure investment that individual institutions cannot fund independently.
- Hybrid:Template storage on-premise with algorithm processing in cloud environments addresses template storage liability concerns that property-casualty insurers increasingly exclude from cyber policies.
- On-Premise:Legacy COBOL-based transaction processing systems at major money-center banks require biometric middleware without disrupting sub-second authorization latency requirements.
- Mobile Solutions:Device-integrated biometric APIs leverage consumer familiarity with smartphone-native authentication for retail banking applications.
On-premise retains incumbent footprint; cloud-based is gaining share fastest as procurement authority shifts from CIOs to CISOs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Biometric engineering talent concentrates in the US Northeast corridor, anchoring product development for financial identity verification systems. Canadian compliance expertise sustains cross-border platform qualification. Mexican retail banking expansion draws vendor investment under USMCA provisions.
United States
FFIEC multi-factor authentication mandates compel regional banks and credit unions to upgrade legacy password systems. The Federal Reserve's real-time payment infrastructure elevates identity verification standards nationwide. The Boston-to-Washington DC financial corridor hosts the densest concentration of biometric deployment for branch authentication and mobile onboarding workflows.
Canada
FINTRAC anti-money-laundering rule tightening sustains procurement of high-assurance biometric platforms. The Office of the Superintendent of Financial Institutions enforces identity standards that parallel US regulatory frameworks. Toronto's financial district anchors cross-border vendor qualification activity serving both Canadian and US compliance audits.
Mexico
US-Mexico-Canada Agreement financial services provisions open procurement pathways for biometric vendors. Mexican retail banking expansion generates demand for smartphone-native authentication solutions. Mexico City Metro and Nuevo León industrial centers concentrate deployment of cloud-based identity platforms for nearshoring banking operations.
North America BFSI Biometrics Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across the North American BFSI biometrics landscape. Market structure tilts toward consolidation as defense-grade security portfolios extend into financial services. Three archetypes dominate: government-credentialing heritage firms, iris recognition specialists, and cloud-native identity platforms. Strategic moves center on SOC 2 Type II certification acquisition and domestic data localization partnerships.
Within the government-credentialing tier, IDEMIA anchors high-assurance banking contracts through its heritage in secure credential issuance. NEC Corporation occupies a specialized position in iris recognition applications for vault and data center physical access. Thales Group exemplifies the defense-to-finance extension archetype, with its security portfolio reaching cloud-based biometric platforms for investment firms.
| Leading Market Players |
|---|
| Thales Group |
| Fujitsu |
| Veridium |
| Aware, Inc. |
| AllTrust Networks |
| NEC Corporation |
| IDEMIA |
| HID Global |
| Fingerprint Cards AB |
| Others |
Pricing and Supply Chain Analysis
Capacitive sensor fabrication costs cascade through three distinct pricing tiers as hardware moves from East Asian foundries to North American credit union networks and tier-one banking infrastructure. Liveness detection algorithm licensing fees concentrate pricing power among vendors with NIST-certified biometric engines, while subscription SaaS models compress upfront capital barriers for regional institutions.
Pricing Analysis
The bundled-versus-unbundled service split separates core banking platform providers from specialized biometric vendors, with credit unions driving unbundled procurement to escape legacy core vendor markups. Pricing stratifies across premium, standard, and economy tiers based on SOC 2 Type II certification status and domestic data localization guarantees. Cost compression in the standard tier intensifies because cloud-native entrants are undercutting on-premise incumbents with consumption-based billing. Regional banks with assets below $5 billion exhibit the highest price sensitivity, while tier-one institutions prioritize certification grade over per-seat economics.
Supply Chain Analysis
Reverse-logistics flows for fingerprint sensor refurbishment remain underdeveloped, exposing credit unions to hardware refresh cycles without secondary market alternatives. Sensor fabrication concentrates in Taiwan, South Korea, and China, with East Asian foundry capacity anchoring component availability. Raw material dependencies span silicon wafers, rare-earth magnets for iris scanners, and specialized optical glass for facial recognition modules. Single-source vulnerability in CMOS sensor supply creates exposure to geopolitical disruption. Distribution runs through systems integrators with FFIEC compliance expertise rather than direct vendor relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where FFIEC multi-factor authentication mandates generate recurring procurement cycles as compliance deadlines cascade through institution tiers. The Federal Reserve's real-time payment infrastructure timeline sustains demand velocity across the forecast window.
For Market Incumbents: Extend defense-grade security portfolios into cloud-native delivery models to counter emerging fintech-native identity platforms. IDEMIA and Thales Group should deepen ISO 27001 certification moats as smaller vendors struggle with audit resource intensity. Vertical integration into domestic data center partnerships addresses state-level privacy fragmentation that threatens multi-state contract renewals.
For New Entrants and Emerging Players: Mid-tier credit unions with $500 million to $2 billion in assets represent the most penetrable buyer archetype, as these institutions actively disintermediate core banking vendors for specialized identity solutions. Voice recognition for call center passive authentication offers white-space expansion with lower algorithm development barriers than facial or iris modalities. A channel partnership strategy with regional systems integrators accelerates FFIEC compliance validation without direct regulatory engagement costs.
For Investors and Strategic Acquirers: Consolidation pressure builds where SOC 2 Type II certification scarcity concentrates valuation premiums among audit-ready vendors. Long-term viability favors platforms with interoperable template federation capabilities that enable credit union network effects. The acquisition target archetype combines behavioral biometrics IP with existing banking channel relationships. Monitor NIST demographic bias audit results as an inflection indicator for vendor disqualification risk.
| Strategic Initiative | Industry Significance |
|---|---|
| Cloud Template Federation Partnership | Enables credit union networks to share infrastructure investment across state-level privacy jurisdictions. |
| Domestic Data Localization Buildout | Addresses Illinois BIPA and California CCPA retention requirements that offshore platforms cannot satisfy. |
| Behavioral Biometrics Acquisition | Complements static authentication with continuous session monitoring for mid-tier investment firm clients. |
| SOC 2 Type II Certification Investment | Unlocks tier-one bank procurement where OCC third-party scrutiny blocks uncertified vendors. |
| Voice Recognition Platform Launch | Captures call center automation budgets while reducing average handle time under consumer protection rules. |
Research Methodology
Multiple input streams — primary interviews with CISOs and procurement officers at regional banks, secondary validation against FFIEC guidance documents and FINTRAC enforcement records, and technical specification analysis of NIST-certified biometric engines — were reconciled through bottom-up and top-down triangulation. Conversations with credit union technology executives, core banking vendor product managers, and biometric SaaS platform engineers informed deployment architecture assumptions. Secondary sources encompassed regulatory filings from the Federal Reserve and OCC, patent databases for liveness detection algorithms, and infrastructure spend disclosures from major cloud providers.
Data-stream reconciliation anchored volume projections to biometric authentication transaction growth trajectories across the analysis window, with segmentation modeled by technology modality, deployment architecture, and institutional asset tier. CAGRs were derived from regression analysis of historical procurement cycles correlated with regulatory mandate effective dates. Industry-specific forecast inputs included core banking system refresh timelines and credit union merger activity patterns that concentrate purchasing authority.
Inputs from primary stakeholder interviews and regulatory document repositories were available through the study window; gaps in real-time payment infrastructure deployment schedules introduce uncertainty bands around near-term authentication volume projections. Practitioners should monitor state-level biometric privacy legislative activity and NIST demographic performance testing protocol updates for early signals of vendor qualification disruption.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Risk Management and Compliance
Oil and Gas Risk Management Market
Risk Management and Compliance
Employee Benefits Strategy and Consulting Market
Risk Management and Compliance
Europe Strategy Consulting Market
Risk Management and Compliance
Pre Trade Risk Management Solution Market
Risk Management and Compliance
Operations Advisory Service Market
Risk Management and Compliance
Global Strategy Consulting Market
Risk Management and Compliance
Enterprise Risk Management Market
Risk Management and Compliance
Sustainable Finance Market
Risk Management and Compliance
Governance, Risk and Compliance Platform Market
Risk Management and Compliance
Global Compliance Management Software Market
Risk Management and Compliance
Global Regulatory Reporting and Compliance Market
Risk Management and Compliance
UK Anti Money Laundering Solutions Market
Risk Management and Compliance
Loan Compliance Management Software Market
Risk Management and Compliance
Financial Risk Management Software Market
Risk Management and Compliance
Medical Device Cyber Risk Quantification Market
Risk Management and Compliance
Global Energy Trading and Risk Management (ETRM) Market