
 Home Equity Lending Market | 2026-2036
Home Equity Lending Market Size, Share, and Industry Trends Forecast 2026-2036
Home Equity Lending Market Foresight
The United States is reconfiguring its home equity origination infrastructure as rate volatility forces lenders to retool pricing engines and digital underwriting stacks. JPMorgan Chase leverages its retail deposit base to sustain below-market funding costs for HELOC originations. Wells Fargo anchors its position through branch-level loan officer networks that dominate in suburban markets with high homeowner equity penetration. Figure Technologies differentiates via blockchain-secured rapid-close products that compress approval timelines from weeks to days.
Home equity lending comprises secured credit products collateralized by residential property value exceeding existing mortgage balances, with loan-to-value ratios typically capped between eighty and ninety percent depending on borrower credit tier and lien position. These instruments serve primarily as liquidity extraction mechanisms for asset-rich households seeking to finance consumption, investment, or liability restructuring without disposing of underlying real estate. Fixed-rate home equity loans command the largest volume share among product types, reflecting borrower preference for payment certainty amid rate uncertainty. Home equity lines of credit represent the fastest-expanding segment, driven by draw flexibility that aligns with phased renovation timelines. Cash-out refinance activity has contracted structurally as prevailing rates exceed most outstanding mortgage coupons, redirecting volume toward standalone second-lien products.
The Consumer Financial Protection Bureau enforces Truth in Lending Act disclosure requirements that shape origination documentation and advertising standards for home equity products. Federal Housing Finance Agency guidelines on high-LTV lending influence secondary market eligibility and thus primary market pricing. State-level usury statutes and foreclosure process variations create patchwork compliance obligations that favor multistate lenders with dedicated regulatory operations. Stakeholders must monitor how Basel III endgame proposals recalibrate risk-weighted capital requirements for residential real estate exposures, as this will directly alter return thresholds for new originations.
Market Dynamics
The Federal Reserve's sustained restrictive posture on benchmark rates is compressing net interest margins across origination channels while simultaneously locking millions of homeowners into low-rate first mortgages, creating structural demand for standalone second-lien products.
Growth Catalysts
- Home Renovation Tax Credits:The Inflation Reduction Act's energy efficiency rebates for residential retrofits are channeling liquidity demand toward HELOC structures that align draw schedules with contractor payment milestones.
- Blockchain-Enabled Title Verification:Distributed ledger protocols for lien priority confirmation are compressing title search timelines from days to hours, accelerating closing velocity in competitive purchase markets.
- Sun Belt Migration Concentration:Texas, Florida, and Arizona are absorbing disproportionate inbound household formation, expanding the addressable base of high-equity borrowers with tappable collateral.
Market Restraints
- Deposit Funding Cost Volatility:Regional banks reliant on brokered deposits face 150-250 basis point funding disadvantages versus money-center institutions with sticky retail core deposits.
- Basel III Endgame Capital Requirements:Proposed risk-weighting increases for high-LTV residential exposures would elevate minimum return thresholds, constraining marginal originations.
- Cash-Out Refinance Substitution Collapse:The rate differential between outstanding mortgages and current coupons has eliminated cash-out refinancing as a viable alternative, capping total home equity extraction volume.
Strategic Opportunities
- Digital-First Subprime Rehabilitation:Thin-file borrowers with recovered credit profiles represent an underserved segment for secured products with automated income verification bypassing traditional documentation requirements.
- HELOC-Linked Investment Platforms:Fintech intermediaries are constructing draw automation tools that synchronize home equity access with portfolio rebalancing triggers, creating new origination partnerships.
- State-Level Green Energy Mandates:California's solar installation requirements and New York's building electrification codes are generating renovation financing demand that specialized lenders can productize.
Industry Challenges
- Appraisal Capacity Constraints:Licensed residential appraisers have declined 20% since 2007, creating bottlenecks for collateral valuation in high-volume origination windows.
- Legacy Core System Integration:Mainframe-dependent institutions face seven-figure modernization costs to enable real-time draw authorization and mobile servicing interfaces.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Home Equity Lending Market |
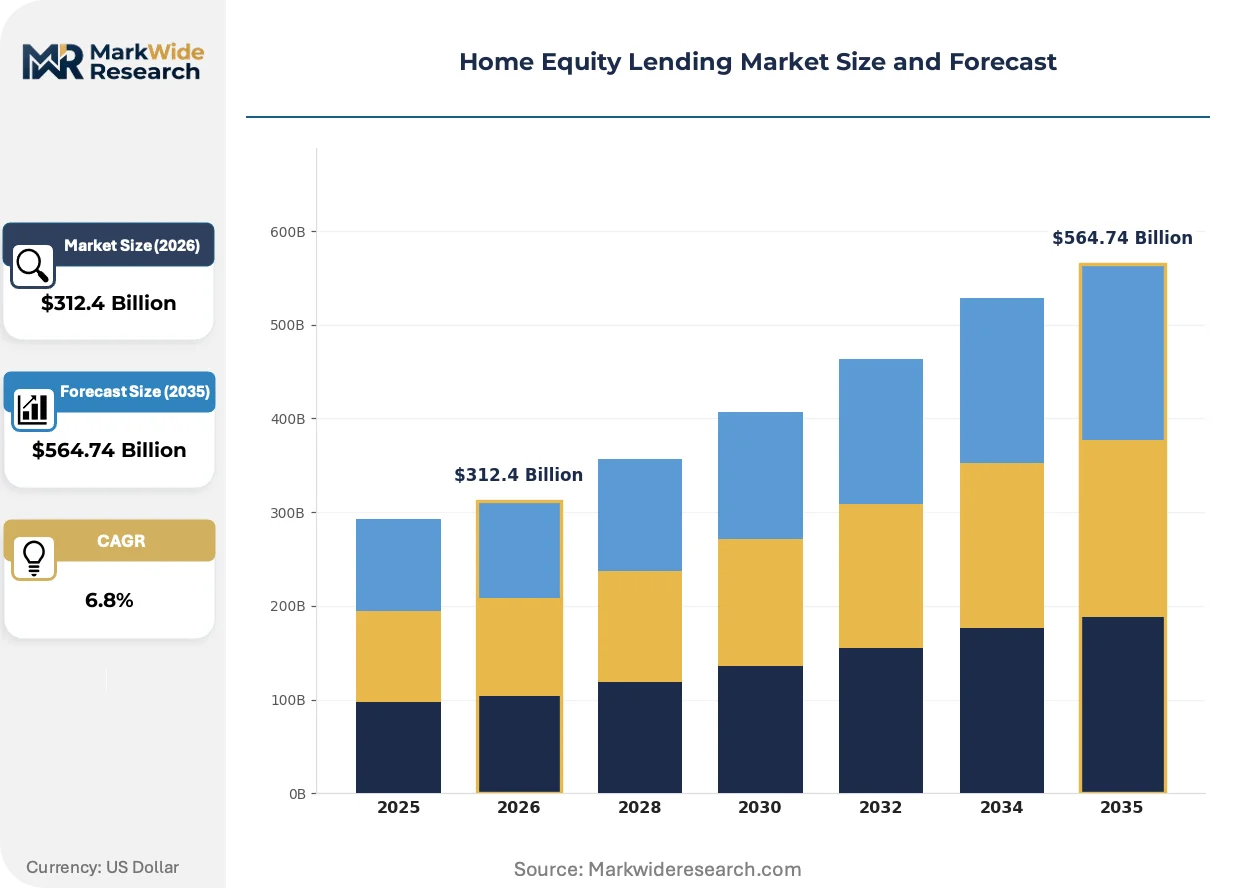
| Market Size in 2026 | $312.4 Billion |
| Market Size in 2035 | $564.74 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Home Equity Line of Credit, Home Equity Loan, Cash-Out Refinance, Reverse Mortgage Interest Rate Type: Fixed Rate, Variable Rate, Hybrid Rate, Adjustable Rate Borrower Profile: First-Time Homeowners, Investors, Retirees, Low-Income Families Purpose of Loan: Debt Consolidation, Home Renovation, Major Purchase, Education Expenses |
| Companies Covered | Bank of America, JPMorgan Chase, Wells Fargo, PNC Financial Services, U.S. Bank, Figure Technologies, Unison, Hometap, Navy Federal Credit Union, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Home Equity Lending Market Shifts & Advancements
Automated valuation models and alternative credit data are restructuring underwriting economics, compressing the cost to originate while expanding the pool of qualified borrowers beyond traditional FICO boundaries.
Automated valuation models leveraging satellite imagery and municipal tax records are replacing physical appraisals for low-LTV originations. JPMorgan Chase and Wells Fargo have deployed these tools for HELOCs below 70% combined loan-to-value, cutting collateral review costs by 60%. The technology is rendering obsolete the three-day appraisal turnaround that previously constrained digital closing velocity.
The Consumer Financial Protection Bureau's 2023 RESPA marketing services agreement guidance is tightening co-marketing relationships between lenders and real estate brokerages. This regulatory friction is elevating customer acquisition costs for depository institutions dependent on referral networks. Independent mortgage banks with direct-to-consumer digital channels are capturing disproportionate volume as referral-dependent lenders restructure compliance frameworks.
Borrowers are fragmenting their liquidity sourcing across multiple unsecured and secured products rather than consolidating into single large draws. Credit unions and fintech platforms are responding with modular draw structures that permit borrowers to lock portions of HELOC balances into fixed-rate term loans. This behavioral shift is most pronounced among homeowners aged 45-60 in high-equity suburban markets where renovation timelines extend 18-36 months.
Home Equity Lending Market Segmentation
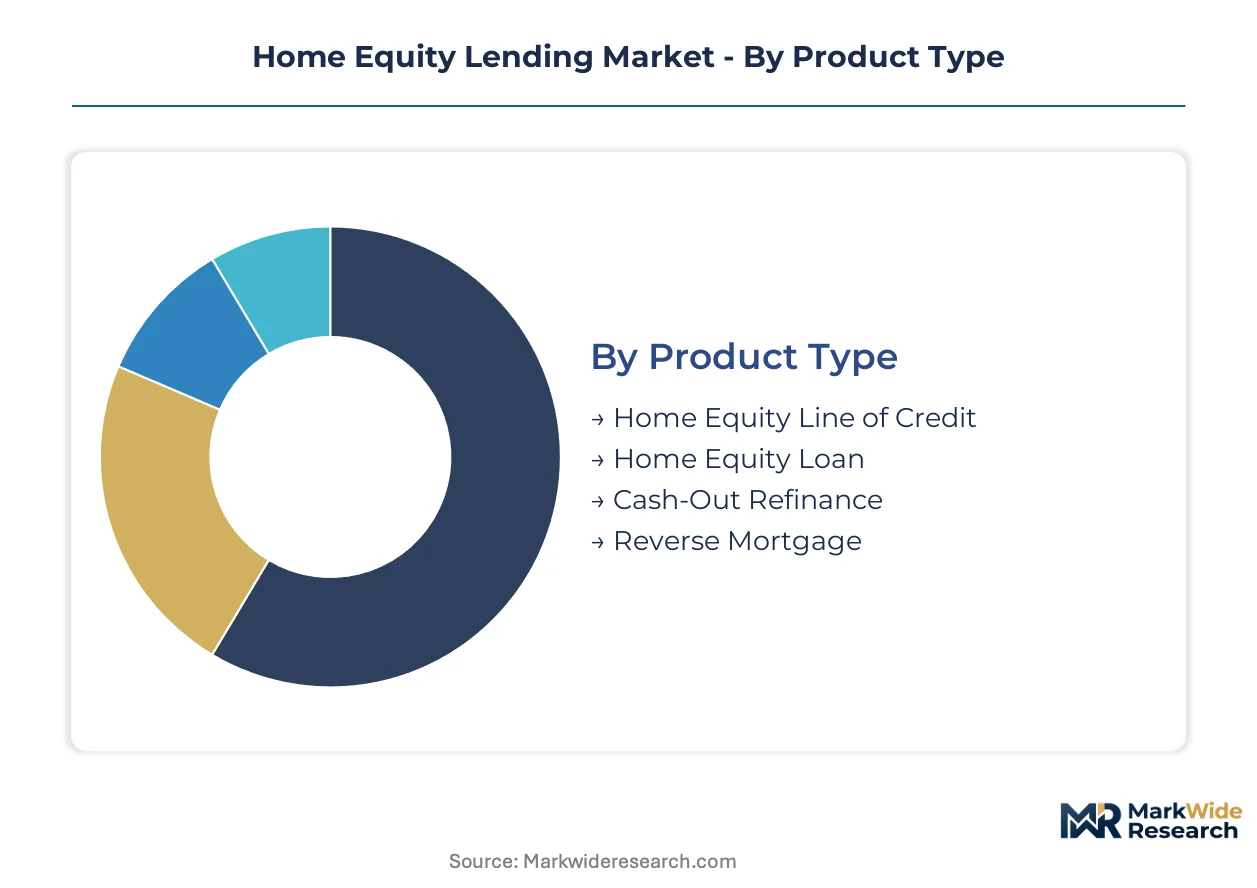
Home equity lending segmentation reveals how product architecture, pricing mechanics, and borrower circumstances combine to determine origination economics. Lenders calibrate underwriting engines and servicing infrastructure around these segment boundaries.
Product Type:
After-sales-service intensity varies sharply across product types, with draw-management complexity driving operational cost structures.
- Home Equity Line of Credit:Revolving credit structures with variable-rate pricing and multi-year draw periods require active account monitoring and periodic limit adjustments. Demand concentrates among aging homeowners in Sun Belt states financing phased renovation timelines, with draw automation tools reducing servicing overhead.
- Home Equity Loan:Closed-end term loans with fixed amortization schedules demand minimal ongoing servicing beyond payment processing and escrow administration. First-lien position originations in suburban markets with high equity penetration dominate volume, as borrowers prioritize payment certainty over flexibility.
- Cash-Out Refinance:First-mortgage replacement products integrating equity extraction into rate-term refinancing.
- Reverse Mortgage:Negative-amortization products for senior homeowners converting home equity into income streams without monthly payments.
By volume, Home Equity Loan leads. By growth pace, Home Equity Line of Credit is ahead.
Interest Rate Type:
Cost tier differentiation separates mass-market originations from specialized products requiring sophisticated hedging infrastructure.
- Fixed Rate:Rate-lock commitments transfer interest risk to lender balance sheets, requiring derivatives hedging or retained portfolio absorption. Demand clusters among risk-averse borrowers in volatile rate environments seeking payment predictability.
- Variable Rate:Prime-indexed pricing shifts rate risk to borrowers while compressing origination spreads. Investors and short-duration borrowers in rising-rate environments favor this structure for its lower initial carrying cost.
- Hybrid Rate:Fixed-to-float conversion features blending initial payment stability with eventual rate exposure.
- Adjustable Rate:Periodic reset mechanisms with rate caps and floors creating structured risk-sharing.
Fixed Rate commands the largest origination volume. Variable Rate is expanding most quickly as prime-indexed HELOCs capture renovation demand.
Borrower Profile:
Customer-type stratification determines acquisition channel economics and default risk calibration.
- First-Time Homeowners:Recent entrants with limited equity cushions and thin credit files require enhanced documentation and conservative LTV limits. Suburban markets with rapid price appreciation generate disproportionate volume as equity builds quickly.
- Investors:Non-owner-occupied collateral and rental income-dependent underwriting demand specialized appraisal and cash-flow verification. Sun Belt rental markets with strong occupancy trends attract concentration.
- Retirees:Fixed-income borrowers with substantial equity but declining earnings capacity.
- Low-Income Families:Subsidized program eligibility and community development financial institution partnerships.
First-Time Homeowners generate the highest origination count. Investors are gaining share fastest as rental property equity extraction accelerates.
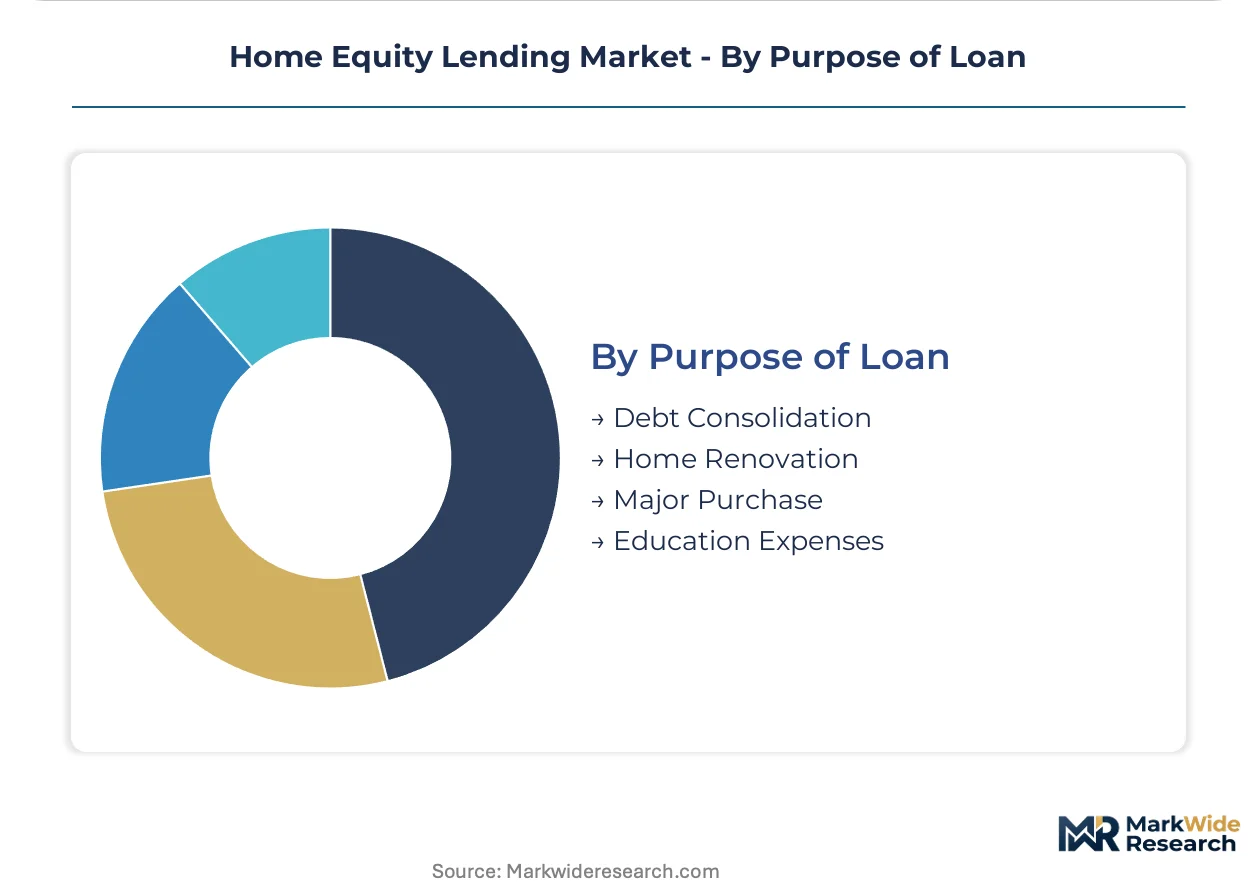
Purpose of Loan:
Application-driven segmentation shapes marketing alignment and collateral verification requirements.
- Debt Consolidation:Liability restructuring transactions replacing high-rate unsecured balances with secured obligations. Credit card-dependent households in high-equity markets drive volume as rate differentials widen.
- Home Renovation:Improvement-financing originations requiring contractor verification and draw inspection protocols. Energy retrofit demand tied to IRA tax credits concentrates in states with aggressive decarbonization mandates.
- Major Purchase:Liquidity events funding vehicles, medical expenses, or business investment.
- Education Expenses:Tuition and student debt replacement using residential collateral.
Home Renovation leads by dollar volume. Debt Consolidation is climbing the fastest as credit card rates reset higher.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Deposit-rich money-center institutions concentrate origination capacity in jurisdictions with favorable collateral frameworks and regulatory clarity. Jurisdictional variation in lien priority rules and foreclosure timelines creates structural advantages for lenders operating across multiple state-level markets.
United States
Sun Belt migration and aging homeowner renovation demand drive volume concentration in Texas, Florida, and Arizona. The Consumer Financial Protection Bureau enforces Truth in Lending Act disclosure requirements that shape origination documentation standards. Dallas-Fort Worth and Houston metro areas exhibit the fastest HELOC origination growth as inbound household formation expands the addressable borrower base.
Canada
Home equity line of credit products dominate consumer secured borrowing as homeowners avoid first-mortgage breakage penalties. The Office of the Superintendent of Financial Institutions regulates capital adequacy requirements for residential real estate exposures. Toronto and Vancouver markets concentrate origination activity where home price appreciation has created substantial tappable equity among long-tenure owners.
United Kingdom
Equity release products for retirees represent the fastest-growing segment as demographic aging accelerates. The Financial Conduct Authority oversees mortgage lending conduct standards and product disclosure requirements. London and Southeast England anchor volume given concentrated property wealth and higher average loan sizes relative to regional markets.
Australia
Offset mortgage structures and redraw facilities compete with standalone home equity products for consumer liquidity preference. The Australian Prudential Regulation Authority sets capital buffers for residential mortgage exposures. Sydney and Melbourne metropolitan areas generate disproportionate origination volume amid sustained property price elevation.
Germany
Pfandbrief-covered bank funding enables below-market pricing for residential secured lending products. BaFin supervises mortgage credit institutions under the German Banking Act framework. Frankfurt and Munich financial centers concentrate lender headquarters and underwriting operations serving high-equity borrowers in southern and western states.
Home Equity Lending Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream with narrower origination footprints. The market structures around three tiers: money-center depository institutions with retail deposit advantages, regional banks with branch-level relationship networks, and fintech platforms with digital-first underwriting engines. Strategic differentiation concentrates on funding cost position, closing velocity, and borrower segment specialization. Competitive moves emphasize deposit base expansion through acquisition and technology licensing for automated valuation integration.
Among money-center depository institutions, JPMorgan Chase and Wells Fargo exemplify divergent positioning strategies. JPMorgan Chase occupies a position anchored in retail deposit funding advantages that sustain below-market HELOC pricing. Wells Fargo represents branch-network-centric origination dominance in suburban markets with high homeowner equity penetration. Figure Technologies sits within the fintech tier, exemplifying blockchain-secured rapid-close product architecture that compresses approval timelines.
| Leading Market Players |
|---|
| Bank of America |
| JPMorgan Chase |
| Wells Fargo |
| PNC Financial Services |
| U.S. Bank |
| Figure Technologies |
| Unison |
| Hometap |
| Navy Federal Credit Union |
| Others |
Supply & Pricing Matrix
Intermodal freight corridors connecting Texas Gulf Coast ports to Sun Belt distribution centers transmit funding cost volatility directly into regional pricing spreads, concentrating margin pressure on regional banks while amplifying rate differentiation between money-center deposit franchises and brokered-deposit-dependent originators.
Pricing Analysis
The Truth in Lending Act dictates the pricing tier structure through mandated disclosure granularity that elevates compliance overhead for smaller originators. Three-tier pricing structure across premium, standard, and economy levels separates JPMorgan Chase's retail-funded HELOCs from regional bank products and fintech rapid-close offerings. Price differentiation hinges on funding source stability and automated underwriting penetration. Cost compression in the standard tier is intensifying because Basel III endgame proposals threaten capital charges on high-LTV exposures. First-time homeowners with thin credit files exhibit highest price sensitivity; retirees with substantial equity cushions show least.
Supply Chain Analysis
Tariff exposure between China and the United States dominates technology procurement risk for automated valuation model satellite imagery components and blockchain verification hardware. Origination infrastructure concentrates in the United States, Canada, and the United Kingdom, with secondary servicing capacity in India and the Philippines. Raw material dependencies span licensed appraiser labor pools, cloud computing infrastructure, and core banking system middleware. Single-source vulnerability in legacy mainframe-dependent institutions constrains real-time draw authorization capabilities. Distribution runs through direct-to-consumer digital channels, branch-network loan officers, and fintech platform partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Deposit base consolidation among money-center institutions has shifted negotiating leverage toward borrowers with pristine credit profiles, fragmenting price discovery across multiple origination channels.
For Market Incumbents: Build switching-cost moats through HELOC-linked investment platform integrations that synchronize draw automation with borrower portfolio management. Deepen core deposit franchises through acquisition of regional banks with sticky retail bases. Defend against fintech velocity advantages by licensing automated valuation technology from satellite imagery providers. Prioritize vertical integration into title verification services to compress closing timelines. For New Entrants and Emerging Players: Pursue thin-file subprime rehabilitation segments where automated income verification bypasses traditional documentation requirements. Target Sun Belt states with inbound household formation and rapid home price appreciation. Penetrate modular draw structure demand among homeowners aged 45-60 financing phased renovations. Angle go-to-market through contractor partnership networks capturing energy retrofit demand tied to Inflation Reduction Act incentives. For Investors and Strategic Acquirers: Carve-out targets emerge from regional bank holding companies with distressed deposit franchises but intact suburban branch networks. Long-term viability centers on funding cost positioning and regulatory compliance infrastructure scale over the next decade. Acquisition archetype: mid-tier institutions with mainframe modernization deficits but strong geographic equity penetration. Watch Federal Reserve rate trajectory as inflection signal for origination margin recovery.| Strategic Initiative | Industry Significance |
|---|---|
| Automated Valuation Model Deployment | JPMorgan Chase and Wells Fargo cut collateral review costs by 60% for low-LTV HELOC originations. |
| Blockchain-Enabled Title Verification | Figure Technologies compresses lien priority confirmation from days to hours through distributed ledger protocols. |
| Deposit Base Expansion | Money-center institutions acquire regional banks to sustain below-market funding costs for HELOC pricing. |
| Modular Draw Structure Launch | Credit unions and fintechs capture fragmented liquidity sourcing behavior among renovation borrowers. |
| Green Energy Mandate Productization | Specialized lenders align draw schedules with California solar and New York electrification code timelines. |
Research Methodology
The analysis maps HELOC, home equity loan, cash-out refinance, and reverse mortgage sub-sectors, each validated through chief lending officers, digital product executives, regulatory compliance leads, and secondary market traders. Primary interviews with heads of consumer lending at money-center and regional banks, fintech platform founders, and credit union executives combined with secondary validation from Federal Reserve flow of funds data, Consumer Financial Protection Bureau disclosure filings, FHFA mortgage market indices, and Basel Committee regulatory consultations. Bottom-up origination volume triangulation against top-down household equity extraction estimates anchored market sizing.
Assumptions held fixed include Federal Reserve benchmark rate posture, Basel III endgame implementation trajectory, and Sun Belt migration patterns; variables included home price appreciation rates and appraisal capacity constraints. The projection horizon spans product type, interest rate structure, borrower profile, and loan purpose segmentation dimensions. CAGRs derived from trend extrapolation moderated by regulatory capital requirement sensitivity analysis. Forecast inputs incorporated Federal Housing Finance Agency high-LTV lending guidelines and state-level usury statute variations.
Macroeconomic conditions sit as an overlay; deviation in benchmark rate trajectories, home price correction severity, or appraisal labor pool recovery would shift the trajectory. Forecasts reflect documented assumptions subject to revision from regulatory rulemaking or technological disruption in underwriting automation. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Loans and Leasing
Commercial Lending Market
Loans and Leasing
China Car Loan Market
Loans and Leasing
Europe Mortgage Lending Market
Loans and Leasing
Digital Lending Market
Loans and Leasing
Car Leasing Market
Loans and Leasing
Alternative Financing Market
Loans and Leasing
Refinancing Market
Loans and Leasing
Europe Car Loan Market
Loans and Leasing
Asia-Pacific Car Loan Market
Loans and Leasing
Germany Auto Loan Market
Loans and Leasing
Global Automotive Financing Market
Loans and Leasing
Asset-Based Lending Market
Loans and Leasing
France Student Loan Market
Loans and Leasing
Canada Mortgage/Loan Brokers Market
Loans and Leasing
India Used Car Financing Market
Loans and Leasing
Europe Used Car Financing Market