
 Global Regulatory Reporting and Compliance Market | 2026-2036
Global Regulatory Reporting and Compliance Market Size, Share, and Industry Trends Forecast 2026-2036
Global Regulatory Reporting and Compliance Market Foresight
Cloud-native architecture is tilting the delivery model for regulatory reporting platforms away from legacy on-premises installations. Deloitte leverages its consulting footprint to embed compliance tools directly into client ERP environments. IBM anchors its position through AI-powered data lineage engines that trace regulatory inputs across fragmented source systems. Thomson Reuters competes by controlling proprietary taxonomies that map local rules to global reporting standards.
Regulatory reporting and compliance encompasses the systematic collection, validation, and submission of structured data to government agencies and standard-setting bodies, typically requiring XBRL tagging, audit trails, and real-time monitoring dashboards. The primary purpose is to enable transparent oversight while reducing the manual burden of multi-jurisdiction filings. Cloud deployment models now capture the fastest expansion as banks seek elastic capacity for quarterly reporting spikes, while on-premises solutions retain dominance among central banks with data sovereignty mandates. Within industry verticals, BFSI occupies the deepest margin pools due to the density of capital requirements, though energy and utilities reporting is accelerating as emissions disclosures proliferate.
The SEC, EMA, and ECB collectively shape product roadmaps through divergent data standards and submission timelines that vendors must harmonize. The EU Green Deal and CSRD are forcing platform providers to build emissions calculation modules that interface with existing financial reporting stacks. Stakeholders must monitor whether emerging AI audit requirements fragment compliance architectures or consolidate them onto unified governance platforms.
Market Dynamics
Cloud-native compliance platforms are displacing legacy on-premises installations as financial institutions confront overlapping mandates from the SEC, EMA, and ECB that demand elastic data infrastructure for quarterly reporting spikes.
Growth Catalysts
- EU AI Act compliance mandates:Financial institutions in Europe must deploy automated audit trails for algorithmic decision-making, forcing procurement of integrated governance platforms that unify risk scoring with disclosure workflows.
- Cross-border banking consolidation:Merged entities spanning Singapore, the United Kingdom, and the United States require harmonized reporting stacks that collapse multiple national taxonomies into single submission pipelines.
- XBRL tagging automation:Machine learning engines now extract structured data from unstructured source documents, compressing preparation cycles for Basel III liquidity reports and SEC climate disclosures.
Market Restraints
- Data sovereignty fragmentation:Central banks in Germany, France, and Switzerland mandate on-premise storage for supervisory data, blocking cloud migration for critical reporting functions and inflating infrastructure duplication costs.
- Specialized talent scarcity:Firms competing for professionals fluent in both regulatory taxonomy design and distributed systems architecture face wage premiums exceeding forty percent in London and New York.
- Interoperability tax:Vendor-specific data lineage formats create switching costs that lock institutions into incumbent platforms despite functional gaps in emissions calculation modules.
Strategic Opportunities
- CSRD emissions integration:The EU Corporate Sustainability Reporting Directive forces non-financial corporates to adopt calculation engines that interface with existing ERP systems, opening adjacent markets beyond banking.
- Energy sector verticalization:Oil majors and utilities in the United States face SEC climate disclosure rules that demand granular Scope 3 tracking, creating demand for sector-specific compliance modules.
- API-first distribution:Embedded compliance widgets delivered through banking-as-a-service platforms allow regtech vendors to penetrate mid-market fintechs without direct enterprise sales cycles.
Industry Challenges
- Legacy system entanglement:Decades-old core banking infrastructure at major institutions resists real-time data extraction, forcing expensive middleware layers that degrade reporting latency.
- Regulatory timeline misalignment:Divergent implementation schedules between the EU AI Act and SEC climate rules complicate product roadmaps for platform vendors serving multinational clients.
- Validation engine calibration:Automated rule-checking systems require continuous retraining as national regulators issue interpretive guidance that shifts submission requirements mid-cycle.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Regulatory Reporting and Compliance Market |
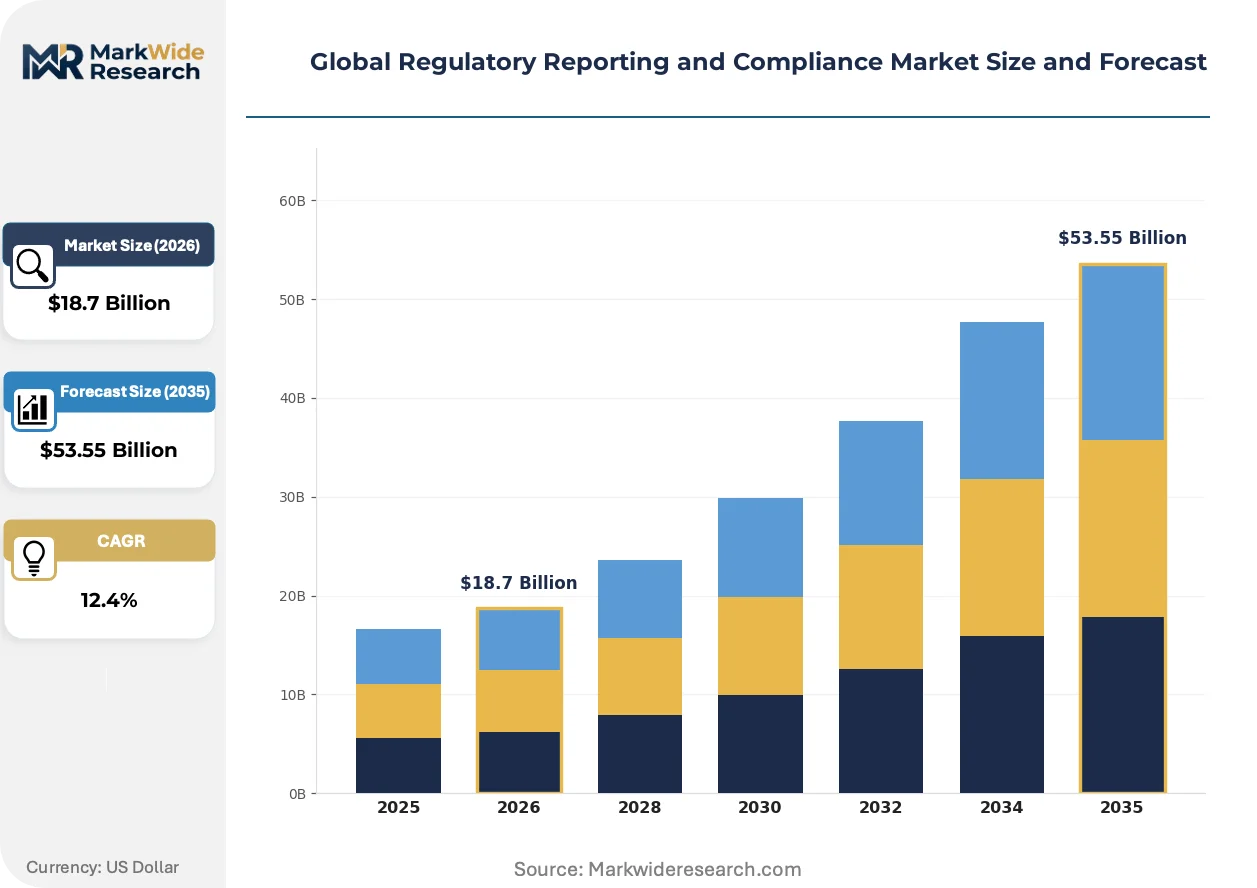
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $53.55 Billion |
| CAGR (2026 – 2036) | 12.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Type: Risk Management, Audit Management, Data Security, Document Management, Compliance Monitoring, Fraud Detection Deployment Model: Cloud, On-Premises, Hybrid, Managed Services Industry Vertical: BFSI, Telecommunications, Energy & Utilities, Manufacturing, Government, Transportation End User: Large Enterprises, Small & Medium Enterprises, Regulatory Authorities, Consulting Firms, Financial Institutions |
| Companies Covered | Deloitte, PwC, EY, KPMG, Accenture, Thomson Reuters, Wolters Kluwer, IBM, Oracle, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Regulatory Reporting and Compliance Market Shifts & Advancements
Regulatory reporting infrastructure is converging with enterprise risk management systems as real-time supervision mandates compress the gap between data generation and submission deadlines.
Distributed ledger technology is virtualizing audit trail architecture for cross-border payment reporting. Major correspondent banks in Singapore and London are piloting immutable transaction logs that satisfy both MAS and FCA record-keeping requirements. This virtualization eliminates reconciliation delays between nostro accounts and regulatory submissions, compressing settlement-to-reporting cycles from days to minutes.
The EU Green Deal and CSRD are forcing platform providers to build emissions calculation modules that interface with existing financial reporting stacks. Industrial consequence includes mandatory Scope 3 supply chain disclosures that require data extraction from tier-three suppliers. Energy and utilities verticals in Germany and France are responding fastest, deploying integrated ESG-ERP connectors ahead of enforcement deadlines.
Consolidated procurement of compliance platforms is displacing point solutions as chief risk officers seek unified governance dashboards. Mid-cap banks in the United States are abandoning siloed AML, KYC, and capital adequacy tools in favor of vendor ecosystems offering API-linked modules. This concentration is most visible among regional banks seeking to satisfy OCC and Federal Reserve examination expectations without expanding internal technology headcount.
Global Regulatory Reporting and Compliance Market Segmentation
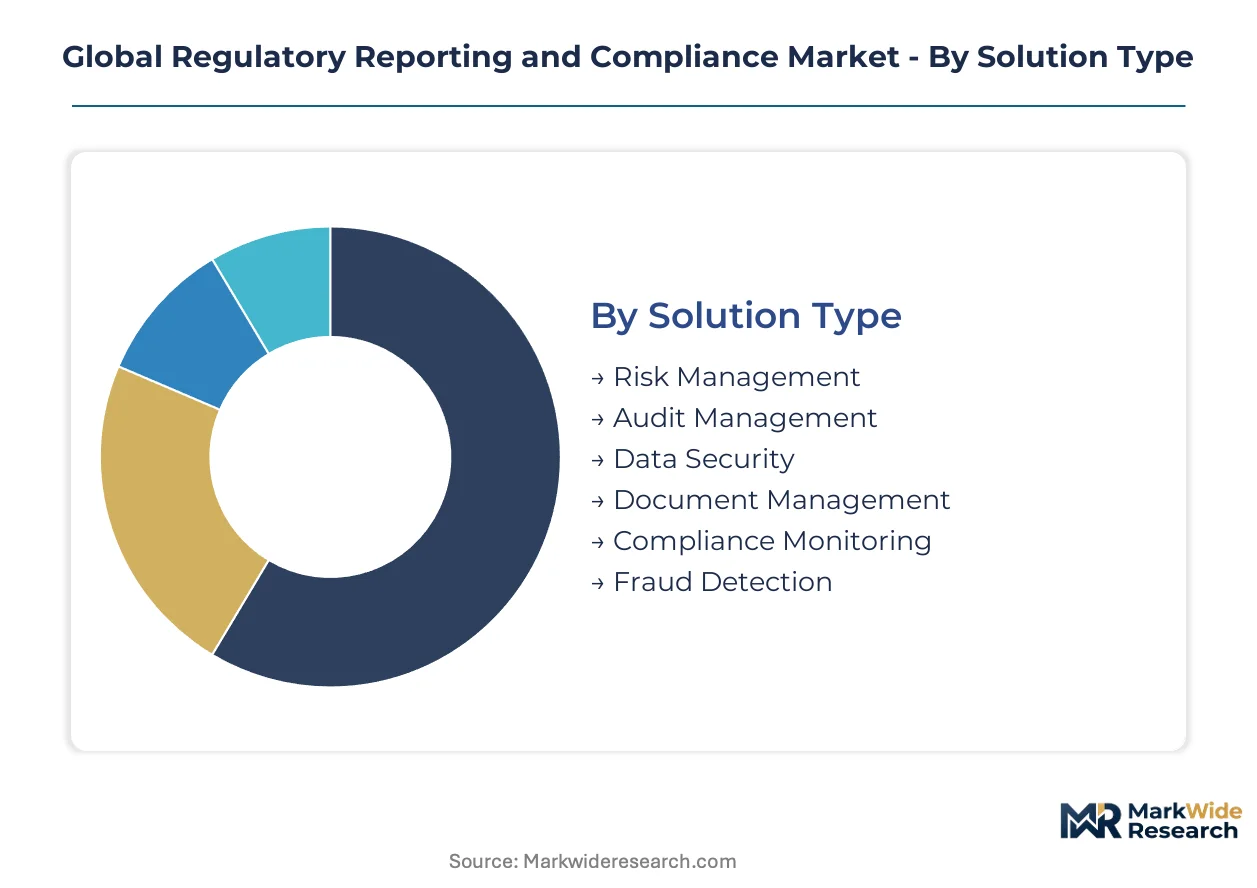
Regulatory reporting platforms fragment across solution architectures, infrastructure models, and buyer sophistication levels. Procurement patterns diverge sharply between institutions seeking point solutions versus unified governance stacks.
Solution Type:
Functional specialization determines pricing tiers and integration complexity across compliance workflows.
- Risk Management:Capital adequacy engines calculate exposure thresholds against Basel III and local central bank requirements. Tier-one banks in the United States and United Kingdom deploy these modules to automate stress test submissions to the Federal Reserve and Prudential Regulation Authority.
- Audit Management:Workflow engines coordinate internal control documentation, evidence collection, and external auditor handoffs. Demand concentrates among mid-cap European banks preparing for ECB supervisory review and evaluation process examinations.
- Data Security:Encryption and access governance layers protect supervisory data subject to GDPR and national banking secrecy laws.
- Document Management:Repository systems version-control policy documents, regulatory correspondence, and submission templates.
- Compliance Monitoring:Real-time dashboards track rule changes across multiple jurisdictions and flag obligation gaps.
- Fraud Detection:Pattern recognition engines identify anomalous transactions for SAR filing automation.
Risk Management holds installed capacity. Audit Management is rotating up the share rankings.
Deployment Model:
Infrastructure location choices reflect data sovereignty constraints and elasticity requirements for quarterly reporting spikes.
- Cloud:Elastic compute architectures scale processing capacity during regulatory filing windows without permanent hardware investment. Singaporean banks and fintechs favor this model to satisfy MAS technology risk management guidelines while avoiding capital expenditure.
- On-Premises:Physical server installations within institutional data centers satisfy central bank mandates for supervisory data localization. German Bundesbank and Swiss National Bank requirements force this architecture for critical liquidity reporting functions.
- Hybrid:Split configurations run sensitive calculations on-premise while pushing non-confidential analytics to cloud environments.
- Managed Services:Third-party operated infrastructure outsources maintenance and patch management to specialized vendors.
On-Premises holds installed capacity. Cloud is climbing the fastest as data localization rules evolve.
Industry Vertical:
Sector-specific disclosure obligations create divergent module requirements and sales cycle lengths.
- BFSI:Dense capital requirements and transaction monitoring mandates generate the deepest procurement budgets. Universal banks spanning the United States, United Kingdom, and Singapore account for the majority of platform revenue through integrated Basel, AML, and climate disclosure stacks.
- Telecommunications:Spectrum licensing and consumer protection filings drive demand for regulatory calendar management tools.
- Energy & Utilities:SEC climate disclosure rules and EU CSRD obligations force emissions calculation integration with existing ERP systems. Oil majors in the United States and utilities in Germany are deploying Scope 3 tracking modules ahead of enforcement deadlines.
- Manufacturing:Supply chain due diligence and product safety reporting requirements shape platform configuration.
- Government:Public sector procurement rules and transparency mandates create specialized workflow needs.
- Transportation:Safety incident reporting and emissions tracking for maritime and aviation regulators.
BFSI holds installed capacity. Energy & Utilities is gaining share fastest as ESG disclosure mandates expand.
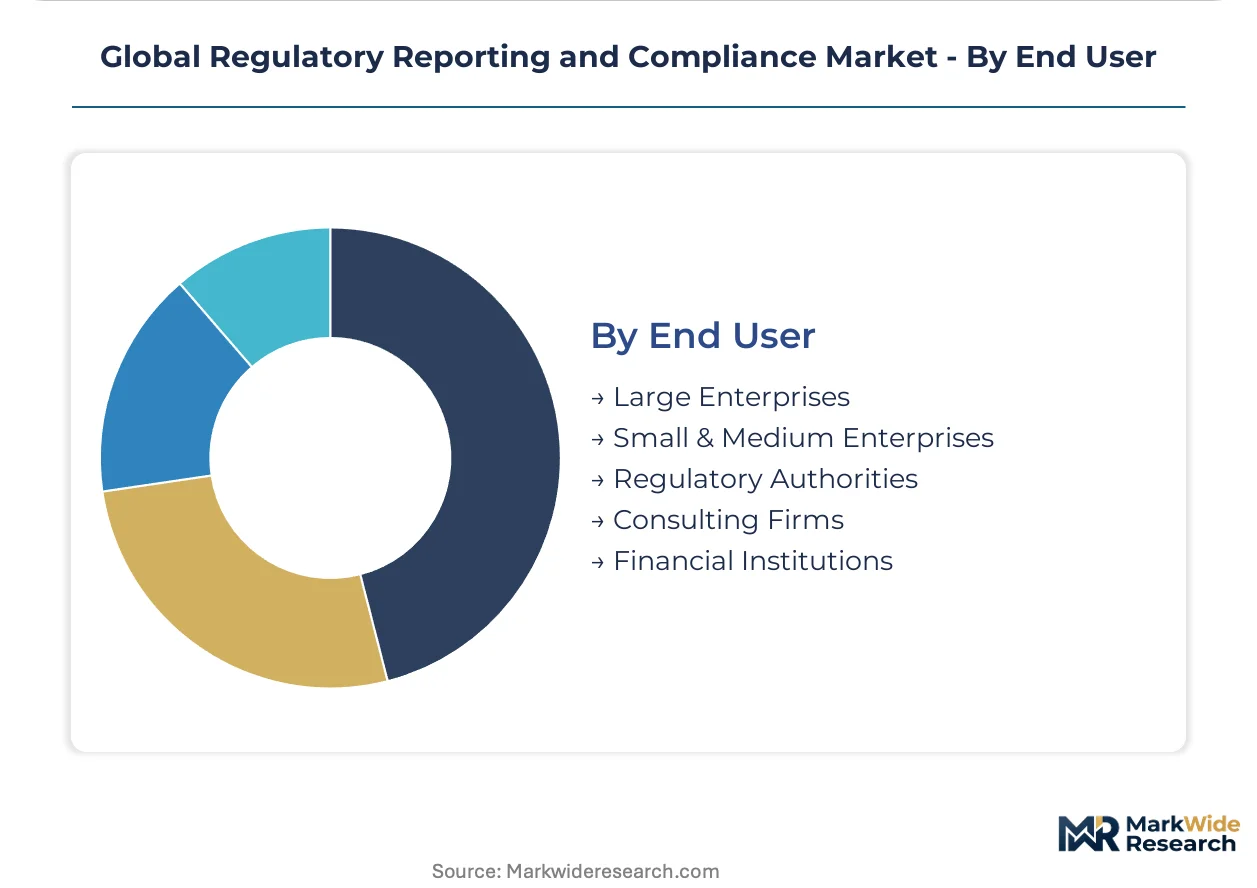
End User:
Organizational scale and regulatory role determine platform sophistication and integration depth.
- Large Enterprises:Complex multi-entity structures require harmonized reporting across dozens of national regulators. These buyers command the largest implementation budgets and longest sales cycles, typically consolidating previously siloed AML, KYC, and capital adequacy tools.
- Small & Medium Enterprises:Limited internal compliance headcount drives preference for standardized SaaS modules with pre-configured regulatory templates. Mid-market fintechs in Singapore and the United States adopt API-embedded widgets through banking-as-a-service platforms.
- Regulatory Authorities:Supervisory agencies themselves procure data collection and analytics platforms to process submissions from regulated entities.
- Consulting Firms:Advisory practices license platforms to deliver managed reporting services to client institutions.
- Financial Institutions:A cross-cutting category spanning banks, insurers, and asset managers with specialized prudential reporting needs.
Large Enterprises hold installed capacity. Small & Medium Enterprises is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Large financial institutions headquartered in the United States, the United Kingdom, and Singapore generate the deepest procurement budgets for regulatory reporting platforms. These buyers seek unified governance stacks that collapse multiple national taxonomies into single submission pipelines. Cloud-native architectures now capture the fastest expansion as banks confront overlapping mandates from the SEC, EMA, and ECB.
United States
Universal banks and asset managers drive platform procurement to automate SEC climate disclosure submissions and Basel III liquidity reports. The SEC mandates granular emissions tracking for oil majors and utilities, forcing integration of Scope 3 calculation engines with existing ERP systems. New York and Chicago host the densest concentrations of compliance technology deployments as regional banks abandon siloed AML and KYC tools.
United Kingdom
Cross-border banking consolidation between London and Singapore creates demand for harmonized reporting stacks. The Prudential Regulation Authority and FCA impose overlapping capital adequacy and transaction monitoring requirements that favor integrated governance platforms. The City of London anchors the deepest vendor ecosystems as mid-cap institutions consolidate previously separate compliance point solutions.
Germany
Industrial conglomerates and utilities deploy emissions calculation modules ahead of EU CSRD enforcement deadlines. The Bundesbank mandates on-premise storage for supervisory liquidity data, blocking cloud migration for critical reporting functions and inflating infrastructure duplication costs. Frankfurt and Munich concentrate the fastest ESG-ERP connector deployments as energy verticals respond to EU Green Deal obligations.
Singapore
Correspondent banks and fintechs favor elastic cloud architectures to satisfy MAS technology risk management guidelines. The Monetary Authority of Singapore pilots distributed ledger infrastructure for immutable cross-border payment audit trails. The financial district hosts the densest regtech vendor penetration as banking-as-a-service platforms embed compliance widgets for mid-market fintechs.
Switzerland
Private banks and wealth managers procure data lineage engines to trace regulatory inputs across fragmented source systems. The Swiss National Bank enforces data sovereignty mandates that force on-premise installations for critical supervisory submissions. Zurich and Geneva concentrate specialized deployments as institutions compete for talent fluent in both regulatory taxonomy design and distributed systems architecture.
Global Regulatory Reporting and Compliance Market Competitive Landscape
Channel-controlling players compete with product-specialist players across three distinct tiers. The market structure tilts toward consolidation as chief risk officers abandon siloed point solutions in favor of unified governance dashboards. Strategic archetypes include consulting-anchored integrators, AI-powered data lineage specialists, and proprietary taxonomy controllers. Dominant competitive moves encompass M&A to absorb emissions calculation capabilities and strategic partnerships to embed compliance widgets into banking-as-a-service platforms.
Among consulting-anchored integrators, Deloitte and PwC exemplify the channel-control archetype by embedding compliance tools directly into client ERP environments. IBM occupies a position as the AI-powered data lineage specialist, tracing regulatory inputs across fragmented source systems. Thomson Reuters sits within the proprietary taxonomy tier, mapping local rules to global reporting standards through controlled classification frameworks.
| Leading Market Players |
|---|
| Deloitte |
| PwC |
| EY |
| KPMG |
| Accenture |
| Thomson Reuters |
| Wolters Kluwer |
| IBM |
| Oracle |
| Others |
Supply & Pricing Matrix
Specialized engineering talent concentration in London and New York anchors cost structures for regulatory reporting platforms, with wage premiums exceeding forty percent for professionals fluent in both regulatory taxonomy design and distributed systems architecture. This upstream scarcity funnels margin pools toward vendors controlling proprietary data lineage engines and embedded ERP integration capabilities.
Pricing Analysis
Cost-plus contracts with inflation indexation dominate enterprise procurement for on-premise installations, particularly where central banks mandate data sovereignty. Pricing stratifies across premium, standard, and economy tiers based on deployment complexity and XBRL taxonomy coverage breadth. Cost compression in mid-market SaaS tiers is intensifying because API-first distribution models reduce customer acquisition overhead. Small and medium enterprises exhibit highest price sensitivity, while large universal banks prioritize functional depth over unit economics.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk for hardware-dependent on-premise installations, though software-native platforms face minimal physical component exposure. Cloud infrastructure draws from hyperscaler concentrations in the United States, Ireland, and Singapore, with compute and storage as primary inputs. Single-source vulnerability in specialized regulatory taxonomy databases creates switching costs that lock institutions into incumbent platforms. Distribution runs through direct enterprise sales for tier-one banks and API-embedded widgets for mid-market fintechs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbent platform vendors face substitution pressure from banking-as-a-service providers embedding compliance widgets, forcing defensive architecture investments to maintain enterprise relationships.
For Market Incumbents: Build data lineage moats through AI-powered traceability engines that span fragmented source systems. Incumbents should acquire emissions calculation specialists to plug CSRD capability gaps before EU enforcement deadlines. Vertical integration into ERP environments via consulting partnerships defends against API-first challengers eroding mid-market share. For New Entrants and Emerging Players: Mid-market fintechs in Singapore and the United States represent the most penetrable entry point for API-embedded compliance widgets. Energy sector verticalization offers adjacent expansion as oil majors deploy Scope 3 tracking modules. A channel partnership strategy with banking-as-a-service platforms bypasses direct enterprise sales cycle barriers. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regtech specialists holding proprietary taxonomy libraries but lacking cloud-native architecture. Long-term viability hinges on consolidation plays that harmonize multi-jurisdiction submission pipelines. Watch for divergence between EU AI Act and SEC climate rule implementation schedules as inflection indicator for platform fragmentation versus unification bets.| Strategic Initiative | Industry Significance |
|---|---|
| Emissions Calculation Module Development | CSRD compliance deadlines in Germany and France force ERP integration investments ahead of enforcement. |
| API-First Distribution Partnership | Banking-as-a-service platforms in Singapore enable mid-market fintech penetration without direct sales overhead. |
| Data Lineage Engine Acquisition | Proprietary traceability capabilities defend against IBM and Oracle in Federal Reserve stress test automation. |
| Cloud-Native Architecture Migration | Elastic capacity for quarterly SEC and ECB reporting spikes displaces legacy on-premise installations. |
| Cross-Border Taxonomy Harmonization | Singapore-London-United States banking consolidation demands collapsed multi-national submission pipelines. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of SEC filings, ECB supervisory data, and MAS technology risk guidelines. Chief risk officers, regulatory technology procurement leads, and compliance architecture specialists provided qualitative input across tier-one banks in the United States, United Kingdom, and Singapore. Bottom-up vendor revenue estimates triangulate against top-down addressable market calculations derived from financial institution IT spending disclosures.
Forecast inputs span deployment model elasticity, jurisdiction-specific regulatory timeline divergence, and vertical adoption patterns across BFSI and energy sectors. Segmentation dimensions include solution architecture, infrastructure location, and buyer sophistication tier. CAGRs emerge from growth rate reconciliation across primary demand indicators and secondary macroeconomic overlays. XBRL automation penetration and ESG disclosure mandate expansion serve as industry-specific demand drivers.
Macroeconomic conditions sit as an overlay; deviation in interest rate trajectories and cross-border banking consolidation velocity would shift the trajectory. Forecasts reflect assumptions about regulatory implementation schedules and technology adoption curves. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Risk Management and Compliance
Global Management Decision Market
Risk Management and Compliance
Europe Sustainable Finance Market
Risk Management and Compliance
Global Credit Risk Rating Software Market
Risk Management and Compliance
United States Governance, Risk and Compliance Platform Market
Risk Management and Compliance
Enterprise Governance, Risk, and Compliance (Egrc) Market
Risk Management and Compliance
Financial Risk Management Software Market
Risk Management and Compliance
NPL Management Market
Risk Management and Compliance
Stress Testing Services Market
Risk Management and Compliance
Risk Analytics Market
Risk Management and Compliance
Risk-Based Monitoring Software Market
Risk Management and Compliance
Europe Governance, Risk and Compliance Platform Market
Risk Management and Compliance
BFSI Security Market
Risk Management and Compliance
Cyber Security in BFSI Market
Risk Management and Compliance
Disclosure Management Market
Risk Management and Compliance
Certificates Market
Risk Management and Compliance
Global Strategy Consulting Market