
 Fraud Detection and Prevention (FDP) Market | 2026-2036
Fraud Detection and Prevention (FDP) Market Size, Share, and Industry Trends Forecast 2026-2036
Fraud Detection and Prevention (FDP) Market Analysis
PCI DSS Level 1 certification is redrawing competitive boundaries in enterprise fraud prevention, elevating compliance costs for new entrants while favoring established platforms. ACI Worldwide leverages its real-time payment rail integrations to sustain dominance in high-velocity transaction screening. IBM anchors its position through hybrid cloud architectures that span on-premises legacy cores and elastic cloud workloads. Socure differentiates via AI-native identity verification that reduces synthetic fraud exposure for digital-native lenders.
Fraud detection and prevention encompasses systems that analyze behavioral patterns, device fingerprints, and transactional anomalies to intercept unauthorized financial activity before settlement completes. These platforms employ sub-100-millisecond inference latencies and ensemble models combining rules engines with gradient-boosted classifiers to flag suspicious events without degrading customer experience. Machine Learning and Artificial Intelligence segments command the deepest R&D investment as supervised and unsupervised algorithms displace static rule sets in card-not-present and account takeover scenarios. Cloud-Based and Software as a Service deployments are expanding fastest among mid-market banks and fintechs seeking elastic capacity without capital-intensive infrastructure, though On-Premises retains stronghold status at tier-one institutions with sovereign data requirements.
The Federal Reserve's FedNow service guidelines, the EU AI Act's risk classification framework for credit decisions, and India's RBI mandates on digital lending transparency are collectively tightening compliance thresholds for fraud platform vendors. These standards shape procurement criteria, forcing explainable model architectures and audit-ready decision trails as non-negotiable features. Stakeholders must monitor how regulatory divergence between Washington, Brussels, and New Delhi fragments certification requirements and influences platform architecture roadmaps.
Market Dynamics
Real-time payment rail proliferation is compressing fraud detection windows from minutes to milliseconds, forcing infrastructure rebuilds across banking cores and merchant acquirers.
Growth Catalysts
- FedNow service expansion:The Federal Reserve's instant payment infrastructure mandates sub-second settlement verification, driving demand for low-latency screening engines among US financial institutions.
- EU AI Act risk classification:Credit decision algorithms now face mandatory explainability requirements, compelling banks to upgrade from black-box models to interpretable ensemble architectures.
- Device intelligence convergence:Behavioral biometrics fused with device fingerprinting creates multi-factor authentication without friction, accelerating adoption among digital-native lenders.
Market Restraints
- PCI DSS Level 1 certification costs:Annual compliance audits and infrastructure hardening impose six-figure minimums, excluding regional banks and emerging fintechs from enterprise procurement pools.
- GPU compute scarcity:Training and inference for large fraud models depends on concentrated semiconductor supply from Taiwan and South Korea, creating capacity bottlenecks during demand spikes.
- Cross-border data localization:India's RBI and China's PIPL impose sovereign storage mandates that fragment cloud architectures and inflate operational complexity for multinational platforms.
Strategic Opportunities
- Embedded finance penetration in Brazil:Underbanked populations and PIX instant payment adoption create greenfield demand for AI-native identity verification among neobanks and retail platforms.
- Regulatory sandbox participation:The UK's FCA and Singapore's MAS offer controlled testing environments for novel behavioral analytics, accelerating time-to-market for explainable model architectures.
- Graph neural network integration:Combining entity resolution with network analysis enables detection of synthetic identity rings and mule account clusters invisible to transactional rules alone.
Industry Challenges
- Adversarial machine learning expertise gap:Defending against model poisoning and evasion attacks requires scarce security researchers capable of red-teaming production inference pipelines.
- Legacy core integration friction:Mainframe banking systems built on COBOL architectures resist API-native fraud orchestration, forcing expensive middleware layers and extended deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fraud Detection and Prevention (FDP) Market |
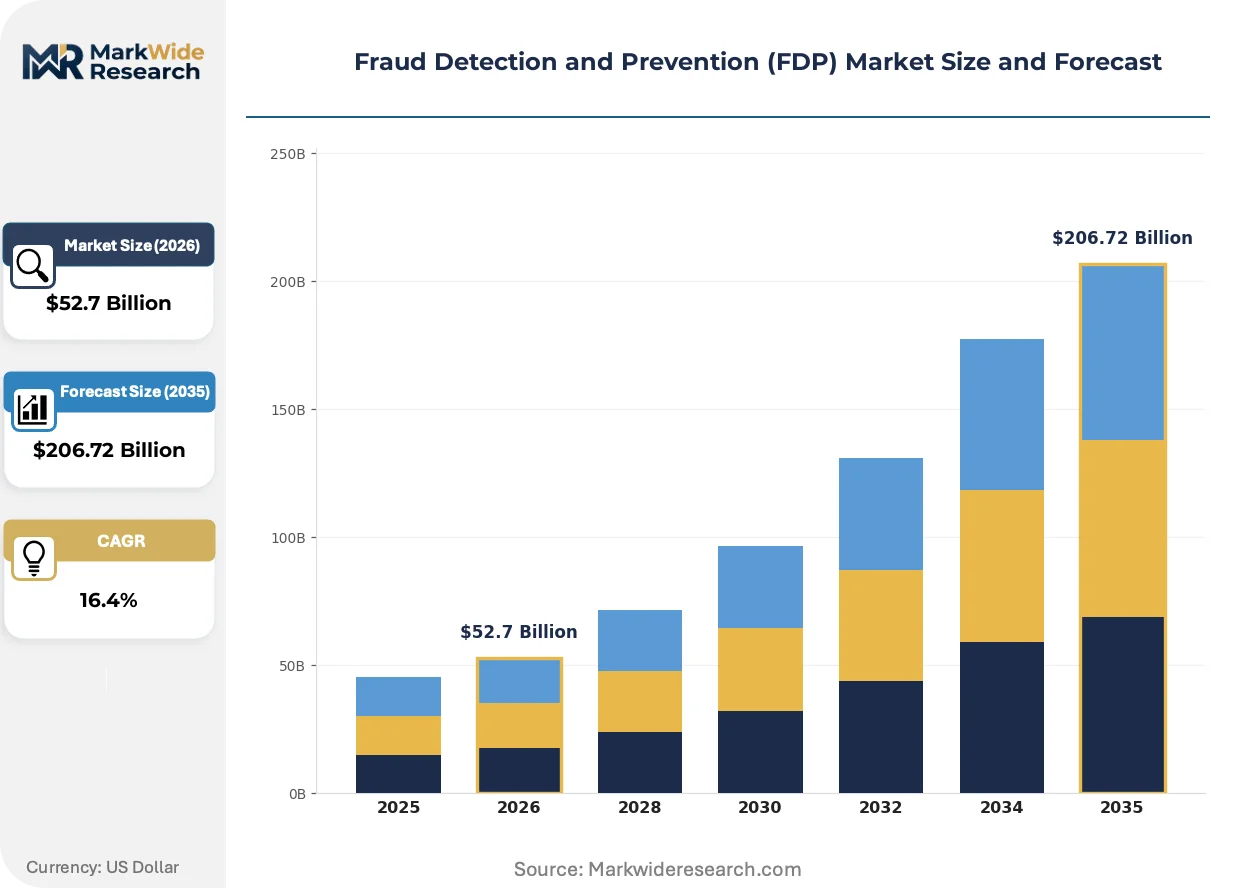
| Market Size in 2026 | $52.7 Billion |
| Market Size in 2035 | $206.72 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Machine Learning, Biometrics, Rules-Based Systems, Artificial Intelligence Deployment: Cloud-Based, On-Premises, Hybrid, Software as a Service End User: Banking, Insurance, Retail, Telecom Service Type: Consulting, Integration, Support, Managed Services |
| Companies Covered | ACI Worldwide, Inc., Oracle Corporation, International Business Machines Corporation (IBM), Sift, Socure, SAS Institute Inc., NICE Ltd, Experian, Fair Isaac Corporation (FICO), Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fraud Detection and Prevention (FDP) Market Emerging Trajectories
Ensemble model architectures are fragmenting the competitive landscape as specialized vendors displace monolithic platforms. Three developments are compressing innovation cycles and reshaping procurement criteria.
Graph-based anomaly detection is fragmenting traditional rules-engine dominance. These systems map transactional relationships across entities, exposing coordinated fraud patterns invisible to linear scoring. Tier-one banks in the United States and United Kingdom are deploying graph neural networks for synthetic identity detection. The technology is fragmenting vendor market share by enabling modular, best-of-breed procurement over single-stack solutions.
The EU AI Act's risk-based classification framework is mandating algorithmic impact assessments for credit-adjacent fraud decisions. Vendors must now document training data provenance, model performance across demographic slices, and human oversight protocols. European banks are responding by prioritizing interpretable gradient-boosted models over deep neural networks for high-stakes decisions.
Merchant acquirers are unbundling fraud liability from payment processing, creating standalone underwriting products. This disintermediation pressures legacy platforms that bundled screening with settlement. The shift is most visible in the United States, where vertical software companies seek specialized fraud APIs rather than processor-embedded tools.
Fraud Detection and Prevention (FDP) Market Segmentation
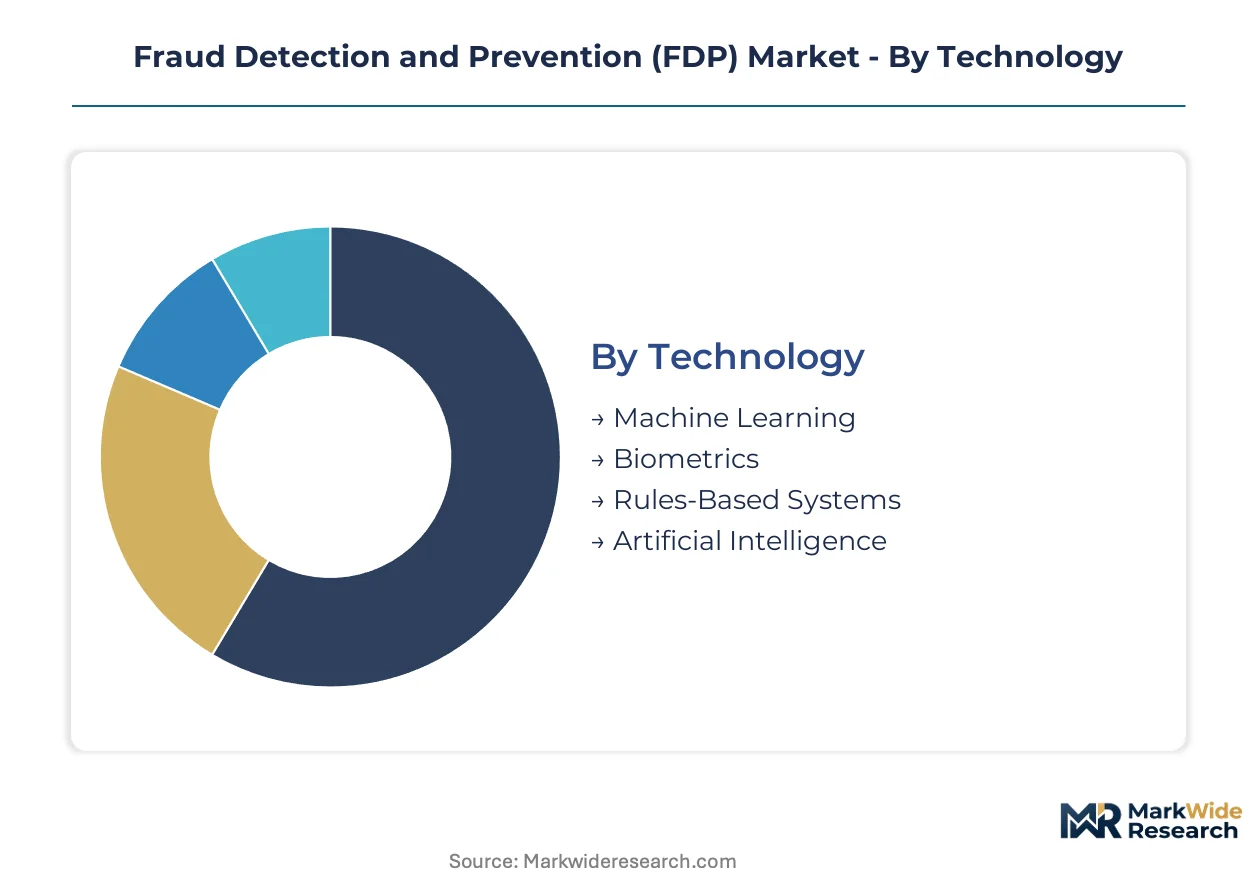
Technology, deployment mode, end-user vertical, and service architecture each channel procurement decisions differently. Banks prioritize real-time inference latency while insurers weight audit trail completeness. Understanding these segment boundaries clarifies where platform vendors must specialize versus where consolidation pressures apply.
Technology:
Technology segments flow through distinct sales channels: ML and AI platforms sell direct to enterprise data science teams, biometrics route through identity verification specialists, while rules-based systems persist in reseller networks serving regional banks.
- Machine Learning:Gradient-boosted classifiers and anomaly detection algorithms process transactional features in sub-100-millisecond windows. US tier-one banks deploy these for FedNow instant payment screening where latency thresholds are non-negotiable.
- Artificial Intelligence:Deep neural networks and transformer architectures power natural language processing for document fraud and synthetic identity detection. Digital-native lenders in India favor AI-native stacks for RBI-mandated digital lending transparency.
- Biometrics:Behavioral and physiological authentication layers.
- Rules-Based Systems:Static threshold engines for legacy core integration.
Rules-based systems dominate installed base. Artificial Intelligence is where expansion concentrates.
Deployment:
Deployment economics stratify sharply: cloud and SaaS offerings carry lower upfront commitments but recurring subscription drag, while on-premises installations demand capital allocation but eliminate ongoing vendor dependency.
- Cloud-Based:Elastic compute provisioning scales inference capacity during transaction volume spikes without hardware procurement cycles. Mid-market fintechs in the United Kingdom favor this model for FCA sandbox participation flexibility.
- Software as a Service:Pre-configured fraud orchestration layers with API-native integration reduce time-to-value for merchant acquirers unbundling liability from processing. US vertical software platforms drive demand here.
- On-Premises:Sovereign data control for tier-one institutions.
- Hybrid:Split architectures spanning legacy cores and cloud burst capacity.
On-premises retains the largest installed footprint. Cloud-based deployments are climbing the fastest.
End User:
End-user concentration determines feature prioritization: banking demands real-time throughput, insurance requires retrospective case reconstruction, retail prioritizes checkout friction minimization.
- Banking:Real-time transaction monitoring across payment rails including FedNow, SWIFT gpi, and card networks. US institutions lead deployment of graph neural networks for synthetic identity ring detection.
- Retail:Merchant acquirers and e-commerce platforms deploy device fingerprinting fused with behavioral biometrics to reduce card-not-present fraud without checkout abandonment. Demand clusters in the United States among marketplace operators.
- Insurance:Claims fraud detection and policy application verification.
- Telecom:Subscription fraud and SIM swap prevention.
Banking commands the deepest technology investment. Retail represents the steepest expansion trajectory.
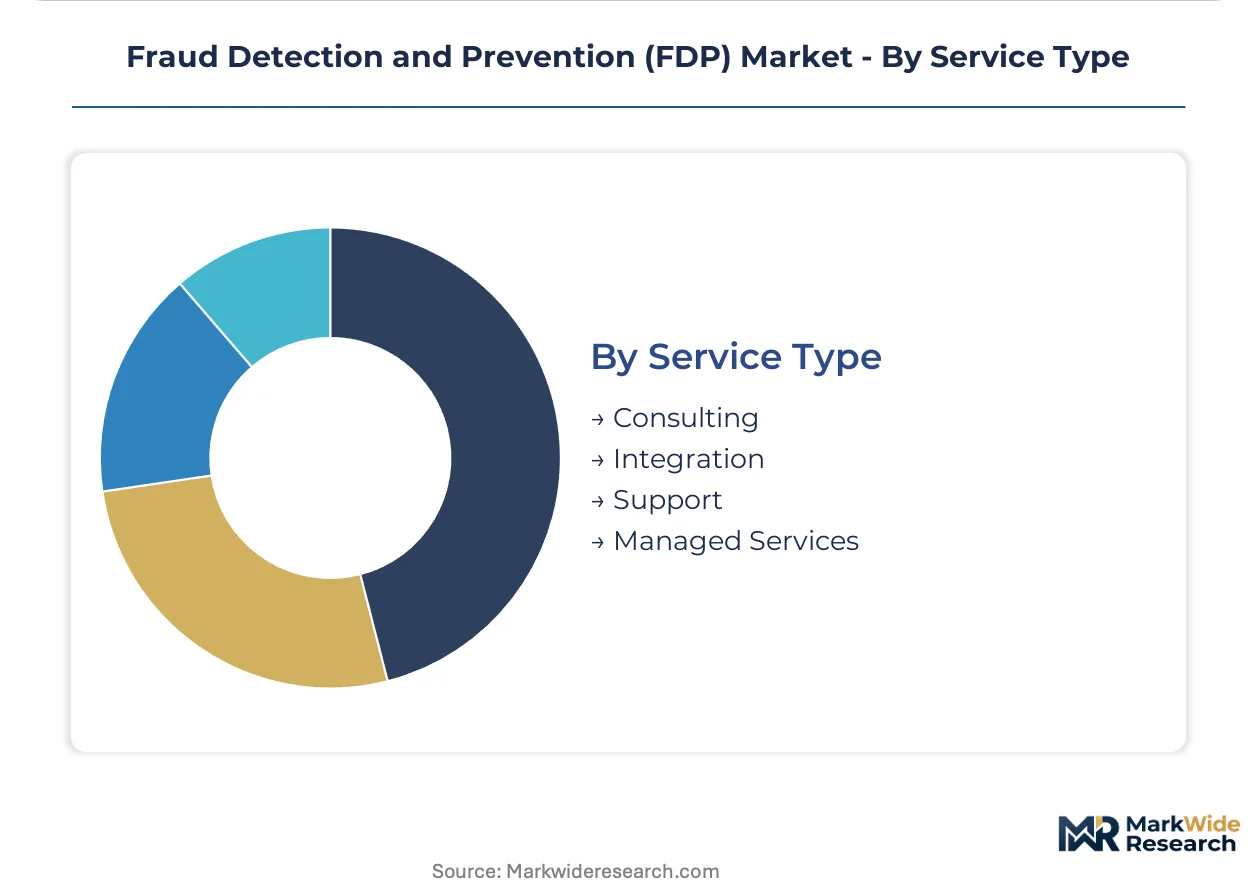
Service Type:
Service margins compress from consulting through managed services as intellectual property yield gives way to labor arbitrage, though recurring revenue stability inverts this preference for vendor valuation.
- Integration:Core banking system connectivity and API orchestration layers bridge COBOL mainframes to modern inference pipelines. European banks facing EU AI Act compliance deadlines drive premium pricing here.
- Managed Services:Outsourced model tuning, alert triage, and false positive reduction. Indian banks leverage these offerings to access scarce adversarial machine learning expertise without direct hiring.
- Consulting:Risk assessment and architecture design engagements.
- Support:Maintenance and incident response contracts.
Support dominates current revenue mix. Managed services is where vendor expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Enterprise procurement of fraud detection platforms concentrates among banking institutions in the United States, digital payment providers in India, and merchant acquirers in the United Kingdom. Regulatory mandates for real-time settlement verification and algorithmic explainability are accelerating infrastructure replacement cycles across these markets.
United States
The Federal Reserve's FedNow instant payment rail mandates sub-second transaction screening, driving tier-one banks toward low-latency inference engines. The SEC and CFPB maintain parallel enforcement on algorithmic fairness in credit decisions. New York and San Francisco host the densest clusters of fintechs deploying AI-native identity verification for digital lending.
United Kingdom
Merchant acquirers and neobanks dominate demand as embedded finance penetration deepens across retail platforms. The FCA's regulatory sandbox accelerates testing of explainable behavioral analytics for high-stakes credit decisions. London's financial technology corridor anchors development of graph neural network architectures for synthetic identity detection.
India
Digital payment volume surges through UPI and RBI-mandated real-time settlement systems, compressing fraud detection windows to milliseconds. The RBI's digital lending transparency guidelines force upgrades to audit-ready decision trails. Mumbai and Bangalore concentrate vendor development centers serving both domestic banks and export markets.
Germany
Automotive and industrial conglomerates drive demand for B2B payment fraud prevention as supply chain digitization accelerates. The EU AI Act's risk classification framework imposes mandatory explainability requirements on credit-adjacent algorithms. Frankfurt's banking cluster and Munich's insurance hub anchor enterprise procurement of hybrid cloud fraud orchestration layers.
Brazil
PIX instant payment adoption among underbanked populations creates greenfield demand for AI-native identity verification. The central bank's open banking mandates expose legacy fraud infrastructure gaps among regional institutions. São Paulo's fintech ecosystem leads deployment of device intelligence fused with behavioral biometrics for card-not-present protection.
Fraud Detection and Prevention (FDP) Market Vendor Landscape
Player mix skews toward established enterprise software vendors with payment rail integrations and emerging AI-native specialists with identity verification focus. Market structure exhibits tiered consolidation: a handful of platform vendors control high-velocity transaction screening among tier-one banks, while dozens of specialists fragment mid-market and regional segments. Dominant competitive moves include M&A to acquire real-time payment certifications and strategic partnerships to bridge legacy core systems with cloud-native inference pipelines.
Within the established platform tier, ACI Worldwide, IBM, and Oracle occupy positions defined by their payment infrastructure heritage and hybrid cloud architectures. ACI Worldwide exemplifies the real-time rail integration archetype. IBM anchors the hybrid deployment model spanning on-premises legacy cores and elastic cloud workloads. Oracle represents the database-to-application stack consolidation play. These vendors compete for procurement decisions where FedNow compliance and PCI DSS Level 1 certification serve as threshold requirements.
| Leading Market Players |
|---|
| ACI Worldwide, Inc. |
| Oracle Corporation |
| International Business Machines Corporation (IBM) |
| Sift |
| Socure |
| SAS Institute Inc. |
| NICE Ltd |
| Experian |
| Fair Isaac Corporation (FICO) |
| Others |
Supply Flow & Price Mechanics
Capacity utilization at GPU foundries in Taiwan and South Korea sets minimum viable scale for fraud model training, concentrating supply leverage among hyperscalers and tier-one banks while compressing margin floors for mid-market SaaS entrants. This scale dynamic cascades through procurement pools, where PCI DSS Level 1 certification acts as a price-segregating threshold that fragments buyer access.
Pricing Analysis
Cost-plus contracts with NVIDIA H100 indexation dominate training infrastructure procurement, anchoring SaaS pricing floors to semiconductor spot markets. Three-tier pricing structure across premium, standard, and economy levels separates FedNow-certified orchestration layers from sandbox-limited APIs and unbundled point solutions. Pricing pressure stems from GPU compute scarcity and foundry concentration, forcing mid-market vendors toward margin compression. Regional banks exhibit highest price sensitivity due to PCI DSS audit burden, while tier-one institutions prioritize latency guarantees over unit economics.
Supply Chain Analysis
Strategic stockpiling of inference accelerators has displaced just-in-time provisioning as lead times for advanced GPUs extend beyond procurement cycles. Taiwan, South Korea, and the United States concentrate foundry capacity and cloud hyperscaler infrastructure. Raw material dependencies center on advanced packaging substrates, high-bandwidth memory modules, and specialized cooling systems. Single-source vulnerability at TSMC's N4 process node creates systemic exposure for model training pipelines. Distribution runs through direct hyperscaler partnerships and certified systems integrators serving regulated financial institutions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Open-source fraud detection frameworks and commodity ML pipelines threaten to commoditize screening layers, forcing incumbents to defend through real-time rail integration and sovereign certification moats.
For Market Incumbents: Fortify PCI DSS Level 1 certification barriers through annual audit automation and hardware security module standardization. Acquire adversarial machine learning talent clusters in Bangalore and Tel Aviv to defend against model evasion. Deepen FedNow integration partnerships before instant payment volume crosses inflection thresholds.
For New Entrants and Emerging Players: FCA regulatory sandbox fast-tracks offer controlled testing pathways for explainable behavioral analytics without full compliance burden. Target Brazil's PIX ecosystem and India's UPI merchant networks where legacy infrastructure gaps create greenfield deployment windows. Lead with device intelligence APIs that bypass core banking integration complexity.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among managed services providers serving Indian banks with outsourced model tuning and alert triage. Long-term viability rests on hybrid cloud orchestration capabilities spanning COBOL mainframes and elastic inference. Watch for EU AI Act enforcement intensity as signal for interpretable model architecture demand inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Real-Time Payment Rail Certification | FedNow compliance mandates sub-second screening latency, elevating technical barriers for new entrants. |
| Adversarial ML Talent Acquisition | Red-teaming expertise scarcity in Bangalore and Tel Aviv concentrates defensive capability among acquirers. |
| Graph Neural Network Integration | Synthetic identity ring detection via entity resolution creates modular procurement demand beyond rules engines. |
| Regulatory Sandbox Participation | FCA and MAS controlled testing accelerates explainable model time-to-market for behavioral analytics. |
| Hybrid Cloud Architecture Expansion | Split deployments spanning legacy cores and burst capacity address sovereign data requirements in Germany and India. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of SEC 10-K filings, ECB payment statistics, and RBI digital lending circulars. Interviews with fraud operations executives at tier-one banks, model risk officers at neobanks, and procurement leads at merchant acquirers were validated against hyperscaler capex disclosures and PCI SSC certification registries. Bottom-up deployment estimates triangulate against top-down payment volume projections.
Segmentation dimensions modeled span technology type, deployment mode, end-user vertical, and service architecture across the analysis window. CAGRs derive from elasticity-adjusted adoption curves weighted by regulatory enforcement timelines. Industry-specific inputs include FedNow transaction velocity assumptions, EU AI Act compliance cost pass-through rates, and UPI merchant onboarding trajectories.
Underlying assumptions cover real-time payment rail proliferation, GPU supply normalization, and regulatory divergence between Washington, Brussels, and New Delhi, with deviation risk concentrated in semiconductor export controls and sovereign data localization mandates. Revision becomes warranted when FedNow transaction volume or EU AI Act enforcement intensity crosses thresholds that alter platform procurement urgency.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Risk Management and Compliance
Europe Strategy Consulting Market
Risk Management and Compliance
Asset Liability Management (ALM) Solution Market
Risk Management and Compliance
UK Anti Money Laundering Solutions Market
Risk Management and Compliance
Cyber Security in BFSI Market
Risk Management and Compliance
BFSI Security Market
Risk Management and Compliance
Stress Testing Solutions Market
Risk Management and Compliance
Europe Strategic Consulting Services Market
Risk Management and Compliance
NPL Management Market
Risk Management and Compliance
Enterprise Governance, Risk, and Compliance (Egrc) Market
Risk Management and Compliance
Asia-Pacific Compliance and Traceability Solutions Market
Risk Management and Compliance
Quality Warranty Management Market
Risk Management and Compliance
Global Compliance Management Software Market
Risk Management and Compliance
Stress Testing Services Market
Risk Management and Compliance
Medical Device Cyber Risk Quantification Market
Risk Management and Compliance
Treasury and Risk Management Market
Risk Management and Compliance
Global Financial Crime and Fraud Management Solutions Market