
 Singapore Fintech Market | 2026-2036
Singapore Fintech Market Size, Share, and Industry Trends Forecast 2026-2036
Singapore Fintech Market Outlook
Embedded finance infrastructure is fragmenting the traditional banking stack as non-financial platforms integrate lending, payments, and insurance into native user journeys. Wise leverages its multi-currency corridor network to sustain low-cost cross-border settlement for SMEs across ASEAN markets. Grab Financial Group anchors its super-app ecosystem with payment and lending products embedded within ride-hailing and delivery workflows. Nium competes on B2B payment rails, offering licensed issuance and real-time remittance across a growing corridor map.
Singapore fintech encompasses technology-enabled financial services delivered through software platforms, APIs, and mobile interfaces, typically operating under Payment Services Act licensing with requirements for capital adequacy, technology risk management, and anti-money laundering controls; the sector's primary purpose is to reduce friction in fund flows, credit allocation, and risk transfer between consumers, enterprises, and financial institutions. Payment Processing leads transaction volume but faces margin compression as infrastructure commoditizes, while Wealth Management and InsurTech capture higher fee pools by targeting underserved mass-affluent segments with automated advisory and parametric coverage products. Blockchain and AI within the Technology dimension attract the bulk of venture deployment, though Cloud Computing underpins operational scale for nearly every licensed entity.
The Monetary Authority of Singapore shapes market access through its Payment Services Act and Digital Bank licensing frameworks, while the Personal Data Protection Commission enforces data governance standards that constrain customer acquisition tactics and cross-border data flows. The Association of Banks in Singapore coordinates industry standards for API interoperability and open finance data sharing. Stakeholders must monitor how MAS evolves its stablecoin and tokenized securities frameworks, as these rulings will determine which technology architectures gain regulatory legitimacy and which business models require structural overhaul.
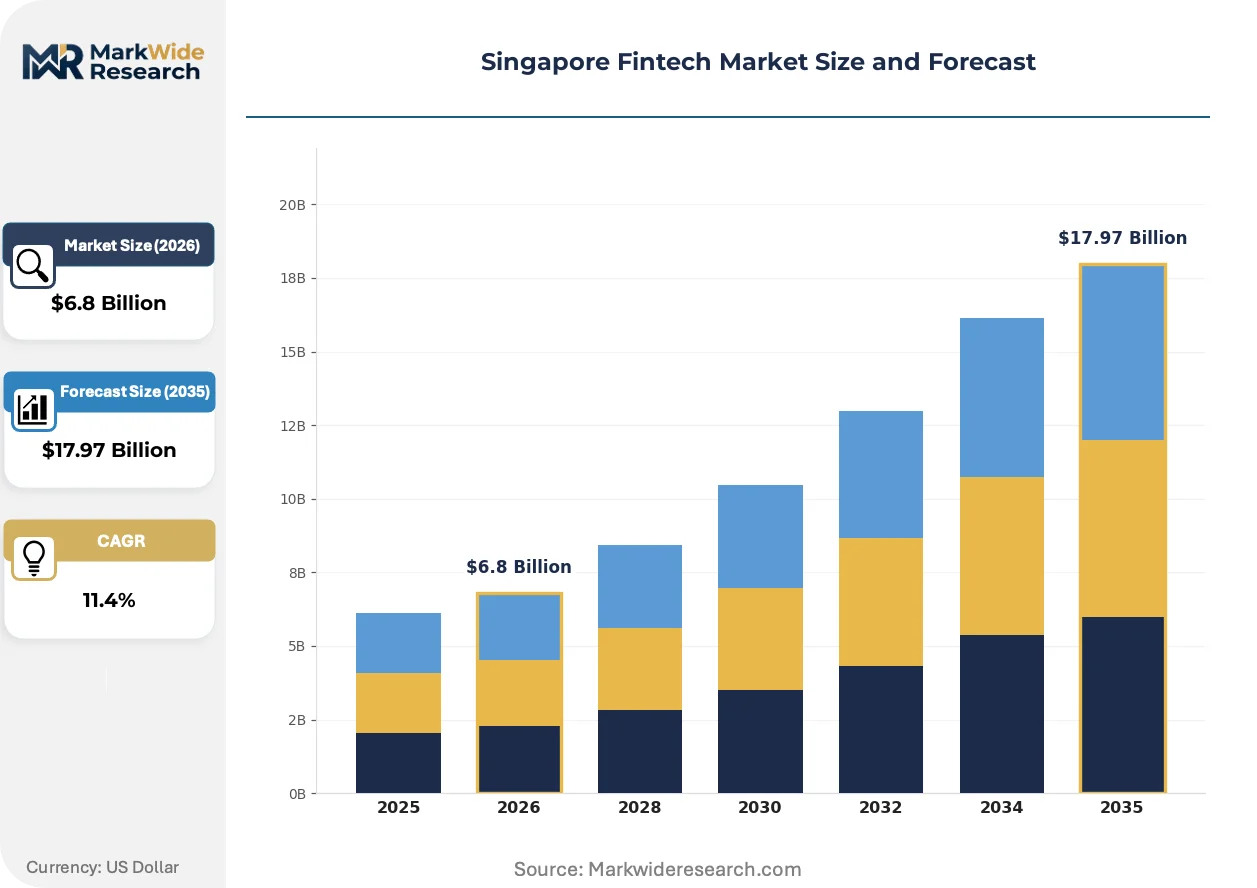
Market Dynamics
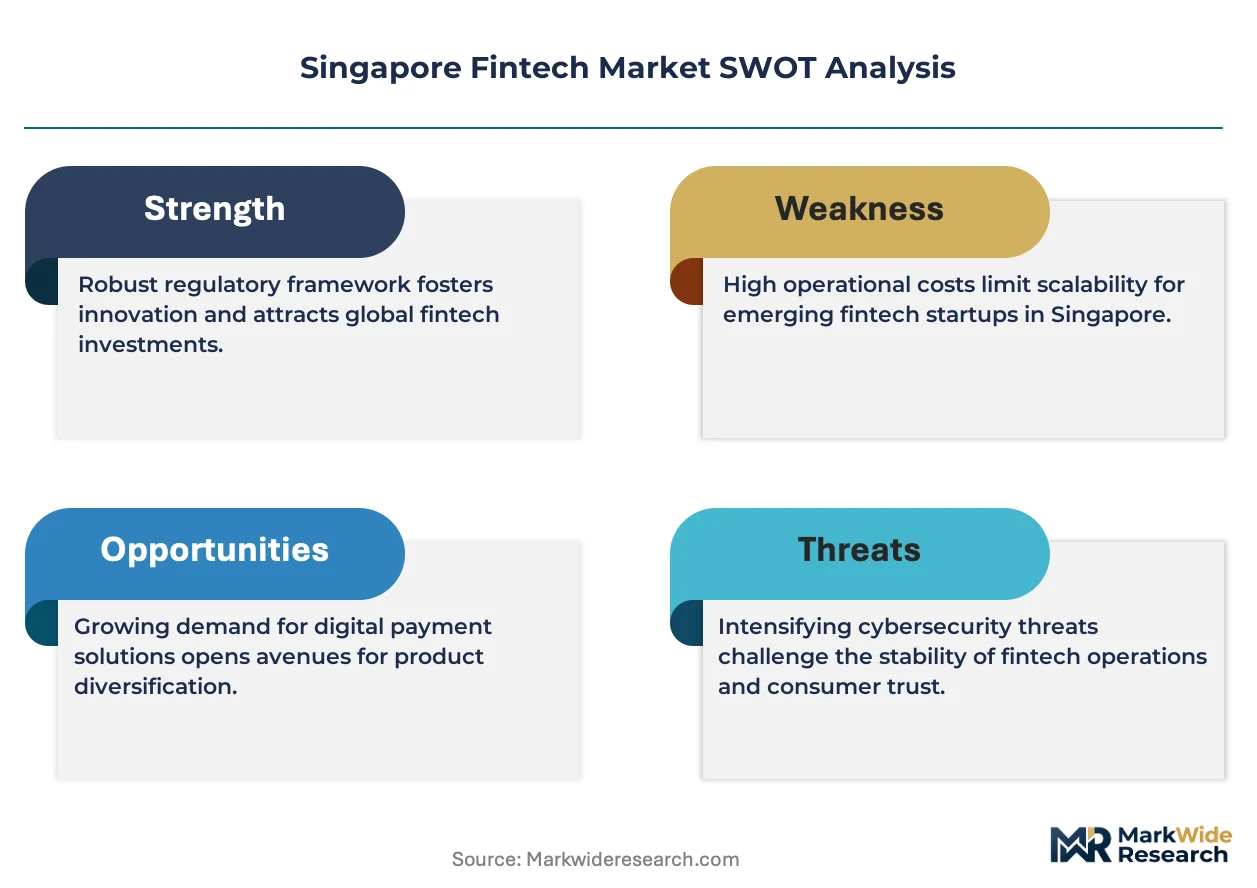
The Payment Services Act administered by the Monetary Authority of Singapore is compressing licensing timelines while elevating capital requirements, forcing unlicensed operators to exit and consolidating market share among entities with compliant technology risk management frameworks.
Growth Catalysts
- Digital Banking Licenses:The Monetary Authority of Singapore's issuance of full digital bank licenses enables neobanks to compete directly with incumbent lenders on deposit-taking and lending products.
- Cross-Border SME Payments:Small enterprises across Southeast Asia are expanding transaction volumes through embedded payment rails integrated into accounting and procurement platforms.
- RegTech Automation:Anti-money laundering compliance software is reducing manual Know-Your-Customer processing costs for Payment Services Act licensees.
Market Restraints
- Capital Adequacy Requirements:The Monetary Authority of Singapore mandates minimum base capital thresholds that constrain early-stage fintech scaling.
- Technology Risk Concentration:Cloud infrastructure dependencies on hyperscale providers create single-point-of-failure exposure for licensed payment institutions.
- Data Localization Friction:The Personal Data Protection Commission's cross-border data transfer restrictions complicate regional headquarters operations serving ASEAN markets.
Strategic Opportunities
- Tokenized Securities Infrastructure:The Monetary Authority of Singapore's evolving framework for digital assets creates white space for licensed custody and settlement providers.
- Parametric Insurance Integration:InsurTech platforms can embed climate-triggered coverage into supply chain finance products for agricultural exporters.
- Wealth Management Automation:Mass-affluent segments remain underserved by automated advisory platforms compliant with the Financial Advisers Act.
Industry Challenges
- Specialized Talent Scarcity:The shortage of professionals combining payment systems engineering with regulatory compliance expertise delays product launches.
- Legacy Core Integration:Banks migrating to open API architectures face middleware complexity when connecting cloud-native fintech stacks to mainframe deposit systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Singapore Fintech Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $17.97 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Payment Processing, Digital Banking, Wealth Management, InsurTech Technology: Blockchain, AI, Mobile Apps, Cloud Computing End User: Consumers, Small Enterprises, Corporates, Financial Institutions Solution: RegTech, Robo-Advisors, Peer-to-Peer Lending, Cryptocurrency Exchanges |
| Companies Covered | Wise, ChainUp, Grab Financial Group, Osome, Thunes, Nium, Stripe, Xendit, Airwallex, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Singapore Fintech Market Strategic Shifts
Embedded finance architectures are dissolving traditional boundaries between financial and non-financial platforms, with software providers across logistics, payroll, and e-commerce verticals building native payment and lending capabilities.
Application Programming Interfaces for real-time account verification and fund transfer are collapsing the distinction between banking infrastructure and enterprise software. Mid-market enterprises in manufacturing and trade finance are adopting these interfaces to automate supplier payments without maintaining direct banking relationships. This convergence is compressing margins for standalone payment processors while expanding addressable revenue for vertical software platforms.
The Monetary Authority of Singapore's stablecoin regulatory framework is establishing reserve backing and redemption standards that exceed regional counterparts. Issuers must hold liquid assets in segregated trusts and maintain minimum capital buffers. Digital payment token service providers are restructuring treasury operations and issuer partnerships to meet these prudential requirements ahead of enforcement deadlines.
Small enterprise finance teams are consolidating vendor relationships by selecting platforms that combine payment execution, foreign exchange hedging, and working capital analytics. Procurement departments previously managing separate banking and treasury software contracts are negotiating bundled subscriptions with fintech infrastructure providers. This consolidation pattern is most pronounced among export-oriented manufacturers with multi-currency receivables across ASEAN markets.
Singapore Fintech Market Segmentation
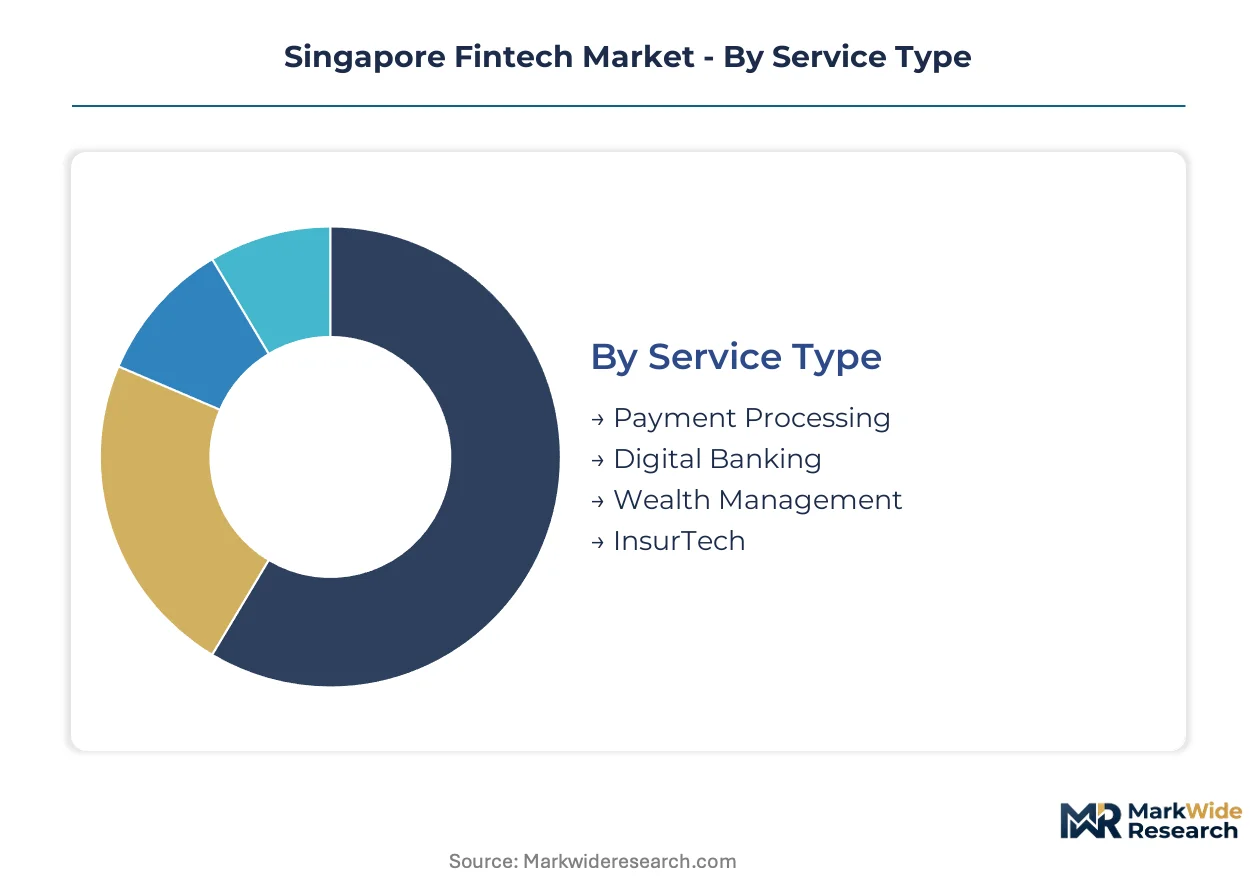
Singapore's fintech landscape fragments across four distinct dimensions that shape how capital deploys and how regulators apply differentiated oversight. Service type captures revenue concentration, technology drives venture allocation, end user determines compliance intensity, and solution type reveals where automation displaces legacy infrastructure.
Service Type:
Cost tier differentiation separates high-volume, low-margin infrastructure plays from advisory and risk-transfer services that command premium economics.
- Payment Processing:Transaction rails handle clearing, settlement, and foreign exchange conversion for retail and B2B flows. Singapore's position as ASEAN's treasury hub concentrates demand from commodity traders and e-commerce marketplaces seeking real-time multi-currency settlement. Infrastructure commoditization compresses per-transaction margins while volume scale sustains platform economics.
- Digital Banking:Full-stack neobanks compete on deposit-taking, lending, and treasury management products under MAS licensing frameworks. Mass-affluent consumers and SME finance teams drive account opening velocity, attracted by native mobile interfaces and faster credit decisioning than incumbent lenders.
- Wealth Management:Automated advisory and portfolio construction tools target underserved segments below private banking thresholds. MAS compliance requirements for the Financial Advisers Act constrain customer acquisition tactics while creating barriers for unlicensed robo-advisory entrants.
- InsurTech:Parametric coverage, embedded distribution, and claims automation reshape risk transfer for consumers and enterprises. Agricultural exporters and logistics operators generate concentrated demand for climate-triggered products integrated into supply chain finance workflows.
Payment Processing commands the established base. The steepest expansion runs through Digital Banking.
Technology:
Application maturity varies sharply across this dimension, with some architectures already operational standards and others awaiting regulatory clarity.
- Blockchain:Distributed ledger infrastructure underpins tokenized securities, stablecoin issuance, and cross-border settlement networks. MAS frameworks for digital assets and payment tokens determine which custody and exchange architectures gain licensed legitimacy. Treasury operations restructuring accelerates as enforcement deadlines approach for reserve backing requirements.
- AI:Machine learning models automate credit underwriting, fraud detection, and anti-money laundering surveillance. RegTech vendors and digital banks deploy these tools to reduce manual Know-Your-Customer processing costs while satisfying MAS technology risk management standards.
- Mobile Apps:Native iOS and Android interfaces serve as the primary customer touchpoint for neobanks, payment wallets, and investment platforms. Super-app ecosystems embed financial services within non-financial workflows, collapsing the distinction between banking infrastructure and consumer software.
- Cloud Computing:Hyperscale infrastructure underpins operational scale for virtually every licensed payment institution and digital bank. Single-provider concentration creates systemic resilience concerns that MAS technology risk guidelines explicitly address through multi-cloud and disaster recovery mandates.
Cloud Computing anchors current operations. The steepest expansion trajectory belongs to Blockchain.
End User:
Customer type determines compliance burden intensity and product complexity requirements across the licensing spectrum.
- Consumers:Individual account holders demand frictionless onboarding, real-time payments, and intuitive mobile interfaces. MAS consumer protection rules and the Personal Data Protection Commission's cross-border transfer restrictions constrain acquisition tactics and data architecture choices.
- Small Enterprises:SME finance teams prioritize consolidated platforms combining payment execution, FX hedging, and working capital analytics. Export-oriented manufacturers with multi-currency ASEAN receivables drive vendor consolidation toward bundled infrastructure subscriptions.
- Corporates:Large enterprise treasury departments require API-native connectivity, multi-entity cash pooling, and sophisticated hedging instruments. Regional headquarters operations in Singapore serve ASEAN subsidiaries while navigating data localization friction from PDPC regulations.
- Financial Institutions:Banks, insurers, and asset managers procure fintech infrastructure for core modernization, distribution partnerships, and regulatory compliance. Legacy core integration challenges emerge when connecting cloud-native stacks to mainframe deposit systems.
Financial Institutions represent the established revenue base. Small Enterprises are climbing the fastest as embedded finance penetration deepens.
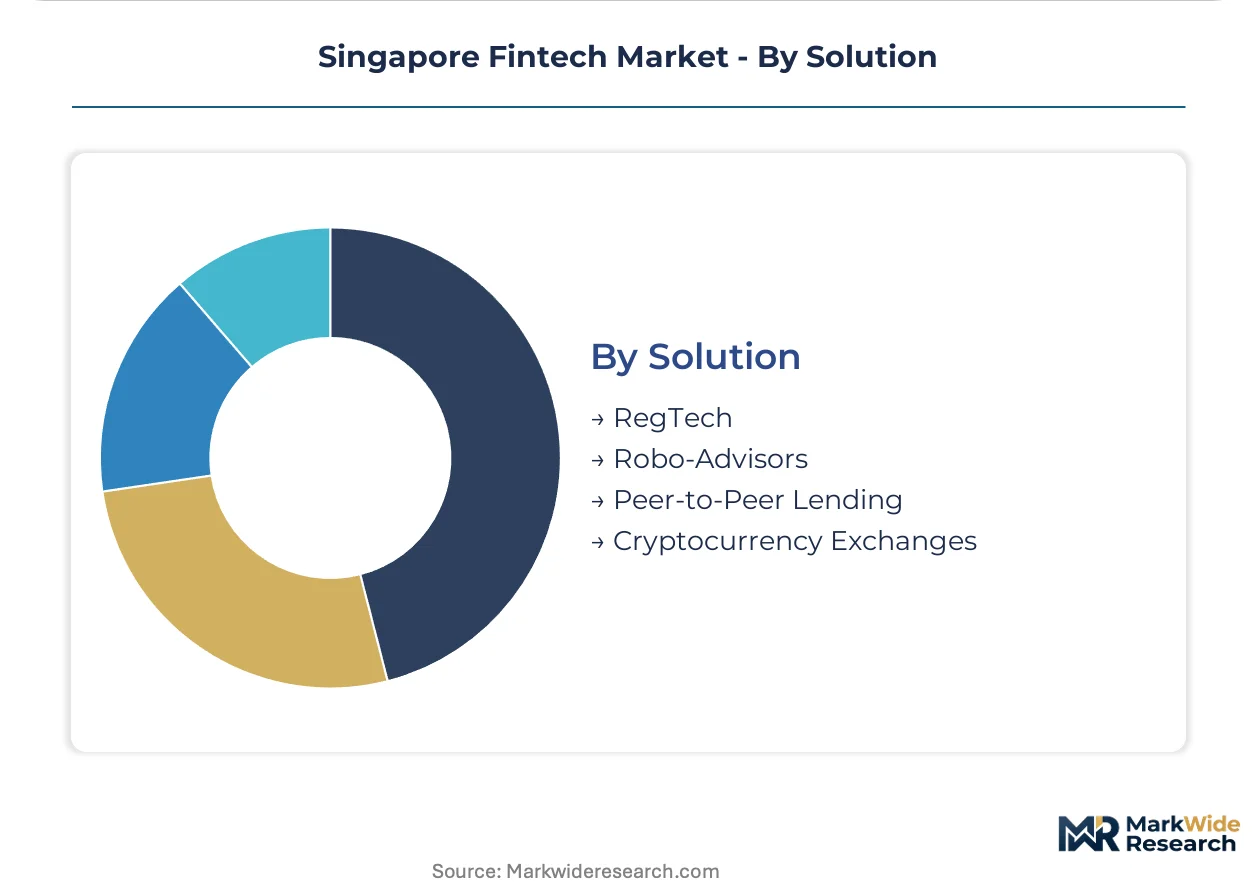
Solution:
Maturity stage separates regulated, licensed offerings from experimental models awaiting supervisory frameworks.
- RegTech:Compliance automation software reduces manual processing costs for AML, KYC, and regulatory reporting obligations. MAS licensees deploy these tools to satisfy technology risk management requirements while compressing operational expenditure.
- Robo-Advisors:Automated portfolio construction and rebalancing platforms target mass-affluent segments with lower account minimums than traditional wealth managers. Financial Advisers Act licensing constraints limit unregulated entrants and protect compliant operators.
- Peer-to-Peer Lending:Direct matching platforms connect borrowers with institutional and retail capital providers outside traditional bank intermediation. MAS licensing under the Securities and Futures Act governs marketplace operators, creating structural barriers to unlicensed scaling.
- Cryptocurrency Exchanges:Digital payment token service providers enable spot trading, custody, and institutional brokerage. MAS stablecoin reserve backing and redemption standards exceed regional counterparts, forcing treasury restructuring ahead of enforcement deadlines.
RegTech holds the established installed base. Cryptocurrency Exchanges are gaining share fastest as tokenized securities frameworks mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-oriented SMEs and mass-affluent retail consumers dominate regional demand, with ASEAN treasury operations and cross-border trade finance driving platform adoption across Southeast Asian markets.
Indonesia
Micro-merchants and agricultural exporters generate concentrated demand for embedded payment and parametric insurance products. Bank Indonesia's QRIS interoperability mandate accelerates digital wallet consolidation. Jakarta anchors fintech infrastructure development, with Surabaya emerging as a secondary hub for supply chain finance platforms serving commodity traders.
Vietnam
E-commerce marketplace sellers and manufacturing SMEs prioritize multi-currency receivables management and working capital analytics. State Bank of Vietnam's sandbox licensing for payment intermediaries attracts regional platform operators. Ho Chi Minh City concentrates venture deployment, while Hanoi hosts regulatory technology vendors serving state-owned bank modernization programs.
Thailand
Cross-border tourism merchants and automotive parts exporters drive demand for real-time settlement and FX hedging tools. Bank of Thailand's PromptPay infrastructure creates API-native payment rails for platform integration. Bangkok hosts regional headquarters for payment processors serving Indochina corridors, with Chiang Mai developing specialized RegTech talent pools.
Malaysia
Islamic finance institutions and palm oil exporters seek Shariah-compliant digital banking and trade finance automation. Bank Negara Malaysia's regulatory sandbox for digital banks enables neobank market entry. Kuala Lumpur anchors ASEAN Islamic fintech development, with Penang hosting B2B payment infrastructure serving electronics manufacturing supply chains.
Philippines
Overseas Filipino Worker remittance recipients and rural micro-entrepreneurs demand low-cost cross-border settlement and mobile-first credit products. Bangko Sentral ng Pilipinas' digital bank licensing framework expands formal financial access. Metro Manila concentrates platform development, while Cebu emerges as a hub for remittance technology serving diaspora corridors.
Singapore Fintech Market Competitive Environment
Channel-controlling players compete with product-specialist players for embedded finance integration partnerships, creating a tiered structure where super-app ecosystems and standalone infrastructure providers occupy distinct competitive positions. The market fragments across three strategic archetypes: cross-border payment corridor operators, vertical software-embedded finance platforms, and licensed B2B payment infrastructure providers. Competitive moves concentrate on API interoperability partnerships and regional licensing acquisitions that expand addressable corridor coverage.
Among Singapore-headquartered operators, Wise exemplifies the cross-border corridor specialist archetype, while Grab Financial Group anchors the super-app embedded finance tier. Nium occupies a position within licensed B2B payment infrastructure, representing the banking-as-a-service model for enterprise treasury operations.
| Leading Market Players |
|---|
| Wise |
| ChainUp |
| Grab Financial Group |
| Osome |
| Thunes |
| Nium |
| Stripe |
| Xendit |
| Airwallex |
| Others |
Value Chain & Pricing Dynamics
Overcapacity in cloud infrastructure across Southeast Asian data centers is compressing hosting costs for Payment Services Act licensees while simultaneously eroding margins for standalone infrastructure providers. This utilization dynamic forces fintech operators to bundle payment execution with treasury analytics and foreign exchange hedging to defend pricing power.
Pricing Analysis
Cost-plus contracts with Singapore Interbank Offered Rate indexation dominate enterprise treasury management agreements. Three-tier pricing structure across premium API tiers, standard SaaS subscriptions, and economy transaction fees separates full-stack digital banks from payment processors from embedded finance enablers. Pricing pressure stems from infrastructure commoditization as hyperscale cloud providers race to capture fintech workloads. SME finance teams exhibit highest price sensitivity, while corporate treasury departments prioritize API reliability over per-transaction cost.
Supply Chain Analysis
Upstream feedstock for fintech infrastructure draws from cloud computing capacity concentrated in Singapore, Malaysia, and Indonesia. Critical inputs include hyperscale server clusters, subsea cable bandwidth, and licensed payment rail connectivity. Single-source vulnerability runs through AWS, Azure, and GCP dominance, creating systemic resilience concerns that MAS technology risk guidelines explicitly address. Distribution runs through API-first platforms embedding financial services into accounting, procurement, and logistics software.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
SME finance team consolidation toward bundled platform subscriptions is shifting buyer power toward vertical software providers with embedded finance capabilities. This concentration pressures standalone payment processors to integrate upstream or accept margin compression.
For Market Incumbents: Build regulatory moats through Digital Bank license utilization and Payment Services Act major payment institution status. Incumbents should deepen API interoperability partnerships with enterprise resource planning vendors to lock in distribution. Cloud-native neobanks threaten deposit-taking franchises through faster credit decisioning. Capacity addition in Indonesia and Vietnam treasury corridors defends corridor coverage against Wise and Airwallex expansion. For New Entrants and Emerging Players: Establish a beachhead in parametric insurance for agricultural exporters, where MAS frameworks remain less prescriptive than banking licenses. White space concentrates in climate-triggered coverage integrated with supply chain finance. The most penetrable segment comprises mid-market manufacturers with multi-currency ASEAN receivables lacking automated hedging tools. Go-to-market should anchor with accounting platform partnerships rather than direct customer acquisition. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among RegTech vendors with multi-year AML compliance contracts. Long-term viability across the projection horizon favors licensed infrastructure plays over unregulated marketplace models. Acquisition targets should combine payment systems engineering talent with existing MAS licensing. The signal to watch is MAS stablecoin framework enforcement deadlines, which will force treasury restructuring and create distressed opportunities among non-compliant issuers.| Strategic Initiative | Industry Significance |
|---|---|
| API Interoperability Partnership | Embedding payment rails into SAP and Oracle ecosystems captures enterprise treasury workflows. |
| Regional Licensing Acquisition | Indonesia and Vietnam payment licenses expand corridor coverage for ASEAN cross-border settlement. |
| Regulatory Technology Investment | Automated KYC processing reduces operational expenditure for Payment Services Act compliance. |
| Parametric Product Development | Climate-triggered coverage integrated with trade finance addresses agricultural exporter demand. |
| Multi-Cloud Infrastructure Migration | Distributed architecture satisfies MAS technology risk management disaster recovery mandates. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of MAS regulatory circulars, PDPC enforcement decisions, and ASEAN central bank payment system reports. Interviews with payment systems engineers, compliance officers at licensed institutions, corporate treasury managers, and API platform architects informed demand-side validation. Secondary sources include Payment Services Act licensing registers, digital bank authorization announcements, and hyperscale cloud provider capex disclosures. Bottom-up transaction volume modeling and top-down GDP-attribution approaches triangulate market size estimates.
Forecast inputs incorporate technology adoption curves across blockchain, AI underwriting, and cloud infrastructure deployment. Segmentation dimensions span service type, technology architecture, end-user category, and solution maturity stage. CAGRs derive from regression analysis against macroeconomic indicators and regulatory event timelines. Industry-specific inputs include MAS stablecoin framework implementation schedules and Digital Bank license utilization rates.
Sensitivities concentrate around MAS stablecoin reserve backing enforcement and PDPC cross-border data transfer ruling evolution. Forecasts reflect assumptions regarding license approval velocity and technology risk management compliance costs. Cross-checking against Monetary Authority of Singapore published fintech licensing statistics is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
FinTech
Cyber Security in Fintech Market
FinTech
Robo-Advisory Software Market
FinTech
Latin America AI in Fintech Market
FinTech
Finance Cloud Market
FinTech
Indonesia Financial Technology Services Market
FinTech
Intelligent Cash Deposit Machine Market
FinTech
China Fintech Market
FinTech
Germany Fintech Market
FinTech
Spend Management Platform Market
FinTech
Smart Advisors Market
FinTech
Global Cloud Financial Close Solutions Software Market
FinTech
AI Finance Market
FinTech
Smart Finance Connectivity Market
FinTech
Europe Fintech Cloud Market
FinTech
US AI in Fintech Market
FinTech
Asia-Pacific Financial Analytics Market