
 Intellectual Property Insurance Market | 2026-2036
Intellectual Property Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
Intellectual Property Insurance Market Insights
A shortage of underwriters trained in patent claim construction is unwinding capacity growth across the specialty lines sector. Munich Re leverages its captive legal analytics platform to price infringement risk with greater granularity. Chubb Limited sustains leadership in enforcement cost coverage through dedicated IP claims units in London and New York. Lloyd's of London competes via syndicate specialization in cross-border trademark disputes.
Intellectual property insurance indemnifies policyholders against legal expenses and damages arising from allegations of patent, trademark, copyright, or trade secret infringement, with policies typically attaching at defense cost thresholds of $1 million or higher and responding to both offensive enforcement actions and defensive liability claims. Patent insurance dominates premium volume given the asymmetric cost structure of US district court litigation, where defense expenditures routinely exceed $2 million per claim through trial. Trademark insurance is expanding fastest among direct-to-consumer brands confronting marketplace counterfeiting on e-commerce platforms. Brokers and agents control the dominant distribution channel, capturing commissions of 15-20 percent on specialty IP placements that require bespoke manuscript wording.
The US Patent and Trademark Office's inter partes review proceedings, the EU's Unified Patent Court framework, and China's National Intellectual Property Administration administrative enforcement pathways are reshaping where policyholders choose to litigate and thus where insurers must reserve defense cost capacity. The US Securities and Exchange Commission's intensified scrutiny of IP asset valuations in SPAC disclosures is prompting D&O carriers to exclude patent-related representations from standalone coverage. Stakeholders must monitor how jurisdictional forum selection in infringement cases alters loss cost development patterns across policy years.
Market Dynamics
Patent litigation volume asymmetry between plaintiffs and defendants is compressing risk appetite across specialty underwriters, forcing carriers to reserve defense cost capacity against unpredictable US district court award schedules while pricing premiums against inter partes review success rates.
Growth Catalysts
- US Inflation Reduction Act:Domestic manufacturing incentives are intensifying IP asset valuation disputes, triggering coverage purchases among reshoring pharmaceutical and clean technology firms.
- E-commerce counterfeiting surge:Direct-to-consumer brands confronting marketplace infringement on digital platforms are expanding trademark insurance attach points.
- Venture-backed startup concentration:Silicon Valley corridor pre-IPO portfolio protection demand is concentrating premium growth in technology transfer coverage lines.
Market Restraints
- Underwriter talent scarcity:A shortage of professionals trained in patent claim construction is unwinding capacity growth across specialty lines.
- Defense cost volatility:US district court litigation expenditures routinely exceed attach point thresholds, eroding loss ratio predictability.
- Forum selection uncertainty:The EU Unified Patent Court framework and China's administrative enforcement pathways are fragmenting reserving methodologies.
Strategic Opportunities
- EU Unified Patent Court:The new pan-European litigation venue creates white space for cross-border enforcement cost products with unified jurisdiction clauses.
- Legal analytics convergence:Integration of machine learning with claims databases enables granular infringement risk pricing for previously uninsurable patent portfolios.
- Embedded distribution:Technology Errors and Omissions carriers are bundling IP riders into core policies through managing general agent channels.
Industry Challenges
- Patent claim construction expertise:Underwriting teams lack sufficient technical depth to assess software and biotechnology patent validity challenges.
- SEC disclosure scrutiny:Intensified examination of IP asset valuations in SPAC filings is forcing D&O carriers to exclude patent-related representations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Intellectual Property Insurance Market |
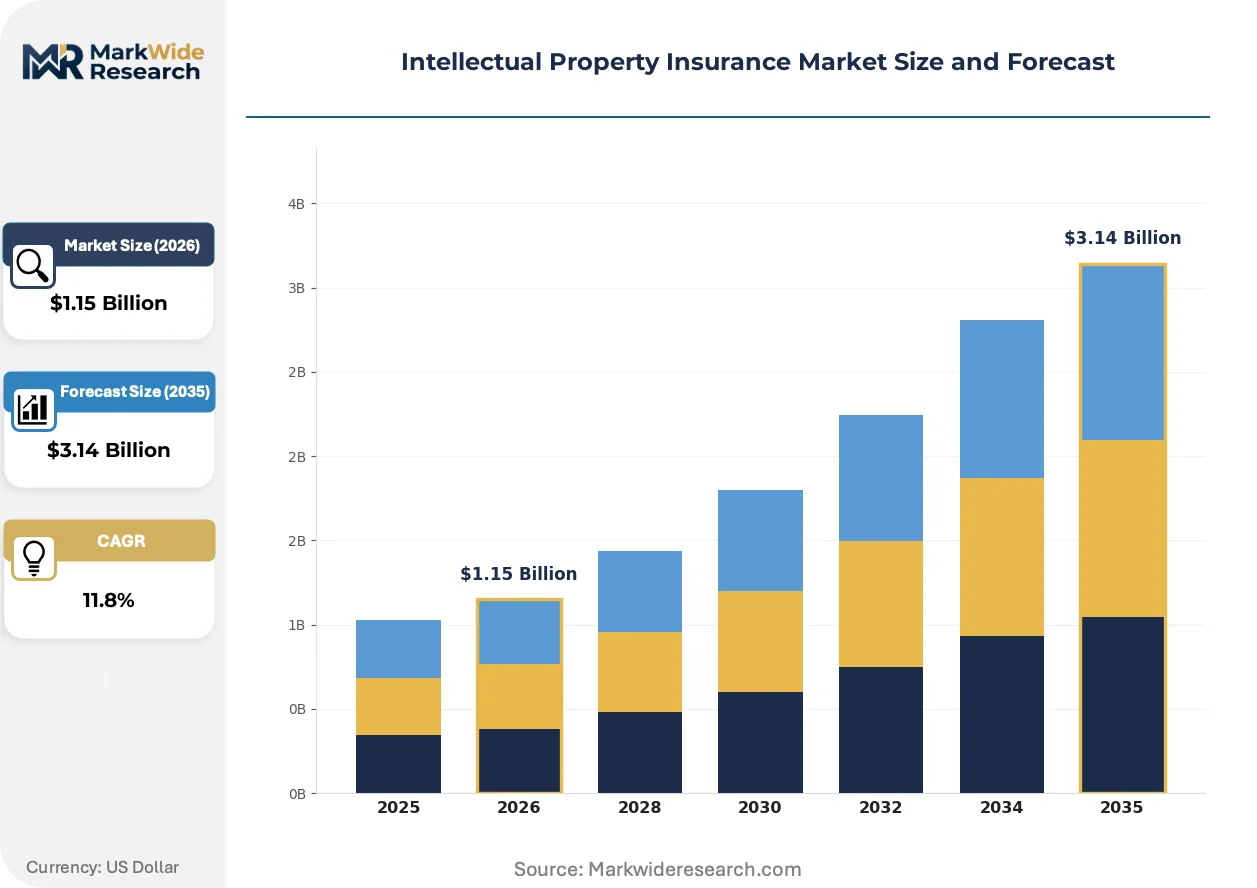
| Market Size in 2026 | $1.15 Billion |
| Market Size in 2035 | $3.14 Billion |
| CAGR (2026 – 2036) | 11.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Policy Type: Patent Insurance, Trademark Insurance, Copyright Insurance, Trade Secret Insurance Coverage Type: Legal Defense, Infringement Liability, Enforcement Costs, Settlement Costs, Royalties Protection End User: Startups, Technology Firms, Manufacturing Companies, Research Institutions, Licensing Agencies Distribution Channel: Direct Sales, Brokers & Agents, Online Platforms, Bancassurance, Corporate Partnerships |
| Companies Covered | AXA XL, Chubb Limited, Allianz Global Corporate & Specialty, Munich Re, Swiss Re, Lloyd’s of London, Tokio Marine HCC, CFC Underwriting, The Hanover Insurance Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Intellectual Property Insurance Market Trends and Innovations
Legal technology platforms are compressing the information asymmetry between insurers and policyholders, enabling real-time litigation outcome modeling that reshapes how defense cost reserves are allocated across policy years.
Embedded patent analytics software is miniaturizing the due diligence cycle for underwriters assessing portfolio risk. Munich Re's captive legal analytics platform ingests claim construction history and inter partes review outcomes to price infringement exposure at the individual asset level. Specialty carriers adopting these tools are compressing quote turnaround from weeks to days for complex technology portfolios.
The US Securities and Exchange Commission's intensified scrutiny of intangible asset valuations is forcing disclosure standardization across SPAC mergers and venture-backed IPOs. This regulatory pressure is extending downstream to D&O underwriters, who now exclude patent-related forward-looking statements from standalone coverage. Technology sector policyholders in California and Massachusetts are responding by purchasing dedicated IP enforcement cost riders separate from management liability towers.
Brokerage commission compression is driving disintermediation experiments in the middle market segment. Managing general agents with captive legal expertise are capturing placement flow directly from venture capital-backed startups, bypassing traditional retail broker networks. This channel shift is most visible in the Silicon Valley corridor, where pre-IPO firms prioritize speed of coverage placement over rate negotiation leverage.
Intellectual Property Insurance Market Segmentation
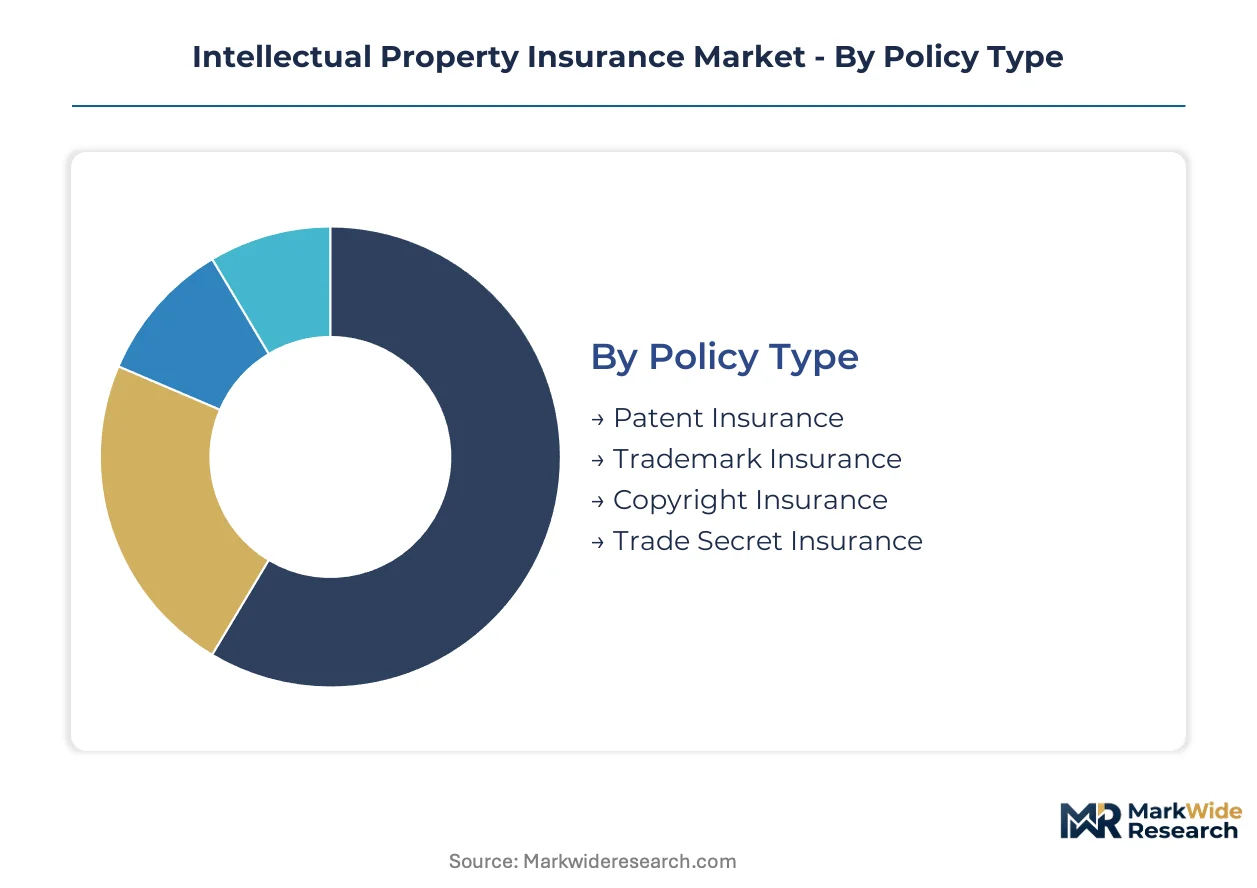
IP insurance segmentation reflects the asymmetric cost structures of different infringement pathways. Patent litigation in US district courts demands defense reserves an order of magnitude above trademark disputes. Regulatory forum selection across the USPTO, EU Unified Patent Court, and China's NIPA reshapes where carriers allocate capital by policy type.
Policy Type:
USPTO inter partes review proceedings and EU Unitary Patent enforcement create divergent loss cost profiles across policy forms.
- Patent Insurance:Policies attach at defense cost thresholds exceeding $1 million and respond to both offensive enforcement and defensive liability claims. Technology firms in California's Silicon Valley corridor concentrate purchases here as pre-IPO portfolio protection against NPE litigation. US district court defense expenditures routinely exceed $2 million per claim through trial, compressing underwriter risk appetite.
- Trademark Insurance:Direct-to-consumer brands confronting marketplace counterfeiting on Amazon and Alibaba platforms are expanding attach points fastest. E-commerce infringement volume asymmetry between platform sellers and brand owners creates predictable enforcement cost structures that carriers price more aggressively than patent portfolios.
- Copyright Insurance:Software code and media content creators in creative clusters purchase coverage against open-source contamination claims. Digital distribution platforms intensify exposure aggregation.
- Trade Secret Insurance:Employee mobility between competing firms in Massachusetts and Texas technology corridors drives demand for misappropriation defense coverage. Economic espionage prosecutions under the Defend Trade Secrets Act shape policy wording.
Patent Insurance handles the majority of premium throughput; Trademark Insurance is climbing the fastest on share.
Coverage Type:
Defense cost volatility in US litigation creates tiered pricing structures that separate premium reserve requirements.
- Legal Defense:Covers attorney fees, expert witness costs, and discovery expenses through trial or settlement. US district court award unpredictability forces carriers to reserve against $2 million-plus exposures per claim.
- Infringement Liability:Responds to damages awards and willful enhancement penalties. Damages caps in certain US jurisdictions fragment reserving methodologies.
- Enforcement Costs:Offensive coverage for patentees pursuing infringers, including filing fees and international coordination. Chubb Limited sustains leadership here through dedicated IP claims units.
- Settlement Costs:Structured settlement facilitation and licensing negotiation expenses. Mediation success rates vary by technology sector.
- Royalties Protection:Secures licensing revenue streams against counterparty default or contract dispute. Pharmaceutical reshoring under the US Inflation Reduction Act intensifies valuation disputes.
Legal Defense commands the dominant share of capacity allocation; Enforcement Costs is expanding most quickly as patentees pursue offensive strategies.
End User:
Customer maturity and capital access determine policy structure complexity and attachment point selection.
- Startups:Venture-backed firms in pre-IPO stages prioritize speed of coverage placement over rate negotiation. Managing general agents with captive legal expertise capture this flow directly in Silicon Valley.
- Technology Firms:Established software and biotechnology companies purchase portfolio-level coverage with manuscript wording. Patent claim construction expertise scarcity limits underwriter appetite for complex portfolios.
- Manufacturing Companies:Reshoring pharmaceutical and clean technology firms under US Inflation Reduction Act incentives trigger coverage purchases as IP asset valuation disputes intensify.
- Research Institutions:University technology transfer offices seek enforcement cost coverage for licensed patent families. Bayh-Dole compliance requirements shape policy terms.
- Licensing Agencies:Non-practicing entities and patent assertion entities concentrate offensive enforcement coverage demand. Forum selection in Eastern Texas or Western District of Wisconsin alters pricing.
Technology Firms represent the largest premium pool; Startups are gaining share fastest as venture deployment concentrates in AI and biotech.
Distribution Channel:
Commission structures and placement velocity create channel conflict between traditional brokers and direct channels.
- Brokers & Agents:Control dominant placement flow with 15-20 percent commissions on specialty IP risks requiring bespoke manuscript wording. Retail networks retain complex technology portfolio business.
- Direct Sales:Carriers bypass intermediaries for Fortune 500 accounts with in-house risk management functions. Lloyd's of London syndicates compete directly for cross-border trademark disputes.
- Online Platforms:Digital distribution experiments target middle-market trademark coverage with standardized wording. Speed of quote delivery compensates for limited customization.
- Bancassurance:Commercial bank referral networks attach IP riders to working capital facilities. Relationship banking models in Germany and Switzerland drive penetration.
- Corporate Partnerships:Technology Errors and Omissions carriers bundle IP riders into core policies through managing general agent channels. Embedded distribution compresses customer acquisition costs.
Brokers & Agents transact the majority of premium volume; Corporate Partnerships is ascending fastest as E&O carriers integrate IP coverage.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply by jurisdiction. US buyers prioritize patent defense against non-practicing entities. European purchasers favor unified enforcement cost coverage. Asian markets emphasize trademark protection against platform counterfeiting.
United States
Venture-backed technology firms and reshoring pharmaceutical companies drive demand. The SEC intensifies scrutiny of IP asset valuations in SPAC disclosures, forcing D&O carriers to exclude patent-related representations. Silicon Valley concentrates pre-IPO portfolio protection purchases.
Germany
Automotive and industrial machinery manufacturers seek enforcement cost coverage for patent families. The EU Unified Patent Court framework reshapes forum selection strategies. Munich anchors specialty underwriter operations serving cross-border disputes.
China
Platform brands confronting e-commerce counterfeiting expand trademark insurance attach points. The National Intellectual Property Administration administrative enforcement pathway offers faster resolution than courts. Shenzhen and Hangzhou cluster direct-to-consumer policyholders.
United Kingdom
Lloyd's syndicates specialize in cross-border trademark disputes and enforcement cost products. The UK's post-Brexit IP regime creates coverage uncertainty for EU patent families. London concentrates broker placement flow for complex manuscript wording.
Japan
Electronics and semiconductor firms purchase portfolio-level coverage against open-source contamination claims. METI guidelines on trade secret management shape policy terms. Tokyo and Osaka anchor technology transfer offices seeking enforcement protection.
Intellectual Property Insurance Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in the IP insurance market. Global reinsurance groups with captive legal analytics platforms command premium pricing power through granular infringement risk assessment. Specialist Lloyd's syndicates and managing general agents compete on placement velocity for venture-backed accounts. Capacity expansion through dedicated IP claims units and strategic partnerships with technology E&O carriers represent the dominant competitive moves.
Within the integrated tier, Munich Re and Chubb Limited exemplify divergent strategic positions. Munich Re leverages its captive legal analytics platform to price infringement risk at the individual asset level. Chubb Limited sustains leadership in enforcement cost coverage through dedicated IP claims units in London and New York. Lloyd's of London occupies a distinct position competing via syndicate specialization in cross-border trademark disputes.
| Leading Market Players |
|---|
| AXA XL |
| Chubb Limited |
| Allianz Global Corporate & Specialty |
| Munich Re |
| Swiss Re |
| Lloyd's of London |
| Tokio Marine HCC |
| CFC Underwriting |
| The Hanover Insurance Group |
| Others |
Pricing and Supply Chain Analysis
Capacity reservation agreements with Lloyd's syndicates and Munich Re lock in defense cost coverage access while stabilizing premium visibility across multi-year policy periods. These structures bind Silicon Valley startups to named underwriters through minimum premium commitments, insulating carriers from spot-market volatility while granting policyholders priority claims unit access.
Pricing Analysis
Long-term manuscript contracts dominate specialty IP placements, with bespoke wording negotiated over 15-20 percent commission structures. Price differentiation hinges on underwriter patent claim construction expertise and dedicated claims unit access, with Chubb and Munich Re commanding premium positioning. Pricing pressure stems from defense cost volatility in US district courts routinely exceeding $2 million per claim. Startups demonstrate highest price sensitivity, prioritizing placement velocity over rate negotiation.
Supply Chain Analysis
Just-in-time underwriting capacity deployment prevails among carriers responding to Silicon Valley pre-IPO demand spikes. Legal talent concentrates in London, New York, and Munich, where patent claim construction specialists anchor dedicated IP units. Raw material dependencies include proprietary litigation databases, captive legal analytics platforms, and inter partes review outcome histories. Single-source vulnerability sits with underwriter talent scarcity constraining capacity expansion. Distribution runs through managing general agents capturing venture-backed placement flow directly.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Intellectual property insurance functions as a service-attach layer expanding faster than underlying technology E&O coverage, with enforcement cost riders and embedded distribution compressing customer acquisition costs for carriers.
For Market Incumbents: Shield portfolio profitability by deepening captive legal analytics capabilities against Munich Re's asset-level pricing granularity. Accelerate dedicated IP claims unit expansion in London and New York to defend Chubb's enforcement cost leadership against syndicate specialization. Patent claim construction expertise scarcity threatens capacity growth; recruit technical underwriters from USPTO examination corps and district court clerkships. For New Entrants and Emerging Players: Lead with EU Unified Patent Court enforcement cost products targeting German automotive and industrial machinery manufacturers seeking unified jurisdiction coverage. White space concentrates in cross-border trademark disputes for direct-to-consumer brands confronting Amazon and Alibaba counterfeiting. Deploy through managing general agent channels embedding IP riders into technology E&O policies. For Investors and Strategic Acquirers: Managing general agents with captive legal expertise and established Silicon Valley venture capital relationships represent the most defensible acquisition archetype. Long-term viability hinges on underwriting talent pipelines and litigation database integration. Watch inter partes review success rate divergence as an inflection indicator for patent insurance loss cost development.| Strategic Initiative | Industry Significance |
|---|---|
| Legal Analytics Platform Integration | Munich Re's captive platform enables asset-level infringement pricing previously unachievable. |
| Dedicated IP Claims Unit Expansion | Chubb sustains enforcement cost leadership through specialized London and New York operations. |
| Managing General Agent Channel Development | Embedded distribution through technology E&O carriers compresses startup customer acquisition costs. |
| EU Unified Patent Court Product Launch | White space for cross-border enforcement coverage with unified jurisdiction clauses emerges. |
| Patent Claim Construction Talent Recruitment | USPTO examination corps and district court clerkships supply scarce technical underwriting expertise. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with specialty underwriters, IP claims unit directors, managing general agents, and venture capital risk managers; and secondary validation through Lloyd's market filings, USPTO inter partes review statistics, SEC SPAC disclosure records, and EU Unified Patent Court procedural documents. Bottom-up policy placement data triangulated against top-down premium pool estimates from regulatory returns.
Across the projection horizon, the analytical framework modeled segmentation by policy type, coverage tier, end-user maturity, and distribution channel complexity. CAGRs derived from historical loss cost development patterns and capacity expansion trajectories. Forecast inputs incorporated patent litigation volume trends, forum selection shifts, and underwriter talent pipeline constraints.
Underlying assumptions cover defense cost inflation stability and jurisdictional enforcement pathway reliability, with deviation risk concentrated in US district court award unpredictability and EU Unified Patent Court operational maturation. Practitioners should keep alternative scenarios live as SEC disclosure scrutiny and reshoring incentive structures evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance
Compulsory Third Party (CTP) Insurance Market
Insurance
India Electronic Gadget Insurance Market
Insurance
France Property and Casualty Insurance Market
Insurance
US Extended Warranty Market
Insurance
United Kingdom Parametric Insurance Market
Insurance
India Health Insurance Market
Insurance
UK Dental Insurance Market
Insurance
Europe Mobile Phone Insurance Market
Insurance
Australia Parametric Insurance Market
Insurance
Art Insurance Market
Insurance
US Homeowner's Insurance Market
Insurance
Global Livestock Insurance Market
Insurance
Spain Parametric Insurance Market
Insurance
Global Flood Insurance Market
Insurance
US Long-Term Care Private Insurance Market
Insurance
Financial Guarantee Market