
 Global Management Decision Market | 2026-2036
Global Management Decision Market Size, Share, and Industry Trends Forecast 2026-2036
Global Management Decision Market Foresight
Modular bundling of decision support tools with risk management modules is restructuring procurement patterns across enterprise buyers. FICO leverages its embedded scoring architectures to sustain dominance in credit-risk decisioning. IBM Corporation anchors its position through hybrid cloud deployments that integrate with legacy mainframe infrastructure. SAS Institute Inc. differentiates via deep statistical computing heritage and specialized vertical analytics.
Management decision systems comprise software platforms that apply algorithmic models, rule engines, and machine learning pipelines to transform structured and unstructured data into actionable operational choices, typically processing inputs through sub-200-millisecond latency thresholds for real-time use cases. These systems serve primarily to reduce cognitive load on human decision-makers while standardizing outcomes across geographically distributed operations. Cloud-based deployment now captures the fastest expansion as enterprises retire on-premises data centers, while decision support systems retain the largest installed base despite slower growth. Predictive analytics commands premium pricing due to specialized talent scarcity in model development and validation.
The EU AI Act imposes conformity assessment requirements on high-risk automated decision systems, compelling vendors to reengineer audit trails and explainability interfaces. In the United States, the SEC scrutinizes algorithmic trading decisions for market manipulation risks, while HIPAA constrains healthcare applications of patient-facing automated recommendations. Stakeholders must monitor evolving liability frameworks that assign accountability between platform vendors and enterprise deployers when algorithmic outputs cause measurable harm.
Market Dynamics
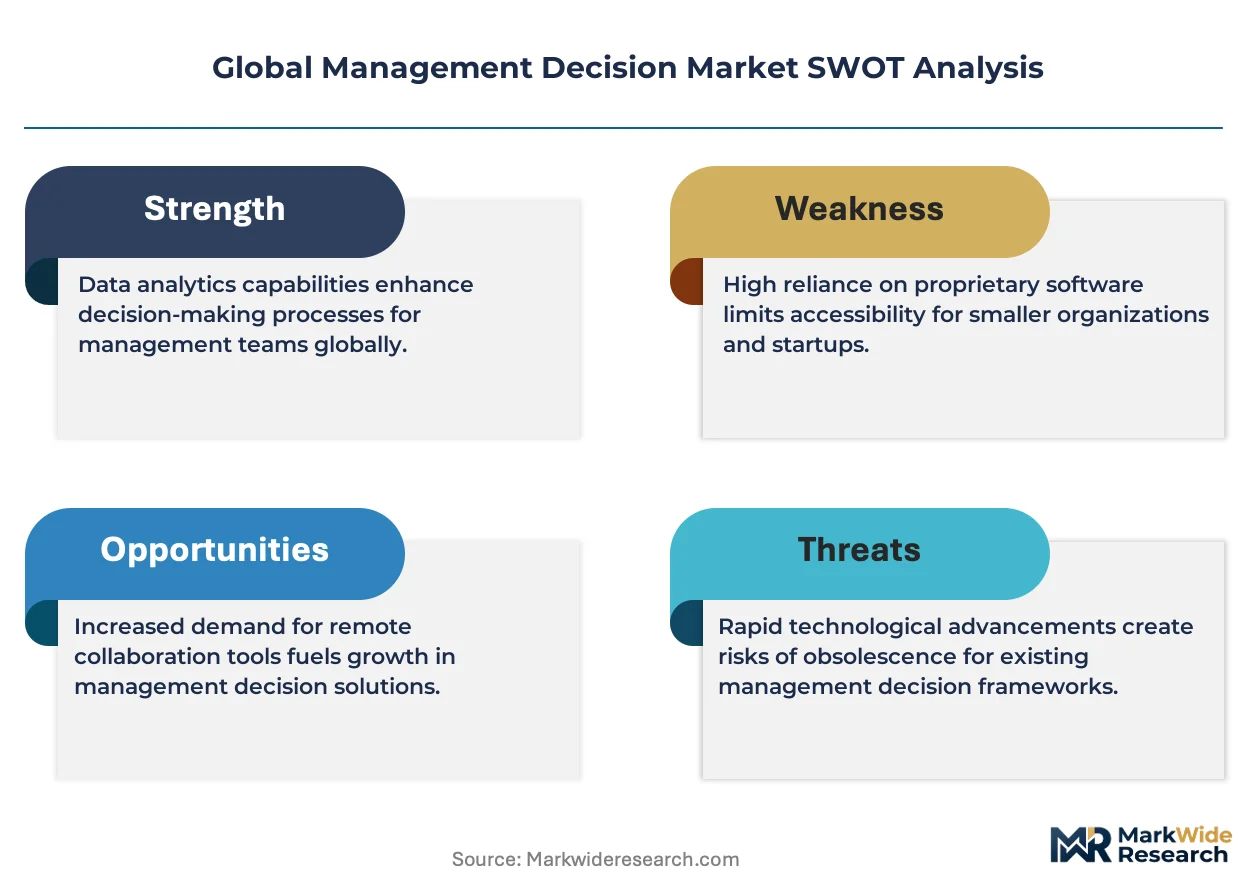
Cloud migration is forcing wholesale architectural redesign as enterprises dismantle on-premises decision engines and reconstitute them as microservices across distributed infrastructure. The EU AI Act's conformity assessment mandates are compressing vendor development cycles while elevating audit-ready explainability from feature to prerequisite.
Growth Catalysts
- EU AI Act compliance deadlines:High-risk system classification is accelerating procurement of audit-trail-enabled platforms across German automotive and French healthcare deployers.
- Real-time latency requirements:Sub-200-millisecond decision thresholds in algorithmic trading and fraud detection are pulling specialized inference hardware into enterprise data centers.
- Industrial predictive analytics:German manufacturers are embedding supply-chain optimization models directly into ERP systems, creating pull-through demand for integrated decision layers.
Market Restraints
- Specialized talent scarcity:Model validation and MLOps engineering command premium compensation, inflating total cost of ownership for predictive analytics deployments.
- Legacy mainframe dependency:Financial institutions in the United States face technical debt from decades-old COBOL decision rules that resist cloud-native refactoring.
- Cross-border data friction:GDPR data-localization requirements constrain multi-tenant SaaS architectures, forcing redundant infrastructure investment across EU member states.
Strategic Opportunities
- Edge inference expansion:Manufacturing facilities in India are deploying localized decision nodes to reduce cloud egress costs and latency for quality-control automation.
- Hybrid cloud arbitrage:Workload portability between private data centers and hyperscale providers enables cost optimization for batch versus real-time decision workloads.
- Explainability-as-a-service:Regulatory pressure from the SEC on algorithmic trading transparency is creating subscription revenue streams for interpretability tooling vendors.
Industry Challenges
- Model drift management:Production ML systems require continuous retraining pipelines that most enterprise IT organizations lack operational maturity to sustain.
- Interoperability fragmentation:Absence of standardized decision-model exchange formats forces costly custom integration between vendor platforms and existing BI infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Management Decision Market |
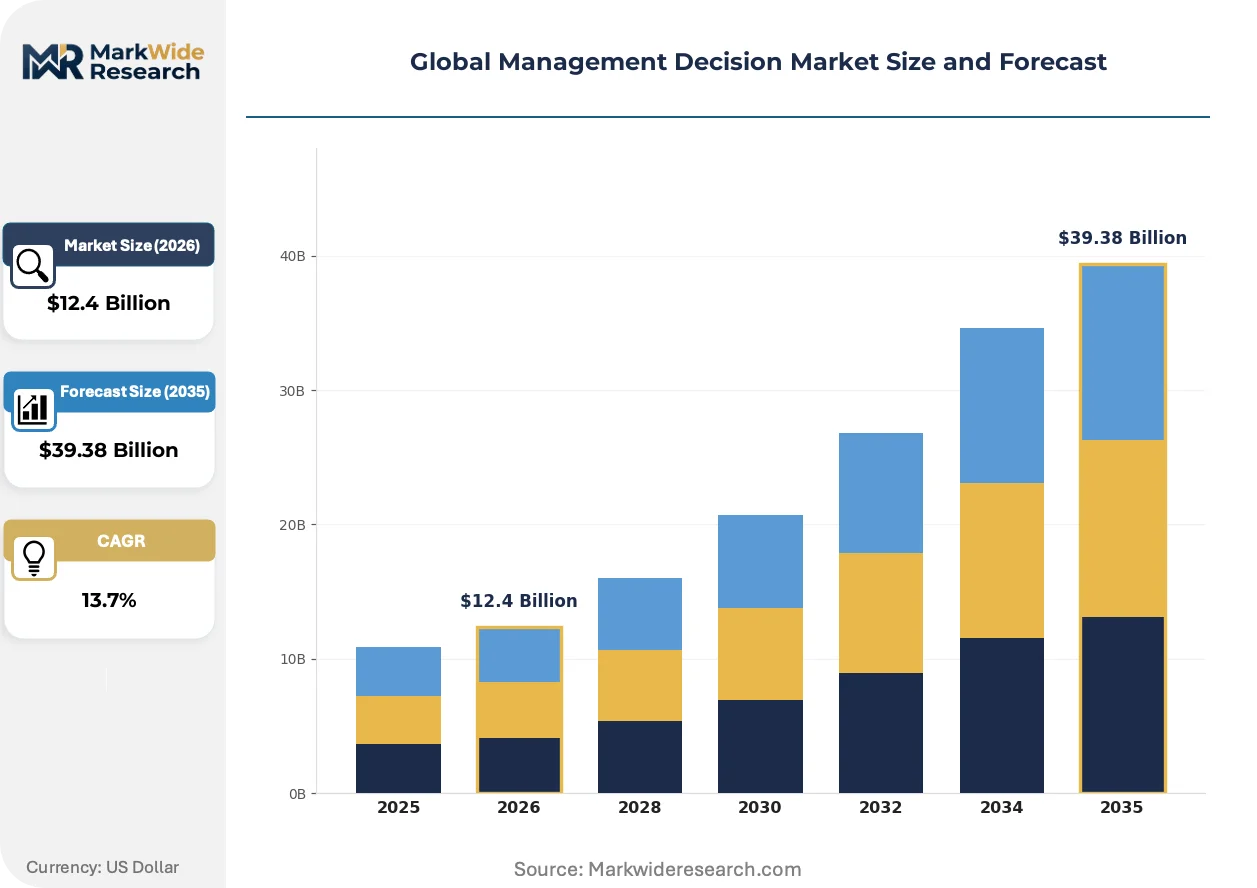
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $39.38 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premises, Cloud-Based, Hybrid, Edge Computing Solution Offering: Decision Support Systems, Business Intelligence, Predictive Analytics, Risk Management Tools, Performance Management Application: Strategic Planning, Operational Efficiency, Customer Insights, Supply Chain Optimization, Fraud Detection End User: Financial Institutions, Telecommunications Providers, Government Agencies, Manufacturing Firms, Technology Companies |
| Companies Covered | FICO, IBM Corporation, SAS Institute Inc., Oracle Corporation, Pegasystems Inc., TIBCO Software Inc., Experian plc, Sapiens International Corporation, Equifax Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Management Decision Market Shifts & Advancements
Decision-system architectures are converging on composable, API-first designs that decouple inference engines from data pipelines. This structural shift is enabling faster substitution of underlying models without wholesale platform replacement.
Retrieval-augmented generation is integrating structured enterprise data with large language model outputs to ground automated recommendations in authoritative source documents. Healthcare providers in the United States are piloting clinical decision support that surfaces citation-backed treatment options. This convergence is compressing the gap between probabilistic predictions and auditable decision rationale.
The EU AI Act's high-risk system designation is forcing vendors to reengineer platforms with built-in conformity assessment documentation. Automated decision systems used in credit scoring and employment screening now require human-in-the-loop override capabilities. French and German deployers are prioritizing vendors with pre-certified technical documentation packages.
Enterprise buyers are consolidating vendor relationships around platforms that bundle decision engines with embedded risk management modules. Financial institutions in the United States are retiring point solutions in favor of integrated suites that unify credit, fraud, and compliance decisioning. This bundling is squeezing standalone analytics vendors without adjacent workflow tooling.
Global Management Decision Market Segmentation
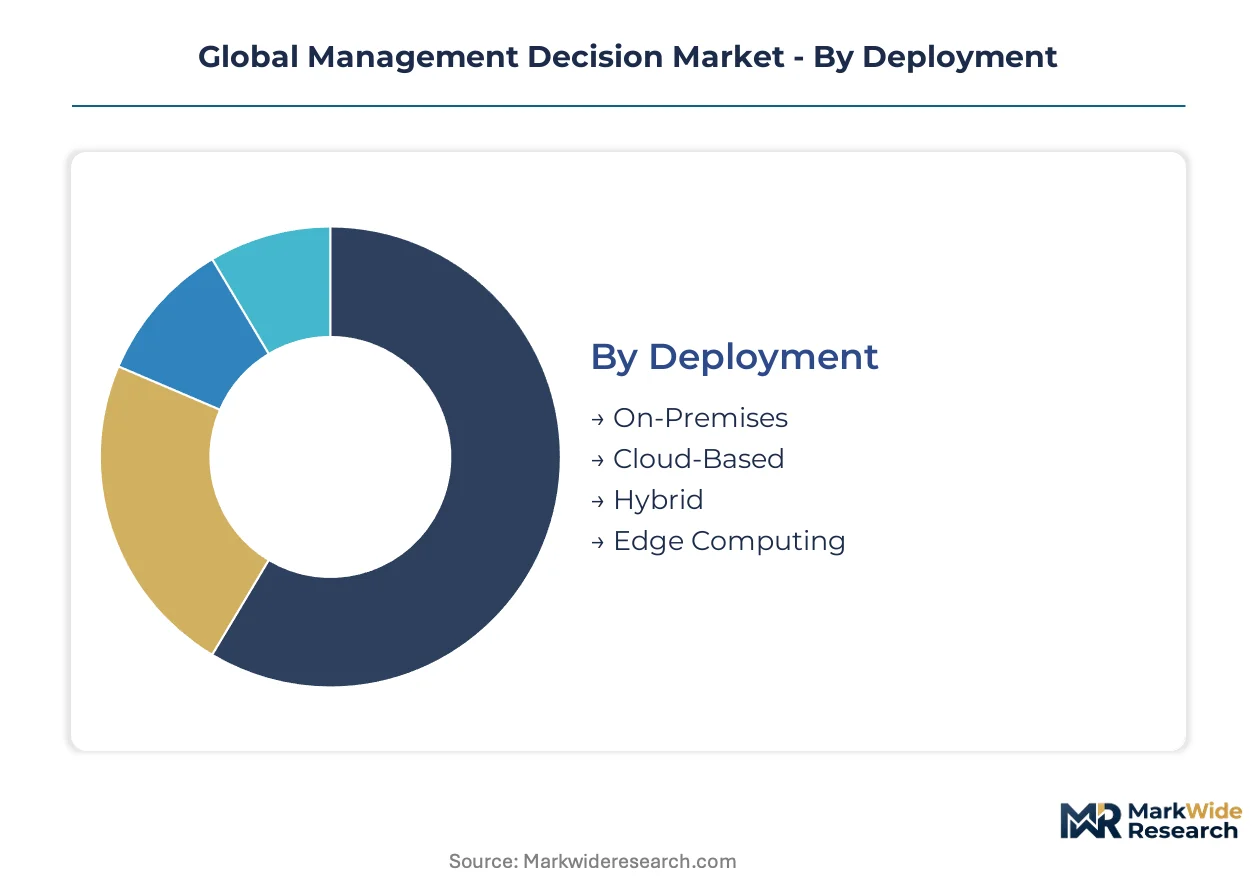
Deployment architecture determines latency thresholds, compliance exposure, and total cost of ownership for management decision platforms. Solution bundling patterns and application specificity further differentiate procurement strategies across enterprise buyers.
Deployment:
Cloud-based architectures demand the heaviest upfront investment in data migration and security reconfiguration, while edge computing requires specialized hardware procurement.
- Cloud-Based:Distributed microservices architectures enable sub-200-millisecond inference latency for real-time fraud detection and algorithmic trading. Financial institutions in the United States are dismantling on-premises data centers to capture elastic scaling benefits, though GDPR data-localization requirements force redundant EU infrastructure investment.
- Hybrid:Workload portability between private data centers and hyperscale providers optimizes cost for batch versus real-time decision workloads. German automotive manufacturers favor this model to keep sensitive supply-chain data on-premises while bursting compute to cloud for demand forecasting.
- On-Premises:Legacy COBOL decision rules in U.S. financial institutions resist cloud-native refactoring due to decades of technical debt accumulation.
- Edge Computing:Localized inference nodes reduce cloud egress costs for quality-control automation in Indian manufacturing facilities.
Most installed capacity flows through Cloud-Based deployment. Expansion is steepest in Edge Computing.
Solution Offering:
End-use complexity drives pricing differentiation, with predictive analytics commanding premium tiers due to specialized talent requirements.
- Predictive Analytics:Machine learning pipelines for demand forecasting and risk scoring require continuous model retraining infrastructure. German industrial manufacturers embed these capabilities directly into ERP systems, pulling through integrated decision layer demand despite MLOps engineering scarcity inflating ownership costs.
- Decision Support Systems:Rule engines and algorithmic models reduce cognitive load on human decision-makers across geographically distributed operations. Healthcare providers in the United States pilot clinical applications that surface citation-backed treatment options through retrieval-augmented generation.
- Business Intelligence:Standardized dashboards and reporting tools retain the largest installed base despite slower growth trajectories.
- Risk Management Tools:SEC scrutiny of algorithmic trading decisions elevates demand for audit-trail-enabled platforms with explainability interfaces.
- Performance Management:KPI tracking and benchmarking modules complete bundled procurement patterns across enterprise buyers.
Predictive Analytics captures the steepest pricing premiums. Decision Support Systems maintain the broadest installed footprint.
Application:
Regulatory intensity varies sharply by use case, with fraud detection facing the strictest audit requirements.
- Fraud Detection:Real-time transaction scoring requires specialized inference hardware to meet sub-200-millisecond latency thresholds. U.S. financial institutions consolidate vendor relationships around platforms bundling fraud decisioning with credit and compliance modules.
- Supply Chain Optimization:Predictive models for inventory positioning and logistics routing embed directly into manufacturing ERP systems. French and German deployers prioritize vendors with pre-certified EU AI Act technical documentation packages.
- Strategic Planning:Long-horizon scenario modeling supports C-suite capital allocation decisions with lower latency sensitivity.
- Operational Efficiency:Process automation and resource allocation algorithms standardize outcomes across distributed facilities.
- Customer Insights:Behavioral segmentation and churn prediction models face GDPR consent management constraints in EU deployments.
Supply Chain Optimization absorbs the most vendor engineering resources for compliance certification. Fraud Detection expands most quickly among regulated financial institutions.
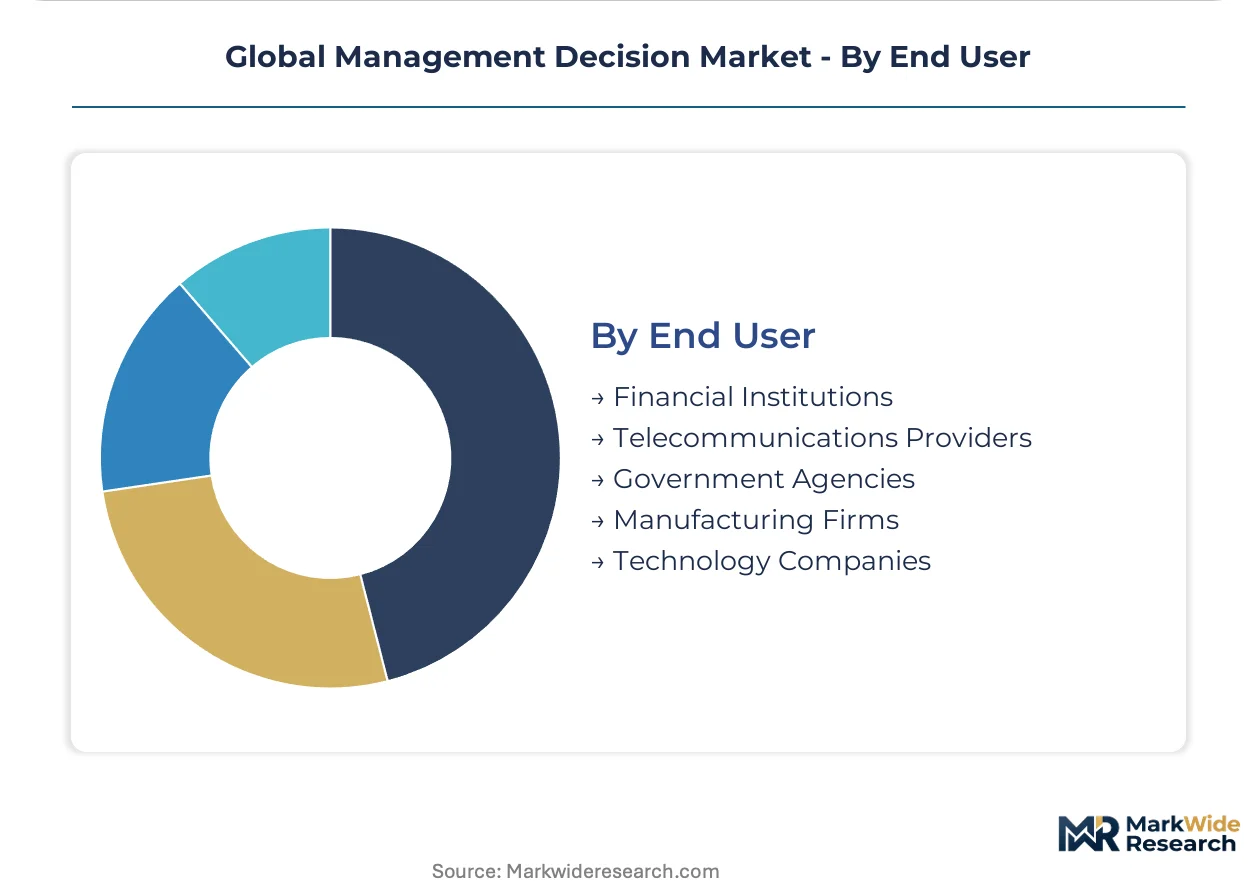
End User:
Procurement sophistication correlates with regulatory exposure, driving tiered vendor engagement models.
- Financial Institutions:SEC algorithmic trading scrutiny and HIPAA healthcare constraints demand audit-ready explainability as prerequisite rather than feature. U.S. banks retire point solutions for integrated suites unifying credit, fraud, and compliance decisioning.
- Manufacturing Firms:German automotive and industrial producers drive predictive analytics demand for supply-chain optimization, embedding models directly into operational technology stacks.
- Government Agencies:Procurement cycles lag commercial sectors due to budget authorization requirements and public transparency mandates.
- Telecommunications Providers:Network optimization and customer retention decisioning require real-time infrastructure at massive scale.
- Technology Companies:Native cloud architecture adoption outpaces legacy industries, enabling faster microservices deployment.
Financial Institutions deploy the most comprehensive audit-trail infrastructure. Manufacturing Firms post the steepest expansion trajectory in predictive analytics procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Decision support systems originated in United States financial institutions during the 1970s, with early credit-scoring algorithms pioneered by Fair Isaac Corporation. Cloud infrastructure and regulatory complexity now drive geographic differentiation across deployment patterns.
United States
Financial institutions dismantle on-premises data centers for elastic cloud scaling. SEC scrutiny of algorithmic trading elevates demand for audit-trail-enabled platforms with explainability interfaces. New York and Chicago trading hubs deploy sub-200-millisecond inference hardware for real-time fraud detection.
Germany
Automotive and industrial manufacturers embed predictive models directly into ERP systems for supply-chain optimization. EU AI Act conformity assessment mandates compress vendor development cycles while elevating documentation requirements. Stuttgart and Munich clusters prioritize pre-certified technical packages from platform vendors.
France
Healthcare deployers pilot clinical decision support grounded in retrieval-augmented generation for citation-backed treatment options. CNIL enforces GDPR consent management constraints on customer-facing automated recommendations. Paris and Lyon healthcare systems demand human-in-the-loop override capabilities for high-risk screening applications.
India
Manufacturing facilities deploy localized edge inference nodes to reduce cloud egress costs for quality-control automation. RBI guidelines on digital lending algorithms create compliance templates for automated credit decisioning. Bangalore and Pune technology corridors accelerate microservices adoption faster than legacy industries.
United Kingdom
Financial services firms consolidate vendor relationships around bundled platforms unifying credit, fraud, and compliance decisioning. FCA conduct rules scrutinize algorithmic outcomes for consumer harm. London fintech clusters drive API-first architectures that decouple inference engines from data pipelines.
Global Management Decision Market Competitive Landscape
Premium-margin players sit above commodity-margin players across explainability depth and audit-trail completeness. The vendor base stratifies into three tiers: established analytics platforms with embedded risk modules, specialized scoring engine providers, and emerging cloud-native challengers. Dominant competitive moves include modular bundling of decision engines with adjacent workflow tooling and hybrid cloud arbitrage partnerships with hyperscale infrastructure providers.
Within the embedded-scoring tier, FICO and Experian plc represent archetypes of credit-risk heritage translated into real-time decisioning infrastructure. IBM Corporation anchors the hybrid-cloud vector through mainframe integration capabilities. SAS Institute Inc. occupies a specialized position rooted in statistical computing depth.
| Leading Market Players |
|---|
| FICO |
| IBM Corporation |
| SAS Institute Inc. |
| Oracle Corporation |
| Pegasystems Inc. |
| TIBCO Software Inc. |
| Experian plc |
| Sapiens International Corporation |
| Equifax Inc. |
| Others |
Supply & Pricing Matrix
MLOps engineering talent scarcity cascades through predictive analytics deployments, inflating subscription tiers for real-time inference platforms while compressing margins on legacy decision support licenses. German automotive manufacturers absorb premium pricing for EU AI Act pre-certified packages, whereas Indian manufacturing facilities prioritize edge computing nodes that slash cloud egress expenditures.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates audit-trail-enabled platforms with human-in-the-loop capabilities from stripped-down rule engines and open-source inference libraries. Price differentiation hinges on explainability depth and latency performance, with sub-200-millisecond thresholds commanding substantial premiums. Cost compression in standard tiers intensifies because hyperscale cloud providers bundle competing decision engines into broader infrastructure contracts. Mid-market financial institutions in the United States exhibit acute price sensitivity, while German industrial manufacturers prioritize compliance certification over unit economics.
Supply Chain Analysis
Refurbished inference hardware flows through secondary markets as financial institutions in the United States retire on-premises data center assets, creating arbitrage opportunities for Indian edge computing deployers. Supply concentrates in Taiwan for specialized GPU fabrication, the United States for cloud infrastructure orchestration tools, and Germany for industrial ERP integration modules. Component dependencies include NVIDIA tensor processing units, ARM-based inference accelerators, and proprietary mainframe connectivity adapters. Single-source vulnerability around Taiwanese semiconductor fabrication threatens continuity for real-time latency-sensitive deployments. Distribution runs through direct enterprise sales teams for premium tiers and hyperscale marketplace listings for standardized cloud offerings.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Quality specifications now dominate procurement criteria as EU AI Act compliance documentation displaces feature-checklist buying. Premium audit-trail capabilities separate viable platforms from commodity alternatives.
For Market Incumbents: Deploy hybrid cloud arbitrage partnerships to defend against hyperscale providers bundling decision engines into infrastructure contracts. FICO and IBM Corporation must accelerate mainframe-to-microservices refactoring to neutralize cloud-native challengers exploiting technical debt in legacy COBOL rule bases. Certification investment in EU AI Act pre-approved documentation packages anchors retention of German automotive and French healthcare accounts. For New Entrants and Emerging Players: Systems integrators with embedded ERP practices offer the most penetrable channel for predictive analytics modules targeting mid-tier manufacturing firms in India. White-space concentration appears in clinical decision support for rural United States healthcare networks lacking citation-backed treatment infrastructure. API-first architectures that decouple inference engines from data pipelines enable faster substitution cycles against entrenched platforms. For Investors and Strategic Acquirers: Consolidation pressure builds where MLOps engineering talent scarcity inflates ownership costs beyond standalone vendor sustainability. Long-term viability favors platforms bundling decision engines with adjacent risk management workflows rather than point-solution analytics providers. Acquisition target archetype: cloud-native challengers with pre-built EU AI Act documentation and established German manufacturing relationships. Watch SEC enforcement actions on algorithmic trading explainability as inflection signal for audit-trail platform valuations.| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Certification Pre-Approval | Accelerates procurement cycles for German automotive and French healthcare deployers. |
| Hybrid Cloud Arbitrage Partnership | Enables workload portability between private data centers and hyperscale providers. |
| Retrieval-Augmented Generation Integration | Grounds clinical recommendations in citation-backed source documents for HIPAA compliance. |
| Edge Inference Node Deployment | Reduces cloud egress costs for quality-control automation in Indian manufacturing. |
| Microservices Architecture Migration | Decouples inference engines from data pipelines for faster model substitution. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with CTOs, IT procurement officers, platform engineers, and integration specialists at financial institutions, automotive manufacturers, and healthcare systems. Secondary validation drew from SEC filings, hyperscaler capex disclosures, EU AI Act regulatory documentation, and hospital procurement databases. Bottom-up deployment modeling and top-down market sizing triangulated volume estimates across cloud, hybrid, on-premises, and edge computing architectures.
Segment-weighting approaches distributed value across deployment models, solution offerings, applications, and end-user industries, with regional adoption patterns and regulatory intensity scoring applied throughout the projection horizon. CAGRs derived from fitted growth curves adjusted for compliance deadline acceleration and cloud migration velocity. Industry-specific inputs included real-time latency requirement penetration, MLOps engineering wage inflation indices, and EU AI Act conformity assessment timeline assumptions.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to SEC enforcement intensity on algorithmic trading transparency and Taiwanese semiconductor supply continuity. Forecasts reflect documented assumptions about cloud migration velocity and regulatory compliance cost trajectories. Practitioners should monitor EU AI Act delegated act publications and hyperscale provider bundling announcements for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Risk Management and Compliance
Asia-Pacific Sustainable Finance Market
Risk Management and Compliance
Compliance As a Service Market
Risk Management and Compliance
Legal Advisory Service Market
Risk Management and Compliance
Anti-Money Laundering (AML) Market
Risk Management and Compliance
Cyber Security in BFSI Market
Risk Management and Compliance
Risk-Based Monitoring Software Market
Risk Management and Compliance
Travel Risk Management Services Market
Risk Management and Compliance
Treasury and Risk Management Application Market
Risk Management and Compliance
Employee Benefits Strategy and Consulting Market
Risk Management and Compliance
Global Liquidity Asset Liability Management Solutions Market
Risk Management and Compliance
Global Financial Crime and Fraud Management Solutions Market
Risk Management and Compliance
Global Asset Integrity Management Market
Risk Management and Compliance
Asia-Pacific Compliance and Traceability Solutions Market
Risk Management and Compliance
Surety Market
Risk Management and Compliance
Southeast Asia Credit and Risk Management Market
Risk Management and Compliance
AI in Fraud Management Market