
 Data Analytics in Banking Market | 2026-2036
Data Analytics in Banking Market Size, Share, and Industry Trends Forecast 2026-2036
Data Analytics in Banking Market Outlook
Mid-tier commercial banks is bifurcating from global systemically important banks as the fastest-growing buyer archetype for analytics platforms. IBM Corporation leverages its Watson portfolio to anchor enterprise-grade deployments across North American institutions. Microsoft Corporation competes through Azure-native analytics stacks that integrate with existing cloud migrations. SAP SE specializes in embedding analytics within core banking ERP workflows.
Data analytics in banking encompasses the systematic extraction, processing, and modeling of structured and unstructured financial data to generate actionable intelligence for credit decisions, operational optimization, and regulatory compliance. The discipline relies on distributed computing architectures, machine learning pipelines, and real-time stream processing to handle petabyte-scale transaction volumes across core banking systems. Predictive analytics and prescriptive analytics command the deepest investment pools as institutions automate lending decisions and dynamic pricing. Cloud-based deployment is displacing on-premises infrastructure fastest among challenger banks and digital-native subsidiaries.
The EU AI Act, GDPR, and the US SEC's climate disclosure rules collectively elevate explainability and auditability requirements for algorithmic banking models. The US OCC and Federal Reserve supervise model risk management through SR 11-7 guidance, forcing banks to maintain documentation trails for every automated decision. Stakeholders must monitor how jurisdictional fragmentation in AI governance reshapes vendor certification requirements and cross-border data residency obligations.
Market Dynamics
Retail banking divisions are accelerating their migration from descriptive reporting to predictive decisioning platforms, forcing infrastructure vendors to rebuild core architectures around real-time inference engines rather than batch-oriented data warehouses.
Growth Catalysts
- EU AI Act compliance mandates:European institutions must deploy explainable credit scoring models by enforcement deadlines, creating immediate procurement windows for audit-ready analytics platforms.
- Challenger bank cloud-native stacks:Digital-first subsidiaries of established banking groups are skipping on-premises entirely, purchasing fully managed analytics-as-a-service from birth.
- Real-time payment modernization:FedNow and instant payment rails in the United States, United Kingdom, and Brazil are generating petabyte-scale transaction streams requiring stream-processing infrastructure.
Market Restraints
- GPU compute cost volatility:Training large language models for fraud detection consumes scarce NVIDIA H100 clusters, with cloud rental rates fluctuating based on hyperscaler capacity allocation.
- Data residency fragmentation:Russia, China, and Indonesia enforce strict data localization laws that prevent cross-border model training, fragmenting vendor addressable markets.
- Model documentation burden:SR 11-7 guidance from US banking supervisors requires exhaustive model risk management paperwork, extending sales cycles by 8-14 months for complex deployments.
Strategic Opportunities
- Embedded finance analytics:Non-bank platforms offering lending, payments, or treasury services lack in-house data science teams, creating white-label analytics demand from fintech infrastructure providers.
- Climate risk stress testing:The US SEC's climate disclosure rules and the EU's CSRD mandate scenario analysis capabilities that most institutions currently lack, opening greenfield procurement for physical risk modeling tools.
- Graph neural networks for AML:Converging graph databases with deep learning architectures enables detection of layered money laundering schemes that rules-based systems miss entirely.
Industry Challenges
- Quantitative talent scarcity:Banks compete with technology firms and hedge funds for PhD-level machine learning engineers, with compensation premiums reaching 40-60% above traditional IT roles.
- Core banking integration complexity:Decades-old COBOL-based transaction engines resist API connectivity, forcing expensive middleware layers that degrade real-time analytics performance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Data Analytics in Banking Market |
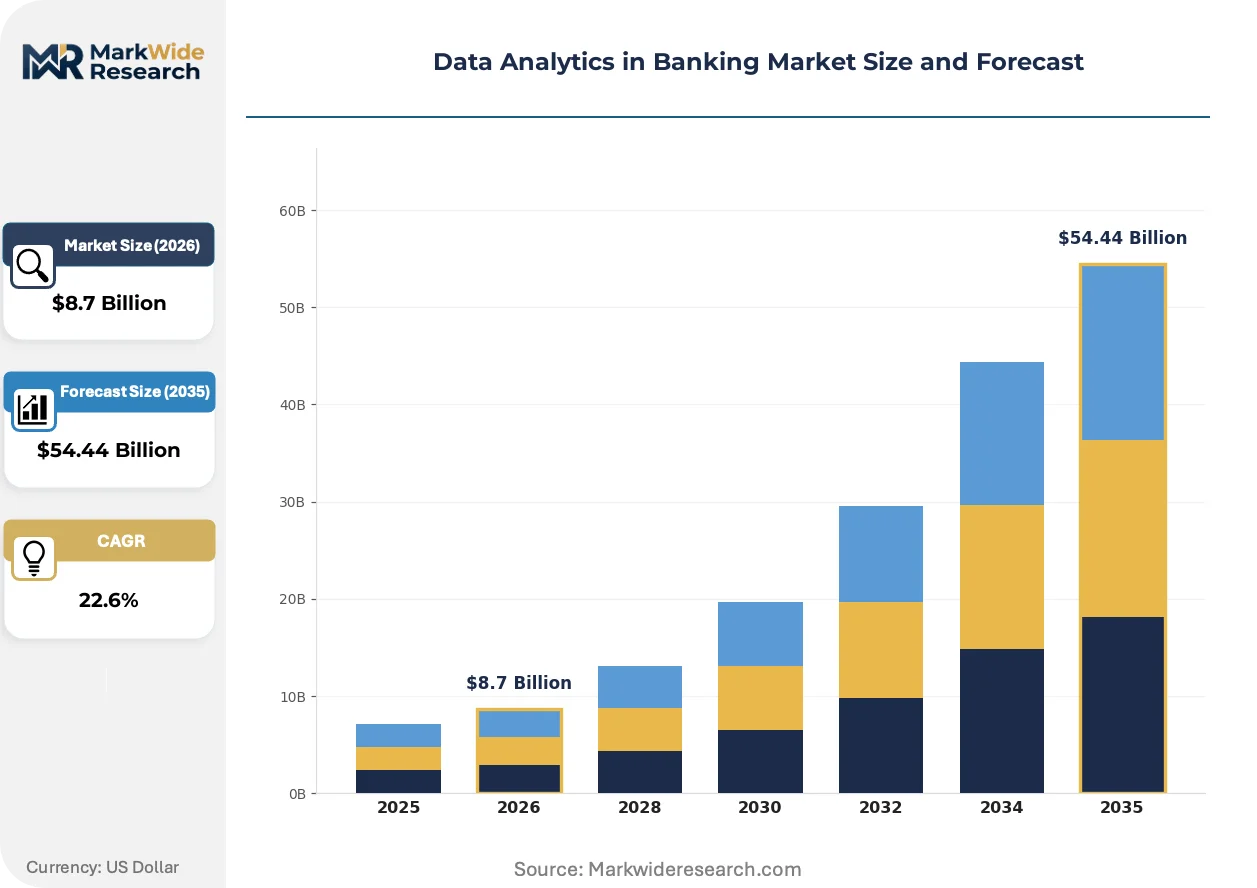
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $54.44 Billion |
| CAGR (2026 – 2036) | 22.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
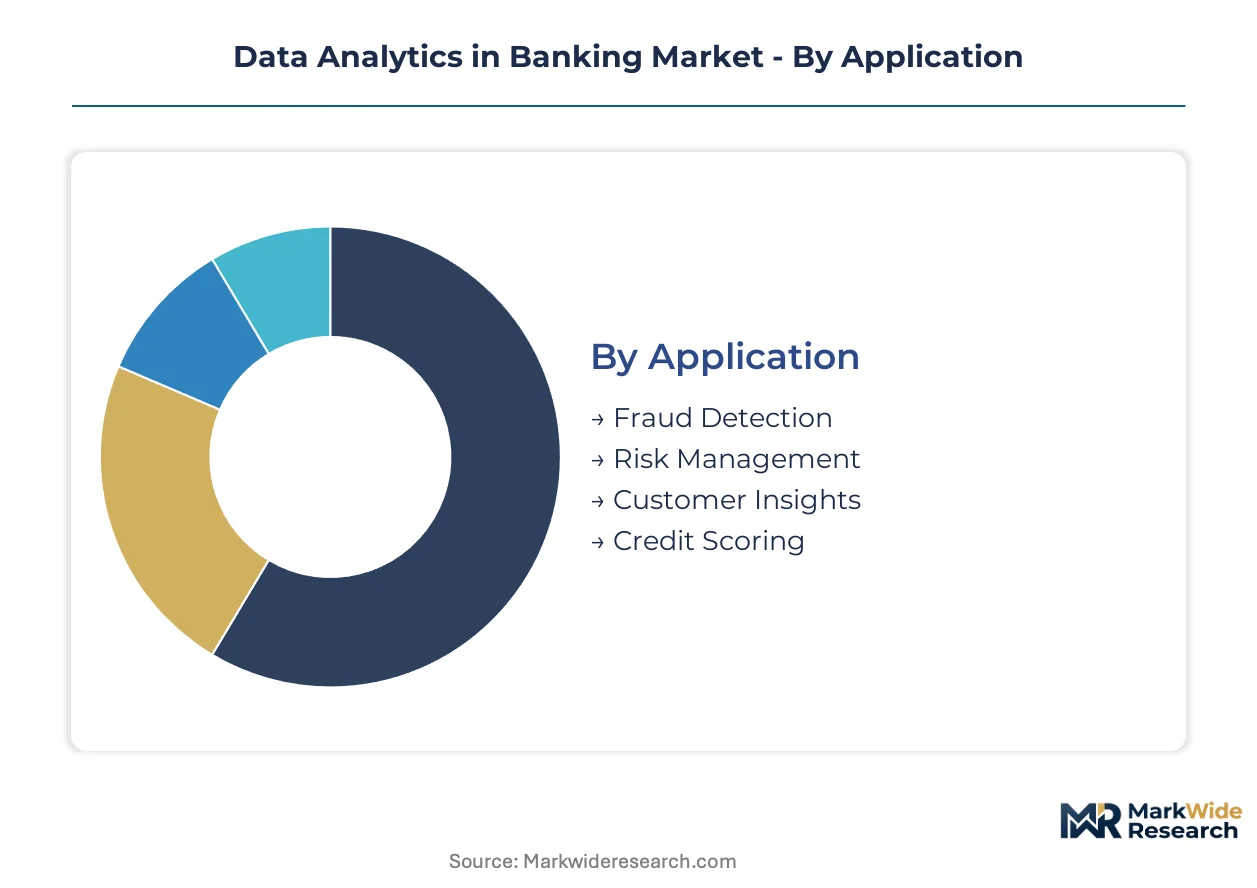
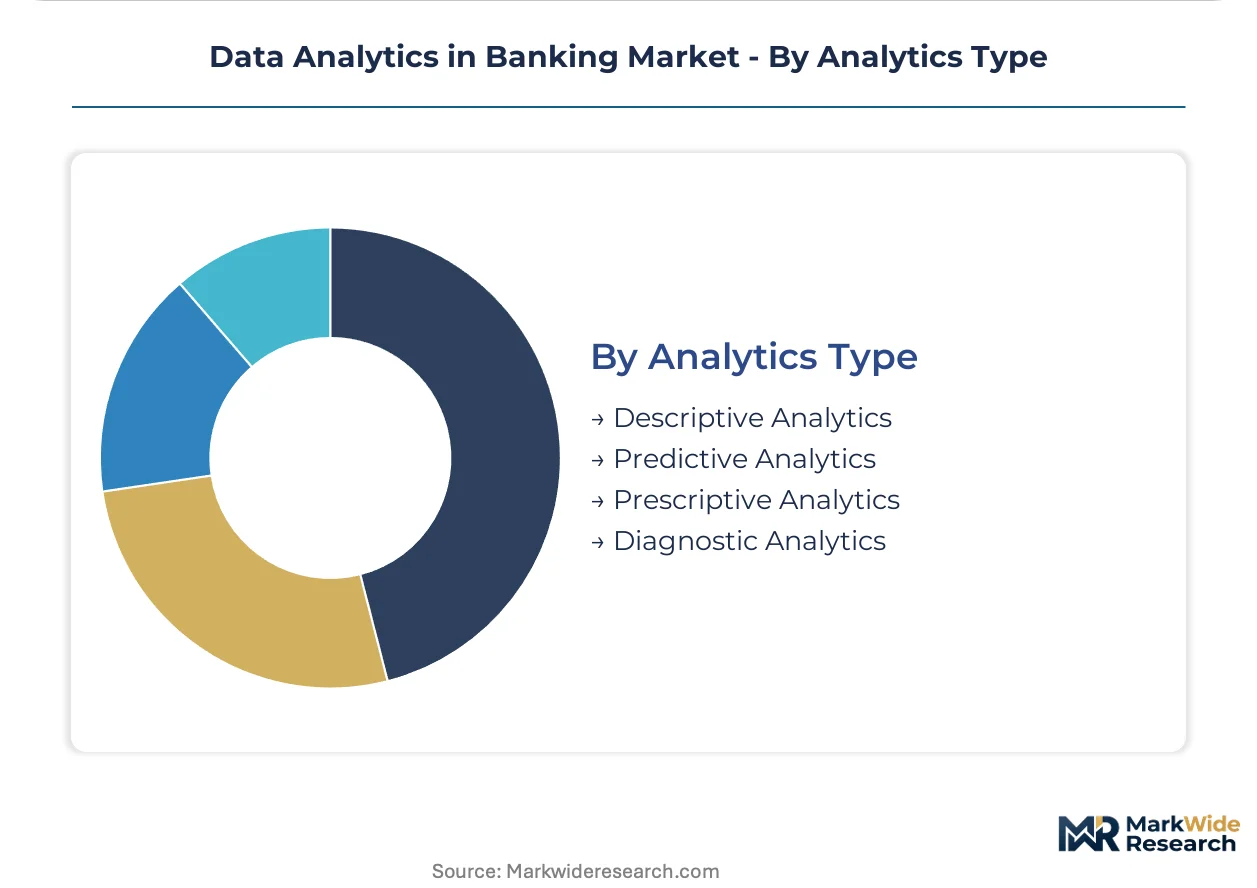
| Segmentation | Application: Fraud Detection, Risk Management, Customer Insights, Credit Scoring Client Type: Banks, Credit Unions, Investment Firms, Insurance Companies Deployment Model: On-Premises, Cloud-Based, Hybrid, Managed Services Analytics Type: Descriptive Analytics, Predictive Analytics, Prescriptive Analytics, Diagnostic Analytics |
| Companies Covered | IBM Corporation, SAS Institute Inc., Oracle Corporation, Microsoft Corporation, SAP SE, FICO, Teradata Corporation, Alteryx Inc., Databricks Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Data Analytics in Banking Market Strategic Shifts
Banking analytics is pivoting from retrospective dashboards to anticipatory systems that intervene before customer attrition or credit deterioration occurs, compressing the latency between signal detection and business action from days to milliseconds.
Feature stores are consolidating previously siloed data preparation workflows into reusable, versioned repositories. Mid-tier commercial banks with limited data engineering headcount are adopting managed feature platforms from cloud providers, collapsing model deployment timelines from quarters to weeks. This architectural standardization is supplanting bespoke ETL pipelines that required custom engineering for each use case.
The EU AI Act's risk-based classification system imposes mandatory human oversight on high-risk credit decisions. Institutions serving European Union markets are retrofitting automated lending engines with "human-in-the-loop" checkpoints, triggering vendor competition around interpretability interfaces. Retail mortgage originators face the steepest compliance burden, as their algorithms directly affect consumer financial access.
Outcome-based contracting is displacing traditional seat-license pricing for analytics software. Procurement teams at United States regional banks now negotiate contracts tied to measurable fraud reduction percentages or customer lifetime value improvements, transferring performance risk to vendors. This shift concentrates vendor selection among providers willing to guarantee operational results rather than merely license technology access.
Data Analytics in Banking Market Segmentation
Segmentation in banking analytics reveals how procurement priorities diverge across institution size, regulatory exposure, and infrastructure maturity. Vendor positioning succeeds only when aligned to specific deployment constraints and compliance obligations within each slice.
Application:
Fraud detection platforms face acute substitution pressure from quantum-resistant cryptographic verification systems, while credit scoring modules confront embedded finance competitors offering algorithmic underwriting as-a-service.
- Fraud Detection:Real-time transaction monitoring employs ensemble machine learning models trained on synthetic identity patterns and mule account behaviors. United States regional banks concentrate procurement here as FedNow adoption expands real-time payment fraud exposure.
- Risk Management:Stress testing engines integrate counterparty exposure metrics with climate scenario modeling for regulatory capital calculations. European institutions under ECB supervision drive demand for audit-ready model documentation.
- Customer Insights:Next-best-action engines analyze behavioral signals across digital channels.
- Credit Scoring:Alternative data ingestion from cash-flow patterns and employment verification APIs.
Risk management retains volume leadership; customer insights holds the steepest expansion curve.
Client Type:
Cost tier stratification separates global systemically important banks with captive engineering teams from mid-tier institutions dependent on vendor-managed infrastructure.
- Banks:Universal and retail banking groups deploy end-to-end analytics stacks spanning treasury, lending, and payments operations. Money-center institutions in the United States rebuild core data lakes to support real-time inference at scale.
- Credit Unions:Member-owned cooperatives prioritize member attrition prediction and loan portfolio optimization within constrained IT budgets.
- Investment Firms:Asset managers and broker-dealers apply natural language processing to earnings transcripts and regulatory filings.
- Insurance Companies:Bancassurance subsidiaries and standalone carriers embed banking analytics for payment-linked policy pricing.
Banks dominate absolute spending; credit unions are expanding most quickly as cloud-native platforms democratize enterprise-grade capabilities.
Deployment Model:
Volume concentration clusters in cloud-native architectures among challenger institutions, while hybrid configurations persist where legacy core banking systems resist full migration.
- Cloud-Based:Fully managed analytics-as-a-service eliminates capital expenditure for data center infrastructure. Digital-first subsidiaries of established banking groups in the United Kingdom and Brazil adopt this model exclusively from inception.
- Hybrid:Sensitive customer data resides on-premises while compute-intensive model training leverages burst capacity in public cloud environments.
- On-Premises:Air-gapped installations serve jurisdictions with strict data localization mandates.
- Managed Services:Third-party operation of analytics infrastructure transfers operational risk to specialized vendors.
Cloud-based deployments command the steepest expansion trajectory; hybrid retains dominant share among incumbent institutions.
Analytics Type:
Maturity gradients separate descriptive reporting installations approaching end-of-life from prescriptive systems generating automated intervention recommendations.
- Predictive Analytics:Machine learning models forecast credit deterioration, payment default probability, and customer lifetime value erosion. Retail banking divisions accelerate migration to these platforms for proactive retention and pricing decisions.
- Prescriptive Analytics:Optimization engines recommend specific actions—interest rate adjustments, credit limit modifications, or collection sequencing—to maximize portfolio returns.
- Descriptive Analytics:Retrospective dashboards and regulatory reporting templates summarize historical performance.
- Diagnostic Analytics:Root-cause analysis tools isolate drivers of portfolio underperformance or operational inefficiency.
Descriptive analytics retains installed base dominance; prescriptive analytics gains share fastest as outcome-based contracting transfers performance risk to vendors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States-based analytics vendors export enterprise-grade platforms to European and Asia-Pacific banking institutions, establishing bidirectional technology flows that concentrate procurement decisions in financial centers with stringent regulatory environments.
United States
Money-center banks in New York and San Francisco are rebuilding core data lakes to support real-time inference at scale. The SEC's climate disclosure rules and OCC SR 11-7 guidance mandate exhaustive model documentation, extending sales cycles for complex deployments. The Charlotte-Raleigh banking corridor anchors domestic demand for fraud detection platforms as FedNow adoption accelerates.
United Kingdom
London-based challenger banks and digital-first subsidiaries adopt cloud-native analytics stacks exclusively from inception. The Financial Conduct Authority's operational resilience requirements intersect with GDPR data governance standards, reshaping vendor certification criteria. The Manchester-Leeds fintech cluster generates concentrated demand for embedded finance analytics infrastructure.
Germany
Frankfurt-based universal banks under ECB supervision drive procurement for audit-ready stress testing engines. The EU AI Act's risk-based classification system imposes mandatory human oversight on high-risk credit decisions, forcing retrofitting of automated lending engines. The Berlin-Brandenburg startup ecosystem anchors adoption of graph neural networks for AML detection.
Japan
Tokyo's megabanks apply natural language processing to earnings transcripts and regulatory filings for investment decisioning. METI's data free flow with trust initiative shapes cross-border model training protocols amid strict data residency considerations. The Osaka-Kobe financial district concentrates demand for prescriptive analytics optimizing portfolio returns.
Brazil
São Paulo-based retail banks accelerate migration to predictive decisioning platforms for proactive customer retention. The Central Bank of Brazil's instant payment rail Pix generates petabyte-scale transaction streams requiring stream-processing infrastructure. The Rio de Janeiro commercial banking corridor adopts outcome-based contracting tied to measurable fraud reduction percentages.
Data Analytics in Banking Market Competitive Environment
Player mix skews toward diversified technology conglomerates with cloud-native portfolios, creating a tiered structure where enterprise-grade deployments concentrate among three strategic archetypes: legacy enterprise software vendors with embedded banking workflows, hyperscale cloud providers with native analytics stacks, and specialized data platform vendors with vertical-specific feature stores. Competitive moves center on outcome-based contracting structures that transfer performance risk to vendors, and strategic partnerships bridging legacy core banking systems with modern inference engines.
Within the legacy enterprise tier, IBM Corporation and SAP SE occupy positions representing opposing integration philosophies—Watson-anchored cognitive deployments versus ERP-embedded analytics workflows. Microsoft Corporation exemplifies the hyperscale archetype through Azure-native stacks that synchronize with institutional cloud migration timelines. These three entities collectively represent the dominant competitive vectors shaping procurement criteria across North American and European institutions.
| Leading Market Players |
|---|
| IBM Corporation |
| SAS Institute Inc. |
| Oracle Corporation |
| Microsoft Corporation |
| SAP SE |
| FICO |
| Teradata Corporation |
| Alteryx Inc. |
| Databricks Inc. |
| Others |
Value Chain & Pricing Dynamics
Outcome-based contracting locks in multi-year analytics platform commitments while transferring performance risk to vendors, binding United States regional banks to fraud-reduction guarantees and European institutions to EU AI Act audit-readiness milestones. This structure compresses price visibility for buyers while securing recurring revenue pipelines for cloud-native infrastructure providers.
Pricing Analysis
Next-generation real-time inference engines command substantial premiums over batch-oriented legacy warehouses still deployed at incumbent institutions. Pricing stratifies across premium, standard, and economy tiers keyed to model explainability depth, regulatory certification grade, and burst compute capacity allocation. Cost compression in the standard tier intensifies as managed feature stores from hyperscalers commoditize previously bespoke data preparation workflows. Mid-tier commercial banks exhibit acute price sensitivity, while money-center institutions prioritize audit trail completeness over licensing expenditure.
Supply Chain Analysis
Strategic stockpiling of GPU compute capacity dominates vendor procurement strategies as NVIDIA H100 cluster availability fluctuates with hyperscaler allocation decisions. Hardware supply concentrates in Taiwan, South Korea, and the United States for advanced semiconductor fabrication feeding model training infrastructure. Software supply draws from open-source machine learning frameworks, proprietary banking ERP modules, and cloud-native analytics stacks. Single-source vulnerability in specialized AI accelerator chips exposes vendors to capacity rationing during demand spikes. Distribution runs through direct enterprise sales teams supplemented by systems integrators bridging legacy core banking connectivity gaps.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across regulatory jurisdictions and buyer archetypes creates specialized niches for vendors targeting compliance-heavy European deployments or cloud-native challenger bank stacks. The bifurcation between incumbent infrastructure rebuilds and greenfield digital-native deployments opens multiple entry vectors.
For Market Incumbents: Shield installed base relationships by embedding analytics deeper within core banking ERP workflows, countering the threat of disintermediation by standalone AI platform vendors. Prioritize certification investment for EU AI Act high-risk system compliance to maintain European procurement eligibility. Channel control through exclusive partnerships with regional systems integrators defends against hyperscaler encroachment in the mid-tier commercial bank segment.
For New Entrants and Emerging Players: Anchor in the credit union segment where cloud-native platform democratization has outpaced internal data engineering capacity, creating immediate managed analytics-as-a-service demand. Target the climate risk stress testing application where regulatory mandates outstrip institutional modeling capabilities. A white-label embedded finance go-to-market angle bypasses direct competition with established banking software vendors.
For Investors and Strategic Acquirers: Specialized feature store vendors with pre-built banking data pipelines represent the most compelling acquisition archetype as model deployment timelines compress from quarters to weeks. Long-term viability hinges on differentiation durability against hyperscaler managed service expansion. Watch for inflection when outcome-based contracting penetration crosses threshold levels forcing smaller vendors to assume unsustainable performance guarantees.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Azure-native stacks synchronize with institutional cloud migration timelines at United States money-center banks. |
| Regulatory Certification Pathway | EU AI Act audit-ready documentation opens procurement windows across ECB-supervised institutions. |
| Strategic Partnership | Systems integrator alliances bridge COBOL-based core banking systems with modern inference engines. |
| Acquisition of Specialist Firm | Graph database vendors with AML-specific neural network training data accelerate fraud detection capabilities. |
| Geographic Expansion | Brazilian Pix instant payment infrastructure generates localized stream-processing demand in São Paulo. |
Study Parameters
The analysis maps predictive analytics platforms, prescriptive optimization engines, fraud detection modules, and climate risk stress testing tools, each validated through chief data officers, model risk management leads, procurement executives at regional banks, and cloud infrastructure architects. Primary interviews with these stakeholders combined trade publication validation, SEC 10-K software revenue disclosures, ECB supervisory guidance documents, and hyperscaler capex breakdowns. Bottom-up deployment sizing and top-down banking IT spend allocation triangulate market boundaries.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation dimensions modeled include deployment architecture, institution size tier, analytics maturity stage, application use case, and jurisdictional regulatory cluster. CAGRs derived from fitted growth curves incorporating FedNow adoption trajectories, EU AI Act enforcement phase-ins, and cloud migration velocity at challenger institutions.
Material uncertainties — GPU supply constraints, data localization law expansion, quantitative talent scarcity — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory enforcement timing and infrastructure replacement cycles. Revision becomes warranted when explainable AI mandate adoption crosses compliance threshold levels or when hyperscaler pricing volatility disrupts outcome-based contract economics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Banking
Africa Data Analytics in Banking Market
Banking
Banking Wearable Market
Banking
Banking Tax Management Software Market
Banking
Southeast Asia Commercial Banking Market
Banking
Banking ERP Software Market
Banking
Australia Data Analytics in Banking Market
Banking
US Data Analytics in Banking Market
Banking
Latin America Neo Banking Services Market
Banking
Asia-Pacific Challenger Banks Market
Banking
E-Banking Market
Banking
Smart ATM Market
Banking
South Korea Data Analytics in Banking Market
Banking
Virtual Teller Machine (VTM) Market
Banking
Singapore Neobanking Market
Banking
Armenia Banking Market
Banking
Voice Banking Market