
 Risk Management Market | 2026-2036
Risk Management Market Size, Share, and Industry Trends Forecast 2026-2036
Risk Management Market Analysis
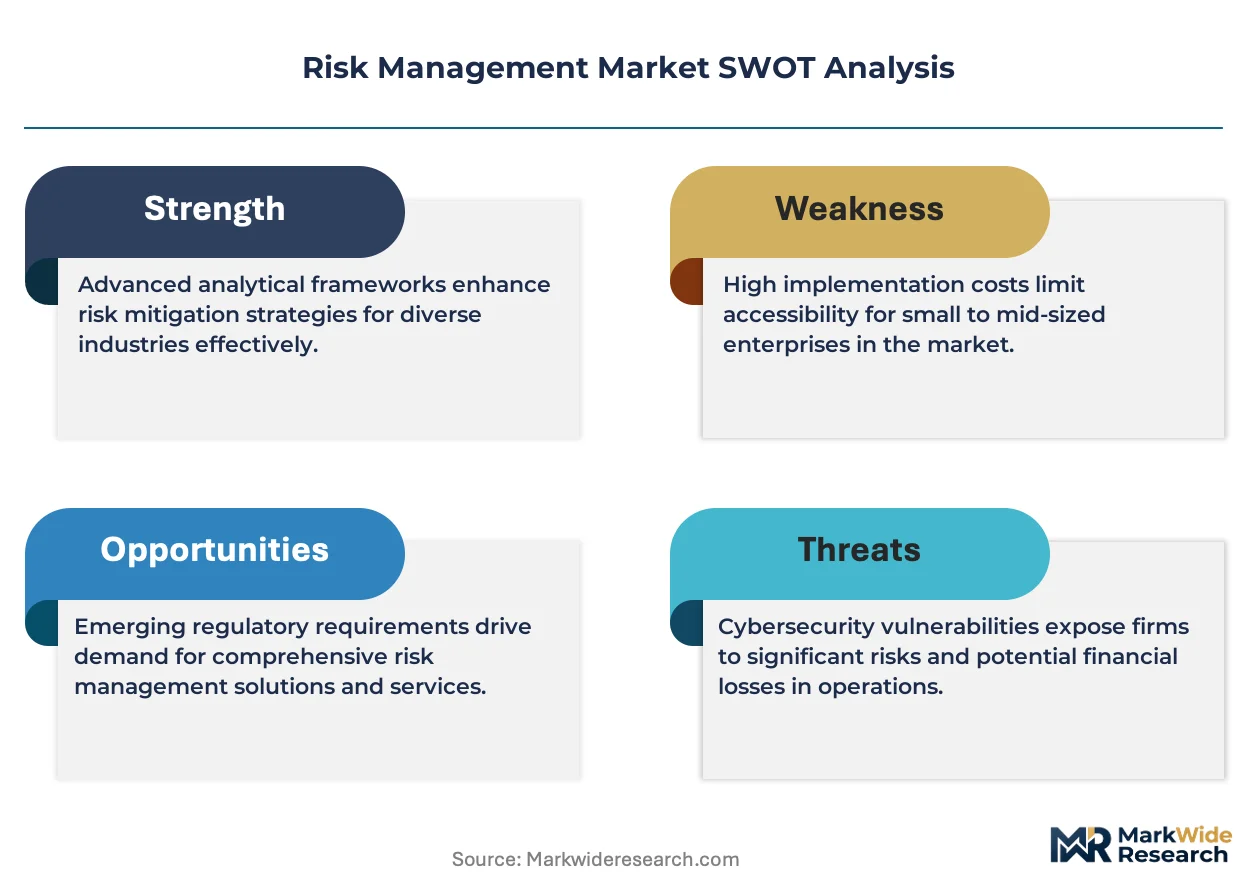
Modular platform bundling is broadening buyer choice in enterprise risk management. IBM Corporation leverages its Watson analytics backbone to anchor governance-risk-compliance suites for multinational banks. Oracle Corporation competes through deep vertical integration of cloud infrastructure with predictive risk scoring engines. SAP SE specializes in embedding operational risk modules directly within ERP workflows to reduce implementation friction.
Risk management encompasses the systematic identification, quantification, and mitigation of threats to organizational capital and earnings through statistical modeling, scenario analysis, and control frameworks. The discipline relies on probability distributions, Key Risk Indicators, and stress-testing protocols to protect balance sheets and operational continuity. Software and analytics segments command the deepest margin pools as buyers prioritize real-time monitoring over episodic consulting engagements. Financial services and energy applications absorb the largest share of platform spending due to capital-intensive exposures and stringent prudential requirements. SME end users represent the fastest-expanding addressable base as cloud delivery collapses deployment costs.
The SEC climate disclosure rules, EU DORA, and Basel III operational risk frameworks are reshaping product specifications and procurement timelines across the sector. Compliance mandates now require auditable data lineage, automated control testing, and third-party risk dashboards as standard features. Stakeholders must evaluate vendor roadmaps against evolving jurisdictional requirements rather than current functionality alone.
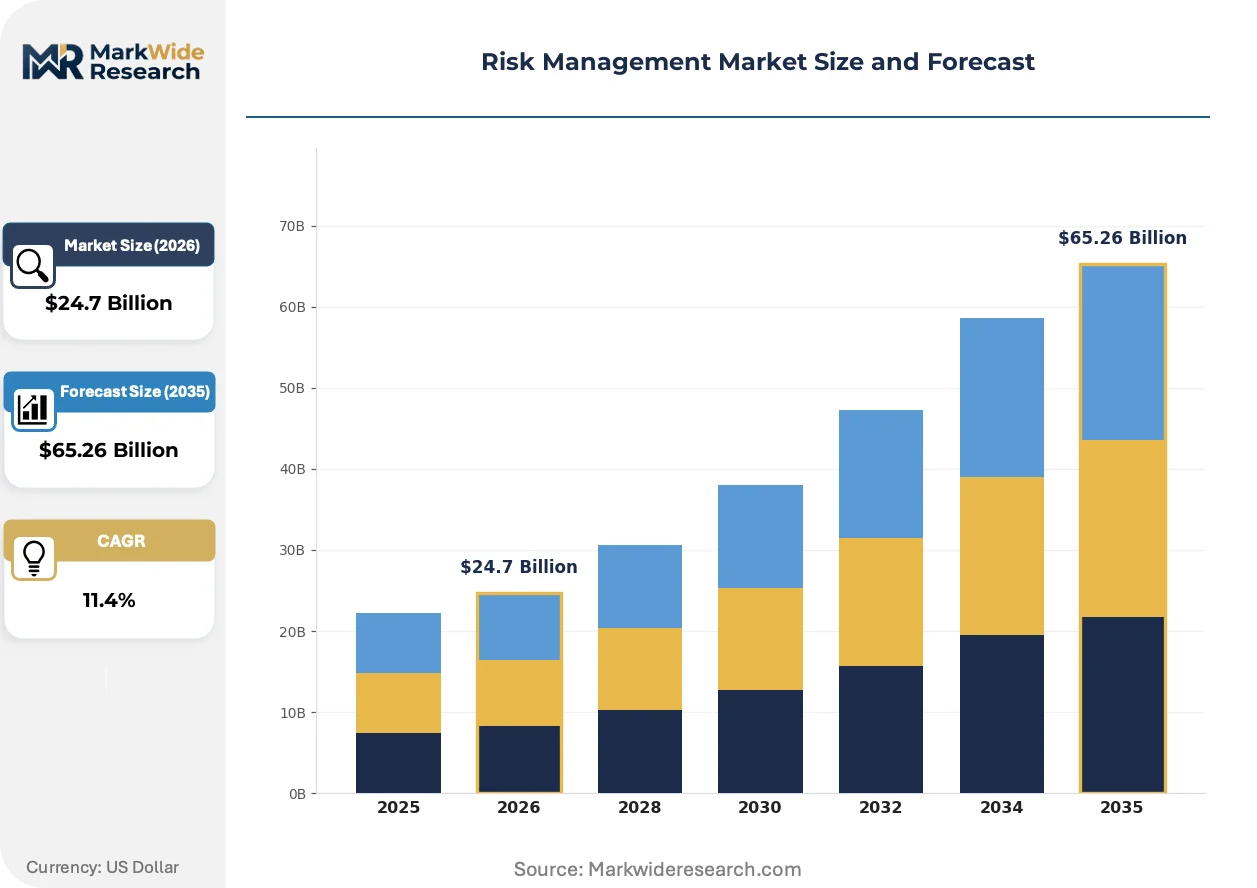
Market Dynamics
Financial institutions are consolidating fragmented risk silos into unified data fabrics as prudential supervisors mandate real-time capital adequacy reporting. This architectural shift is compressing procurement cycles and elevating platform vendors with native cloud analytics over point-solution specialists.
Growth Catalysts
- EU DORA operational resilience mandates:European banking supervisors now require automated third-party risk monitoring and incident reporting within strict timeframes, forcing institutions to upgrade legacy governance infrastructure.
- Cloud-native stress-testing engines:Energy trading desks and insurance underwriters are adopting elastic compute architectures that collapse scenario runtime from days to hours during volatility spikes.
- United States cybersecurity exposure concentration:Critical infrastructure operators face SEC disclosure obligations and private litigation risk, accelerating spending on integrated threat-intelligence and operational risk platforms.
Market Restraints
- Specialized actuarial talent scarcity:Quantitative risk modelers with cross-functional expertise in both statistical methods and regulatory frameworks command premium compensation that inflates implementation costs.
- Data localization requirements:Divergent national privacy regimes fragment cloud architectures, forcing vendors to maintain redundant infrastructure across jurisdictions and eroding platform economics.
- Legacy system entrenchment:Core banking platforms with decades of embedded risk logic resist API-based integration, extending deployment timelines and inflating professional services dependencies.
Strategic Opportunities
- India SME banking digitization:The Reserve Bank of India's push for financial inclusion and digital lending is creating first-mover advantage for cloud-delivered risk-scoring platforms targeting tier-2 and tier-3 cities.
- Climate risk stress-testing convergence:The Network for Greening the Financial System scenarios are integrating physical and transition risk models, opening white space for vendors with geospatial analytics capabilities.
- Embedded insurance partnerships:E-commerce platforms and mobility providers are white-labeling risk engines for real-time underwriting, bypassing traditional broker distribution channels.
Industry Challenges
- Model risk management certification:SR 11-7 and equivalent supervisory guidance demand documented validation frameworks that many vendors lack, creating procurement friction with regulated buyers.
- Interoperability protocol fragmentation:Absence of unified data standards between risk, finance, and compliance systems forces costly bespoke integration work at each deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Risk Management Market |
| Market Size in 2026 | $24.7 Billion |
| Market Size in 2035 | $65.26 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Consulting, Software, Analytics, Training Application: Financial Services, Healthcare, Manufacturing, Energy End User: Corporations, Government, Nonprofits, SMEs Industry Vertical: Insurance, Banking, Utilities, Transportation |
| Companies Covered | IBM Corporation, Oracle Corporation, ServiceNow, SAP SE, MetricStream, SAS Institute, Fiserv, NAVEX Global, Moody's Analytics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Risk Management Market Emerging Trajectories
Generative AI is penetrating risk modeling workflows, automating narrative generation for regulatory submissions and accelerating scenario design. Simultaneously, supervisory technology is tightening audit trails and compressing reporting latency requirements.
Machine learning for anomaly detection is integrating behavioral biometrics, transaction pattern analysis, and external threat feeds into unified surveillance layers. Mid-market banks and regional insurers are adopting these capabilities through API-accessible microservices rather than enterprise license commitments. The structural result is compressing time-to-value for advanced analytics and displacing multi-year implementation paradigms.
The EU AI Act risk-based classification framework is reclassifying certain credit-scoring and fraud-detection algorithms as high-risk systems subject to conformity assessment. Vendors must now embed explainability features and human-in-the-loop governance by design. Financial services firms in Germany and France are front-running compliance by procuring only certified platforms, reshaping competitive qualification criteria.
Chief risk officers are unbundling monolithic platform contracts into modular component sourcing, selecting best-of-breed engines for credit, market, and operational risk separately. This disaggregated procurement pattern favors specialized vendors with open architectures over integrated suite providers. The shift is most pronounced among asset managers and hedge funds in the United States seeking to optimize total cost of ownership.
Risk Management Market Segmentation
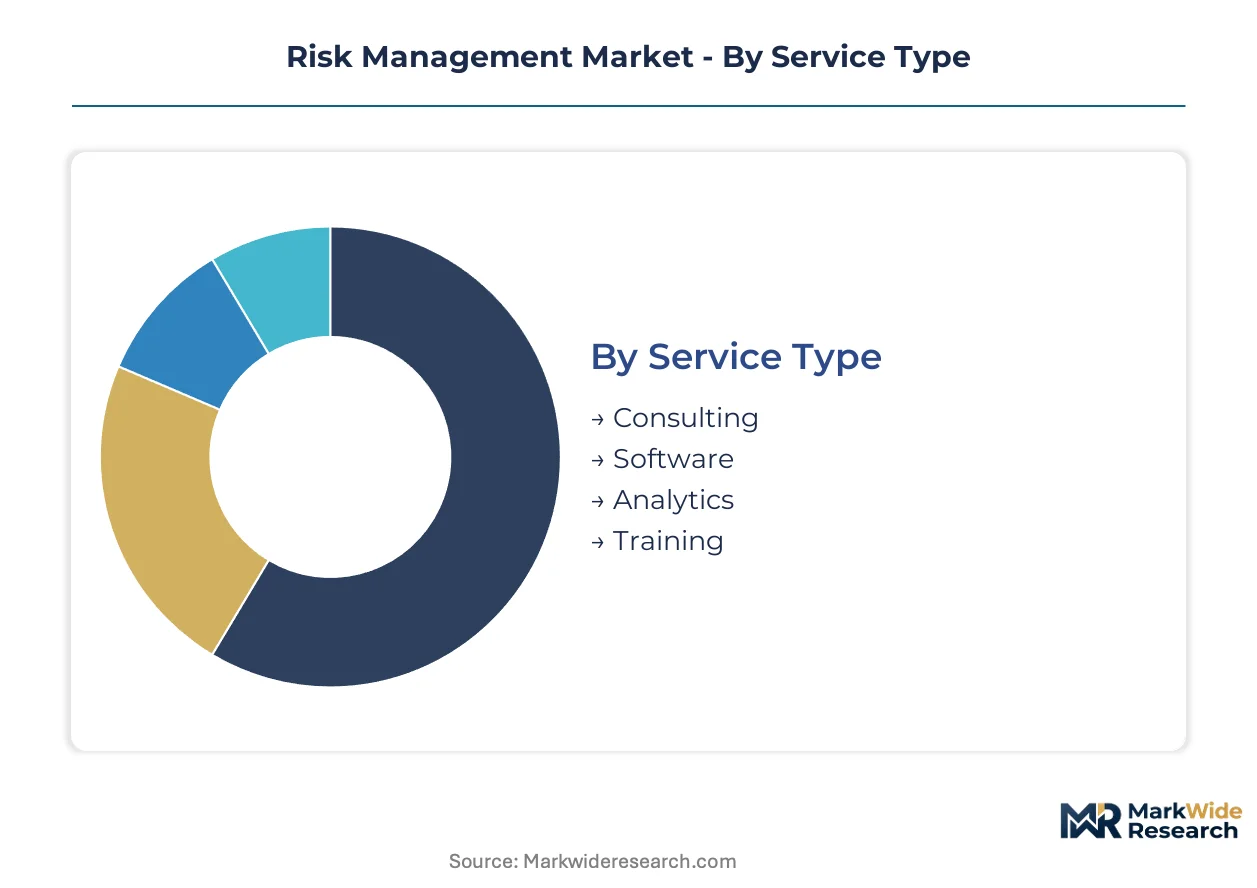
Risk management procurement patterns diverge sharply between capital-intensive incumbents seeking integrated suites and agile entrants prioritizing modular components. Understanding these segment fault lines reveals where margin pools concentrate and which technology architectures will dominate next-generation deployments.
Service Type:
Software commands volume dominance while analytics captures premium pricing through proprietary model IP.
- Software:Cloud-native platforms with embedded workflow automation and API-first architectures now absorb the majority of enterprise procurement budgets. United States banking regulators mandate real-time capital reporting, forcing institutions toward continuous-deployment risk engines rather than batch-processed legacy systems.
- Analytics:Predictive scoring engines leveraging alternative data streams and machine learning classifiers deliver the highest per-seat economics. Energy trading desks in Germany and France pay substantial premiums for geospatial climate risk models that satisfy EU Green Deal stress-testing requirements.
- Consulting:Advisory services concentrate on regulatory implementation and model validation for Basel III operational risk frameworks.
- Training:Certification programs address acute shortages in quantitative risk modeling and SR 11-7 compliance documentation.
Today's leader: Software. Tomorrow's challenger: Analytics.
Application:
Financial Services anchors absolute spending while Healthcare exhibits the steepest expansion trajectory from a smaller base.
- Financial Services:Integrated governance-risk-compliance platforms with native cloud analytics dominate procurement at multinational banks. SEC climate disclosure rules and EU DORA mandates compress implementation timelines from years to quarters.
- Healthcare:HIPAA-compliant risk engines with embedded patient data anonymization are gaining share fastest among hospital networks and pharmaceutical supply chains. United States health systems face ransomware exposure concentration that accelerates cyber risk platform adoption.
- Manufacturing:Operational risk modules targeting supply chain disruption and quality control absorb investment from automotive and electronics producers.
- Energy:Physical asset risk scoring and commodity price stress-testing concentrate demand among European utilities navigating transition risk scenarios.
Financial Services maintains incumbent dominance; Healthcare offers the most open competitive terrain for specialized entrants.
End User:
Corporations drive mature-market revenue while SMEs represent the addressable base expanding most quickly.
- Corporations:Fortune 500 risk functions consolidate fragmented point solutions into unified data fabrics with auditable lineage. Procurement cycles favor vendors offering professional services alongside platform licenses.
- SMEs:Tier-2 and tier-3 enterprises in India access cloud-delivered risk scoring through subscription tiers that collapse deployment costs. RBI financial inclusion mandates create first-mover advantage for API-accessible microservices.
- Government:Public sector procurement prioritizes FedRAMP and equivalent security certifications for critical infrastructure risk monitoring.
- Nonprofits:Grant-funded organizations adopt donor-mandated risk frameworks with limited customization requirements.
Corporations defend spending leadership; SMEs unlock volume scalability for cloud-native architectures.
Industry Vertical:
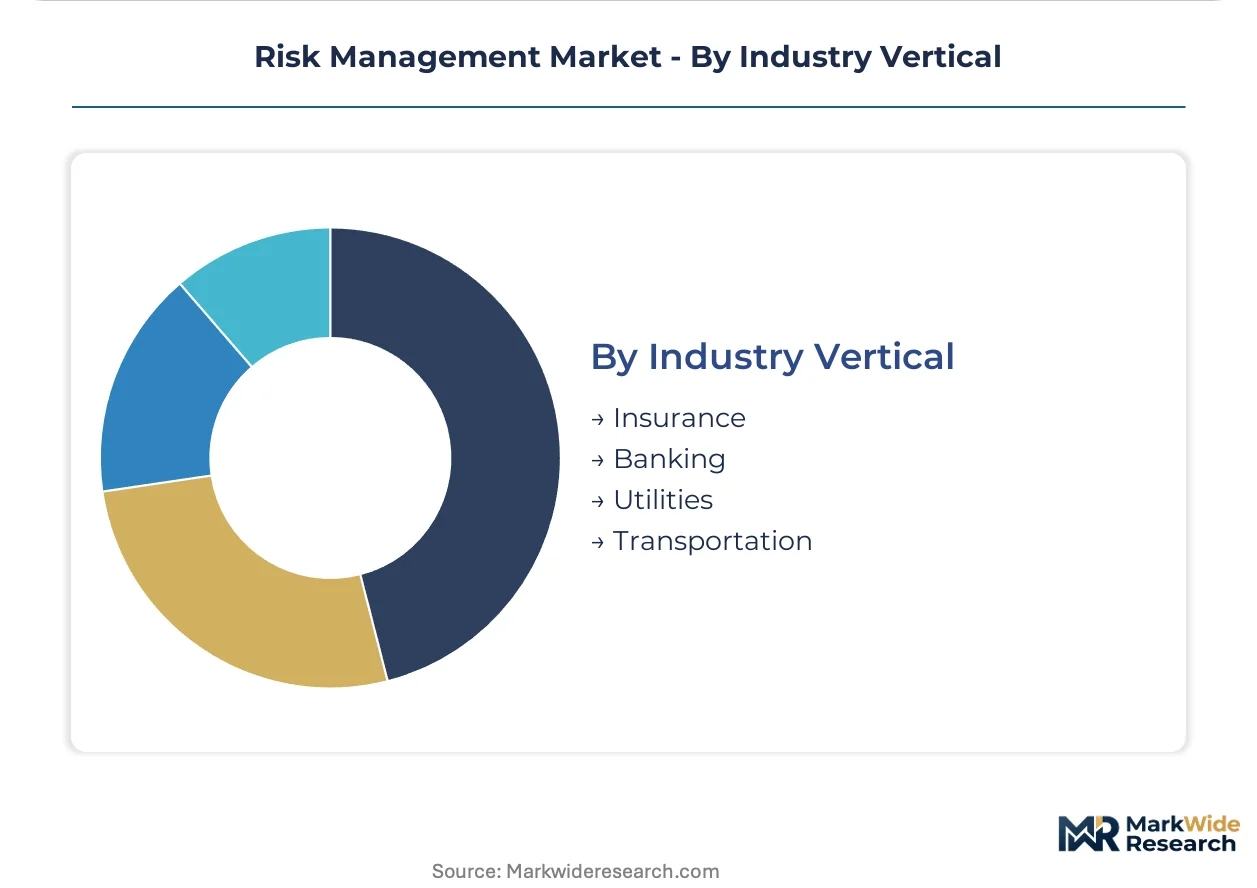
Banking concentrates platform investment while Insurance offers specialized model risk management opportunities.
- Banking:Real-time capital adequacy reporting and automated control testing absorb the deepest technology budgets. European supervisors enforce DORA third-party risk monitoring that elevates native cloud vendors over legacy specialists.
- Insurance:Actuarial model validation and climate risk integration create demand for geospatial analytics capabilities. The Network for Greening the Financial System scenarios reshape product specifications across underwriting divisions.
- Utilities:Physical asset integrity and cyber-physical system protection dominate risk function priorities.
- Transportation:Logistics disruption modeling and fleet safety analytics concentrate spending among maritime and aviation operators.
Banking retains structural primacy; Insurance rewards vendors with climate-analytics differentiation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Risk management platforms originated in the United States financial centers during the 1990s derivatives trading boom, then diffused through London and Frankfurt as Basel accords tightened capital requirements. Today procurement concentrates in banking clusters where regulatory velocity and technology infrastructure intersect.
United States
SEC climate disclosure obligations and cybersecurity incident reporting mandates compress procurement timelines for Fortune 500 risk functions. The Federal Reserve's supervisory expectations for model risk management elevate vendors with documented SR 11-7 validation frameworks. New York and Chicago banking clusters drive demand for real-time capital adequacy engines.
Germany
EU DORA operational resilience requirements force automated third-party risk monitoring upgrades across Frankfurt's banking concentration. BaFin enforcement of BCBS 239 data aggregation standards privileges native cloud analytics over legacy specialists. Munich and Stuttgart industrial corridors absorb operational risk modules for automotive supply chain protection.
United Kingdom
Prudential Regulation Authority expectations for climate risk stress-testing reshape Lloyd's and London market underwriting platforms. The Financial Conduct Authority's operational resilience rules mandate maximum tolerable downtime specifications. The City of London and Edinburgh financial centers concentrate governance-risk-compliance suite procurement.
India
RBI financial inclusion mandates and digital lending guidelines create first-mover opportunity for cloud-delivered risk scoring in tier-2 and tier-3 cities. SEBI's tightening disclosure requirements for mutual funds and portfolio managers accelerate platform adoption. Mumbai and Bangalore technology corridors host emerging vendor development clusters.
Japan
METI's cybersecurity framework for critical infrastructure operators elevates integrated threat intelligence spending among Tokyo and Osaka banking concentrations. The Financial Services Agency's operational risk guidance for regional banks collapses deployment timelines. Nagoya manufacturing clusters adopt supply chain disruption modeling for automotive and electronics production.
Risk Management Market Vendor Landscape
The competitive structure tilts toward integrated platform providers with native cloud architectures. Incumbent technology conglomerates with adjacent enterprise software franchises command disproportionate share in banking and insurance verticals. Three archetypes dominate: full-stack suite vendors, specialized analytics engines, and verticalized workflow platforms. Consolidation pressure intensifies as point-solution specialists face procurement exclusion from unified data fabric mandates. Strategic partnerships between cloud hyperscalers and risk engine developers accelerate capability bundling.
Among the integrated suite tier, IBM Corporation, Oracle Corporation, and SAP SE anchor competitive positioning through governance-risk-compliance convergence. IBM Corporation leverages Watson analytics infrastructure for multinational banking deployments. Oracle Corporation exemplifies verticalized cloud infrastructure integration with predictive scoring capabilities. SAP SE occupies a position embedding operational risk modules directly within ERP workflows to reduce implementation friction. These three conglomerates represent the architectural direction buyers prioritize for real-time capital reporting and automated control testing.
| Leading Market Players |
|---|
| IBM Corporation |
| Oracle Corporation |
| ServiceNow |
| SAP SE |
| MetricStream |
| SAS Institute |
| Fiserv |
| NAVEX Global |
| Moody's Analytics |
| Others |
Supply Flow & Price Mechanics
Fortune 500 risk functions in the United States and European banking clusters anchor procurement volume, concentrating buying power around subscription-based SaaS platforms with tiered deployment scales. This buyer concentration elevates vendors with native cloud architectures while compressing margins for legacy specialists dependent on professional services.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates enterprise risk platform procurement, with differentiation driven by certification grade (FedRAMP, ISO 27001, SOC 2) and customization depth for regulatory frameworks. Cost compression in the standard tier is intensifying because hyperscaler marketplace listings are collapsing customer acquisition costs for API-first entrants. SME segments in India and Southeast Asia exhibit highest price sensitivity, while multinational banks in Frankfurt and New York accept substantial premiums for real-time capital adequacy engines with embedded DORA compliance.
Supply Chain Analysis
Cloud infrastructure supply rests on hyperscaler data center networks concentrated in the United States, Ireland, and Singapore, with specialized compute for risk analytics drawing from NVIDIA GPU clusters and proprietary ASIC development in Taiwan and South Korea. Raw material dependencies span advanced semiconductors, high-bandwidth memory modules, and specialized cooling systems. Single-source vulnerability in EU sovereign cloud certifications fragments platform economics. Distribution runs through direct enterprise sales teams, hyperscaler marketplaces, and systems integrator partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in risk management platforms stems from collapsing cloud delivery costs and accelerating premium-tier demand for AI-augmented analytics engines.
For Market Incumbents: Acquire specialized climate risk analytics capabilities to defend against geospatial insurgents targeting EU Green Deal stress-testing mandates. Consolidate fragmented model validation frameworks into unified SR 11-7 certification suites. Channel control through embedded insurance partnerships offers defensive moats against API-first disaggregators. For New Entrants and Emerging Players: Tier-2 and tier-3 banks in India represent the most penetrable buyer archetype, with RBI financial inclusion mandates collapsing procurement barriers for cloud-native entrants. White-label risk engines for e-commerce platforms bypass traditional broker channels. A microservices-first go-to-market strategy compresses time-to-value against suite incumbents. For Investors and Strategic Acquirers: Cloud hyperscalers with adjacent financial services verticals are the most active acquirer in this space, seeking to bundle risk engines into broader enterprise workload offerings. Long-term viability favors vendors with documented EU AI Act conformity assessment pathways. The signal to watch is DORA implementation timelines accelerating third-party risk platform replacement cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies credit, market, and operational risk modules into continuous-deployment data fabrics for Basel III compliance. |
| Acquisition of Specialist Firm | Absorbs geospatial climate analytics capabilities required for Network for Greening the Financial System scenario modeling. |
| Strategic Partnership | Embeds risk scoring engines within ERP workflows to reduce implementation friction at SAP and Oracle accounts. |
| Product Launch | Introduces API-accessible microservices targeting mid-market banks seeking compressed deployment timelines. |
| Geographic Expansion | Establishes cloud delivery infrastructure in Mumbai and Bangalore for RBI-mandated digital lending platforms. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with chief risk officers, enterprise architects, regulatory compliance leads, and procurement directors at financial institutions with secondary validation against SEC filings, ECB supervisory guidance, RBI circulars, and vendor hyperscaler marketplace disclosures. Bottom-up deployment estimates triangulated against top-down regulatory mandate timelines.
Segment-weighting approaches applied differential growth assumptions across software, analytics, consulting, and training service types, with deployment model, organization size, vertical integration complexity, and regional regulatory velocity as core segmentation dimensions. CAGRs derived from regression analysis of historical procurement cycles against regulatory implementation deadlines, incorporating cloud adoption curves and SME banking digitization rates as industry-specific inputs.
Underlying measurement precision varies by segment; software and analytics carry tighter precision than consulting and training due to disclosed vendor bookings. Forecasts reflect documented assumptions about DORA implementation rigor and EU AI Act enforcement sequencing. Regulatory delay, hyperscaler marketplace commission structure shifts, and actuarial talent scarcity warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Risk Management and Compliance
AI in Fraud Management Market
Risk Management and Compliance
Digital Risk Management Market
Risk Management and Compliance
North America Strategic Consulting Market
Risk Management and Compliance
Europe BFSI Biometrics Market
Risk Management and Compliance
Cyber Security in BFSI Market
Risk Management and Compliance
United States Governance, Risk and Compliance Platform Market
Risk Management and Compliance
Europe Sustainable Finance Market
Risk Management and Compliance
Anti-Money Laundering (AML) Market
Risk Management and Compliance
Global Risk and Compliance Consulting Services Market
Risk Management and Compliance
Governance, Risk and Compliance Platform Market
Risk Management and Compliance
Global Strategy Consulting Market
Risk Management and Compliance
Asia-Pacific BFSI Biometrics Market
Risk Management and Compliance
Europe Strategy Consulting Market
Risk Management and Compliance
Corporate Investigation Services Market
Risk Management and Compliance
Asset Liability Management (ALM) Solution Market
Risk Management and Compliance
Risk Analytics Market