
 Riot Control System Market | 2026-2036
Riot Control System Market Size, Share, and Industry Trends Forecast 2026-2036
Riot Control System Market Intelligence
EU Green Deal chemical reform standards are consolidating compliance costs around environmental persistence testing for tear gas formulations. Desert Wolf leverages its Southern African manufacturing base to sustain cost advantages in mobile water cannon systems. Combined Systems, Inc. anchors North American supply through captive production of pyrotechnic delivery mechanisms. Safariland, LLC differentiates via vertical integration into less-lethal projectile molding and carrier platform integration.
Riot control systems encompass engineered non-lethal force delivery platforms including kinetic impact projectiles, aerosol chemical agents, acoustic deterrent devices, and hydraulic dispersal equipment designed to incapacitate or disperse hostile crowds without permanent injury. These systems typically operate at calibrated pressure thresholds below 150 psi for water cannons and employ CS or OC formulations at concentrations under 10% for respiratory effect with minimal lasting harm. Surveillance Systems within the Technology dimension dominates current procurement budgets as municipalities integrate facial recognition and thermal monitoring into command infrastructure. Crowd Control Drones represent the fastest-expanding segment as autonomous aerial platforms extend situational awareness beyond ground-based officer sightlines. Non-Lethal Weapons under Product Type occupies the deepest margin pool due to recurring consumable demand for chemical refills and projectile replenishment.
FDA oversight of chemical irritant formulations intersects with EPA discharge permitting for water cannon effluent in the United States, while REACH compliance governs substance authorization across European supply chains. BIS certification requirements in India mandate domestic testing protocols that extend market access timelines for foreign manufacturers. Stakeholders must monitor evolving restrictions on kinetic projectile kinetic energy thresholds as liability frameworks shift toward stricter operator accountability standards.
Market Dynamics
EU Green Deal chemical reform standards are consolidating compliance costs around environmental persistence testing for tear gas formulations, forcing manufacturers to reconfigure supply chains and R&D priorities across European markets.
Growth Catalysts
- Urbanization pressures:Municipal police departments in India, Brazil, and Nigeria are expanding non-lethal procurement budgets to manage denser population concentrations and elevated protest frequency.
- REACH substance authorization:European manufacturers reformulating CS and OC agents toward biodegradable analogs are capturing premium positioning as regulatory deadlines approach.
- Autonomous platform integration:Crowd control drones with thermal payload and acoustic deterrent modules are extending situational awareness beyond ground-based officer limitations.
Market Restraints
- Specialty chemical supply concentration:Precursor synthesis for pyrotechnic irritant charges concentrates in Chinese and Indian fine chemical clusters, exposing buyers to export licensing volatility.
- Kinetic energy liability thresholds:German and French courts are tightening operator accountability standards for rubber projectile impact force, constraining product design parameters.
- Water cannon effluent permitting:EPA discharge requirements in the United States impose site-specific wastewater treatment obligations that extend deployment timelines and capital requirements.
Strategic Opportunities
- India PLI scheme localization:Domestic security manufacturing incentives are accelerating local production capacity for tear gas canisters and launcher systems, compressing import dependency.
- Acoustic deterrent convergence:Integration of directional sound arrays with facial recognition command infrastructure creates bundled procurement opportunities for surveillance-technology vendors.
- Less-lethal projectile molding:Backward integration into polymer formulation and carrier platform design enables margin capture from recurring consumable replenishment cycles.
Industry Challenges
- BIS certification timelines:India's Bureau of Indian Standards mandates domestic testing protocols that extend market access by 12-18 months for foreign manufacturers.
- Legacy system integration friction:Municipal command centers face technical debt when interfacing new autonomous aerial platforms with existing radio-frequency dispatch architectures.
- Pyrotechnic specialist labor scarcity:Qualified formulation chemists for stable irritant charge design remain concentrated in defense-sector employment pools.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Riot Control System Market |
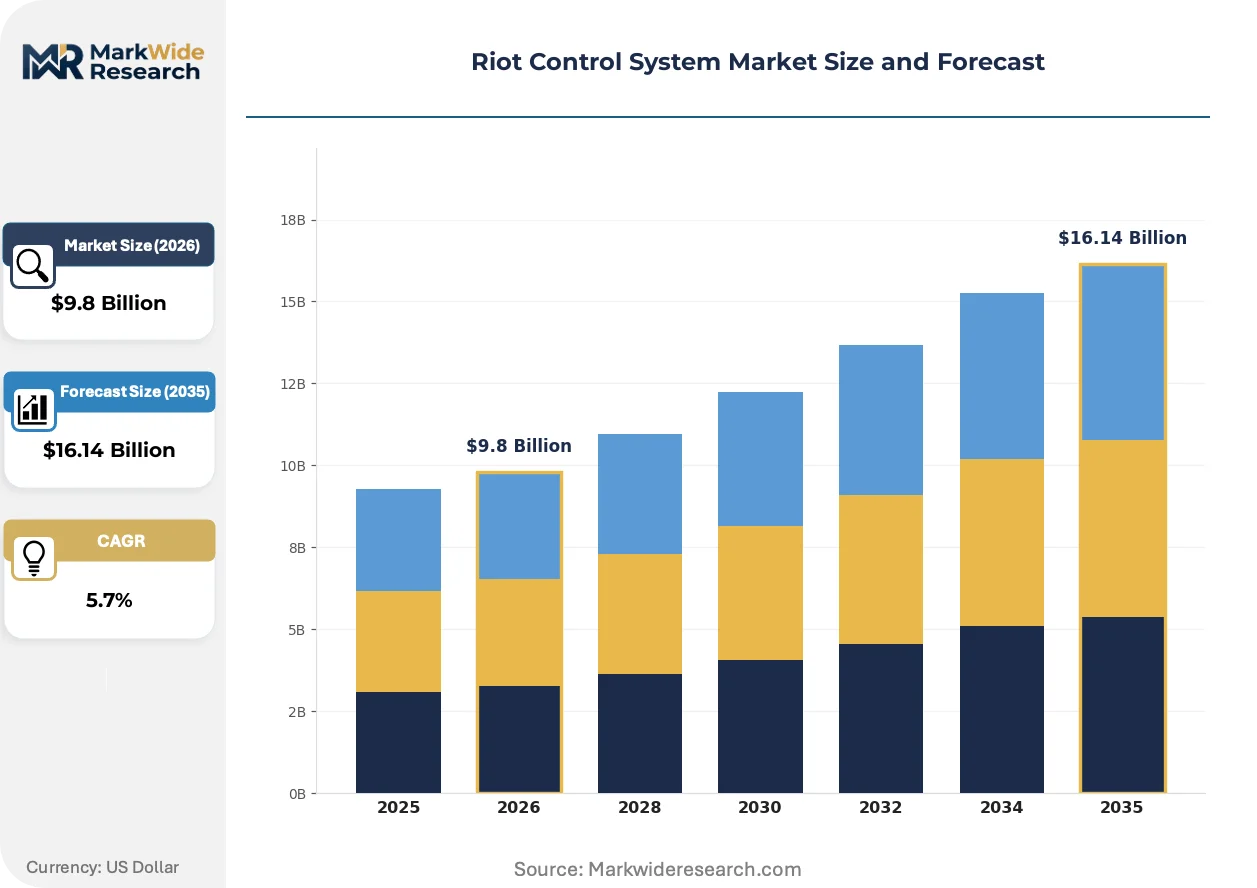
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $16.14 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Non-Lethal Weapons, Tear Gas, Rubber Bullets, Water Cannons Deployment Mode: On-Premise, Mobile Units, Fixed Installations, Remote Monitoring End User: Law Enforcement, Private Security, Military, Emergency Services Technology: Surveillance Systems, Communication Devices, Crowd Control Drones, Barriers |
| Companies Covered | Desert Wolf, Combined Systems, Inc., Safariland, LLC, BAE Systems Plc, Axon Enterprise Inc., Amtec Less Lethal Systems, LRAD Corporation, Genasys, Inc., Rheinmetall AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Riot Control System Market Strategic Shifts & Innovations
Active reformulation of chemical irritants toward reduced environmental persistence is intersecting with autonomous platform proliferation and procurement model evolution across municipal security budgets.
Biodegradable CS analogs are absorbing R&D investment from European and North American manufacturers seeking REACH compliance ahead of 2027 substance review deadlines. Law enforcement agencies in Germany, France, and the Netherlands are piloting these reformulated agents in controlled urban deployment scenarios. The transition is compressing demand for legacy chloroacetophenone formulations while elevating pricing power for certified biodegradable suppliers.
EU Green Deal chemical reform standards are mandating environmental fate testing for all new irritant submissions to ECHA. Manufacturers must document aquatic toxicity and soil degradation pathways before market authorization. Tear gas formulation suppliers with captive analytical capabilities are internalizing compliance costs that smaller competitors cannot absorb, consolidating the European supplier base.
Municipal procurement departments are unbundling after-sales service contracts from initial system acquisition, shifting toward performance-based maintenance agreements with penalty clauses for response-time failures. Police departments in London, Los Angeles, and São Paulo are piloting these arrangements for water cannon and drone fleet management. The model transfers operational risk to vendors while compressing upfront capital requirements for cash-constrained agencies.
Riot Control System Market Segmentation
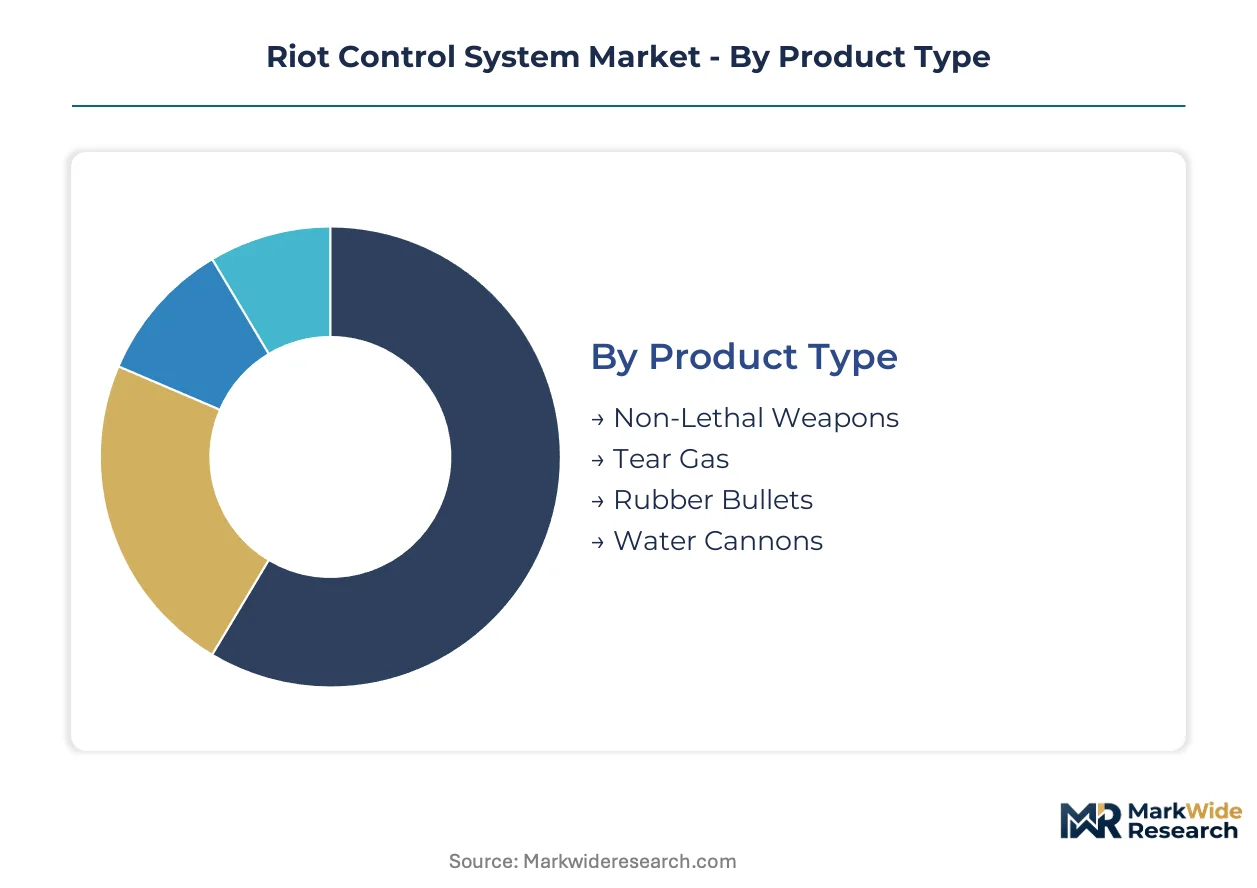
Riot control system procurement divides across multiple axes that determine capital deployment cycles, regulatory exposure, and operational integration complexity. Understanding these segment boundaries clarifies where manufacturers concentrate R&D investment and where procurement budgets flow.
Product Type:
Capital intensity varies sharply across this category, with chemical production infrastructure and precision molding equipment demanding the heaviest upfront outlays.
- Non-Lethal Weapons:Encompasses kinetic impact projectiles, directed-energy devices, and electroshock systems requiring calibrated force thresholds below lethal thresholds. Indian municipal police departments under the PLI scheme are expanding procurement of domestically manufactured launcher systems to reduce import dependency.
- Tear Gas:CS and OC formulations in aerosol, powder, or pyrotechnic delivery configurations. REACH substance authorization deadlines are forcing European manufacturers toward biodegradable analogs with elevated R&D amortization.
- Rubber Bullets:Kinetic impact munitions with calibrated deformation characteristics. German and French courts are tightening operator liability standards for impact force.
- Water Cannons:Hydraulic dispersal platforms operating at calibrated pressure thresholds. EPA discharge permitting in the United States imposes site-specific wastewater treatment obligations.
Non-Lethal Weapons absorbs the bulk of installed capacity; Tear Gas is expanding most quickly.
Deployment Mode:
Operational tempo and mobility requirements shape procurement patterns across urban, perimeter, and remote security scenarios.
- On-Premise:Fixed installations at government facilities, courthouses, and critical infrastructure nodes. Brazilian municipal budgets are prioritizing permanent barrier and surveillance integration at protest-prone administrative centers.
- Mobile Units:Vehicle-mounted water cannons, launcher platforms, and command vehicles. Desert Wolf sustains cost advantages through Southern African manufacturing of truck-based hydraulic systems.
- Fixed Installations:Permanent barrier systems, acoustic deterrent arrays, and integrated command infrastructure. London and São Paulo police departments are piloting performance-based maintenance agreements for fleet management.
- Remote Monitoring:Sensor networks and autonomous platform control stations extending officer situational awareness beyond physical presence.
Mobile Units command the largest share of active procurement; Remote Monitoring is climbing the fastest.
End User:
Budget authority and rules of engagement divergence create distinct specification requirements across institutional buyer types.
- Law Enforcement:Municipal and national police agencies with calibrated escalation protocols. Nigerian police departments are expanding non-lethal procurement budgets to manage elevated protest frequency in dense urban corridors.
- Private Security:Corporate and facility protection services operating under stricter liability frameworks. Los Angeles commercial district associations are contracting bundled surveillance-deterrent services.
- Military:Armed forces in peacekeeping and domestic security roles with heavier armor integration requirements.
- Emergency Services:Fire and medical responders requiring protective barrier and crowd dispersal capabilities during mass casualty events.
Law Enforcement dominates current order books; Private Security is gaining share fastest.
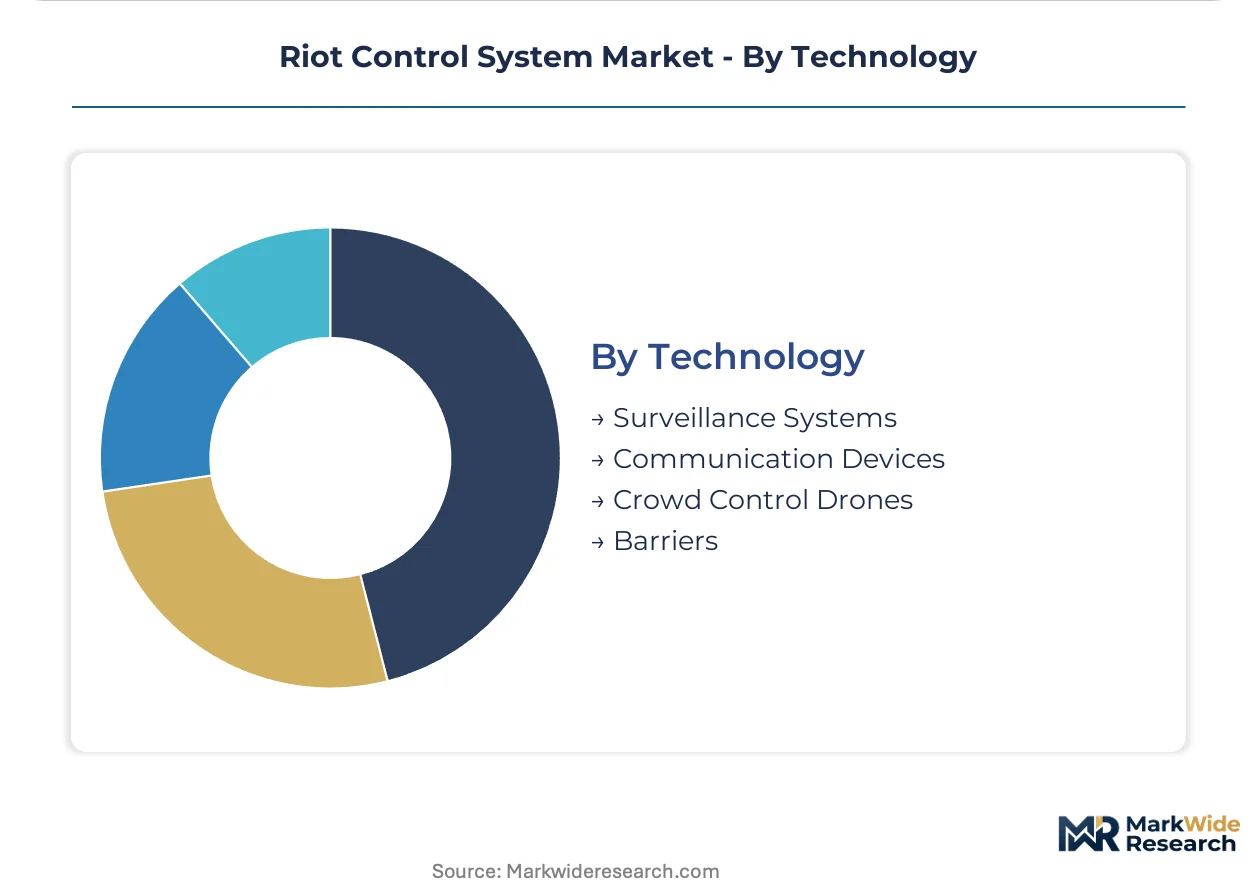
Technology:
Integration complexity and data infrastructure requirements differentiate capital deployment patterns across technology categories.
- Surveillance Systems:Facial recognition, thermal monitoring, and video analytics integrated into command infrastructure. This segment captures the deepest share of current municipal procurement budgets.
- Communication Devices:Encrypted radio, mesh networking, and interoperable dispatch systems. Legacy system integration friction constrains upgrade cycles in older municipal command centers.
- Crowd Control Drones:Autonomous aerial platforms with thermal payload and acoustic deterrent modules. Thermal-equipped units are extending situational awareness beyond ground-based officer limitations.
- Barriers:Rapid-deployment physical obstruction systems including modular fencing and vehicle arrestment.
Surveillance Systems holds the largest installed base; Crowd Control Drones is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special Economic Zones in Gujarat and Tamil Nadu are concentrating domestic security manufacturing capacity under India's PLI scheme, drawing component suppliers and assembly operations into tax-advantaged corridors.
United States
Municipal police departments in Los Angeles and Chicago are expanding procurement of integrated surveillance-deterrent systems. EPA discharge permitting for water cannon effluent imposes site-specific wastewater treatment obligations that extend deployment timelines. The Southeast industrial corridor hosts expanding assembly operations for less-lethal projectile molding.
Germany
Federal and state police agencies are piloting biodegradable CS analogs ahead of REACH substance review deadlines. ECHA environmental fate testing mandates are consolidating compliance costs around aquatic toxicity documentation. The Ruhr industrial basin maintains concentrated capacity for pyrotechnic charge formulation and precision molding equipment.
India
Municipal police departments in Mumbai and Delhi are accelerating tear gas canister procurement under expanded non-lethal budgets. BIS certification requirements mandate domestic testing protocols that extend market access timelines for foreign manufacturers. The Pune-Ahmednagar corridor is emerging as a production cluster for launcher system assembly.
Brazil
São Paulo and Rio de Janeiro municipal budgets are prioritizing mobile water cannon fleets and permanent barrier integration at protest-prone administrative centers. ANVISA oversight intersects with municipal procurement regulations for chemical irritant deployment. The São Paulo state industrial zone sustains regional assembly capacity for vehicle-mounted hydraulic platforms.
South Africa
Desert Wolf leverages its Southern African manufacturing base to sustain cost advantages in mobile water cannon systems for export markets across sub-Saharan Africa. National procurement frameworks emphasize local content requirements for security equipment. The Gauteng industrial hub concentrates fabrication capacity for truck-based dispersal platforms.
Riot Control System Market Key Industry Players
North American producers anchor one tier; European and Southern African specialists hold differentiated positions in chemical formulation and mobile platform assembly. The vendor base concentrates around defense-sector spinoffs and dedicated less-lethal equipment fabricators. Three archetypes dominate: integrated defense conglomerates with riot control divisions, pure-play non-lethal specialists, and surveillance-technology vendors extending into acoustic deterrent convergence. Competitive moves center on backward integration into polymer formulation and performance-based maintenance contract unbundling.
Among the named players, Desert Wolf exemplifies the regional-cost-advantage archetype through its Southern African manufacturing positioning. Combined Systems, Inc. and Safariland, LLC represent North American captive-production models, with the former anchoring pyrotechnic delivery mechanism supply and the latter occupying a position in less-lethal projectile molding and carrier platform integration. These three illustrate how geographic specialization and vertical scope differentiation create tiered competitive positioning.
| Leading Market Players |
|---|
| Desert Wolf |
| Combined Systems, Inc. |
| Safariland, LLC |
| BAE Systems Plc |
| Axon Enterprise Inc. |
| Amtec Less Lethal Systems |
| LRAD Corporation |
| Genasys, Inc. |
| Rheinmetall AG |
| Others |
Cost & Logistics Intelligence
EU Green Deal chemical reform standards are forcing municipal procurement departments toward certified biodegradable tear gas formulations, compelling manufacturers to absorb elevated R&D amortization and environmental testing costs that compress margins on legacy chloroacetophenone products.
Pricing Analysis
Short lead-time premiums distinguish procurement contracts for municipal police departments facing elevated protest frequency, with spot inventory of pyrotechnic irritant charges commanding discounts against certified biodegradable analogs. Three-tier pricing structure across premium, standard, and economy levels separates REACH-compliant European suppliers from Indian PLI-scheme domestic producers and uncertified import alternatives. Cost compression in standard-tier chemical formulations is intensifying because BIS certification timelines extend market access for foreign manufacturers. Private security contractors exhibit highest price sensitivity due to stricter liability frameworks, while military buyers prioritize performance specifications over unit economics.
Supply Chain Analysis
Pyrotechnic irritant charge synthesis rests on Chinese and Indian fine chemical clusters, with precursor manufacturing concentrated in specialized defense-sector facilities across the Yangtze River Delta and Gujarat chemical corridor. Critical inputs include chloroacetophenone precursors, stabilizer compounds, and precision-molded polymer carriers for kinetic projectiles. Single-source vulnerability concentrates in qualified formulation chemists for stable irritant charge design, with talent pools anchored in defense-sector employment. Distribution runs through government procurement frameworks with mandated local content requirements, direct municipal contracting, and defense channel intermediaries for military end-users.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure from REACH substance authorization deadlines and BIS certification barriers is eliminating smaller tear gas formulation suppliers lacking captive analytical capabilities.
For Market Incumbents: Anchor market position through backward integration into polymer formulation and carrier platform design, capturing margin from recurring consumable replenishment cycles. Invest in Southern African or Indian manufacturing footprints to sustain cost advantages against emerging domestic producers. Threat substitution from acoustic deterrent convergence demands surveillance-technology partnership development. For New Entrants and Emerging Players: Capture white-space opportunity in performance-based maintenance agreements for water cannon and drone fleet management, transferring operational risk from cash-constrained municipal agencies. Target Brazilian and Nigerian municipal police departments expanding non-lethal procurement budgets. Go-to-market angle centers on unbundled after-sales service contracts with penalty clauses for response-time failures. For Investors and Strategic Acquirers: Re-rating potential sits with European manufacturers possessing captive environmental fate testing capabilities given REACH compliance deadlines approaching. Long-term viability favors suppliers with biodegradable CS analog certification and autonomous platform integration expertise. Signal to watch: municipal procurement pilot adoption rates for bundled surveillance-deterrent services in London, Los Angeles, and São Paulo.| Strategic Initiative | Industry Significance |
|---|---|
| Biodegradable Formulation Certification | ECHA environmental fate testing mandates consolidate European supplier base around compliant producers. |
| Performance-Based Maintenance Contracts | London and São Paulo police pilots transfer operational risk to vendors while compressing upfront capital requirements. |
| Southern African Manufacturing Expansion | Desert Wolf leverages regional cost advantages in mobile water cannon systems for sub-Saharan export markets. |
| Acoustic Deterrent Convergence | Directional sound array integration with facial recognition infrastructure creates bundled procurement opportunities. |
| Domestic Production Localization | India PLI scheme accelerates tear gas canister and launcher system assembly in Gujarat and Tamil Nadu corridors. |
Research Approach
Independent corroboration across municipal police procurement officers, defense sector manufacturing executives, chemical formulation specialists, and regulatory compliance consultants underwrites the qualitative findings. Primary interviews with plant managers at pyrotechnic charge facilities, procurement leads at European law enforcement agencies, and distribution channel partners specialized in security equipment supplemented secondary validation through customs trade data, ECHA substance authorization filings, SEC 10-K disclosures from listed defense conglomerates, and Bureau of Indian Standards certification records. Bottom-up tear gas canister volume estimates triangulate against top-down municipal security budget allocations across the analysis window.
Comparable-period anchoring to historical procurement cycles from 2019 through 2024 establishes baseline growth trajectories for projection modeling. Segmentation dimensions encompass product type, deployment mode, end user archetype, and technology integration complexity, with regional regulatory clusters treated as distinct forecast inputs. CAGRs derive from weighted-average growth assumptions calibrated to documented procurement expansion in India, Brazil, and Nigeria. Industry-specific inputs include BIS certification timeline distributions, REACH substance review deadline proximity, and EPA discharge permitting backlog severity.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EU Green Deal chemical reform implementation pace, Indian PLI scheme localization success, and kinetic energy liability threshold tightening in German and French courts. Assumptions reflect documented procurement patterns, regulatory filing trajectories, and manufacturer capacity expansion announcements. Export licensing volatility from Chinese and Indian fine chemical clusters, autonomous platform integration friction with legacy radio-frequency dispatch architectures, and pyrotechnic specialist labor scarcity warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Security and Surveillance
Asia-Pacific Security Services Market
Security and Surveillance
North America Security Services Market
Security and Surveillance
Residential Security Market
Security and Surveillance
Consumer Security Market
Security and Surveillance
Europe Security Assurance Market
Security and Surveillance
TSCM Equipment Market
Security and Surveillance
Russian Intelligent Eavesdropping Detection System Market
Security and Surveillance
Situational Awareness System Market
Security and Surveillance
Global Container Security Market
Security and Surveillance
Urban Security Screening Market
Security and Surveillance
Global Security and Vulnerability Management Market
Security and Surveillance
Intrusion Alarm System Market
Security and Surveillance
Europe Security Screening Market
Security and Surveillance
Security Product Integration Services Market
Security and Surveillance
Europe Urban Security Screening Market
Security and Surveillance
Vietnam Private Security Market