
 Vietnam Private Security Market | 2026-2036
Vietnam Private Security Market Size, Share, and Industry Trends Forecast 2026-2036
Vietnam Private Security Market Insights
Direct sales to enterprise clients is fragmenting as multinational manufacturers and logistics operators diversify vendor relationships beyond single-source guarding contracts. PMV Security sustains dominance in industrial zone deployments across southern provinces, leveraging long-standing relationships with Korean and Japanese factory investors. Securitas competes through technology-integrated service bundles that combine guarding personnel with remote monitoring infrastructure. Vietnam Manpower anchors the labor-supply side of the market, controlling recruitment pipelines that feed personnel-intensive contracts for residential and commercial applications.
Vietnam private security encompasses manned guarding, electronic surveillance, risk consulting, and protective operations delivered to commercial, industrial, and institutional clients, typically involving licensed personnel, certified alarm response protocols, and integrated command center coordination. The primary purpose centers on asset protection, personnel safety, and operational continuity for foreign-invested enterprises operating in Vietnam's manufacturing and logistics corridors. Guarding services occupies the largest revenue pool due to persistent labor cost advantages and regulatory mandates for physical presence at commercial facilities, while monitoring services registers the fastest structural expansion as cloud-based video analytics and remote command centers displace on-site supervision in tier-one cities. CCTV systems within the technology dimension concentrates margin capture among providers capable of bundling hardware installation with recurring software maintenance contracts.
Vietnam's Ministry of Public Security administers licensing under Decree 96/2016/ND-CP, requiring security firms to meet capital thresholds, training standards, and equipment specifications that filter out informal operators. The country's national standards body issues technical certifications for alarm systems and access control devices, creating compliance costs that favor established players with dedicated regulatory affairs capacity. Provincial People's Committees in Binh Duong, Dong Nai, and Bac Ninh add local operating permits that extend setup timelines for new entrants. Stakeholders must monitor whether proposed amendments to the Cybersecurity Law will impose data localization requirements on cloud-connected surveillance platforms, potentially restructuring technology procurement patterns across the market.
Market Dynamics
Cloud-connected video analytics is virtualizing command center operations across Vietnamese manufacturing corridors, compressing headcount requirements for tier-one facility contracts while elevating technical certification barriers for incumbent guarding providers.
Growth Catalysts
- Foreign manufacturing FDI:Korean and Japanese electronics assemblers in Binh Duong and Dong Nai provinces mandate integrated guarding and electronic surveillance for facility insurance compliance, expanding contract scope beyond pure manned services.
- Decree 96/2016/ND-CP enforcement:Tightened licensing requirements for security service operators are filtering out informal competitors, concentrating contract volumes among capitalized firms with dedicated regulatory affairs capacity.
- Secondary city branch expansion:State-owned and joint-stock banks are extending physical networks into tier-three urban centers, generating demand for standardized guarding protocols and centralized alarm monitoring infrastructure.
Market Restraints
- Licensed personnel wage inflation:Minimum certification requirements under Ministry of Public Security guidelines are constraining labor supply elasticity, elevating unit costs for personnel-intensive residential and commercial contracts.
- Cloud platform data sovereignty uncertainty:Proposed amendments to Vietnam's Cybersecurity Law threaten to impose localization mandates on foreign-hosted video management software, complicating technology procurement for multinational security integrators.
- Provincial permit fragmentation:People's Committees in Bac Ninh, Hai Phong, and Can Tho maintain non-harmonized operating license procedures, extending market entry timelines for security firms seeking national coverage.
Strategic Opportunities
- Central Highlands logistics corridors:Underpenetrated warehousing zones around Da Nang and Quy Nhon lack established security service density, creating first-mover positioning for providers capable of deploying hybrid guarding-technology bundles.
- Integrated facility management convergence:Bundling security with cleaning, landscaping, and technical maintenance services is capturing procurement consolidation mandates from Japanese automotive and electronics investors seeking single-source facility vendors.
- GB standards alignment for Chinese manufacturers:Vietnamese security firms certifying to Chinese national technical specifications are securing cross-border contract extensions from mainland electronics suppliers relocating assembly operations to northern provinces.
Industry Challenges
- Command center technician scarcity:Certified operators capable of managing multi-site video analytics platforms and coordinating mobile response units remain concentrated in Ho Chi Minh City and Hanoi, constraining service quality in provincial deployments.
- Legacy analog infrastructure retrofit complexity:Decades-old CCTV installations in state-owned industrial parks require phased replacement with IP-based systems, demanding capital-intensive project structuring that strains mid-tier operator balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vietnam Private Security Market |
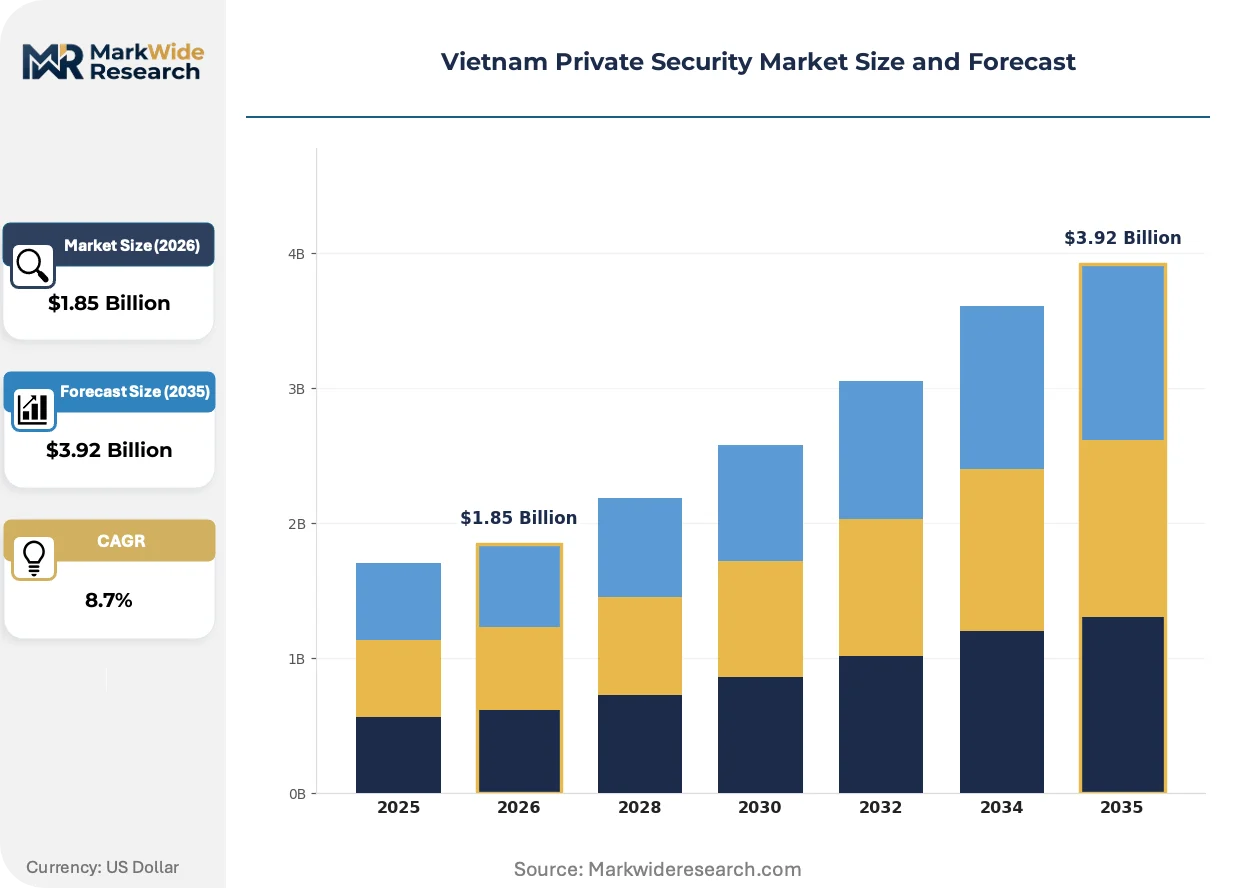
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.92 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Guarding Services, Monitoring Services, Consultancy Services, Event Security End User: Residential, Retail, Banking, Oil & Gas Technology: CCTV Systems, Intrusion Detection, Access Control, Alarm Systems Application: Commercial, Industrial, Personal, Government |
| Companies Covered | Vietnam Manpower, PMV Security, Vietnam Day and Night Security Services Co., Ltd., Night and Day Security Services Co. Ltd., Securitas, Secom, T-Force Security, The Brink’s Co., Global Guardian, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vietnam Private Security Market Trends and Innovations
Technology convergence and procurement model evolution are restructuring competitive positioning across Vietnamese security services, compressing margins for pure-play guarding while elevating value capture for integrated platform providers.
Cloud-based video management software is virtualizing perimeter monitoring functions for manufacturing and logistics facilities, enabling centralized oversight of multi-site operations from command centers in Ho Chi Minh City. Electronics assemblers in Dong Nai and Binh Duong are adopting these platforms at accelerating rates, displacing on-site supervisor headcounts while demanding 24/7 remote incident verification protocols.
Decree 96/2016/ND-CP amendments under Ministry of Public Security review are tightening training hour mandates and equipment specification requirements for licensed security enterprises. Industrial zone operators in Bac Ninh and Hai Phong face elevated compliance documentation burdens, prompting contract consolidation toward established providers with dedicated legal and certification staff.
Enterprise procurement is fragmenting single-source guarding relationships as multinational manufacturers diversify vendor portfolios across regional security networks. Japanese automotive investors in Thai Nguyen and Vinh Phuc are unbundling facility services, separating manned guarding from electronic surveillance and risk consulting to optimize category-specific supplier performance metrics.
Vietnam Private Security Market Segmentation
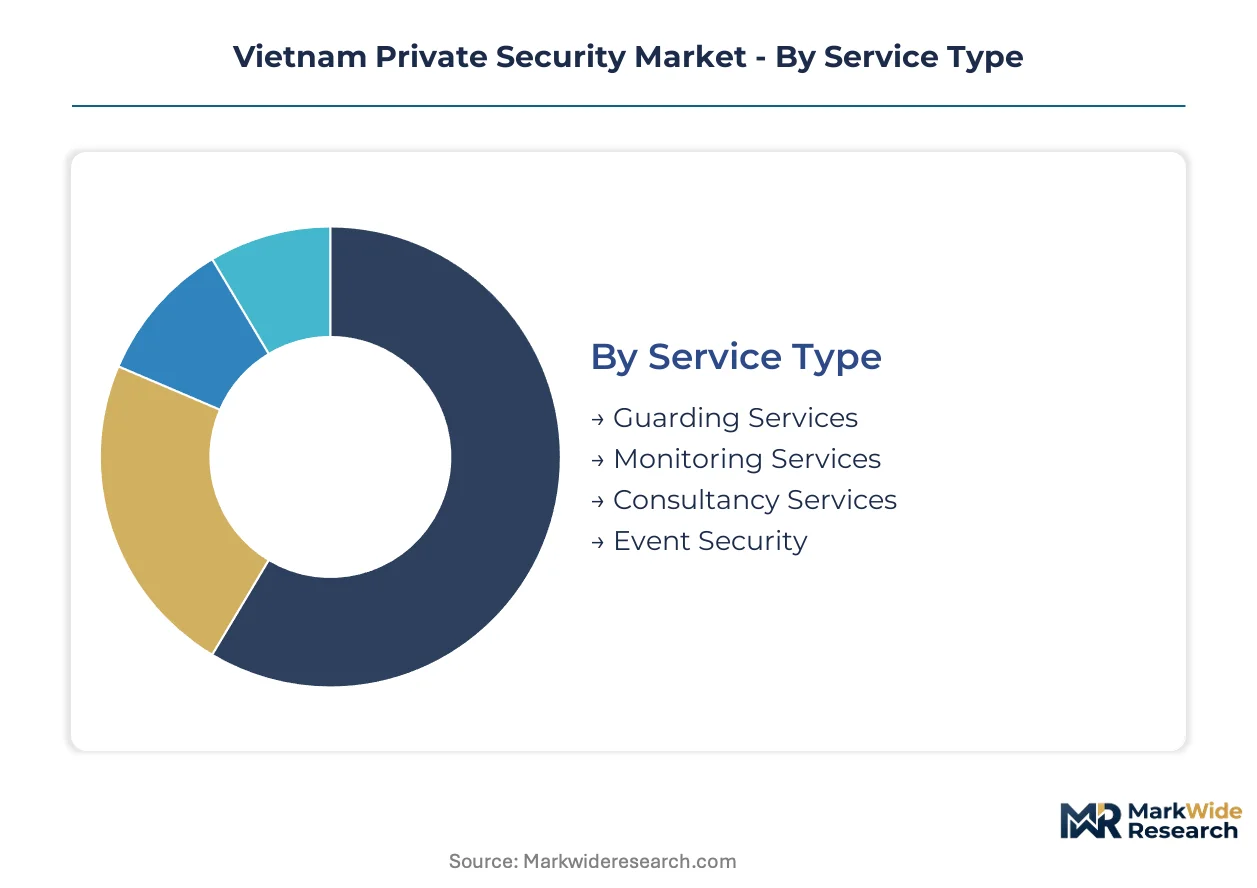
Segmentation in Vietnam's private security market reveals distinct procurement patterns across service modalities, end-use verticals, and technology integration levels. Foreign-invested manufacturers drive contract specifications that favor bundled guarding-technology solutions over standalone offerings.
Service Type:
Demand spans from labor-intensive physical presence to algorithm-driven remote oversight, with procurement decisions increasingly weighted toward integrated delivery models.
- Guarding Services:Licensed personnel deployment for perimeter control, access verification, and incident response at commercial and industrial facilities. Demand concentrates in Binh Duong and Dong Nai manufacturing corridors, where Korean and Japanese electronics assemblers mandate 24/7 physical presence for insurance compliance.
- Monitoring Services:Centralized command center operations combining video analytics, alarm verification, and mobile response coordination. Ho Chi Minh City and Hanoi command centers are displacing on-site supervisor headcounts as cloud-connected platforms enable multi-site oversight.
- Consultancy Services:Risk assessment, security audit, and protocol design delivered to banking and energy sector clients.
- Event Security:Temporary personnel deployment and crowd management for corporate and public gatherings.
Established volume favors Guarding Services; emerging adoption favors Monitoring Services.
End User:
Customer archetypes range from price-sensitive residential communities to compliance-driven multinational facilities, each imposing distinct certification and liability requirements.
- Residential:Gated community and apartment complex contracts emphasizing access control and patrol services. Secondary cities including Can Tho and Hai Phong are generating contract growth as urbanization accelerates.
- Retail:Loss prevention and customer safety services for shopping centers and franchise networks.
- Banking:Integrated guarding and alarm monitoring for branch networks expanding into tier-three urban centers. State-owned and joint-stock banks are standardizing security protocols across provincial deployments.
- Oil & Gas:Critical infrastructure protection combining perimeter surveillance with emergency response protocols.
Banking verticals anchor contract standardization; industrial corridors drive technology integration premiums.
Technology:
Hardware procurement patterns separate providers capable of recurring software maintenance from installation-only vendors.
- CCTV Systems:IP-based video surveillance with edge analytics and cloud storage integration. Electronics manufacturers in Bac Ninh and Thai Nguyen are replacing analog infrastructure with networked platforms requiring certified technician support.
- Intrusion Detection:Perimeter sensors and motion detection systems for facility boundary protection.
- Access Control:Biometric and card-based entry management systems.
- Alarm Systems:Intrusion alert infrastructure with Ministry of Public Security certification requirements.
Margin capture concentrates in CCTV Systems; compliance complexity elevates technical certification barriers across all technology categories.
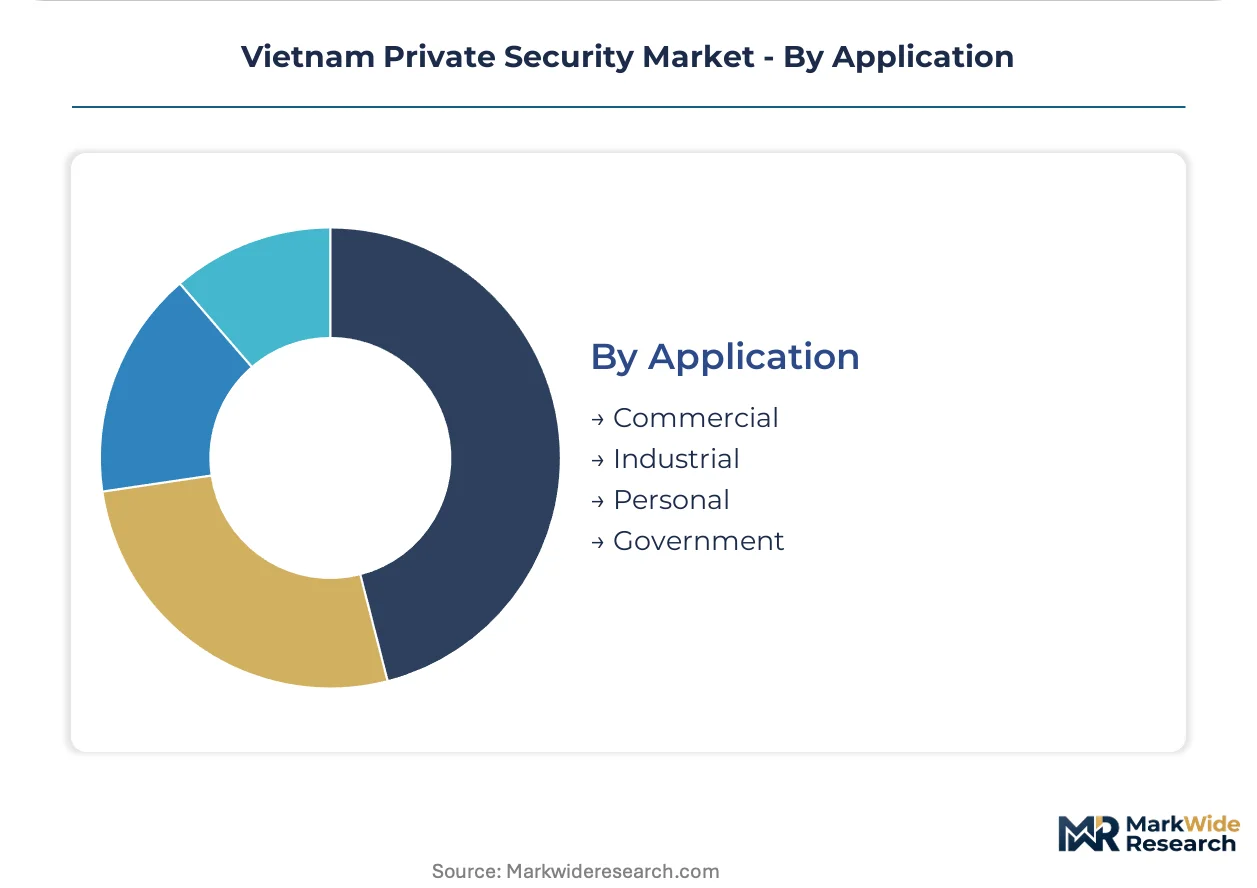
Application:
Deployment contexts determine regulatory jurisdiction, with provincial People's Committees imposing non-harmonized operating permit requirements.
- Commercial:Office buildings, retail centers, and hospitality facilities in Ho Chi Minh City and Hanoi. Foreign property developers are unbundling facility services, creating separate procurement streams for guarding and electronic surveillance.
- Industrial:Manufacturing parks and logistics warehouses across southern and northern provinces. Japanese automotive investors are consolidating vendor relationships through integrated facility management contracts.
- Personal:Executive protection and residential security for high-net-worth individuals.
- Government:State facility protection under Ministry of Public Security oversight.
Industrial applications command technology integration premiums; commercial contracts fragment across specialized providers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ho Chi Minh City commands 35-40% pricing premiums over Hanoi for equivalent integrated guarding contracts, reflecting foreign manufacturing density in southern industrial corridors versus state-sector concentration in the north.
Southern Key Economic Region
Binh Duong and Dong Nai provinces anchor contract volume through Korean and Japanese electronics assemblers mandating 24/7 physical presence for insurance compliance. Provincial People's Committees in these jurisdictions enforce Decree 96/2016/ND-CP licensing with additional local operating permits that extend setup timelines. The manufacturing corridor stretching from Ho Chi Minh City to Bien Hoa generates the highest technology integration premiums as cloud-connected surveillance displaces on-site supervision.
Red River Delta
Bac Ninh and Thai Nguyen provinces attract northern expansion from mainland Chinese electronics suppliers relocating assembly operations. The Ministry of Public Security maintains stricter training hour verification protocols in this jurisdiction compared to southern provinces. Japanese automotive investors in Vinh Phuc are unbundling facility services, creating separate procurement streams for guarding and electronic surveillance.
Central Coast
Da Nang and Quy Nhon logistics corridors remain underpenetrated relative to northern and southern industrial zones, lacking established security service density. Provincial permit fragmentation in this region creates longer market entry timelines for firms seeking national coverage. The warehousing zones around these port cities present first-mover positioning for providers capable of deploying hybrid guarding-technology bundles.
Mekong Delta
Can Tho generates contract growth as urbanization accelerates residential and commercial security demand in tier-three urban centers. State-owned banks extending branch networks into this region require standardized guarding protocols and centralized alarm monitoring infrastructure. Secondary city expansion here operates at lower contract values than Ho Chi Minh City equivalents due to reduced foreign direct investment density.
Vietnam Private Security Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in pure-play guarding or labor supply. The market structure concentrates contract volumes among capitalized firms with dedicated regulatory affairs capacity, filtering informal competitors through Decree 96/2016/ND-CP enforcement. Three archetypes dominate: industrial zone specialists with long-standing foreign investor relationships, technology-integrated service bundlers combining personnel with remote monitoring, and labor-supply anchors controlling recruitment pipelines. Competitive moves center on procurement consolidation mandates for single-source facility vendors and cross-border contract extensions through GB standards alignment.
Among Vietnamese-established operators, PMV Security and Vietnam Manpower occupy distinct positions within the competitive structure. PMV Security exemplifies the industrial zone specialist archetype, while Vietnam Manpower anchors the labor-supply side of personnel-intensive contracts. Securitas represents the multinational integrator model competing through technology-integrated service bundles. These three entities collectively illustrate the market's segmentation across relationship-based industrial deployment, recruitment pipeline control, and technology-platform integration.
| Leading Market Players |
|---|
| Vietnam Manpower |
| PMV Security |
| Vietnam Day and Night Security Services Co., Ltd. |
| Night and Day Security Services Co. Ltd. |
| Securitas |
| Secom |
| T-Force Security |
| The Brink's Co. |
| Global Guardian |
| Others |
Pricing and Supply Chain Analysis
Ho Chi Minh City and its surrounding industrial corridor command 35-40% pricing premiums over northern equivalents, as Binh Duong and Dong Nai manufacturing density concentrates licensed security capacity and elevates procurement leverage for Korean and Japanese electronics assemblers. This southern supply concentration filters through to contract structures, where technology-integrated bundles capture margin premiums unavailable in labor-only guarding markets.
Pricing Analysis
The customization-premium spread between configured-to-order integrated guarding-technology bundles and standard manned guarding contracts runs wide across Vietnamese industrial zones. Contract-based long-term offtake dominates enterprise procurement, with price differentiation anchored in certification grade under Decree 96/2016/ND-CP and geographic delivery cost to provincial manufacturing parks. Pricing pressure stems from licensed personnel wage inflation as Ministry of Public Security training mandates constrain labor supply elasticity. State-owned banks and residential communities in secondary cities exhibit highest price sensitivity, while Japanese automotive investors in Thai Nguyen and Vinh Phuc demonstrate lowest sensitivity due to insurance compliance mandates.
Supply Chain Analysis
Export-control regimes on advanced video analytics chipsets and cloud management software limit flows from US and EU suppliers into Vietnamese security integrators, forcing reliance on Chinese and South Korean hardware alternatives. Component dependencies center on IP cameras from Hikvision and Dahua, edge computing hardware from Taiwanese ODMs, and fiber optic infrastructure from Chinese cable manufacturers. Single-source vulnerability concentrates in cloud platform data sovereignty uncertainty as Cybersecurity Law amendments threaten localization mandates. Distribution runs through direct enterprise sales teams for multinational manufacturers and provincial dealer networks for mid-tier commercial clients.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cloud-connected video analytics is compressing headcount requirements and restructuring competitive positioning across Vietnamese security services, with Decree 96/2016/ND-CP amendments accelerating consolidation toward capitalized platform providers.
For Market Incumbents: Build regulatory compliance moats through dedicated legal affairs capacity and pre-positioned provincial operating permits in Bac Ninh, Hai Phong, and Can Tho. Incumbents should deepen backward integration into recruitment pipelines to offset licensed personnel wage inflation, while capturing procurement consolidation mandates from Japanese automotive investors seeking single-source facility vendors. The threat of informal competitors filtering back through regulatory gaps demands sustained certification investment. For New Entrants and Emerging Players: Build out hybrid guarding-technology bundles targeting underpenetrated Central Highlands logistics corridors around Da Nang and Quy Nhon, where established security service density remains thin. The most penetrable segment lies in warehousing zones serving port expansion, with go-to-market execution anchored through GB standards alignment for Chinese electronics suppliers relocating from mainland assembly operations. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors platform integrators with recurring software maintenance revenue over pure-play guarding operators facing margin compression. Long-term viability rests on providers capable of virtualizing command center operations and certifying multi-site video analytics capabilities. The acquisition target archetype combines provincial permit portfolios with cloud-connected surveillance infrastructure. Watch for Cybersecurity Law finalization as the inflection signal restructuring technology procurement patterns.| Strategic Initiative | Industry Significance |
|---|---|
| Technology-Integrated Service Bundling | Combines guarding personnel with remote monitoring infrastructure to displace on-site supervisor headcounts in Binh Duong manufacturing parks. |
| Provincial Permit Portfolio Expansion | Accelerates market entry timelines across Bac Ninh, Hai Phong, and Can Tho through pre-cleared local operating licenses. |
| GB Standards Certification | Unlocks cross-border contract extensions from Chinese electronics suppliers relocating assembly to northern Vietnamese provinces. |
| Recruitment Pipeline Control | Captures labor-supply leverage for personnel-intensive residential and commercial contracts in secondary cities. |
| Cloud Platform Localization | Preempts Cybersecurity Law data sovereignty mandates by establishing domestic-hosted video management infrastructure. |
Research Methodology
Two parallel data streams informed the analysis: primary engagement with security service executives, regulatory affairs directors at multinational manufacturers, provincial licensing officers, and facility management procurement leads; and secondary validation through Ministry of Public Security decree filings, provincial People's Committee operating permit databases, industrial zone developer disclosures, and customs records on security hardware imports. Bottom-up triangulation across contract value estimates and top-down reconciliation against foreign direct investment flows anchored market sizing.
Forecast inputs incorporated service type segmentation across guarding, monitoring, consultancy, and event security modalities; technology integration levels from analog legacy to cloud-connected analytics; and end-user verticals spanning industrial manufacturing, banking, residential, and oil & gas applications. CAGRs were derived through regression analysis of historical contract volume patterns against FDI inflow projections and regulatory enforcement intensity. Industry-specific inputs included electronics assembler facility expansion timelines and state-owned bank branch network extension plans.
The forecast holds incumbent behavior within observed patterns; aggressive technology investment or acquisition moves by mid-tier operators would shift outcomes beyond modeled ranges. Material shifts in Cybersecurity Law finalization, provincial permit harmonization, or foreign manufacturing FDI diversion would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Security and Surveillance
Alarm Monitoring [Central Stations] Software Market
Security and Surveillance
North America People Screening Market
Security and Surveillance
Global Threat Intelligence Management Market
Security and Surveillance
Alarm Monitoring Software Market
Security and Surveillance
Air Cargo Security and Screening Systems Market
Security and Surveillance
North America Security Screening Market
Security and Surveillance
Surveillance Radars Market
Security and Surveillance
North America Security Testing Market
Security and Surveillance
Residential Security Market
Security and Surveillance
Private Security Market
Security and Surveillance
Explosive Detection Technology Market
Security and Surveillance
Manned Guarding Services Market
Security and Surveillance
Global Wireless Monitoring and Surveillance Market
Security and Surveillance
North America Cargo and Vehicle Screening Market
Security and Surveillance
Airport Baggage Screening Systems Market
Security and Surveillance
Air Cargo Security Equipment Market