
 Urban Security Screening Market | 2026-2036
Urban Security Screening Market Size, Share, and Industry Trends Forecast 2026-2036
Urban Security Screening Market Analytics
Software-defined threat detection is expanding the recurring revenue base for urban security screening vendors beyond hardware sales alone. Smiths Detection Group Ltd. leverages its service network across European transit hubs to sustain long-term contracts. Leidos Holdings Inc. anchors its position through deep integration with U.S. federal security infrastructure. Evolv Technologies Holdings Inc. differentiates via AI-driven weapons detection systems deployed at entertainment venues and sports stadiums.
Urban security screening encompasses the deployment of sensor arrays, imaging systems, and automated analytics platforms designed to identify concealed threats in high-footfall public environments, typically operating at throughput rates exceeding 2,000 persons per hour in mass transit configurations. The primary commercial purpose centers on preventing unauthorized weapons, explosives, and hazardous materials from entering controlled spaces while minimizing passenger friction. X-ray screening and biometric scanners command the largest installed base, though explosive detection systems are capturing disproportionate investment as regulatory thresholds tighten. Cloud-based solutions are outpacing on-premises deployments in new installations, reflecting municipal IT modernization budgets and centralized command-center architectures.
The U.S. Transportation Security Administration, EU Aviation Safety Agency, and Germany's Federal Police coordinate screening standards that directly shape vendor product roadmaps and certification timelines. The EU AI Act introduces conformity requirements for automated threat classification algorithms that will reshape R&D priorities for European deployments. Stakeholders must monitor how divergent transatlantic AI governance frameworks affect interoperability and export compliance for screening platforms.
Market Dynamics
Transit authorities in Germany, the United States, and the United Kingdom are accelerating replacement of legacy metal detectors with AI-enabled sensor arrays capable of discriminating weapons from personal electronics at passenger throughput rates exceeding 2,000 persons per hour.
Growth Catalysts
- EU AI Act conformity mandates:Automated threat classification algorithms deployed in European transit hubs must now meet standardized transparency and accuracy thresholds, forcing platform upgrades and expanding addressable market for certified vendors.
- Explosive trace detection integration:Mass transit operators in France and the Netherlands are embedding ion mobility spectrometry modules into existing X-ray tunnels to address evolving improvised explosive device signatures.
- Stadium and entertainment venue procurement:Sports franchises in Spain and Italy are deploying concealed weapons detection systems as standard ingress infrastructure, replicating aviation-security protocols in civilian entertainment architecture.
Market Restraints
- Semiconductor component concentration:Field-programmable gate arrays and high-speed analog-to-digital converters essential for real-time image processing depend on concentrated Asian foundry capacity, exposing European and North American integrators to supply disruption.
- EU AI Act algorithmic audit costs:Conformity assessment procedures for machine-learning threat classifiers impose six-figure certification expenditures that disproportionately burden mid-tier municipal procurement budgets.
- Millimeter-wave scanner technical ceilings:Current passive millimeter-wave imagers struggle to detect non-metallic threats concealed under multilayer clothing in high-humidity environments, limiting deployment latitude in subtropical transit corridors.
Strategic Opportunities
- India metro rail expansion:Delhi Metro Rail Corporation and Mumbai Metro are tendering for integrated screening platforms across 45 new stations, representing greenfield deployment absent legacy infrastructure replacement costs.
- Cloud-native command center architectures:Centralized threat data lakes are converging with municipal IT modernization budgets, enabling software-as-a-service revenue models that decouple vendor economics from hardware shipment cycles.
- Brazil urban security modernization:São Paulo and Rio de Janeiro transit authorities are piloting biometric-integrated screening corridors under federal public safety initiatives, opening Latin American market access for EU-certified platforms.
Industry Challenges
- Machine learning engineering talent scarcity:Vendors competing for computer vision specialists capable of training threat-detection models on sparse, security-classified datasets face recruitment friction against technology sector compensation benchmarks.
- Legacy analog system interoperability:Transit operators in older European metropolitan networks maintain decades-old screening hardware with proprietary communication protocols, complicating phased upgrades to IP-based sensor networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Urban Security Screening Market |
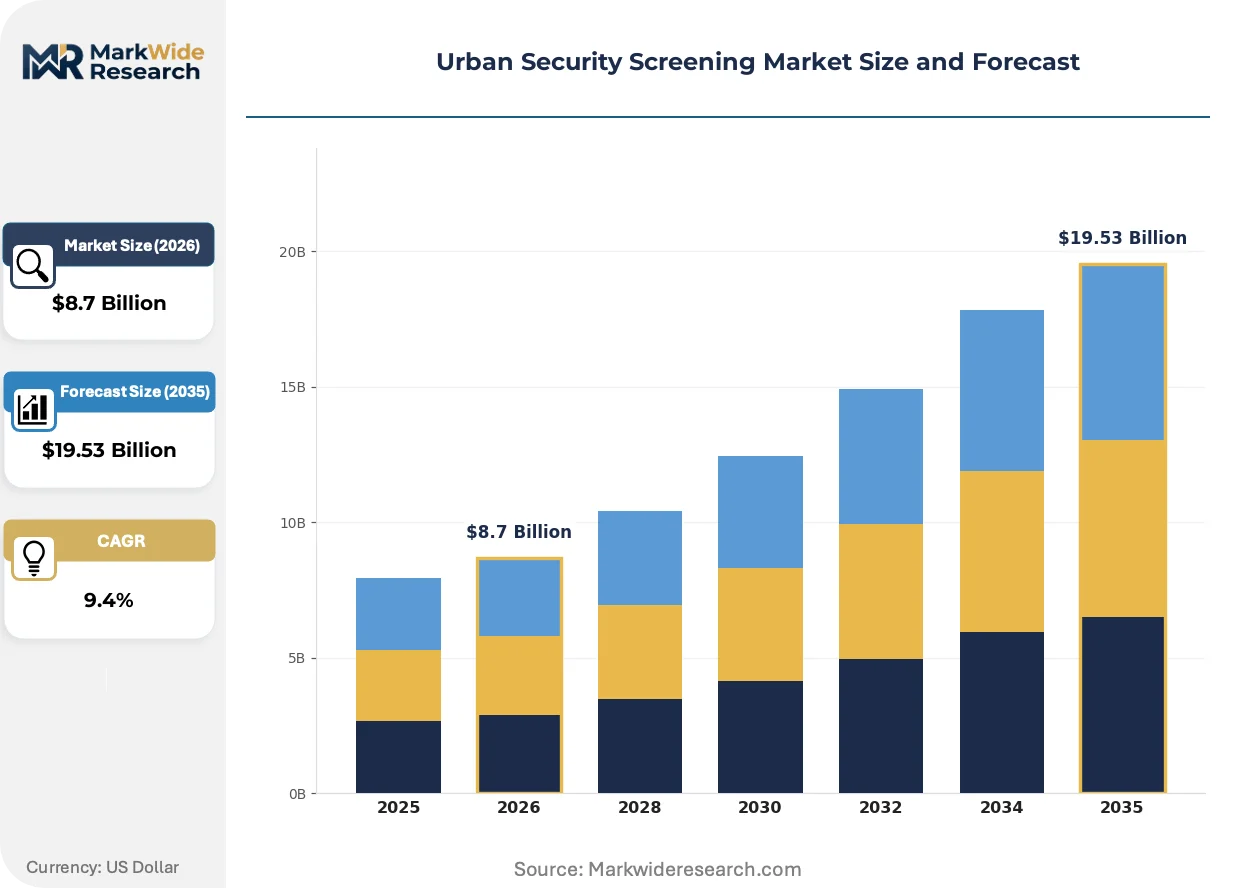
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application Type: Metal Detectors, X-ray Screening, Explosive Detection, Biometric Scanners End User: Government Agencies, Transportation Hubs, Entertainment Venues, Educational Institutions Technology: Passive Infrared, Ultrasonic Sensors, Surveillance Cameras, Artificial Intelligence Deployment Mode: Cloud-based Solutions, On-premises Systems, Hybrid Deployments, Mobile Units |
| Companies Covered | Nuctech Company Limited, OSI Systems Inc., Smiths Detection Group Ltd., Bruker Corporation, Astrophysics Inc., Leidos Holdings Inc., L3Harris Technologies, Evolv Technologies Holdings Inc., Rapiscan Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Urban Security Screening Market Evolving Landscape
Passive screening modalities are displacing active passenger pat-down protocols as primary threat detection layers, compressing labor costs while elevating sensor fusion and edge computing requirements for platform architects.
Multi-spectral imaging arrays combining active millimeter-wave and passive terahertz sensors are converging with deep learning inference engines to reduce false alarm rates below 5% in high-throughput mass transit configurations. Frankfurt Airport and Berlin Hauptbahnhof have operationalized these fused systems since 2023, establishing performance benchmarks that procurement specifications in Paris Charles de Gaulle and London Heathrow now explicitly reference. The structural consequence is compressing competitive differentiation around algorithm training dataset scale rather than hardware sensor specifications alone.
The EU AI Act introduces mandatory conformity assessment for automated threat classification systems deployed in public spaces, requiring documented accuracy thresholds and human oversight protocols for algorithmic decisions. This regulatory architecture elevates compliance costs for non-European vendors while creating certification moats for established European platform suppliers. German Federal Police technical standards for railway screening now explicitly reference AI Act conformity, diverging from U.S. Transportation Security Administration performance-based specifications that omit algorithmic governance requirements.
Outcome-based service contracts are displacing capital expenditure procurement models for urban screening infrastructure, with transit authorities in the United Kingdom and Netherlands preferring per-passenger-screened pricing tied to uptime guarantees and false alarm rate ceilings. This reconfiguration transfers operational risk to vendors while compressing hardware margin realization into extended service revenue streams. The shift is most visible in London Underground's station modernization program, where 15-year service concessions now outnumber direct equipment purchases in tender awards.
Urban Security Screening Market Segmentation
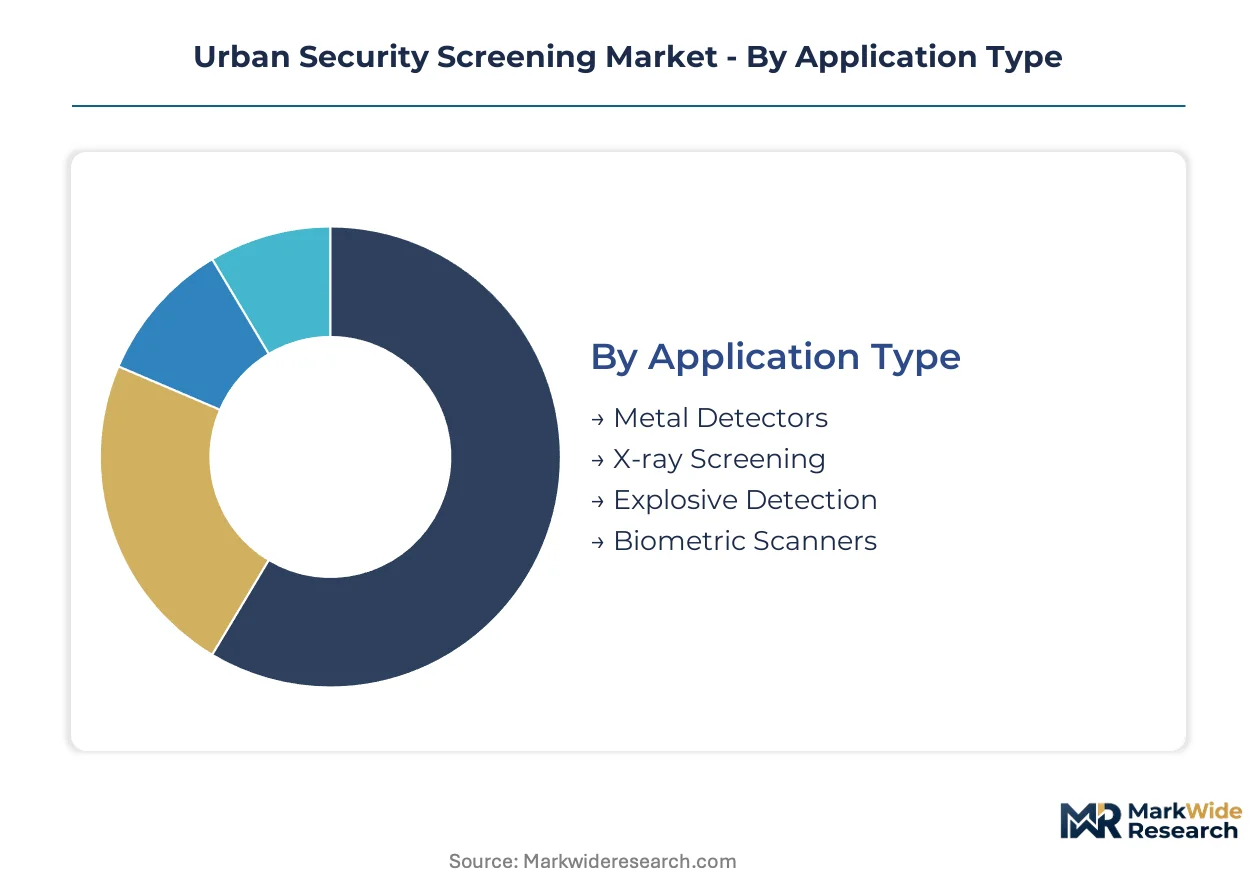
Urban security screening procurement decisions hinge on throughput requirements, threat specificity, and integration complexity with existing municipal infrastructure. Vendors structure product portfolios across four dimensions to match divergent operational constraints.
Application Type:
Transit authorities prioritize detection accuracy against passenger flow targets when selecting screening modalities for high-footfall environments.
- X-ray Screening:Dual-energy transmission systems discriminate organic from inorganic materials at conveyor speeds exceeding 0.5 meters per second. Frankfurt Airport and Berlin Hauptbahnhof have standardized on tunnel configurations processing 3,600 bags hourly, driven by EU Aviation Safety Agency baggage handling mandates.
- Explosive Detection:Ion mobility spectrometry and computed tomography platforms trace vapor and particulate residues at sensitivity thresholds below nanogram concentrations. France and the Netherlands are embedding these modules into existing X-ray tunnels to address evolving improvised explosive device signatures.
- Metal Detectors:Multi-zone walkthrough arrays remain the default for cost-constrained municipal deployments with moderate throughput requirements.
- Biometric Scanners:Facial recognition and fingerprint matching systems accelerate identity verification at immigration checkpoints.
X-ray Screening leads on scale; Explosive Detection leads on momentum.
End User:
Budget cycles and regulatory oversight intensity vary sharply across buyer categories, shaping contract duration and service bundling preferences.
- Transportation Hubs:Airports and railway terminals demand 99.5% uptime guarantees with sub-5% false alarm rates. London Underground's station modernization program now awards 15-year service concessions rather than direct equipment purchases, transferring operational risk to vendors.
- Government Agencies:Federal police and border control units procure certified platforms under national security procurement frameworks. Germany's Federal Police technical standards for railway screening explicitly reference EU AI Act conformity, diverging from U.S. Transportation Security Administration performance-based specifications.
- Entertainment Venues:Sports franchises in Spain and Italy deploy concealed weapons detection as standard ingress infrastructure, replicating aviation-security protocols in civilian architecture.
- Educational Institutions:Universities and K-12 districts represent emerging demand with limited capital budgets and dispersed geographic footprints.
Transportation Hubs concentrate procurement volume; Entertainment Venues are climbing the fastest.
Technology:
Algorithmic performance and sensor fusion capabilities now determine competitive differentiation more than hardware specifications alone.
- Artificial Intelligence:Deep learning inference engines process multi-spectral sensor feeds to reduce false alarm rates below 5% in high-throughput configurations. Multi-spectral imaging arrays combining active millimeter-wave and passive terahertz sensors converge with these engines at Frankfurt Airport and Berlin Hauptbahnhof, establishing benchmarks now referenced in Paris Charles de Gaulle and London Heathrow procurement specifications.
- Surveillance Cameras:High-resolution visible-spectrum and thermal imaging arrays provide behavioral analytics and post-incident forensic review.
- Passive Infrared:Motion detection systems trigger secondary screening protocols with minimal power consumption.
- Ultrasonic Sensors:Acoustic ranging platforms supplement optical systems in low-visibility environments.
Artificial Intelligence commands R&D investment intensity; Surveillance Cameras retain the broadest installed base.
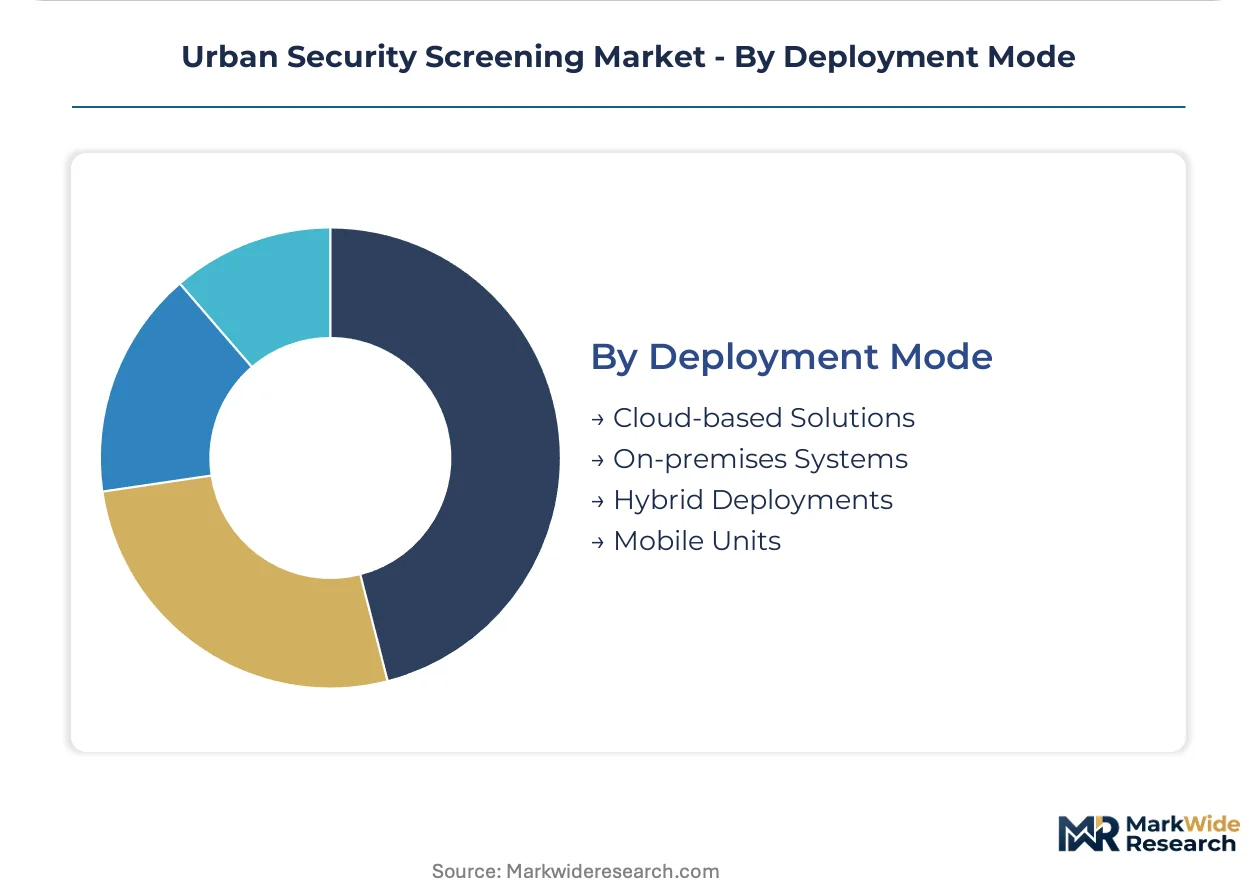
Deployment Mode:
IT modernization budgets and centralized command architectures are shifting procurement preferences away from capital-intensive on-premises installations.
- Cloud-based Solutions:Centralized threat data lakes integrate with municipal IT infrastructure, enabling software-as-a-service revenue models that decouple vendor economics from hardware shipment cycles. Cloud-native architectures are outpacing on-premises deployments in new installations across the United Kingdom and Netherlands.
- Hybrid Deployments:Edge processing for latency-sensitive detection combined with cloud analytics for pattern recognition and fleet management.
- On-premises Systems:Air-gapped configurations persist in classified government facilities with data sovereignty requirements.
- Mobile Units:Rapidly deployable screening trailers serve temporary events and emergency response scenarios.
Cloud-based Solutions are gaining share fastest; On-premises Systems retain dominance in classified environments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping vendor deployment strategies as the EU AI Act imposes six-figure certification costs that diverge sharply from U.S. performance-based specifications. Compliance cost differentials are concentrating platform development investment in jurisdictions with harmonized standards.
United States
The U.S. Transportation Security Administration maintains performance-based procurement frameworks that omit algorithmic governance requirements. Transit authorities in New York and Chicago are accelerating replacement of legacy metal detectors with AI-enabled sensor arrays. The TSA's Screening Partnership Program is expanding private sector participation at 22 airports nationwide.
Germany
German Federal Police technical standards for railway screening explicitly reference EU AI Act conformity, creating certification moats for established European suppliers. Frankfurt Airport and Berlin Hauptbahnhof have operationalized multi-spectral imaging systems since 2023. Bavaria's transit modernization program is tendering for 15-year service concessions rather than direct equipment purchases.
United Kingdom
London Underground's station modernization program now awards long-term service concessions transferring operational risk to vendors. The UK Home Office is coordinating screening standards with EU Aviation Safety Agency directives post-Brexit. Manchester and Birmingham transit hubs are piloting cloud-native command center architectures.
France
Paris Charles de Gaulle procurement specifications now explicitly reference Frankfurt Airport performance benchmarks for fused sensor systems. Mass transit operators are embedding ion mobility spectrometry modules into existing X-ray tunnels. The country's national cybersecurity regulator is tightening data sovereignty requirements for cloud-based screening platforms.
India
Delhi Metro Rail Corporation and Mumbai Metro are tendering for integrated screening platforms across 45 new stations. The Bureau of Indian Standards is developing localization requirements for critical security electronics. These greenfield deployments avoid legacy infrastructure replacement costs that burden European and North American operators.
Urban Security Screening Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with system integrators capturing premium pricing in transportation hubs while component suppliers serve cost-constrained municipal deployments. The vendor base concentrates around three tiers: multinational defense conglomerates with federal security infrastructure integration, European-certified platform specialists leveraging EU AI Act compliance moats, and emerging AI-native challengers attacking entertainment venue and sports stadium verticals. Dominant competitive moves include technology licensing partnerships for algorithm training datasets and geographic expansion through outcome-based service concessions.
Within the European-certified tier, Smiths Detection Group Ltd. and Nuctech Company Limited exemplify divergent strategic positioning. Smiths Detection leverages its service network across European transit hubs to sustain long-term contracts, while Nuctech's Chinese manufacturing base addresses cost-sensitive emerging market procurement. Leidos Holdings Inc. anchors the federal infrastructure integration archetype through deep relationships with U.S. security agencies. Evolv Technologies Holdings Inc. occupies a distinct position among AI-native specialists targeting weapons detection at civilian entertainment venues.
| Leading Market Players |
|---|
| Nuctech Company Limited |
| OSI Systems Inc. |
| Smiths Detection Group Ltd. |
| Bruker Corporation |
| Astrophysics Inc. |
| Leidos Holdings Inc. |
| L3Harris Technologies |
| Evolv Technologies Holdings Inc. |
| Rapiscan Systems |
| Others |
Value Network & Pricing Analysis
EU AI Act conformity mandates gate qualified supply access and premium-tier pricing power for urban security screening platforms, as vendors without certified algorithmic transparency documentation face exclusion from German Federal Police and EU Aviation Safety Agency procurement frameworks while commanding standard-tier margins.
Pricing Analysis
Capacity additions in India are reshaping price floors for standard-tier screening hardware, forcing mid-market vendors to differentiate through after-sales service bundling. Pricing stratifies across AI-certified premium, legacy-standard, and economy tiers based on algorithm accuracy thresholds and EU AI Act compliance documentation. Cost compression in the standard tier stems from Indian manufacturing scale, while transportation hubs with 99.5% uptime requirements show least price sensitivity.
Supply Chain Analysis
EU AI Act certification requirements gate component supplier qualification, limiting approved sources for field-programmable gate arrays and high-speed analog-to-digital converters to Taiwan, South Korea, and select U.S. fabs. Raw material dependencies span rare earth elements for sensor arrays, specialized substrates for millimeter-wave components, and security-grade encryption chipsets. Single-source vulnerability concentrates in advanced semiconductor foundry capacity. Distribution runs through systems integrators with federal security infrastructure clearance.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
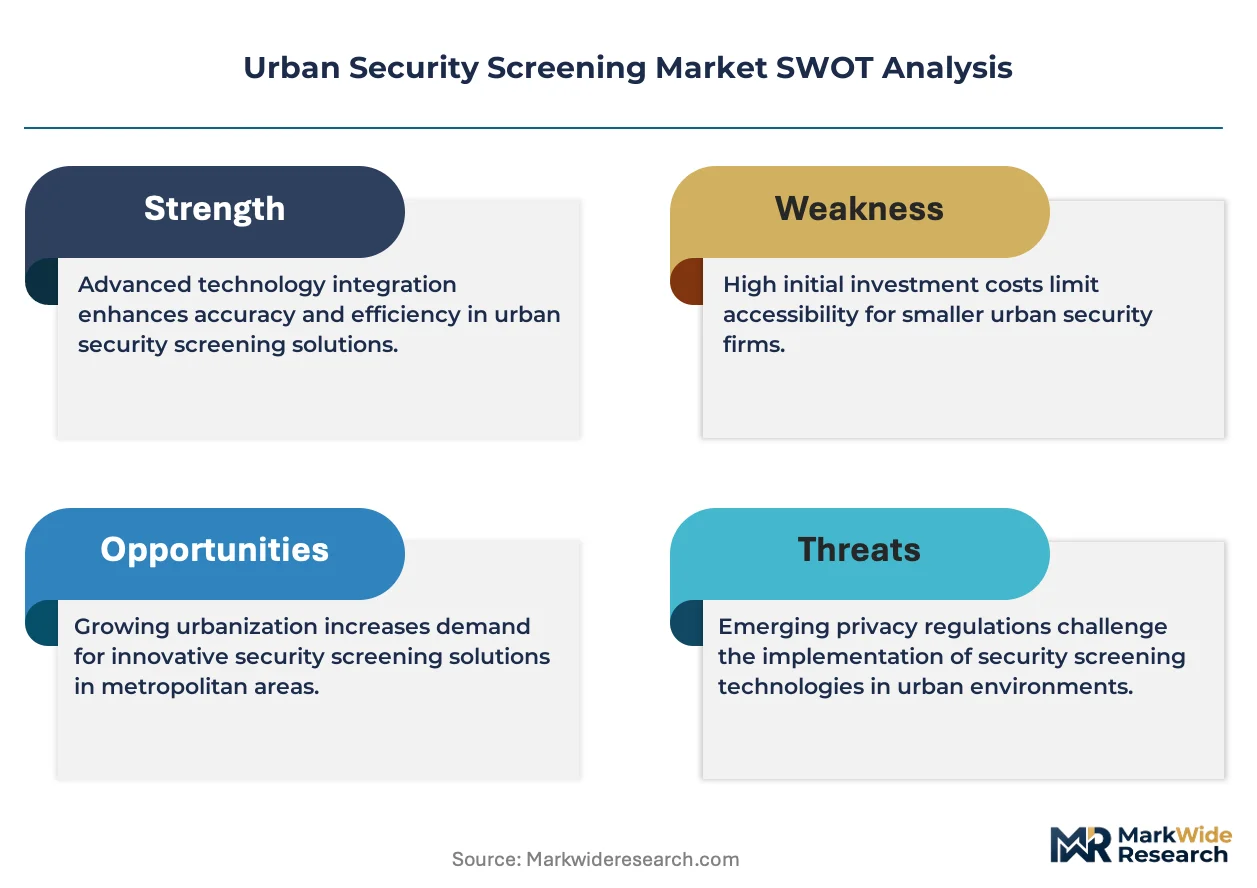
Urban security screening offers margin expansion through cloud-native service models that convert capital expenditure procurement into recurring revenue streams, as transit authorities shift from equipment ownership to per-passenger-screened contracts with uptime guarantees.
For Market Incumbents: Hedge against AI-native challengers by deepening algorithm training dataset partnerships with European federal police agencies. Acquire edge computing specialists to compress inference latency below rival platforms. Certification moats around EU AI Act conformity documentation defend pricing power in German and French procurement.
For New Entrants and Emerging Players: The premium-economy price gap in biometric-integrated screening corridors offers entry into Brazil's São Paulo and Rio de Janeiro transit pilots under federal public safety initiatives. Target educational institutions with dispersed footprints and limited capital budgets. Pursue hardware-as-a-service positioning to bypass upfront procurement friction.
For Investors and Strategic Acquirers: Roll-up economics work for regional service specialists because outcome-based contracts transfer operational risk to vendors and extend revenue visibility. Five-to-ten year viability hinges on cloud-native platform architecture. Monitor India metro rail tender awards as inflection indicator for emerging market demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Certification Investment | Documentation of algorithmic transparency creates procurement moats in German Federal Police tenders. |
| Cloud-Native Command Center Deployment | Municipal IT modernization budgets in Netherlands and UK enable SaaS revenue decoupled from hardware cycles. |
| India Metro Rail Market Entry | Greenfield deployment across 45 new stations avoids legacy replacement costs burdening European operators. |
| Multi-Spectral Sensor Fusion R&D | Frankfurt Airport benchmarks for combined millimeter-wave and terahertz arrays set procurement specifications. |
| Algorithm Training Dataset Partnership | Security-classified threat libraries from federal agencies differentiate false alarm performance below 5%. |
Research Methodology
Direct dialogue with transit authority procurement officers, federal police technical standards directors, platform engineering leads at screening vendors, and municipal IT modernization chiefs grounded qualitative findings. Secondary validation drew from EU Aviation Safety Agency certification databases, U.S. Transportation Security Administration procurement filings, German Federal Police technical standards documentation, and Bureau of Indian Standards draft localization requirements. Bottom-up station-level deployment tracking and top-down vendor revenue analysis were triangulated.
Bottom-up modeling aggregated individual transit hub procurement timelines, airport modernization budgets, and stadium security infrastructure investments across the projection horizon. Segmentation dimensions included application type, end-user category, technology tier, and deployment mode. CAGRs were derived from installed base replacement cycles and greenfield expansion trajectories. Forecast inputs incorporated EU AI Act implementation timelines and India metro rail construction schedules.
Caveats apply where EU AI Act enforcement intensity, semiconductor supply disruption, or India localization mandate timing could materially shift the outlook. A model refresh is warranted upon material change in federal security procurement framework revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Security and Surveillance
Prescriptive Security Market
Security and Surveillance
Global Intrusion Detection System Market
Security and Surveillance
Intrusion Alarm System Market
Security and Surveillance
Consumer Security Market
Security and Surveillance
Intelligent Fencing Market
Security and Surveillance
North America Cargo and Vehicle Screening Market
Security and Surveillance
India Electronic Security Market
Security and Surveillance
Asia-Pacific Urban Security Screening Market
Security and Surveillance
Underwater Security (Systems and Services) Market
Security and Surveillance
Global X-Ray Security Scanner Market
Security and Surveillance
North America Security Screening Market
Security and Surveillance
Global Container Security Market
Security and Surveillance
Security and Surveillance Equipment Market
Security and Surveillance
Smart Security in Healthcare Market
Security and Surveillance
Destructible Security Labels Market
Security and Surveillance
Global Security Policy Management Market