
 United States Data Center Physical Security Market | 2026-2036
United States Data Center Physical Security Market Size, Share, and Industry Trends Forecast 2026-2036
United States Data Center Physical Security Market Insights
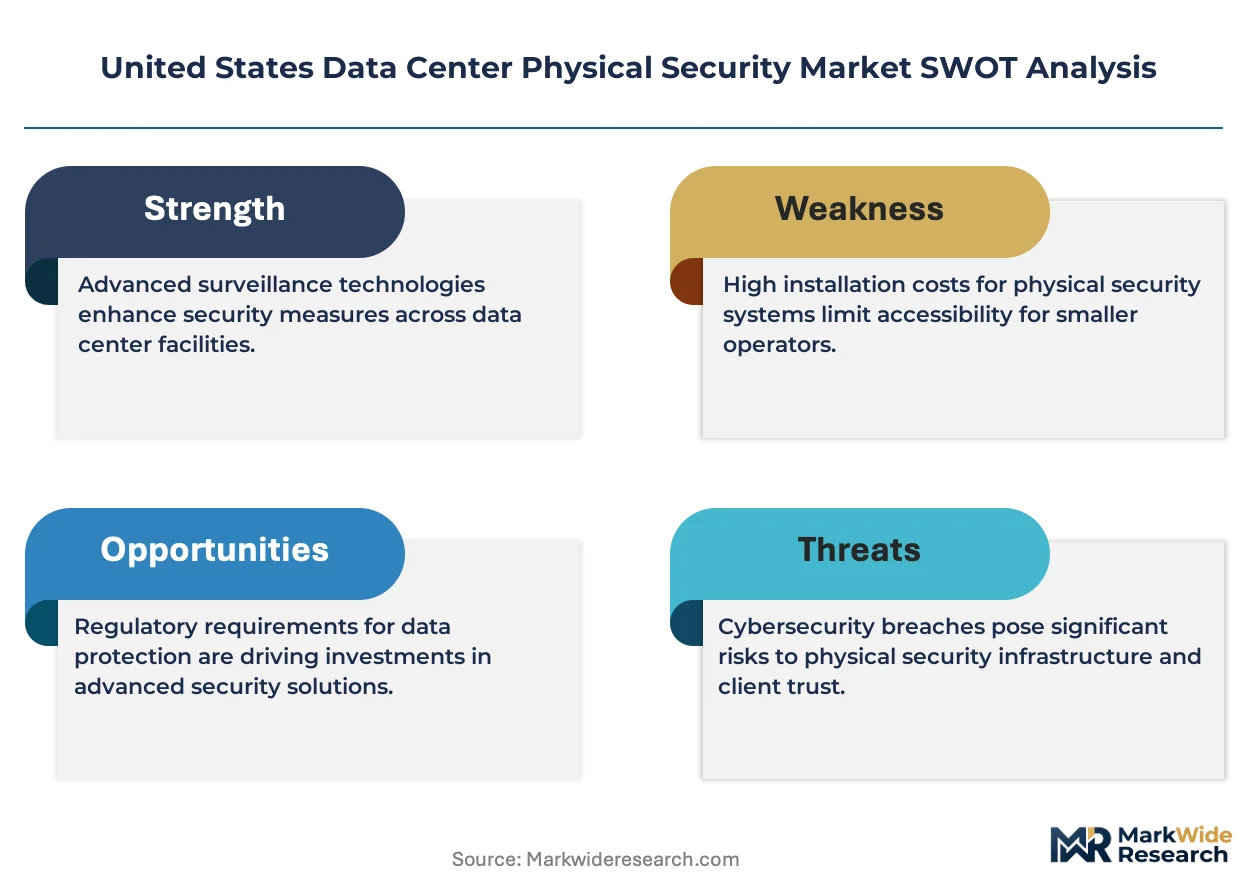
Hyperscale cloud operators are unwinding the traditional enterprise-dominated procurement model for data center physical security. Johnson Controls leverages its building automation heritage to anchor integrated security-environmental control packages. Schneider Electric competes through energy-efficient security infrastructure that reduces total facility power overhead. Genetec Inc. specializes in unified video and access platforms tailored to multi-tenant colocation environments.
Data center physical security encompasses layered protection systems—biometric access control, video surveillance with analytics, perimeter intrusion detection, and environmental threat monitoring—designed to safeguard critical computing infrastructure against unauthorized entry, sabotage, and natural hazards. These systems typically operate at 99.999% availability thresholds with sub-second alarm response protocols. Surveillance systems and access control together capture the largest share of solution spending, while environmental monitoring registers the fastest expansion as thermal and flooding risks intensify. Cloud-based and hybrid implementation models are gaining share against legacy on-premise deployments, though managed services still command premium pricing for Tier III and Tier IV facilities.
FERC reliability standards, NERC CIP cybersecurity-physical security convergence rules, and state-level data protection frameworks collectively mandate multi-factor authentication, video retention, and perimeter hardening. The Department of Homeland Security designates data centers as critical infrastructure, triggering additional federal security audit requirements. Stakeholders must weigh capital intensity against operational flexibility when selecting between integrated platform providers and best-of-breed component specialists.
Market Dynamics
Hyperscale cloud operators are compressing procurement cycles and demanding unified security-environmental platforms, forcing legacy component vendors to integrate or exit. NERC CIP compliance deadlines and state-level biometric mandates are accelerating replacement of standalone access systems with converged identity platforms.
Growth Catalysts
- NERC CIP-006 Perimeter Hardening:Electric utility-owned data centers must deploy intrusion detection and video surveillance meeting strict reliability standards, driving replacement demand across critical infrastructure facilities.
- Biometric Convergence:Multi-factor authentication combining facial recognition with mobile credentials is replacing card-based access in Tier III and Tier IV facilities seeking audit trail automation.
- Northern Virginia Cluster Density:Data Center Alley's concentrated facility footprint creates amplified security investment intensity as colocation operators compete on compliance certification visibility.
Market Restraints
- Semiconductor Supply Concentration:Video analytics chipsets and edge AI processors face sourcing constraints from concentrated East Asian foundry capacity, extending equipment lead times.
- Copper and Rare Earth Input Volatility:Perimeter cabling and magnetic sensor components expose security infrastructure margins to commodity price swings in construction-grade materials.
- Technical Integration Debt:Legacy building management systems with proprietary protocols resist API-based integration with modern security platforms, forcing costly middleware deployments.
Strategic Opportunities
- Texas Secondary Markets:Dallas-Fort Worth and emerging Austin-San Antonio corridors offer underpenetrated deployment potential as hyperscalers diversify beyond Northern Virginia.
- AI-Enabled Video Analytics:Behavioral recognition and anomaly detection algorithms are converging with thermal imaging to create premium service tiers for financial services tenants.
- IRA Energy Efficiency Incentives:Federal tax credits for facility efficiency upgrades indirectly subsidize integrated security-environmental control replacements reducing power overhead.
Industry Challenges
- Converged Skill Scarcity:Technicians fluent in both cybersecurity frameworks and physical access hardware remain scarce, inflating deployment and maintenance labor costs.
- Tier Certification Timelines:Uptime Institute and SOC 2 audit cycles extend 12-18 months, delaying revenue recognition for security upgrades tied to compliance milestones.
- Legacy PACS Migration Friction:Proprietary access control databases resist standardized export formats, complicating platform transitions for multi-tenant facilities with heterogeneous tenant systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Data Center Physical Security Market |
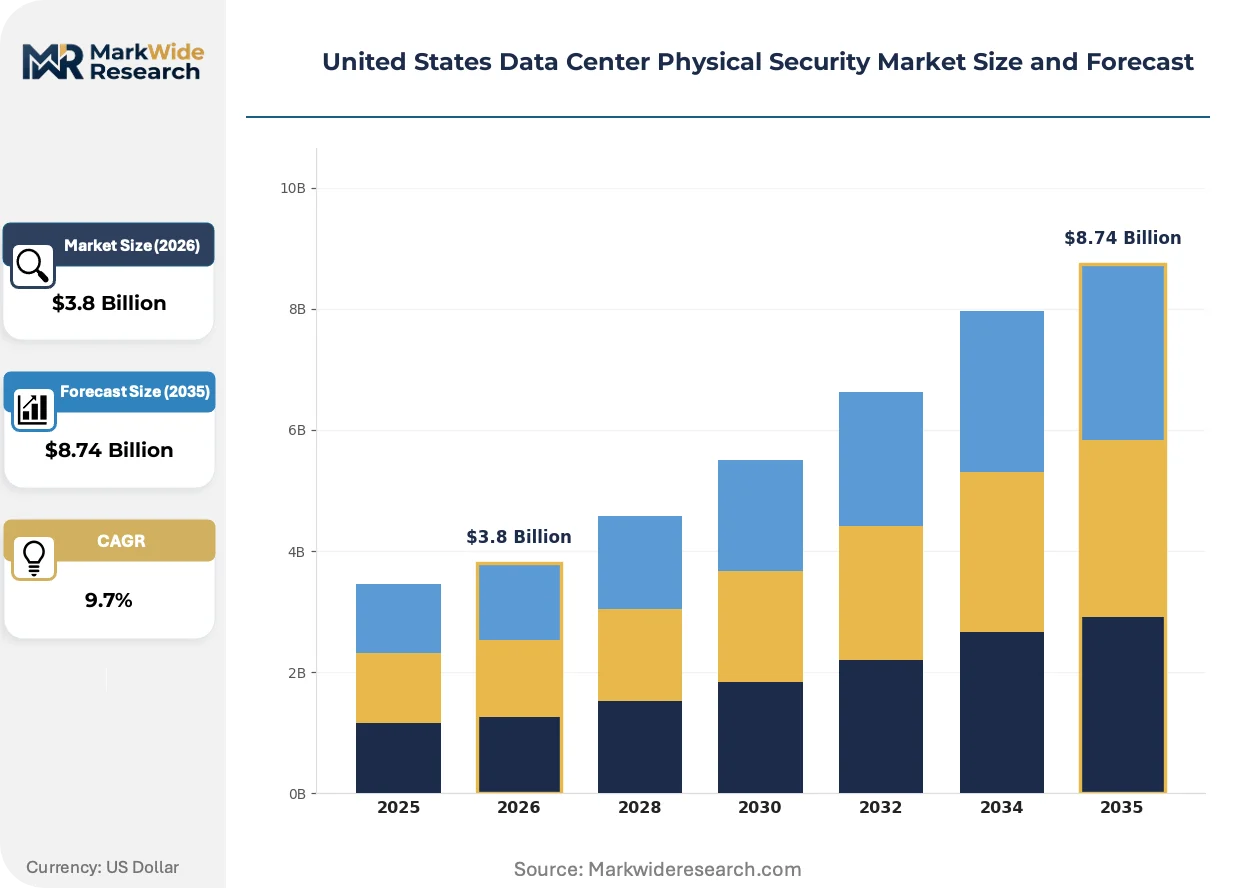
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.74 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Type: Access Control, Surveillance Systems, Intrusion Detection, Environmental Monitoring End User: Colocation Providers, Enterprises, Government Agencies, Telecommunication Companies Implementation Model: On-Premise, Cloud-Based, Hybrid, Managed Services Component: Hardware, Software, Services, Integration |
| Companies Covered | Axis Communications AB, Johnson Controls, Bosch Sicherheitssysteme GmbH, ABB Ltd, Securitas Technology, Honeywell International Inc., Schneider Electric, Genetec Inc., Cisco Systems, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Data Center Physical Security Market Trends and Innovations
Edge-native security architectures are collapsing the traditional perimeter-to-core hierarchy, distributing intelligence across facility entry points rather than centralizing processing. This structural reconfiguration demands new hardware form factors and software orchestration layers.
Frictionless access credentials leveraging smartphone-based digital wallets and Bluetooth Low Energy beacons are supplanting physical card and fob systems. Hyperscale operators are piloting these platforms at scale in Northern Virginia and Dallas-Fort Worth facilities. The shift is compressing credential provisioning from days to minutes while eliminating card inventory management overhead.
FERC reliability standards and evolving NERC CIP cybersecurity-physical security convergence rules are mandating encrypted video transmission and tamper-evident logging. Data center operators serving electric utilities must now demonstrate sub-second alarm correlation between cyber and physical events. Texas and Virginia facilities face the most intensive audit scrutiny due to concentration of utility-interconnected load.
Consumption-based service models for security infrastructure are displacing traditional capital purchase arrangements among mid-tier colocation providers. These operators prefer operational expenditure treatment for access control and surveillance upgrades. The pattern is most visible in secondary markets where credit availability constrains upfront facility investment.
United States Data Center Physical Security Market Segmentation
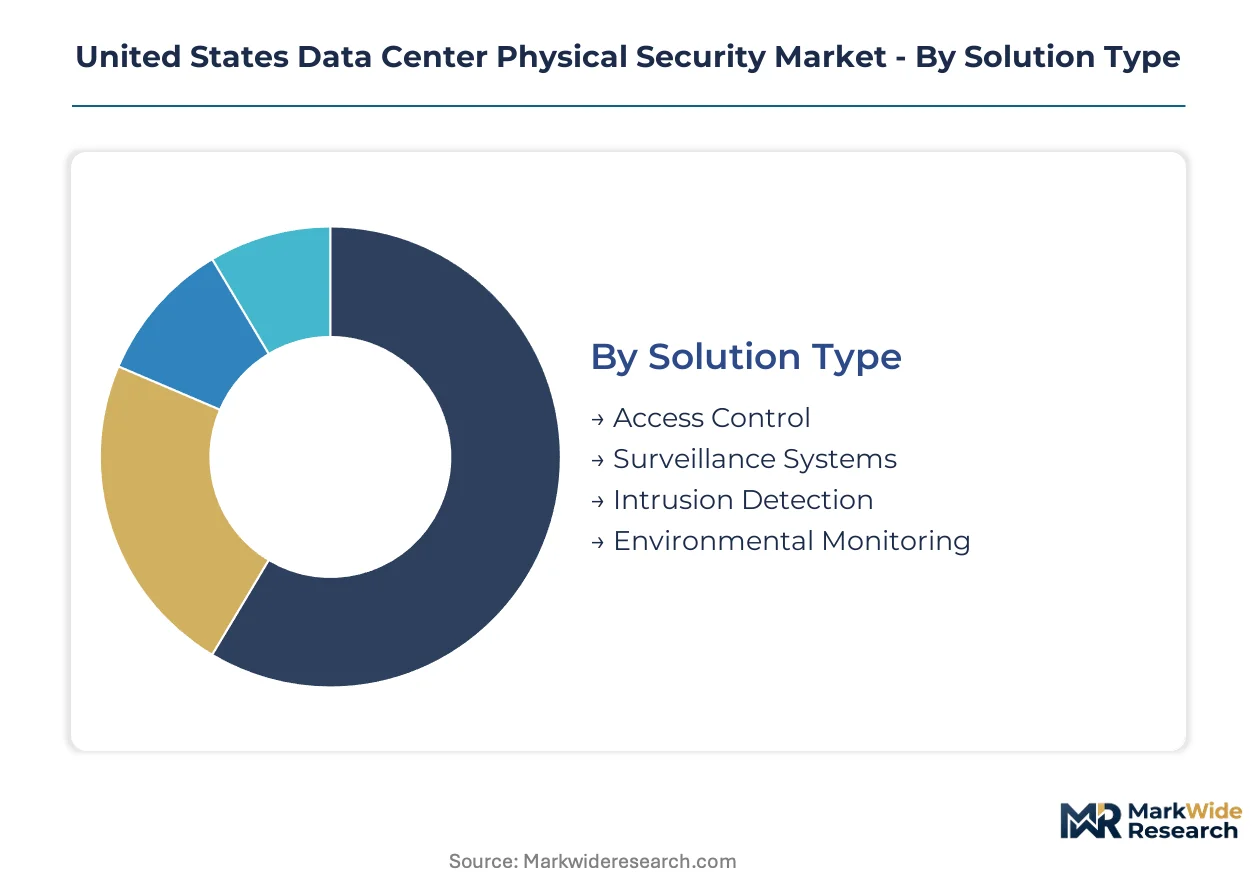
Security procurement patterns across the United States diverge sharply by facility tier and operator type. Hyperscale cloud deployments favor unified platforms while legacy enterprise sites maintain heterogeneous component stacks. Understanding these segment boundaries clarifies where integration pressure versus modular flexibility determines vendor selection.
Solution Type:
Domestic demand concentrates in perimeter hardening and biometric systems driven by NERC CIP mandates and Virginia state-level data protection frameworks. Export-oriented solution development remains minimal given the market's inward-facing regulatory complexity.
- Access Control:Multi-factor authentication systems combining facial recognition with mobile credentials dominate Tier III and Tier IV facility upgrades. Northern Virginia's Data Center Alley generates the densest deployment activity as colocation operators compete on SOC 2 audit readiness.
- Surveillance Systems:Video analytics platforms with edge AI processing enable sub-second alarm correlation required by FERC reliability standards. Dallas-Fort Worth hyperscale campuses are replacing legacy camera networks with encrypted transmission architectures ahead of compliance deadlines.
- Intrusion Detection:Perimeter sensor arrays with thermal imaging capabilities protect utility-interconnected facilities.
- Environmental Monitoring:Flooding and thermal risk sensors are expanding fastest among coastal and high-density compute facilities.
Surveillance systems command the established base. The steepest expansion runs through environmental monitoring.
End User:
Procurement scale varies dramatically across operator categories, with hyperscale cloud platforms compressing decision cycles while government agencies extend evaluation timelines through federal security audit requirements.
- Colocation Providers:Multi-tenant operators demand unified video-access platforms with tenant-segregated audit trails. Texas secondary markets including Austin-San Antonio corridors show underpenetrated potential as providers diversify beyond Northern Virginia saturation.
- Enterprises:Corporate data centers prioritize integration with existing building management systems over greenfield platform deployments. Financial services tenants in particular drive premium tiers for behavioral recognition analytics.
- Government Agencies:Federal facilities face Department of Homeland Security critical infrastructure designation triggering enhanced perimeter hardening mandates.
- Telecommunication Companies:Carrier hotel operators balance legacy PACS migration against converged identity platform adoption.
Colocation providers anchor current revenue concentration. Enterprise procurement is gaining share fastest as cloud repatriation accelerates security infrastructure refresh cycles.
Implementation Model:
Capital availability constraints in secondary markets are shifting preference toward operational expenditure treatment, while Tier III and Tier IV facilities maintain capital purchase arrangements for compliance certification visibility.
- On-Premise:Legacy deployments persist where air-gapped architectures satisfy electric utility NERC CIP isolation requirements. Virginia utility-interconnected data centers retain substantial on-premise video storage to demonstrate tamper-evident logging.
- Cloud-Based:Centralized security orchestration platforms reduce facility-level hardware footprints. Mid-tier colocation providers in Dallas-Fort Worth prefer cloud-based access control to accelerate multi-site credential provisioning.
- Hybrid:Edge-native architectures distribute intelligence across entry points while maintaining centralized policy management. This model addresses latency requirements for sub-second alarm response without full on-premise infrastructure burden.
- Managed Services:Premium-priced offerings dominate Tier III and Tier IV facilities where 99.999% availability thresholds demand specialized maintenance labor.
On-premise systems retain the installed base. Cloud-based and hybrid models are climbing the fastest as consumption-based service preferences spread.
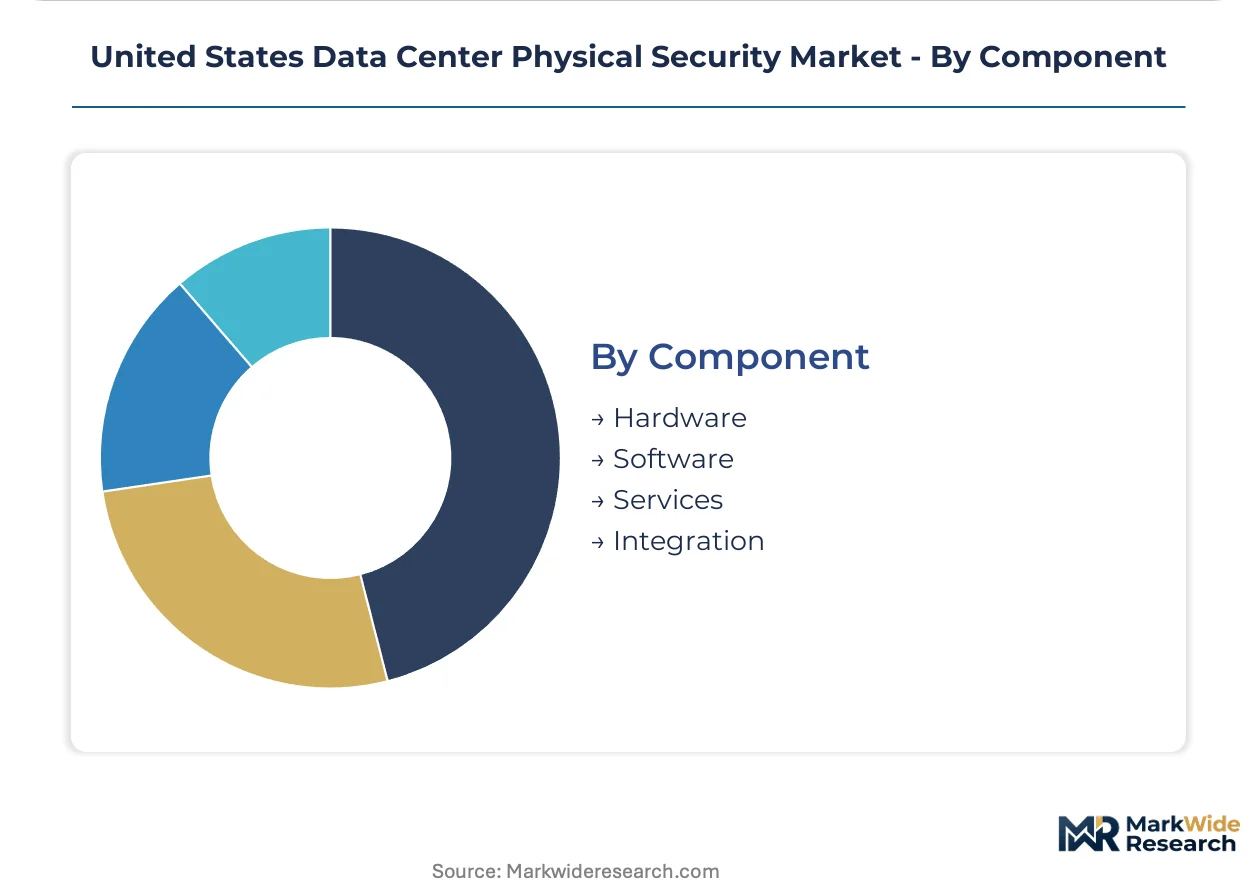
Component:
Supply chain concentration in East Asian foundries for video analytics chipsets and edge AI processors creates sourcing vulnerability across hardware procurement, while services margins expand with converged skill scarcity.
- Hardware:Biometric readers, thermal cameras, and perimeter sensors face extended lead times from semiconductor supply constraints. Copper and rare earth input volatility further pressures cabling and magnetic sensor component costs.
- Software:Unified security-environmental platforms with API-based orchestration layers command premium positioning. Behavioral recognition algorithms for financial services tenants represent a specialized development track.
- Services:Installation and maintenance labor costs inflate due to technician scarcity spanning both cybersecurity frameworks and physical access hardware expertise.
- Integration:Middleware deployments bridge legacy building management systems with proprietary protocols against modern API-based security platforms.
Hardware captures the dominant revenue share. Services are expanding most quickly as labor scarcity and managed service preferences compound.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Facility clustering in Northern Virginia and Dallas-Fort Worth concentrates security procurement scale, while state-level biometric mandates and FERC reliability standards create divergent compliance burdens across metropolitan markets.
Northern Virginia
Data Center Alley generates the densest physical security investment intensity in the nation. Virginia's biometric data protection statutes mandate encrypted credential storage for multi-tenant facilities. Loudoun County and Prince William County host hyperscale campuses where colocation operators compete on SOC 2 audit readiness through unified access-video platforms.
Dallas-Fort Worth
Texas utility-interconnected load concentration triggers intensive FERC and NERC CIP audit scrutiny. The state's absence of comprehensive biometric privacy laws accelerates facial recognition deployment relative to coastal jurisdictions. Irving and Plano hyperscale facilities are replacing legacy camera networks with encrypted transmission architectures ahead of compliance deadlines.
Phoenix
Arizona's arid climate reduces flooding risk but intensifies thermal monitoring requirements for high-density compute. State-level data breach notification laws mandate video retention periods for facilities handling financial services tenants. The Phoenix-Mesa corridor attracts secondary market investment as hyperscalers diversify beyond Northern Virginia saturation.
Chicago
Illinois biometric information privacy statutes impose strict consent protocols for facial recognition systems, lengthening procurement cycles relative to Texas. The state's central grid position supports utility-interconnected facilities subject to NERC CIP-006 perimeter hardening. Elk Grove Village and Aurora data centers face extended lead times for compliant access control upgrades.
Silicon Valley
California's Consumer Privacy Act and emerging biometric regulations create layered compliance complexity for physical security systems. Seismic risk mandates drive environmental monitoring investment intensity above national averages. Santa Clara and San Jose facilities prioritize thermal and structural sensors alongside traditional intrusion detection.
United States Data Center Physical Security Market Competitive Landscape
Concentration sits with diversified building technology conglomerates and specialized security platform vendors. The market structure reflects a bifurcation between integrated solution providers and component specialists. Johnson Controls and Schneider Electric anchor the integrated platform archetype, while Genetec Inc. occupies the unified software specialist position. Competitive dynamics center on M&A activity consolidating access control and video analytics capabilities, alongside strategic partnerships bridging legacy building management protocols with API-native security orchestration.
Among the named vendors in this study, Johnson Controls and Schneider Electric exemplify the building automation heritage archetype leveraging environmental control integration. Genetec Inc. represents the pure-play unified platform specialist focused on multi-tenant colocation workflows. Bosch Sicherheitssysteme GmbH and Axis Communications AB occupy positions within the European-engineered component tier, with geographic origin evident in their corporate designations. Honeywell International Inc. and Cisco Systems anchor the diversified technology conglomerate archetype, their scale enabling cross-subsidization of security-specific R&D. Securitas Technology represents the security services lineage transitioning toward technology-enabled delivery models.
| Leading Market Players |
|---|
| Axis Communications AB |
| Johnson Controls |
| Bosch Sicherheitssysteme GmbH |
| ABB Ltd |
| Securitas Technology |
| Honeywell International Inc. |
| Schneider Electric |
| Genetec Inc. |
| Cisco Systems |
| Others |
Pricing and Supply Chain Analysis
Hyperscale facility clustering in Northern Virginia and Dallas-Fort Worth generates procurement scale economies that compress vendor margins while elevating price floors for Tier III and Tier IV certification-grade systems. This concentration dynamic simultaneously tightens supply chain leverage toward East Asian semiconductor foundries and copper cabling suppliers, embedding commodity volatility directly into security infrastructure costs.
Pricing Analysis
Volume-discount tiering separates hyperscale cloud operators from mid-tier colocation providers from legacy enterprise sites, with the latter facing the steepest per-unit premiums due to fragmented procurement. Price differentiation hinges on Uptime Institute certification grade and NERC CIP compliance bundling, with utility-interconnected facilities absorbing premium markups for encrypted video architectures. Cost compression in the mid-tier colocation segment is intensifying because consumption-based service models displace capital purchases. Enterprise buyers with heterogeneous legacy stacks exhibit the highest price sensitivity, while hyperscalers prioritize total cost of ownership over unit pricing.
Supply Chain Analysis
Extended lead times for video analytics chipsets and edge AI processors signal inventory strain across security hardware procurement channels. Manufacturing concentrates in Taiwan, South Korea, and China for semiconductor components, while domestic suppliers dominate perimeter cabling and sensor assembly. Raw material dependencies span copper for cabling infrastructure, rare earth elements for magnetic sensors, and silicon carbide substrates for thermal imaging modules. Single-source vulnerability in East Asian foundry capacity exposes margins to geopolitical disruption. Distribution runs through authorized systems integrators and direct OEM relationships with hyperscale facility developers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United States data center physical security market rewards vendors who command converged cyber-physical expertise, a capability gap that inflates deployment costs and extends certification timelines. Organizations that bridge this scarcity through targeted workforce development or acquisition capture disproportionate margin in Tier III and Tier IV facility upgrades.
For Market Incumbents: Consolidate access control and video analytics capabilities through targeted acquisition of edge AI software specialists, defending against pure-play platform vendors eroding integrated market share. Deepen backward integration into thermal sensor manufacturing to offset rare earth input volatility and secure supply continuity for utility-interconnected facility deployments. For New Entrants and Emerging Players: Differentiate on frictionless credential platforms leveraging smartphone-based digital wallets, targeting the underpenetrated Austin-San Antonio corridor where hyperscalers diversify beyond Northern Virginia saturation. Pursue white-label partnerships with mid-tier Texas colocation providers seeking rapid SOC 2 audit readiness without capital-intensive platform builds. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors unified security-environmental platform vendors with established API orchestration layers over legacy component specialists facing integration debt. Long-term viability hinges on recurring revenue exposure through managed services contracts rather than transactional hardware sales. Monitor NERC CIP compliance deadline acceleration as the critical inflection signal for replacement demand intensity.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies video, access, and environmental control layers for hyperscale procurement efficiency. |
| Acquisition of Specialist Firm | Captures edge AI analytics capabilities required for FERC sub-second alarm correlation mandates. |
| Strategic Partnership | Bridges legacy building management protocols with API-native security orchestration layers. |
| Geographic Expansion | Establishes presence in Dallas-Fort Worth and Austin-San Antonio corridors ahead of hyperscale diversification. |
| Product Launch | Introduces frictionless mobile credential systems compressing provisioning from days to minutes. |
Research Methodology
A standing panel of data center facility directors, physical security operations managers, colocation procurement leads, and NERC CIP compliance officers provided ongoing calibration across primary fieldwork. Secondary validation drew from FERC reliability filings, Uptime Institute certification databases, state-level biometric privacy statutes, hyperscaler capital expenditure disclosures, and building automation industry trade data. Bottom-up facility-level procurement estimates triangulated against top-down market sizing derived from vendor revenue disclosures and systems integrator project pipelines.
Consistency checks validated volume and value outputs against external benchmarks including hyperscale construction permit data, electric utility interconnection queue filings, and security hardware import records. The analytical framework modeled demand across solution type, facility tier, implementation model, and operator category throughout the projection horizon. CAGRs were derived from segmented growth rate analysis incorporating NERC CIP compliance cycle timing, biometric mandate adoption curves, and regional facility construction pipelines.
Forecasts assume regulatory continuity in FERC reliability standards and state-level biometric privacy regimes; material policy shifts would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Physical Security
Global Wearable Security Device Market
Physical Security
Physical Security Services Market
Physical Security
Physical Security Equipment Market
Physical Security
Body Armor Market
Physical Security
Europe Physical Security Market
Physical Security
Tactical Vests Market
Physical Security
Policing Technologies Market
Physical Security
Global Data Center Physical Security Market
Physical Security
Body Armor Plates Market
Physical Security
Asia-Pacific Data Center Physical Security Market
Physical Security
Physical Security Market
Physical Security
France Data Center Physical Security Market
Physical Security
Europe Cargo Inspection Market
Physical Security
Security Market
Physical Security
North America Physical Security Market
Physical Security
Airport Full Body Scanner Market