
 Riot Control Equipment Market | 2026-2036
Riot Control Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Riot Control Equipment Market Analytics
Specialized polymer engineering talent is unwinding supply bottlenecks for next-generation protective gear. Safariland, LLC leverages deep vertical integration in ballistic materials to sustain premium positioning across North American police agencies. Rheinmetall AG anchors European demand through military-grade crowd control systems with hardened acoustic platforms. NonLethal Technologies, Inc. differentiates via concentrated R&D in irritant chemistry for constrained-geometry deployment.
Riot control equipment encompasses protective ensembles, chemical irritant formulations, kinetic impact projectiles, and area-denial systems engineered to neutralize threats without lethal force, typically rated to NIJ Level IIIA ballistic resistance or equivalent blunt-trauma standards for torso and cranial coverage. The primary commercial purpose centers on enabling state and private security actors to enforce public order while minimizing fatality risk in volatile crowd scenarios. Protective gear and non-lethal weapons together capture the dominant margin pool, with chemical agents facing reformulation pressure under tightening environmental compliance. Surveillance systems within the technology dimension are expanding fastest as AI-enabled drone and sensor platforms integrate with real-time command infrastructure.
FDA and EPA oversight in the United States governs irritant agent composition and environmental discharge, while the EU REACH framework and F-Gas Regulation restrict persistent chemical carriers and propellant systems. These standards compel manufacturers to redesign formulations and seek alternative delivery mechanisms, raising compliance costs but also creating technical barriers for new entrants. Stakeholders must monitor evolving export control classifications for acoustic and directed-energy platforms, as dual-use designations could reshape channel access and partnership structures.
Market Dynamics
EU Green Deal chemical restrictions are forcing wholesale reformulation of irritant agents, compressing product development cycles while opening technical moats for compliant suppliers across European and export markets.
Growth Catalysts
- Law enforcement modernization mandates:State police forces in India are executing multi-year equipment upgrade programs, expanding procurement volumes for protective ensembles and crowd-control systems.
- AI-enabled surveillance integration:Drone and sensor platforms with real-time command infrastructure are displacing legacy observation methods in volatile crowd scenarios.
- REACH compliance barriers:The EU's chemical framework is filtering out non-compliant suppliers, concentrating market share among reformulation-capable manufacturers.
Market Restraints
- Specialized polymer supply concentration:Engineering talent for next-generation protective gear clusters in Germany and the United States, creating bottlenecks for second-tier manufacturers.
- Propellant system redesign costs:F-Gas Regulation restrictions on persistent chemical carriers are elevating R&D expenditure for irritant delivery mechanisms.
- Ballistic materials input volatility:Aramid fiber and ceramic plate supply chains face price pressure from aerospace and automotive competing demand.
Strategic Opportunities
- Acoustic platform dual-use classification:Military-grade crowd control systems with hardened acoustic platforms are creating new export channels as defense budgets expand in Eastern Europe.
- Constrained-geometry irritant deployment:Urban riot scenarios are driving demand for compact chemical agent systems operable in narrow corridors and indoor environments.
- NIJ certification arbitrage:Level IIIA ballistic resistance standards are becoming procurement gatekeepers in Middle Eastern and Southeast Asian security markets.
Industry Challenges
- Cross-functional polymer engineering scarcity:Manufacturers struggle to recruit talent capable of integrating blunt-trauma standards with lightweight wearable design.
- Multi-jurisdiction certification timelines:Simultaneous FDA, EPA, and EU REACH approval processes extend product launch windows by 18-24 months.
- Legacy equipment integration friction:New sensor platforms face interoperability gaps with existing police command infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Riot Control Equipment Market |
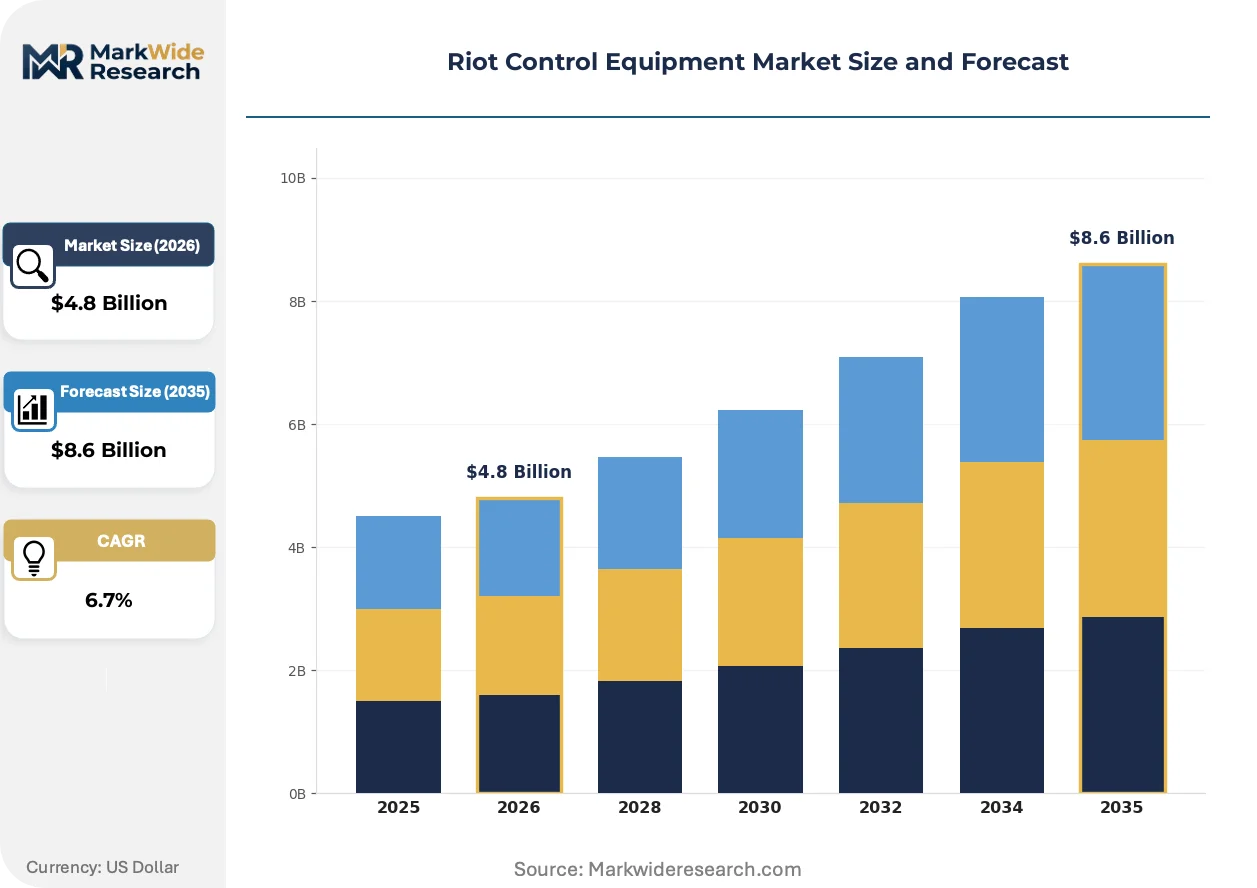
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Protective Gear, Chemical Agents, Water Cannons, Non-lethal Weapons Application: Crowd Management, Civil Unrest, Law Enforcement Training, Security Operations Technology: Ballistic Technology, Acoustic Devices, Irritant Delivery, Surveillance Systems End User: Police Agencies, Military Forces, Private Security, Government Organizations |
| Companies Covered | Combined Systems, Inc., Safariland, LLC, Axon Enterprise, Inc., NonLethal Technologies, Inc., BAE Systems Plc, Rheinmetall AG, Amtec Less Lethal Systems, Chemring Group PLC, Lamperd Less Lethal, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Riot Control Equipment Market Evolving Landscape
Three interconnected shifts are compressing traditional equipment categories while expanding the technology perimeter of crowd-control operations.
Smart textile architectures with embedded sensor networks are fragmenting the protective gear category. Municipal police departments in France and Germany are piloting biometric-monitoring ensembles that track officer vital signs during prolonged crowd engagements. This convergence of personal protection and real-time health data is fragmenting procurement decisions across separate IT and equipment budgets.
REACH and the EU F-Gas Regulation are mandating propellant system redesigns with accelerated phase-out timelines. Manufacturers are abandoning hydrofluorocarbon carriers in favor of mechanical compression and nitrogen-based delivery. Irritant chemistry specialists with in-house reformulation capabilities are capturing displaced market share from import-dependent distributors.
Consolidated procurement frameworks are displacing fragmented purchasing across Indian state police forces. Maharashtra and Uttar Pradesh have established centralized tendering for riot control inventories, compressing vendor relationships from dozens to handfuls. This concentration is visible across subcontinent security agencies as fiscal accountability mandates override historical supplier preferences.
Riot Control Equipment Market Segmentation
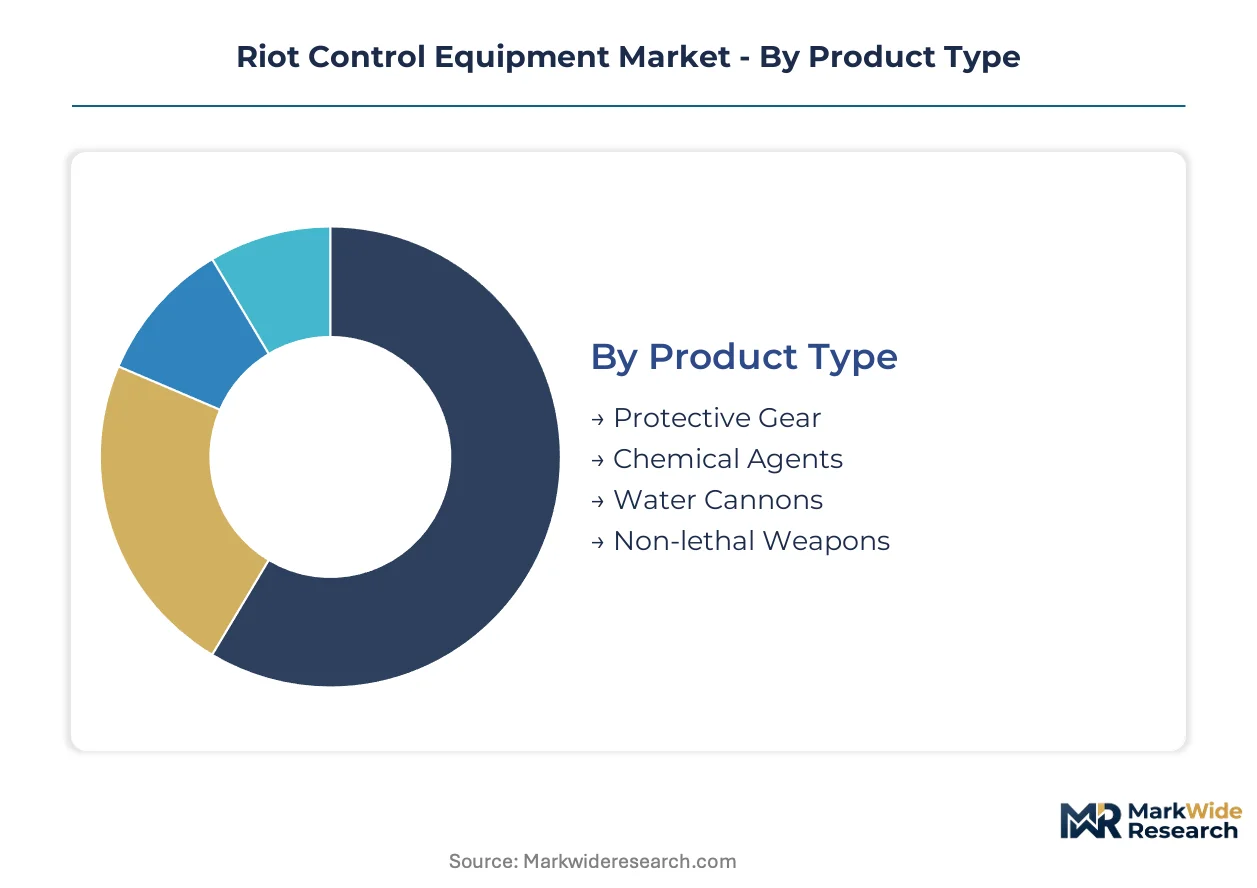
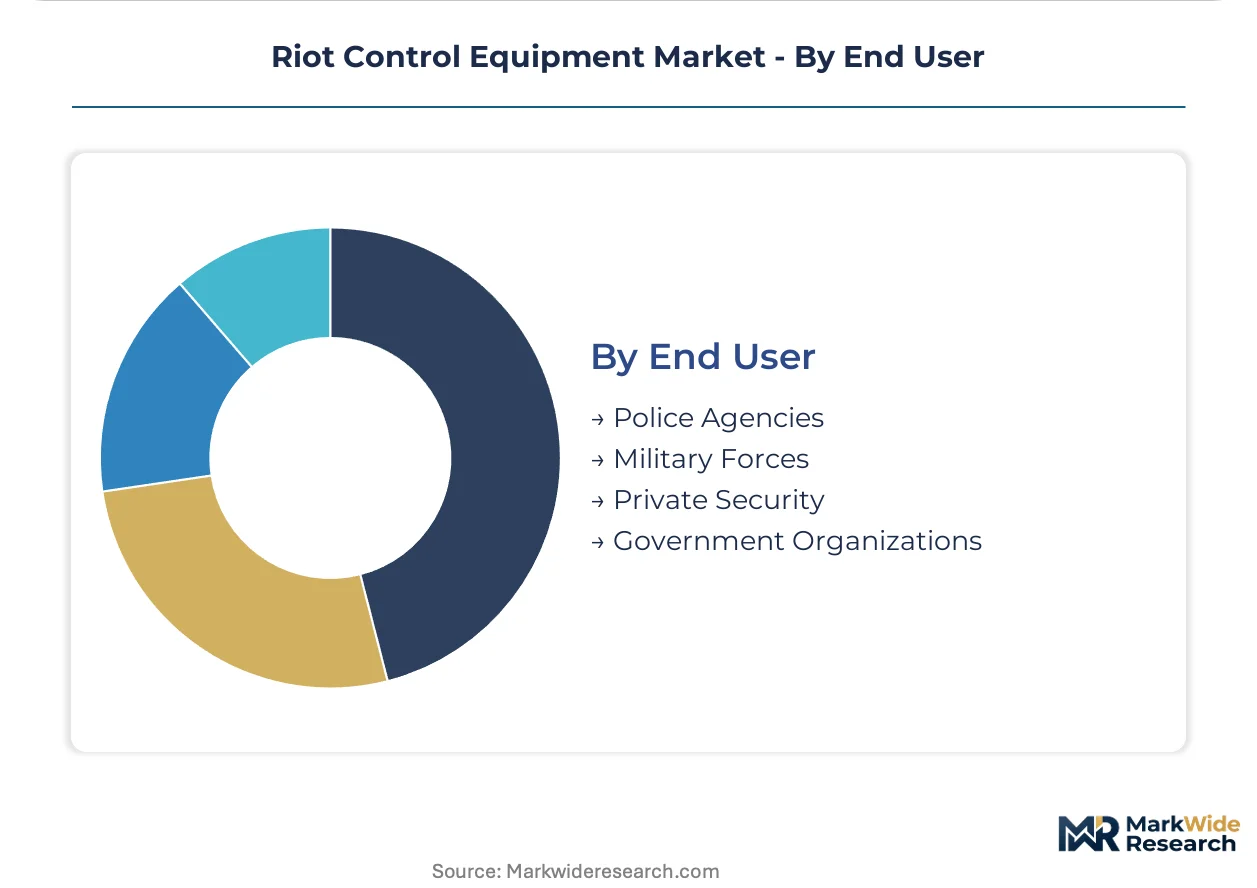
Procurement patterns across riot control equipment diverge sharply by institutional buyer type and deployment scenario. Channel access varies: police agencies favor certified domestic suppliers, military forces require hardened specifications, and private security operators prioritize rapid availability over compliance depth.
Product Type:
Channel concentration differs materially across these four categories, with protective gear and chemical agents flowing through established defense contractors while water cannons and non-lethal weapons reach end-users via specialized distributors.
- Protective Gear:Ensembles engineered to NIJ Level IIIA ballistic resistance integrate aramid fibers and ceramic trauma plates for torso and cranial coverage. Demand clusters in Indian state police modernization programs where Maharashtra and Uttar Pradesh centralize tendering for complete officer protection systems.
- Chemical Agents:Irritant formulations combine OC (oleoresin capsicum) or CS compounds with propellant systems now undergoing forced redesign under EU REACH and F-Gas Regulation constraints. European procurement is filtering toward reformulation-capable manufacturers with in-house chemistry capabilities.
- Water Cannons:Vehicle-mounted crowd dispersal systems with high-pressure delivery mechanisms serve municipal police departments facing large-scale assembly scenarios.
- Non-lethal Weapons:Kinetic impact projectiles and directed-energy platforms span baton rounds, rubber bullets, and acoustic deterrents rated for variable engagement distances.
Protective gear dominates installed base. Chemical agents are where expansion concentrates.
Application:
Cost tier stratification separates these four deployment contexts, with civil unrest scenarios commanding premium pricing for rapid-response capabilities while training applications tolerate extended procurement cycles.
- Crowd Management:Pre-planned event security at sporting venues and political gatherings demands portable barrier systems and surveillance integration. French and German municipal police pilot biometric-monitoring ensembles that fragment procurement across IT and equipment budgets.
- Civil Unrest:Rapidly escalating confrontation scenarios require hardened acoustic platforms and military-grade crowd control systems. Eastern European defense budgets are expanding procurement channels for these capabilities.
- Law Enforcement Training:Simulation environments and scenario-based instruction consume non-lethal ammunition and protective equipment at volume discounts.
- Security Operations:Critical infrastructure protection and VIP detail assignments prioritize concealable protection over area-denial systems.
Crowd management claims the largest operational footprint. Civil unrest applications are climbing the fastest.
Technology:
Supply concentration for specialized polymer engineering and irritant chemistry creates uneven access to these four technology domains, with ballistic and acoustic platforms bottlenecked by Germany and United States talent clusters.
- Ballistic Technology:Composite armor systems and trauma-resistant textiles require cross-functional polymer engineering scarce across second-tier manufacturers. Aramid fiber supply chains face competing aerospace and automotive demand.
- Acoustic Devices:Hardened sound projection platforms with directional beamforming are attracting dual-use export control scrutiny as defense applications expand.
- Irritant Delivery:Mechanical compression and nitrogen-based propellant systems are displacing hydrofluorocarbon carriers under EU regulatory phase-out timelines.
- Surveillance Systems:AI-enabled drone and sensor platforms with real-time command infrastructure are gaining share fastest as legacy observation methods face displacement.
Ballistic technology anchors current procurement volumes. Surveillance systems are where vendor investment concentrates.
End User:
Customer type determines certification burden and channel structure, with police agencies requiring multi-jurisdiction approvals while private security faces lighter compliance obligations.
- Police Agencies:Municipal and state forces across India, France, and Germany execute multi-year equipment upgrade programs with centralized tendering frameworks. Simultaneous FDA, EPA, and EU REACH approval processes extend product launch windows.
- Military Forces:Defense ministry procurement prioritizes hardened specifications and export-controlled acoustic platforms for contested environments.
- Private Security:Corporate and facility protection operators favor rapid procurement cycles and concealable protection systems over area-denial capabilities.
- Government Organizations:Border control and correctional facilities represent specialized demand for constrained-geometry irritant deployment in narrow corridors.
Police agencies dominate procurement volume. Private security is where channel expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India consumes riot control equipment through centralized state police tenders, while European procurement filters through REACH-compliant reformulation requirements, and North American demand channels toward integrated surveillance platforms.
United States
Municipal police departments prioritize AI-enabled drone platforms with real-time command infrastructure. FDA and EPA oversight governs irritant agent composition and environmental discharge standards. Engineering talent clusters in the Southeast and Southwest drive polymer innovation for next-generation protective ensembles.
Germany
Rheinmetall anchors European demand for military-grade crowd control systems with hardened acoustic platforms. The EU F-Gas Regulation restricts persistent chemical carriers and propellant systems. Bavaria and Baden-Württemberg host specialized polymer engineering clusters that unwind supply bottlenecks for ballistic materials.
India
Maharashtra and Uttar Pradesh state police forces execute multi-year equipment upgrade programs with centralized tendering frameworks. Domestic procurement policies favor BIS-certified suppliers for protective gear and crowd-control systems. Manufacturing activity concentrates in Tamil Nadu and Gujarat for irritant chemistry and textile armor production.
France
Municipal police in Paris and Lyon pilot biometric-monitoring ensembles that fragment procurement across IT and equipment budgets. EU REACH compliance creates technical barriers for non-reformulated chemical agents. The Île-de-France region attracts surveillance systems integration for pre-planned event security at sporting venues.
United Kingdom
Defense ministry procurement prioritizes hardened specifications for contested environment deployments. The UK operates under retained EU REACH regulations with independent chemical authorization processes. Greater Manchester and West Midlands police forces modernize protective ensembles through consolidated national frameworks.
Riot Control Equipment Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with the upper stratum controlling captive supply chains for ballistic fibers and irritant chemistry. The middle layer fragments across regional distributors lacking reformulation capabilities under tightening environmental compliance. Two strategic archetypes dominate: vertically integrated defense contractors with military-grade certifications, and chemistry specialists with in-house propellant redesign capabilities. Competitive moves concentrate on M&A for polymer engineering talent and strategic partnerships to bypass multi-jurisdiction certification timelines.
Among North American integrated suppliers, Safariland, LLC and Axon Enterprise, Inc. occupy positions that exemplify the premium-tier archetype through sustained relationships with municipal and state police agencies. Rheinmetall AG anchors the European defense-contractor segment, representing the hardened-specification vector for military-grade crowd control systems. NonLethal Technologies, Inc. sits within the specialist tier as a chemistry-focused entity navigating REACH-driven reformulation requirements.
| Leading Market Players |
|---|
| Combined Systems, Inc. |
| Safariland, LLC |
| Axon Enterprise, Inc. |
| NonLethal Technologies, Inc. |
| BAE Systems Plc |
| Rheinmetall AG |
| Amtec Less Lethal Systems |
| Chemring Group PLC |
| Lamperd Less Lethal, Inc. |
| Others |
Value Network & Pricing Analysis
90-to-120-day certification timelines for NIJ Level IIIA protective ensembles concentrate pricing power with Germany and United States manufacturers possessing captive polymer engineering talent, while REACH-compliant irritant chemistry commands persistent premiums over import-dependent distributors facing reformulation failure.
Pricing Analysis
Long-term offtake contracts dominate procurement for Indian state police modernization programs, with Maharashtra and Uttar Pradesh centralizing tendering across multi-year equipment upgrade cycles. Three-tier pricing structure across premium, standard, and economy levels separates NIJ-certified domestic suppliers from BIS-certified regional manufacturers and uncertified import distributors. Pricing pressure stems from F-Gas Regulation compliance costs elevating R&D expenditure for nitrogen-based propellant redesigns. Private security operators exhibit highest price sensitivity, tolerating extended procurement cycles for volume discounts, while military forces prioritize hardened specifications over unit cost.
Supply Chain Analysis
Inventory buffers for aramid fiber and ceramic trauma plates stretch 60-to-90 days as aerospace and automotive competing demand strains ballistic materials input channels. Manufacturing concentration clusters in Germany, the United States, and India, with Tamil Nadu and Gujarat hosting irritant chemistry and textile armor production. Raw material dependencies center on aramid fiber supply chains, ceramic plate feedstocks, and nitrogen-based propellant carriers. Single-source vulnerability persists for specialized polymer engineering talent concentrated in Bavaria and Baden-Württemberg. Distribution runs through established defense contractors for protective gear and chemical agents, with water cannons and non-lethal weapons reaching end-users via specialized distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach opportunities expand faster than hardware as AI-enabled surveillance platforms integrate real-time command infrastructure, generating recurring software licensing and maintenance revenue streams beyond initial equipment procurement.
For Market Incumbents: Fortify captive supply chains for ballistic fibers and irritant chemistry through backward integration into aramid fiber processing and in-house propellant reformulation capabilities. Certification investment in simultaneous FDA, EPA, and EU REACH approvals creates technical moats against import-dependent distributors facing 18-to-24-month launch windows. For New Entrants and Emerging Players: Anchor in constrained-geometry irritant deployment for urban riot scenarios in narrow corridors and indoor environments, where legacy suppliers lack compact chemical agent system portfolios. Private security channel expansion offers the most penetrable entry vector, prioritizing rapid procurement cycles and concealable protection systems over area-denial capabilities through specialized distributor partnerships. For Investors and Strategic Acquirers: Long-term, this sits as a compliance-arbitrage play because REACH and F-Gas Regulation phase-out timelines are filtering market share toward reformulation-capable manufacturers with in-house chemistry capabilities. Acquisition targets should display vertical integration in ballistic materials or irritant chemistry, with export control classification expertise for acoustic platform dual-use designations. Monitor EU Green Deal chemical restriction enforcement intensity as the primary inflection indicator for competitive repositioning.| Strategic Initiative | Industry Significance |
|---|---|
| NIJ Certification Investment | Maharashtra and Uttar Pradesh centralized tendering mandates Level IIIA compliance as procurement gatekeeper. |
| Propellant System Redesign | Nitrogen-based delivery mechanisms displace hydrofluorocarbon carriers under EU F-Gas Regulation constraints. |
| AI Surveillance Platform Integration | Real-time command infrastructure generates recurring software revenue beyond hardware procurement. |
| Polymer Engineering Talent Acquisition | Germany and United States clusters unwind supply bottlenecks for next-generation protective ensembles. |
| REACH Compliance Arbitrage | Reformulation-capable manufacturers capture displaced share from import-dependent distributors. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of regulatory filings, customs trade data, and state police tender documentation through structured interviews with protective equipment procurement officers, irritant chemistry R&D directors, defense ministry acquisition leads, and specialized distributor channel managers. Bottom-up demand modeling triangulates against top-down market sizing across product type, application, technology, and end user segmentation dimensions.
Segmentation dimensions modeled include protective gear, chemical agents, water cannons, and non-lethal weapons by product type; crowd management, civil unrest, law enforcement training, and security operations by application; ballistic technology, acoustic devices, irritant delivery, and surveillance systems by technology; and police agencies, military forces, private security, and government organizations by end user. CAGRs derive from weighted scenario analysis incorporating law enforcement modernization mandate intensity, REACH compliance timeline acceleration, and AI surveillance platform adoption curves across the analysis window.
Material uncertainties — regulatory enforcement intensity shifts, aramid fiber supply chain disruptions, and dual-use export control reclassifications — sit outside the modeled envelope. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Safety Equipment and Personal Protective Equipment (PPE)
Europe Safety Switches Market
Safety Equipment and Personal Protective Equipment (PPE)
Padlock Seals Market
Safety Equipment and Personal Protective Equipment (PPE)
Electrical Safety Analyzers Market
Safety Equipment and Personal Protective Equipment (PPE)
Smart Personal Protective Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Ballistic Floatation Vest Market
Safety Equipment and Personal Protective Equipment (PPE)
Driving Protection Gear Market
Safety Equipment and Personal Protective Equipment (PPE)
Hand Sanitizer Spray Pen Market
Safety Equipment and Personal Protective Equipment (PPE)
China Hand Sanitizer Market
Safety Equipment and Personal Protective Equipment (PPE)
Smart Barrier Gate Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Safes and Vaults Market
Safety Equipment and Personal Protective Equipment (PPE)
Emergency Showers Market
Safety Equipment and Personal Protective Equipment (PPE)
Africa Riot Control Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Middle East and Africa Safety Motion Control Market
Safety Equipment and Personal Protective Equipment (PPE)
Self-Contained Breathing Apparatus (SCBA) Cylinders Market
Safety Equipment and Personal Protective Equipment (PPE)
Protective Goggles Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Surgical Mask and Respirators Market