
 North America Security Services Market | 2026-2036
North America Security Services Market Size, Share, and Industry Trends Forecast 2026-2036
North America Security Services Market Insights
Subscription-based managed security contracts is tilting capital requirements away from heavy upfront infrastructure, allowing mid-scale operators to challenge legacy incumbents. Allied Universal leverages its national guard force footprint to bundle physical patrols with remote monitoring dashboards. Palo Alto Networks anchors enterprise cybersecurity demand through cloud-native threat detection platforms that compete with traditional perimeter defenses.
Security services encompass the provision of protective measures—spanning manned guarding, electronic surveillance, cyber threat monitoring, and risk consulting—delivered under contract to safeguard assets, personnel, and information against unauthorized access, theft, or disruption. These services integrate hardware sensors, software analytics, and trained human response teams to create layered defense architectures for commercial, institutional, and government clients. Managed services and cybersecurity application segments command expanding margin pools as clients shift from capital-intensive ownership to ongoing operational expenditure models. Video surveillance technology leads in deployment volume across corporate end users, while biometrics and intrusion detection systems represent faster-growth categories driven by zero-trust access mandates.
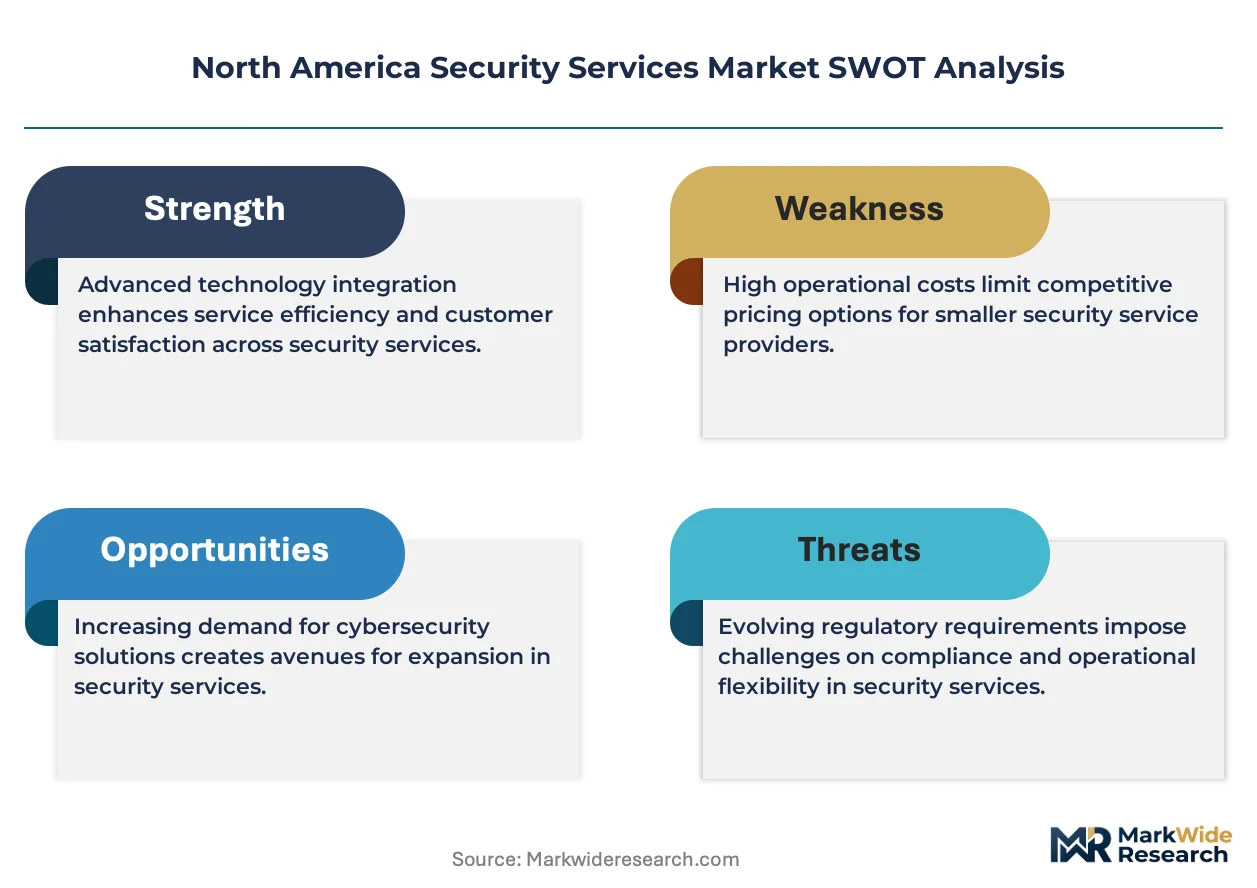
U.S. federal procurement rules, Canadian federal security clearance frameworks, and emerging state-level biometric privacy statutes in Illinois, Texas, and California collectively reshape vendor qualification requirements and liability exposure. The U.S. Department of Homeland Security and Transport Canada both tightened critical infrastructure protection standards, forcing service providers to certify personnel against updated threat-assessment protocols. Stakeholders must weigh the cost of compliance infrastructure against the pricing power that certified status confers in restricted contract bidding.
Market Dynamics
The migration from capital-intensive security infrastructure to subscription-managed service models is compressing vendor margins while democratizing access for mid-scale buyers across U.S. and Canadian enterprise accounts.
Growth Catalysts
- Biometric privacy statutes:Illinois BIPA and emerging Texas and California frameworks mandate vendor certification upgrades, creating contracted demand for compliant identity verification systems.
- Critical infrastructure protection:U.S. Department of Homeland Security tightened personnel certification protocols, forcing facility operators into recurring security service engagements.
- Zero-trust mandates:Federal government end-users require integrated physical-digital access platforms, bundling manned guarding with cyber-monitoring dashboards.
Market Restraints
- Personnel cost inflation:Licensed security guard wages in California and New York metropolitan corridors compress operator margins on fixed-price municipal contracts.
- Supply concentration in biometric sensors:Hardware dependence on concentrated semiconductor foundries creates vulnerability for integrated platform vendors.
- Fragmented municipal procurement:Non-standardized bidding requirements across U.S. states extend sales cycles and inflate compliance overhead.
Strategic Opportunities
- Canadian federal security clearance frameworks:Transport Canada infrastructure protection standards create certified vendor scarcity for cross-border operators.
- AI-enhanced video analytics:Machine vision convergence with edge computing enables predictive threat detection for corporate campus end-users.
- Remote monitoring channel expansion:Subscription dashboards bypass traditional guard-force intermediaries, opening direct enterprise relationships.
Industry Challenges
- Cyber-physical integration complexity:Legacy access control systems resist seamless API connection with cloud-native threat detection platforms.
- Clearance timeline bottlenecks:U.S. federal background check backlogs extend personnel deployment schedules for critical infrastructure contracts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Security Services Market |
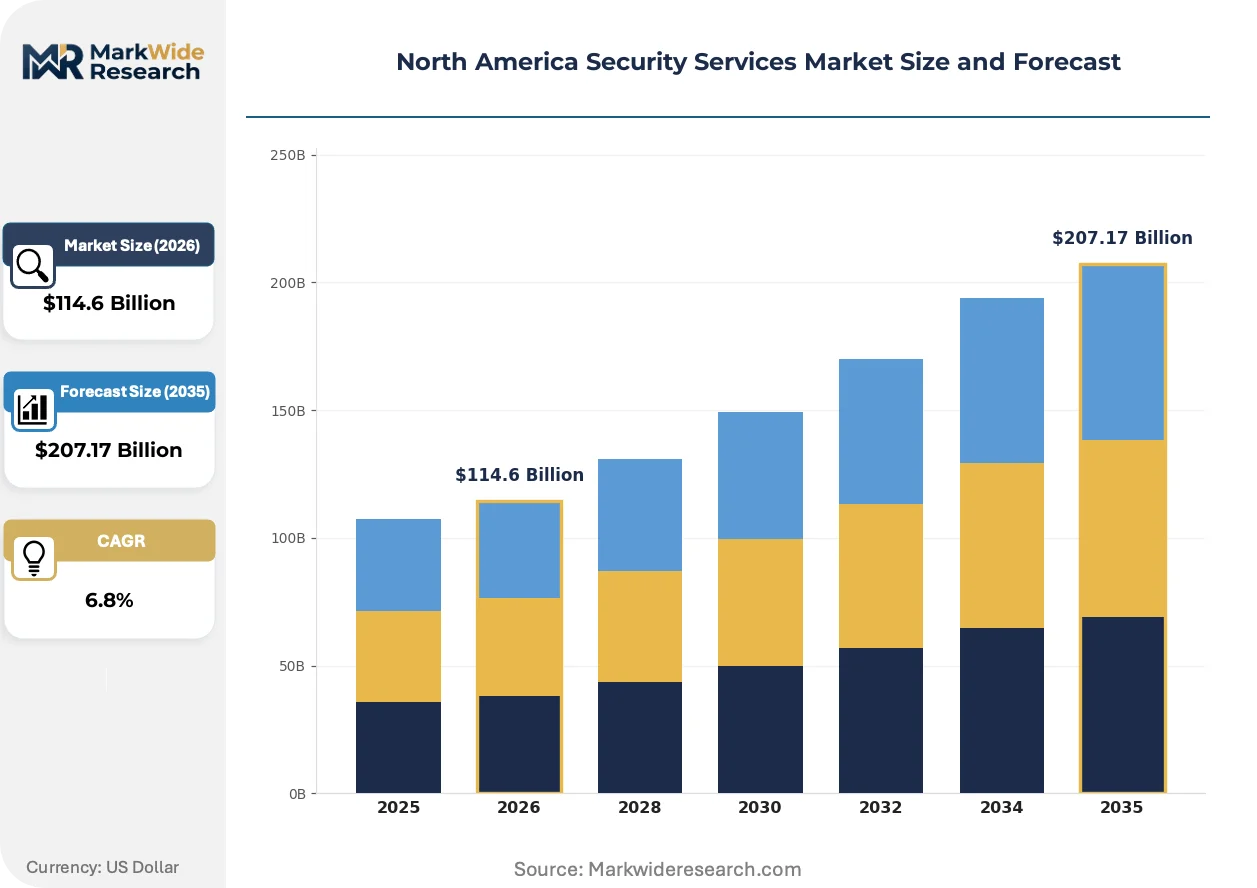
| Market Size in 2026 | $114.6 Billion |
| Market Size in 2035 | $207.17 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Monitoring, Consulting, Response, Managed Services End User: Government, Corporate, Residential, Healthcare Technology: Video Surveillance, Access Control, Intrusion Detection, Biometrics Application: Personal Security, Cybersecurity, Risk Management, Event Security |
| Companies Covered | Allied Universal, GardaWorld, ADT Security Services, Securitas Inc., G4S Limited, Palo Alto Networks, Honeywell International, Inc., Johnson Controls, Trustwave Holdings, Inc, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Security Services Market Trends and Innovations
Security service delivery is compressing around predictive, data-driven response models that merge sensor networks with automated dispatch systems, displacing reactive patrol-based architectures.
Cloud-native threat detection platforms are rendering obsolete perimeter-based firewall defenses in enterprise cybersecurity procurement. Financial services and healthcare end-users in the U.S. Northeast are adopting these platforms at accelerated replacement cycles. Traditional managed security providers face compression in hardware resale margins as software subscriptions capture value.
Illinois BIPA and pending Texas biometric statutes impose strict consent and retention protocols on identity verification deployments. Vendors must re-engineer data handling architectures or face statutory damages. Corporate campus operators in California are pre-emptively adopting deletion-schedule compliance ahead of anticipated state-level extensions.
Enterprise buyers are consolidating vendor relationships around integrated physical-cyber service bundles, displacing siloed guard-force and IT security contracts. This consolidation favors national operators with cross-functional certification portfolios. The U.S. federal sector shows the most visible concentration, with integrated platform mandates in new facility construction.
North America Security Services Market Segmentation
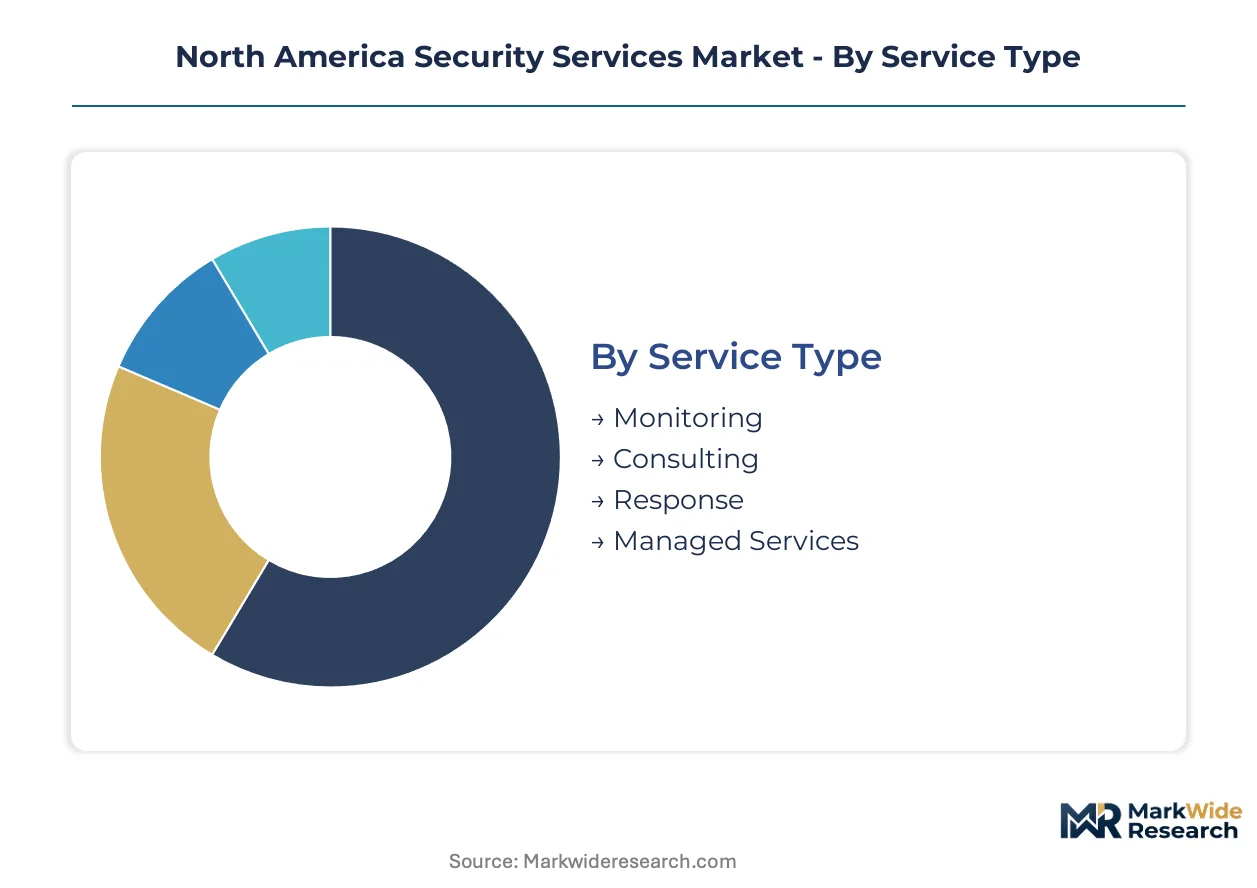
Security service procurement patterns diverge sharply across client sophistication levels and threat exposure profiles. Vendors must calibrate capability bundles to match divergent compliance burdens and operational tempo requirements.
Service Type:
Mature guard-force offerings coexist with emerging predictive analytics platforms, creating a bifurcated vendor landscape.
- Monitoring:Continuous oversight of sensor networks and alarm systems through centralized operations centers. U.S. federal facilities and critical infrastructure operators drive contract volume under DHS-mandated surveillance protocols.
- Managed Services:Subscription-based outsourcing of entire security functions including personnel, technology, and compliance management. Corporate campuses in California and Texas are consolidating fragmented vendor relationships into single-provider contracts to reduce liability exposure under biometric privacy statutes.
- Consulting:Risk assessment and security architecture design delivered on project basis.
- Response:Rapid deployment of armed or unarmed personnel following alarm triggers.
Monitoring handles the majority of throughput; Managed Services is expanding most quickly on share.
End User:
Cost tier stratification separates price-sensitive residential accounts from premium government mandates with certification requirements.
- Government:Federal, state, and municipal contracts requiring cleared personnel and audited compliance chains. The U.S. Department of Homeland Security and Transport Canada infrastructure programs concentrate procurement in integrated physical-digital platforms with mandatory personnel certification.
- Corporate:Commercial enterprises spanning financial services, technology, and manufacturing verticals. Northeast U.S. financial institutions and healthcare systems are replacing perimeter firewalls with cloud-native threat detection bundled into facility security contracts.
- Healthcare:Hospitals and medical systems facing joint HIPAA and physical access compliance.
- Residential:Homeowners and multi-tenant properties purchasing monitored alarm and video verification.
Government commands the premium pricing tier; Corporate is climbing the fastest on contract value.
Technology:
Volume deployment favors established surveillance hardware while margin capture shifts toward biometric and AI-enhanced systems.
- Video Surveillance:Camera networks with varying degrees of analytics integration deployed across corporate and government facilities. Enterprise buyers in the U.S. Northeast are accelerating replacement cycles to incorporate machine vision and edge computing for predictive threat detection.
- Biometrics:Fingerprint, facial recognition, and behavioral identity verification systems. Illinois BIPA and pending Texas statutes impose strict consent and data retention protocols, forcing vendors to re-engineer architectures or face statutory damages.
- Access Control:Card-based, mobile credential, and wireless entry management systems.
- Intrusion Detection:Perimeter sensors, motion detectors, and glass-break monitors.
Video Surveillance leads deployment volume; Biometrics is gaining share fastest on margin contribution.
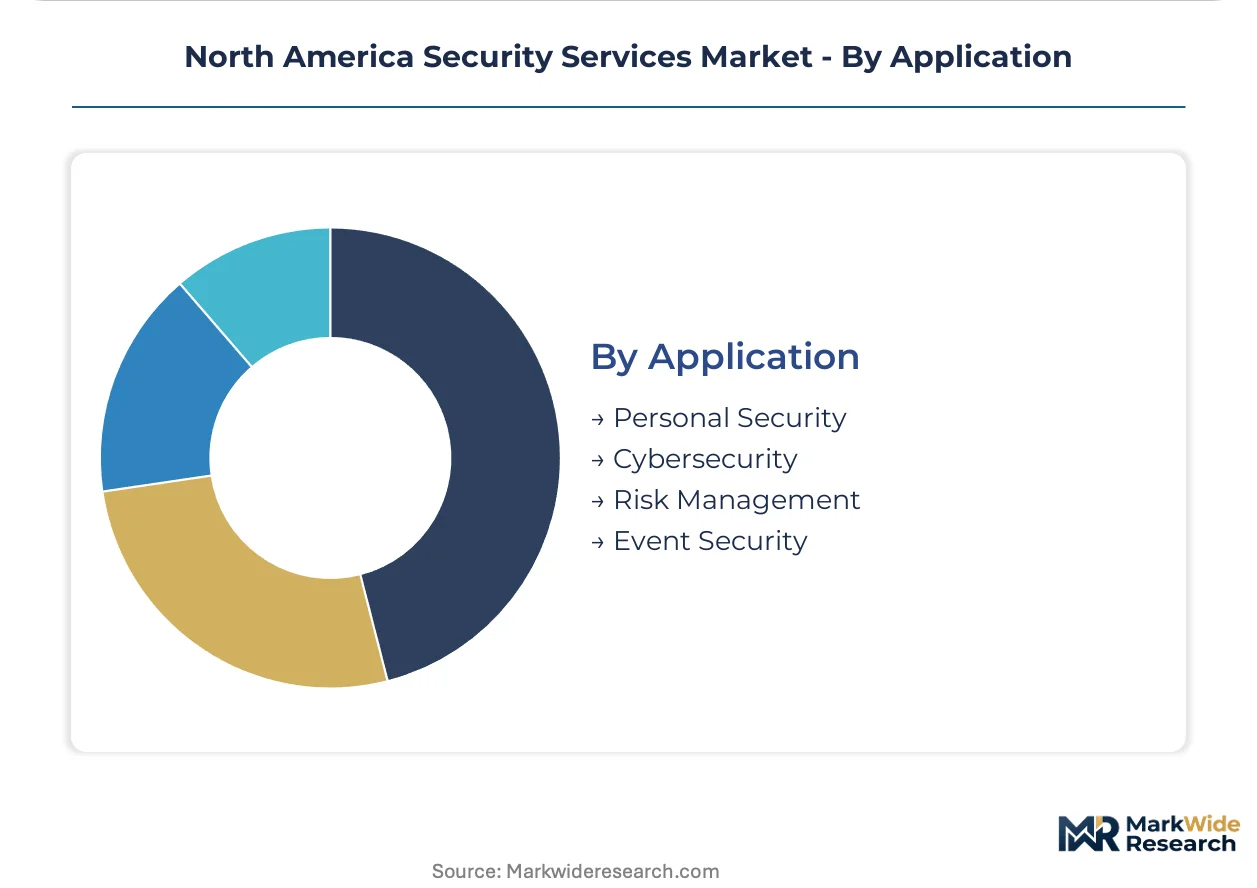
Application:
Customer type separates episodic event-based purchasing from continuous operational expenditure commitments.
- Cybersecurity:Network monitoring, endpoint protection, and cloud security delivered as managed service. Palo Alto Networks anchors enterprise demand through cloud-native platforms competing with traditional perimeter defenses in U.S. corporate accounts.
- Risk Management:Comprehensive threat assessment, business continuity planning, and insurance-adjacent consulting. Financial services and critical infrastructure operators in Canada and the U.S. are bundling these services into multi-year enterprise agreements.
- Personal Security:Executive protection and close-quarters guard services for high-net-worth individuals.
- Event Security:Temporary staffing and crowd management for sporting, entertainment, and political gatherings.
Cybersecurity captures the recurring revenue base; Risk Management is expanding most quickly on attach rates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States commands premium contract pricing for cleared personnel and integrated platforms, while Canadian federal certification scarcity creates vendor bottlenecks that inflate service rates in cross-border infrastructure corridors.
United States
Corporate campuses in California and Texas are consolidating fragmented vendor relationships into single-provider managed service contracts to reduce liability exposure under biometric privacy statutes. The Department of Homeland Security mandates updated personnel certification protocols for critical infrastructure operators. Northeast financial institutions in New York and Boston are accelerating replacement cycles for cloud-native threat detection bundled into facility security contracts.
Canada
Transport Canada infrastructure protection standards create certified vendor scarcity for operators seeking cross-border government contracts. The federal Privacy Act tightens compliance requirements for identity verification system deployments. Ontario and Quebec corporate accounts are pre-emptively adopting deletion-schedule compliance frameworks ahead of anticipated provincial biometric extensions.
Mexico
Manufacturing clusters along the northern border states drive demand for integrated physical-digital security platforms serving U.S.-linked supply chains. Federal energy infrastructure programs mandate international-standard personnel vetting for facility operators. Monterrey and Tijuana industrial zones concentrate contract volume for cross-border logistics security services.
North America Security Services Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying sensors, analytics engines, and credentialing hardware to bundled service providers. The vendor base separates into three functional tiers: national guard-force operators with cleared personnel rosters, cybersecurity-native firms anchoring cloud-native threat detection, and hardware-software bundlers bridging physical access with network monitoring. Consolidation pressure favors operators with cross-functional certification portfolios capable of bidding on integrated federal mandates. Dominant competitive moves include vertical capability stacking through strategic partnerships and geographic footprint expansion to capture municipal procurement clusters.
Among North American platform integrators, Allied Universal exemplifies the guard-force-to-technology bundling archetype, while Palo Alto Networks occupies the cybersecurity-native position competing with traditional perimeter defenses. GardaWorld represents the cross-border operator archetype navigating dual federal certification frameworks. These three anchors illustrate the strategic divergence between physical-dominant, cyber-dominant, and hybrid service models competing for consolidated enterprise contracts.
| Leading Market Players |
|---|
| Allied Universal |
| GardaWorld |
| ADT Security Services |
| Securitas Inc. |
| G4S Limited |
| Palo Alto Networks |
| Honeywell International, Inc. |
| Johnson Controls |
| Trustwave Holdings, Inc |
| Others |
Pricing and Supply Chain Analysis
Undercapacity in cleared security personnel pools across the U.S. Northeast and Canadian federal corridors is compressing operator margins while elevating pricing power for certified vendors bidding on integrated government contracts. This utilization squeeze forces mid-scale operators toward subscription-managed service models that reduce upfront capital burdens but lock in recurring revenue commitments.
Pricing Analysis
The customization-premium spread between standard guard-force contracts and configured-to-order integrated platforms spans three distinct tiers based on certification density and cyber-physical bundling. Subscription-based managed security services dominate enterprise procurement, with price differentiation driven by federal clearance levels and biometric compliance certification under Illinois BIPA and pending Texas statutes. Pricing pressure stems from licensed guard wage inflation in California and New York metropolitan corridors, where municipal fixed-price contracts squeeze operator margins. Government end-users show the lowest price sensitivity due to mandated compliance requirements, while residential monitoring segments face acute cost consciousness.
Supply Chain Analysis
Upstream feedstock dependencies for integrated security platforms center on semiconductor foundries in Taiwan, South Korea, and the United States producing biometric sensors and edge-computing processors. The hardware layer draws from concentrated chip fabrication, camera module assembly in China and Mexico, and cloud infrastructure provision by U.S.-based hyperscalers. Single-source vulnerability in advanced semiconductor nodes creates procurement risk for vendors building AI-enhanced video analytics. Distribution runs through direct enterprise sales teams for large government and corporate accounts, with regional system integrators serving mid-market buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market demands substitution defense as cloud-native cybersecurity platforms and AI-automated monitoring systems displace traditional guard-force intermediaries. Incumbents must navigate technology substitution threats while preserving human-in-the-loop certification advantages.
For Market Incumbents: Harden competitive moats by securing Transport Canada and U.S. federal security clearance frameworks ahead of cross-border infrastructure contract waves. Invest in backward integration into biometric sensor calibration and edge-computing hardware to reduce dependence on concentrated semiconductor suppliers. Prioritize API development that bridges legacy access control systems with cloud-native threat detection platforms, addressing the cyber-physical integration complexity that stalls competitor deployments. For New Entrants and Emerging Players: Pursue white-space opportunities in Canadian federal security clearance scarcity zones, where certified vendor bottlenecks inflate service rates for cross-border operators. Target mid-scale corporate campuses in Texas and California seeking consolidated managed service contracts to reduce biometric privacy liability exposure. Lead with remote monitoring dashboard subscriptions that bypass traditional guard-force intermediaries, opening direct enterprise relationships without heavy personnel infrastructure. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because federal integrated platform mandates favor national operators with cross-functional certification portfolios capable of bidding on restricted contracts. Acquisition targets should display cleared personnel rosters, existing API infrastructure for cyber-physical integration, and established relationships with U.S. Department of Homeland Security procurement channels. The signal to watch is Transport Canada certification queue lengths, which indicate scarcity premiums available to cross-border certified vendors.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Bundles manned guarding with cloud-native threat detection to meet zero-trust federal mandates. |
| Certification Investment | Secures Transport Canada and DHS personnel clearances that create bidding advantages in restricted contracts. |
| Backward Integration | Captures biometric sensor calibration and edge-computing hardware to reduce semiconductor foundry dependence. |
| Geographic Expansion | Establishes presence in Canadian federal corridors and Texas biometric compliance zones ahead of regulatory waves. |
| Strategic Partnership | Links legacy access control OEMs with API bridges to cloud-native cybersecurity platforms. |
Research Methodology
A standing panel of security operations directors, federal procurement officers, biometric system engineers, and managed service contract managers provided ongoing calibration across the research cycle. Primary fieldwork combined structured interviews with these practitioners alongside secondary validation through U.S. Department of Homeland Security procurement databases, Transport Canada infrastructure protection standards filings, state-level biometric privacy statute tracking, and SEC disclosures from publicly traded security service operators. Bottom-up contract volume analysis triangulated against top-down market sizing derived from federal budget appropriations and corporate security expenditure surveys.
Scenario-bracketing anchored the analytical framework, with projections tested across conservative, baseline, and expansion cases over the projection horizon. Segmentation dimensions modeled include service type, end-user vertical, technology deployment, and application area, with additional granularity around certification tier and cyber-physical integration maturity. CAGRs were derived from fitted growth curves applied to contract value data, incorporating inputs from personnel cost inflation indices and regulatory compliance burden assessments.
Sensitivities concentrate around federal background check backlog resolution timelines, state-level biometric statute adoption schedules, and semiconductor supply availability for edge-computing components. Forecasts reflect documented assumptions regarding procurement consolidation rates and substitution thresholds between human-guard and AI-automated monitoring systems. Cross-checking against U.S. General Services Administration contract award databases and Canadian federal procurement disclosure records is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Security and Surveillance
Resale Authentication Services Market
Security and Surveillance
Europe People Screening Market
Security and Surveillance
Perimeter Security Market
Security and Surveillance
North America Security Screening Market
Security and Surveillance
Full Body Scanner Market
Security and Surveillance
India Electronic Security Market
Security and Surveillance
Global Security Orchestration Market
Security and Surveillance
Security Analytics Market
Security and Surveillance
Signal Jamming Systems Market
Security and Surveillance
Door and Window Alarm Market
Security and Surveillance
Security Product Integration Services Market
Security and Surveillance
Middle East Manned Security Services Market
Security and Surveillance
Anti-Piracy Protection Market
Security and Surveillance
Face Smart Lockers Market
Security and Surveillance
Proactive Security Market
Security and Surveillance
Global Threat Intelligence Management Market