
 Situational Awareness System Market | 2026-2036
Situational Awareness System Market Size, Share, and Industry Trends Forecast 2026-2036
Situational Awareness System Market Analytics
Platform licensing revenue is tilting toward predictive analytics modules as defense operators prioritize subscription-based threat intelligence over perpetual hardware sales. BAE Systems plc leverages its sovereign UK manufacturing base to sustain classified program access across British and Australian naval contracts. Lockheed Martin Corporation anchors the high-altitude ISR segment through persistent investment in multi-domain command architectures. Microsoft Corporation competes in the software layer by extending Azure Government cloud instances to classified situational awareness workloads.
A situational awareness system integrates heterogeneous sensor inputs—radar returns, electro-optical feeds, AIS transponder data, and GPS telemetry—into a unified operational picture through real-time data fusion algorithms and geospatial rendering engines. Its primary purpose is to compress decision cycles for operators monitoring complex, dynamic environments where threat discrimination and response coordination carry mission-critical stakes. Command & Control Systems occupy the largest value pool given their position as the integration hub requiring bespoke military certification, while Data Fusion Systems represent the fastest-expanding segment as AI-driven correlation engines displace manual sensor triage. Threat Assessment Tools remain a concentrated margin pocket where specialized algorithm vendors differentiate through proprietary pattern-recognition libraries.
The US Department of Defense mandates FIPS 140-2 cryptographic validation and DoD 8570 cybersecurity workforce standards for all deployed situational awareness platforms, creating compliance barriers that favor incumbent suppliers with sustained certification investment. NATO STANAG interoperability protocols and the EU AI Act's risk-classification framework for autonomous decision-support systems are simultaneously shaping procurement specifications across allied defense markets. Stakeholders must monitor whether emerging export control regimes on AI-enabled sensor processing will fragment supplier access across transatlantic and Indo-Pacific defense procurement channels.
Market Dynamics
Defense procurement officers are consolidating vendor relationships around integrated platform providers capable of delivering end-to-end sensor fusion, compressing the addressable market for standalone subsystem suppliers and elevating certification-heavy incumbents.
Growth Catalysts
- NATO STANAG Interoperability Mandates:Allied defense ministries are synchronizing procurement specifications around common data exchange protocols, forcing platform upgrades across member fleets and creating replacement cycles for legacy command systems.
- AI-Driven Sensor Correlation:Machine learning architectures are automating threat discrimination from multi-source intelligence feeds, reducing operator cognitive load and compressing engagement timelines for naval and aerial surveillance missions.
- Homeland Security Infrastructure Modernization:Border monitoring agencies in the United States are deploying networked coastal radar and electro-optical suites, sustaining demand for fused maritime domain awareness platforms.
Market Restraints
- Semiconductor Supply Concentration:Advanced FPGA and GPU processors for real-time data fusion concentrate fabrication in East Asian foundries, exposing defense primes to export control disruptions and foundry allocation constraints.
- Protracted Military Certification Cycles:Platform validation against FIPS 140-2 and DoD 8570 standards consumes 18-36 months, freezing vendor cash flow and deterring venture-backed entrants from classified program participation.
- Skilled Cybersecurity Workforce Scarcity:Cleared personnel holding DoD 8570 certifications remain concentrated among incumbent contractors, inflating labor costs and constraining platform deployment velocity.
Strategic Opportunities
- Space-Based Sensing Integration:Low-earth orbit constellations delivering persistent synthetic aperture radar coverage are converging with terrestrial fusion architectures, enabling real-time target tracking previously requiring high-altitude ISR aircraft.
- EU AI Act Risk Classification Framework:The European Union's tiered compliance regime for autonomous decision-support systems is creating premium market segments for vendors with pre-certified algorithm libraries and audit-ready model documentation.
- Urban Air Mobility Surveillance:Metropolitan police and emergency response agencies are piloting integrated drone detection and counter-UAS coordination platforms, opening civilian adjacent demand for military-heritage sensor fusion technology.
Industry Challenges
- Cross-Domain Data Standardization:Harmonizing sensor ontologies across air, maritime, ground, and space domains requires reconciling incompatible legacy message formats, delaying joint all-domain command implementations.
- Model Explainability Requirements:Operator trust in AI-generated threat assessments demands interpretable decision pathways, forcing algorithm developers to sacrifice predictive accuracy for auditability in safety-critical engagements.
- Legacy System Integration Friction:Fielded command platforms running 1990s-era software architectures resist API-based connectivity, necessitating costly middleware development for fleet-wide data fusion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Situational Awareness System Market |
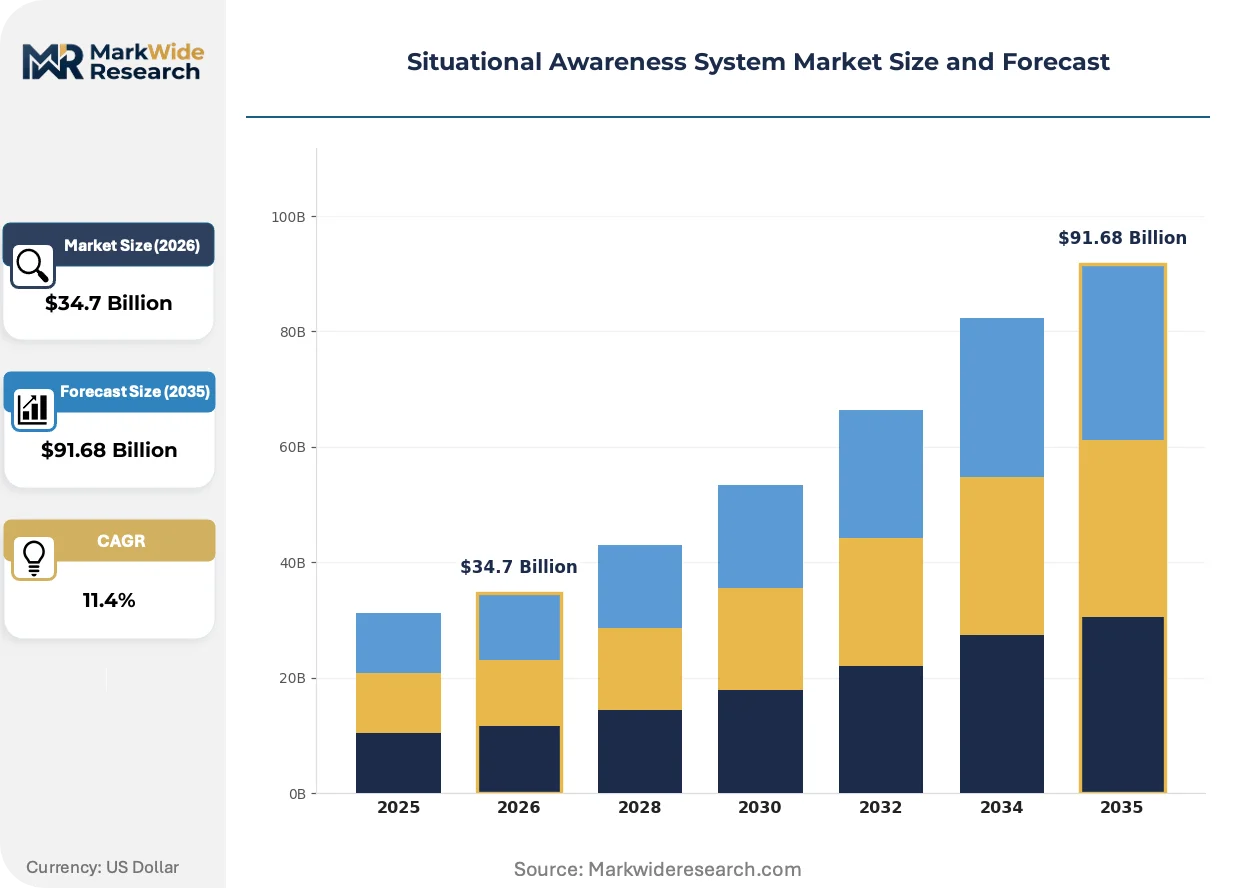
| Market Size in 2026 | $34.7 Billion |
| Market Size in 2035 | $91.68 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Command & Control Systems, Data Fusion Systems, Threat Assessment Tools, Visual Display Systems End User: Military, Emergency Responders, Aviation, Maritime Technology: Radar Systems, LiDAR, AIS, GPS Application: Border Security, Smart Cities, Disaster Management, Maritime Surveillance |
| Companies Covered | BAE Systems plc, Northrop Grumman Corporation, Lockheed Martin Corporation, L3Harris Technologies Inc., Boeing Company, RTX Corporation, General Electric, Microsoft Corporation, Honeywell International Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Situational Awareness System Market Evolving Landscape
Computational architectures are migrating from hardware-dependent processing stacks toward software-defined environments, decoupling sensor acquisition from analytical capability and enabling rapid algorithm deployment without platform recertification.
Edge computing nodes embedded within sensor platforms are virtualizing traditional centralized processing functions, enabling real-time correlation at the collection point. Naval surface combatants and unmanned aerial systems are adopting these distributed architectures to reduce bandwidth dependence and survive contested communications environments. This virtualization is compressing the hardware refresh cycle, allowing capability upgrades through over-the-air software deployment rather than physical subsystem replacement.
The EU AI Act's risk-based classification framework is mandating conformity assessments for autonomous threat evaluation modules, compelling vendors to document training data provenance and model validation protocols. Defense procurement offices in France, Germany, and Italy are embedding these requirements into tender specifications, favoring suppliers with established algorithm governance infrastructure. High-stakes segments including autonomous engagement authorization are experiencing extended qualification timelines as national regulators interpret prohibited AI practices.
Subscription-based threat intelligence delivery is displacing perpetual license sales for predictive analytics modules, unbundling software capability from platform hardware. Defense operators in the United States and United Kingdom are piloting consumption-priced models for cyber threat feeds and pattern-recognition algorithm updates, transferring technology refresh risk to vendors. This transition is most visible in naval fleet modernization programs, where platform primes are retaining algorithm ownership and delivering capability as a service across 10-year operational support contracts.
Situational Awareness System Market Segmentation
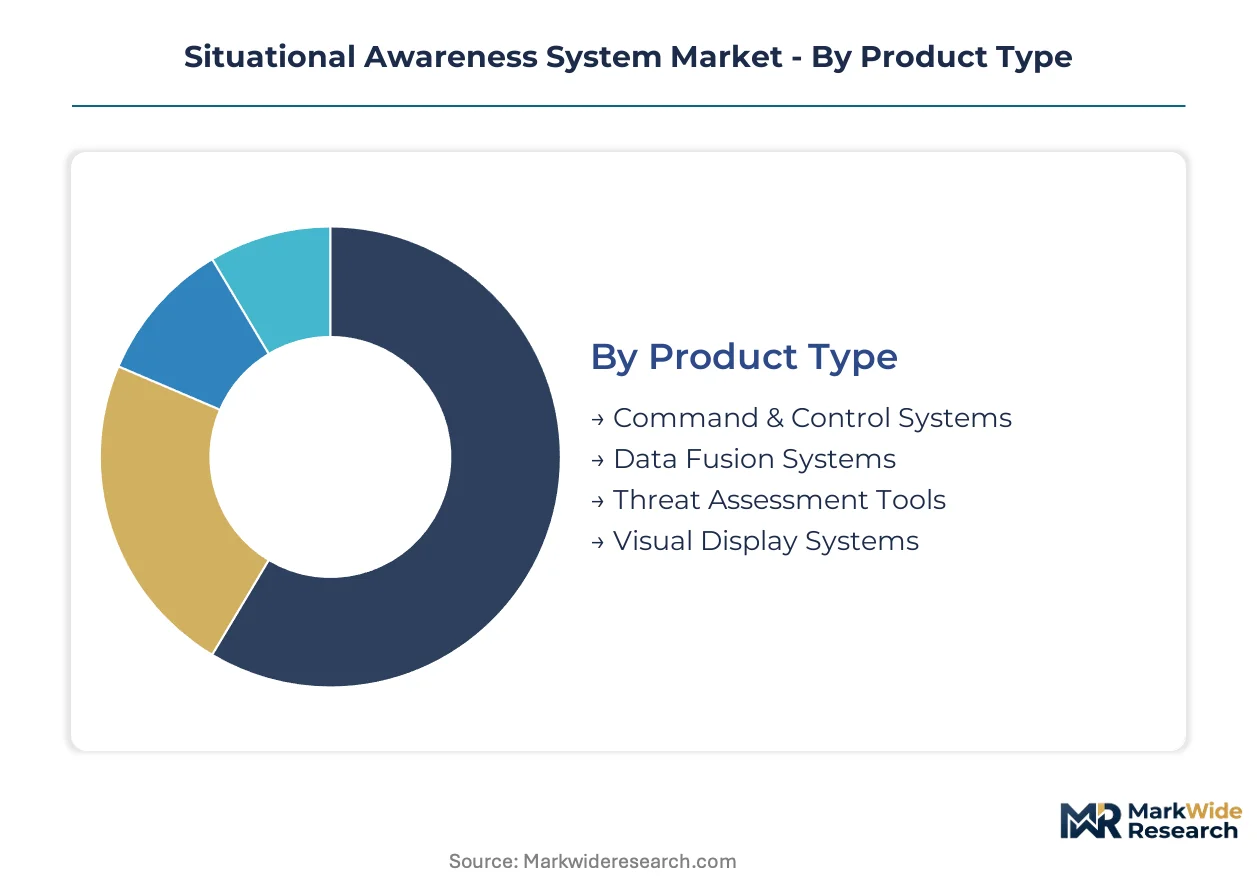
Segmentation in the situational awareness system market reveals how procurement priorities diverge across mission profiles and operational environments. Technical specifications, certification requirements, and integration complexity vary substantially by product architecture and end-use domain, creating distinct competitive arenas with differentiated margin structures.
Product Type:
After-sales service intensity varies dramatically across product categories, with software-intensive segments demanding continuous algorithm updates and threat library refreshes while hardware-centric platforms rely on periodic depot maintenance cycles.
- Command & Control Systems:These platforms integrate multi-source sensor feeds into unified operational displays through hardened military-grade computing architectures. Military procurement offices in the United States and United Kingdom prioritize these systems for fleet-wide modernization, driven by NATO STANAG interoperability mandates that force replacement of legacy message-handling infrastructure.
- Data Fusion Systems:Machine learning correlation engines automate threat discrimination from heterogeneous intelligence streams, reducing operator cognitive load during high-tempo engagements. Maritime surveillance programs across allied navies are accelerating adoption as distributed sensor networks proliferate and manual triage becomes operationally untenable.
- Threat Assessment Tools:Specialized algorithm libraries deliver pattern recognition for specific threat categories.
- Visual Display Systems:Geospatial rendering engines present fused data through intuitive operator interfaces.
By volume, Command & Control Systems leads. By growth pace, Data Fusion Systems is climbing the fastest.
End User:
Cost tier differentiation separates mission-critical military deployments from civilian-adjacent applications, with defense programs absorbing premium pricing for hardened platforms while emergency response agencies optimize for interoperability with existing municipal infrastructure.
- Military:Integrated command platforms serving joint all-domain operations require FIPS 140-2 cryptographic validation and sustained cybersecurity certification investment. The US Department of Defense anchors demand through naval fleet upgrades and homeland security infrastructure directives that mandate networked coastal surveillance.
- Maritime:Port authorities and coastal defense agencies deploy fused radar and electro-optical suites for vessel traffic management and anomaly detection. European procurement offices are embedding EU AI Act conformity assessments into tender specifications, extending qualification timelines for autonomous threat evaluation modules.
- Aviation:Airport operators and air navigation service providers integrate multi-sensor surveillance for drone detection and runway incursion prevention.
- Emergency Responders:Metropolitan police and fire departments pilot integrated coordination platforms for urban air mobility monitoring and disaster response.
Military commands the largest revenue pool. Maritime applications are gaining share fastest as port security budgets expand.
Technology:
Supply concentration shapes competitive dynamics, with advanced processing components concentrating fabrication in East Asian foundries and exposing defense primes to export control disruptions.
- Radar Systems:Active electronically scanned arrays and synthetic aperture processing deliver all-weather detection and tracking capabilities. Naval surface combatants across NATO member fleets are upgrading to software-defined radar architectures that enable capability refresh through firmware deployment.
- GPS:Positioning, navigation, and timing services underpin geospatial correlation across all fusion architectures. Military operators are diversifying signal sources as jamming threats proliferate in contested electromagnetic environments.
- LiDAR:Laser ranging systems provide high-resolution three-dimensional mapping for close-range precision applications.
- AIS:Automatic Identification System transponder monitoring enables cooperative vessel tracking and anomaly detection in maritime domain awareness.
Radar Systems dominates installed base. GPS integration is expanding most quickly as resilient positioning becomes mission-critical.
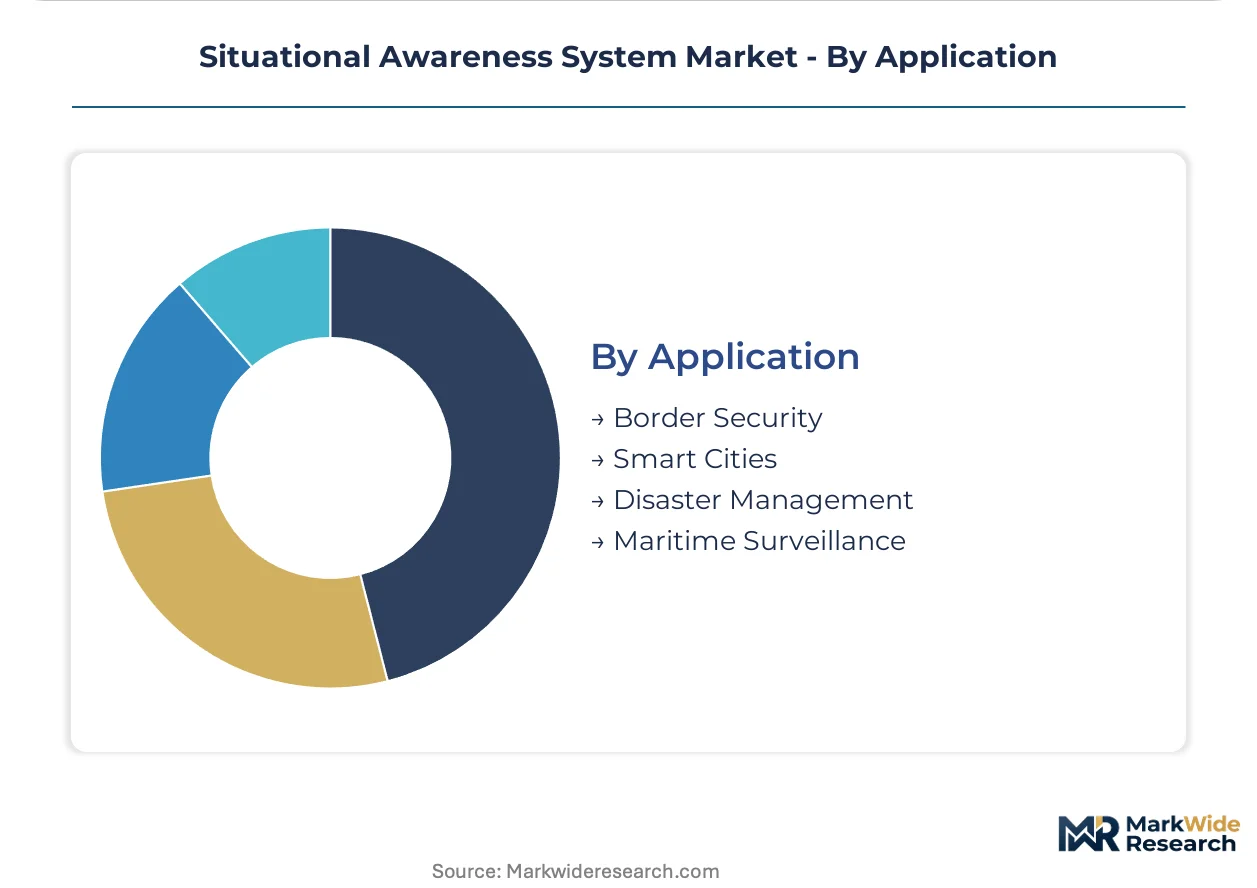
Application:
Maturity gradients separate established defense applications from emerging civilian markets, with border security and maritime surveillance benefiting from decades of operational refinement while smart city deployments navigate fragmented procurement authority.
- Border Security:Integrated coastal and land frontier surveillance networks combine radar, electro-optical, and unattended ground sensor feeds into unified operational pictures. US Customs and Border Protection sustains demand through continuous infrastructure modernization programs spanning southern and northern frontiers.
- Maritime Surveillance:Exclusive economic zone monitoring and port security operations fuse satellite AIS, coastal radar, and patrol aircraft feeds. Indo-Pacific navies are prioritizing these capabilities as contested waterways drive requirements for persistent domain awareness.
- Disaster Management:Emergency operations centers coordinate multi-agency response through common operating platforms during natural catastrophes.
- Smart Cities:Metropolitan agencies pilot integrated sensor networks for traffic management, public safety, and environmental monitoring.
Border Security generates the largest contract value. Smart Cities represents the steepest expansion trajectory as municipal digitization accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Defense procurement elasticity varies sharply by geography. United States buyers absorb premium pricing for FIPS 140-2 certified platforms, while European ministries negotiate harder on unit costs under collective NATO frameworks. Emerging maritime surveillance programs in the Indo-Pacific show intermediate price sensitivity.
United States
Homeland Security infrastructure directives and naval fleet modernization sustain demand for integrated command platforms. The Department of Defense mandates FIPS 140-2 cryptographic validation and DoD 8570 cybersecurity workforce standards for all deployed systems. San Diego and Norfolk anchor coastal radar network expansion, with Pacific Northwest facilities supporting space-based sensing integration programs.
United Kingdom
British naval contracts and Australian allied programs drive procurement of sovereign-manufactured command systems. The UK Ministry of Defence embeds NATO STANAG interoperability protocols into tender specifications for fleet-wide upgrades. BAE Systems plc maintains classified program access from its UK manufacturing base, with Glasgow and Portsmouth facilities handling integrated platform delivery.
Germany
Bundeswehr modernization and Franco-German defense cooperation accelerate replacement of legacy message-handling infrastructure. The EU AI Act's risk-classification framework shapes procurement specifications for autonomous decision-support modules. Munich and Hamburg industrial clusters concentrate algorithm development for pattern-recognition libraries serving threat assessment applications.
France
Naval Group-led surface combatant programs and exclusive economic zone monitoring requirements expand maritime domain awareness procurement. ANSM and national regulators interpret prohibited AI practices under the EU AI Act, extending qualification timelines for autonomous engagement authorization. Toulon and Brest harbor facilities drive coastal surveillance network integration with satellite AIS feeds.
Japan
Maritime Self-Defense Force distributed fleet architectures and contested waterway surveillance priorities elevate demand for resilient positioning and multi-sensor fusion. METI coordinates domestic semiconductor supply security for advanced FPGA and GPU processors. Yokosuka and Sasebo anchor Indo-Pacific naval modernization, with Tokyo Bay facilities supporting software-defined radar architecture deployment.
Situational Awareness System Market Competitive Landscape
Systems integrators and algorithm specialists split the market between platform-heavy and software-centric value capture. Defense procurement consolidation around end-to-end sensor fusion capability compresses the addressable market for standalone subsystem suppliers. Three archetypes dominate: sovereign manufacturing champions with classified program access, multi-domain command architects with persistent ISR investment, and cloud-native software layers extending government cloud instances. Competitive positioning hardens through sustained certification investment and strategic partnerships for space-based sensing integration.
Within the sovereign manufacturing tier, BAE Systems plc represents UK-based classified program access across naval contracts. Lockheed Martin Corporation anchors multi-domain command architecture development for high-altitude ISR segments. Microsoft Corporation exemplifies cloud-native software layer competition through Azure Government extensions to classified workloads. These three occupy positions spanning hardware platform delivery, integrated system architecture, and software-defined capability deployment.
| Leading Market Players |
|---|
| BAE Systems plc |
| Northrop Grumman Corporation |
| Lockheed Martin Corporation |
| L3Harris Technologies Inc. |
| Boeing Company |
| RTX Corporation |
| General Electric |
| Microsoft Corporation |
| Honeywell International Inc. |
| Others |
Value Network & Pricing Analysis
Trans-Pacific shipping lanes connecting East Asian semiconductor foundries to NATO defense primes carry freight cost volatility that amplifies pricing power for FIPS 140-2 certified platform integrators while compressing margins for subsystem vendors lacking after-sales service depth.
Pricing Analysis
Subscription-based algorithm update contracts now generate the majority of lifetime value for Data Fusion Systems vendors, displacing perpetual hardware sales. Three-tier pricing structure across premium, standard, and economy levels separates FIPS 140-2 certified command platforms from commercial-grade alternatives and uncertified subsystems. Pricing pressure stems from defense procurement consolidation around end-to-end sensor fusion providers. Emergency response agencies show highest price sensitivity, absorbing only commercial-grade platforms without military certification investment.
Supply Chain Analysis
TSMC, Samsung Foundry, and Intel Foundry Services concentrate advanced FPGA and GPU fabrication for real-time data fusion processors. Defense primes draw from Taiwanese, South Korean, and domestic US wafer capacity while sourcing radar components and electro-optical sensors from specialized German and Japanese suppliers. Single-source vulnerability in East Asian foundry allocation exposes platform delivery timelines to export control disruptions. Distribution runs through prime contractor integration facilities rather than open component markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Algorithm-as-a-service revenue layers for predictive threat analytics are expanding faster than hardware platform sales, transforming procurement economics toward recurring consumption models.
For Market Incumbents: Insulate classified program access through sustained FIPS 140-2 and DoD 8570 certification investment, creating compliance moats against venture-backed entrants. Deepen backward integration into software-defined radar architectures to capture firmware deployment value. Vertical integration threat from cloud-native software layers demands accelerated algorithm governance infrastructure development.
For New Entrants and Emerging Players: Urban air mobility surveillance markets in metropolitan police departments offer lowest certification barriers for military-heritage technology adaptation. Target drone detection and counter-UAS coordination platforms as the most penetrable civilian-adjacent segment. Go-to-market leverage rests on consumption-priced threat intelligence pilots rather than capital-intensive platform sales.
For Investors and Strategic Acquirers: Carve-out targets emerge from defense primes divesting non-core sensor subsystem divisions under procurement consolidation pressure. Long-term viability favors algorithm specialists with pre-certified pattern-recognition libraries and audit-ready model documentation under EU AI Act frameworks. Watch NATO STANAG mandate acceleration as inflection signal for replacement cycle timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Algorithm Governance Infrastructure Investment | EU AI Act conformity assessments favor vendors with documented training data provenance and model validation protocols. |
| Space-Based Sensing Integration Partnership | Low-earth orbit synthetic aperture radar constellations enable real-time target tracking without high-altitude ISR aircraft dependency. |
| Software-Defined Radar Architecture Deployment | Firmware-based capability refresh compresses hardware refresh cycles for NATO naval fleet modernization programs. |
| Consumption-Priced Threat Intelligence Pilot | Subscription models transfer technology refresh risk to vendors across 10-year operational support contracts. |
| Edge Computing Node Virtualization | Distributed processing architectures reduce bandwidth dependence for unmanned aerial systems in contested communications environments. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of defense procurement databases, NATO STANAG protocol documentation, and EU AI Act regulatory filings. Primary interviews engaged platform engineering directors at systems integrators, cybersecurity certification officers at prime contractors, and procurement leads at allied defense ministries. Secondary validation drew from DoD budget justification materials, SEC 10-K disclosures by listed defense primes, and customs records for FPGA and GPU import flows. Bottom-up segment sizing triangulated against top-down defense expenditure allocation models.
Forecast inputs incorporate platform deployment timelines, certification cycle durations, and algorithm subscription attach rates across the projection horizon. Segmentation modeling spans product architecture, end-use domain, technology type, and application maturity. CAGRs derive from deployment velocity assumptions calibrated to observed NATO modernization program pacing and homeland security infrastructure directive implementation. Industry-specific inputs include FIPS 140-2 validation queue lengths and EU AI Act conformity assessment throughput.
The forecast holds incumbent behavior within observed patterns; aggressive moves by cloud-native software entrants or sovereign manufacturing champions would shift outcomes. Semiconductor export control tightening, accelerated NATO STANAG mandate adoption, or EU AI Act prohibited AI practice reinterpretation could revise trajectory. Quarterly review of defense procurement tender issuance volumes and foundry allocation announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Security and Surveillance
Global Firearm Sight Market
Security and Surveillance
Global Wireless Monitoring and Surveillance Market
Security and Surveillance
X-Ray Security Screening System Market
Security and Surveillance
North America Wireless Monitoring and Surveillance Market
Security and Surveillance
Global Manned Security Service Market
Security and Surveillance
Explosive Trace Detection Market
Security and Surveillance
Surveillance Radars Market
Security and Surveillance
Global Security Assurance Market
Security and Surveillance
Global Corporate Travel Security Market
Security and Surveillance
Perimeter Security Market
Security and Surveillance
Global Contraband Detector Market
Security and Surveillance
Maritime Security Market
Security and Surveillance
Middle East and Africa Cargo and Vehicle Screening Market
Security and Surveillance
Asia-Pacific Urban Security Screening Market
Security and Surveillance
Global Police and Law Enforcement Equipment Market
Security and Surveillance
North America Security Testing Market