
 Middle East and Africa Surveillance IP Cameras Market | 2026-2036
Middle East and Africa Surveillance IP Cameras Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Surveillance IP Cameras Market Insights
GB/T 28181 and ONVIF Profile S certification cycles are unwinding vendor eligibility across Middle East and Africa public tenders, forcing non-compliant suppliers out of government procurement pipelines. Hangzhou Hikvision Digital Technology Co., Ltd. leverages its vertically integrated sensor fabrication to dominate price-sensitive municipal contracts in Egypt and Nigeria. Hanwha Vision anchors its position through AI-analytics-integrated PTZ lines that sustain premium positioning in UAE commercial developments. Axis Communications AB differentiates via cybersecurity-hardened firmware that meets Saudi NCA and UAE NESA compliance mandates.
Surveillance IP cameras are network-connected digital imaging devices capturing video streams at resolutions from 2MP to 8MP+, compressing data through H.265 or H.266 codecs for bandwidth-efficient transmission over Ethernet or wireless infrastructure, primarily deployed for real-time security monitoring and forensic evidence collection. Dome cameras lead commercial indoor installations across Gulf retail and healthcare facilities due to vandal-resistant housings and discreet positioning. IP-based technology segments are displacing legacy analog infrastructure fastest in South African banking and transportation verticals where PoE switching reduces cabling costs. Cloud-based architectures are concentrating margin pools in recurring software subscriptions rather than one-time hardware sales.
The UAE's National Electronic Security Authority and Saudi Arabia's National Cybersecurity Authority enforce encryption standards for video transmission, while South Africa's Protection of Personal Information Act governs biometric data capture from analytics-enabled cameras. These frameworks are reshaping R&D priorities toward edge-computing architectures that process sensitive data locally rather than transmitting raw feeds to centralized servers. Stakeholders must monitor evolving data-localization mandates and certification reciprocity agreements between Gulf regulators and European standards bodies to anticipate compliance cost trajectories.
Market Dynamics
GB/T 28181 and ONVIF Profile S certification cycles are forcing rapid vendor consolidation across Middle East and Africa public tenders, eliminating non-compliant suppliers from government procurement pipelines and redistributing contract flows toward certified manufacturers.
Growth Catalysts
- NEOM megaproject procurement:Saudi Arabia's gigaproject zones are mandating AI-integrated surveillance infrastructure for smart city corridors, creating concentrated demand for edge-computing camera networks.
- UAE NESA encryption mandates:The National Electronic Security Authority's transmission standards are accelerating replacement cycles for legacy analog systems in Dubai commercial developments.
- South African banking vertical:Financial institutions are deploying PoE-switched IP architectures to reduce cabling costs while meeting POPIA biometric data governance requirements.
Market Restraints
- Sensor supply concentration:CMOS image sensor fabrication concentrates in East Asian foundries, exposing MEA integrators to shipping delays and currency volatility.
- Data localization costs:Saudi NCA and UAE PDPL requirements for domestic video storage are forcing costly edge server deployments that inflate total cost of ownership.
- Power infrastructure gaps:Unreliable grid supply in Nigerian and Egyptian municipal deployments necessitates expensive UPS backup systems for continuous recording.
Strategic Opportunities
- Kenya smart city expansion:Nairobi's Konza Technopolis and Mombasa port modernization are opening procurement channels for traffic-management camera networks with local assembly requirements.
- Healthcare surveillance integration:UAE and Saudi hospital operators are converging patient monitoring with security infrastructure, creating demand for dual-purpose video analytics.
- Cloud-VMS subscription models:South African SMB segments are adopting software-as-a-service video management, shifting margin pools from hardware sales toward recurring revenue streams.
Industry Challenges
- Certification timeline compression:GB/T 28181 and ONVIF Profile T testing cycles now exceed 14 months, delaying product launches and freezing R&D roadmaps.
- Cybersecurity skill scarcity:Gulf system integrators face acute shortages of firmware-hardening specialists capable of meeting NCA and NESA penetration-testing standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Surveillance IP Cameras Market |
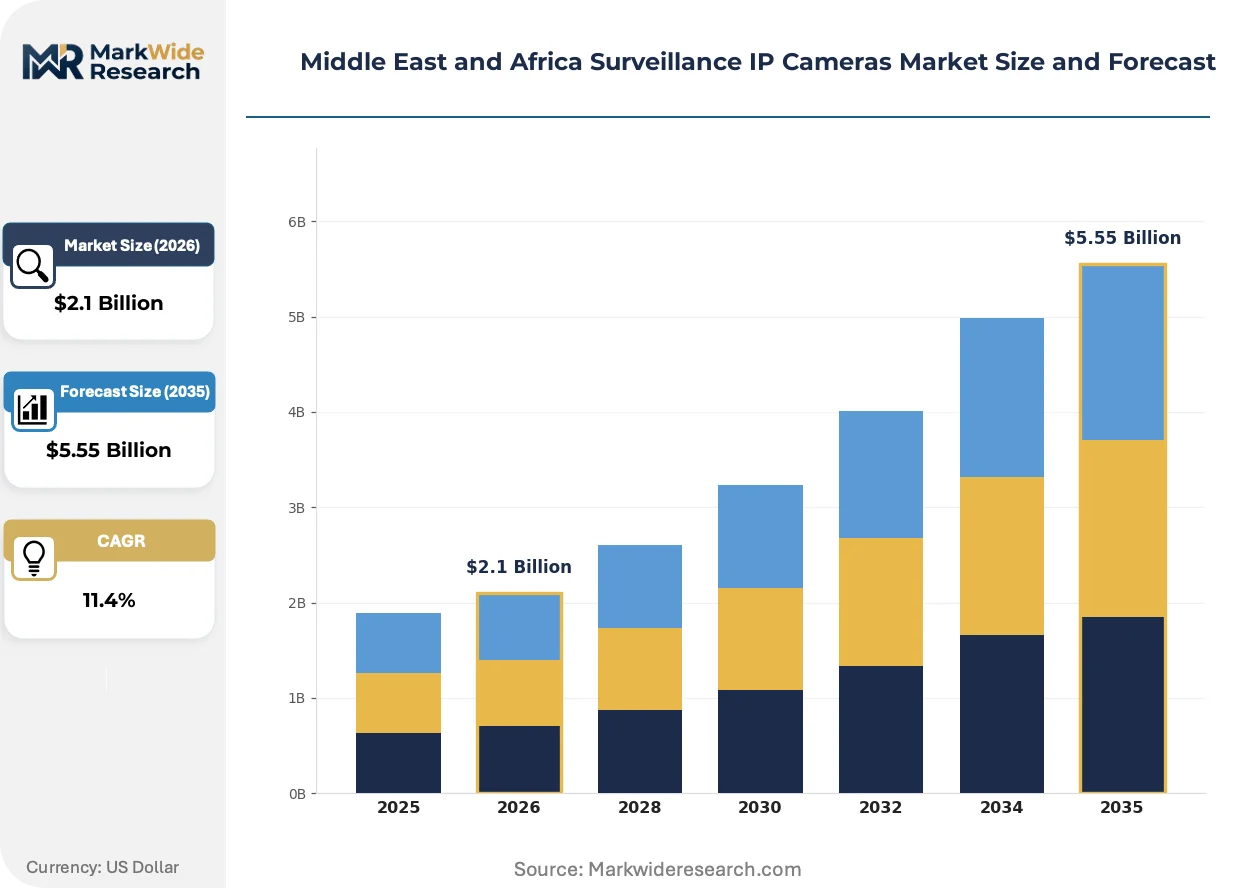
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $5.55 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bullet Cameras, Dome Cameras, PTZ Cameras, C-Mount Cameras Use Case: Retail Security, Industrial Monitoring, Home Surveillance, Traffic Management Technology: Analog, IP-Based, Wireless, Cloud-Based End User: Government, Healthcare Facilities, Transportation, Educational Institutions |
| Companies Covered | Hangzhou Hikvision Digital Technology Co., Ltd., Honeywell International Inc., Hanwha Vision, Bosch Sicherheitssysteme GmbH, Teledyne FLIR LLC, Zhejiang Uniview Technologies Co., Ltd., Axis Communications AB, Panasonic Corporation, Sony Corporation, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Surveillance IP Cameras Market Trends and Innovations
Edge-computing architectures are displacing centralized server processing across Middle East and Africa deployments, driven by data localization mandates and bandwidth constraints in secondary cities.
H.266/VVC codec adoption is displacing H.265 compression in bandwidth-constrained MEA municipal networks. Dubai Roads and Transport Authority and Riyadh Municipality are mandating the newer standard for 4K traffic monitoring feeds. The codec transition is compressing storage infrastructure requirements by half while extending retention periods for forensic evidence.
UAE PDPL and Saudi PDPL are imposing explicit consent mechanisms for biometric capture from analytics-enabled cameras. Retail and hospitality operators must now deploy localized processing to strip identifying markers before cloud transmission. Commercial developments in Abu Dhabi and Jeddah are responding by specifying on-camera AI chips that process facial data at the edge.
Outcome-based service contracts are replacing capital expenditure procurement in South African banking and logistics verticals. Standard Bank and Transnet are contracting for guaranteed uptime and incident-response SLAs rather than purchasing hardware outright. This shift concentrates vendor selection on remote diagnostic capabilities and spare-parts logistics rather than upfront equipment pricing.
Middle East and Africa Surveillance IP Cameras Market Segmentation
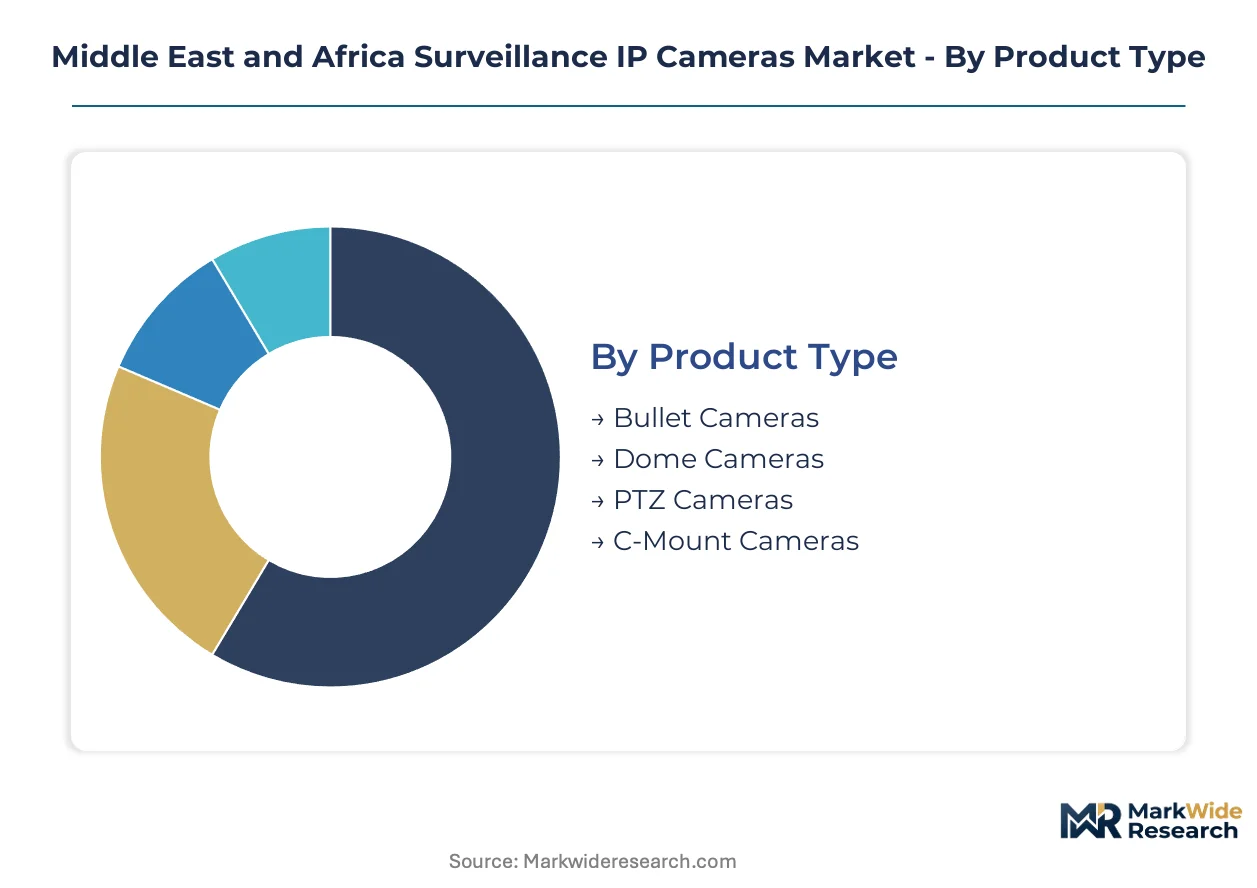
Regulatory fragmentation across Gulf Cooperation Council states and African Union members creates divergent procurement specifications that reshape segment prioritization. Certification mandates for encryption, data localization, and ONVIF compliance force integrators to align product portfolios with jurisdiction-specific technical standards rather than deploying uniform regional SKUs.
Product Type:
UAE NESA and Saudi NCA encryption standards differentiate dome and bullet camera eligibility for government tenders based on vandal-resistance ratings and tamper-detection firmware.
- Dome Cameras:Vandal-resistant housings with discreet positioning dominate Gulf retail and healthcare indoor installations. Dubai Mall operators and Saudi hospital chains specify IP66-rated domes with edge-computing chipsets to satisfy PDPL biometric processing requirements without cloud transmission.
- PTZ Cameras:Motorized pan-tilt-zoom mechanisms with optical zoom ranges reaching 30x sustain premium positioning in UAE commercial developments. Abu Dhabi airport expansions and Riyadh financial district towers demand AI-analytics-integrated PTZ lines for automated perimeter tracking.
- Bullet Cameras:Weather-sealed cylindrical housings with IR illumination penetrate price-sensitive Egyptian and Nigerian municipal contracts where long-range perimeter coverage outweighs aesthetic constraints.
- C-Mount Cameras:Interchangeable lens systems with CS-mount compatibility serve specialized industrial inspection applications in South African mining and petrochemical facilities requiring macro or telephoto optics.
Established volume favors dome cameras; emerging adoption favors PTZ cameras.
Use Case:
Cost tier stratification separates high-compliance government corridors from margin-constrained consumer deployments.
- Traffic Management:License plate recognition and vehicle-classification algorithms process 4K feeds at roadside edge servers. Dubai Roads and Transport Authority mandates H.266/VVC compression for arterial monitoring networks, compressing storage infrastructure while extending forensic retention.
- Retail Security:Shelf-edge cameras with heat-mapping analytics track customer flow patterns in UAE hypermarkets. POPIA compliance in South African mall deployments requires on-camera processing to strip identifying markers before cloud transmission.
- Industrial Monitoring:Explosion-proof housings with thermal imaging protect Saudi Aramco facilities and Nigerian LNG terminals where hazardous area classification dictates ATEX-certified sensor modules.
- Home Surveillance:Battery-powered wireless units with solar panel compatibility address power infrastructure gaps in Kenyan and Ghanaian residential estates where grid reliability falls below continuous recording thresholds.
Traffic management commands the steepest expansion trajectory; home surveillance faces margin compression from unlicensed import channels.
Technology:
Customer type separates legacy analog replacement cycles from greenfield cloud-native architectures.
- IP-Based:Power-over-Ethernet switching reduces cabling costs in South African banking verticals where Standard Bank and FirstRand are displacing coaxial infrastructure. PoE++ standards support heater-equipped outdoor housings for Johannesburg and Cape Town climate extremes.
- Cloud-Based:Software-as-a-service video management shifts margin pools from hardware sales toward recurring subscriptions in South African SMB logistics. Transnet port modernization contracts specify guaranteed uptime SLAs with remote diagnostic capabilities rather than capital expenditure procurement.
- Wireless:4G/LTE cellular backhaul serves Nigerian and Egyptian municipal deployments where fiber trenching costs exceed camera hardware budgets by an order of magnitude.
- Analog:Coaxial CVBS infrastructure persists in legacy Egyptian government facilities and Algerian state enterprises where budget freezes delay IP migration timelines.
IP-based systems anchor current procurement volumes; cloud-based architectures are gaining share fastest in commercial verticals.
End User:
Geography concentrates government demand in Gulf megaprojects while healthcare integration drives UAE and Saudi hospital operator procurement.
- Government:NEOM megaproject zones mandate AI-integrated surveillance infrastructure with edge-computing camera networks for smart city corridors. Saudi Arabia's gigaproject procurement specifies GB/T 28181 and ONVIF Profile S certification as mandatory tender preconditions.
- Healthcare Facilities:Patient monitoring convergence with security infrastructure creates demand for dual-purpose video analytics in UAE and Saudi hospital operators. Cleveland Clinic Abu Dhabi and Saudi German Hospital Group deploy fall-detection algorithms on existing security camera networks.
- Transportation:Nairobi's Konza Technopolis and Mombasa port modernization open procurement channels for traffic-management networks with local assembly requirements under Kenya's Buy Kenya Build Kenya policy.
- Educational Institutions:Campus perimeter security and classroom monitoring drive South African university tenders where POPIA student data protection requires localized storage with no cloud egress.
Government vertical sustains premium pricing power; healthcare facilities represent the most rapidly expanding customer category.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Government buyers dominate procurement across the Middle East and Africa, with Gulf sovereign wealth funds and African municipal authorities driving divergent demand patterns. Compliance mandates from Saudi Arabia's National Cybersecurity Authority and the UAE's National Electronic Security Authority reshape vendor eligibility. Smart city megaprojects concentrate spending in specific urban corridors.
Saudi Arabia
NEOM gigaproject zones mandate AI-integrated surveillance infrastructure for smart city corridors. The National Cybersecurity Authority enforces encryption standards for video transmission that eliminate uncertified suppliers from government tenders. Riyadh's financial district towers specify AI-analytics-integrated PTZ cameras for automated perimeter tracking.
United Arab Emirates
Dubai commercial developments accelerate replacement cycles for legacy analog systems under National Electronic Security Authority mandates. Cleveland Clinic Abu Dhabi deploys fall-detection algorithms on security camera networks, converging patient monitoring with surveillance infrastructure. Dubai Mall operators specify IP66-rated dome cameras with edge-computing chipsets to satisfy PDPL biometric processing requirements.
South Africa
Standard Bank and FirstRand displace coaxial infrastructure with PoE-switched IP architectures to reduce cabling costs while meeting POPIA biometric data governance. Transnet port modernization contracts specify guaranteed uptime SLAs with remote diagnostic capabilities. Johannesburg and Cape Town climate extremes drive demand for PoE++ standards supporting heater-equipped outdoor housings.
Egypt
Price-sensitive municipal contracts prioritize bullet cameras with IR illumination for long-range perimeter coverage over aesthetic constraints. Budget freezes delay IP migration timelines in legacy government facilities where coaxial CVBS infrastructure persists. Cairo's urban expansion zones attract procurement for traffic-management networks with basic edge-server deployments.
Nigeria
Unreliable grid supply necessitates expensive UPS backup systems for continuous recording in municipal deployments. 4G/LTE cellular backhaul serves deployments where fiber trenching costs exceed camera hardware budgets. Lagos port modernization and Abuja smart city pilots open procurement channels with local assembly requirements under domestic content policies.
Middle East and Africa Surveillance IP Cameras Market Competitive Landscape
Player mix skews toward diversified technology conglomerates with security divisions alongside specialized video surveillance manufacturers. The competitive structure concentrates around three strategic archetypes: vertically integrated sensor fabricators capturing municipal price-sensitive contracts, cybersecurity-hardened specialists commanding premium positioning in compliance-heavy Gulf developments, and diversified industrial conglomerates leveraging existing government relationships. Dominant competitive moves include certification-driven portfolio rationalization and geographic expansion through local system integrator partnerships.
Within the diversified conglomerate tier, Honeywell International Inc. and Panasonic Corporation occupy positions anchored by cross-selling opportunities across building automation and security integration. Among specialized surveillance manufacturers, Hangzhou Hikvision Digital Technology Co., Ltd. exemplifies the vertically integrated archetype with in-house sensor production capabilities, while Axis Communications AB represents the cybersecurity-specialist positioning with firmware-hardened architectures. Hanwha Vision sits within the premium-tier segment through AI-analytics integration. Bosch Sicherheitssysteme GmbH anchors the European-origin engineering-focused tier, with Zhejiang Uniview Technologies Co., Ltd. and Teledyne FLIR LLC occupying distinct thermal-imaging and advanced optics specializations respectively.
| Leading Market Players |
|---|
| Hangzhou Hikvision Digital Technology Co., Ltd. |
| Honeywell International Inc. |
| Hanwha Vision |
| Bosch Sicherheitssysteme GmbH |
| Teledyne FLIR LLC |
| Zhejiang Uniview Technologies Co., Ltd. |
| Axis Communications AB |
| Panasonic Corporation |
| Sony Corporation |
| Others |
Pricing and Supply Chain Analysis
Fourteen-to-eighteen-month certification cycles for GB/T 28181 and ONVIF Profile S compliance concentrate pricing power among pre-certified vendors while squeezing margins for late entrants awaiting eligibility. Saudi NCA and UAE NESA encryption mandates create tiered procurement eligibility that separates premium-compliant suppliers from price-competitive but uncertified alternatives. This structural bottleneck lets certified manufacturers command project premiums in Gulf government tenders while Egyptian and Nigerian municipal buyers face constrained vendor pools.
Pricing Analysis
Cost-plus contracts with CMOS sensor indexation dominate large-scale municipal deployments across the Middle East and Africa. Three-tier pricing structure across premium, standard, and economy levels separates NCA/NESA-certified AI-analytics PTZ lines from basic IP dome units and legacy analog replacements. Pricing pressure stems from H.266/VVC codec transitions compressing storage infrastructure budgets and redirecting spend toward software subscriptions. Government verticals exhibit lowest price sensitivity due to compliance mandates, while South African SMB logistics segments drive hardest bargaining through outcome-based SLA contracting.
Supply Chain Analysis
Strategic stockpiling of CMOS image sensors and edge-computing chipsets prevails over just-in-time approaches given 90-120 day foundry lead times and shipping volatility through Red Sea corridors. East Asian fabrication in Taiwan, South Korea, and China anchors component sourcing, with PoE++ switchgear and ATEX-certified housings drawing from German and Japanese specialist suppliers. Single-source vulnerability concentrates in advanced AI processor supply, where NVIDIA and Qualcomm allocations determine product launch timelines. Distribution runs through Dubai-based integrators serving Gulf markets and Johannesburg logistics hubs penetrating Sub-Saharan Africa.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory fragmentation across Gulf Cooperation Council states and African Union members fragments procurement specifications, creating niche opportunities for compliance-specialized vendors. Divergent encryption standards, data localization mandates, and certification reciprocity gaps let targeted players capture premium positioning without head-to-head competition against diversified conglomerates.
For Market Incumbents: Consolidate certification advantages by accelerating GB/T 28181 and ONVIF Profile T pre-testing before formal submission cycles freeze competitor eligibility. Deepen backward integration into edge-computing chipsets to reduce exposure to NVIDIA allocation constraints threatening PTZ camera production schedules. Anchor channel control through exclusive system integrator partnerships in Riyadh and Dubai that lock out emerging entrants from specification-setting conversations. For New Entrants and Emerging Players: Differentiate on localized firmware development capabilities that satisfy Saudi NCA penetration-testing standards faster than legacy vendors with rigid global codebases. Target Kenyan smart city expansion through Konza Technopolis traffic-management tenders where Buy Kenya Build Kenya local assembly requirements disadvantage pure-import suppliers. Pursue cloud-VMS subscription models in South African SMB logistics where Transnet outcome-based contracting has normalized SaaS procurement expectations. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with underperforming security divisions lacking Gulf compliance certification. Long-term viability hinges on edge-AI processing capabilities that displace centralized server architectures across data localization mandates. Acquisition priority falls on vendors with existing NCA/NESA approvals and established Dubai integrator relationships. Watch H.266/VVC codec adoption rates across Dubai Roads and Transport Authority deployments as inflection indicator for storage infrastructure compression trends.| Strategic Initiative | Industry Significance |
|---|---|
| Certification Pre-Investment | Early GB/T 28181 testing locks out competitors from NEOM and Riyadh financial district tenders. |
| Edge-AI Chipset Partnership | Qualcomm or Ambarella alliances secure allocation priority for biometric-processing camera lines. |
| Local Assembly Joint Venture | Kenya and Nigeria domestic content policies require manufacturing presence for port modernization eligibility. |
| Outcome-Based Service Contracting | Guaranteed uptime SLAs with Standard Bank and Transnet shift margin pools toward recurring software revenue. |
| Cybersecurity Firmware Hardening | NCA and NESA penetration-testing capabilities differentiate premium positioning in UAE commercial developments. |
Research Methodology
Cross-validation between primary interviews with system integrators, government procurement officers, and hospital biomedical engineering directors and secondary validation through Saudi NCA certification registries, UAE NESA compliance disclosures, and South African POPIA guidance documents anchors the qualitative findings. Customs records from Dubai Jebel Ali port and Lagos Apapa terminal trace hardware import volumes by vendor origin. Bottom-up demand modeling from individual megaproject procurement schedules triangulates against top-down market sizing from regional security spending budgets.
Sensitivity analysis around codec transition timelines, edge-server deployment costs, and certification approval delays tests forecast robustness across the projection horizon. Segmentation dimensions modeled include product type, use case, technology architecture, and end-user vertical with jurisdiction-specific regulatory cluster as cross-cutting variable. CAGRs derive from fitted growth curves calibrated to NEOM construction phase schedules and Kenyan smart city procurement waves. Forecast inputs incorporate CMOS sensor foundry capacity announcements and Gulf sovereign wealth fund infrastructure commitment disclosures.
Material uncertainties — regulatory reciprocity negotiations between Gulf authorities and European standards bodies, Red Sea shipping disruption persistence, edge-AI processor allocation shocks — sit outside the modeled envelope. Forecasts reflect assumptions about certification timeline stability and megaproject execution continuity. Revision becomes warranted when NCA or NESA encryption standard updates trigger hardware replacement cycles ahead of modeled depreciation schedules.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Video Surveillance Systems
China Surveillance Storage Market
Video Surveillance Systems
Night Vision Outdoor Camera Market
Video Surveillance Systems
Wireless Home Security Camera Market
Video Surveillance Systems
Global CCTV Market
Video Surveillance Systems
Canada Surveillance Storage Market
Video Surveillance Systems
Night Vision System (NVS) Market
Video Surveillance Systems
Video Surveillance and Vsaas Market
Video Surveillance Systems
Brazil Surveillance IP Cameras Market
Video Surveillance Systems
North America Crawler Camera System Market
Video Surveillance Systems
Asia-Pacific Surveillance Analog Camera Market
Video Surveillance Systems
Europe Video Surveillance Systems Market
Video Surveillance Systems
India Surveillance Camera Market
Video Surveillance Systems
Smart Doorbell Camera Market
Video Surveillance Systems
Global Body Worn Cameras Market
Video Surveillance Systems
Europe Video Surveillance As a Service Market
Video Surveillance Systems
Germany Surveillance IP Camera Market