
 Biodegradable Gloves Market | 2026-2036
Biodegradable Gloves Market Size, Share, and Industry Trends Forecast 2026-2036
Biodegradable Gloves Market Outlook
Project finance for biopolymer production facilities is tilting competitive dynamics toward manufacturers with captive raw material access. Top Glove Corporation Bhd leverages its integrated rubber supply chain across Southeast Asian plantations to control input costs. Ansell Limited anchors its position through R&D intensity in nitrile-alternative formulations. SHOWA Group specializes in precision-engineered biodegradable solutions for chemical-resistant applications.
Biodegradable gloves are disposable hand protection devices engineered from plant-derived polymers or compostable synthetic blends, designed to decompose under industrial composting conditions within defined timeframes. Nitrile alternatives dominate current production volumes due to established barrier performance against pathogens and chemicals, while latex retains share in surgical settings requiring tactile sensitivity. Healthcare application leads absolute demand as hospitals face escalating clinical waste disposal costs, though catering segments show accelerated procurement shifts driven by municipal organic waste mandates. Certification stratification creates margin pools, with FDA-cleared and ASTM D6400-compliant products commanding procurement premiums over uncertified alternatives.
EPA industrial composting standards and FDA medical device regulations jointly define product qualification pathways for US market entry. The EU Green Deal and REACH chemical restrictions shape formulation choices for European suppliers, while ISO 14855 biodegradation testing protocols provide cross-border validation frameworks. Stakeholders must monitor evolving composting infrastructure availability against certification requirements to align capacity investments with regional waste processing capabilities.
Market Dynamics
Healthcare procurement teams face mounting pressure from clinical waste disposal costs exceeding traditional landfill fees by multiples, while EU Green Deal mandates force accelerated material substitution across European supply chains.
Growth Catalysts
- EU Green Deal single-use plastics directive:The framework accelerates biopolymer substitution across medical and food-service supply chains, compelling distributors to stock certified compostable alternatives.
- Healthcare waste management economics:Hospital systems in Germany and France face landfill diversion targets that make biodegradable gloves cost-competitive against conventional nitrile when total disposal costs are calculated.
- Industrial composting infrastructure expansion:Municipal organic waste processing capacity in the Netherlands and Belgium creates viable end-of-life pathways for ASTM D6400-certified products.
Market Restraints
- Natural rubber latex price volatility:Plantation yield fluctuations across Southeast Asian growing regions create input cost instability for plant-derived polymer formulations.
- Barrier performance gaps:Current biopolymer blends fail to match nitrile's chemical resistance against specific solvents used in laboratory and industrial cleaning applications.
- Certification timeline friction:FDA medical device clearance and ASTM D6400 compliance processes extend product launch cycles by 18-24 months versus conventional glove introductions.
Strategic Opportunities
- Catering and food processing segments:Municipal organic waste mandates in Italian and Spanish cities create procurement pull for certified compostable hand protection in commercial kitchens.
- Nitrile-biopolymer hybrid formulations:Convergence of synthetic rubber performance with compostable backbones offers pathway to displace conventional nitrile in chemical-resistant applications.
- Direct hospital system contracting:Bypassing traditional medical distributors through GPO-aligned direct sourcing agreements captures margin currently absorbed by intermediaries.
Industry Challenges
- Composting infrastructure mismatch:Industrial composting facility availability varies dramatically between German urban centers and Eastern European regions, creating certification compliance gaps.
- Biopolymer processing expertise scarcity:Extrusion and dipping line operators with experience in plant-derived polymer rheology remain concentrated among legacy natural rubber glove manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Biodegradable Gloves Market |
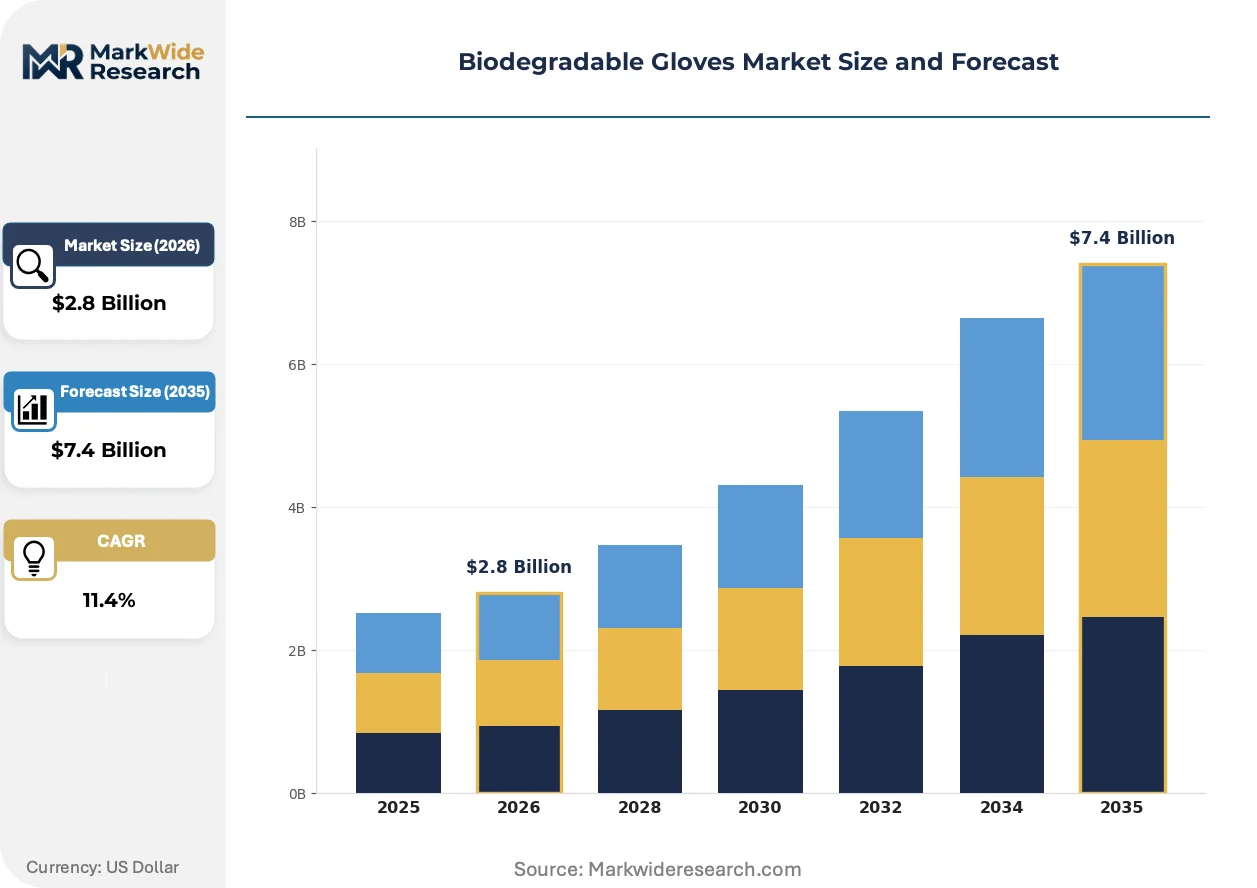
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $7.4 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Latex, Nitrile, Vinyl, Polyethylene Application: Healthcare, Catering, Cleaning, Agriculture End User: Hospitals, Restaurants, Households, Laboratories Certification: FDA, ISO, ASTM, EN |
| Companies Covered | SHOWA Group, Top Glove Corporation Bhd, Innovative Gloves Co., Ltd., SW Safety Solutions Inc., Ansell Limited, Hourglass International, Inc., Biogone, SunEco Tech Ventures Private Limited, Worldchamp (Huizhou) Plastics Products Co., Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Biodegradable Gloves Market Strategic Shifts
Material science breakthroughs and regulatory stringency are compressing the performance gap between biodegradable alternatives and petroleum-based hand protection, reshaping procurement criteria across institutional buyers.
Polylactic acid-nitrile copolymer blends is rendering obsolete the historical trade-off between compostability and chemical resistance that constrained early biopolymer glove adoption. Laboratory procurement managers in pharmaceutical manufacturing facilities are piloting these formulations for solvent-handling protocols previously reserved for conventional nitrile. The technology is rendering obsolete single-material product architectures that forced buyers to choose between performance and end-of-life compliance.
REACH chemical restrictions on specific plasticizers and accelerators are forcing reformulation of synthetic rubber glove production across European manufacturing bases. The regulation eliminates cross-border supply of non-compliant inventory and accelerates R&D spending toward bio-based curing agents. German clinical waste regulations mandating accelerated biodegradation timelines for disposable medical products are most affected, driving hospital procurement teams to pre-qualify ASTM D6400 suppliers.
Certification-driven preference stratification is splitting procurement decisions between premium-priced validated products and uncertified alternatives with unverified degradation claims. Group purchasing organizations for US hospital systems are inserting compostability requirements into glove category specifications, displacing price-only award criteria. This pattern is most visible in Pacific Northwest healthcare networks where state-level organic waste mandates align procurement incentives with environmental performance metrics.
Biodegradable Gloves Market Segmentation
Procurement patterns in biodegradable gloves diverge sharply by turnover velocity. High-frequency replacement segments like healthcare drive volume, while certification-heavy categories command margin premiums that reshape supplier economics.
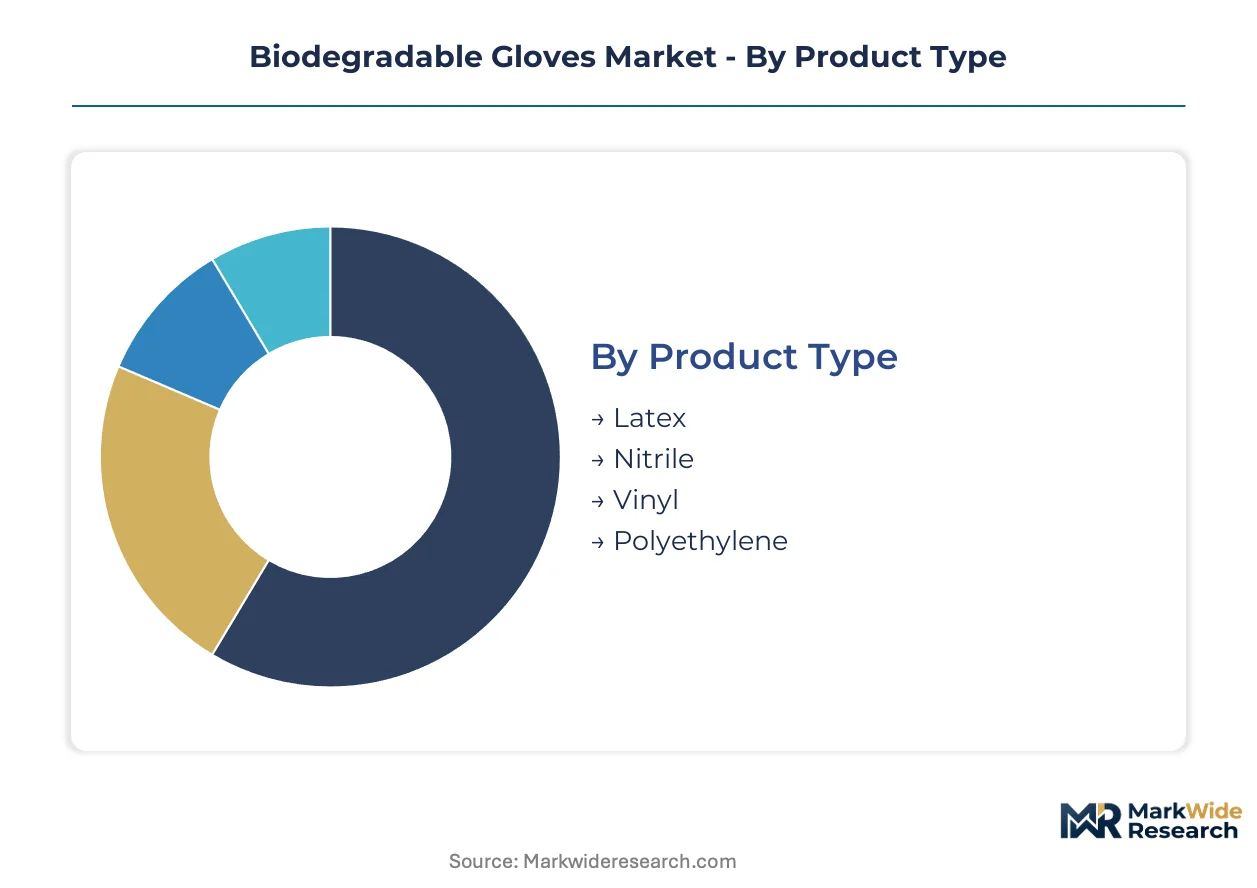
Product Type:
Cycle times vary from weeks in food-service polyethylene to months in laboratory nitrile, creating distinct inventory and margin profiles across the four material platforms.
- Nitrile:Engineered from acrylonitrile-butadiene copolymer with compostable plasticizer systems, delivering puncture resistance exceeding 3.5 Newtons. German hospital procurement teams specify nitrile alternatives for chemotherapy handling protocols where barrier integrity is non-negotiable, though industrial composting infrastructure gaps in Eastern Europe constrain rollout.
- Latex:Derived from Hevea brasiliensis sap with reduced protein content to minimize Type I hypersensitivity. Surgical suites in France and Belgium retain latex preference for microsurgical procedures requiring 0.08mm tactile discrimination, yet plantation supply volatility from Thai and Indonesian sources disrupts contract pricing.
- Vinyl:Polyvinyl chloride formulations with bio-based plasticizer substitutes for low-risk, short-duration tasks.
- Polyethylene:Cast film constructions for single-use food contact with minimal barrier requirements and rapid disposal cycles.
Nitrile dominates installed base. Polyethylene is where expansion concentrates.
Application:
Cost tier stratification separates premium-validated healthcare procurement from price-sensitive agricultural bulk purchasing.
- Healthcare:Encompasses examination, surgical, and chemotherapy-rated gloves subject to FDA medical device clearance and ASTM D6400 compostability dual certification. Netherlands hospital systems now mandate biodegradable alternatives for all non-sterile examination categories, with disposal cost accounting making certified products cost-neutral against conventional nitrile.
- Catering:Food-contact gloves governed by EU Regulation 1935/2004 and municipal organic waste mandates in Italian cities. Milan and Rome commercial kitchen procurement specifications now require EN 13432 compliance, creating pull-through demand that outpaces healthcare conversion rates in absolute volume terms.
- Cleaning:Industrial and household sanitation gloves with moderate chemical resistance requirements.
- Agriculture:Bulk purchasing for harvesting and pesticide application with minimal certification overhead.
Healthcare dominates installed base. Catering is climbing the fastest.
End User:
Customer type determines contract structure, with institutional buyers demanding multi-year supply agreements unavailable to fragmented household purchasers.
- Hospitals:Integrated delivery networks and standalone facilities purchasing through group purchasing organizations with sustainability scorecards. Pacific Northwest healthcare networks in Washington and Oregon have inserted compostability metrics into glove category RFPs, displacing price-only award criteria.
- Restaurants:Chain and independent foodservice operations responding to municipal organic waste diversion mandates. Barcelona and Madrid municipal regulations now fine commercial kitchens for non-compostable disposables in organic waste streams, accelerating procurement shifts.
- Households:Retail channel consumers with sporadic purchasing and minimal certification awareness.
- Laboratories:Research and pharmaceutical manufacturing facilities with solvent resistance specifications.
Hospitals dominate installed base. Restaurants are gaining share fastest.
Certification:
Margin pools concentrate in multi-certified products, with uncertified alternatives trapped in commodity pricing.
- FDA:Medical device clearance for examination and surgical gloves under 21 CFR 880.6250, requiring biocompatibility testing and quality system regulation compliance. US hospital procurement teams treat FDA clearance as table stakes, with ASTM D6400 compostability becoming the differentiating criterion.
- ASTM:D6400 and D6868 standards for industrial compostability, specifying 90% biodegradation within 180 days under controlled conditions. German clinical waste regulations explicitly reference ASTM D6400 for accelerated biodegradation timelines, creating regulatory alignment between US certification and EU procurement requirements.
- ISO:14855 biodegradation testing protocols providing cross-border validation frameworks.
- EN:13432 European standard for packaging recoverable through composting and biodegradation.
FDA dominates installed base. ASTM is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement teams in Germany and municipal organic waste mandates in Italy concentrate institutional buyer archetypes. Clinical waste disposal economics and regulatory stringency create divergent adoption velocities across national boundaries.
Germany
Federal clinical waste regulations mandate accelerated biodegradation timelines for disposable medical products, compelling hospital systems to pre-qualify ASTM D6400 suppliers. The country's national pharmaceutical regulator aligns procurement specifications with compostability metrics. The Rhine-Ruhr metropolitan cluster hosts integrated delivery networks negotiating multi-year direct sourcing agreements with certified manufacturers.
United States
FDA medical device clearance requirements intersect with state-level organic waste mandates in Washington and Oregon to reshape hospital procurement scorecards. EPA industrial composting standards define product qualification pathways for market entry. Pacific Northwest healthcare networks now insert compostability requirements into glove category RFPs, displacing price-only award criteria.
Italy
Municipal organic waste diversion mandates in Milan and Rome commercial kitchens accelerate procurement shifts faster than healthcare conversion rates. EU Regulation 1935/2004 governs food-contact compliance specifications. The Lombardy industrial corridor concentrates catering supply chain distributors responding to fines for non-compostable disposables in organic waste streams.
Netherlands
Hospital systems mandate biodegradable alternatives for all non-sterile examination categories, with disposal cost accounting rendering certified products cost-neutral against conventional nitrile. Municipal organic waste processing capacity creates viable end-of-life pathways for ASTM D6400-certified products. The Randstad urban agglomeration leads procurement specification development for integrated healthcare networks.
France
Surgical suites retain latex preference for microsurgical procedures requiring precise tactile discrimination, though plantation supply volatility disrupts contract pricing. REACH chemical restrictions force reformulation of synthetic rubber production across European manufacturing bases. The Île-de-France region anchors hospital procurement concentration, with landfill diversion targets making biodegradable gloves economically competitive.
Biodegradable Gloves Market Competitive Environment
Channel-controlling players compete with product-specialist players across procurement tiers. The vendor base fragments between integrated rubber plantation operators and precision-engineered biopolymer formulators. Three strategic archetypes dominate: captive raw material controllers, R&D-intensive formulation specialists, and certification-anchored direct contractors. Capacity expansion and backward integration into upstream polymer production represent the dominant competitive moves reshaping supplier economics.
Among plantation-integrated operators, Top Glove Corporation Bhd exemplifies captive supply chain control across Southeast Asian growing regions. Ansell Limited occupies a position within the R&D-intensive tier, while SHOWA Group represents the precision-engineered specialist archetype for chemical-resistant applications. These three anchors illustrate how competitive positioning stratifies between cost control, technical differentiation, and application-specific certification depth.
| Leading Market Players |
|---|
| SHOWA Group |
| Top Glove Corporation Bhd |
| Innovative Gloves Co., Ltd. |
| SW Safety Solutions Inc. |
| Ansell Limited |
| Hourglass International, Inc. |
| Biogone |
| SunEco Tech Ventures Private Limited |
| Worldchamp (Huizhou) Plastics Products Co., Ltd |
| Others |
Value Chain & Pricing Dynamics
Malaysian rubber plantation concentration upstream feeds directly into margin capture by integrated glove manufacturers with captive latex supply, while downstream hospital procurement teams in Germany and the Netherlands face total-cost-of-ownership calculations that elevate certified compostable premiums over commodity alternatives.
Pricing Analysis
Certification level creates the primary spread between procurement tiers, with FDA-cleared and ASTM D6400-compliant products commanding substantial premiums over uncertified alternatives in hospital system RFPs. Three-tier pricing structure separates premium-validated healthcare grades from mid-tier food-service certifications and economy-grade uncertified bulk supply. Cost compression in the economy tier is intensifying because Southeast Asian plantation yield fluctuations destabilize input costs for natural rubber formulations. Agricultural bulk purchasers exhibit highest price sensitivity, while German integrated delivery networks prioritize total disposal cost neutrality over unit price.
Supply Chain Analysis
REACH chemical restrictions on plasticizers and accelerators limit cross-border flows of non-compliant synthetic rubber formulations into European manufacturing bases. Production gravity centers on Malaysia, Thailand, and Indonesia for natural rubber latex, with China and South Korea dominating nitrile-butadiene copolymer supply. The supply chain rests on Hevea brasiliensis sap, acrylonitrile monomer, and bio-based plasticizer substitutes as critical inputs. Single-source vulnerability concentrates in Southeast Asian plantation regions exposed to climate-induced yield volatility. Distribution runs through medical distributors and group purchasing organizations in healthcare, with direct sourcing agreements emerging as an alternative channel.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Biodegradable glove procurement is transitioning toward platform-economics dynamics where ASTM D6400 certification interoperability enables hospital systems to switch suppliers without requalification burden, much as cloud infrastructure standards reduced switching costs across enterprise software.
For Market Incumbents: Pre-empt certification commoditization by locking in multi-year direct sourcing agreements with German and Netherlands hospital systems before ASTM D6400 becomes table stakes. Backward integration into biopolymer fermentation capacity secures margin control against plantation supply volatility from Thai and Indonesian sources. Capacity addition in European compounding facilities mitigates REACH reformulation disruption.
For New Entrants and Emerging Players: Establish a beachhead in Italian and Spanish catering segments where municipal organic waste mandates create procurement pull with lower certification overhead than healthcare FDA pathways. Food-service distributors in Milan and Rome commercial kitchens represent the most penetrable entry point. A go-to-market angle anchored to EN 13432 compliance for kitchen operations bypasses the 18-24 month FDA clearance timeline that constrains healthcare entry.
For Investors and Strategic Acquirers: Capital is best deployed toward mid-cap biopolymer formulators with ASTM D6400 validation and existing relationships with Pacific Northwest healthcare networks, where state-level organic waste mandates align procurement incentives with environmental performance metrics. Long-term viability hinges on composting infrastructure buildout keeping pace with certification requirements. The signal to watch is industrial composting facility permitting velocity in Eastern European regions, where infrastructure gaps currently constrain certified product rollout.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Biopolymer Production | Captive supply of PLA-nitrile copolymers insulates margin from plantation price volatility. |
| ASTM D6400 Certification Acceleration | German clinical waste regulations explicitly reference this standard for hospital procurement compliance. |
| Direct Hospital System Contracting | Bypassing GPO intermediaries captures margin currently absorbed by medical distributors in US and EU markets. |
| Catering Segment Specialization | Milan and Rome municipal fines for non-compostable disposables create immediate procurement pull. |
| Hybrid Formulation R&D Partnership | Collaboration with pharmaceutical manufacturers pilots solvent-resistant biopolymers for laboratory applications. |
Study Parameters
Desk research of FDA 510(k) filings, ASTM standard documentation, and EU Green Deal regulatory texts preceded structured interviews with hospital procurement managers, GPO contracts directors, biopolymer R&D leads, and industrial composting facility operators. Secondary validation drew from customs trade data for natural rubber imports, SEC filings of listed glove manufacturers, and hospital sustainability reporting databases. Bottom-up demand modeling from end-use segments was triangulated against top-down market sizing from production capacity disclosures.
Assumptions held fixed include current REACH chemical restrictions and EPA industrial composting standards, while variables tested included biopolymer cost reduction trajectories and municipal organic waste mandate expansion rates. Segmentation dimensions spanned material platform, application category, certification tier, and regional regulatory cluster. CAGRs were derived from installed base penetration curves and replacement cycle analysis. Forecast inputs incorporated clinical waste disposal cost inflation and industrial composting infrastructure buildout timelines.
Sensitivities concentrate around biopolymer barrier performance breakthroughs and composting facility permitting delays. Forecasts reflect assumptions about certification timeline friction and plantation supply stability. Material shifts in EU Green Deal enforcement stringency or FDA medical device clearance pathways would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Safety Equipment and Personal Protective Equipment (PPE)
Military Gas Mask Market
Safety Equipment and Personal Protective Equipment (PPE)
FFP2 Grade Medical Protective Mask Market
Safety Equipment and Personal Protective Equipment (PPE)
Hand Sanitizer Spray Pen Market
Safety Equipment and Personal Protective Equipment (PPE)
Chemical Protective Gloves Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Collision Avoidance System Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Anti-Vibration Gloves Market
Safety Equipment and Personal Protective Equipment (PPE)
Medical Radiation Protection Aprons Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Powered Air Purifying Respirator (PAPR) Market
Safety Equipment and Personal Protective Equipment (PPE)
Premium Motorcycle Helmets Market
Safety Equipment and Personal Protective Equipment (PPE)
Anti-Fatigue Mats Market
Safety Equipment and Personal Protective Equipment (PPE)
Outdoor Safety Lock Market
Safety Equipment and Personal Protective Equipment (PPE)
Edge Protector Market
Safety Equipment and Personal Protective Equipment (PPE)
Protective Eye Wear Market
Safety Equipment and Personal Protective Equipment (PPE)
Latin America Hand Sanitizer Market
Safety Equipment and Personal Protective Equipment (PPE)
Hearing Protection Devices Market
Safety Equipment and Personal Protective Equipment (PPE)
United States Emergency Lighting Market