
 Intrusion Alarm System Market | 2026-2036
Intrusion Alarm System Market Size, Share, and Industry Trends Forecast 2026-2036
Intrusion Alarm System Market Analytics
UL 2610 certification for commercial premises is rotating toward baseline expectation across new construction. Honeywell International Inc. leverages its integrated building automation portfolio to anchor enterprise contracts. Schneider Electric SE competes through energy-management convergence with security infrastructure. Robert Bosch GmbH differentiates on sensor fusion algorithms that reduce false alarm rates.
An intrusion alarm system detects unauthorized entry through perimeter sensors, motion detectors, and glass-break recognition, typically communicating via cellular, IP, or PSTN pathways to central monitoring stations or local annunciators; its primary purpose is to deter theft, trigger law enforcement dispatch, and limit property loss. Wireless alarms lead residential retrofit activity due to minimal installation disruption, while monitored systems command recurring revenue pools from commercial subscribers. PIR sensors dominate volume shipments, though glass break detectors are gaining share in retail and banking applications where perimeter hardening takes priority.
FCC Part 15 governs radio frequency emissions for wireless alarm transmitters in the United States, while the EU Radio Equipment Directive mandates CE marking for RF-enabled devices sold across member states. ETSI EN 300 220 shapes spectrum allocation for European short-range devices, directly affecting product architecture decisions. Stakeholders must weigh cloud-based monitoring migration against legacy PSTN sunset timelines when planning platform roadmaps.

Market Dynamics
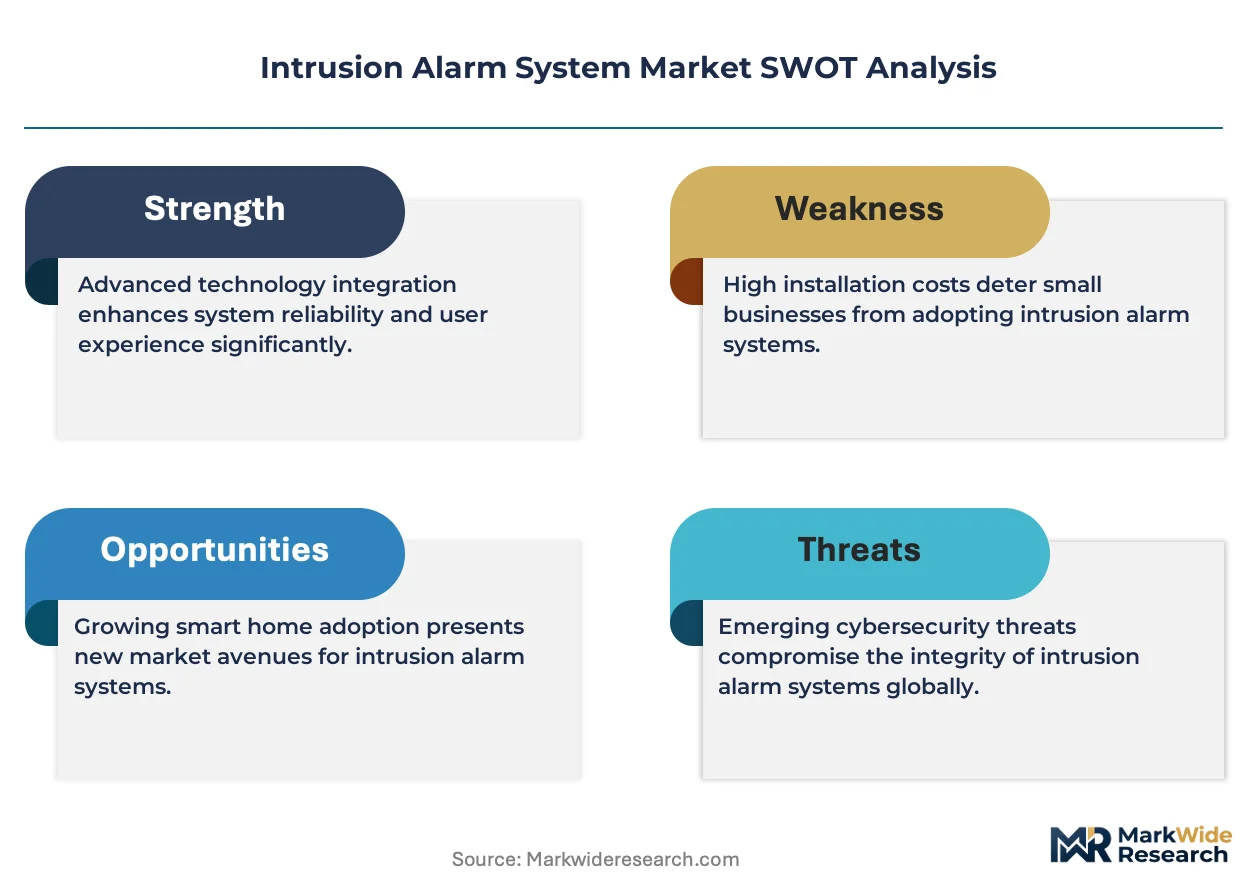
Wireless sensor networks are compressing installation timelines while UL 2610 certification mandates are hardening compliance thresholds for commercial premises, forcing manufacturers to recalibrate R&D roadmaps around dual-band RF architectures and cloud-native monitoring platforms.
Growth Catalysts
- Smart Home Integration:Residential property owners are accelerating retrofit activity through minimally disruptive wireless alarm deployments that sync with voice assistants and mobile ecosystems.
- EU Radio Equipment Directive:CE marking mandates for RF-enabled devices are standardizing product architectures across member states, reducing fragmentation in cross-border supply chains.
- Perimeter Hardening Priorities:Banking and retail verticals are elevating glass break detector specifications as primary defense layers against smash-and-grab incidents.
Market Restraints
- PSTN Sunset Timelines:Legacy copper network decommissioning across multiple jurisdictions is stranding installed base connectivity and forcing premature upgrade cycles.
- Semiconductor Supply Concentration:RF transceiver and PIR sensor chip sourcing remains concentrated in East Asian foundry networks, exposing lead time volatility.
- False Alarm Penalty Regimes:Municipal dispatch fee structures in major metro areas are dampening subscriber appetite for unverified alarm systems.
Strategic Opportunities
- German Wireless Concentration:Outsize demand density for cellular-connected alarms in German residential retrofit channels offers templateable deployment playbooks for adjacent markets.
- Energy-Security Convergence:Building automation integrators are bundling intrusion detection with HVAC and lighting control, opening enterprise contract expansion paths.
- Sensor Fusion Architectures:Multi-modal detection combining PIR, acoustic, and video verification is compressing false alarm rates below insurer risk thresholds.
Industry Challenges
- RF Engineering Talent Scarcity:Shortage of engineers proficient in ETSI EN 300 220 spectrum compliance and antenna design is elongating product certification timelines.
- Cloud Migration Integration Friction:Hybrid architectures bridging legacy PSTN panels with IP/cellular backhaul are generating interoperability failures in field deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Intrusion Alarm System Market |
| Market Size in 2026 | $52.7 Billion |
| Market Size in 2035 | $108.91 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wired Alarms, Wireless Alarms, Monitored Systems, Unmonitored Systems Technology: PIR Sensors, Contact Sensors, Glass Break Sensors, Smoke Detectors End User: Residential, Commercial, Industrial, Government Installation Type: Do-It-Yourself, Professional, Integrated Systems, Cloud-Based |
| Companies Covered | Honeywell International Inc., Schneider Electric SE, ADT Inc., Panasonic Corporation, ASSA ABLOY AB, Johnson Controls International plc, Robert Bosch GmbH, Axis Communications AB, Hikvision Digital Technology Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Intrusion Alarm System Market Evolving Landscape
Cellular and IP pathway dominance is displacing copper-dependent communication, while AI-driven sensor fusion and tightening certification regimes are compressing product lifecycles and reshaping vendor competitive moats.
AI-powered video verification is displacing standalone PIR sensors in premium commercial installations. Large-format retail and logistics warehouse operators are adopting dual-technology detectors that cross-reference thermal signatures with machine-learning object classification. This convergence is displacing traditional alarm panel architectures that relied on single-sensor triggers, compressing false dispatch rates and enabling outcome-based monitoring contracts.
FCC Part 15 emission standards are tightening spurious radiation limits for wireless alarm transmitters operating in unlicensed bands. Equipment manufacturers must redesign RF front-ends and antenna configurations to maintain compliance as spectral congestion intensifies from IoT device proliferation. Commercial integrators in the United States are responding by specifying pre-certified modular radios rather than discrete component builds.
Subscription-based monitoring contracts are displacing equipment-only sales in residential channels. Home security dealers are bundling hardware installation with recurring central station services, compressing upfront capital barriers for property owners. This shift is most pronounced in suburban markets where DIY installation competence remains uneven and insurer premium discounts for monitored systems create tangible value capture.
Intrusion Alarm System Market Segmentation
Intrusion alarm system purchasing flows through distinct channel configurations that shape vendor strategy and margin structure. Product architecture, technology integration depth, and installation complexity determine whether systems reach end users through retail, dealer networks, or enterprise integrators.
Product Type:
Wireless alarms and monitored systems dominate professional dealer channels, while wired configurations and unmonitored options concentrate in retail and direct-to-consumer pathways.
- Wired Alarms:Hardwired sensor networks using dedicated low-voltage cabling deliver superior reliability and immunity to RF interference. Commercial construction in Germany and retrofit mandates across US educational facilities sustain steady demand despite installation labor intensity.
- Wireless Alarms:Battery-powered sensor networks communicating via cellular or proprietary RF protocols enable rapid deployment without structural disruption. Residential retrofit activity across suburban US markets and German multi-family housing accelerates uptake where landlord restrictions prohibit permanent modifications.
- Monitored Systems:Central station oversight with automated law enforcement dispatch commands premium recurring revenue streams.
- Unmonitored Systems:Local annunciation-only configurations serve price-sensitive segments and rural areas beyond cellular coverage.
By volume, wireless alarms lead. By growth pace, monitored systems are expanding most quickly.
Technology:
Sensor technology selection follows application risk profiles, with banking and retail verticals prioritizing perimeter detection while residential installations emphasize motion-based coverage.
- PIR Sensors:Passive infrared detectors identify thermal signature changes from moving bodies within defined coverage zones. Volume shipments concentrate in residential installations across India and Brazil where cost minimization dominates specification criteria.
- Glass Break Sensors:Acoustic pattern recognition algorithms tuned to specific frequency signatures of breaking glass. Banking branches in US metropolitan areas and jewelry retail in Dubai deploy these as primary perimeter defense layers against smash-and-grab tactics.
- Contact Sensors:Magnetic reed switches monitor door and window status through circuit continuity.
- Smoke Detectors:Photoelectric or ionization sensors for fire safety integration within unified alarm panels.
PIR sensors ship in greatest volume. Glass break sensors gain share fastest among commercial verticals.
End User:
Customer type determines procurement modality, with residential buyers favoring subscription bundles and industrial purchasers demanding customized integration with existing facility management platforms.
- Residential:Single-family and multi-family property owners purchasing through dealer networks or retail channels. Smart home ecosystem compatibility drives specification in US and UK markets where voice assistant integration has become baseline expectation.
- Commercial:Retail, office, and hospitality properties requiring UL 2610 or equivalent certification. Large-format retail chains across France and logistics warehouse operators in Netherlands prioritize video verification integration to qualify for insurer premium discounts.
- Industrial:Manufacturing and critical infrastructure sites with harsh environment requirements.
- Government:Federal, state, and municipal facilities with classified or sensitive operational mandates.
Residential captures greatest unit volume. Commercial delivers steepest value expansion trajectory.
Installation Type:
Service delivery models stratify by customer technical sophistication, with cloud migration enabling remote configuration that blurs historical boundaries between professional and self-installed systems.
- Professional:Certified technician deployment with programming, testing, and monitoring activation. German residential retrofit channels and US commercial construction specifications mandate professional installation to maintain warranty and insurance validity.
- Cloud-Based:IP-connected panels with browser or mobile application configuration eliminating on-site programming visits. Australian and Canadian markets show accelerating uptake among small commercial subscribers seeking centralized multi-site management without dealer dependency.
- Do-It-Yourself:Consumer self-installation with peel-and-stick sensors and app-guided setup.
- Integrated Systems:Unified deployment with HVAC, lighting, and access control through single building automation platform.
Professional installation handles greatest installed base value. Cloud-based deployment climbs fastest as cellular module costs decline.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Import dependence for RF modules and sensor assemblies concentrates in East Asian supply chains, while finished system exports flow toward German residential retrofit channels and US commercial construction sites. Regulatory divergence between FCC Part 15 emission limits and ETSI EN 300 220 spectrum rules fragments product architectures across Atlantic markets.
United States
Commercial construction specifications mandate UL 2610 certification for new office and retail builds, compressing vendor qualification timelines. FCC Part 15 governs unlicensed band emissions for wireless transmitters, with spurious radiation limits tightening as IoT density increases. Installer networks in Texas and Florida concentrate demand for monitored systems bundled with insurer-mandated central station dispatch.
Germany
Multi-family housing landlords drive wireless alarm retrofit activity where permanent structural modifications face rental agreement restrictions. CE marking under the EU Radio Equipment Directive standardizes RF-enabled device compliance across member state borders. The Rhine-Ruhr metropolitan corridor hosts dense installer networks capturing outsized residential demand concentration for cellular-connected panels.
China
Domestic manufacturing capacity for PIR sensors and RF transceivers supplies downstream assembly operations across Asia-Pacific. MIIT radio type approval requirements govern spectrum allocation for short-range devices operating in unlicensed bands. Shenzhen industrial clusters concentrate module production serving export markets facing divergent FCC and ETSI certification requirements.
United Kingdom
Voice assistant integration drives smart home ecosystem compatibility as baseline specification in suburban residential markets. Building regulations for new construction increasingly reference monitored alarm systems as standard fit-out requirements. Greater London installer networks specialize in heritage building retrofits where wireless deployment avoids structural damage to protected facades.
India
Cost-minimization dominates sensor specification criteria in residential installations across tier-2 and tier-3 urban centers. BIS certification requirements for electronic safety equipment create compliance barriers for imported finished systems. Maharashtra industrial corridors concentrate domestic assembly operations sourcing RF modules from East Asian suppliers.
Intrusion Alarm System Market Competitive Landscape
Concentration sits with diversified industrial conglomerates possessing integrated building automation portfolios. The vendor base spans three tiers: multinational technology conglomerates with cross-subsidized R&D budgets, specialized security equipment manufacturers focused on sensor innovation, and regional assembly operations serving price-sensitive emerging markets. Competitive dynamics center on certification pre-positioning for UL 2610 and CE marking mandates, alongside strategic partnerships between module suppliers and monitoring service operators.
Among diversified technology conglomerates, Honeywell International Inc., Schneider Electric SE, and Robert Bosch GmbH exemplify archetypes competing through convergence strategies. Honeywell anchors enterprise contracts through building automation integration. Schneider Electric occupies a position emphasizing energy-management convergence with security infrastructure. Bosch represents sensor fusion specialization targeting false alarm rate compression. Each leverages captive distribution channels and pre-existing facility management relationships to defend installed base positions against modular challenger entrants.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| Schneider Electric SE |
| ADT Inc. |
| Panasonic Corporation |
| ASSA ABLOY AB |
| Johnson Controls International plc |
| Robert Bosch GmbH |
| Axis Communications AB |
| Hikvision Digital Technology Co., Ltd. |
| Others |
Value Network & Pricing Analysis
UL 2610 certification gates both supplier qualification timelines and price differentiation between commercial-grade and residential-tier intrusion alarm systems, compressing margin structures for uncertified manufacturers while rewarding pre-qualified vendors with pricing power in enterprise procurement channels.
Pricing Analysis
Industrial OEM buyers anchor three-tier pricing structure across premium, standard, and economy levels in the intrusion alarm system market. Price differentiation separates UL 2610-certified commercial panels from uncertified residential units and further stratifies by cellular module integration depth. Pricing pressure stems from semiconductor cost compression in RF transceiver components, squeezing margins in the economy tier. Residential retrofit channels exhibit highest price sensitivity, while banking and critical infrastructure verticals absorb premium pricing for verified alarm architectures.
Supply Chain Analysis
Shenzhen industrial clusters concentrate RF module and PIR sensor production, creating single-source vulnerability for global alarm system assemblers. East Asian foundry networks in Taiwan, South Korea, and China supply RF transceivers, PIR sensor chips, and cellular modems that feed downstream assembly operations. Tariff exposure on Chinese-manufactured electronics components threatens cost structures for North American and European integrators. Distribution runs through certified installer networks in Germany and the United States, with direct-to-consumer channels gaining share in suburban residential markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory entrenchment around UL 2610 and CE marking standards creates durable defensive moats for pre-certified vendors, as switching costs for enterprise buyers escalate when facility-wide alarm architectures require requalification.
For Market Incumbents: Secure UL 2610 pre-certification pipelines for next-generation dual-band RF architectures before PSTN sunset deadlines strand legacy installed bases. Deepen backward integration into sensor fusion algorithm development to differentiate against modular challenger entrants. Channel control through captive installer networks in the Rhine-Ruhr corridor and Texas-Florida metroplexes defends recurring revenue pools from monitoring service competitors. For New Entrants and Emerging Players: Anchor in German multi-family housing retrofit channels where landlord restrictions on structural modifications favor wireless cellular-connected panels over hardwired alternatives. Target cloud-based configuration platforms for small commercial subscribers in Australia and Canada seeking multi-site management without dealer dependency. Partner with smart home ecosystem platforms to bypass traditional installer gatekeepers in voice assistant-integrated residential segments. For Investors and Strategic Acquirers: UL 2610 certification mandates reshape the acquisition landscape toward targets with pre-existing commercial construction specifications and central station monitoring relationships. Long-term viability favors vertically integrated security technology specialists with captive RF engineering talent and energy-management convergence capabilities. Monitor FCC Part 15 emission standard tightening as signal for modular radio specification shifts favoring pre-certified subsystem suppliers over discrete component builders.| Strategic Initiative | Industry Significance |
|---|---|
| UL 2610 Certification Pre-Positioning | Commercial construction specifications in Texas and Florida mandate certified panels for new builds. |
| Sensor Fusion Algorithm Development | Bosch's multi-modal detection architectures compress false alarm rates below insurer risk thresholds. |
| Cellular Module Integration | Cloud-native monitoring platforms displace copper-dependent PSTN pathways across suburban US markets. |
| Installer Network Captivity | German Rhine-Ruhr corridor hosts dense certified technician networks controlling retrofit channel access. |
| Energy-Security Convergence | Schneider Electric bundles intrusion detection with HVAC control to expand enterprise contract values. |
Research Methodology
Initial hypotheses were tested against primary input from central station monitoring operators, commercial security integrators, RF engineering specialists, and facility management directors, and refined through secondary validation against FCC Part 15 filings, ETSI EN 300 220 compliance databases, UL certification registries, and customs trade data for RF module imports. Bottom-up shipment estimates from sensor manufacturers were triangulated with top-down construction spending data across the analysis window.
Variance decomposition across product type, sensor technology, end-user vertical, and installation modality shaped the analytical framework over the projection horizon. CAGRs were derived from fitted growth curves applied to segment-level baseline estimates. Industry-specific forecast inputs incorporated PSTN sunset timelines by jurisdiction and smart home ecosystem penetration rates by metropolitan statistical area.
Decision-makers should treat outputs as directional under assumptions of steady regulatory enforcement and no catastrophic semiconductor supply disruption; material deviation would warrant model refresh. Practitioners should keep alternative scenarios live as FCC emission standard tightening and EU Radio Equipment Directive enforcement timelines evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Security and Surveillance
Situational Awareness System Market
Security and Surveillance
Home Security Sensors Market
Security and Surveillance
India Electronic Security Market
Security and Surveillance
Air Cargo Security Equipment Market
Security and Surveillance
Manned Guarding Services Market
Security and Surveillance
Global Adaptive Security Market
Security and Surveillance
Signal Jammer Market
Security and Surveillance
TSCM Equipment Market
Security and Surveillance
Sirens Market
Security and Surveillance
Asia-Pacific Security Services Market
Security and Surveillance
Night Vision Scopes Market
Security and Surveillance
India Perimeter Intrusion Detection and Prevention Market
Security and Surveillance
North America People Screening Market
Security and Surveillance
Latin America Electronics Security Market
Security and Surveillance
Ballistic Protection Scanners Market
Security and Surveillance
Global Security and Vulnerability Management Market